
AI
The $7.6 Trillion Silicon Imperative: How the AI Investment Boom is Rewiring the Global Economy

A deep dive into the massive AI investment boom reshaping global markets. Big Tech hyperscalers are expected to spend $800 billion in 2026 on AI infrastructure, pushing total AI capex toward a staggering $7.6 trillion by 2031.
The “cloud,” for all its ethereal branding, has always been a remarkably heavy thing. It is made of steel, concrete, rare-earth metals, and miles of copper cabling. But what was once a quiet, steady accumulation of server farms has recently mutated into an industrial mobilization unseen since the construction of the U.S. Interstate Highway System or the post-war reconstruction of Europe. We are in the throes of a massive AI investment boom, one that is violently reshaping the topography of global markets, straining power grids, and testing the limits of human capital.
At the vanguard of this epochal shift are the “Big Four” hyperscalers—Alphabet, Amazon, Meta, and Microsoft. Driven by an arms-race mentality and a fear of obsolescence, these titans are unleashing capital at a scale that defies historical precedent. As we look toward AI infrastructure spending 2026, the combined capital expenditures (capex) of these firms are projected to hit an eye-watering $720 billion to $800 billion.
But this is merely the opening salvo. When you factor in the broader ecosystem—real estate investment trusts (REITs), utility upgrades, specialized cooling systems, and next-generation networking architectures—total global investment in artificial intelligence physical infrastructure could hit $7.6 trillion by 2031.
This is not a software update. It is a fundamental rewiring of the global economy. To understand where the market is headed, we must look past the flashing green lights of the major indices and examine the steel, silicon, and electrons quietly being poured into the earth.
The Scale of the Build: Decoding Hyperscalers AI Capex
To appreciate the sheer velocity of the big tech AI infrastructure boom, one must look at the balance sheets. In a typical technology cycle, capital expenditure rises linearly, trailing revenue. Today, the curve has gone asymptotic.
As recent earnings reports indicate, the hyperscalers AI capex is not being diverted into abstract research and development or speculative marketing. It is being violently injected into the physical layer of the internet. By the end of 2026, Microsoft, Amazon, Google, and Meta are expected to collectively spend nearly 80% more than their record-breaking 2024 outlays, according to analysis in the Financial Times.
Why this staggering sum? Because the foundational architecture of computing is changing.
- The Silicon Tax: Upwards of 60% of an AI data center’s budget goes directly to silicon. While Nvidia remains the undisputed kingmaker, commanding premium margins for its Blackwell architectures, the reliance on a single vendor has spurred massive investments in custom ASIC (Application-Specific Integrated Circuit) chips, such as Google’s TPUs and Amazon’s Trainium chips.
- The Networking Bottleneck: An AI supercomputer is only as fast as its slowest connection. Moving data between tens of thousands of GPUs requires specialized networking equipment, fundamentally altering the supply chains managed by firms like Broadcom and Arista Networks.
- The Power Paradigm: Traditional data centers draw roughly 10 to 15 kilowatts per rack. High-density AI clusters require upwards of 100 kilowatts per rack, demanding entirely new power delivery and thermal management architectures.
“We are no longer building data centers; we are building localized compute-cities. The capital requirements have transitioned from traditional IT budgeting to sovereign-level infrastructure financing.” — Chief Technology Officer, Tier-1 Hyperscaler]
From Training to Inference: The Strategic Drivers
Skeptics often point to the relatively modest immediate revenue generated by generative AI tools, questioning the return on investment (ROI) for this hyperscalers AI spending 2026. But this views the technology through the rear-view mirror. The current spending is not designed for the AI of 2024; it is the necessary foundation for the “Agentic AI” of 2027 and beyond.
The first phase of the AI revolution was defined by training—feeding massive language models the entirety of the open internet. Training is capital intensive but computationally finite. We are now entering the inference phase, where these models are deployed continuously in the real world to solve problems, generate code, and automate workflows.
If Agentic AI—systems that execute multi-step tasks autonomously rather than simply answering queries—becomes embedded in enterprise operations, the compute requirements will scale infinitely. Every time an AI agent negotiates a supply chain contract or dynamically reroutes logistics, it triggers an inference workload.
As McKinsey & Company notes in their latest technology forecast, if generative AI achieves scale across global enterprises, it could add between $2.6 trillion and $4.4 trillion to global GDP annually. To capture that value, the infrastructure must exist first. In Silicon Valley, the prevailing wisdom is brutal: overbuilding is a financial risk; underbuilding is an existential one.
Reshaping Markets: The Ripple Effect Beyond Silicon
The impact of AI investment on markets extends far beyond the “Magnificent Seven.” The most sophisticated institutional investors have moved past the primary beneficiaries (Nvidia, Microsoft) and are aggressively positioning in the secondary and tertiary derivatives of the AI data center investment forecast.
This “picks and shovels” rotation reveals the true anatomy of the boom.
1. The Landlords of the AI Age (Digital Real Estate)
Hyperscalers cannot permit and build facilities fast enough to meet their own timelines, forcing them into the arms of specialized real estate operators. Firms like Equinix and Digital Realty are leasing build-to-suit campuses before the concrete is even poured. In prime data center markets like Northern Virginia and Dublin, vacancy rates have plunged below 3%, giving landlords extraordinary pricing power and locking in high-margin, decade-long leases.
2. The Thermal Management Imperative
You cannot cool a 100-kilowatt AI rack with air. The thermal density of modern GPUs requires direct-to-chip liquid cooling and sophisticated immersion systems. This has vaulted previously unglamorous industrial engineering firms like Vertiv into the center of the technology ecosystem. The liquid cooling market, fundamentally non-existent at this scale five years ago, is growing at a compound annual growth rate (CAGR) of over 25%.
3. The Foundries and the Bottleneck
No matter how many chips Microsoft or Google design, they must physically be printed. Taiwan Semiconductor Manufacturing Company (TSMC) essentially holds a monopoly on the advanced packaging (CoWoS) required for top-tier AI chips. In turn, TSMC relies entirely on ASML for the Extreme Ultraviolet (EUV) lithography machines required to manufacture sub-7-nanometer chips. As Bloomberg recently highlighted, this highly concentrated supply chain is both the engine and the Achilles heel of the AI capex trillions 2031 trajectory.
Table: The AI Infrastructure Value Chain (2026 Projections)
| Sector | Core Function | Key Beneficiaries | 2026 Market Dynamics |
| Compute Silicon | Model training & inference processing | Nvidia, AMD, Custom ASICs | Constrained by advanced packaging (CoWoS) capacity. |
| Networking | High-speed data transfer between GPU clusters | Broadcom, Arista Networks | Shift from traditional copper to silicon photonics. |
| Physical Infrastructure | Colocation, land, and facility leasing | Digital Realty, Equinix | Near-zero vacancy in Tier 1 markets; soaring lease rates. |
| Thermal & Power | Liquid cooling, power distribution units | Vertiv, Schneider Electric | Transition from air-cooling to direct-to-chip liquid systems. |
Powering the Beast: The Terawatt Challenge
If there is a hard limit to the AI investment boom, it is not capital, and it is not silicon. It is the physics of electricity.
A standard data center consumes roughly the same amount of power as a small town. A gigawatt-scale AI campus, the likes of which are currently being proposed in the U.S. Midwest and the Middle East, consumes the equivalent of a major metropolitan city.
According to projections by Goldman Sachs Research, data center power demand will rise 165% by 2030, necessitating an estimated $720 billion in grid upgrades in the U.S. alone.
This presents a profound geopolitical and economic bottleneck. While you can expedite the manufacturing of a semiconductor, you cannot hack the permitting process for high-voltage transmission lines, nor can you “download” a nuclear reactor. The grid moves at the speed of bureaucracy, while AI moves at the speed of software.
Consequently, the big tech AI infrastructure boom is rapidly becoming an energy story. We are witnessing the unprecedented sight of tech companies signing long-term power purchase agreements (PPAs) with nuclear plant operators—such as Microsoft’s deal to revive a reactor at Three Mile Island, or Amazon’s acquisition of a nuclear-powered data center campus in Pennsylvania. In the race to $7.6 trillion, the ultimate victor may not be the company with the best algorithms, but the one that secures the most megawatts.
“The constraint on artificial intelligence is no longer algorithmic capability; it is base-load power. We are re-entering an era where energy abundance is the primary driver of digital supremacy.” — Lead Energy Analyst, Global Investment Bank]
The Bubble Question: Irrational Exuberance or Foundational Pivot?
With numbers this vast—$800 billion in 2026, $7.6 trillion by 2031—the specter of the year 2000 looms large. Is this a replay of the Dot-com telecom crash, where miles of “dark fiber” were laid across the ocean floor only to go unused for a decade as the companies that funded them went bankrupt?
The parallels are tempting, but fundamentally flawed.
During the Dot-com boom, infrastructure was built by highly leveraged upstarts reliant on speculative debt and venture capital. When the market turned, the debt crushed them. Today’s AI investment boom is being funded from the fortress balance sheets of the most profitable companies in human history.
As noted by The Economist’s recent analysis of Big Tech cash flows, the hyperscalers are largely funding this $800 billion buildout out of operational free cash flow. They are not borrowing at 7% to buy GPUs; they are reinvesting their dominant search, e-commerce, and enterprise software monopolies into the next paradigm.
Furthermore, unlike the speculative bandwidth of 2000, AI compute is fungible. If a specific AI startup fails, the underlying infrastructure (the GPUs, the data centers, the power contracts) retains immense value and can be instantly re-leased to another tenant running different workloads.
However, risks remain profound. If the cost of inference does not fall drastically, or if “killer applications” in enterprise productivity fail to materialize by 2027, Wall Street will demand a reckoning. Margins will compress, and the valuation multiples of the “picks and shovels” companies could experience a violent reversion to the mean.
Broader Implications: Geopolitics and the Road to 2031
As we look toward the projected $7.6 trillion total AI capex trillions 2031 milestone, the conversation shifts from economics to geopolitics. Compute is the new oil.
National governments have awakened to the reality that AI infrastructure is a sovereign imperative. A nation that relies entirely on foreign compute to run its healthcare system, optimize its grid, and manage its military logistics is fundamentally insecure. This is driving a secondary, state-sponsored AI investment boom, characterized by the rise of “Sovereign AI.”
Governments across Europe, the Middle East, and Asia are subsidizing domestic AI data centers and purchasing massive GPU clusters to ensure they control their own data and cultural narratives. This state-level intervention guarantees a floor for AI infrastructure demand, even if commercial enterprise adoption experiences temporary headwinds.
Concurrently, the U.S. and its allies are weaponizing the supply chain. Export controls on advanced semiconductors and semiconductor manufacturing equipment (SME) are designed to throttle the AI capabilities of strategic rivals. This geopolitical fragmentation ensures that the infrastructure boom will be geographically redundant and inherently inefficient—meaning it will require even more capital than a perfectly globalized market would dictate.
Conclusion: The Burden of the Future
The $800 billion expected to be deployed by hyperscalers in 2026 is a staggering sum, but it is merely the downpayment on a new industrial reality. The impact of AI investment on markets has already fundamentally altered the valuation of the semiconductor industry, revived the nuclear power debate, and transformed digital real estate into the world’s most coveted asset class.
As total investment marches toward $7.6 trillion by 2031, we must recognize that we are not simply building faster computers. We are constructing the central nervous system for the mid-21st century economy.
There will undoubtedly be cycles of boom and bust, moments of overcapacity, and spectacular localized failures. But the vector is clear. The companies pouring concrete and silicon into the ground today understand a brutal historical truth: in a technological revolution of this magnitude, the only thing more expensive than building the infrastructure is being the one left renting it.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


AI
Inside the White House Feud: How Trump’s Allies Are Painting Anthropic’s Dario Amodei as the Face of ‘AI Doomerism’
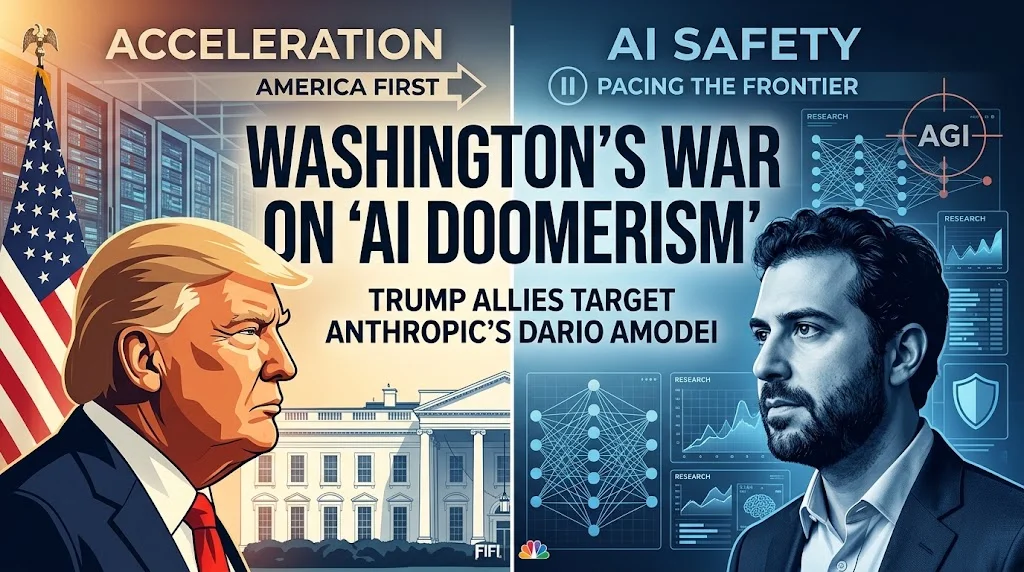
As tech leaders push for international safeguards at the UN, Washington’s inner circle is framing safety-first mandates as a direct threat to American innovation and global dominance.
A high-stakes battle over the future trajectory of artificial intelligence has moved from Silicon Valley boardrooms directly into the West Wing. Internal White House memos and statements from presidential advisers signal a concerted effort by political allies of President Donald Trump to target Anthropic CEO Dario Amodei as the primary architect of “AI doomerism.”
The ideological rift comes at a pivotal moment. While frontier AI executives call for cautious development in light of self-improving models, the Trump administration is doubling down on an “America First” accelerationist agenda, warning that safety-driven slowdowns will surrender geopolitical victory to foreign adversaries.
1. The Memo: Branding Effective Altruism as an “AI-Doom Pipeline”
At the center of the political offensive is a White House memo drafted by key political strategists. The document explicitly criticizes the philosophical underpinnings of Effective Altruism (EA)—a movement influential among Anthropic’s founding team that prioritizes mitigating existential risks from advanced technology.
According to sources familiar with the administration’s strategy, the memo outlines how safety-centric advocacy functions as an “AI-doom pipeline” that hampers domestic progress. One official close to the administration remarked that Amodei represents:
“The embodiment of an ideology and globalist approach to innovation that is fundamentally counter to the President’s America First agenda.”
This offensive reflects a broader effort to dismantle regulatory frameworks and third-party oversight mechanisms that administration officials view as disguised attempts to stall American market velocity.
2. Pacing the Frontier vs. “Don’t Kill the Golden Goose”
The campaign against Amodei follows a series of public warnings from Anthropic’s leadership. In a landmark essay, Amodei called on frontier labs to “pace the frontier” by committing to independent safety testing and slowing down deployment schedules when necessary, as detailed in reports by The Washington Post.
Amodei emphasized that recent breakthroughs in recursive self-improvement—where AI models are used to train and refine their own next-generation successors—require rigorous safety boundaries before systems exceed human control capacity, a point reiterated in coverage by TIME Magazine.
                 FRONTIER AI DEVELOPMENT SPECTRUM

   [ White House / Acceleration ]          [ Anthropic / Safety Pacing ]
  ─────────────────────────────────      ─────────────────────────────────
  • "Don't kill the Golden Goose"        • Third-party safety evaluations
  • Maximize speed & infrastructure     • Pause/Slow down if risk spikes
  • Unilateral advantage over China       • Multi-lateral coordination
In response, President Trump rejected calls to restrain the industry, lashing out at regulatory proposals and stating at the United Nations that the U.S. “rejects any attempt to construct a globalist scheme to control artificial intelligence,” according to reporting from LiveMint. Trump’s core stance remains straightforward: slowing down U.S. labs directly benefits China.
3. The China Dilemma and the UN Speech
The debate reached global prominence during the United Nations General Assembly, where Dario Amodei, OpenAI CEO Sam Altman, and other tech leaders addressed world leaders on catastrophic risks, as covered by The Guardian.
Amodei argued that while Chinese technological parity poses an existential geopolitical hazard, unmonitored recursive models pose an equal operational threat:
| Policy Dimension | Administration Alignment | Anthropic Alignment |
| Primary Goal | Outpace China at all costs | Ensure safety while maintaining lead |
| Governance Mechanism | Deregulation & domestic industrial builds | Third-party audits & safety benchmarks |
| Global Frameworks | Strongly Rejected (“Globalist scheme”) | Advocated (International safety standards) |
| Perspective on Speed | “Don’t kill the Golden Goose” | “Pacing the frontier” when risks escalate |
Prominent right-leaning technology leaders, including administration AI adviser David Sacks, pushed back on social media, questioning the independence of non-profit safety bodies like Model Evaluation and Threat Research (METR) and claiming they are closely aligned with Anthropic’s leadership network.
4. What Lies Ahead for AI Policy
The clash between Washington and San Francisco highlights a fundamental divergence in how the future of artificial intelligence is conceived:
- Industrial Policy Push: The White House is pushing forward with fast-tracked data center permitting, energy deregulation, and aggressive chip export controls to secure an insurmountable lead over Beijing.
- Corporate Safety Mandates: Frontier labs face internal pressure from researchers demanding strict adherence to safety protocols, creating tension between market pressure to deploy and institutional safety commitments.
- The Regulatory Vacuum: With federal legislative action stalled, the conflict between presidential executive action and voluntary lab commitments will dictate the pace of AI releases through the rest of the decade.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Is the AI stock rally a bubble? The honest answer in 2026 is that the market itself is genuinely split — and the concentration numbers explain why the debate has gotten so intense. Roughly two dozen stocks now account for over half of the S&P 500’s total value, a concentration level comparable to the 32-stock peak reached during the 2000 dot-com bubble, according to market analysis relayed through Charles Schwab’s commentary. Three companies alone — Alphabet, Amazon, and Meta — are expected to drive roughly 70% of the S&P 500’s entire 2026 earnings growth.
That’s the bear case in a single statistic: an index marketed to investors as broadly diversified across 500 companies is, in practice, a leveraged bet on whether a handful of AI infrastructure spenders convert capital expenditure into earnings fast enough to justify their valuations.
The Bull Case: Spending Is Turning Into Real Revenue
Featured Snippet Target: The bull case for 2026’s AI rally rests on genuine, verifiable revenue growth rather than pure speculation — Microsoft’s AI revenue run rate surpassed $37 billion annually, Alphabet’s Google Cloud backlog nearly doubled to over $460 billion, and Amazon Web Services grew 28% — figures that distinguish this cycle from dot-com-era companies that had capital spending but little corresponding revenue.
Alphabet spent $35.67 billion on capital expenditure in a single recent quarter — more than double the prior year’s pace — while Amazon led hyperscaler quarterly spending at $44.2 billion, according to reporting compiled by Yahoo Finance’s technology desk. Combined, the four largest U.S. hyperscalers — Alphabet, Amazon, Microsoft, and Meta — are on pace to spend over $700 billion in 2026 alone. Unlike the fiber-optic overbuild of the dot-com era, where telecom capacity sat unused for years, current AI infrastructure spending is being absorbed by measurable, growing cloud and AI-service revenue in the same reporting periods it’s being deployed.
The Financing Shift That’s Making Analysts Nervous
What has shifted the debate in recent months isn’t the spending itself — it’s how that spending is being funded. Goldman Sachs has characterized 2026 as marking a transition from a low-cost-of-capital “Modern” market cycle to a higher-volatility “Post-Modern” one, in which capital expenditure is increasingly rewarded over shareholder buybacks: S&P 500 companies posted 24% year-on-year capex growth in the second quarter of 2026 alongside a 1% decline in gross buybacks, according to market commentary circulated via KuCoin’s research desk.
Consensus hyperscaler capex estimates for the 2026-2028 period were revised upward from roughly $2.5 trillion to $2.8 trillion during recent earnings seasons, with gross debt issuance among these companies expected to peak near $460 billion in fiscal 2028 — roughly a third of total capex — according to Macquarie’s Investment Strategy Insights. Alphabet’s own June 2026 equity raise, combining Class A common stock, Class C capital stock, and mandatory convertible preferred shares, ranks as the largest single AI-funding capital raise in market history. That shift — from funding AI buildout purely from operating cash flow toward relying on debt and equity markets — is precisely the kind of financing pattern that historically precedes sharper corrections when growth expectations disappoint, even when the underlying business fundamentals remain genuinely strong.
Early Cracks Have Already Appeared
The market has not been uniformly bullish through 2026 — there have already been real bouts of AI-specific volatility. Mid-September commentary from CNBC noted bond yields spiking and AI-linked stocks selling off even as broader investor sentiment remained constructive on equities generally — an early signal that markets have begun pricing a wider range of outcomes for the AI capex cycle than the largely unbroken bull run of the year’s first half suggested. That divergence between AI-specific stocks and the broader market is itself notable: in a genuine across-the-board bubble, sentiment tends to move in lockstep across a sector; a split reaction suggests investors are starting to differentiate between AI companies converting spending into revenue and those merely riding sector-wide enthusiasm.
What Would Actually Confirm a Bubble
The distinction analysts increasingly draw is not “is there a lot of spending” — there unambiguously is — but whether that spending is converting into durable revenue at a pace that justifies current valuations. The genuinely bubble-confirming scenario would involve a sustained gap opening between hyperscaler capex growth and actual AI-linked revenue growth, forcing companies to either write down infrastructure investments or continue raising debt at deteriorating terms to sustain spending. As of September 2026, revenue growth at the largest hyperscalers has generally kept pace with — and in some cases exceeded — capex growth, which is the key data point separating this cycle from a pure speculative bubble so far.
The Bottom Line
The 2026 AI trade sits in a genuinely ambiguous middle ground: spending levels and market concentration have reached bubble-era extremes by historical comparison, but the revenue being generated alongside that spending remains real and, so far, largely justifies it. The financing shift toward debt — rather than the spending level itself — is the single most important variable to watch, because it introduces a genuine failure mode (refinancing risk, credit-market stress) that pure equity-funded capex would not carry. Neither the unambiguous bull case nor the unambiguous bubble case is fully supported by the data as it stands; both remain live possibilities depending on how the next several quarters of hyperscaler earnings play out.
Next step: Track the spread between hyperscaler capex growth rates and their AI-linked revenue growth rates each earnings season — a widening gap, more than any single stock’s valuation multiple, would be the clearest confirming signal that 2026’s AI rally has crossed from justified investment into unsustainable bubble territory.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
How big is the AI chip industry in 2026? Global semiconductor revenue is projected to exceed $1.3 trillion in 2026 — a 64% increase and the fastest growth the industry has recorded in more than 20 years, according to research firm Gartner. That would mark a third consecutive year of double-digit growth for the sector, driven by surging demand for AI processing, data-center infrastructure, and rising memory prices, per Gartner senior principal analyst Rajeev Rajput.
That single statistic captures why “technology news” in 2026 is really one story told through dozens of companies: an unprecedented, sustained capital-spending cycle built around artificial intelligence infrastructure.
Hyperscalers Are the Engine
The chip boom is being funded almost entirely by a handful of technology giants. Alphabet, Amazon, Microsoft, and Meta — the hyperscalers building the cloud infrastructure that AI models run on — have collectively committed more than $700 billion in 2026 capital spending, according to reporting relayed through Yahoo Finance’s technology desk. Alphabet alone spent $35.67 billion on capital expenditure in a single quarter — more than double the prior year’s pace — while its Google Cloud backlog nearly doubled to over $460 billion. Amazon led quarterly spending at $44.2 billion as AWS grew 28%, and Microsoft’s fiscal third-quarter capex rose 84% year-over-year to $30.88 billion as its AI revenue run rate surpassed $37 billion annually.
Featured Snippet Target: The four largest U.S. hyperscalers — Alphabet, Amazon, Microsoft, and Meta — are on pace to spend over $700 billion combined on AI infrastructure in 2026, a figure Reuters’ Morning Bid podcast described as rising “all the time” and directly responsible for surging demand for AI chips and data-center equipment.
That spending has increasingly shifted from being funded purely by operating cash flow to relying on debt and equity markets. Alphabet’s June 2026 equity raise — combining Class A common stock, Class C capital stock, and mandatory convertible preferred shares — ranks as the largest single AI-funding capital raise in market history, according to market commentary circulated via KuCoin’s research desk. Goldman Sachs has characterized this as a structural shift from a low-cost-of-capital “Modern” cycle to a higher-volatility “Post-Modern” one, in which markets increasingly reward capital expenditure over share buybacks — S&P 500 companies posted 24% year-on-year capex growth in the second quarter of 2026 alongside a 1% decline in gross buybacks.
Nvidia’s Next Move — and Who’s Chasing It
Nvidia remains the chip industry’s dominant supplier, and its next-generation product cycle is central to 2026’s technology narrative. The company introduced its Rubin CPX GPU — built for massive-context AI workloads capable of handling million-token software coding and generative-video tasks — with availability expected by the end of 2026, according to trade coverage from DigiTimes. Competitors are racing to diversify the supply chain around Nvidia’s dominance: AMD is preparing new product launches with OpenAI as a customer, Broadcom and OpenAI are targeting mass production of custom AI silicon in 2026, and Broadcom separately secured a $10 billion custom-chip production order from a major new customer, according to the same industry reporting.
China’s chip ecosystem is developing along a parallel, more insulated track. Huawei and Cambricon Technologies are together projected to ship over a million AI chips by 2026, with JPMorgan forecasting Huawei alone shipping 600,000 to 650,000 units, as Beijing pushes to reduce reliance on U.S.-made chips amid ongoing export restrictions.
Where the Growth Is Concentrated
Analysts covering the sector point to datacenter accelerators as the single largest growth pocket within the broader chip market — that segment alone is projected to exceed $300 billion in 2026, according to industry analysis from TechInsights, with knock-on effects spanning process technology (including the industry’s push toward 2-nanometer manufacturing), advanced packaging techniques, and power infrastructure needed to run increasingly energy-intensive AI data centers.
That last point — power — has become a genuine bottleneck rather than a footnote. Industry commentary increasingly frames electricity supply and cooling capacity, not chip fabrication itself, as the binding constraint on how quickly AI infrastructure can scale, positioning data-center operators and power-infrastructure companies as unexpected beneficiaries of the AI boom alongside the chipmakers themselves.
The Risk Beneath the Boom
Not every voice in the technology sector is unreservedly bullish on the pace of spending. Analysis circulated through Charles Schwab’s market commentary notes that three hyperscalers — Alphabet, Amazon, and Meta — now account for roughly 70% of the S&P 500’s expected 2026 earnings growth, meaning the index’s apparent 500-company diversification offers less real downside protection than investors might assume if AI capital spending fails to convert into earnings at the pace currently priced in.
That concentration risk has already produced volatility. Mid-September market commentary from CNBC noted bond yields spiking and AI-linked stocks selling off even as broader investor sentiment stayed constructive on equities overall — an early signal that markets are starting to price a wider range of outcomes for the AI capex cycle than the unbroken bull run of the year’s first half suggested.
The Bottom Line
Technology news in 2026 is dominated by a single, self-reinforcing cycle: hyperscaler capital spending is driving record semiconductor demand, chipmakers are racing to keep pace with that demand through new architectures and expanded manufacturing, and financial markets are increasingly rewarding — and increasingly questioning — the sustainability of spending at this scale. Whether that questioning turns into a genuine correction depends on whether AI infrastructure investment converts into earnings growth fast enough to justify the capital already committed.
Next step: Track quarterly hyperscaler capex guidance alongside chipmaker order backlogs — the gap between the two, more than any single product launch, is the clearest early signal of whether 2026’s AI infrastructure boom is accelerating or beginning to plateau.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Apply for a Bank Account Online: What You Need and How Long It Actually Takes

World’s Largest Economies: Ranking the Top Global Powers

Business Loan: A Complete 2026 Guide to Rates, Types, and Qualifying

Fast Invoice Factoring: How to Turn Unpaid Invoices Into Cash Within 24 Hours

Investment Banking Services: What They Cost and How to Choose the Right Firm in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025