
Industory
Here’s How Much It’ll Cost You to Be Part of SpaceX’s Record-Breaking $75 Billion IPO

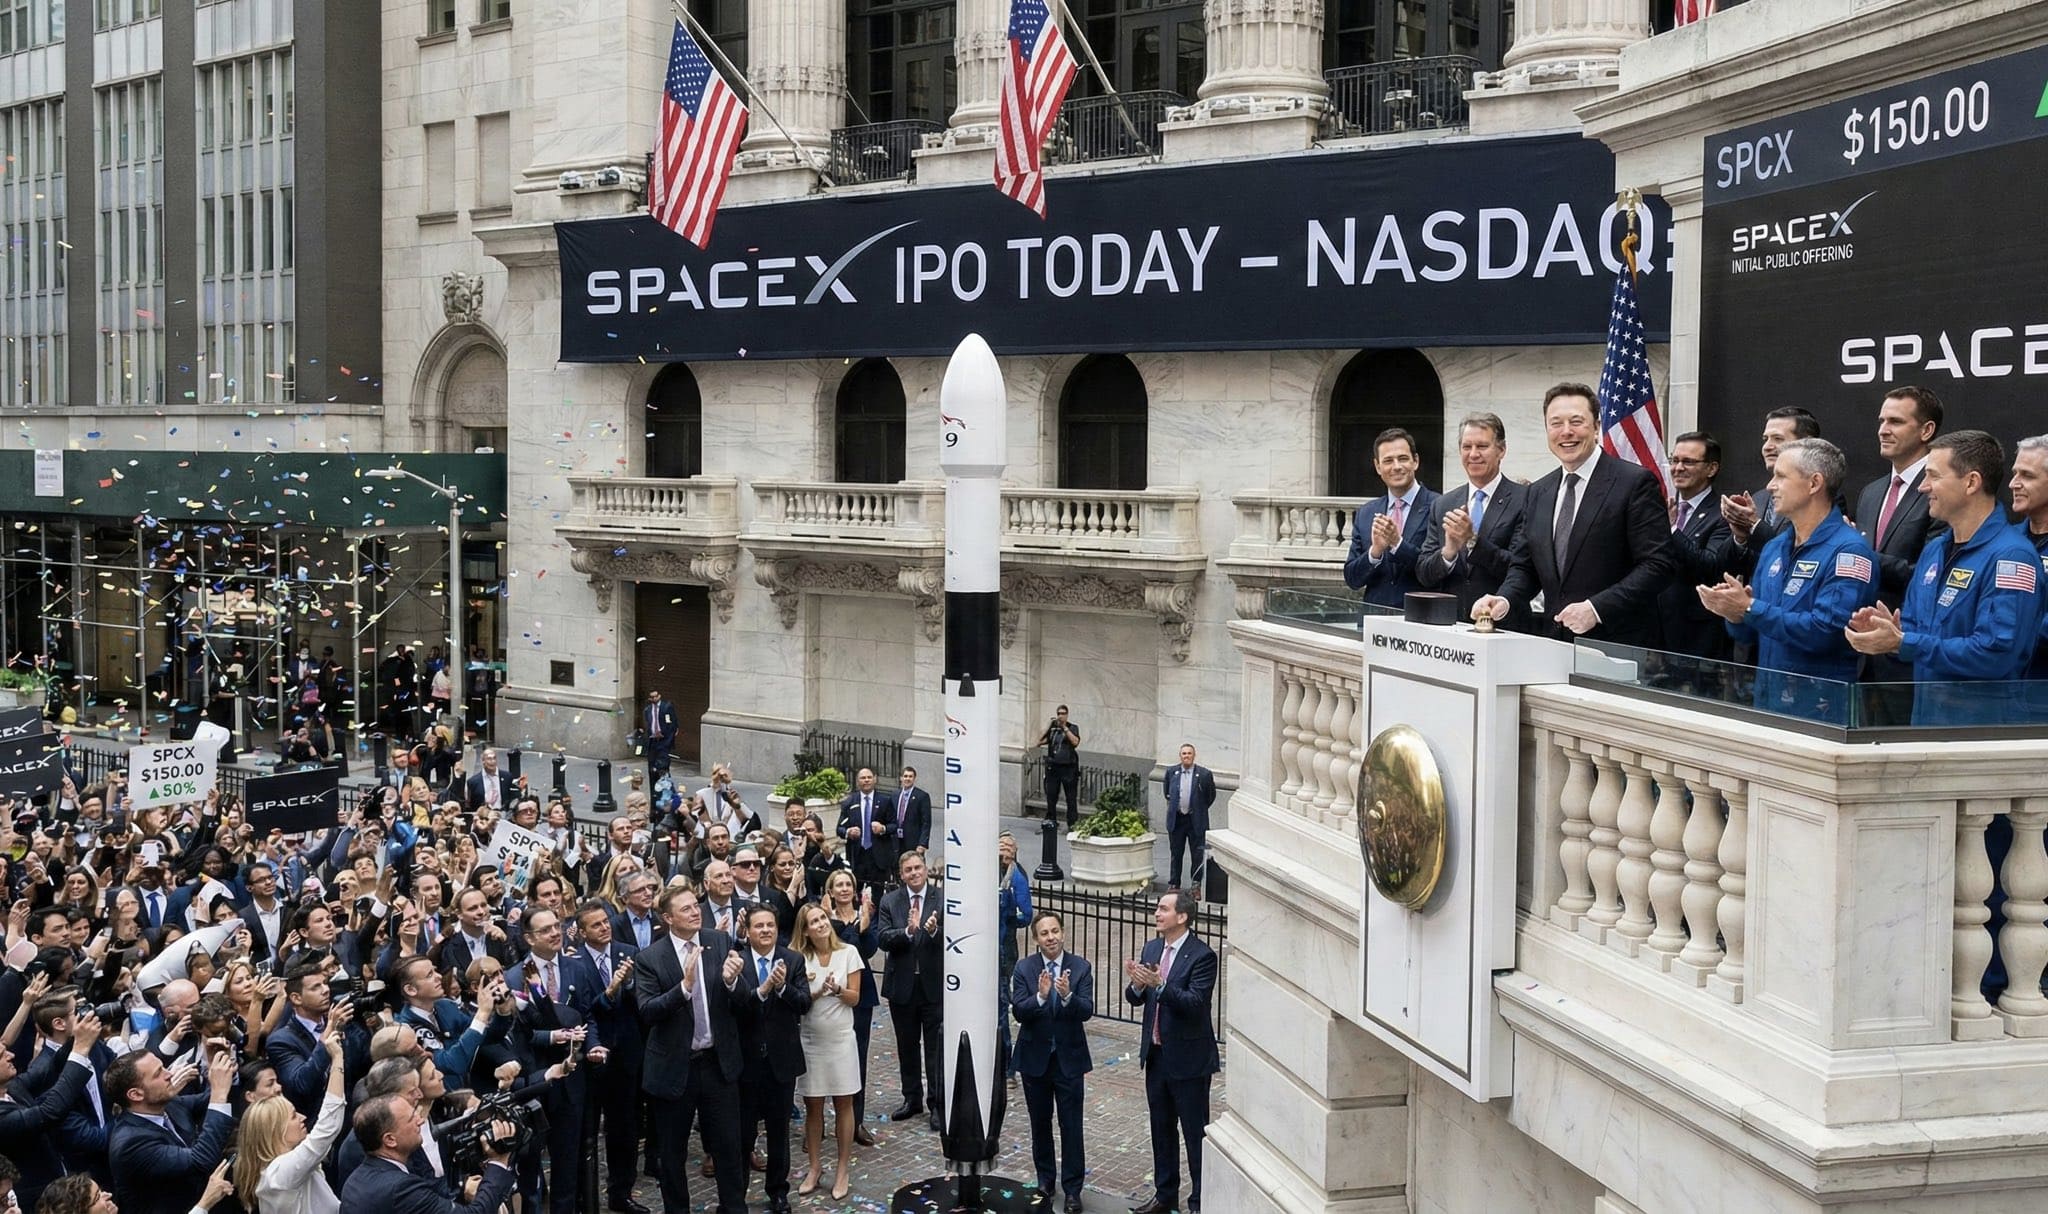
The number that matters most arrived late on Tuesday.
Reuters reported that SpaceX plans to raise $75 billion by selling 555.6 million shares at $135 per share, implying a valuation of $1.75 trillion to $1.8 trillion — making it, by almost any measure, the largest initial public offering in the history of capital markets. Not the largest tech IPO. Not the largest American IPO. The largest, full stop. Pricing is June 11. Trading opens on Nasdaq under SPCX on June 12. If you’ve been waiting for a number to work with, you have one now: $135 a share. StocktwitsChatForest
That figure defines who gets in, who gets squeezed out, and exactly what kind of bet you’re making if you click “buy.”
The Moment That Changed Everything
For most of its 24-year history, SpaceX operated as a deliberately opaque private company. Elon Musk saw no reason to open the books, and institutional capital was happy to keep filling the coffers through tender offers and secondary transactions. The most recent of those, in December 2025, priced shares at approximately $421 each, implying a valuation of roughly $800 billion. Then came the xAI merger in February 2026, the confidential S-1 filed on April 1, and suddenly the calculus shifted. SpaceX filed its initial public offering with the SEC in May 2026, seeking to raise more than $75 billion. BitMEXThe Motley Fool
The context matters. This offering lands in a market already primed for mega-listings, with OpenAI and Anthropic both reportedly targeting public debuts before year-end. But nothing in that queue comes close to SpaceX’s scale. The current IPO record is held by Saudi Aramco, which raised $29.4 billion when it went public in 2019. SpaceX’s planned offering would surpass that by more than 2.5 times. Alibaba’s $22 billion U.S. record from 2014 isn’t even in the conversation. The $135 share price isn’t just a number — it’s the entry ticket to what many are calling a generational market event, and understanding exactly what you’re paying for requires reading more than the headline. Crypto Briefing
How Much Will SpaceX IPO Shares Actually Cost You?
At $135 per share — the price point Reuters reported the company is targeting for its 555.6 million-share offering — the minimum cost of participation is theoretically one share. In practice, the economics are more complicated. Stocktwits
SpaceX says in its prospectus that certain Class A shares are expected to be offered to retail investors through Charles Schwab, Fidelity Brokerage Services and Fidelity Capital Markets, Robinhood Financial, SoFi Securities, and E*Trade by Morgan Stanley via their online brokerage platforms. That’s the good news. The less comfortable truth is that each of those platforms carries different access thresholds. BeInCrypto
For the SpaceX IPO, investors must have a minimum account balance of $100,000 to participate through Charles Schwab. Robinhood’s bar is lower — Robinhood has offered IPO access to all users through its IPO Access feature with no minimum balance requirement, though allocations are not guaranteed and are typically small for high-demand offerings. Fidelity and SoFi sit somewhere in between, each with their own eligibility checks and suitability questionnaires designed to satisfy FINRA guidance. The Motley FoolBASENOR
Yet the per-share price only tells part of the story. The real question is whether you’ll receive any allocation at all. One of the most notable features of the planned offering is a retail investor allocation of up to 30% of available shares — roughly three times the typical Wall Street norm. On a $75 billion raise, that translates to roughly $22.5 billion earmarked for individual investors. SpaceX CFO Bret Johnsen has said: “Retail is going to be a critical part of this and a bigger part than any IPO in history.” Tech InsiderChatForest
Still, the math cuts both ways. If retail demand collectively requests $100 billion worth of shares — entirely plausible given the hype — against a supply of $22.5 billion, the fill rate is roughly 22.5 cents per requested dollar. Submit a $1,350 indication of interest for ten shares, and you might receive two. Submit nothing, and you’ll be buying on the open market at whatever premium day-one trading delivers. ChatForest
The distribution architecture is layered deliberately. Bank of America will target high-net-worth U.S. individuals; Morgan Stanley via E*Trade will handle smaller retail buyers. UBS and Citi will handle international retail and institutional distribution. Goldman Sachs leads the entire syndicate of 23 underwriting banks — a structure designed both to maximise geographic reach and to give Musk’s populist instincts institutional scaffolding. mexc
What You’re Actually Buying — And What You’re Not
The SpaceX IPO retail investor cost is $135 per share. What that purchases, however, is more specific than owning a piece of the company you’re imagining.
The S-1 confirms Class A shares carry standard one-vote-per-share rights, while insiders hold Class B shares with 10 votes each. Musk holds 85.1% of combined voting power through this dual-class share structure. Buying at $135 gives you economic rights — a claim on future earnings and any dividends — but essentially no governance influence. SpaceX is a bet on Musk’s continued judgment, not a vehicle for shareholder input. Those are different things, and the distinction matters more at a $1.75 trillion valuation than it would at $175 billion. Thevccorner
What the valuation is actually pricing requires careful unpacking. For fiscal year 2025, SpaceX reported $18.67 billion in consolidated revenue, with adjusted EBITDA of $6.58 billion. But the net loss was $4.9 billion. For context: the SpaceX IPO 2026 valuation target of $1.75 trillion implies approximately 109 to 116 times trailing 2025 revenue. On 2026 forward revenue projections of $27 to $30 billion, the multiple compresses to 58 to 65 times. The Tech MarketerThe Tech Marketer
What does a People Also Ask question look like here? Let’s answer it directly.
What is SpaceX’s valuation at IPO, and what does it mean for investors?
SpaceX is targeting a listing valuation of $1.75 trillion, implying roughly 94 to 110 times trailing annual revenue of $18.7 billion. At $135 per share, the company would be among the ten most valuable public entities on Earth from its first trading day — pricing in growth scenarios that extend years into the future, anchored by Starlink’s profitability and the contested promise of the xAI division.
The Starlink business is the core that justifies the floor. Starlink contributed $11.4 billion of SpaceX’s 2025 revenue — 61% of the total. That’s a real, recurring, cash-generating subscription business serving millions of users globally. The xAI division, absorbed in the February 2026 merger, is the speculative ceiling — the company posted a $4.28 billion net loss in Q1 2026 alone, alongside an accumulated deficit of $41.3 billion. BitMEXBitMEX
The Second-Order Effects No One Is Pricing In
There is one dimension of this IPO that most retail participants aren’t thinking about, and it could matter far more than whether you receive your allocation at $135.
Due to a Nasdaq index rule revision effective May 1, 2026, SpaceX will automatically enter the Nasdaq 100 Index on its 15th trading day — roughly July 6. That means every index fund tracking the Nasdaq 100 — every retirement account holding QQQ, every passive ETF, every institutional allocation that benchmarks to the index — will be mechanically forced to buy SPCX whether the fund manager wants to or not. The scale of that auto-buy pressure is difficult to quantify precisely, but it’s measured in the tens of billions of dollars. Passive investors who don’t participate in the IPO will own SpaceX anyway, inside their existing holdings, within weeks of listing. Tradingkey
This structural demand floor changes the conventional IPO calculus. The typical post-listing fade that follows a hyped offering — the window when patient investors buy the dip while momentum chasers exit — may be compressed or eliminated entirely by index inclusion buying. That’s a genuine consideration for investors assessing whether $135 is expensive or merely the starting point.
What it also creates is a perverse outcome for those who expressly don’t want exposure. If you hold a broad Nasdaq index fund and believe SpaceX’s valuation is untenable, your only clean exit is to actively reduce your index position — which most passive investors won’t do. SpaceX at $1.75 trillion isn’t just an IPO. It’s a reweighting of the entire Nasdaq.
The Case Against $135
The bull case writes itself: Starlink is a profitable monopoly on space-based internet, Starship rewrites the economics of heavy-lift launch, and the xAI division could become an AI infrastructure layer that generates revenue no one has yet modelled. That’s the story being sold on the roadshow.
The bears have their own numbers. Near $2 trillion, buyers would be paying one of the steepest valuations ever assigned to a company that doesn’t yet turn a profit on a consolidated basis, and whose one money-maker is watching its per-user revenue shrink. Jay Ritter, the IPO expert at the University of Florida whose research spans four decades of listing data, notes that large IPOs have historically underperformed the S&P 500 in the years following listing. Saudi Aramco, the previous record IPO, traded below its IPO price for extended periods. The Motley FoolBackpack Exchange
The comparison to Saudi Aramco is instructive in a way that gets underplayed. Aramco was profitable, asset-heavy, and priced into a market that understood its core business intimately. SpaceX is loss-making on a GAAP basis, integrating a recently acquired AI company, and asking investors to price in a $26.5 trillion total addressable market — a figure SpaceX describes as “the largest actionable TAM in human history,” encompassing space services, AI infrastructure, enterprise software, and digital advertising. Whether that TAM is visionary or promotional depends entirely on your conviction about Musk’s execution over the next decade. It is not a number anyone can verify today. Thevccorner
There is also the float problem. Morningstar’s Franco Granda flagged the structural concern, projecting 20% to 30% stock swings versus Tesla’s 10% to 15%, because of a thin float of 3% to 4%. Less paper for sale means more violent moves — in both directions. Retail investors who buy at $135 and face a 25% drawdown in the first weeks of trading will need genuinely long time horizons to absorb it. Yahoo Finance
The Calculation You Actually Have to Make
At $135 a share, the SpaceX IPO is accessible in theory and rationed in practice. The platforms are real, the retail allocation is historically unprecedented, and the listing date of June 12 is nine days away as this article is written.
Yet the number that deserves the most scrutiny isn’t $135. It’s $1.75 trillion. That’s the valuation at which a profitable satellite business, a loss-making AI division, and an extraordinarily capital-intensive rocket programme are being bundled and sold as a single story. Starlink earns the valuation it’s been assigned. The rest requires faith.
What Musk has understood, from Tesla to SpaceX, is that faith is a legitimate market force. Investors who bought Tesla in 2010 and held didn’t do so because the discounted cash flow models supported it. They did so because they believed a particular individual could reshape an industry, and they were right. The SpaceX IPO is asking you to make the same bet, at a valuation twenty times larger, on a company that spans rockets, satellites, and artificial intelligence simultaneously.
$135 is the cost of entry. Whether that’s the opportunity of a generation or the peak of a cycle is the question the roadshow won’t answer for you.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Paris and Berlin have reached a pivotal automotive compromise. Its implications extend well beyond tariffs, raising difficult questions about manufacturing, technology, jobs, trade alliances and the future of affordable electric vehicles.
Europe’s automotive confrontation with China is entering a more consequential phase. Having imposed tariffs on Chinese-made electric vehicles, the European Union is now moving toward a policy that could influence not only where cars are sold, but also where their components are manufactured, their batteries are sourced and their technology is developed.
A new Franco-German agreement announced on October 16 seeks to strengthen European production through stricter Made in Europe requirements while offering greater flexibility on vehicle emissions.
For Chinese manufacturers such as BYD, Chery, Xpeng and Changan, the message is increasingly difficult to ignore: access to European customers may remain open, but access to European industrial incentives could become dependent on making a substantially greater economic contribution within the region.
The agreement represents a political breakthrough between Europe’s two largest economies. But it is not yet binding EU legislation, and crucial details remain subject to negotiation.
According to Reuters’ October 16 report, Germany and France must secure support from other EU governments and the European Parliament before their proposals can take effect.
The stakes are considerable. Europe’s automotive industry supports extensive manufacturing and supplier networks, while Chinese companies increasingly regard the continent as an important destination for overseas expansion.
The central question is no longer simply whether Chinese electric vehicles can compete in Europe. It is whether European policy can preserve industrial value without undermining competition, investment and the transition to cleaner transport.
What Germany and France Have Agreed
At the centre of the compromise is a narrower definition of what constitutes a European-made vehicle for specified public financial support and government procurement.
The French and German position builds on the European Commission’s Industrial Accelerator Act, proposed on March 4, 2026.
That initiative seeks to strengthen domestic industrial capacity by linking certain subsidies, procurement decisions and investment incentives to European production and lower-carbon manufacturing.
Under the latest Franco-German approach, qualifying automotive production would primarily cover the EU’s 27 member states. Some closely integrated European partners could participate under additional conditions.
Reporting by Euronews identifies a proposed threshold requiring 70% European-origin components, excluding batteries, alongside European battery-content conditions.
The October agreement also points toward stronger expectations for research and development in Europe.
Three elements deserve particular attention.
First, assembling a vehicle in Europe may not be enough. The value of its components and the structure of its supply chain could determine whether it qualifies for public incentives.
Second, battery sourcing matters separately. European policymakers want more of the economic value generated by electric vehicles—including battery technology and manufacturing—to remain within the region.
Third, engineering and research could become part of industrial eligibility. A factory that assembles imported components offers a different economic contribution from a facility supported by local suppliers, researchers and engineering teams.
Reports on the Franco-German position indicate a potential 2028 implementation horizon for key automotive sourcing conditions. However, eligibility calculations, transitional arrangements and research requirements remain unsettled.
These distinctions matter because the new framework would not automatically prohibit the sale of foreign vehicles. Instead, it could affect which vehicles benefit from specified public support.
Why Germany and France Reached a Compromise
France and Germany share concerns about competition from Chinese manufacturers, but their approaches to industrial policy have not always aligned.
France has consistently advocated a stronger European preference in industrial subsidies and public procurement. Its argument is that public spending should support production, investment and employment within Europe.
Germany has traditionally placed greater emphasis on maintaining internationally integrated supply chains and protecting established automotive manufacturers from abrupt regulatory change.
German brands depend on extensive supplier relationships and sell vehicles in international markets, including China. Policies designed to restrict Chinese competition could also complicate their own global operations.
The October compromise connects these industrial interests with a politically sensitive question: the EU’s vehicle emissions framework for 2035.
Under the joint position, the proposed 2035 emissions target would be a 90% reduction from 2021 levels, without requiring manufacturers to compensate for the remaining 10% through additional measures.
That offers greater flexibility than the European Commission’s earlier proposal.
Reuters reported that European automotive shares advanced following the agreement, while Volkswagen welcomed the prospect of stronger incentives for European manufacturing.
The political bargain is therefore clear.
Germany gains greater flexibility over future automotive technologies. France gains stronger support for European industrial preferences.
Yet neither outcome is guaranteed. Other EU institutions and member states retain a role in determining the final rules.
China’s Expanding Automotive Presence Explains Europe’s Urgency
The debate is taking place against an extraordinary transformation in international vehicle trade.
China has become the world’s largest vehicle exporter, with domestic manufacturers expanding across electric vehicles, plug-in hybrids and conventional models.
European companies remain major global manufacturers. Yet Chinese competitors have demonstrated increasingly strong capabilities in battery technology, software integration, manufacturing scale and price competitiveness.
The latest Eurostat figures, published October 13, show that China accounted for 42% of the EU’s electric-car imports in 2025.
That figure measures China’s share of imported electric cars, not its share of all vehicles sold in the EU—a distinction that is essential for interpreting the market.
The same Eurostat release shows that:
- EU imports of electric and hybrid cars reached €45.1 billion in 2025.
- Exports of these vehicles totaled €64.7 billion.
- Almost 4.8 million hybrid and electric cars were produced in the EU.
- Hybrid and electric models accounted for nearly 40% of EU car production.
These numbers demonstrate that Europe is not a passive participant in the electric-vehicle transition. It retains substantial production capabilities and an important export position.
But its manufacturing base faces intense competition over costs, batteries and future technologies.
China’s domestic market conditions provide an additional reason for its automakers to expand overseas.
According to Associated Press reporting on October 12, Chinese passenger-vehicle exports increased 64% year over year in September 2026, reaching approximately 919,000 units.
Weakness in domestic demand has made foreign markets particularly important for Chinese carmakers.
Europe consequently faces two interconnected pressures: a wave of increasingly competitive imports and the need to attract long-term investment into its own automotive industry.
The Three Layers of Europe’s New Automotive Trade Strategy
Europe’s emerging approach combines existing tariffs, restrictions on certain imports and proposed local-production incentives.
Understanding the differences is essential.
1. Existing tariffs on Chinese battery-electric cars
In October 2024, the European Commission imposed additional countervailing duties on battery-electric vehicles manufactured in China following an anti-subsidy investigation.
The definitive rates included:
| Manufacturer | Additional countervailing duty |
|---|---|
| BYD | 17.0% |
| Geely | 18.8% |
| SAIC | 35.3% |
| Tesla’s Shanghai production | 7.8% |
These are additional countervailing duties, not necessarily the complete applicable import-tariff burden.
The duties were introduced to address subsidy-related injury concerns identified by the Commission. They are distinct from the proposed Made in Europe requirements.
The legal basis and company-specific rates appear in the EU’s definitive countervailing duty regulation.
2. New restrictions on hybrid-vehicle imports
Chinese manufacturers responded to the earlier battery-electric tariffs partly by expanding sales of hybrid vehicles.
Brussels and Beijing subsequently reached an agreement aimed at limiting Chinese-built hybrid imports.
On October 12, Reuters reported that the EU and China had agreed on an initial annual limit of 350,000 hybrid vehicles, with the volume allowed to increase by 6% annually.
The safeguard arrangement is intended to last four years and would apply to other trading partners under its broader framework.
Its precise implementation remains important, particularly for companies planning European sales and production.
3. Proposed incentives favouring European manufacturing
The third layer is potentially the most transformative.
Unlike import duties or quotas, local-content requirements influence investment decisions inside the European economy.
A Chinese-owned company that establishes genuine manufacturing operations within the EU could potentially qualify under the relevant rules if its vehicles meet the applicable component, battery and other eligibility conditions.
This means the policy distinguishes between the location of production and the nationality of the corporate owner.
That distinction could fundamentally change Chinese automakers’ strategies.
How BYD, Chery, Xpeng and Changan Could Respond
Chinese manufacturers are not approaching this policy shift without preparation.
Many have already started building or developing European production capacity.
Reuters reported on October 13 that several major Chinese manufacturers were accelerating local manufacturing, engineering and supplier partnerships before the rules were finalized.
BYD: From vehicle exports toward European production
BYD has pursued overseas manufacturing expansion, including investment in Hungary.
European production could reduce reliance on imports from China and provide a more durable base for growth.
However, a European assembly plant would not automatically satisfy the proposed sourcing requirements.
The company would also need to evaluate where batteries, electronics, motors and other vehicle components originate.
The economic calculation is straightforward but demanding: local production may improve regulatory resilience while adding new capital expenditure and operating costs.
Chery: Building a localized industrial strategy
Chery has emphasized European production and local engineering capabilities.
For the company, establishing relationships with European component manufacturers could become as important as developing competitive models.
Such partnerships can provide access to technical capabilities, distribution networks and manufacturing expertise.
But integrating an international supplier base takes time, especially when production schedules and regulatory standards are evolving.
Xpeng: Partnerships as a route to market
Xpeng provides another example of how Chinese manufacturers can enter Europe without relying exclusively on new, wholly owned factories.
Reuters reported that Magna was already building electric vehicles for Xpeng in Austria.
Contract manufacturing can accelerate market access by using established production facilities.
Yet the proposed rules suggest that production location alone may be insufficient. Component sourcing and potentially research activity could become important additional considerations.
Changan: A longer-term European commitment
Changan has outlined ambitious plans for European production.
According to Reuters, the company is targeting production capacity of 180,000 vehicles annually in Europe by 2028 and 350,000 by 2030.
These are company targets rather than achieved production figures.
If implemented successfully, they would demonstrate how Chinese manufacturers can respond to trade restrictions by becoming increasingly embedded in Europe’s industrial ecosystem.
The broader implication is striking: policies intended to protect European manufacturing may also attract greater investment from Chinese competitors.
That could create European jobs while intensifying competition for established local brands.
The 70% Rule Could Transform Automotive Supply Chains
The most economically important feature of the proposed framework may be the component-value requirement.
Automotive production depends on complex international networks supplying batteries, semiconductors, electronic systems, transmissions, motors and other components.
A car sold as European-made can contain substantial imported value.
The proposed 70% threshold for non-battery components would therefore affect procurement decisions throughout the industry.
Manufacturers seeking to qualify for particular subsidies could need to purchase more components from EU suppliers or reorganize existing production networks.
For European parts manufacturers, this could create significant commercial opportunities.
For automakers, however, the transition may prove expensive.
A company might need to replace an efficient international supplier with a local alternative that initially has higher costs or limited production capacity.
The result could be higher short-term manufacturing expenses, even if additional investment eventually improves European competitiveness.
There is also a longer-term industrial benefit to consider.
Component factories generate more than direct employment. They support specialist engineering, machinery purchases, logistics services and technical training.
If local-content rules encourage these activities, the economic gains could extend beyond individual assembly plants.
But the outcome depends on whether European suppliers can achieve competitive costs and reliable production at scale.
Protection alone cannot guarantee industrial efficiency.
Why Britain, Turkey, Japan and South Korea Are Concerned
The emerging definition of Europe presents a challenge for countries with automotive industries closely connected to EU manufacturers.
Britain has historically been deeply integrated into European automotive production.
Turkey is another important manufacturing partner, supplying vehicles and components through longstanding commercial relationships.
Japan and South Korea are major automotive investors with extensive European operations and international supply chains.
The Franco-German proposal leaves room for certain European partners that were part of the EU internal market on January 1, 2020, but participation would be conditional.
The United Kingdom could potentially qualify if it accepted relevant trade-defence and investment-alignment requirements.
This could involve difficult choices over Britain’s treatment of Chinese-manufactured vehicles.
As The Guardian reported, UK officials have been weighing the implications of closer alignment with Europe’s automotive trade measures.
Turkey faces a different problem.
Despite extensive automotive supply-chain integration with Europe, it may fall outside the narrower geographical conditions.
A vehicle manufactured in Turkey could therefore encounter different treatment from a comparable vehicle made within the EU, depending on the eventual legislation.
This matters for European manufacturers as much as for Chinese brands.
Companies cannot reorganize decades of industrial specialization without costs.
The European Parliament’s September 2026 briefing on the Industrial Accelerator Act highlights the importance of international trade and investment considerations in implementing the proposal.
The political challenge will be defining European economic interests without unnecessarily disrupting production networks that already contribute to European employment.
Europe’s Trade Deficit With China Adds Pressure
The automotive dispute is part of a much broader economic imbalance.
According to Eurostat’s April 2026 publication, the EU imported €559.4 billion in goods from China during 2025 while exporting €199.6 billion.
That produced a merchandise trade deficit of €359.8 billion.
This deficit extends well beyond automobiles, covering machinery, electronics, chemicals and other manufactured products.
For European policymakers, the figures reinforce concerns about industrial competitiveness and reliance on external suppliers.
But trade deficits alone do not establish that particular imports are unfair or economically harmful.
Imports also provide inputs for European factories and affordable products for businesses and households.
The more difficult policy question is whether Europe can reduce strategically important dependencies without sacrificing the benefits of international trade.
The automotive sector is becoming a test case for that broader industrial strategy.
Could ‘Made in Europe’ Make Electric Cars More Expensive?
For European consumers, the consequences are less certain than the political debate sometimes suggests.
There are several competing effects.
Stricter local-content conditions could increase manufacturing costs when companies must replace established suppliers or invest in additional European facilities.
Reduced access to subsidies for some imported models could also affect their effective purchase prices.
Meanwhile, tariffs and import quotas can reduce competitive pressure from foreign manufacturers.
These developments may slow price reductions in some vehicle segments.
On the other hand, new factories and supplier investment could eventually improve production efficiency and reduce Europe’s dependence on imported components.
Competition among Chinese-owned manufacturers producing inside Europe and established European brands could remain substantial.
The Commission’s proposal is also targeted: it does not create a blanket prohibition on selling imported cars.
The impact on consumer prices will therefore depend on the final eligibility rules, available incentives, manufacturers’ pricing strategies and the extent of local investment.
Consumers should not assume that every Chinese-made vehicle will become ineligible for purchase or that all electric cars will necessarily become more expensive.
The Climate Policy Dilemma
Europe’s automotive industrial ambitions are colliding with its climate objectives.
Local production is intended to strengthen manufacturing employment and reduce strategic dependencies.
But loosening 2035 emissions requirements could alter manufacturers’ incentives to accelerate the shift toward fully electric vehicles.
This is why environmental organizations have criticized the Franco-German agreement.
The central concern is that additional flexibility for combustion-engine and hybrid technologies may delay investment in the next generation of affordable electric cars.
Supporters of the compromise offer a different argument.
They contend that manufacturers need realistic timelines, affordable energy and financial flexibility to survive the transition.
The challenge is not choosing between industrial competitiveness and decarbonization as though the two objectives are always mutually exclusive.
It is creating a framework in which European companies can develop competitive clean technologies while managing the costs of transforming factories, workforces and supply chains.
Without continued technological innovation, trade protection could offer only temporary relief.
What Happens Next: The 2026–2028 Policy Timeline
The agreement announced by France and Germany marks an important political step rather than the end of the legislative process.
Several developments will determine what the new automotive framework eventually looks like.
Late 2026: EU institutions and member states are expected to continue negotiating the automotive package and local-content requirements. Additional trade initiatives involving China are also under consideration.
November 20, 2026: A planned EU–UK summit could influence discussions over Britain’s role in the proposed European preference framework.
Early 2027: A common legislative text could begin to emerge, although adoption remains uncertain.
2028: The reported Franco-German position envisages implementation of important automotive local-content conditions, subject to the legislative process.
2035: Proposed changes to vehicle-emissions requirements could significantly influence the long-term balance between battery-electric, hybrid and combustion-engine technologies.
These are policy milestones and negotiating expectations, not confirmation that every proposed measure will enter into force on the dates described.
Frequently Asked Questions
What is the Made in Europe automotive policy?
It is a proposed framework linking certain public procurement decisions, subsidies and industrial incentives to European manufacturing and component sourcing. It forms part of the EU’s wider efforts to strengthen industrial competitiveness.
Does the policy ban Chinese electric vehicles?
No. The proposed local-content requirements are not a blanket import ban. They primarily concern eligibility for specified public support and procurement. Separate EU tariffs and proposed safeguards affect certain China-made vehicles.
What does the 70% European-content requirement mean?
The proposed rule concerns the value of European-origin vehicle components, excluding batteries. It should not be interpreted as a requirement that 70% of the entire vehicle’s weight, retail price or battery must originate in Europe.
Can Chinese carmakers qualify by building factories in Europe?
Potentially, yes. Chinese ownership does not automatically exclude a vehicle from satisfying geographical manufacturing requirements. However, assembly location, component origin and other conditions would still need to be met.
When could the new rules take effect?
Some proposals envisage implementation from 2028, but final dates depend on negotiations among EU institutions and member states. As of October 18, 2026, the Franco-German compromise is not binding EU law.
Will the agreement increase electric-car prices?
It could raise costs for some manufacturers or affect subsidy eligibility for particular models. However, its overall influence on retail prices remains uncertain and will depend on competition, investment and the final rules.
Conclusion: Europe Is Redefining the Terms of Automotive Competition
The Franco-German agreement marks a shift in Europe’s approach to competition with Chinese automakers.
Tariffs remain important, but the emerging strategy goes further: public industrial support may increasingly depend on where automotive value is created.
That creates opportunities for European suppliers, workers and manufacturing regions. It also offers Chinese automakers a path toward deeper localization rather than exclusion.
The policy’s success will ultimately be measured less by the number of imports it restricts than by the competitive industries it helps create.
Europe needs more than protected factories. It needs affordable vehicles, advanced battery technology, productive supply chains, skilled workers and manufacturers capable of competing internationally without permanent dependence on public support.
Chinese automakers, meanwhile, face a choice between relying on exports and committing greater capital, technology and expertise to European operations.
The likely result is not a simple retreat by China from Europe’s automotive market.
It could instead be the beginning of a new industrial contest—one increasingly fought inside Europe itself.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
TSMC reported record third-quarter revenue of approximately NT$1.49 trillion, up about 50% year over year. The key editorial question is how much optimism was already priced into shares. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
TSMC reported record third-quarter revenue of approximately NT$1.49 trillion, up about 50% year over year. The key editorial question is how much optimism was already priced into shares. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
The AI boom increasingly looks like an industrial investment cycle rather than a story about chatbots alone. Reuters’ October 12 preview described expectations for another very strong quarter at TSMC, reflecting demand for advanced chips and packaging. The nuance matters: a foundry’s sales, a GPU supplier’s orders and a cloud operator’s eventual return on investment occupy different points in the chain. Sources: Reuters chip demand report and IREN fiscal results.
The important context competitors can overlook
Investors should distinguish model training hardware from inference demand, production capacity from booked orders, and one-time buildouts from recurring utilization. Advanced packaging, memory, power availability and data-center cooling can become bottlenecks even when silicon demand is strong. A boom in infrastructure spending is not automatically proof that every new capacity project will produce attractive cash returns. For primary-source checks and current reporting, see Reuters chip demand report and Reuters bond market analysis. The key distinction is connect chipmaker profits to supply-chain constraints.
A practical way to use this information
An evidence-led article should compare announced capital spending with actual deployments, gross margin trends, customer concentration and power constraints. Avoid ranking chip companies solely on price appreciation; a more useful framework examines whether a business captures durable economics as the cost of AI computation changes. Revenue forecasts must be dated and clearly identified as estimates.
Follow the money along the AI supply chain
A cloud company budgets for compute; a chip designer sells accelerators; a foundry fabricates the designs; memory and packaging suppliers help assemble deployable systems; and a data-center operator supplies space, cooling and power. Delays at any stage can push revenue recognition into a different quarter. The October 12 Reuters TSMC preview is a useful piece of the story, but not proof that all participants share equally in the profits.
The strongest follow-up article would compare order backlogs, capital intensity and gross margins across these stages rather than extrapolating from one supplier’s exceptional growth.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Why is TSMC important to AI? It manufactures advanced semiconductors used by major technology companies.
Can rising AI demand still hurt some investors? Yes. Heavy capital spending, valuation risk and financing costs can offset revenue growth.
Follow the hardware from design to deployment
An AI accelerator does not arrive in a functioning data center simply because a chipmaker announces high demand. Designers such as Nvidia develop chips and systems; contract manufacturers such as TSMC fabricate advanced semiconductors; packaging providers integrate critical components; memory suppliers deliver high-bandwidth memory; network equipment and power infrastructure complete the installation. Bottlenecks at any stage can prevent a customer from using purchased capacity on schedule. Investors who focus only on the most visible brand miss the economics and constraints of the suppliers behind it.
The supply chain is also geographically distributed. Semiconductor fabrication and advanced packaging involve specialized equipment and long qualification processes. A customer cannot necessarily replace one advanced production facility with another at short notice. This supports supplier bargaining power in some circumstances but can increase geopolitical and operational concentration risk. The right editorial question is which constraint is binding now, supported by current evidence, rather than assuming every part of the chain faces identical shortages.
Four numbers reveal more than a chip-sales headline
First, look at revenue by segment and how rapidly each segment is changing. Second, inspect gross margin to see whether pricing power and production efficiency are translating into earnings. Third, review capital expenditure and capital intensity: growth that needs enormous new factories has a different funding profile from growth on existing capacity. Fourth, compare customer inventories and order visibility where those details are disclosed. Rising shipments into warehouses are not equivalent to a sustainable rise in end-user consumption.
Companies report different financial calendars and currencies. A Taiwanese foundry’s monthly sales announcement may not align neatly with a U.S. semiconductor designer’s fiscal quarter. Foreign-exchange translation can distort comparisons. When an article uses quarter-on-quarter or year-on-year growth, make the period explicit and avoid mixing projected sales with realized earnings. A comparison table should describe the business model of each company as well as its latest relevant metric.
Why packaging, memory and electricity can limit AI growth
Advanced packaging connects processors and memory in dense, high-performance systems. Manufacturing these components at scale requires engineering expertise and expensive equipment. Even when enough compute chips are available, a shortage of qualified packaging or memory can delay completed systems. At the deployment site, customers need reliable grid connections, transformers, cooling and networking. An equipment delivery that arrives before the building is ready does not immediately create usable computing capacity.
Power availability is not a purely technological footnote. Electricity contracts can influence operating costs for years; permitting and interconnection queues can delay planned facilities. Investors evaluating a data-center project should distinguish contracted megawatts, physically energized capacity and servers generating billable workloads. Headlines often conflate those milestones. The gap between ordering equipment and earning revenue is a critical part of the investment risk.
How AI investment could disappoint without a collapse
One scenario is that software adoption grows but not fast enough to justify every planned data-center investment. Another is that demand remains high, but competition lowers the price customers pay per unit of computing. A third is that hardware improves quickly, making recent generations less economically attractive before they are fully depreciated. None implies that AI is useless; they describe how a useful technology can produce uneven shareholder returns. Telecom investment cycles offer an instructive reminder that demand growth and attractive capital returns are not identical.
The upside scenario also deserves fair treatment. If enterprises discover reliable, high-value applications and capacity becomes heavily utilized, recurring compute revenue could support continued equipment demand. Evidence would include contracted usage, improved utilization, margins and identifiable business outcomes—not just press releases announcing larger model sizes. Investors should evaluate multiple possibilities rather than extrapolate the best recent quarter indefinitely.
An AI infrastructure due-diligence sheet
For chip designers: note product mix, customer concentration, gross margin and potential restrictions on sales. For foundries: monitor leading-edge capacity, packaging constraints, yield trends and capital expenditure. For memory suppliers: distinguish conventional memory from advanced HBM demand. For cloud operators: track compute utilization, capital cost, customer retention and cash generation. For data-center developers: verify grid power, physical construction, commissioning and signed customer commitments.
Use earnings materials and regulatory filings from each company, supported by market coverage that distinguishes analyst estimates from actual results. A strong AI chip article can capture the excitement of the investment cycle without implying that all parts of the supply chain will prosper equally.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Jeff Bezos has floated a future in which artificial intelligence makes workers productive enough that some people might choose a three-day workweek while still supporting their families. The Amazon founder made the point during an October 7, 2026 interview with Fox News. He did not announce that Amazon is adopting a three-day schedule or that AI guarantees shorter hours for everyone. The underlying distinction is crucial: Bezos was describing a possible long-term economic outcome, not a new employment policy. Fox News’s account of the interview and Fast Company’s focused coverage make that clear.
Key takeaways:
- Bezos linked the possibility of fewer working days to future gains in AI-driven productivity.
- He suggested greater output could make single-income households or shorter working schedules financially feasible for some families.
- There is no evidence in the cited interview of a universal three-day-workweek plan at Amazon.
- Research shows AI can save time on some tasks, but broad effects on compensation and employment remain unsettled.
What did Jeff Bezos say?
In the Fox interview, Bezos discussed an optimistic vision of technological progress. His argument was that powerful AI tools could raise economic output enough to expand people’s choices. If a person can generate greater value in less time—and share financially in that improvement—working fewer days could become an option rather than a forced reduction in income.
That scenario is different from predicting every office will close on Thursdays and Fridays. It is also different from a government-mandated reduction in work hours. Fast Company reported Bezos’s additional concern that firms might face labor shortages if people respond to higher productivity by choosing more leisure time.
The prediction has attracted attention because it reverses the most alarming version of the AI-and-jobs debate. Instead of imagining machines replacing so many workers that employment vanishes, Bezos emphasized the possibility of prosperity, shorter hours and tighter labor supply.
Why the productivity argument matters
Labor productivity is commonly measured as output per hour worked. That is the U.S. Bureau of Labor Statistics’ definition. A software developer completing work that used to require ten hours in six may produce more per hour. A customer-service team handling routine requests faster may serve more customers without increasing headcount at the same rate.
But greater task efficiency does not automatically mean that an employee receives proportionally higher wages or fewer shifts. Businesses choose how to allocate productivity gains among pricing, investment, expansion, profits, compensation and staffing. Workers’ bargaining power, competition, management priorities and public policy can all shape the outcome.
A simple illustration—not a forecast
Imagine an employee currently produces 40 units of useful output during a 40-hour week. Productivity is one unit per hour. If technology raises the rate to 1.67 units an hour, a 24-hour week could, arithmetically, produce approximately 40 units.
That calculation only shows a technical possibility. It assumes the tasks can be reorganized, demand stays sufficiently steady, management accepts the schedule, and pay arrangements remain favorable. Healthcare, aviation, emergency services, logistics and many other occupations require coverage across specific hours; AI cannot simply eliminate the need for people to be present.
The important question is not whether an AI tool sometimes saves time. It is whether the gain is widespread, reliable and shared in a way that makes shorter schedules financially sustainable.
What does current research show about AI and jobs?
The evidence is more restrained than the boldest predictions. A June 2026 International Labour Organization review found evidence of real but uneven productivity gains. It also concluded that large-scale job displacement had remained limited in the material reviewed, while warning about inequality, weakened entry-level pathways and shifting job quality.
Separately, Yale’s Budget Lab tracker, updated September 15, 2026, reported no clear economy-wide labor-market disruption attributable to AI in the indicators it examined. Its researchers cautioned that the findings could change as technology adoption and data evolve.
These results do not prove Bezos wrong. They show that the conditions for a large-scale three-day week have not yet been demonstrated by broad labor data. Firms are experimenting with AI, but productivity effects differ among tasks, occupations and organizations.
Task savings are not the same as job transformation
An AI assistant might draft a first version of a memo quickly, but a professional still needs to check accuracy, speak with clients, make decisions and accept responsibility. A factory might improve planning efficiency while remaining constrained by physical machinery. A hospital might automate paperwork yet still need the same number of nurses for bedside care.
This distinction between automating tasks and replacing whole jobs is essential. Headlines suggesting a direct line from better chatbots to a nationwide three-day week skip multiple economic steps.
Could workers keep the same pay while working less?
They could in some workplaces, but that would require an employer decision, collective agreement, regulatory change or a labor-market environment supportive of higher effective hourly compensation. An employee moving from five eight-hour days to three eight-hour days would cut weekly hours from 40 to 24—a 40% reduction in hours. Keeping weekly pay unchanged would require compensation per hour to increase by about 67%, before considering other changes in productivity or operating costs.
That is a much larger adjustment than ordinary schedule flexibility. The arithmetic does not make it impossible; it makes the necessary improvement explicit. By contrast, a four-day, 32-hour schedule requires a 20% reduction in hours, a different benchmark entirely.
Any employer trial must ask whether output, service quality, employee retention and customer coverage are maintained. Studies of particular programs may be promising, but results do not transfer uniformly to every industry.
What about Amazon employees?
There is no verified connection between Bezos’s prediction and an official companywide Amazon three-day-workweek policy. Bezos is Amazon’s founder and executive chair, but his personal economic forecast should not be presented as a company announcement.
Amazon operates a mixture of offices, warehouses, cloud-computing facilities, transportation networks and other businesses. Working-hour patterns depend on the role and contract. A broad change in hours would require formal employee communications and operational planning, not merely comments in a television interview.
Readers searching “Is Amazon switching to three days?” should therefore receive an unambiguous answer: not on the basis of this interview.
Could AI create a labor shortage instead of mass unemployment?
Bezos’s labor-shortage concern is plausible as a scenario, but it is not an established forecast. If incomes rose while more workers elected to reduce hours, businesses might face greater competition for labor. Yet other forces could push the opposite way: some jobs could be automated, employers could reduce hiring, or new industries might absorb displaced workers.
The net result will depend on adoption speed, which tasks AI performs reliably, the cost of computing and energy, economic growth and how governments and companies manage the transition. Reuters’ October 2026 discussion of AI at work also emphasized that AI is changing tasks within jobs, with younger and experienced workers potentially affected differently.
Frequently asked questions
Did Jeff Bezos predict a three-day workweek?
Yes. He discussed it as a possible consequence of greater AI productivity during an October 7, 2026 Fox News interview. It was not a commitment to a timetable.
Is Amazon moving to a three-day workweek?
No companywide shift was announced in the interview. Any claimed policy should be verified against Amazon’s official employment communications.
Would a three-day workweek mean three eight-hour days?
Not necessarily. A three-day schedule could mean 24 hours, longer shifts or another arrangement. Bezos did not establish a universal definition or wage agreement.
Will AI eliminate the need to work?
There is no evidence supporting that as an inevitable outcome. The ILO’s 2026 review describes heterogeneous gains and risks rather than the disappearance of work.
Could AI make one-income households more common?
It could in theory if household purchasing power rises materially, but wages, housing costs, childcare, benefits and employment security also matter. The claim remains a scenario, not a confirmed demographic trend.
When could three-day workweeks become common?
No defensible national timetable can be inferred from the cited interview. Some employers may experiment sooner than others.
The bigger economic question
The provocative part of Bezos’s vision is not whether software can perform individual tasks faster. It is whether future productivity gains become broadly shared prosperity. If workers capture enough benefit, shorter schedules may become more feasible. If gains are concentrated in profits or paired with job insecurity, fewer working hours could instead mean lower household income. Those are fundamentally different futures, and the evidence today does not settle which will dominate.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Geopolitics and Your Portfolio: How International Affairs Move Global Markets
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025