
AI
Oracle (ORCL) Stock Analysis: AI Cloud Growth Ahead of Sept 10 Earnings

Oracle reports fiscal Q1 2027 earnings on September 10, 2026, the first test of whether the company’s pivot from legacy database vendor to hyperscale AI infrastructure provider can sustain the growth rate management itself guided to just three months ago. The stakes are unusually high: Oracle is guiding to the fastest quarterly revenue growth in its recent history, backed by a $638 billion order backlog that now anchors nearly every bull and bear argument on the stock.
The Setup Heading Into Q1 FY2027
Oracle closed fiscal 2026 with record numbers that reset the market’s understanding of its growth ceiling:
| Metric | FY2026 Q4 (Reported) | FY2027 Q1 (Guided/Consensus) |
|---|---|---|
| Total Revenue | $19.18B (+21% YoY) | ~$19.13B, guided 27–29% YoY growth |
| Cloud Infrastructure (OCI) Revenue Growth | +93% YoY | Guided 58–64% cloud growth |
| Adjusted EPS | $2.11 (beat $1.96 consensus) | Guided $1.72–$1.76 |
| Remaining Performance Obligations (RPO) | $638B | — |
| FY2027 Capex Guidance | Up to $95B | — |
The headline figure investors keep returning to is the $638 billion RPO — Oracle’s contracted-but-not-yet-recognized revenue — which includes a five-year, $300 billion cloud-computing agreement with OpenAI. That single contract now anchors a meaningful share of Wall Street’s bull case, and just as prominently, its bear case: multiple analysts have flagged that nearly half of Oracle’s contracted revenue traces back to one AI-lab counterparty, concentrating execution risk if OpenAI’s own capital plans shift.
Why the Market Is Split on Valuation
Sentiment on ORCL has bifurcated sharply over 2026:
- The bull case rests on Oracle’s transformation into critical AI-training infrastructure. J.P. Morgan has maintained an Overweight rating, arguing the buildout thesis extends beyond raw infrastructure into cloud applications and database modernization — a “diversified growth” argument meant to counter the OpenAI-concentration criticism. Consensus analyst price targets run as high as $400, with a mean around $253, implying substantial upside from levels near $160.
- The bear case centers on financing risk. Oracle raised $43 billion in debt and $5 billion in equity in fiscal 2026 alone, and management has guided to roughly $40 billion in additional financing for fiscal 2027 — including a previously announced $20 billion at-the-market equity issuance. Combined with capex guidance of up to $95 billion, that spending pace has pushed free cash flow negative, a structural feature bears argue the market has under-priced relative to Oracle’s historically conservative balance sheet.
Oracle stock dropped roughly 7% after-hours following its June 2026 fiscal Q4 report, despite beating on both revenue and earnings — a reaction driven almost entirely by the market reading an unchanged full-year revenue outlook as a signal that AI-driven demand might be plateauing relative to hyperscaler peers who had raised their own guidance more aggressively in the same window.
What to Watch in the September 10 Report
- Cloud infrastructure (OCI) growth cadence. Guidance calls for 58–64% growth — a deceleration from Q4’s 93%, but off a much larger base. Any print materially below that range would revive the demand-plateau narrative that hit the stock in June.
- RPO conversion. Investors will scrutinize how much of the $638 billion backlog is converting into recognized revenue on schedule, since the entire bull thesis depends on data-center capacity coming online fast enough to bill against signed contracts.
- Financing disclosures. With another ~$40 billion in planned fiscal 2027 financing, any update on debt terms, equity dilution pace, or credit-rating commentary will move the stock independent of the topline numbers.
- Customer concentration commentary. Any additional color on the OpenAI relationship, or disclosure of new large enterprise commitments (Oracle signed $67 billion in new AI infrastructure contracts in Q4 alone, including four customers each committing more than $8 billion), will factor into how analysts model durability of the RPO figure.
- Government and enterprise contract wins. Oracle secured a $400 million, 10-year federal contract in mid-2026, part of a broader push into public-sector cloud that diversifies revenue away from pure hyperscaler-AI exposure.
Institutional Investor Framework
For portfolio construction purposes, Oracle now trades less like a legacy enterprise software name and more like AI infrastructure peers (Nvidia, Broadcom, hyperscaler capex plays). That reclassification matters for valuation multiples: applying a 20–22x multiple to elevated fiscal 2028 earnings estimates supports price targets in the $240–$250 range cited by several sell-side desks, implying meaningful upside from current levels if execution holds — but also meaning the stock now carries the multiple compression risk associated with capex-heavy AI infrastructure plays broadly, not just software-company risk.
Bottom Line
Oracle’s September 10 fiscal Q1 2027 report is a referendum on whether 27–29% guided revenue growth and 58–64% cloud growth are achievable without further financing-driven balance sheet strain. The $638 billion RPO remains the single most important number in the Oracle thesis — both as the source of extraordinary growth visibility and as the concentration risk that keeps institutional bears engaged even as price targets on the Street continue to climb.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


AI
Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power
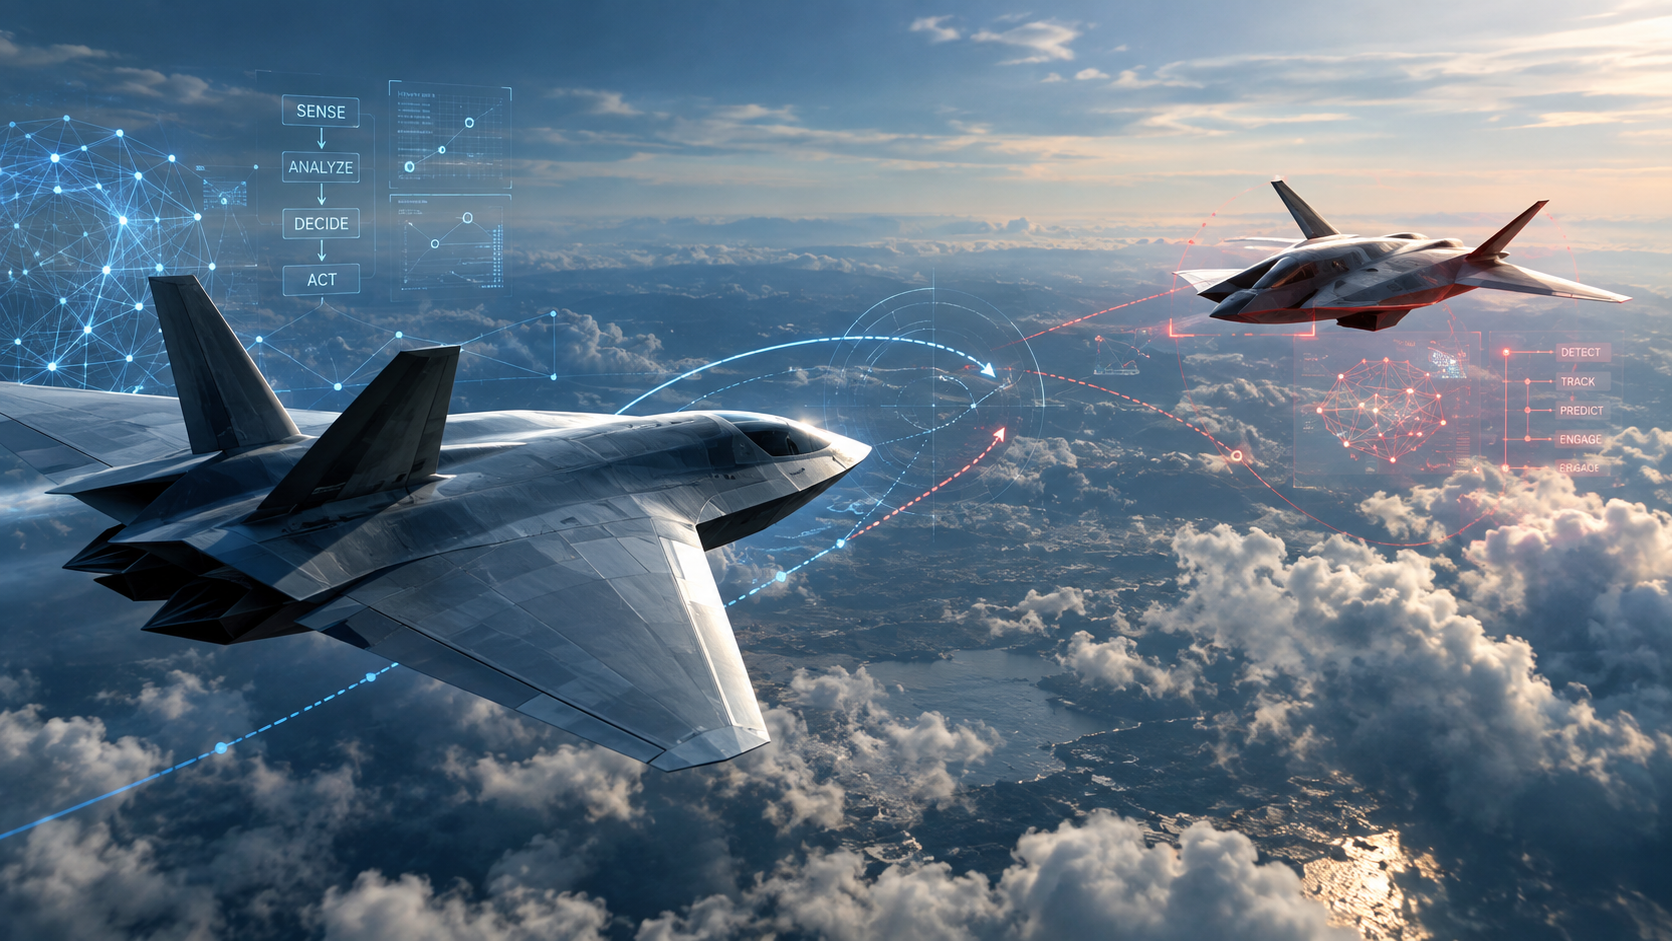
The military balance of power across the Indo-Pacific is undergoing a fundamental transformation. As both the United States and China transition artificial intelligence from simulator environments to front-line fighter jets, the primary threat of accidental military escalation in international airspace is shifting from human pilot miscalculation to machine learning error.
While much of the diplomatic discourse surrounding military AI focuses on nuclear command and strategic autonomy, the most immediate danger lies in tactical air intercepts over contested waters like the South China Sea and the Taiwan Strait. Without clear, bilateral rules of engagement (RoE) specifically tailored for autonomous aircraft, a routine encounter between uncrewed combat air vehicles (UCAVs) could trigger a rapid, unintended escalation ladder that human command structures cannot arrest in time.
The Dawn of Mach-Speed Autonomy
The race to field autonomous combat aircraft is no longer theoretical; it is an operational priority for both Washington and Beijing.
Under the U.S. Air Force’s Collaborative Combat Aircraft (CCA) initiative, the Pentagon plans to field at least 1,000 AI-enabled “loyal wingmen”—uncrewed aircraft designed to fly alongside crewed platforms like the F-35 and Next Generation Air Dominance (NGAD) fighters. Experiments conducted under the DARPA Air Combat Evolution (ACE) program have already demonstrated that AI agents can successfully outmaneuver human pilots in visual-range dogfights, adapting to tactical dynamic shifts at sub-second speeds. Details outlined by the U.S. Department of Defense emphasize the imperative of responsible autonomy, yet tactical real-time execution in contested zones remains a major wild card.
Concurrently, the People’s Liberation Army Air Force (PLAAF) is aggressively pursuing its own uncrewed platforms. Chinese defense contractors have showcased platforms such as the FH-97A and the WZ-8, designed to perform autonomous reconnaissance, electronic warfare, and forward-line air-to-air suppression. Research published by the RAND Corporation indicates that Beijing views military AI integration as a “force multiplier” capable of offsetting traditional U.S. power projection advantages in the First Island Chain.
The Escalation Trap: Why AI Changes Air-to-Air Tactics
In conventional intercept scenarios involving piloted aircraft—such as a Chinese J-16 intercepting a U.S. RC-135—human pilots operate under established visual signals, radio frequencies, and the multilateral Code for Unplanned Encounters at Sea (CUES). When a human pilot assesses intent, they rely on visual cues, physical distance, and tactical behavior to gauge aggression versus standard shadowing.
When two autonomous or semi-autonomous systems intercept one another, these human buffers disappear:
- Compression of the OODA Loop: Machine-learning algorithms operate on microsecond decision cycles. If an autonomous aircraft interprets a standard radar lock, electronic jamming pod, or evasive banking maneuver by an opposing drone as an incoming attack vector, its predictive neural networks may trigger defensive or pre-emptive maneuvers instantly.
- The “Black Box” Problem: Deep neural networks operate via complex pattern matching rather than deterministic logic trees. As noted in security studies by the Center for Strategic and International Studies (CSIS), predicting how an edge-deployed military AI model will respond to unpredictable real-world inputs (such as spoofed GPS or unexpected weather events) remains an unsolved challenge.
- Loss of Signaling Nuance: Human pilots can de-escalate a confrontation by rocking wings, pulling back on throttles, or establishing radio contact. Autonomous systems lack standard mechanisms to convey ambiguous or non-hostile intent to an opposing nation’s algorithmic system.
+-----------------------------------------------------------------------+
|                       THE ACCIDENTAL ESCALATION LOOP                 |
|                                                                       |
|   [U.S. Autonomous CCA]  <--- Sensor Query --->  [PLA Autonomous UCAV]|
|            |                                            |             |
|   Algorithm perceives                               Algorithm perceives|
|   evasive banking as hostile                         radar lock as     |
|   targeting signal                                  pre-emptive strike|
|            |                                            |             |
|            v                                            v             |
|   Automated Countermeasure                       Automated Deficit    |
|   Deployments (Chaff/Jamming)                    Tracking & Target    |
|            |                                     Acquisition          |
|            +-------------------+------------------------+             |
|                                |                                      |
|                                v                                      |
|             HUMAN COMMANDERS NOTIFIED POST-DISCHARGE                  |
|             (Escalation threshold crossed in <3 seconds)             |
+-----------------------------------------------------------------------+
The Existing Governance Vacuum
Multilateral efforts to regulate military AI have made modest progress, but they fall short of addressing tactical air intercepts.
The Responsible AI in the Military Domain (REAIM) summits and the U.S.-led Declaration on Responsible Military Use of Artificial Intelligence and Autonomy offer general principles regarding human oversight, command structure integrity, and rigorous testing. Similarly, diplomatic analysis published by the Brookings Institution highlights that high-level bilateral summits between Washington and Beijing have opened initial dialogues on AI risk reduction.
However, these broad political declarations lack operational mechanics. They do not define:
- What constitutes a hostile act by an autonomous platform in international airspace.
- What standardized electronic signals an uncrewed system must broadcast to declare peaceful transit.
- How machine-to-machine communications should function during an unintended proximity event.
Without concrete, technical protocols embedded directly into aircraft software suites, high-level political commitments will fail the moment silicon meets silicon over the Western Pacific.
A Four-Pillar Blueprint for U.S.-China AI Air Engagement
To mitigate the risk of an unintended confrontation, defense officials and technical experts from the United States and China must establish a dedicated Autonomous Air De-confliction Framework. Analysts writing in Foreign Affairs repeatedly note that arms control in the digital age requires technical solutions co-designed alongside strategic policy.
1. Hard-Coded Strategic Fail-Safes
Both nations should agree to hard-code deterministic “red lines” into autonomous flight control systems that cannot be overridden by machine-learning models. These include hard caps on maximum speed increases during close encounters, mandatory stand-off distances when intercepting uncrewed platforms, and automated weapon system lock-outs unless explicit human authority is transmitted.
2. Standardized Autonomous Identification Friend-or-Foe (A-IFF)
Similar to transponder systems used in commercial aviation, military uncrewed systems operating in international airspace should transmit a standardized, cryptographically signed “Autonomous Platform Intent” signal. This broadcast would inform nearby air units of the flight’s mission state, autonomous level (e.g., tethered to human lead vs. fully autonomous), and non-aggressive flight path vector.
3. Machine-to-Machine De-confliction Hotlines
Traditional voice-based communication links—such as the U.S.-China Defense Telephone Link—are too slow to manage algorithmic interactions. A modern de-confliction protocol requires an automated, low-latency data channel between U.S. Indo-Pacific Command and the PLA Eastern/Southern Theater Commands. This channel would automatically ping human operators the instant two opposing autonomous platforms enter a designated safety perimeter.
4. Joint Synthetic Simulation and Stress-Testing
Before deploying advanced autonomous fighters at scale, defense laboratories from both nations should participate in joint track-sharing and simulated scenario stress-tests. By running algorithmic models against each other in virtual environments, both sides can identify edge cases where neural networks misinterpret opponent maneuvers, allowing software engineers to patch systemic vulnerabilities before they manifest in real air combat.
The Imperative of Algorithmic Restraint
The integration of artificial intelligence into air warfare is an inevitable reality driven by strategic competition and technological momentum. However, autonomy without governance introduces an unacceptable level of operational risk.
If Washington and Beijing fail to establish clear rules of engagement for autonomous combat jets today, they risk allowing computer algorithms to dictate the timing and conditions of a major-power conflict tomorrow. Establishing guardrails for AI air power is not a sign of military weakness—it is a mandatory requirement for strategic stability in the 21st century.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Key Takeaways
- The “Planet Labs and Goldman” link is research coverage, not a partnership. We found no public announcement of a commercial deal. Goldman Sachs analysts cover Planet Labs (NYSE: PL) with a Neutral rating and have raised their price target at least twice this year, first to $18 and then to $20.
- The business is growing fast. Planet’s second-quarter fiscal 2027 revenue hit a record $116.1 million, up 58% year over year, with backlog of about $814.9 million.
- The stock has been a roller coaster. It peaked at $51.76 on May 28, according to TheStreet, and is now down roughly 11% for the year.
- Satellite data has been a Wall Street edge for over a decade. Academic work on parking-lot imagery shows funds have profited from it, and that the advantage stayed concentrated among a select few large investors.
- The next chapter is defense, sovereign demand and AI in orbit. Those are lumpier, bigger-ticket revenue streams than retail parking lots ever were.
Type “Planet Labs Goldman” into a search bar and you’ll find a jumble of analyst notes, price targets and stock-move headlines. It’s natural to assume the two companies are working together. As far as the public record shows, they aren’t.
The real connection is more interesting. Planet Labs is one of the clearest examples of a company turning pictures of Earth into financial-grade information, and Goldman Sachs is one of the institutions deciding what that business is worth. Meanwhile, the broader market for satellite imagery in investing has been quietly maturing for more than a decade.
This guide separates the signal from the noise: who Planet is, what Goldman thinks, how Wall Street has used satellite data, and what to track if you want to evaluate the opportunity yourself. It’s information, not investment advice.
What Planet Labs Actually Sells
Planet Labs PBC, based in San Francisco, operates a large fleet of Earth-observation satellites. The company provides near-daily imagery of the planet’s landmass and sells it, along with analytics, to governments and commercial customers in agriculture, energy, environmental monitoring and defense.
Three product ideas matter for this story:
- Daily, wide-area imagery. Frequency is the product. A picture that updates every day reveals change, and change is what investors and intelligence analysts pay for.
- Specialized sensors. Planet’s Tanager spacecraft targets greenhouse gases such as methane, which turns an environmental question into a measurable data feed.
- Satellite services for sovereign customers. Governments increasingly want their own dedicated capability, and Planet builds and operates it for them.
The Latest Scorecard
Planet reported second-quarter fiscal 2027 results (quarter ended July 31, 2026) in early September. Here is how the numbers looked, from the company’s earnings release and the earnings-call recap.
| Metric | Result | Why it matters |
|---|---|---|
| Revenue | $116.1M, up 58% year over year | A record quarter, well above what analysts expected |
| Net loss | $9.4M, versus $22.6M a year earlier | Losses are shrinking |
| Adjusted EBITDA | $13.9M profit | Operating leverage is showing up |
| Backlog | About $814.9M; roughly half converts within 12 months | Gives forward visibility |
| Cash and short-term investments | $865.4M | Funds capital-intensive satellite builds |
| Defense and intelligence revenue | Up more than 90% | The fastest-growing customer group |
| Third-quarter guidance | $101M to $105M | Below the roughly $114M analysts expected |
| Fiscal 2027 revenue guidance | $430M to $441M, up 40% to 43% | Raised at the low end |
Two things deserve a flag. First, about 12% of second-quarter revenue was “point-in-time” revenue from a satellite handover, versus 1% a year earlier. That kind of revenue is real, but lumpy. Second, the soft third-quarter guide is exactly why the stock reacted so sharply, as 247WallSt noted.
Where Goldman Sachs Fits In
Goldman’s role in this story is as an evaluator. Its equity-research team rates Planet Neutral, which generally signals that the analysts don’t expect the shares to meaningfully beat or lag their coverage group.
The firm’s price-target path tells you how its view evolved:
- March 23, 2026: target raised to $18 from $16.40 after quarterly results beat expectations, driven by defense, intelligence and civil government demand.
- April 20, 2026: target raised to $20 from $18, reflecting improved confidence in the commercial outlook.
In the March note, the analyst said Planet was seeing strong demand signals and making sensible long-term investments. In other words, Goldman liked the business but wasn’t sold on the price. That’s the common story with a stock that had already climbed about 793% over the prior year, according to Investing.com.
The Stock: Boom, Bust, Rebuild?
Planet shares rode a speculative wave early in 2026, peaked at $51.76 in May and have corrected since. TheStreet reports the stock is down about 11% year to date but up nearly 18% over twelve months.
Recent catalysts include:
- A successful launch of 20 satellites, including 18 SuperDove imaging satellites, a Tanager-2 hyperspectral satellite, and an experimental space-based AI computing node developed with Alphabet.
- A record quarter and a growing backlog.
- Sovereign wins such as a seven-figure contract with the Greek government, reported by Investing.com.
The risks are just as concrete. Capital spending is heavy, GAAP profitability remains out of reach, revenue timing can be uneven, and the sector’s enthusiasm can evaporate quickly.
How Wall Street Has Used Satellite Data
Long before Planet was a public company, investors figured out that pictures from orbit could predict earnings.
The best-known example is the parking lot. Companies began selling analysis of retailers’ car counts in the early 2010s. Researchers at UC Berkeley examined 4.8 million images covering 67,000 U.S. stores and found the strategy could indeed deliver an edge, and that the data hadn’t spread much beyond hedge funds. Their warning was blunt: the practice may disadvantage everyday investors who can’t see the same data.
A CNBC feature on alternative data explained the basic logic. Consistently empty parking lots can signal weak store traffic, giving a fund reason to bet against a retailer before the quarterly report lands.
Satellite data has since widened well beyond retail:
- Commodities: crop health, soil moisture and storage activity.
- Energy: tank levels, flaring and shipping patterns.
- Supply chains: port congestion, factory activity and construction progress.
- Climate and ESG: methane plumes, deforestation and land-use change.
A Simple Framework for Judging a Geospatial Stock
| Question | What to look for | Planet today |
|---|---|---|
| Is demand durable? | Backlog and recurring contracts | About $815M backlog; 98% of annual contract value is recurring |
| Is growth profitable? | Adjusted EBITDA and free cash flow | Adjusted EBITDA positive in Q2, guided to a loss in Q3 |
| How concentrated is the customer base? | Government vs. commercial mix | Defense and intelligence growing fastest |
| Is the balance sheet strong? | Cash versus capex needs | $865M cash against $100M to $115M of planned capex |
| Is revenue predictable? | Share of lumpy, point-in-time sales | 12% in Q2, up sharply from a year ago |
Three Risks the Headline Numbers Don’t Show
Strong quarters can hide structural questions. If you’re weighing Planet or any rival, put these three on your checklist.
- Competition. Earth observation is crowded, and governments can choose among several suppliers. One Seeking Alpha analysis argues that the business is strong but that competition remains a long-term risk and valuation may cap future returns.
- Deal conversion. Large sovereign contracts move the needle, but they arrive on irregular timelines. Coverage of the September report pointed out that Planet’s conversion rate on bigger sovereign deals is still being established, which leaves room for guidance to slip if timing moves.
- Narrative dependence. Space stocks trade as a group. When enthusiasm around the sector fades, even companies with improving fundamentals can fall hard, which is part of what the 2026 round trip from $51.76 looks like.
None of these cancel the growth story. They explain why a 58% revenue increase and a falling share price can show up in the same month, and why a Neutral rating from an analyst can be perfectly consistent with a rising business.
The Compliance Question
Is it fair for a fund to trade on satellite imagery? Generally, publicly observable data processed legally is a legitimate research input. The sensitive lines involve how data is collected, what contracts permit, and whether any of it amounts to material nonpublic information. Investors should treat the source as an essential part of due diligence.
Asked & Answered
Does Goldman Sachs partner with Planet Labs?
We found no public announcement of a commercial partnership. Goldman’s visible connection is analyst coverage: a Neutral rating with price targets raised in March and April of 2026.
What does a Neutral rating mean?
It signals that the analysts don’t expect the stock to meaningfully outperform or underperform the companies they cover. It is not a sell call.
Is Planet Labs profitable?
Not on a GAAP basis. It posted a $9.4 million net loss in the latest quarter, though adjusted EBITDA was positive at $13.9 million and losses have narrowed from a year earlier.
How do hedge funds use satellite imagery?
Typical uses include counting cars at retailers, estimating crop yields, tracking oil storage and monitoring shipping. The goal is to see change before it appears in company reports.
Is trading on satellite data legal?
Using lawfully obtained, publicly observable information is generally accepted. Problems arise with misrepresented sourcing or confidential information, so funds typically run these datasets past compliance teams.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Shivon Zilis spent years out of the spotlight. Then she took the stand in one of the biggest tech trials of the decade. Here’s her professional background and what her testimony revealed about how AI companies are governed.
Key Takeaways
- Current role: She is Director of Operations and Special Projects at Neuralink. americankahani
- Background: Yale graduate with degrees in economics and philosophy, with earlier roles in AI at Tesla and a seat on OpenAI’s board.
- Why she’s in the news: She testified in Musk v. Altman in Oakland in May 2026.
- Trial outcome: A nine-person jury found Musk waited too long to sue, and the judge dismissed his claims. abc7news
- What’s next: Musk said he would appeal to the Ninth Circuit.
Career Timeline
| Period | Role |
|---|---|
| 2015 | Named to Forbes 30 Under 30 in venture capital |
| Early career | Co-founder of Creative Destruction Lab’s AI and quantum machine learning streams in Toronto |
| 2017–2019 | Project director in AI at Tesla |
| Through 2023 | OpenAI adviser, then board member |
| Sept 2023 | Joined the board of Shield AI, a defense-tech company focused on autonomous drones |
| Present | Neuralink, Director of Operations and Special Projects gulfnewsmoney |
Her résumé spans venture capital, AI research and brain-computer interfaces. That breadth explains why she became a connecting figure across several Musk-linked companies.
Why She Testified
Zilis was initially a co-plaintiff in the case, though she dropped off at her own request before the trial began. OpenAI’s lawyers argued she knew about Musk’s plans for a rival AI company while she sat on OpenAI’s board. CNN’s coverage is not the source for this; see instead the syndicated CNN report of her testimony, which describes her role in the flow of information between Musk and OpenAI during critical periods. keytkeyt
Her testimony covered several threads:
- Funding discussions: She said many funding options were discussed, including giving Musk a majority stake in OpenAI. keyt
- Her board role: Once on the board, she said she did not discuss her OpenAI work with Musk. piedmontexedra
- The Microsoft deal: OpenAI’s lawyers noted that she voted as a board member to approve the Microsoft agreement. piedmontexedra
- Her resignation: Courthouse News reported she said she stepped down in 2023 after Musk started xAI and began recruiting from OpenAI. letsdatascience
The Conflict-of-Interest Question
The trial put a governance problem on public display. OpenAI president Greg Brockman testified that the board let her stay because she described her relationship with Musk as platonic. Reporting from Courthouse News shows Zilis insisting that their personal relationship did not influence her board duties. keyt
That conflict is the lesson for startups and boards. When a director has close personal ties to a founder of a competing venture, the safeguards matter: disclosure, recusal and documentation. Whether those safeguards were adequate is a judgment the jury never reached on the merits.
The Verdict
On May 18, a jury in Oakland ruled against Musk after short deliberations. The jury sided with OpenAI’s argument that Musk waited too long to bring his claims. TechCrunch reported that the verdict was unanimous and rested on a statute of limitations defense. Al JazeeraTechCrunch
Two details matter for accuracy:
- It wasn’t a ruling on merits. Because the case was dismissed on timing grounds, the jury did not decide the substance of Musk’s allegations. piedmontexedra
- The jury was advisory. Judge Yvonne Gonzalez Rogers accepted the verdict as the court’s own. abc7news
Musk called it a “calendar technicality” and said he would appeal. Al Jazeera’s explainer notes the trial never became the sweeping test of AI’s future that many expected. Engadget
What Zilis’s Role Says About Tech Power Networks
Zilis isn’t unusual in having overlapping roles. Early AI companies were built by small groups of people who moved between founding teams, boards and advisory roles. What’s different is that the AI industry now carries enormous valuations. OpenAI is valued around $852 billion and is planning an IPO in late 2026. At that scale, informal arrangements that once looked harmless get scrutinized. The Hill
Three takeaways for founders and investors:
- Document information flows between board members and affiliated companies.
- Treat personal relationships as governance facts, not private matters, when they touch competing ventures.
- Expect discovery. Text messages and board records can end up in front of a jury.
What to Watch Next
- The appeal: A Ninth Circuit filing would keep the case alive.
- xAI’s separate claims: xAI is pursuing its own trade-secret and antitrust claims against OpenAI. ascendants
- OpenAI’s IPO: The verdict removed an immediate legal threat to its restructuring.
- Neuralink: Zilis’s day job continues to sit at the frontier of brain-computer interface development.
FAQ
What does Shivon Zilis do?
She is an executive at Neuralink and a former OpenAI board member.
Where did she study?
Yale, with degrees in economics and philosophy, according to profiles.
Why did she testify?
She was a board member during the period at issue in Musk’s lawsuit against OpenAI.
Did Musk win?
No. The court dismissed his claims on statute of limitations grounds, and he has said he will appeal.
Zilis’s testimony turned a low-profile executive into a central witness in a case about who controls AI. The legal result rested on timing, not substance, so the governance questions her testimony raised remain open. For anyone building or investing in AI companies, her story is a reminder that board seats, personal ties and competing ventures can collide, and that courts will examine all three.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025