
Global Economy
Why Global Inflation Is Rising Again in 2026, and What It Means for Pakistan

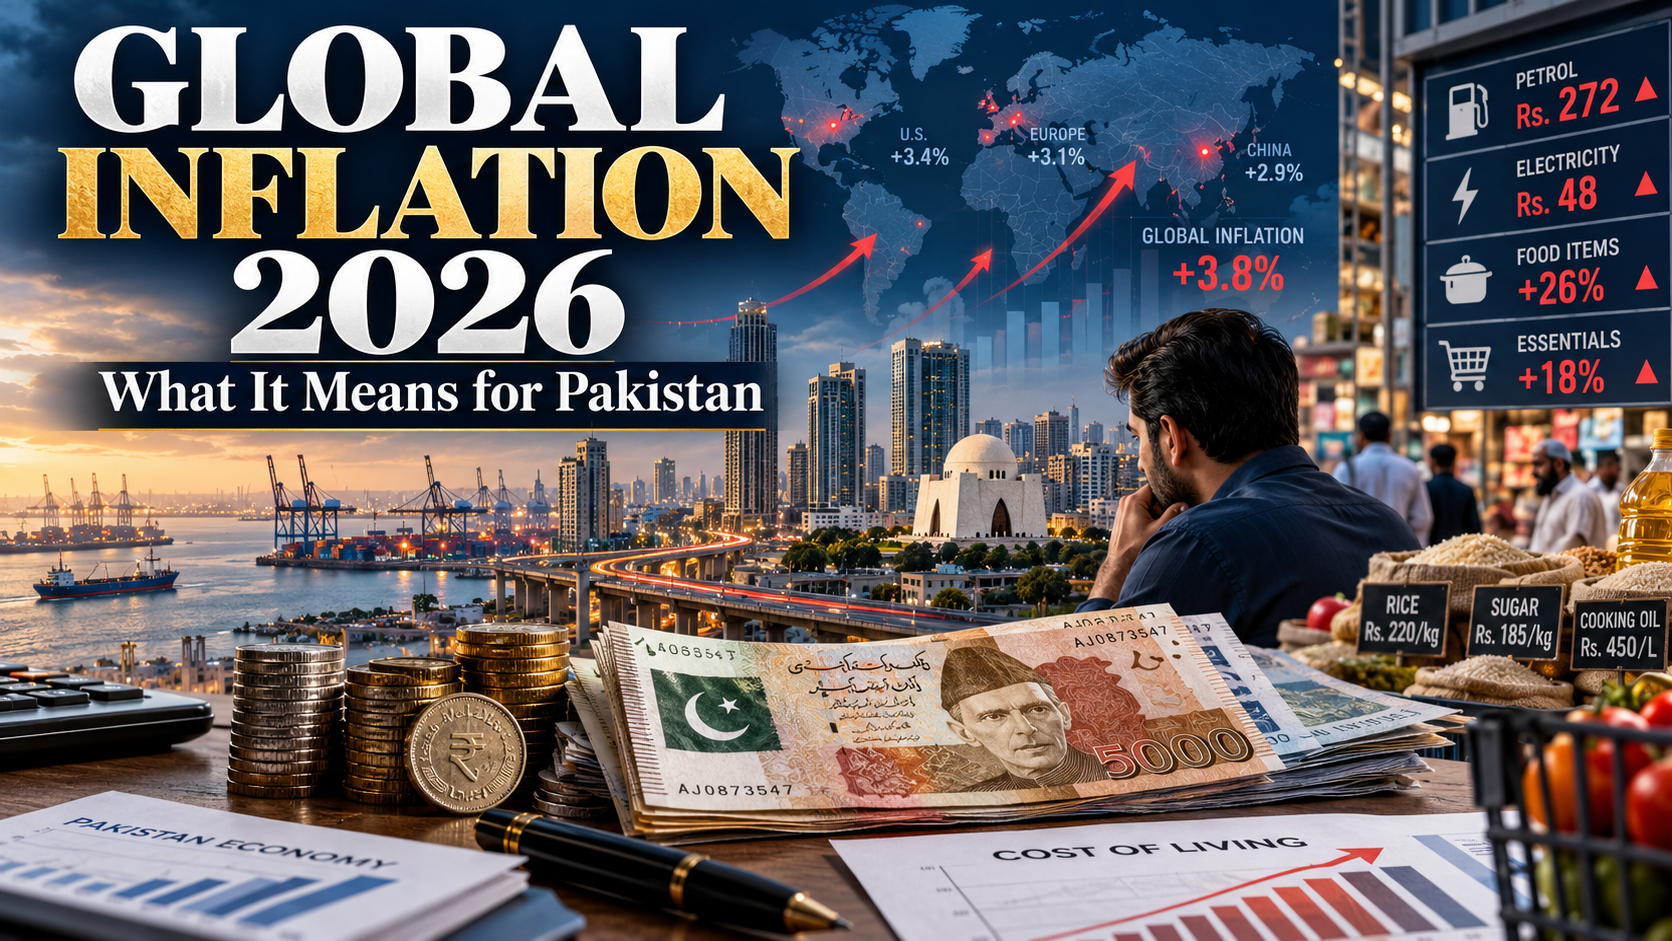
Global inflation is rising again in 2026, and energy is the main cause. The International Monetary Fund expects global headline inflation to climb to 4.7% this year, up from 4.1% in 2025, mainly because of higher energy and food prices (IMF, World Economic Outlook, October 2026). For import-dependent countries such as Pakistan, the shock arrives through fuel pumps, transport fares and the cost of imported goods.
Key Takeaways
- The IMF projects global inflation of 4.7% in 2026, easing to 4.1% in 2027.
- Energy and food prices are the main drivers, linked to the Middle East conflict and supply disruptions.
- Global growth is slowing at the same time, to about 3.1% in 2026, which makes the trade-off harder for central banks.
- Pakistan’s headline inflation was 10.26% year on year in September 2026, well above the State Bank’s 5 to 7% target range.
- Households and businesses should plan for higher transport and import costs, and should not assume a quick return to lower inflation.
The IMF numbers in brief
The IMF sees global growth slowing from 3.5% in 2025 to 3.1% in 2026, before recovering to 3.4% in 2027 (Trend.az, reporting the IMF release). The more worrying signal is that inflation is rising while growth slows. When an economy slows and prices rise together, policymakers have fewer good options.
The IMF has also said the global economy is resilient but increasingly uneven. Countries that benefit from the AI investment boom or favourable terms of trade are doing relatively well. Many energy-importing and low-income countries face much harder conditions (Trend.az).
Why energy is doing the damage
Energy feeds into almost everything: freight, fertiliser, food processing, manufacturing and electricity. One press summary of the IMF analysis reports that energy prices remain roughly a quarter higher than before the shock (Outlook India).
This is why interest rates alone cannot solve the problem. Higher borrowing costs reduce demand, but they do not produce more oil or gas. Central banks can slow second-round effects, where higher fuel costs feed into wages and expectations. They cannot lower the price of a barrel.
Supply shock or demand boom?
Demand-driven inflation comes from too much spending chasing too few goods. Supply-driven inflation comes from higher input costs that squeeze output. The 2026 episode is mostly supply-driven, and that changes the policy answer. Rate rises work well against demand-driven inflation. Against supply-driven inflation, they work more slowly and at a higher cost to growth.
A Pakistani analysis published in April made this point directly: inflation there is no longer driven solely by excess demand, yet policy still relies heavily on high interest rates (Bol News).
Our reading is that global inflation in 2026 is a supply problem that central banks will try to treat with demand tools. A prolonged period of high rates looks more likely than a sharp reversal.
Pakistan: inflation above 10% and the rate dilemma
Headline inflation in September 2026 was 10.26% year on year, and the monthly rise of 1.27% was driven by energy costs (ARY News, citing PBS data). Electricity and fuel offset a sharp slowdown in food prices. Core inflation, which excludes food and energy, ran between 8.1% and 8.6% (The Express Tribune).
The State Bank kept its policy rate at 11.5% in September, by a seven-to-three vote (The Express Tribune). It had raised rates by 100 basis points in April, the first hike in nearly three years (Bol News).
The government has told the IMF that inflation could fall to 7.5% if the Middle East situation normalises and Brent averages $80 a barrel in the current fiscal year. That is a conditional assumption, not a forecast. The IMF has urged Pakistan to adjust both exchange-rate and interest-rate policy to keep inflation and the current account deficit under control (The Express Tribune).
How the shock travels
For a Pakistani household, the chain is short. Petrol and diesel prices move first. Transport fares follow within weeks. Food prices rise through freight and packaging. Imported goods become more expensive as the rupee comes under pressure.
Food complicates the picture. Tomato prices fell about 25% month on month in the September data, and chicken prices fell about 8% (ARY News). Seasonal food swings can hide energy pressure for a month or two, which is why economists watch core inflation alongside headline figures.
What this means for households and businesses
Households: Treat transport and utility costs as fixed for budgeting purposes. If you carry variable-rate debt, remember that the policy rate feeds directly into repayments.
Small businesses and importers: Build fuel and freight surcharges into quotes where possible. Review supplier contracts for currency clauses. Keep working capital buffers, because higher rates raise the cost of bridging cash gaps.
Investors: A prolonged hold at high rates is a different environment from a rapid easing cycle. This is general information, not investment advice.
Risks, limitations and uncertainties
- IMF figures are projections. They will change as conflict and energy prices evolve, and the October outlook flags downside risks.
- The government’s 7.5% assumption depends on Brent averaging $80 a barrel. A sustained spike would push inflation higher.
- Pakistan’s monthly CPI and policy-rate figures are subject to revision.
- Pakistan can diverge from the global average because of the rupee, administered prices and food supply.
This article is for general information and is not personalised financial or economic advice.
FAQ
Will global inflation rise in 2026? The IMF expects global headline inflation to rise to 4.7% in 2026, from 4.1% in 2025 (IMF).
Why is inflation rising again? Energy and food costs are the main drivers, with supply disruptions linked to the Middle East conflict pushing fuel prices up.
Will inflation fall in 2027? The IMF projects global inflation easing to 4.1% in 2027. That could change quickly if energy supply worsens.
Why is Pakistan’s inflation above the global average? Pakistan imports much of its fuel, so energy shocks pass through quickly. Electricity and fuel rose in the latest data, and the rupee adds pressure.
Will the State Bank raise rates again? It has kept rates at 11.5% and has signalled it will tighten further if needed to prevent second-round effects. Future decisions depend on inflation, the exchange rate and energy prices.
Conclusion
Global inflation is rising in 2026 because energy and food costs have jumped, and the IMF expects it to ease only gradually. For Pakistan, the challenge is sharper, with inflation above 10% and limited room to cut rates. Watch oil prices, the State Bank’s next decision and monthly CPI releases. Those signals will show whether the shock is fading or becoming entrenched.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Global growth is not the same as broad prosperity. Pakistan’s outcomes will depend less on the global average than on the channels through which external demand, energy, financing, and technology influence local firms. This feature explains the mechanisms, risks and practical decisions that matter through 2027, with particular attention to Pakistan’s different exposure to energy prices, external financing, global trade and AI investment.
At a glance
- World output is forecast to rise, but opportunities and costs are uneven across countries.
- Global inflation forecasts do not predict household prices in Pakistan.
- The AI capital expenditure cycle lifts trade in electronics but may not translate into productivity gains everywhere.
- Pakistan’s IMF staff-level agreement is a milestone, not final Board approval.
- Stronger exports, competitive energy, fiscal credibility and skills are essential to durable growth.
The verified starting point: what the numbers actually say
The IMF October 2026 World Economic Outlook projects global growth of 3.1% in calendar 2026 and 3.4% in calendar 2027, alongside global headline inflation of 4.7% and 4.1%, respectively. Its statistical cutoff is 1 October 2026. The WTO October 2026 trade outlook projects merchandise trade volume growth of 3.9% in 2026 and 4.1% in 2027, versus commercial-services trade volume growth of 3.3% and 6.4%. These are forecasts from different statistical systems, not interchangeable growth measures.
For Pakistan, the IMF Pakistan October 7 staff-level agreement estimated FY2026 growth of 3.6%, September headline inflation of approximately 10.3%, and gross reserves near $21.5 billion at end-September. The fourth EFF review and third RSF review had reached staff-level agreement only, pending IMF Executive Board approval as of the release. Pakistan’s fiscal years run July–June; IMF global growth figures refer to calendar years.
| Indicator | 2026 | 2027 | Important distinction |
|---|---|---|---|
| IMF world GDP growth | 3.1% | 3.4% | Calendar-year projection |
| IMF world headline inflation | 4.7% | 4.1% | Global estimate, not Pakistan CPI |
| WTO goods trade volume growth | 3.9% | 4.1% | Real volume, not nominal trade value |
| WTO commercial services volume growth | 3.3% | 6.4% | Conditional rebound, not guaranteed |
The World Bank June 2026 Global Economic Prospects provides an earlier comparison framework, but its publication date and methodology differ from the October IMF and WTO releases. A thoughtful analysis should compare like with like and should never treat projections as realized outcomes. For a Pakistan-focused story, the crucial question is how global conditions enter domestic economic life.
Why this story matters now
The WTO October 2026 executive summary says AI-enabling goods accounted for 47% of year-on-year growth in the value of world merchandise trade during the first half of 2026. That does not mean 47% of all merchandise trade was AI-related. It identifies a contribution to growth, and in nominal value terms. The same source notes that AI-enabling goods trade rose 67% year-on-year in that period. These figures show how a narrow technology cycle can make global trade appear stronger even as other sectors struggle.
Meanwhile the Reuters October 2026 IMF annual meetings reports persistent concern about global financial risks, geopolitical disruptions and the uneven sharing of AI gains. The Reuters October 2026 Asian growth describes a region where technology investment supports some exporters while energy costs and higher yields challenge others. Pakistan is therefore exposed simultaneously to a potential technology opportunity and to more conventional fuel, financing and trade vulnerabilities.
Why the headline growth rate hides divergence
For why the headline growth rate hides divergence, Growth averages blur distribution. A country manufacturing sought-after electronics can gain from a technology upcycle while an energy importer faces a larger fuel invoice. That contrast explains why Pakistan needs an exposure-weighted reading of international forecasts rather than simply celebrating a higher headline GDP projection.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For why the headline growth rate hides divergence, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Pakistan’s four exposure channels
For pakistan’s four exposure channels, The most useful indicator is not one number but a sequence: orders received by exporters, import bills, financial inflows, electricity charges and jobs created. These measures reach families at different speeds, which is why apparently stable GDP figures can coexist with a sense of economic pressure.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For pakistan’s four exposure channels, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
What the latest IMF agreement does and does not mean
For what the latest imf agreement does and does not mean, Economic resilience is the capacity to manage adverse shocks without repeatedly disrupting investment and consumption. Predictable policy, transparent fiscal choices and adequate external liquidity matter alongside short-term growth acceleration.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For what the latest imf agreement does and does not mean, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
What businesses should prepare for
For what businesses should prepare for, Growth averages blur distribution. A country manufacturing sought-after electronics can gain from a technology upcycle while an energy importer faces a larger fuel invoice. That contrast explains why Pakistan needs an exposure-weighted reading of international forecasts rather than simply celebrating a higher headline GDP projection.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For what businesses should prepare for, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
The policy choices that determine resilience
For the policy choices that determine resilience, The most useful indicator is not one number but a sequence: orders received by exporters, import bills, financial inflows, electricity charges and jobs created. These measures reach families at different speeds, which is why apparently stable GDP figures can coexist with a sense of economic pressure.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For the policy choices that determine resilience, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Policy options: three alternative paths, not numerical forecasts
| Scenario | Assumptions | Implications for Pakistan | Early warning or confirmation |
|---|---|---|---|
| More favorable | Energy costs stabilize; export markets remain open; AI use generates measurable efficiency | Space for investment, steadier purchasing power and stronger services exports | Export orders, real income and private investment improve together |
| Central case | Global growth follows the broad institutional outlook; commodity and funding pressures fluctuate | Gradual recovery with uneven gains across sectors | Stable external balances without a broad productivity surge |
| Adverse | Energy disruptions persist; financing costs rise; AI investment is repriced | Imports become more costly, credit tighter and fiscal choices harder | Reserves, inflation expectations and financing costs weaken at once |
These are qualitative editorial scenarios, not probabilities assigned by an econometric model. Their value lies in clarifying which evidence would require an updated judgment. The IMF October 2026 World Economic Outlook explicitly emphasizes downside risks involving conflict, trade tension, debt and reassessment of AI expectations.
A practical action agenda
For policymakers, the first responsibility is to protect hard-won macroeconomic stability while removing barriers to productivity. Regulatory predictability, tax administration, targeted social protection and transparent energy decisions are more useful than shifting incentives that are impossible for businesses to plan around. The IMF Pakistan 2026 country report identifies revenue mobilization, reform of state enterprises, energy-sector viability and improvements in human capital as linked policy priorities.
For exporters, resilience means identifying where demand is growing, investing in reliable delivery and obtaining credible certifications. Export strategies should track volumes, domestic value added and customer retention; gross receipts alone do not disclose profitability. For small businesses, the practical priority is to map exposure to fuel, electricity, imports and foreign-exchange requirements and to stress-test cash flows before making expansion commitments.
For households, risk management begins with an affordable budget, attention to debt servicing and a realistic distinction between nominal wage gains and purchasing power. For workers, portable skills and credible training can expand options across changing industries. None of this makes external shocks harmless; it simply offers concrete ways to be less exposed.
How this analysis differs from generic global coverage
Major international reporting is indispensable for establishing what happened. The Reuters October 2026 WTO briefing emphasizes the boost from AI to merchandise trade and the pressure of geopolitical disruption. Institutional releases provide detailed projections. This article goes a step further by asking how those macroeconomic signals might translate into local import costs, export competitiveness, employment, household budgets and reform choices. It is an interpretation of attributed evidence, not a claim of exclusive interviews or original field reporting.
The difference is particularly relevant for Pakistan because a global technology boom may coincide with higher costs for countries that import fuel but do not manufacture the equipment in highest demand. No serious strategy should assume that a worldwide headline rate automatically delivers the same benefits locally.
Frequently asked questions
What is the IMF’s global growth forecast for 2027?
The IMF’s October 2026 World Economic Outlook projects 3.4% global GDP growth in 2027, following 3.1% in 2026. These are calendar-year forecasts and may be revised as new data becomes available. See the IMF October 2026 World Economic Outlook.
Is global inflation expected to fall in 2027?
Yes, the October IMF forecast projects global headline inflation easing from 4.7% in 2026 to 4.1% in 2027. That describes the world aggregate and does not imply that prices in Pakistan will fall in absolute terms.
Is Pakistan’s latest IMF financing already approved?
The 7 October 2026 IMF release announced staff-level agreement for the fourth EFF and third RSF reviews, subject to Executive Board approval. The release should not be described as a completed Board decision. See the IMF Pakistan October 7 staff-level agreement.
Will AI investment create jobs in Pakistan?
It could create demand for implementation, software services and specialist support, while also changing tasks in existing occupations. The result depends on skills, investment, electricity reliability and competitive access to customers. No credible source guarantees a particular employment gain.
Does the WTO predict rapid growth in all kinds of trade?
No. Its October outlook differentiates merchandise volume growth from commercial-services volume growth and notes uneven performance by sector and region. Read the WTO October 2026 executive summary.
What should Pakistani companies monitor through 2027?
Export order books, input costs, electricity reliability, financing terms, exchange-rate conditions and customer demand are more operationally useful than a single global growth figure. Businesses should compare these against their own cash flows and margins.
Conclusion: the decisive issue is transmission, not the headline
Global growth is not the same as broad prosperity. Pakistan’s outcomes will depend less on the global average than on the channels through which external demand, energy, financing, and technology influence local firms. The balance of risks is mixed: advanced technology can expand world production and trade, but it does not neutralize an energy shock or a financing squeeze. For Pakistan, policy credibility, internationally competitive exports and productivity-enhancing investment will determine how much of a fragile global expansion becomes better living standards at home.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Paris and Berlin have reached a pivotal automotive compromise. Its implications extend well beyond tariffs, raising difficult questions about manufacturing, technology, jobs, trade alliances and the future of affordable electric vehicles.
Europe’s automotive confrontation with China is entering a more consequential phase. Having imposed tariffs on Chinese-made electric vehicles, the European Union is now moving toward a policy that could influence not only where cars are sold, but also where their components are manufactured, their batteries are sourced and their technology is developed.
A new Franco-German agreement announced on October 16 seeks to strengthen European production through stricter Made in Europe requirements while offering greater flexibility on vehicle emissions.
For Chinese manufacturers such as BYD, Chery, Xpeng and Changan, the message is increasingly difficult to ignore: access to European customers may remain open, but access to European industrial incentives could become dependent on making a substantially greater economic contribution within the region.
The agreement represents a political breakthrough between Europe’s two largest economies. But it is not yet binding EU legislation, and crucial details remain subject to negotiation.
According to Reuters’ October 16 report, Germany and France must secure support from other EU governments and the European Parliament before their proposals can take effect.
The stakes are considerable. Europe’s automotive industry supports extensive manufacturing and supplier networks, while Chinese companies increasingly regard the continent as an important destination for overseas expansion.
The central question is no longer simply whether Chinese electric vehicles can compete in Europe. It is whether European policy can preserve industrial value without undermining competition, investment and the transition to cleaner transport.
What Germany and France Have Agreed
At the centre of the compromise is a narrower definition of what constitutes a European-made vehicle for specified public financial support and government procurement.
The French and German position builds on the European Commission’s Industrial Accelerator Act, proposed on March 4, 2026.
That initiative seeks to strengthen domestic industrial capacity by linking certain subsidies, procurement decisions and investment incentives to European production and lower-carbon manufacturing.
Under the latest Franco-German approach, qualifying automotive production would primarily cover the EU’s 27 member states. Some closely integrated European partners could participate under additional conditions.
Reporting by Euronews identifies a proposed threshold requiring 70% European-origin components, excluding batteries, alongside European battery-content conditions.
The October agreement also points toward stronger expectations for research and development in Europe.
Three elements deserve particular attention.
First, assembling a vehicle in Europe may not be enough. The value of its components and the structure of its supply chain could determine whether it qualifies for public incentives.
Second, battery sourcing matters separately. European policymakers want more of the economic value generated by electric vehicles—including battery technology and manufacturing—to remain within the region.
Third, engineering and research could become part of industrial eligibility. A factory that assembles imported components offers a different economic contribution from a facility supported by local suppliers, researchers and engineering teams.
Reports on the Franco-German position indicate a potential 2028 implementation horizon for key automotive sourcing conditions. However, eligibility calculations, transitional arrangements and research requirements remain unsettled.
These distinctions matter because the new framework would not automatically prohibit the sale of foreign vehicles. Instead, it could affect which vehicles benefit from specified public support.
Why Germany and France Reached a Compromise
France and Germany share concerns about competition from Chinese manufacturers, but their approaches to industrial policy have not always aligned.
France has consistently advocated a stronger European preference in industrial subsidies and public procurement. Its argument is that public spending should support production, investment and employment within Europe.
Germany has traditionally placed greater emphasis on maintaining internationally integrated supply chains and protecting established automotive manufacturers from abrupt regulatory change.
German brands depend on extensive supplier relationships and sell vehicles in international markets, including China. Policies designed to restrict Chinese competition could also complicate their own global operations.
The October compromise connects these industrial interests with a politically sensitive question: the EU’s vehicle emissions framework for 2035.
Under the joint position, the proposed 2035 emissions target would be a 90% reduction from 2021 levels, without requiring manufacturers to compensate for the remaining 10% through additional measures.
That offers greater flexibility than the European Commission’s earlier proposal.
Reuters reported that European automotive shares advanced following the agreement, while Volkswagen welcomed the prospect of stronger incentives for European manufacturing.
The political bargain is therefore clear.
Germany gains greater flexibility over future automotive technologies. France gains stronger support for European industrial preferences.
Yet neither outcome is guaranteed. Other EU institutions and member states retain a role in determining the final rules.
China’s Expanding Automotive Presence Explains Europe’s Urgency
The debate is taking place against an extraordinary transformation in international vehicle trade.
China has become the world’s largest vehicle exporter, with domestic manufacturers expanding across electric vehicles, plug-in hybrids and conventional models.
European companies remain major global manufacturers. Yet Chinese competitors have demonstrated increasingly strong capabilities in battery technology, software integration, manufacturing scale and price competitiveness.
The latest Eurostat figures, published October 13, show that China accounted for 42% of the EU’s electric-car imports in 2025.
That figure measures China’s share of imported electric cars, not its share of all vehicles sold in the EU—a distinction that is essential for interpreting the market.
The same Eurostat release shows that:
- EU imports of electric and hybrid cars reached €45.1 billion in 2025.
- Exports of these vehicles totaled €64.7 billion.
- Almost 4.8 million hybrid and electric cars were produced in the EU.
- Hybrid and electric models accounted for nearly 40% of EU car production.
These numbers demonstrate that Europe is not a passive participant in the electric-vehicle transition. It retains substantial production capabilities and an important export position.
But its manufacturing base faces intense competition over costs, batteries and future technologies.
China’s domestic market conditions provide an additional reason for its automakers to expand overseas.
According to Associated Press reporting on October 12, Chinese passenger-vehicle exports increased 64% year over year in September 2026, reaching approximately 919,000 units.
Weakness in domestic demand has made foreign markets particularly important for Chinese carmakers.
Europe consequently faces two interconnected pressures: a wave of increasingly competitive imports and the need to attract long-term investment into its own automotive industry.
The Three Layers of Europe’s New Automotive Trade Strategy
Europe’s emerging approach combines existing tariffs, restrictions on certain imports and proposed local-production incentives.
Understanding the differences is essential.
1. Existing tariffs on Chinese battery-electric cars
In October 2024, the European Commission imposed additional countervailing duties on battery-electric vehicles manufactured in China following an anti-subsidy investigation.
The definitive rates included:
| Manufacturer | Additional countervailing duty |
|---|---|
| BYD | 17.0% |
| Geely | 18.8% |
| SAIC | 35.3% |
| Tesla’s Shanghai production | 7.8% |
These are additional countervailing duties, not necessarily the complete applicable import-tariff burden.
The duties were introduced to address subsidy-related injury concerns identified by the Commission. They are distinct from the proposed Made in Europe requirements.
The legal basis and company-specific rates appear in the EU’s definitive countervailing duty regulation.
2. New restrictions on hybrid-vehicle imports
Chinese manufacturers responded to the earlier battery-electric tariffs partly by expanding sales of hybrid vehicles.
Brussels and Beijing subsequently reached an agreement aimed at limiting Chinese-built hybrid imports.
On October 12, Reuters reported that the EU and China had agreed on an initial annual limit of 350,000 hybrid vehicles, with the volume allowed to increase by 6% annually.
The safeguard arrangement is intended to last four years and would apply to other trading partners under its broader framework.
Its precise implementation remains important, particularly for companies planning European sales and production.
3. Proposed incentives favouring European manufacturing
The third layer is potentially the most transformative.
Unlike import duties or quotas, local-content requirements influence investment decisions inside the European economy.
A Chinese-owned company that establishes genuine manufacturing operations within the EU could potentially qualify under the relevant rules if its vehicles meet the applicable component, battery and other eligibility conditions.
This means the policy distinguishes between the location of production and the nationality of the corporate owner.
That distinction could fundamentally change Chinese automakers’ strategies.
How BYD, Chery, Xpeng and Changan Could Respond
Chinese manufacturers are not approaching this policy shift without preparation.
Many have already started building or developing European production capacity.
Reuters reported on October 13 that several major Chinese manufacturers were accelerating local manufacturing, engineering and supplier partnerships before the rules were finalized.
BYD: From vehicle exports toward European production
BYD has pursued overseas manufacturing expansion, including investment in Hungary.
European production could reduce reliance on imports from China and provide a more durable base for growth.
However, a European assembly plant would not automatically satisfy the proposed sourcing requirements.
The company would also need to evaluate where batteries, electronics, motors and other vehicle components originate.
The economic calculation is straightforward but demanding: local production may improve regulatory resilience while adding new capital expenditure and operating costs.
Chery: Building a localized industrial strategy
Chery has emphasized European production and local engineering capabilities.
For the company, establishing relationships with European component manufacturers could become as important as developing competitive models.
Such partnerships can provide access to technical capabilities, distribution networks and manufacturing expertise.
But integrating an international supplier base takes time, especially when production schedules and regulatory standards are evolving.
Xpeng: Partnerships as a route to market
Xpeng provides another example of how Chinese manufacturers can enter Europe without relying exclusively on new, wholly owned factories.
Reuters reported that Magna was already building electric vehicles for Xpeng in Austria.
Contract manufacturing can accelerate market access by using established production facilities.
Yet the proposed rules suggest that production location alone may be insufficient. Component sourcing and potentially research activity could become important additional considerations.
Changan: A longer-term European commitment
Changan has outlined ambitious plans for European production.
According to Reuters, the company is targeting production capacity of 180,000 vehicles annually in Europe by 2028 and 350,000 by 2030.
These are company targets rather than achieved production figures.
If implemented successfully, they would demonstrate how Chinese manufacturers can respond to trade restrictions by becoming increasingly embedded in Europe’s industrial ecosystem.
The broader implication is striking: policies intended to protect European manufacturing may also attract greater investment from Chinese competitors.
That could create European jobs while intensifying competition for established local brands.
The 70% Rule Could Transform Automotive Supply Chains
The most economically important feature of the proposed framework may be the component-value requirement.
Automotive production depends on complex international networks supplying batteries, semiconductors, electronic systems, transmissions, motors and other components.
A car sold as European-made can contain substantial imported value.
The proposed 70% threshold for non-battery components would therefore affect procurement decisions throughout the industry.
Manufacturers seeking to qualify for particular subsidies could need to purchase more components from EU suppliers or reorganize existing production networks.
For European parts manufacturers, this could create significant commercial opportunities.
For automakers, however, the transition may prove expensive.
A company might need to replace an efficient international supplier with a local alternative that initially has higher costs or limited production capacity.
The result could be higher short-term manufacturing expenses, even if additional investment eventually improves European competitiveness.
There is also a longer-term industrial benefit to consider.
Component factories generate more than direct employment. They support specialist engineering, machinery purchases, logistics services and technical training.
If local-content rules encourage these activities, the economic gains could extend beyond individual assembly plants.
But the outcome depends on whether European suppliers can achieve competitive costs and reliable production at scale.
Protection alone cannot guarantee industrial efficiency.
Why Britain, Turkey, Japan and South Korea Are Concerned
The emerging definition of Europe presents a challenge for countries with automotive industries closely connected to EU manufacturers.
Britain has historically been deeply integrated into European automotive production.
Turkey is another important manufacturing partner, supplying vehicles and components through longstanding commercial relationships.
Japan and South Korea are major automotive investors with extensive European operations and international supply chains.
The Franco-German proposal leaves room for certain European partners that were part of the EU internal market on January 1, 2020, but participation would be conditional.
The United Kingdom could potentially qualify if it accepted relevant trade-defence and investment-alignment requirements.
This could involve difficult choices over Britain’s treatment of Chinese-manufactured vehicles.
As The Guardian reported, UK officials have been weighing the implications of closer alignment with Europe’s automotive trade measures.
Turkey faces a different problem.
Despite extensive automotive supply-chain integration with Europe, it may fall outside the narrower geographical conditions.
A vehicle manufactured in Turkey could therefore encounter different treatment from a comparable vehicle made within the EU, depending on the eventual legislation.
This matters for European manufacturers as much as for Chinese brands.
Companies cannot reorganize decades of industrial specialization without costs.
The European Parliament’s September 2026 briefing on the Industrial Accelerator Act highlights the importance of international trade and investment considerations in implementing the proposal.
The political challenge will be defining European economic interests without unnecessarily disrupting production networks that already contribute to European employment.
Europe’s Trade Deficit With China Adds Pressure
The automotive dispute is part of a much broader economic imbalance.
According to Eurostat’s April 2026 publication, the EU imported €559.4 billion in goods from China during 2025 while exporting €199.6 billion.
That produced a merchandise trade deficit of €359.8 billion.
This deficit extends well beyond automobiles, covering machinery, electronics, chemicals and other manufactured products.
For European policymakers, the figures reinforce concerns about industrial competitiveness and reliance on external suppliers.
But trade deficits alone do not establish that particular imports are unfair or economically harmful.
Imports also provide inputs for European factories and affordable products for businesses and households.
The more difficult policy question is whether Europe can reduce strategically important dependencies without sacrificing the benefits of international trade.
The automotive sector is becoming a test case for that broader industrial strategy.
Could ‘Made in Europe’ Make Electric Cars More Expensive?
For European consumers, the consequences are less certain than the political debate sometimes suggests.
There are several competing effects.
Stricter local-content conditions could increase manufacturing costs when companies must replace established suppliers or invest in additional European facilities.
Reduced access to subsidies for some imported models could also affect their effective purchase prices.
Meanwhile, tariffs and import quotas can reduce competitive pressure from foreign manufacturers.
These developments may slow price reductions in some vehicle segments.
On the other hand, new factories and supplier investment could eventually improve production efficiency and reduce Europe’s dependence on imported components.
Competition among Chinese-owned manufacturers producing inside Europe and established European brands could remain substantial.
The Commission’s proposal is also targeted: it does not create a blanket prohibition on selling imported cars.
The impact on consumer prices will therefore depend on the final eligibility rules, available incentives, manufacturers’ pricing strategies and the extent of local investment.
Consumers should not assume that every Chinese-made vehicle will become ineligible for purchase or that all electric cars will necessarily become more expensive.
The Climate Policy Dilemma
Europe’s automotive industrial ambitions are colliding with its climate objectives.
Local production is intended to strengthen manufacturing employment and reduce strategic dependencies.
But loosening 2035 emissions requirements could alter manufacturers’ incentives to accelerate the shift toward fully electric vehicles.
This is why environmental organizations have criticized the Franco-German agreement.
The central concern is that additional flexibility for combustion-engine and hybrid technologies may delay investment in the next generation of affordable electric cars.
Supporters of the compromise offer a different argument.
They contend that manufacturers need realistic timelines, affordable energy and financial flexibility to survive the transition.
The challenge is not choosing between industrial competitiveness and decarbonization as though the two objectives are always mutually exclusive.
It is creating a framework in which European companies can develop competitive clean technologies while managing the costs of transforming factories, workforces and supply chains.
Without continued technological innovation, trade protection could offer only temporary relief.
What Happens Next: The 2026–2028 Policy Timeline
The agreement announced by France and Germany marks an important political step rather than the end of the legislative process.
Several developments will determine what the new automotive framework eventually looks like.
Late 2026: EU institutions and member states are expected to continue negotiating the automotive package and local-content requirements. Additional trade initiatives involving China are also under consideration.
November 20, 2026: A planned EU–UK summit could influence discussions over Britain’s role in the proposed European preference framework.
Early 2027: A common legislative text could begin to emerge, although adoption remains uncertain.
2028: The reported Franco-German position envisages implementation of important automotive local-content conditions, subject to the legislative process.
2035: Proposed changes to vehicle-emissions requirements could significantly influence the long-term balance between battery-electric, hybrid and combustion-engine technologies.
These are policy milestones and negotiating expectations, not confirmation that every proposed measure will enter into force on the dates described.
Frequently Asked Questions
What is the Made in Europe automotive policy?
It is a proposed framework linking certain public procurement decisions, subsidies and industrial incentives to European manufacturing and component sourcing. It forms part of the EU’s wider efforts to strengthen industrial competitiveness.
Does the policy ban Chinese electric vehicles?
No. The proposed local-content requirements are not a blanket import ban. They primarily concern eligibility for specified public support and procurement. Separate EU tariffs and proposed safeguards affect certain China-made vehicles.
What does the 70% European-content requirement mean?
The proposed rule concerns the value of European-origin vehicle components, excluding batteries. It should not be interpreted as a requirement that 70% of the entire vehicle’s weight, retail price or battery must originate in Europe.
Can Chinese carmakers qualify by building factories in Europe?
Potentially, yes. Chinese ownership does not automatically exclude a vehicle from satisfying geographical manufacturing requirements. However, assembly location, component origin and other conditions would still need to be met.
When could the new rules take effect?
Some proposals envisage implementation from 2028, but final dates depend on negotiations among EU institutions and member states. As of October 18, 2026, the Franco-German compromise is not binding EU law.
Will the agreement increase electric-car prices?
It could raise costs for some manufacturers or affect subsidy eligibility for particular models. However, its overall influence on retail prices remains uncertain and will depend on competition, investment and the final rules.
Conclusion: Europe Is Redefining the Terms of Automotive Competition
The Franco-German agreement marks a shift in Europe’s approach to competition with Chinese automakers.
Tariffs remain important, but the emerging strategy goes further: public industrial support may increasingly depend on where automotive value is created.
That creates opportunities for European suppliers, workers and manufacturing regions. It also offers Chinese automakers a path toward deeper localization rather than exclusion.
The policy’s success will ultimately be measured less by the number of imports it restricts than by the competitive industries it helps create.
Europe needs more than protected factories. It needs affordable vehicles, advanced battery technology, productive supply chains, skilled workers and manufacturers capable of competing internationally without permanent dependence on public support.
Chinese automakers, meanwhile, face a choice between relying on exports and committing greater capital, technology and expertise to European operations.
The likely result is not a simple retreat by China from Europe’s automotive market.
It could instead be the beginning of a new industrial contest—one increasingly fought inside Europe itself.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
CoreWeave shares have become a direct test of how investors value artificial-intelligence infrastructure when the cost of capital rises. An October 14 Reuters report described a severe selloff across AI-related stocks after unexpectedly strong U.S. inflation data and singled out CoreWeave’s financing exposure. The central investing question is not whether AI demand exists. It is whether the company’s contracted demand, operating cash generation and available funding can support the speed and cost of construction implied by its expansion plans. For primary-source background, consult Reuters October 14 AI selloff; Financial Times CoreWeave funding; CoreWeave investor relations. In a fast-moving topic, publication time and information cutoff matter: subsequent events may require updating the figures or legal status, not merely changing the date in the footer.
What triggered the latest CoreWeave attention
The October inflation surprise raised investors’ expectations for interest rates and the price of financing long-duration projects. Reuters reported sharp declines in AI-infrastructure names, including CoreWeave, during the October 14 session. A one-day stock move is an observed price reaction, not evidence that its customers have canceled contracts. But the selloff makes funding structure newly important. Businesses that must invest cash today to earn revenue over years are highly sensitive to financing rates, payment schedules and equipment-value assumptions. Investors should confirm the trading session, percentage return and share class from an exchange or market-data service before republishing a price snapshot.
CoreWeave shares have become a direct test of how investors value artificial-intelligence infrastructure when the cost of capital rises.
Why AI infrastructure differs from an ordinary software company
CoreWeave supplies compute infrastructure, including GPU-intensive capacity used for AI workloads. Unlike a software business that can sell more subscriptions with limited marginal hardware investment, a compute provider may need expensive servers, electricity arrangements, networking, cooling systems and leases before customer revenue arrives. This can create a timing mismatch between contracted demand and free cash flow. Contract backlog can indicate future business, but it should never be substituted for cash already received. Terms for delivery, termination, prepayments and customer concentration can matter as much as the top-line headline number.
Debt, leases and the financing sensitivity
The Financial Times described CoreWeave seeking institutional financing for a large infrastructure build-out. Debt and lease obligations create fixed or contractual costs even when equipment utilization fluctuates. Investors should distinguish balance-sheet borrowings, lease liabilities, securitized equipment financing and contingent commitments; simplistic claims that all financing is identical distort risk. The cost of debt can rise sharply if lenders demand more compensation for uncertainty. At the same time, long-duration enterprise contracts can reduce revenue uncertainty. A sensible analysis weighs both sides and studies repayment schedules rather than judging the company by one leverage ratio.
Demand quality and customer concentration
AI companies and enterprise customers can require substantial compute, but customer contracts differ in reliability and profitability. A long agreement with a strong counterparty may support asset-backed financing more effectively than several short contracts with uncertain collection. Yet dependence on a few large buyers creates negotiating power and renewal risks. Look for disclosure about remaining performance obligations, revenue recognition, prepayments, utilization and customer concentration. An impressive backlog can coincide with negative free cash flow because building the capacity to fulfill those obligations is costly. The investment case strengthens only when large demand translates into economic returns after depreciation, interest and maintenance.
What valuation methods tell different stories
Price-to-sales ratios focus on revenue growth but ignore the cost required to deliver it. Enterprise value to EBITDA can obscure heavy capital replacement costs if depreciation is particularly meaningful. Free cash flow, measured consistently, makes investment intensity visible but may temporarily penalize a fast-growing construction phase. No single metric is decisive. Compare the company with infrastructure providers facing similar capital needs rather than only with asset-light software companies. Then stress-test outcomes under higher borrowing rates, slower installations, lower GPU pricing and changes in customer demand. These are scenarios, not assertions about what management will do.
Worked example: how to interpret a difficult headline
Imagine two AI-cloud projects with identical contracted revenue. Project A finances infrastructure at a lower fixed rate and launches on time; Project B faces a financing reset, a construction delay and higher electricity costs. The revenue headline may look the same, but cash generation and equity value could differ considerably. This is why debt maturity, deployment timing and customer collection are better questions than the size of an announced deal alone. This is a deliberately illustrative comparison unless explicit documented numbers are identified. It should not be mistaken for a real person’s financial circumstances, an unverified event, or a guaranteed forecast. Its purpose is to show how a reader can apply the underlying principle and identify which information still needs to be checked.
Three concepts that are often confused
| Concept | What it actually establishes |
|---|---|
| Revenue growth | Describes delivered services; does not equal net cash generation. |
| Backlog or contract value | Indicates potential future work subject to conditions and timing. |
| Cash flow after capital spending | Tests whether expansion economics can sustain funding obligations. |
These distinctions are more than technical niceties. They change the answer to the reader’s question. An estimate does not carry the same evidentiary weight as a final rule; an announcement does not have the same practical consequence as a completed transaction; and a provisional interpretation should not be presented as a confirmed event. Wherever a live source supplies a new fact, the editor should check whether the old text still describes the right stage of the process.
A reader’s verification workflow
Start by recording the precise claim and the date it was allegedly true. Open the primary announcement or filing rather than a social-media screenshot. Ask whether the source has an incentive to present only the most favorable interpretation, and corroborate material facts with reputable independent reporting where available. For numerical claims, note the denominator, timeframe and whether the number is a stock, a flow, a forecast or a realized result. For legal claims, note the court, agency, stage of proceedings and exact published document.
Next, separate information useful for immediate decisions from context that merely explains the headline. A person may need to act on a deadline even when the long-run political debate remains unresolved. Someone evaluating a security may need financing details, while a customer comparing technology products needs a tested specification and local warranty terms. The same headline can matter for different reasons; the article should therefore provide an actionable answer without implying that every reader faces the same circumstances.
Indicators and developments worth monitoring
- Company quarterly financial filings and debt footnotes.
- Interest rates and spreads on financing vehicles.
- Capacity construction and customer-service activation.
- New customer agreements and changes in utilization.
Avoid treating these signals as a checklist that mechanically predicts the future. Some are leading indications and others are lagging measurements. A change becomes significant only after its magnitude, source and comparison period are understood. If two reputable sources disagree, explain the source of the difference—definitions, timing, jurisdiction, measurement or uncertainty—instead of selecting whichever number makes the strongest headline. That practice strengthens both reader trust and the article’s usefulness in search features that surface isolated paragraphs.
The specific information advantage of this article
Growth forecasts grab attention but often hide the cost of building the revenue-generating assets. Treat contract backlog and installed capacity as distinct measures, then compare them with borrowing needs, lease liabilities and cash returns. This is the difference between an AI-demand story and a credible investment-risk story.
Frequently asked questions
Is CoreWeave stock the same as buying Nvidia?
No. CoreWeave operates compute infrastructure with financing and customer risks unlike a semiconductor designer. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Why did rising rates matter?
More expensive capital can reduce the present value of future cash flows and make funding new servers costlier. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does backlog guarantee profit?
No. Contracts must be fulfilled, and expenses, financing and accounting recognition determine profitability. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
What is the biggest unresolved question?
Whether contracted capacity can generate durable cash returns after equipment, power and financing costs. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Bottom line
CoreWeave shares have become a direct test of how investors value artificial-intelligence infrastructure when the cost of capital rises. An October 14 Reuters report described a severe selloff across AI-related stocks after unexpectedly strong U.S. inflation data and singled out CoreWeave’s financing exposure. The central investing question is not whether AI demand exists. It is whether the company’s contracted demand, operating cash generation and available funding can support the speed and cost of construction implied by its expansion plans. The best next step is to identify which of the monitored developments could change this answer and use a current, authenticated record before acting. Clear distinctions between confirmed facts, estimates, proposals and contested claims are more valuable than dramatic certainty.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

AI Investment Boom 2026–2027: Can Pakistan Capture the Upside?

Global Economy 2026–2027: What Slower Growth Means for Pakistan

Why Global Inflation Is Rising Again in 2026, and What It Means for Pakistan

Raast Pakistan 2026: Digital Payments, Fintech

Pakistan Real Estate Tax 2026: What Buyers, Sellers and Investors Must Check

SME Finance Pakistan 2026: Why Small Businesses Still Struggle for Credit

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

Agri-Tech Pakistan 2026: Where Farming Innovation Could Actually Pay

Pakistan Tax Net: Why Agriculture, Retail and Property Are So Hard to Tax

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Pakistan IT Exports 2026: What Would It Take to Reach $10 Billion?

Pakistan AI Policy 2025: Can It Raise Productivity and Create Jobs?

Pakistan Remittances 2026: How Overseas Workers Support the Economy

Can Pakistan Reach $34 Billion in Exports? The Real Barriers and Fastest Fixes

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

World’s Largest Economies: Ranking the Top Global Powers

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Asian Stock Markets 2026: Japan, China, Pakistan & More

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

SpaceX IPO 2026: History’s Biggest Stock Debut?

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Is AI a Stock Bubble in 2026? What the Data Shows
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025