
Technology
Nintendo’s Next Move: Why Metroid Ravenous and Switch 2 Lineups Define Portable Gaming


Nintendo’s software strategy for Switch 2 aims to dominate Q1 2027. Releasing ‘Metroid Ravenous’ as a premium system-seller sidesteps the hardware loss-leader strategy. High-margin Special Editions and digital storefront ecosystems maximize software profitability to cushion the capital expenditure of the hardware launch.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


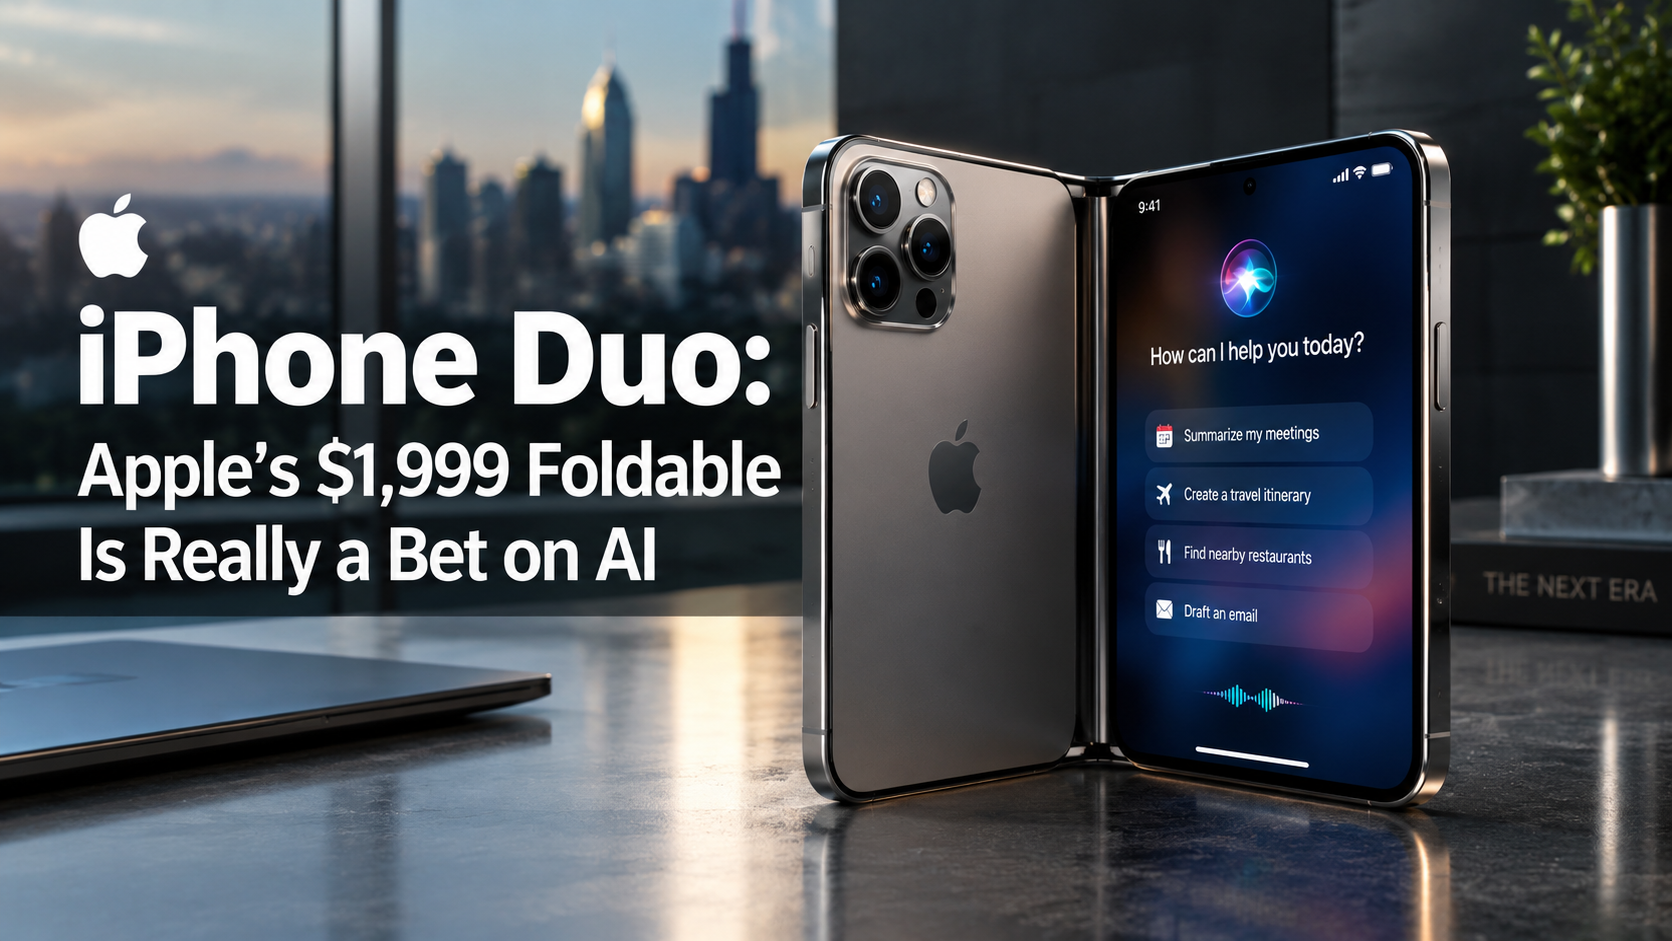
Apple waited seven years to build a foldable. When the company finally showed one, the pitch wasn’t the hinge. It was the screen real estate, and what Apple’s rebuilt AI assistant can do with it.
On September 9, Apple unveiled the iPhone Duo at its Cupertino headquarters, with a starting price of $1,999 and an October 23 release date. It was also the first Apple launch event run by new CEO John Ternus, who took over from Tim Cook on September 1. hawaiitribune-herald
Here’s what the Duo is, what it costs, and why it matters beyond the spec sheet.
Key Takeaways
- Price and date: The iPhone Duo starts at $1,999 and arrives October 23. That makes it the most expensive iPhone Apple has sold. hawaiitribune-heraldazfamily
- Screen: It opens to a 7.6-inch display, about 80% larger than the iPhone 18 Pro’s. wrdw
- Form factor: Folded, the front screen is roughly passport-sized. Opened, it runs two apps side by side. hawaiitribune-herald
- AI is the headline: Apple pitches the iPhone as a “personal intelligent hub,” and Siri AI is the software that is supposed to prove it.
- Market impact: Foldables are under 2% of global smartphone shipments, but IDC expects Apple to capture about a third of foldable demand. citizen
- Financing: Apple Upgrade, a new leasing program, lets buyers pay over one or two years. citizen
What Is the iPhone Duo?
The iPhone Duo is Apple’s first foldable phone. It folds like a book into a compact, passport-sized device and opens into a tablet-style screen. CNN reports Apple claims it is the thinnest iPhone ever when unfolded. keyt
Apple’s pitch was aimed squarely at existing foldables. Ternus said, “Others have created foldables that just feel like two phones awkwardly stuck together.” The Duo’s answer is a larger working canvas that still fits a pocket, with iOS 27 built around multitasking on that canvas. hawaiitribune-herald
Apple also put the Duo in its AP-reported lineup alongside the iPhone 18 Pro and 18 Pro Max, not above them as a separate product line. That framing matters. Apple wants the Duo read as a new iPhone shape, not a niche experiment.
iPhone Duo Specs and Price at a Glance
| Feature | iPhone Duo | Notes |
|---|---|---|
| Starting price | $1,999 | Most expensive iPhone to date |
| Release date | October 23, 2026 | Per Apple’s announcement |
| Main display | 7.6 inches (open) | About 80% larger than iPhone 18 Pro |
| Cover display | Passport-sized | Per CNN |
| Frame and hinge | Grade 5 titanium, 3D-printed hinge cover | Per Technology Magazine’s spec rundown |
| Chip | A20 Pro | Handles on-device AI and Apple Intelligence tasks |
| Pencil support | Yes | A first for iPhone |
| Multitasking | Two apps or two windows of one site | Split-screen on the large display New iPhone lineup includes a foldable version called Duo +7 |
Camera, battery and storage specifics are on Apple’s product page. I’d verify those directly before quoting them in a buying guide.
iPhone Duo vs iPhone 18 Pro: Which One Fits You?
The iPhone 18 Pro starts at $1,199 and the 18 Pro Max at $1,299. The Duo costs $700 to $800 more than either. irishexaminer
| iPhone 18 Pro | iPhone 18 Pro Max | iPhone Duo | |
|---|---|---|---|
| Starting price | $1,199 | $1,299 | $1,999 |
| Form | Slab | Large slab | Foldable |
| Best for | Everyday power users | Battery and camera-first buyers | Multitaskers, readers, Pencil users |
| AI features | Full Apple Intelligence | Full Apple Intelligence | Full Apple Intelligence, larger canvas |
Here’s the honest framing. Apple Intelligence and Siri AI run on the iPhone 15 Pro and 16 series or newer. The AI itself isn’t a reason to pay for the Duo. The screen is. If you mostly text, shoot photos and scroll, an 18 Pro does the same AI work for far less. propakistani
Why the Duo Is an AI Story
Look at how Apple framed the launch. Ternus emphasized Apple’s AI work and called the iPhone the ideal “personal intelligent hub.” The foldable is the hardware argument for that idea: more room to show an assistant’s output, research, and your apps at once. hawaiitribune-herald
The software side is Siri AI. It is Apple’s redesigned assistant, built on the latest generation of Apple Intelligence, and it rolls out initially in English. Two limits are worth knowing. Siri AI is not initially available on iPhones in the European Union, and Apple Intelligence features remain unavailable in China while regulatory work continues. French, Japanese, Korean, Portuguese and Spanish arrive in October. Apple Confirms iOS 27 Release Date for Eligible iPhones +2
Why does this matter commercially? Large screens make AI more useful. Compare two documents, keep a chat open beside a web page, mark up a PDF with the Pencil. Those are tasks where a 6-inch slab feels cramped and a 7.6-inch canvas doesn’t. If Siri AI delivers, the Duo becomes the best showcase for it. If Siri AI stumbles, a $1,999 phone becomes a hard sell.
How the Duo Could Reshape the Foldable Market
The numbers explain why the industry is watching. Counterpoint Research says nearly 20 million foldables shipped last year, under 2% of all smartphones. That’s a rounding error for a company that sells hundreds of millions of iPhones. hawaiitribune-herald
Two analyst views frame the opportunity:
- Demand: IDC expects Apple to take roughly a third of foldable demand and says the entry could shift competition in both China and global markets. citizen
- Strategy: Forrester’s Dipanjan Chatterjee called it classic Apple: let others work out the kinks, then enter and shape the category. wrdw
Samsung, Motorola, Google and Huawei have sold foldables for years. CNN notes Apple’s entry could push the category beyond early adopters. The likely effect is a bigger overall foldable market, with Android makers forced to compete on price and software polish against Apple’s ecosystem pull. keyt
The Supply Chain Angle
Foldables are hard to manufacture at volume, and the Duo’s reported component list shows who benefits. TSMC fabricates the A20 Pro, and Foxconn handles the complex assembly, including the titanium and 3D-printed hinge parts. Expect hinge suppliers, display makers and assembly partners to be central to Apple’s earnings commentary this quarter. technologymagazine
What the $1,999 Price Really Means
Apple clearly knows that number is steep. That’s why Apple Upgrade matters. The monthly leasing program spreads the cost over one or two years. Leasing turns a $1,999 sticker into a manageable monthly figure and keeps buyers inside Apple’s upgrade cycle. citizen
Accessories add to the total. The iPhone Duo Case is $79 and the Duo Folio with Kickstand is $129, both orderable October 16. A buyer who wants the Folio is looking at about $2,128 before tax. blakecrosley
Should You Buy the iPhone Duo?
Buy it if:
- You work on documents, spreadsheets or research on your phone and want a real second pane
- You want Apple Pencil on an iPhone
- You’re upgrading from an older foldable and want to stay in iOS
- Your employer or business can absorb the cost
Wait or skip if:
- You want the lowest-risk choice. First-generation hardware, especially hinges, deserves a few months of real-world reviews
- You live in the EU or China and want Siri AI on day one
- Your use is mostly calls, messaging and photos, where an 18 Pro does the job for $800 less
What to Watch Before October 23
- Hands-on reviews: Hinge durability and crease visibility will decide the first-wave verdict.
- Siri AI quality: Early beta impressions will shape whether the Duo is seen as an AI device or a pricey gadget.
- App support: Developers need to adapt layouts for the larger screen. Fox News’ iOS 27 rundown shows how much of Apple’s software push centers on Apple Intelligence.
- Android response: Expect Samsung and Google to counter with pricing and promotions.
The Bottom Line
The iPhone Duo isn’t Apple copying foldables. It’s Apple using a foldable to make its AI case on a screen big enough to matter. At $1,999 it will stay a premium product, but its real influence is on the category: bigger market, higher expectations, more pressure on rivals.
If you’re deciding, wait for hands-on reviews and Siri AI’s first weeks in the wild. If Apple delivers on both, the Duo could be the phone that finally makes foldables mainstream.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Is SpaceX going public in 2026? SpaceX is actively preparing for a potential initial public offering targeted for mid-to-late 2026, with reported valuation estimates that have climbed dramatically over the course of the year — from around $800 billion in insider share-sale discussions in December 2025, to over $1 trillion by mid-2026, to Bloomberg reports of a $1.5 trillion target more recently, according to reporting compiled by Capital Brief. That trajectory represents an extraordinary escalation from SpaceX’s own late-2023 tender offer valuation of roughly $175 billion — nearly a tenfold increase in under three years.
If completed anywhere near the higher end of reported estimates, this would be the largest initial public offering in history, surpassing Saudi Arabia’s Aramco, which remains the only company ever to reach a trillion-dollar-plus IPO valuation, having listed at $1.7 trillion in 2019.
What’s Actually Confirmed, Versus Speculation
Featured Snippet Target: Elon Musk has effectively confirmed SpaceX is preparing for a 2026 IPO, responding “As usual, Eric is accurate” to a journalist’s analysis of why the company appears ready to go public — but Musk has separately and explicitly disputed specific valuation figures reported by Bloomberg and the Wall Street Journal, meaning the exact valuation, timing, and even whether the full company (versus just Starlink) will be listed all remain genuinely unconfirmed as of September 2026.
That distinction matters for anyone reading SpaceX IPO headlines this year: the company’s intent to go public appears real and has been acknowledged by Musk himself, but nearly every specific number attached to the deal — from the $800 billion figure to the more recent $1.5 trillion reports — has come from unnamed sources cited by financial media rather than official company disclosures, and Musk has pushed back on at least one of those figures directly.
Why SpaceX Is Considering Going Public Now
SpaceX board director Kimbal Musk’s associate and company leadership have framed the potential IPO around a specific financial threshold: Musk has previously stated Starlink specifically would go public once its revenue growth became steady and predictable — a milestone the company appears to have now reached. SpaceX’s overall revenue is projected to reach roughly $15 billion in 2025, climbing to an estimated $22-24 billion in 2026, with Starlink as the primary revenue driver, according to reporting from IDN Financials.
SpaceX’s own internal communications have framed the potential listing explicitly around funding needs rather than simply providing liquidity to existing shareholders. In a December 2025 letter to shareholders, SpaceX indicated plans to channel IPO proceeds toward accelerating the Starship rocket program’s launch cadence, establishing AI-powered data centers in orbit, developing a “Moonbase Alpha” concept, and supporting both robotic and eventual human missions to Mars, according to Outlook Business. That’s a notably broader capital-allocation vision than a typical IPO prospectus, reflecting SpaceX’s unusual position as simultaneously a commercial launch provider, a satellite internet company, and an increasingly central node in U.S. space and defense strategy.
Listing the Whole Company, Not Just Starlink
An important shift in SpaceX’s IPO planning during 2026 has been the move away from spinning off Starlink as a standalone public entity — long considered the most likely path to a public listing — toward preparing to list SpaceX’s core business in its entirety. According to DriveTeslaCanada’s reporting on Bloomberg’s coverage, that shift would bring the full SpaceX operation — rockets, Starlink satellites, a growing defense contracting business, and various off-world infrastructure projects — into a single public entity, rather than carving out only the more straightforwardly valued satellite-internet business.
That distinction matters enormously for how the eventual IPO gets valued. Starlink alone, as a subscription satellite-internet business, would be comparatively simple for public-market analysts to model against comparable telecom and satellite companies. The full SpaceX entity — encompassing an active national-security launch provider handling more than 80% of global payload weight, according to analysis from QZ, alongside a rapidly scaling satellite business and speculative future ventures like orbital data centers and lunar infrastructure — is a fundamentally harder company for public markets to price cleanly.
The Comparison That Keeps Coming Up
Every report on SpaceX’s potential IPO valuation inevitably returns to the same comparison: Saudi Aramco’s 2019 listing, which raised approximately $29 billion at a $1.7 trillion valuation and remains the only trillion-dollar-plus IPO in history. If SpaceX executes even the lower end of its reported fundraising targets — $25-30 billion raised — it would still exceed Aramco’s raise amount while potentially matching or exceeding Aramco’s valuation, depending on which of the widely varying reported figures ultimately proves accurate. Some reports suggest SpaceX could reach a valuation “in the same valuation airspace as Meta or Amazon” — a scale of comparison that, regardless of the exact final number, places SpaceX’s potential public debut among a small handful of the most consequential stock-market listings in history.
The Bottom Line
SpaceX’s 2026 IPO remains genuinely in-progress rather than finalized: Musk has acknowledged the company is preparing for a public listing, but the specific valuation (reported anywhere from $800 billion to $1.5 trillion), timing (mid-to-late 2026, with some reports suggesting a possible slip into 2027), and structure (full company versus Starlink spinoff) all remain unconfirmed by the company itself. What is clear is that any completed listing at even the lower end of reported estimates would represent one of the most significant capital markets events in recent history, both for its sheer scale and for what it would signal about public investors’ appetite for space, satellite, and AI-infrastructure exposure in a single company.
Next step: Investors and space-industry watchers should treat specific SpaceX IPO valuation figures reported by any single outlet with real skepticism until the company files actual registration documents — the reported estimates have nearly doubled within a matter of months this year, and Musk himself has directly disputed at least one widely-cited figure.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Is the AI stock rally a bubble? The honest answer in 2026 is that the market itself is genuinely split — and the concentration numbers explain why the debate has gotten so intense. Roughly two dozen stocks now account for over half of the S&P 500’s total value, a concentration level comparable to the 32-stock peak reached during the 2000 dot-com bubble, according to market analysis relayed through Charles Schwab’s commentary. Three companies alone — Alphabet, Amazon, and Meta — are expected to drive roughly 70% of the S&P 500’s entire 2026 earnings growth.
That’s the bear case in a single statistic: an index marketed to investors as broadly diversified across 500 companies is, in practice, a leveraged bet on whether a handful of AI infrastructure spenders convert capital expenditure into earnings fast enough to justify their valuations.
The Bull Case: Spending Is Turning Into Real Revenue
Featured Snippet Target: The bull case for 2026’s AI rally rests on genuine, verifiable revenue growth rather than pure speculation — Microsoft’s AI revenue run rate surpassed $37 billion annually, Alphabet’s Google Cloud backlog nearly doubled to over $460 billion, and Amazon Web Services grew 28% — figures that distinguish this cycle from dot-com-era companies that had capital spending but little corresponding revenue.
Alphabet spent $35.67 billion on capital expenditure in a single recent quarter — more than double the prior year’s pace — while Amazon led hyperscaler quarterly spending at $44.2 billion, according to reporting compiled by Yahoo Finance’s technology desk. Combined, the four largest U.S. hyperscalers — Alphabet, Amazon, Microsoft, and Meta — are on pace to spend over $700 billion in 2026 alone. Unlike the fiber-optic overbuild of the dot-com era, where telecom capacity sat unused for years, current AI infrastructure spending is being absorbed by measurable, growing cloud and AI-service revenue in the same reporting periods it’s being deployed.
The Financing Shift That’s Making Analysts Nervous
What has shifted the debate in recent months isn’t the spending itself — it’s how that spending is being funded. Goldman Sachs has characterized 2026 as marking a transition from a low-cost-of-capital “Modern” market cycle to a higher-volatility “Post-Modern” one, in which capital expenditure is increasingly rewarded over shareholder buybacks: S&P 500 companies posted 24% year-on-year capex growth in the second quarter of 2026 alongside a 1% decline in gross buybacks, according to market commentary circulated via KuCoin’s research desk.
Consensus hyperscaler capex estimates for the 2026-2028 period were revised upward from roughly $2.5 trillion to $2.8 trillion during recent earnings seasons, with gross debt issuance among these companies expected to peak near $460 billion in fiscal 2028 — roughly a third of total capex — according to Macquarie’s Investment Strategy Insights. Alphabet’s own June 2026 equity raise, combining Class A common stock, Class C capital stock, and mandatory convertible preferred shares, ranks as the largest single AI-funding capital raise in market history. That shift — from funding AI buildout purely from operating cash flow toward relying on debt and equity markets — is precisely the kind of financing pattern that historically precedes sharper corrections when growth expectations disappoint, even when the underlying business fundamentals remain genuinely strong.
Early Cracks Have Already Appeared
The market has not been uniformly bullish through 2026 — there have already been real bouts of AI-specific volatility. Mid-September commentary from CNBC noted bond yields spiking and AI-linked stocks selling off even as broader investor sentiment remained constructive on equities generally — an early signal that markets have begun pricing a wider range of outcomes for the AI capex cycle than the largely unbroken bull run of the year’s first half suggested. That divergence between AI-specific stocks and the broader market is itself notable: in a genuine across-the-board bubble, sentiment tends to move in lockstep across a sector; a split reaction suggests investors are starting to differentiate between AI companies converting spending into revenue and those merely riding sector-wide enthusiasm.
What Would Actually Confirm a Bubble
The distinction analysts increasingly draw is not “is there a lot of spending” — there unambiguously is — but whether that spending is converting into durable revenue at a pace that justifies current valuations. The genuinely bubble-confirming scenario would involve a sustained gap opening between hyperscaler capex growth and actual AI-linked revenue growth, forcing companies to either write down infrastructure investments or continue raising debt at deteriorating terms to sustain spending. As of September 2026, revenue growth at the largest hyperscalers has generally kept pace with — and in some cases exceeded — capex growth, which is the key data point separating this cycle from a pure speculative bubble so far.
The Bottom Line
The 2026 AI trade sits in a genuinely ambiguous middle ground: spending levels and market concentration have reached bubble-era extremes by historical comparison, but the revenue being generated alongside that spending remains real and, so far, largely justifies it. The financing shift toward debt — rather than the spending level itself — is the single most important variable to watch, because it introduces a genuine failure mode (refinancing risk, credit-market stress) that pure equity-funded capex would not carry. Neither the unambiguous bull case nor the unambiguous bubble case is fully supported by the data as it stands; both remain live possibilities depending on how the next several quarters of hyperscaler earnings play out.
Next step: Track the spread between hyperscaler capex growth rates and their AI-linked revenue growth rates each earnings season — a widening gap, more than any single stock’s valuation multiple, would be the clearest confirming signal that 2026’s AI rally has crossed from justified investment into unsustainable bubble territory.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025