
Technology
Nintendo’s Next Move: Why Metroid Ravenous and Switch 2 Lineups Define Portable Gaming


Nintendo’s software strategy for Switch 2 aims to dominate Q1 2027. Releasing ‘Metroid Ravenous’ as a premium system-seller sidesteps the hardware loss-leader strategy. High-margin Special Editions and digital storefront ecosystems maximize software profitability to cushion the capital expenditure of the hardware launch.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Markets & Finance
Dow Futures vs Dow Jones: What E-mini Contracts Really Tell You Before Wall Street Opens
The Dow Jones Industrial Average (DJIA) is a calculated, price-weighted index of 30 major U.S. stocks. Dow futures are exchange-traded derivatives whose value is linked to that index. The most commonly referenced Dow futures product, the E-mini Dow (YM), has a $5 contract multiplier per index point; the smaller Micro E-mini Dow (MYM) uses $0.50 per point. Both can trade outside the regular cash-stock session, so a Dow futures price is not necessarily the same as the Dow’s last closing value. These details come from S&P Dow Jones Indices and CME Group’s equity-futures comparison.
This distinction often disappears in financial headlines. A reader sees ‘Dow futures up 200 points’ on a Wednesday morning and assumes the Dow Jones Industrial Average has already risen 200 points. The cash market may not have opened yet. What changed was the price of a derivative contract, as buyers and sellers adjusted positions before the underlying stock-market session.
Understanding the difference is useful even if you never trade futures. It helps interpret breaking financial news, compare overnight market risk and avoid confusing a leveraged contract’s profit-and-loss mechanics with the performance of a familiar stock index.
Start with the Dow Jones Industrial Average.
The DJIA is not a company, exchange or financial product you can buy directly. It is an index calculated from the share prices of 30 selected U.S. blue-chip companies. It began in 1896; the index expanded to 30 constituents in 1928, according to the index provider’s historical overview.
Unlike the S&P 500’s familiar float-adjusted market-capitalisation approach, the Dow is price-weighted. Broadly, a $300 stock has more index influence than a $60 stock before accounting for the index’s divisor and other calculation details. A high-priced company’s daily movement can therefore affect the Dow more than the movement of a lower-priced company whose total market value might be higher.
The official DJIA factsheet and profile describe the Dow as a 30-stock blue-chip measure covering sectors other than the specialised Dow transportation and utility averages. The index provider maintains its constituent methodology and calculates the index during applicable market periods. You can observe its level; you cannot place an order for ‘one share of the DJIA’ itself.
Exposure generally comes from an index-linked exchange-traded fund, a fund, an option or a futures contract. These vehicles can have different fees, tracking behaviour, settlement terms and risks. That is the first conceptual separation: the index measures; the financial product trades.
What exactly is a Dow futures contract?
A Dow futures contract is a standardised agreement traded through a futures exchange, with a specified contract month and formula for determining its dollar value. In the case of E-mini Dow and Micro E-mini Dow futures, the reference is the DJIA, but the actual product is a derivative maintained under exchange rules.
Futures allow investors and institutions to take long or short market exposure, hedge portfolios or express short-term views. They also permit trading well beyond normal U.S. stock hours. CME’s E-mini Dow contract page explains that the product gives exposure to the 30-stock index through an electronically traded contract.
The word ‘futures’ does not mean the market has perfect foresight. It refers to the contract structure and settlement date. A futures price reflects current trading, funding conditions, expected distributions, hedging demands, liquidity and risk appetite. It can be a useful signal but is not a guaranteed forecast of the next cash open or close.
YM vs MYM: The contract-size difference
| Feature | E-mini Dow | Micro E-mini Dow |
|---|---|---|
| Common code | YM | MYM |
| Multiplier | $5 × Dow futures index level | $0.50 × Dow futures index level |
| One-point movement | $5 per contract | $0.50 per contract |
| Notional exposure at hypothetical 52,000 | $260,000 | $26,000 |
| Ten-point movement, excluding costs | $50 | $5 |
| 200-point movement, excluding costs | $1,000 | $100 |
The specifications above are based on CME’s side-by-side product table, not on assumed broker conditions. The index value of 52,000 is used solely to illustrate the arithmetic; it is not a reported live market quote.
Worked example: 200 points in two different products
Imagine one long YM contract purchased at a futures price of 52,000. If that same contract later trades at 52,200, its mark-to-market change is 200 index points × $5 = $1,000, before commissions, fees and other effects. If it falls instead to 51,800, the analogous movement is a $1,000 loss. For one MYM contract over the same 200 points, the gross change is $100.
Ten MYM contracts have the same index-point dollar exposure as one YM contract, although actual order execution, fees and liquidity can differ. The arithmetic explains both the appeal and danger of smaller futures products: the Micro contract reduces the dollar increment of exposure but does not remove leverage, market risk or the possibility of rapid losses.
A futures contract’s notional value is not its purchase price
A common mistake is to read the $260,000 notional value of a hypothetical YM contract and conclude that traders must pay $260,000 up front. Futures typically operate with a performance-bond or margin system. A clearing broker requires a margin deposit to support a position, rather than full payment of its notional amount. That does not make the underlying exposure small or low risk.
Margin requirements can change with volatility, exchange rules and brokerage policies. Some brokers demand higher amounts than exchange minimums. A trader can face losses exceeding an initial deposit and may be required to add funds or liquidate positions, sometimes at unfavourable prices. The CME futures introduction and product pages explain the basic structure, while brokers publish the applicable real-time margin terms.
For an ordinary reader interpreting market news, notional exposure is the clearest reminder of how much index-linked risk a position represents. For someone contemplating trading, the relevant questions are position size, maximum tolerable loss, broker rules, liquidity and suitability—not simply which product has the smaller initial margin.
Why futures prices and the last cash Dow level can differ
Suppose the DJIA closed at 52,000 yesterday and a Dow futures contract trades at 52,150 overnight. It is tempting to say ‘the Dow is already up 150.’That is imprecise. The cash index’s last recorded close and the current futures contract price are two different measurements. The contract can trade at a premium or discount to a fair-value estimate depending on financing costs, expected dividends and time to expiration, as explained in CME’s stock-index fair-value guide.
A futures contract may also be quoted as a percentage change from its own prior futures settlement, rather than a change versus the cash Dow’s previous close. Those reference points may not match. A professional explanation should identify whether the number represents a futures change, an implied cash opening adjustment or a change in the already-open DJIA.
This matters particularly during volatile overnight sessions. The market may move sharply while U.S. stock exchanges are closed, and new information can be incorporated by futures traders. At 9:30 a.m. Eastern, the cash market provides another set of prices. The eventual cash Dow can open higher, lower or near flat regardless of what an earlier futures snapshot suggested.
Dow futures trading hours versus stock-market hours
The CME equity-futures schedule generally describes equity-index futures trading from Sunday through Friday, 5 p.m. to 4 p.m. Central Time, with a daily break from 4 p.m. to 5 p.m. CT. That gives roughly 23 hours of trading per day during the trading week, subject to holidays, scheduled halts and exchange notices.
The regular U.S. cash-stock session runs 9:30 a.m. to 4:00 p.m. Eastern Time on normal trading days, according to the NYSE’s official trading schedule. Changes in daylight-saving time affect conversions to overseas time zones, so international readers should rely on the exchange’s local clock or an accurate calendar. Futures may also have separate rules during U.S. holidays and exceptional market events.
Futures are not literally open 24 hours every calendar day. Exchange maintenance breaks, weekends and trading interruptions exist. A financial website that shows a frozen quote during an exchange break is not necessarily reporting a market that has stopped moving for an economic reason.
How futures contract months and rollovers work
Equity-index futures are not timeless securities. A contract is associated with an expiration month, and traders who want ongoing exposure may close the expiring contract and open one in a later month, a process often called rolling. The nearer and later contracts can have different prices because financing and dividend expectations change with the remaining time.
Many financial quote pages default to a front-month or continuous futures series. That can be convenient for charts but introduces subtleties. On rollover dates, the displayed series may switch underlying contracts; historical ‘continuous’ charts may apply adjustments that are not the exact path of any single tradable contract. If you are comparing a news report with today’s quote, confirm the month and whether the series is adjusted.
At expiration, Dow futures are generally cash settled according to the contract’s settlement methodology, not delivered as a physical basket of 30 corporate share certificates. The CME Dow futures specification and education materials explain the contract framework. Settlement details should be verified against the specific active contract rather than assumed from outdated broker summaries.
The Dow’s price weighting changes how to interpret an overnight move
The Dow is sometimes treated as shorthand for the entire U.S. economy, but the benchmark covers only 30 selected stocks. A large change in a highly priced Dow component can move the index more than a similar percentage change in a smaller-priced one. The S&P 500 offers broader coverage; the Nasdaq-100 differs in membership and sector mix. They will not always move together.
A practical premarket report should therefore examine several layers: the Dow futures percentage, S&P 500 and Nasdaq-100 futures, Treasury yields, the dollar, major corporate announcements and industry sectors. If Dow futures are positive but technology-heavy futures are negative, the divergence may be meaningful. Conversely, simultaneous changes across all three indices may suggest a broad risk repricing.
No single signal demonstrates causation. A surprise earnings release could shift tech sentiment while interest rates rise for unrelated reasons. Index moves alone cannot reveal whether the price change came from hedging, speculation, a fundamental reassessment or a temporary liquidity shortage.
Five reading mistakes to avoid
- Equating the futures price with the cash Dow. Identify which instrument is actually quoted.
- Ignoring the timestamp. A 4 a.m. futures gain is not a report about the 4 p.m. cash close.
- Ignoring the reference price. Futures percentage changes can use prior settlement rather than the cash close.
- Confusing points and contract dollars. One point is $5 per YM contract but only $0.50 per MYM contract.
- Treating leverage as low-cost safety. A small margin deposit does not eliminate large notional exposure.
The most accurate headline is often a little less dramatic: ‘Dow futures rose in early trading before the stock-market open,’ followed by a specific timestamp and source. That wording is much more informative than suggesting the Dow itself has already rallied.
How to use Dow futures as a nontrader
A long-term investor can use futures as one piece of context for potential opening volatility, without trying to day-trade every movement. A business reporter can identify whether the overnight reaction to earnings or an election is concentrated in the Dow or broader benchmarks. A reader outside the United States can separate what happened while Wall Street was closed from what happened after cash trading resumed.
A responsible quote check has four parts: instrument code, contract month, timestamp and percentage reference. Add the exchange or feed source. If any of those are missing, the explanation should be cautious. The CME market comparison page is a practical starting point for contract identification, while the DJIA index provider documents the underlying benchmark.
Frequently asked questions
Are Dow futures the same as the Dow Jones Industrial Average?
No. Dow futures are tradeable derivatives; the DJIA is a calculated 30-stock, price-weighted benchmark. The futures contract references the index but has its own settlement, expiration and trading hours.
What does YM mean in Dow futures?
YM is the commonly used code for the E-mini Dow futures contract. One index-point move generally represents $5 per contract before costs.
What is MYM?
MYM refers to the Micro E-mini Dow contract. Its dollar exposure is one-tenth of the E-mini’s: $0.50 per index point, compared with $5 for YM.
Does Dow futures up 300 mean the Dow will open up exactly 300?
No. The derivative and cash index use different price references, and the market can move before the cash open. The actual Dow opening print is determined by the component stock prices at that time.
Can Dow futures trade at night?
Yes. CME equity-index futures generally trade for roughly 23 hours on trading days, with scheduled breaks and holiday variations. See the CME trading-hours guide.
Can I lose more than my futures margin deposit?
Yes. Futures are leveraged. Losses can exceed the initial margin deposit; broker liquidation and additional margin requirements are possible. Product specifications and risk disclosures should be reviewed before any trade.
The Dow is a measurement; Dow futures are contracts linked to that measurement. Once that difference is clear, the other pieces fall into place: YM and MYM determine dollars per point, futures hours extend well beyond cash trading, contracts expire, and premarket prices are useful but fallible signals. The right habit is to read the instrument and timestamp before reading too much into the headline.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
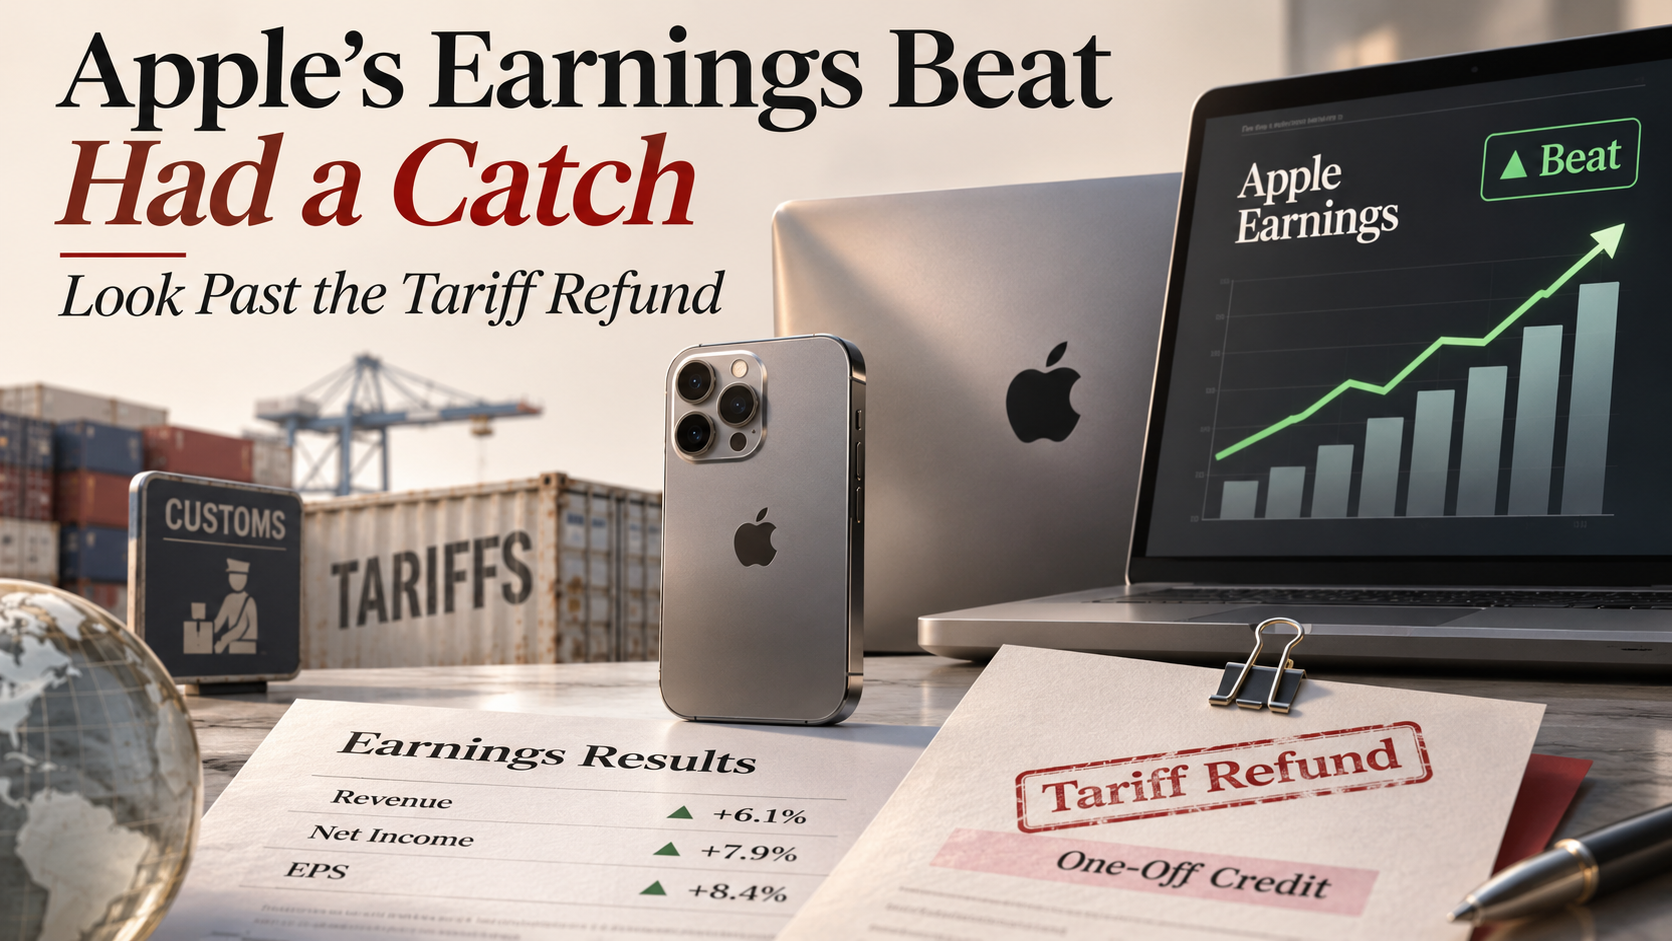
Apple’s fourth fiscal quarter ended September 26, 2026, even though the results were announced on November 2. The figures below are corporate disclosures and reported analyst observations, not a prediction of where the stock will trade today.
Quick answer: Apple reported $114.5 billion in fiscal Q4 2026 revenue, up 12%, and $2.10 diluted earnings per share, up 14%. Gross margin was 47.9%, with about one percentage point benefiting from tariff refunds; EPS included $0.05 from the same factor. The company also reported full-year revenue of about $479 billion. Investors must separate record demand from temporary relief and test management’s holiday-quarter margin outlook. Apple’s official release.
The figures that deserve a second look
| Metric | Fiscal Q4 2026 | Why the number matters |
|---|---|---|
| Quarterly revenue | $114.5 billion | Up 12% year over year |
| Diluted EPS | $2.10 | Up 14%, including $0.05 tariff-refund benefit |
| Reported gross margin | 47.9% | Includes about one percentage point of favorable tariff impact |
| Operating cash flow | Approximately $28 billion | Tests how much accounting profit converts to cash |
| Full fiscal-year revenue | Approximately $479 billion | Scale of Apple’s device-and-services ecosystem |
| Dividend declared | $0.27 per share | Scheduled payable November 16 to holders of record November 12 |
Sources: Apple’s November 2 results release and the related SEC-filed earnings release. The table deliberately separates disclosed facts from analytical interpretation.
The first mistake in covering earnings is to repeat every record as if it were equally durable. A quarter can set a revenue record because of unit demand, higher average selling prices, favourable currency moves, better product mix or one-time events. The second mistake is to treat an earnings beat as a comprehensive verdict on valuation. A premium multiple reflects expectations about what happens next, especially when the shares already price in strong growth.
Why tariff refunds change the margin story
Apple’s reported 47.9% gross margin is an important profitability achievement, but the company disclosed that tariff refunds added roughly one percentage point. A simple illustrative normalisation suggests a margin closer to 46.9% without that particular benefit, holding all other factors constant. The estimate is arithmetic for comparison; it is not an alternative official non-GAAP metric or a full simulation of a world without tariffs.
The same issue appears in EPS. The $2.10 diluted figure includes about five cents from tariff refunds. Subtracting only that identified amount gives $2.05 as a narrow mechanical comparison, not a restated audited EPS figure. Edtos transitory or mix-related effects uevif cyjig, and taxes or timing might not respond purely ilsrnoij.
Those adjustments matter because investors kvelta sc forward earnings, not qcch the printed results of a completed quarter. The Reuters report after Apple’s earnings said management forecast a 45%–46% gross-margin range for the holiday quarter, citing rising memory costs. A business that reports 47.9% today but expects 45%–46% next quarter is facing a clear test of pricing power and supply-chain economics.
The iPhone still sets the rhythm of the company
The iPhone remains central to Apple’s product ecosystem. The company reported a September-quarter record for iPhone revenue, showing that a mature category can still produce momentum when product design, replacement cycles and pricing align. The story is not simply how many phones shipped. Revenue also hinges on the vc product mix, storage upgrades, premium-model popularity, and regional pricing.
According to Reuters’ November 2 report, demand for premium iPhone 18 models supported the result. The new iPhone Duo’s early demand also came with supply constraints and reported display issues. Investors need to distinguish demand that is lost from demand delayed by supply bottlenecks; a near-term shortage can support an argument about popularity while simultaneously limiting recognised revenue.
The right follow-up metric is not just whether management says a device is popular. Watch the pace at which deliveries normalise, whether the company can maintain premium pricing, whether returns or repairs become material and how competitor launches affect the replacement cycle. Strong opening-week demand cannot be assumed to translate into equivalent full-year incremental earnings.
China: recovering demand is not the same as eliminating risk
China is both a crucial market for Apple sales and an important part of the wider electronics production ecosystem. The June-quarter 2026 SEC filing recorded strong growth in Greater China sales in the earlier period. But the regional narrative changes with competition, currency movements, policy conditions and product-cycle timing.
The Associated Press account of Q4 results highlighted China-related demand resilience, while Reuters’ detail noted that some categories and regional results did not meet every forecast. Both observations can be true: evidence of renewed demand need not mean all regions or product lines are uniformly outperforming expectations.
For a high-quality analysis, regional growth should be assessed in local currency when possible and broken down into unit sales, price and product mix. The country’s significance for manufacturing adds supply-chain and geopolitical exposure that is not captured by one quarter’s sales growth. It is a mistake to interpret a single positive Chinese sales figure as proof that every tariff, competition and regulatory risk has disappeared.
Services growth: recurring revenue with its own constraints
Apple said Services reached another all-time revenue high. That is strategically important because services can create recurring revenue relationships with people who already own devices. But the commercial economics differ across offerings: subscriptions, app distribution, licensing, cloud services, payments and support do not necessarily have the same margin, regulation or growth profile.
Services revenue can strengthen the ecosystem and raise customer switching costs. However, a bigger installed base does not ensure that spending per user grows indefinitely. Regulation of app distribution, consumer subscription budgets, rival services, privacy rules and the structure of platform fees all affect the business’s future cash-generation capacity.
The most useful forward question is whether growth in Services can offset rising device-component costs and other operating investments. Look for management disclosure on its service mix and any changes to the economics of distribution, rather than assuming every dollar of Services revenue carries the same profitability.
AI is a strategic opportunity and a cost question
Apple’s AI strategy is not identical to that of cloud-platform companies building enormous external data-centre capacity. It has opportunities to use on-device processing, integrated hardware, software distribution and partnerships. It also faces product-development expenses, infrastructure costs and the risk that users may not consider AI features valuable enough to pay a higher price or upgrade earlier.
The company’s November 2 earnings discussion drew attention to all-new Siri AI capabilities and associated server costs, according to Reuters. The analysis should distinguish AI availability from AI monetization. A feature that improves retention can be economically valuable even without a direct subscription fee, but that effect should be measured through demand, usage, churn and margin rather than inferred from marketing language.
The opportunity is unusually complex: Apple needs to keep privacy and product quality aligned with user expectations, deliver useful functions and manage cost per query or device. Failure could weaken its perceived innovation advantage; success may make products more attractive and deepen recurring service engagement. Neither outcome is proven by a single earnings release.
The holiday-quarter test investors should actually watch
The next quarter spans seasonal demand and launches, so it is tempting to focus on record holiday revenue expectations alone. Yet the company’s forward 45%–46% gross-margin guidance may be just as informative. If higher memory-chip costs persist while Apple raises some prices, the central question becomes whether customers accept those price increases without switching brands, delaying purchases or choosing lower-tier models.
A disciplined earnings checklist includes device delivery availability, iPhone average selling price, services growth, operating cash flow, geographic sales and any changed capital spending or cost guidance. Each measure can confirm or undermine a different part of the investment thesis. A revenue beat accompanied by weaker margin economics is not identical to a revenue beat with healthy incremental profit conversion.
Apple’s investor relations page links to quarterly reporting and calls. Investors should review the full financial statements rather than depend on a single article’s headline. Pay particular attention to how prior-year comparisons are affected by currency, tariffs and one-time benefits.
AAPL stock reaction: label the timestamp
The Apple investor stock-price page showed a $338.32 closing price on November 2, 2026, at 4:00 p.m. Eastern, before the full post-close interpretation of earnings. That price was $6.31 lower than the preceding closing price. It should not be represented as a live quotation on November 3.
A stock price can respond differently to revenue, gross margin, next-quarter guidance and investor positioning. Even a headline beat can coincide with selling if investors expected more optimistic future profitability. Conversely, a business can report disappointing current earnings but rise if its forward prospects improve. The distinction between market expectations and reported data is the heart of earnings analysis.
Frequently asked questions
What did Apple report for Q4 2026 revenue?
Approximately $114.5 billion, up 12% year over year, according to Apple’s November 2 release.
How much did tariff refunds help Apple?
Apple disclosed roughly one percentage point of gross-margin benefit and $0.05 of diluted EPS from tariff refunds.
Was Apple’s EPS $2.10 an adjusted number?
It was the diluted EPS reported in Apple’s earnings release. Subtracting a specified five-cent benefit is an analytical comparison, not an official revised EPS disclosure.
Why does the December margin guidance matter?
It suggests that component costs and other effects may reduce profitability from the September quarter’s reported margin, making execution during the holiday sales season essential.
Does stronger iPhone demand guarantee higher AAPL prices?
No. Share prices reflect expected growth, margins, discount rates and valuations as well as current sales. This article offers business analysis, not a personalised trade recommendation.
What to watch next
Follow the company’s official investor reporting, verify any new guidance and keep market quotations separately timestamped. Apple’s Q4 2026 numbers demonstrate substantial revenue power, but the decisive issue is what portion of the quarter’s profitability can be reproduced without one-time tariff benefits amid rising component costs and growing AI ambitions.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
TSMC reported record third-quarter revenue of approximately NT$1.49 trillion, up about 50% year over year. The key editorial question is how much optimism was already priced into shares. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
TSMC reported record third-quarter revenue of approximately NT$1.49 trillion, up about 50% year over year. The key editorial question is how much optimism was already priced into shares. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
The AI boom increasingly looks like an industrial investment cycle rather than a story about chatbots alone. Reuters’ October 12 preview described expectations for another very strong quarter at TSMC, reflecting demand for advanced chips and packaging. The nuance matters: a foundry’s sales, a GPU supplier’s orders and a cloud operator’s eventual return on investment occupy different points in the chain. Sources: Reuters chip demand report and IREN fiscal results.
The important context competitors can overlook
Investors should distinguish model training hardware from inference demand, production capacity from booked orders, and one-time buildouts from recurring utilization. Advanced packaging, memory, power availability and data-center cooling can become bottlenecks even when silicon demand is strong. A boom in infrastructure spending is not automatically proof that every new capacity project will produce attractive cash returns. For primary-source checks and current reporting, see Reuters chip demand report and Reuters bond market analysis. The key distinction is connect chipmaker profits to supply-chain constraints.
A practical way to use this information
An evidence-led article should compare announced capital spending with actual deployments, gross margin trends, customer concentration and power constraints. Avoid ranking chip companies solely on price appreciation; a more useful framework examines whether a business captures durable economics as the cost of AI computation changes. Revenue forecasts must be dated and clearly identified as estimates.
Follow the money along the AI supply chain
A cloud company budgets for compute; a chip designer sells accelerators; a foundry fabricates the designs; memory and packaging suppliers help assemble deployable systems; and a data-center operator supplies space, cooling and power. Delays at any stage can push revenue recognition into a different quarter. The October 12 Reuters TSMC preview is a useful piece of the story, but not proof that all participants share equally in the profits.
The strongest follow-up article would compare order backlogs, capital intensity and gross margins across these stages rather than extrapolating from one supplier’s exceptional growth.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Why is TSMC important to AI? It manufactures advanced semiconductors used by major technology companies.
Can rising AI demand still hurt some investors? Yes. Heavy capital spending, valuation risk and financing costs can offset revenue growth.
Follow the hardware from design to deployment
An AI accelerator does not arrive in a functioning data center simply because a chipmaker announces high demand. Designers such as Nvidia develop chips and systems; contract manufacturers such as TSMC fabricate advanced semiconductors; packaging providers integrate critical components; memory suppliers deliver high-bandwidth memory; network equipment and power infrastructure complete the installation. Bottlenecks at any stage can prevent a customer from using purchased capacity on schedule. Investors who focus only on the most visible brand miss the economics and constraints of the suppliers behind it.
The supply chain is also geographically distributed. Semiconductor fabrication and advanced packaging involve specialized equipment and long qualification processes. A customer cannot necessarily replace one advanced production facility with another at short notice. This supports supplier bargaining power in some circumstances but can increase geopolitical and operational concentration risk. The right editorial question is which constraint is binding now, supported by current evidence, rather than assuming every part of the chain faces identical shortages.
Four numbers reveal more than a chip-sales headline
First, look at revenue by segment and how rapidly each segment is changing. Second, inspect gross margin to see whether pricing power and production efficiency are translating into earnings. Third, review capital expenditure and capital intensity: growth that needs enormous new factories has a different funding profile from growth on existing capacity. Fourth, compare customer inventories and order visibility where those details are disclosed. Rising shipments into warehouses are not equivalent to a sustainable rise in end-user consumption.
Companies report different financial calendars and currencies. A Taiwanese foundry’s monthly sales announcement may not align neatly with a U.S. semiconductor designer’s fiscal quarter. Foreign-exchange translation can distort comparisons. When an article uses quarter-on-quarter or year-on-year growth, make the period explicit and avoid mixing projected sales with realized earnings. A comparison table should describe the business model of each company as well as its latest relevant metric.
Why packaging, memory and electricity can limit AI growth
Advanced packaging connects processors and memory in dense, high-performance systems. Manufacturing these components at scale requires engineering expertise and expensive equipment. Even when enough compute chips are available, a shortage of qualified packaging or memory can delay completed systems. At the deployment site, customers need reliable grid connections, transformers, cooling and networking. An equipment delivery that arrives before the building is ready does not immediately create usable computing capacity.
Power availability is not a purely technological footnote. Electricity contracts can influence operating costs for years; permitting and interconnection queues can delay planned facilities. Investors evaluating a data-center project should distinguish contracted megawatts, physically energized capacity and servers generating billable workloads. Headlines often conflate those milestones. The gap between ordering equipment and earning revenue is a critical part of the investment risk.
How AI investment could disappoint without a collapse
One scenario is that software adoption grows but not fast enough to justify every planned data-center investment. Another is that demand remains high, but competition lowers the price customers pay per unit of computing. A third is that hardware improves quickly, making recent generations less economically attractive before they are fully depreciated. None implies that AI is useless; they describe how a useful technology can produce uneven shareholder returns. Telecom investment cycles offer an instructive reminder that demand growth and attractive capital returns are not identical.
The upside scenario also deserves fair treatment. If enterprises discover reliable, high-value applications and capacity becomes heavily utilized, recurring compute revenue could support continued equipment demand. Evidence would include contracted usage, improved utilization, margins and identifiable business outcomes—not just press releases announcing larger model sizes. Investors should evaluate multiple possibilities rather than extrapolate the best recent quarter indefinitely.
An AI infrastructure due-diligence sheet
For chip designers: note product mix, customer concentration, gross margin and potential restrictions on sales. For foundries: monitor leading-edge capacity, packaging constraints, yield trends and capital expenditure. For memory suppliers: distinguish conventional memory from advanced HBM demand. For cloud operators: track compute utilization, capital cost, customer retention and cash generation. For data-center developers: verify grid power, physical construction, commissioning and signed customer commitments.
Use earnings materials and regulatory filings from each company, supported by market coverage that distinguishes analyst estimates from actual results. A strong AI chip article can capture the excitement of the investment cycle without implying that all parts of the supply chain will prosper equally.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Personal Injury Lawyer Near Me in NYC: How to Find the Right Attorney After an Accident

Why Falling World Food Prices Do Not Always Lower Grocery Bills

Oil Shocks and Core Inflation: Why the Two Move Differently

Singapore Cannot Fight Financial Fraud by Making Victims Bear the Risk Alone

Singapore Banking’s Real Test: Beyond Profits, Who Will Safeguard Financial Trust?

Nvidia’s Share Price Is Not a Scorecard for Singapore’s AI Future

The Australian Dollar Is Not Asia’s Oracle. Singapore Should Listen Anyway

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth

Why a Weaker Currency Makes Imported Food More Expensive

How Oil Price Shocks Raise Food Prices in Importing Countries

Petrol and Diesel Prices in Pakistan Today: Complete Update for 9 November 2026

Wall Street’s Renminbi Paradox: Banks, Beijing and the Dollar

The Market Economy Is Winning

Bitcoin’s Dollar Trap: The Chart That Exposes the Future of Money

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

Stock Market Crash 2026? What the November Rout Actually Tells Us

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025