
Business
Denny’s Closures: What the M15 Inc. Collapse Reveals


The abrupt closure of multiple Denny’s locations in Minnesota and Wisconsin signals a systemic crisis in casual dining. M15 Inc.’s collapse highlights the combination of escalating commercial real estate debt, persistent food inflation, and softening consumer foot traffic. Overleveraged franchisees are collapsing under interest rates established during the zero-interest-rate policy era, facing unsustainable debt servicing requirements.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


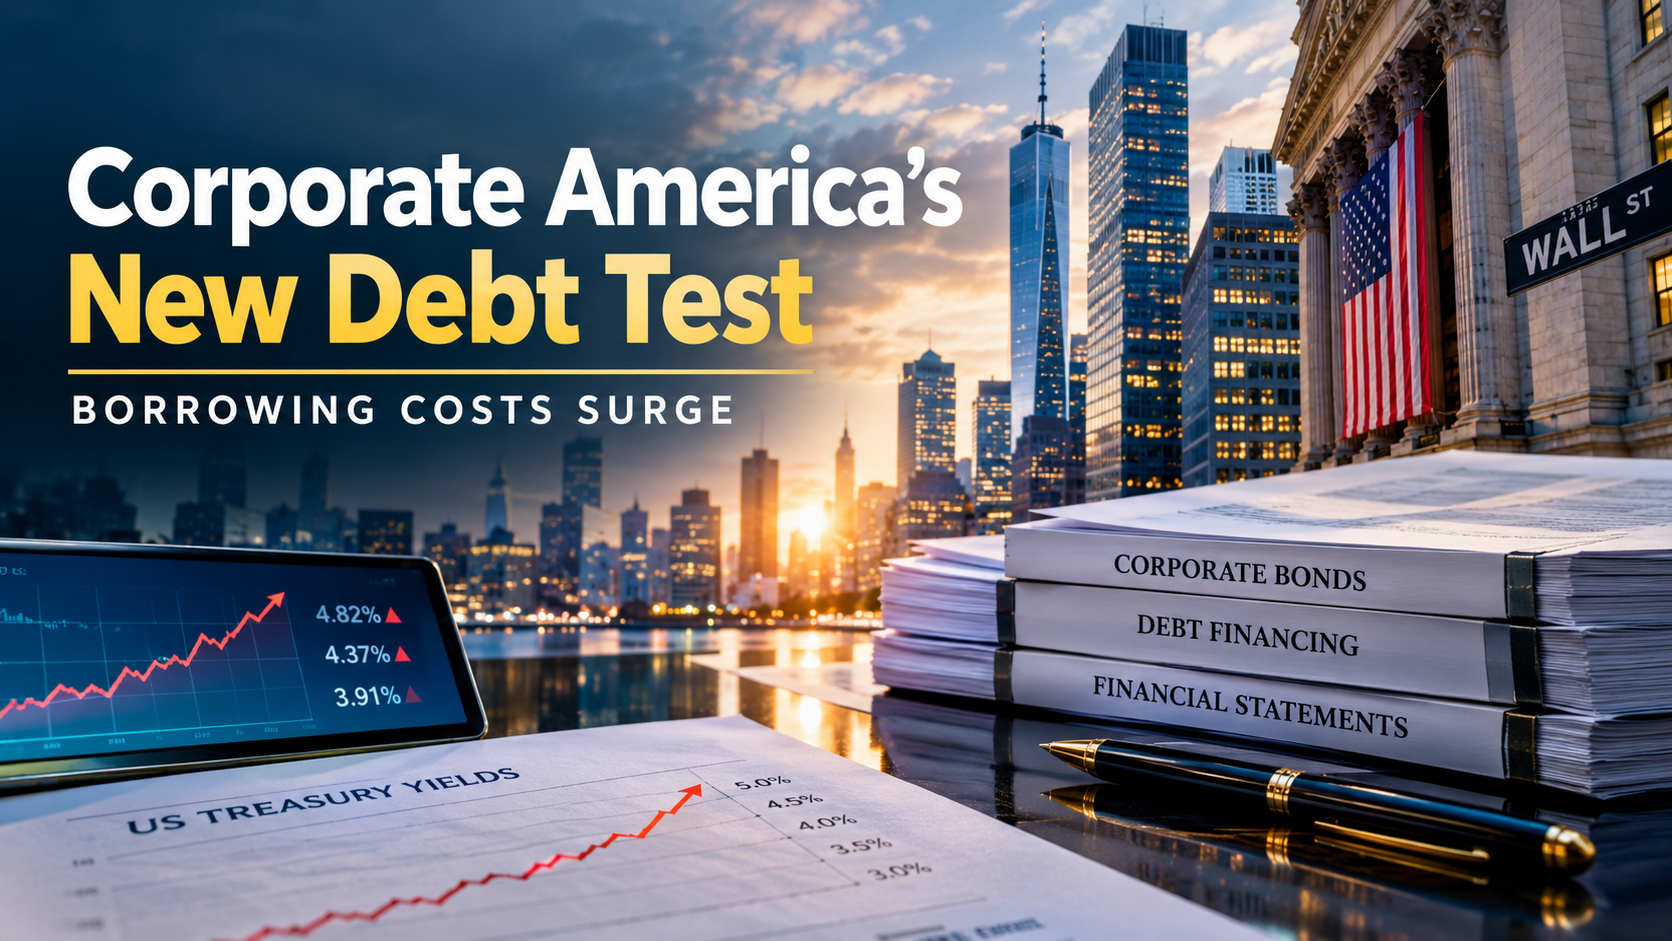
US Treasury yields have climbed to multi-year highs, pushing corporate financing costs higher and creating a growing refinancing challenge for American companies. The immediate pressure is concentrated among weaker borrowers, but a prolonged high-rate environment could eventually affect investment, mergers, buybacks and economic growth across corporate America.
The US bond market has entered a more difficult phase for corporate borrowers.
A sharp rise in Treasury yields is increasingly feeding into the cost of corporate debt, forcing companies to reconsider when and how they borrow. The impact is most severe for highly leveraged and lower-rated businesses, but even investment-grade companies are facing a more expensive capital market than they enjoyed during the ultra-low-rate era of the early 2020s.
The issue is no longer simply whether the Federal Reserve raises or cuts short-term interest rates. The bigger question for corporate America is how long long-term borrowing costs remain elevated.
That distinction matters because companies refinancing debt today are replacing old financing obtained at substantially lower rates with new debt priced in a very different market.
The Treasury market is setting a tougher price for corporate debt
The starting point is the US government bond market.
The 10-year Treasury yield has climbed to levels not seen in more than two decades, increasing the baseline rate against which much of the corporate bond market is priced. Recent market reporting has put the 10-year yield above 5%, with investors demanding greater compensation for holding long-duration government debt.
The Federal Reserve has warned that higher interest rates can increase debt-servicing costs for businesses with substantial leverage and upcoming refinancing requirements. The central bank has also noted that the corporate sector entered 2026 with relatively strong investment-grade credit quality, meaning the current environment should not automatically be interpreted as an economy-wide credit crisis.
That distinction is crucial.
The problem is increasingly concentrated in companies that have some combination of high leverage, weak cash flow, floating-rate liabilities or large amounts of debt coming due.
Federal Reserve financial-stability analysis supports the view that corporate credit vulnerabilities remain uneven rather than universal.
Why refinancing is becoming the central risk
Many companies borrowed heavily when interest rates were exceptionally low.
As those bonds mature, companies must either repay the debt from existing cash, refinance it at prevailing rates, sell assets, raise equity or reduce spending.
The refinancing arithmetic can be painful.
Suppose a company borrowed $10 billion at an average interest rate of 3%. Its annual interest bill would be approximately $300 million.
If that debt has to be refinanced at 6%, the annual interest expense rises to approximately $600 million.
The company has not borrowed another dollar, yet its annual financing burden has doubled.
That is why refinancing can become a hidden earnings shock.
Reuters estimates that approximately $4.3 trillion of US non-financial corporate bonds will mature between 2027 and 2031. Annual maturities are expected to rise from roughly $572 billion in 2027 to approximately $1.03 trillion in 2030.
This creates what investors increasingly describe as a corporate refinancing wall.
The weakest companies are feeling the pressure first
The deterioration is not evenly distributed.
Companies with investment-grade balance sheets can generally access capital markets more easily and often have diversified sources of funding.
Highly leveraged companies have fewer options.
According to the Financial Times, borrowing costs for companies rated CCC or lower have risen to approximately 17%, while their risk premium has reached about 12 percentage points.
That level of financing can fundamentally change corporate decision-making.
A project that looked profitable when money cost 5% may no longer make economic sense when financing costs move substantially higher.
This can lead companies to postpone:
- acquisitions;
- share buybacks;
- expansion projects;
- capital expenditure;
- hiring;
- new factories;
- technology investments;
- refinancing transactions.
The consequences can therefore spread beyond bond investors into the real economy.
Corporate America is not facing one uniform debt crisis
One of the most important nuances missing from many discussions about higher borrowing costs is that corporate America is highly divided.
At one end are highly profitable technology companies and other large investment-grade borrowers with enormous cash flows and strong access to capital markets.
At the other are highly leveraged companies whose earnings leave relatively little room to absorb a major increase in interest expense.
The Federal Reserve’s 2026 Financial Stability Report found that investment-grade corporate credit quality remained robust, although some riskier firms, particularly those dependent on private credit, were experiencing greater debt-servicing challenges.
That suggests the current environment is better described as a credit-selection problem than a generalized corporate solvency crisis.
The longer yields remain elevated, however, the greater the probability that today’s refinancing pressure becomes tomorrow’s default problem.
The corporate bond market is already sending signals
Market pricing provides an important window into this transition.
FRED data show Moody’s seasoned Baa corporate bond yield at approximately 6.73% on October 1, 2026. The Baa spread over the 10-year Treasury was about 1.49 percentage points at the beginning of October.
This distinction is important.
Corporate borrowing costs consist broadly of two components:
Treasury yield + corporate credit spread = corporate borrowing yield
The Treasury component compensates investors for the time value of money and government interest-rate risk.
The credit spread compensates investors for taking corporate credit risk.
When both rise simultaneously, companies experience a much more powerful increase in financing costs.
So far, much of the pressure has come from the Treasury side, although credit spreads for weaker borrowers have also widened substantially.
Paramount’s enormous financing illustrates the new reality
The Paramount Skydance transaction provides a particularly useful case study.
Paramount disclosed plans for tens of billions of dollars of debt financing connected with its acquisition of Warner Bros. Discovery. Its SEC filings show that the transaction involved substantial debt commitments, including a large bridge financing facility that was expected to be replaced or reduced through permanent financing.
The transaction demonstrates a broader challenge facing corporate finance teams.
When financing costs are uncertain, companies increasingly have to think about:
How much should we borrow?
For how long?
At what fixed rate?
How much floating-rate exposure should we accept?
Should we refinance now or wait?
Can the acquisition generate enough additional cash flow to justify the higher financing expense?
Those questions become especially important for highly leveraged mergers and acquisitions.
Why companies are shortening maturities
One logical response to high long-term interest rates is to avoid locking in today’s expensive financing for decades.
Companies may therefore prefer shorter maturities.
The strategy has an obvious advantage: if rates fall later, the company can refinance at a lower cost.
But it also creates another risk.
Shorter maturities mean more refinancing requirements in the future.
If interest rates remain high, companies could find themselves repeatedly refinancing debt at elevated rates.
That creates a difficult trade-off between paying more today for long-term certainty and accepting refinancing risk in exchange for shorter-term flexibility.
AI is creating an important exception
One of the most interesting features of the current credit market is the enormous borrowing associated with artificial intelligence infrastructure.
Technology companies are spending unprecedented amounts on data centres, chips, networking infrastructure and electricity capacity.
The Financial Times has reported estimates that hyperscalers could borrow around $1 trillion through 2030 to support AI infrastructure expansion.
For these companies, the calculation is different.
If management believes that failing to invest in AI infrastructure would result in losing a strategic position, higher financing costs may be treated as the price of maintaining competitive advantage.
This creates a strange two-speed corporate credit market.
AI-related investment can remain aggressive while other companies cut capital spending.
That divergence could become one of the defining characteristics of the next phase of the US corporate bond market.
The refinancing wall could become an earnings problem
The most important transmission mechanism is straightforward:
Higher Treasury yields → higher corporate borrowing costs → higher interest expense → lower free cash flow → reduced investment or weaker credit quality.
For companies with strong margins, the increase may be manageable.
For companies operating with thin margins, it can be decisive.
Consider a company generating $1 billion in annual operating cash flow and paying $300 million in interest.
If refinancing raises annual interest expense to $500 million, the company’s interest burden consumes a much larger share of its cash flow.
Management then has fewer resources available for investment, acquisitions, dividends and buybacks.
If revenues simultaneously weaken, the problem becomes more serious.
Could this trigger a wave of corporate defaults?
Not necessarily.
The Federal Reserve’s earlier 2026 assessment showed that corporate bond issuance remained strong and investment-grade credit quality was generally solid.
That provides an important cushion.
Large corporations have also had years to prepare for higher rates by extending maturities and locking in fixed-rate financing.
But the risk is asymmetric.
A stable economy can allow heavily indebted companies to refinance successfully.
A combination of high interest rates, slowing economic growth and falling corporate profits would be much more dangerous.
That is when refinancing pressure can turn into covenant breaches, distressed exchanges, restructurings and defaults.
The Federal Reserve has explicitly warned that higher rates can amplify vulnerabilities associated with leverage and upcoming refinancing needs.
What investors should watch next
Investors should focus on five indicators rather than Treasury yields alone.
1. The 10-year Treasury yield
A sustained move above current levels would increase the baseline cost of corporate financing.
2. High-yield credit spreads
A sharp widening would indicate that investors are demanding substantially greater compensation for corporate credit risk.
3. Corporate refinancing volumes
If companies begin delaying bond issuance, it could signal that borrowers consider market pricing too expensive.
4. Interest coverage ratios
Companies with declining earnings and rising interest expense are particularly vulnerable.
5. Default and distressed-debt indicators
A sustained increase in defaults would suggest that the refinancing problem is becoming a solvency problem.
The bigger issue is the cost of capital
The most important consequence of the bond sell-off may not be a sudden wave of bankruptcies.
It may be a gradual repricing of corporate decision-making.
For more than a decade, exceptionally low interest rates encouraged companies to borrow cheaply, refinance frequently, acquire competitors and return capital to shareholders.
That model becomes less attractive when the cost of capital rises substantially.
The result could be a more disciplined corporate environment in which companies demand higher returns from acquisitions and capital projects.
That may ultimately be healthy.
But the transition could be painful for companies that built their business models around cheap debt.
A new test for corporate America
The US economy has already demonstrated considerable resilience in the face of higher rates.
The question now is whether that resilience extends to a corporate sector facing a large refinancing cycle.
The numbers suggest that the pressure will build gradually rather than arrive as a single shock.
The immediate danger is concentrated among highly leveraged and lower-rated companies. Investment-grade borrowers remain considerably better positioned.
But the refinancing calendar means the issue cannot simply be dismissed.
With roughly $4.3 trillion of non-financial corporate bonds coming due between 2027 and 2031, the cost of money over the next several years will matter enormously.
If Treasury yields eventually decline, many companies could refinance more comfortably.
If yields remain elevated while earnings weaken, the pressure could move steadily up the credit spectrum.
That makes the current bond-market sell-off more than a story about government debt.
It is becoming a test of how much corporate America can adapt to a world in which capital is no longer cheap.
Bottom line
The US corporate sector is not yet facing a systemic debt crisis. The stronger borrowers retain substantial market access, while investment-grade credit quality remains relatively resilient.
But the refinancing cycle is creating a growing divide between companies that can absorb higher interest costs and those that cannot.
The crucial variable is therefore not simply whether the Federal Reserve raises or lowers its policy rate.
It is whether long-term borrowing costs remain high long enough for the refinancing wall to become an earnings and solvency problem.
For investors, the next phase of the credit cycle will be about separating companies that can grow their cash flows faster than their financing costs from those whose balance sheets were built for the era of cheap money.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Almost every large company is experimenting with AI, and almost none can yet prove it moved the profit line. That gap is the real story of business analytics in 2026.
Key Takeaways
- Adoption is broad, scale is not. In McKinsey’s latest global survey, 62% of respondents said their organizations are at least experimenting with AI agents, but no more than 10% reported scaling agents in any single function (McKinsey).
- Winners are rare and deliberate. About 6% of respondents qualify as “AI high performers,” attributing 5% or more of EBIT to AI and reporting significant value (same McKinsey survey).
- Efficiency is the common goal; growth is the differentiator. Eighty percent say they set efficiency as an objective, but the biggest gainers often add growth or innovation targets too (McKinsey).
- Analytics is shifting from reports to conversations and actions. The change is less about prettier dashboards and more about who can ask questions of data and how fast answers arrive.
| Era | How analytics worked | What changed |
|---|---|---|
| Descriptive BI | Analysts build dashboards | Fast reporting, limited foresight |
| Predictive models | Data scientists forecast demand, churn, risk | Better planning, but specialist-dependent |
| Generative AI | Anyone asks questions in natural language | Wider access to insight |
| Agentic AI | Systems monitor data and take defined actions | Analysis connected to execution |
From Dashboards to Decisions
Traditional business intelligence answered “what happened.” AI-driven analytics tries to answer “what will happen, why, and what should we do?”
The shift shows up in four places:
- Forecasting. Models ingest more signals (pricing, weather, logistics, macro data) to sharpen demand and cash-flow forecasts.
- Anomaly detection. Systems flag unusual transactions, supplier delays, or margin leaks before a human spots them.
- Natural-language querying. Staff ask questions in plain language rather than waiting in an analyst queue.
- Automated action. Agents trigger workflows, such as reordering stock or escalating a risk, within guardrails.
The Reality Check
McKinsey describes a landscape of wider use alongside “stubborn growing pains,” with the move from pilots to scaled impact still a work in progress at most organizations (McKinsey).
Common reasons projects stall:
- Messy data. Models are only as good as the inputs.
- Unclear ownership. No executive is accountable for the business result.
- Workflows left unchanged. AI is bolted onto old processes rather than redesigning them.
- Trust gaps. Leaders hesitate to act on outputs they cannot audit.
What High Performers Do Differently
McKinsey’s high performers share traits worth copying (McKinsey):
- They push for transformative innovation rather than only cost cutting.
- They redesign workflows instead of automating existing ones.
- They scale faster and invest more.
- They use AI across more business functions.
- They have advanced further with AI agents.
Global Considerations
Multinational analytics adds complications that single-market firms avoid:
| Challenge | Why it matters |
|---|---|
| Data residency and privacy rules | Different regions restrict where data can be stored and processed |
| Currency and inflation effects | Forecast models must handle multi-currency volatility |
| Language and local context | Models trained mostly on English data may underperform locally |
| Regulatory divergence | AI governance rules differ across jurisdictions |
| Talent distribution | Skills are concentrated in a few hubs |
How to Build an AI Analytics Roadmap
- Start with a decision, not a tool. Pick one high-value decision (pricing, credit risk, inventory) and measure it.
- Fix the data first. Clean, governed data beats a fancier model.
- Keep a human in the loop for high-stakes calls until accuracy is proven.
- Define the metric. Tie the pilot to revenue, margin, or cost, not “usage.”
- Redesign the workflow. Change who does what, not just which software they use.
- Plan governance early. Document model sources, approvals, and audit trails.
- Scale only what pays. Kill pilots that do not move a number.
Costs and ROI: A Simple Framework
Estimate return as: (annual benefit − annual run cost) ÷ total investment. Benefits include hours saved, errors avoided, and revenue lift; costs include licenses, cloud compute, integration, and training. Be conservative: McKinsey’s data shows efficiency gains are common but enterprise-level profit impact is much rarer.
Risks to Manage
- Inaccuracy. Generative outputs can be confidently wrong; verify before acting.
- Bias. Historical data can encode unfair patterns.
- Security. Sensitive data fed into tools needs controls.
- Overreliance. Skills atrophy when teams stop questioning outputs.
Frequently Asked Questions
How is AI changing business analytics?
It moves analytics from static reports toward forecasting, plain-language querying, and automated actions.
What percentage of companies use AI agents?
In McKinsey’s survey, 62% were at least experimenting, and no more than 10% were scaling them in any one function (McKinsey).
Who are “AI high performers”?
Organizations attributing 5% or more of EBIT to AI and reporting significant value; about 6% of respondents (McKinsey).
Why do AI projects fail to scale?
Poor data, unclear ownership, unchanged workflows, and weak governance.
What should a company do first?
Choose one measurable decision, fix the underlying data, and pilot with a human in the loop.
The companies that win with AI analytics will not be the ones with the most dashboards. They will be the ones that let the answer change what they do on Monday morning.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Business
US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors
Key Takeaways
- Historic Highs: The US 10-year Treasury yield closed at 5.244%, a peak not seen since the prelude to the 2008 global financial crisis.
- Fed Rate Tightening: Markets are pricing in a 70% chance of another Federal Reserve rate hike at the late-October FOMC meeting following September’s shift to a 3.75%–4.00% target range.
- Borrowing Costs Surge: 30-year fixed mortgage rates are spiking past multidecade highs, suppressing real estate transaction volumes.
- Asset Reallocation: Bond yields above 5% create substantial headwind for growth stocks while elevating cash-equivalent instruments to prime investment status.
The Macroeconomic Catalyst: Why Yields Are Surging
The sudden acceleration in benchmark sovereign yields comes on the heels of persistent inflationary pressures driven by global energy disruptions and resilient labor data. When the Federal Reserve raised rates in September to the 3.75%–4.00% range, institutional bond traders initially anticipated a pause. However, hawkish central bank commentary coupled with persistent federal debt issuance has pushed the 10-year Treasury note to 5.244%, a level last recorded in 2007.
According to real-time market tracking from Trading Economics, global fixed-income markets are undergoing a fundamental repricing. High yields mean the government must offer higher returns to attract buyers for its expanding deficit, directly competing with private sector risk assets.
            US 10-Year Treasury Yield Trajectory
   5.5% |                                       * (5.244%)
   5.0% |                                *-----*
   4.5% |                         *-----*
   4.0% |                  *-----*
   3.5% |           *-----*
        +---------------------------------------------------
          Jan 2026    Apr 2026   Jul 2026    Sep 2026
Mortgage Rate Forecast 2026 & Real Estate Impact
The primary transmission mechanism of the benchmark yield spike into the everyday economy is through mortgage lending rates. Because mortgage-backed securities (MBS) are priced relative to the 10-year yield plus a risk spread, residential borrowing costs have responded immediately.
As detailed by financial coverage on CNBC, the spread between the 10-year yield and 30-year fixed mortgage rates remains historically wide due to secondary market volatility.
Housing Market Stress Points:
- Buyer Purchasing Power Reduction: Every 50-basis-point surge in mortgage rates reduces homebuyer purchasing capacity by approximately 5%.
- The “Lock-In” Effect: Existing homeowners with 3%–4% legacy mortgage rates refuse to list properties, driving inventory down to structural lows.
- Commercial Real Estate (CRE) Refinancing: Over $1.2 trillion in commercial debt requires refinancing before year-end, now facing interest expense shocks that threaten regional bank balance sheets.
Fed Rate Hike October Odds & Wall Street Strategy
Derivatives pricing monitored by Bloomberg indicates that money markets are placing roughly a 70% probability on an additional 25-basis-point rate hike at the late-October Federal Open Market Committee (FOMC) meeting.
Financial Sector Asset Class Comparison
| Asset Class | Yield / Return Outlook | Risk Profile | Strategic Investor Positioning |
| US 10-Year Treasury | $5.24\%$ Fixed Return | Low (Sovereign) | Strong buy for income locking; duration risk if yields hit 5.5% |
| S&P 500 Equities | $4.2\%$ Earnings Yield | Moderate / High | Overweight value/cash-flow; underweight non-profitable tech |
| 30-Year Fixed Mortgage | $7.85\% – 8.20\%$ Cost | Low (Consumer Credit) | Refinance freeze; shift toward adjustable-rate structures (ARMs) |
| Gold (Spot) | $-3.71\%$ ($4,127/oz) | Moderate | Tactical buy on dip if real yields stabilize |
Investor Playbook: Navigating a 5%+ Yield Environment
When baseline risk-free cash yields exceed 5%, traditional investment models like the classic 60/40 equity-to-bond portfolio demand recalibration.
- Short-Duration Fixed Income: Capitalize on elevated yield-to-maturity metrics by allocating into 1-to-3 year Treasuries or high-grade corporate debt without locking up capital in long-duration securities.
- Dividend Dividend Aristocrats over Growth: Shift equity exposure toward dividend-paying value stocks possessing robust balance sheets and low net-debt-to-EBITDA ratios.
- Hedging Rate Volatility: Institutional allocators are utilizing interest rate swaps and inverse Treasury ETFs to insulate equity gains against sustained yield spikes.
Frequently Asked Questions (FAQ)
How does the US 10-year yield affect home mortgage rates?
The 10-year Treasury yield serves as the benchmark for 30-year fixed-rate mortgages. Lenders add a spread (typically 1.5% to 3.0%) over the 10-year yield to cover credit risk and servicing costs. When the yield rises to 5.24%, mortgage rates naturally trend upward toward 7.5%–8.2%.
Why are yields rising if the Fed only raised rates to 3.75%-4%?
While the Fed controls short-term overnight rates, the 10-year yield is determined by market demand for long-term government debt. Factors like heavy Treasury debt supply, long-term inflation fears, and international central bank selloffs drive up long-term yields independently of overnight rate levels.
What happens to stock prices when bond yields hit multi-year highs?
Rising bond yields make risk-free fixed income more attractive compared to stocks. Higher discount rates are applied to future corporate earnings calculations, which tends to depress stock valuations, particularly for high-growth tech companies reliant on future earnings.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025