
IMF
Decoding the Latest IMF and World Bank Joint Reports: Growth Forecasts and Debt Crises


The latest joint diagnostics from the IMF and World Bank reveal a bifurcated global economy. While developed economies attempt soft landings, emerging markets face severeliquidity squeezes. Sovereign debt restructuring mechanisms are failing to keep pace with US-dollar obligations, signaling suppressed infrastructure spending in developing nations.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Understand Pakistan’s latest IMF review, Rs86.7 trillion public debt and the structural reforms required to avoid another bailout cycle. Read the analysis.
Key Takeaways
- IMF staff reached an agreement on Pakistan’s fourth EFF review and third RSF review on 7 October 2026, but said releases remained subject to Executive Board approval.
- The Finance Ministry reported Rs86.715 trillion in total public debt at end-June 2026, with a debt-to-GDP ratio of 68.3% on its broad measure; see the Annual Debt Review.
- A primary surplus can coexist with an overall budget deficit because interest payments remain large.
- Reducing repeated IMF dependence requires stronger exports, an affordable energy system, broad-based revenue and better debt management over multiple governments.
Pakistan’s latest IMF discussions are not simply about receiving another tranche. They concern why the country repeatedly needs external support when imports and debt payments strain available foreign currency. The Pakistan IMF programme 2026 reached a new milestone on 7 October, when Fund staff announced agreement on reviews under two facilities, subject to the Executive Board’s approval. The IMF’s statement provides the precise conditional status.
The scale of the long-term problem is visible in the debt numbers. At end-June 2026, total public debt stood at Rs86.715 trillion, the Finance Ministry’s Annual Debt Review reported. Debt-management progress can be real, yet a large stock and recurring external financing needs remain. This article explains how IMF programmes work, what they cannot fix alone, and what would have to change for Pakistan to depend on them less.
Has the IMF approved Pakistan’s October 2026 programme review?
As of the 7 October 2026 IMF announcement, staff had reached an agreement on the fourth EFF review and third RSF review, but approval by the IMF Executive Board was still required. Do not describe the associated potential financing as already disbursed without checking a subsequent Board decision.
What is the current Pakistan IMF programme 2026 status?
On 7 October 2026, IMF staff announced a staff-level agreement concerning the fourth review of Pakistan’s 37-month Extended Fund Facility (EFF) and the third review of a 28-month Resilience and Sustainability Facility (RSF). The IMF press release says approval could make approximately $1.0 billion under the EFF and around $210 million under the RSF available.
| IMF item | 7 October 2026 status | Practical meaning |
|---|---|---|
| EFF fourth review | Staff-level agreement | Not yet an approved disbursement |
| RSF third review | Staff-level agreement | Board decision still required |
| Potential EFF access | About $1.0bn | Conditional on approval |
| Potential RSF access | About $210m | Conditional on approval |
Some commentary casually calls this Pakistan’s ’25th IMF programme’. Counts of historical arrangements can vary with the start date and whether precautionary or emergency facilities are included. For current readers, the useful facts are the legal identity, duration, reviews and conditions of the existing EFF and RSF.
The IMF’s 8 May 2026 Board release confirmed completion of the preceding reviews, making a clear contrast with October’s still-conditional staff agreement. Conflating the two would falsely suggest that a future decision had already occurred.
How big is Pakistan’s public debt, and why does the definition matter?
The Ministry of Finance Annual Debt Review FY2026, published in September, places total public debt at Rs86,715 billion at end-June 2026, with Rs59,441 billion domestic and Rs27,274 billion external. The report gives a broad public-debt ratio of 68.3% of GDP. It separately cites a smaller amount under the fiscal-responsibility law’s definition.
| Stock at end-June 2026 | Amount | Broad classification |
|---|---|---|
| Domestic public debt | Rs59.441tn | Rupee liabilities |
| External public debt | Rs27.274tn | External obligations in rupee terms |
| Total public debt | Rs86.715tn | Finance Ministry headline series |
| Broad debt-to-GDP ratio | 68.3% | End-June 2026 |
Debt stock is not the same as annual debt-service payments. Nor can you divide the total by the population and claim each Pakistani personally owes that amount on demand. Government debt finances spending and refinancing obligations; its cost depends on interest rates, maturities and the exchange rate.
The report says interest expenditure fell in FY26, which is encouraging. Still, falling interest costs in one year do not remove refinancing risk or the burden of financing public services in later years.
Why does Pakistan turn to the IMF repeatedly?
A recurring pressure is the mismatch between the foreign currency earned through exports and other inflows and the currency needed for imports, debt servicing and private-sector payments. When external financing becomes scarce, exchange-rate pressure and reserve losses can become severe. IMF arrangements can provide financing and a framework for policy changes that encourage other creditors to keep supporting the country.
Domestic fiscal structure aggravates the problem. Weak and uneven tax collection leaves the state dependent on borrowing, while inefficient energy and state-owned enterprises can create costly commitments. Investment stays weak when firms cannot predict regulations, exchange-rate arrangements or electricity supply.
The World Bank’s 2026–35 Pakistan partnership framework argues that sustained reform and private investment are needed to overcome decades of volatile growth. That is a long-horizon diagnosis, not something a single IMF review can complete.
An IMF programme may help prevent a financing crisis. It does not automatically create export markets, make provincial tax systems consistent or change the incentives of every public institution.
What does the IMF mean by a primary surplus?
The primary fiscal balance excludes interest payments. A country can collect more revenue than it spends on programmes and administration but still borrow overall because debt servicing absorbs so much cash. The FY2026–27 budget book targets an underlying primary surplus of 2.0% of GDP and estimates a 3.6% overall fiscal deficit on the consolidated budget basis. These are different measures.
Imagine a public budget receiving Rs100, spending Rs95 on non-interest items and Rs20 in interest. The primary surplus is Rs5; the overall deficit is Rs15. That example is purely illustrative, but it captures the difference.
The IMF October 2026 statement supports a strong primary balance while also asking for better debt management and spending quality. Cutting useful maintenance or education merely to hit a near-term target can eventually damage growth and make future debt harder to repay. Good fiscal adjustment asks not only how much is spent but what taxpayers receive.
Are IMF conditions necessarily good or bad for households?
They involve trade-offs. A realistic electricity tariff can slow renewed arrears, but sharply higher bills impose immediate hardship. A flexible exchange rate protects reserves, but depreciation can increase import prices. Tighter monetary policy can protect the purchasing power of money, but raise borrowing costs for small businesses.
The 7 October IMF assessment calls for reducing energy-sector costs, preventing renewed circular debt, improving targeted social support and expanding human-capital spending. These objectives are not identical to indiscriminate austerity. How reforms are designed and who bears the cost determine their fairness.
Pakistan’s policy debate often presents a false choice between ‘accept every condition’ and ‘reject all reform’. Some reforms, like stopping electricity theft or improving procurement, would be worthwhile even without IMF involvement. Others require serious debate over distributional effects, implementation speed and constitutional responsibility.
What would a realistic exit strategy look like?
There is no credible one-year escape from a complex debt and competitiveness problem. A ten-year strategy would aim for sustained growth in higher-value exports, fewer unfunded electricity losses, transparent public debt issuance, a broader revenue base, stable regulation and better public education. The World Bank long-term country framework identifies productive private investment and human capital as central to Pakistan’s future.
Governments should publish measurable targets: export diversity, net energy-sector losses, tax collections sustained after appeal, debt maturities and learning outcomes. These indicators are harder to celebrate at rallies than a loan tranche, but they show whether the economy is becoming structurally more resilient.
The current IMF agreement supplies time and conditional financing. Success would mean using that time to reduce the need for exceptional financing, not merely to prepare for the next round of negotiations.
What This Means for You
Household: Track whether reforms change prices, wages and access to public services rather than interpreting a tranche as immediate economic prosperity. Use reliable inflation and budget data when assessing impact.
Business owner: Plan for exchange-rate, tariff and financing uncertainty. Build cash-flow buffers and review imported-input exposure before committing to long-term borrowing.
Exporter: Look for persistent reductions in administrative and energy costs. IMF approval can improve confidence, but export profitability depends on your business contracts and productivity.
Student: Understand debt stock, annual deficits, primary balances and foreign-exchange reserves as different concepts; mixing them produces misleading arguments.
What to Watch Next
- 26 October 2026: The State Bank monetary-policy decision and any revision to its inflation assessment; verify any schedule change with the SBP.
- Early November 2026, exact release date to be confirmed: Pakistan Bureau of Statistics October inflation and merchandise-trade releases.
- Late October–November 2026, date not yet confirmed: Any IMF Executive Board announcement on the October staff-level agreement; staff agreement is not Board approval.
- Throughout FY2026–27: Updated SBP monthly balance-of-payments and remittance statistics; compare cumulative results rather than one month alone.
Frequently Asked Questions
Has the IMF approved Pakistan’s October 2026 programme review?
As of the 7 October 2026 IMF announcement, staff had reached an agreement on the fourth EFF review and third RSF review, but approval by the IMF Executive Board was still required. Do not describe the associated potential financing as already disbursed without checking a subsequent Board decision.
How much was Pakistan’s public debt at June 2026?
The Finance Ministry’s Annual Debt Review reported total public debt of Rs86.715 trillion at end-June 2026, including Rs59.441 trillion of domestic debt and Rs27.274 trillion of external debt. Its broad debt-to-GDP measure was 68.3%, although legal definitions can produce different debt totals.
What is an IMF Extended Fund Facility?
An Extended Fund Facility is an IMF financing arrangement generally associated with longer-term policy adjustments to address structural balance-of-payments problems. Reviews assess agreed policy commitments. Financing remains subject to the applicable approval and programme terms.
What is a primary fiscal surplus?
A primary surplus exists when government revenue exceeds non-interest expenditure. It does not mean the overall budget is in surplus because interest on existing debt can still create a borrowing requirement. Both measures are needed to evaluate fiscal health.
Can Pakistan stop borrowing from the IMF?
It can reduce dependence over time by increasing foreign-exchange earnings, investment and reliable domestic revenues while managing energy costs and debt maturities. There is no guarantee or quick deadline. Reforms must last across business cycles and changes in government to make external financing shocks less dangerous.
The next IMF disbursement, if approved, will matter for financing and confidence. It will not answer the deeper question. Pakistan stops returning to crisis lending when its productive economy and public institutions can finance stability on their own.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The latest IMF growth forecast suggests the world economy is still expanding. That headline offers limited comfort to poorer countries facing debt service costs, expensive energy and weak access to long-term capital. Economic growth and financial resilience are different measures, and the gap between them is the central challenge for global policymakers.
The IMF’s October 2026 World Economic Outlook projects global growth of 3.1% in 2026 and 3.4% in 2027, with global headline inflation forecast at 4.7% and 4.1%, respectively. These are institutional projections based on a stated information cutoff, not final annual outcomes.
Where growth is coming from
Investment in artificial intelligence and related infrastructure is helping support demand in countries that manufacture hardware or host facilities. But this spending is geographically concentrated. An energy-importing economy outside the technology supply chain may face higher fuel costs without enjoying much of the associated investment boom.
This divergence is important for interpreting the global average. A positive headline number can coexist with stagnant living standards and rising financial stress in particular regions. Policymakers should consider median household experience, real wages and fiscal space as well as GDP.
Debt service crowds out services
At the conclusion of the IMF and World Bank meetings, Reuters reported persistent concern about interest expenses and developing-country financing. Debt servicing competes directly with public spending on health, education, water networks and climate adaptation. A government that refinances at substantially higher rates may have little capacity to build productive infrastructure even when demand for it is obvious.
The level of debt alone does not determine danger. Currency denomination, maturity, the creditor mix, the ability to raise revenue and the growth rate all affect sustainability. Two countries with similar debt-to-GDP ratios can have very different refinancing problems.
Why private capital is difficult to mobilize
Development institutions frequently call for attracting pension funds, insurers and other private investors into emerging-market infrastructure. In principle, the capital pool is large. In practice, political risk, currency mismatch, procurement, revenue collection and legal enforceability can make a project unsuitable for long-term investors.
Blended finance can help if guarantees and concessional funding genuinely absorb risks that private investors cannot control. But governments must disclose contingent liabilities and avoid subsidies that socialize losses while offering little public benefit. Project preparation and transparent procurement can be as important as a large funding announcement.
Climate and energy are fiscal questions
Climate resilience and reliable power determine whether farms, businesses and cities remain productive. Energy shocks affect inflation and trade balances, especially in countries buying fuel in foreign currency. Renewable generation can reduce some exposure but requires grid investment and careful financing.
Debt relief proposals, meanwhile, need to address both incentives and timing. Delayed restructuring can destroy value; rushed restructuring without credible reforms can postpone rather than resolve vulnerabilities. Sustainable development requires a blend of financing, institutional capacity and growth-enhancing investment.
How to read the next forecast
Watch whether growth revisions are broad or concentrated, whether inflation falls as projected and whether debt-service ratios improve. The latest Reuters development-finance reporting also underscores the search for alternatives as traditional public aid faces pressure.
For businesses, higher interest costs and weaker consumer demand can change export and investment plans. For households, inflation and employment matter more than a fraction-of-a-point change in a global forecast. The right editorial treatment connects the macroeconomic release to those practical consequences.
How to test whether a debt proposal is credible
When governments announce a debt restructuring or new development loan, ask four sequential questions. First, what cash payments are due during the next three years? Second, which creditors must agree and which creditors can block the arrangement? Third, what policy or investment changes are expected to generate future revenue? Fourth, what happens if growth and exchange-rate assumptions prove too optimistic? A restructuring can provide breathing room without repairing weak tax collection or unproductive spending. Conversely, a country with good investment prospects may face avoidable hardship if negotiations are delayed. These practical details are often more revealing than broad declarations about a debt crisis.
Frequently asked questions
What is the IMF’s 2026 global growth forecast?
The October 2026 outlook projects 3.1% growth for 2026, with 3.4% forecast for 2027.
Is the World Bank the same institution as the IMF?
No. Their mandates overlap in global development, but the IMF emphasizes macroeconomic and financial stability, while the World Bank focuses more heavily on development finance and poverty reduction.
Why can growth improve while countries struggle?
Aggregate output can grow while high borrowing costs, inflation and unequal access to investment limit the benefits experienced by households.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
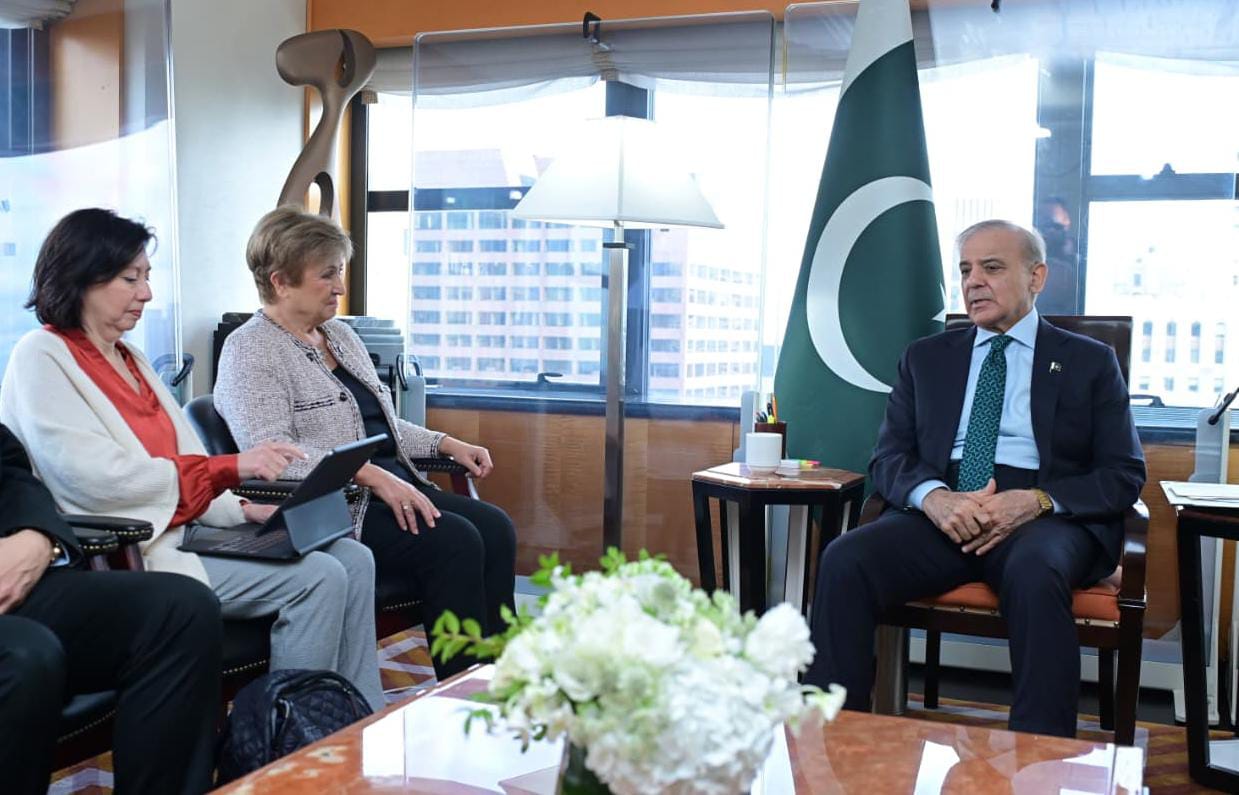
Pakistan is entering a new phase of its economic program, with Prime Minister Shehbaz Sharif saying the country is moving from macroeconomic stabilization toward recovery while reaffirming Islamabad’s commitment to IMF-backed reforms.
The statement came during Sharif’s meeting with International Monetary Fund Managing Director Kristalina Georgieva on the sidelines of the 81st United Nations General Assembly in New York.
The discussion comes at an important point for Pakistan’s economy. After a period dominated by efforts to restore fiscal and external stability, the government’s focus is increasingly shifting toward investment, productivity, exports and longer-term economic growth.

6
PM Shehbaz Sharif Reaffirms Pakistan’s Reform Commitment
According to the government and Radio Pakistan, Sharif told Georgieva that Pakistan was progressing from macroeconomic stabilization toward economic recovery despite regional conflict and external inflationary pressures.
The prime minister pointed to improvements in fiscal discipline, external buffers and investor confidence, while highlighting the National Tariff Regime, domestic revenue mobilization and privatization as important elements of the reform agenda.
Sharif also reiterated that Pakistan intends to remain committed to the IMF-supported reform program.
That commitment matters because the country’s recent economic stabilization has been closely connected to the IMF program and the government’s efforts to meet fiscal and structural targets.
IMF Says Stabilization Efforts Are Producing Results
The IMF’s own assessment provides important context to the government’s claims.
In its May 2026 review, the Fund said strong policy implementation had helped maintain economic stability and improve financing and external conditions. The IMF also approved approximately $1.1 billion under the Extended Fund Facility and about $220 million under the Resilience and Sustainability Facility, taking total disbursements under the two arrangements to about $4.8 billion.
The Fund identified several continuing priorities, including:
- strengthening public finances;
- broadening the tax base;
- improving competition and productivity;
- reforming state-owned enterprises;
- improving energy-sector viability;
- strengthening social protection;
- rebuilding foreign-exchange reserves; and
- improving public-service delivery.
This means Pakistan’s transition to recovery is not simply a question of higher GDP growth. The next phase depends heavily on whether stabilization measures can be converted into sustained productivity, investment and private-sector growth.
Pakistan’s Growth Has Improved, but the Recovery Remains Vulnerable
Pakistan recorded 3.7% GDP growth in FY2026, according to figures cited by the Finance Ministry and the Asian Development Bank. The ADB’s July 2026 outlook also puts Pakistan’s growth forecast at 3.7% for 2026 and 2027.
The ADB, however, has highlighted significant risks surrounding the outlook.
Its July forecast said Pakistan’s 2026 growth was being supported by the recovery in economic activity, but higher energy costs and pressure related to the Middle East conflict represented important downside risks. The ADB projects Pakistan’s inflation at 7.2% in 2026 and 8.3% in 2027.
That distinction is important.
Stabilization does not automatically mean a broad-based economic recovery. Pakistan still needs stronger investment, productivity and export performance to generate durable growth.
What Has Changed in Pakistan’s Economy?
Pakistan’s recent economic story has involved a combination of fiscal consolidation, monetary discipline, external financing and structural reforms.
The IMF reported that Pakistan’s reserves had increased, while fiscal performance remained strong. Its assessment also noted that the country’s economic recovery had gained momentum, although the Middle East conflict had complicated the near-term outlook.
The government’s current economic strategy is therefore moving beyond simply preventing another balance-of-payments crisis.
Finance Minister Muhammad Aurangzeb recently described the next stage as a move toward investment, capital formation, exports and private-sector-led growth. The government has identified macroeconomic stability, structural reforms, investment, exports and improved access to finance among its key priorities.
Why the IMF Review Matters
The upcoming IMF review is one of the most important tests for Pakistan’s reform program.
The IMF-supported Extended Fund Facility was approved in September 2024 and is designed to strengthen macroeconomic resilience while creating conditions for sustainable growth. The program includes fiscal reforms, reserve accumulation, tax-base expansion, SOE restructuring, energy-sector reforms and measures to improve competitiveness.
The forthcoming review will therefore provide an important assessment of whether Pakistan is continuing to meet the commitments associated with the program.
For financial markets and investors, successful implementation can influence perceptions of Pakistan’s external financing position and policy credibility. For households and businesses, however, the more important question is whether stabilization eventually translates into lower economic volatility, stronger investment and sustainable job creation.
Tariff and Revenue Reforms Could Reshape the Business Environment
The government’s National Tariff Regime is another significant component of the reform agenda.
The IMF’s latest Pakistan documentation says authorities are working to reduce tariffs and simplify non-tariff barriers while also pursuing broader regulatory reforms intended to reduce uncertainty and transaction costs for businesses.
The reform agenda also includes changes involving special economic zones and other fiscal incentives.
The objective is to gradually move away from policies that create distortions and toward a more competitive environment in which investment decisions depend more heavily on productivity and market conditions.
Privatization Remains Another Major Test
Privatization is also central to Pakistan’s structural-reform agenda.
The IMF has noted progress on the privatization agenda, including the agreement involving Pakistan International Airlines, while identifying additional SOE and electricity-distribution reforms as part of the broader program.
The government’s challenge will be to demonstrate that privatization and restructuring produce lasting improvements in efficiency rather than simply short-term fiscal relief.
External Financing Remains a Key Vulnerability
Pakistan’s recovery is also taking place against a complicated external backdrop.
Reuters reported in September that Pakistan was seeking an expansion of its 30 billion yuan currency swap arrangement with China when it comes up for renewal in 2027. Finance Minister Muhammad Aurangzeb also said Islamabad was awaiting a US decision concerning a proposed exchange-stabilization facility.
The report underscores an important reality: even as Pakistan’s macroeconomic indicators improve, the country continues to depend on external financing and bilateral and multilateral support to maintain reserves and meet debt obligations.
That makes continued reform implementation particularly important.
Energy Prices Could Complicate the Recovery
Higher energy costs represent another major challenge.
Reuters reported that Pakistan introduced austerity measures in September as rising fuel prices associated with the Gulf conflict increased pressure on the country’s economy. The measures included restrictions on official fuel use, government vehicle purchases and certain official expenditures.
The ADB has similarly warned that higher energy prices could increase inflationary pressure and weaken growth across the region, with Pakistan particularly exposed because of its external energy requirements.
This creates a difficult policy balance: authorities need to preserve fiscal and external stability while preventing higher energy costs from disproportionately affecting households and businesses.
What the Recovery Phase Means for Pakistan
The phrase “from stabilization to recovery” describes a shift in economic priorities.
The stabilization phase focused heavily on preventing external financing crises, controlling inflationary pressures, improving fiscal discipline and rebuilding reserves.
The recovery phase requires something broader:
more private investment + higher productivity + stronger exports + sustainable public finances + structural reform.
The ADB’s 2026–2030 country strategy for Pakistan similarly emphasizes private-sector development, inclusion, resilience and sustainability as key pathways toward longer-term growth.
That suggests the next stage of Pakistan’s economic story will be judged less by emergency stabilization and more by whether the country can turn improved macroeconomic conditions into sustained productive activity.
The Road Ahead
Pakistan has made measurable progress in restoring macroeconomic stability, and international institutions have acknowledged improvements in several areas.
But the economic recovery remains exposed to external shocks, particularly energy prices, geopolitical disruptions, financing conditions and inflation.
The government’s commitment to continued reforms therefore faces a critical test: whether stabilization can be maintained while investment, productivity, exports and private-sector activity expand.
For now, the latest meeting between Shehbaz Sharif and Kristalina Georgieva reinforces the government’s stated intention to remain on the reform path. The IMF review and the implementation of structural measures will provide more concrete evidence of how successfully Pakistan can turn stabilization into sustainable growth.
Key facts at a glance
| Indicator | Latest available information |
|---|---|
| FY2026 GDP growth | 3.7% |
| ADB 2026 Pakistan growth forecast | 3.7% |
| ADB 2027 Pakistan growth forecast | 3.7% |
| ADB 2026 inflation forecast | 7.2% |
| ADB 2027 inflation forecast | 8.3% |
| IMF EFF | 37-month program approved Sept. 2024 |
| IMF/RSF disbursements reported May 2026 | About $4.8 billion combined |
| Major reform areas | Taxation, SOEs, energy, tariffs, competition, reserves |
Sources:IMF
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Geopolitics and Your Portfolio: How International Affairs Move Global Markets
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025