
Cryptocurrency
The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

On August 18, 2026, the SEC proposed “Regulation Crypto Assets” — a new rule framework creating clear, tailored securities-offering pathways for crypto assets, according to the SEC’s own press release. It’s the second major step in a regulatory transformation that began with a March 2026 SEC interpretive framework and builds on 2025’s landmark GENIUS Act stablecoin legislation. For institutional investors, the shift from years of “regulation by enforcement” to a structured statutory framework represents the single most consequential change to the US digital-asset investment landscape since Bitcoin’s creation.
The Three-Layer Regulatory Stack Taking Shape in 2026
Layer 1: The March 2026 SEC Interpretation
In March 2026, the SEC released an interpretative document classifying crypto assets into distinct categories — digital goods, digital collectibles, digital instruments, stablecoins, and digital securities — clarifying under what circumstances non-security crypto assets might still be linked to investment contracts, according to BTCC.
Layer 2: The August 2026 “Regulation Crypto Assets” Proposal
Building on that interpretation, the SEC’s August 18 proposal creates two capital-formation exemptions specifically for crypto issuers, per the SEC:
- A one-time exemption permitting offerings up to $5 million during a four-year period.
- A recurring exemption permitting offerings up to $75 million during each 12-month period.
As of August 20, 2026, this remains a proposed rule, not final regulation — the public comment period runs 60 days from Federal Register publication, per BTCC. SEC Chairman Paul Atkins has framed the shift explicitly: the Commission has “ended the ‘regulation by enforcement’ approach of the past” in favor of cases prioritizing meaningful investor protection, according to Bitcoin Foundation, citing an SEC statement.
Layer 3: The GENIUS Act Stablecoin Framework
Separately, and already further along in implementation, the GENIUS Act establishes a comprehensive federal framework for payment stablecoins, making clear that permitted stablecoins are not securities, commodities, or deposits — instead falling under a distinct regime administered by the OCC, FDIC, Federal Reserve Board, and Treasury, according to Cleary Gottlieb.
The Commodity/Security Divide: Settled for Major Tokens
Perhaps the most consequential development for institutional allocators predates the August proposal: on March 17, 2026, the SEC and CFTC jointly published an interpretive framework classifying 16 crypto assets as digital commodities under CFTC jurisdiction rather than SEC securities jurisdiction, according to Angel Investors Network. This resolves a decade-old ambiguity that had kept many institutional allocators on the sidelines, uncertain whether their crypto holdings could later be reclassified as unregistered securities.
Who Wins and Who Faces Consolidation Pressure
| Market Participant | Regulatory Impact | Strategic Position |
|---|---|---|
| Bank-affiliated stablecoin issuers (JPMorgan, US Bancorp) | GENIUS Act’s $5M excess-capital threshold is trivially achievable | Structurally advantaged — existing customer relationships, compliance infrastructure |
| Large non-bank issuers (Circle, Coinbase) | Can absorb GENIUS Act capital and compliance costs | Competitive, but facing new bank-affiliated entrants |
| Smaller fintech/payment platforms (Stripe, Block-scale) | Face a binary choice: charter a stablecoin bank or exit stablecoin issuance | Consolidation pressure — likely M&A targets or market exits |
| DeFi lending protocols | Operate outside the regulated banking perimeter | Continue offering 5–8% stablecoin yields offshore/unregulated, per Angel Investors Network |
| Institutional allocators of major tokens (BTC, ETH, and 14 others) | Commodity classification (not securities) removes reclassification risk | Materially reduced compliance/legal uncertainty for allocation decisions |
| Early-stage crypto issuers/founders | New $5M/4-year and $75M/year exemptions | Clearer, faster capital-formation pathways once finalized |
Sources: Angel Investors Network, SEC.gov, BTCC — see citations above.
The Institutional Yield Dilemma
The GENIUS Act’s framework implicitly assumes stablecoin issuers will accept zero yield in exchange for federal charter status and regulatory certainty — but DeFi lending protocols on Ethereum and Solana continue offering 5–8% yields on stablecoin deposits outside the regulated banking system, according to Angel Investors Network. This creates a genuine strategic tension for accredited and institutional investors holding large stablecoin positions: hold zero-yield, federally regulated coins, or seek yield in offshore, uninsured, unregulated platforms. This trade-off is likely to remain unresolved through 2026 and represents the clearest open risk-allocation question for institutional treasury and portfolio managers.
Political Context: A Deliberate Strategic Shift
This regulatory transformation reflects an explicit White House-level policy objective. President Trump convened a Working Group on Digital Assets that issued recommendations designed to strengthen American leadership in digital financial technology and position the US as the “crypto capital of the world,” according to Cleary Gottlieb. The regulatory environment shifted “virtually overnight” from an enforcement-heavy skepticism that had effectively excluded traditional financial institutions from digital-asset markets, to a determined flexibility focus.
Legislative friction remains, however: the banking industry is actively lobbying for additional restrictions on stablecoin reward payments, including potential amendments to the CLARITY Act, according to K&L Gates — a live legislative fight institutional investors should track through the remainder of 2026.
An Institutional Due-Diligence Framework for 2026
- Distinguish finalized rules from proposals. The GENIUS Act is enacted law with active implementation; “Regulation Crypto Assets” remains a proposal subject to a 60-day comment period and potential revision — size institutional exposure and compliance planning accordingly.
- Reassess reclassification risk for major holdings. The March 2026 joint SEC-CFTC commodity classification for 16 major crypto assets materially reduces legal uncertainty for institutional allocators — a genuine catalyst for previously sideline capital.
- Model the stablecoin yield trade-off explicitly. Treasury and portfolio managers holding stablecoin positions need a documented policy on regulated-zero-yield versus unregulated-yield-bearing allocations, given the structural tension the GENIUS Act framework creates.
- Track CLARITY Act amendments and banking-industry lobbying as a live legislative risk factor that could alter stablecoin reward/yield economics before institutional strategies are finalized.
The Bottom Line
The 2026 crypto regulatory shift is not a single event but a converging three-layer framework — SEC interpretive guidance, a new capital-formation rule proposal, and enacted GENIUS Act stablecoin legislation — that collectively resolves years of institutional uncertainty around token classification while opening a new, unresolved question around stablecoin yield economics. Institutional investors who have been waiting for regulatory clarity before deploying meaningful capital now have a genuine, if still partially proposed, framework to underwrite that decision.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The Ultimate Ledger of a Nation’s International Economic Transactions
The Balance of Payments (BOP) is one of the most comprehensive and critical macroeconomic accounting tools used by economists, financial analysts, and policymakers. It is a systematic record of all economic transactions conducted between the residents of a country (including individuals, businesses, and the government) and the rest of the world over a specific period, typically a quarter or a year.
For platforms like Thefinance.pk and Economy.com.pk, analyzing a nation’s BOP is non-negotiable. While Gross Domestic Product (GDP) measures domestic production, the BOP measures a country’s financial sovereignty, trade competitiveness, and economic connectivity with global markets. If a country is an economic island, the BOP is the detailed logbook of every ship entering and leaving its ports.
The Accounting Identity of BOP
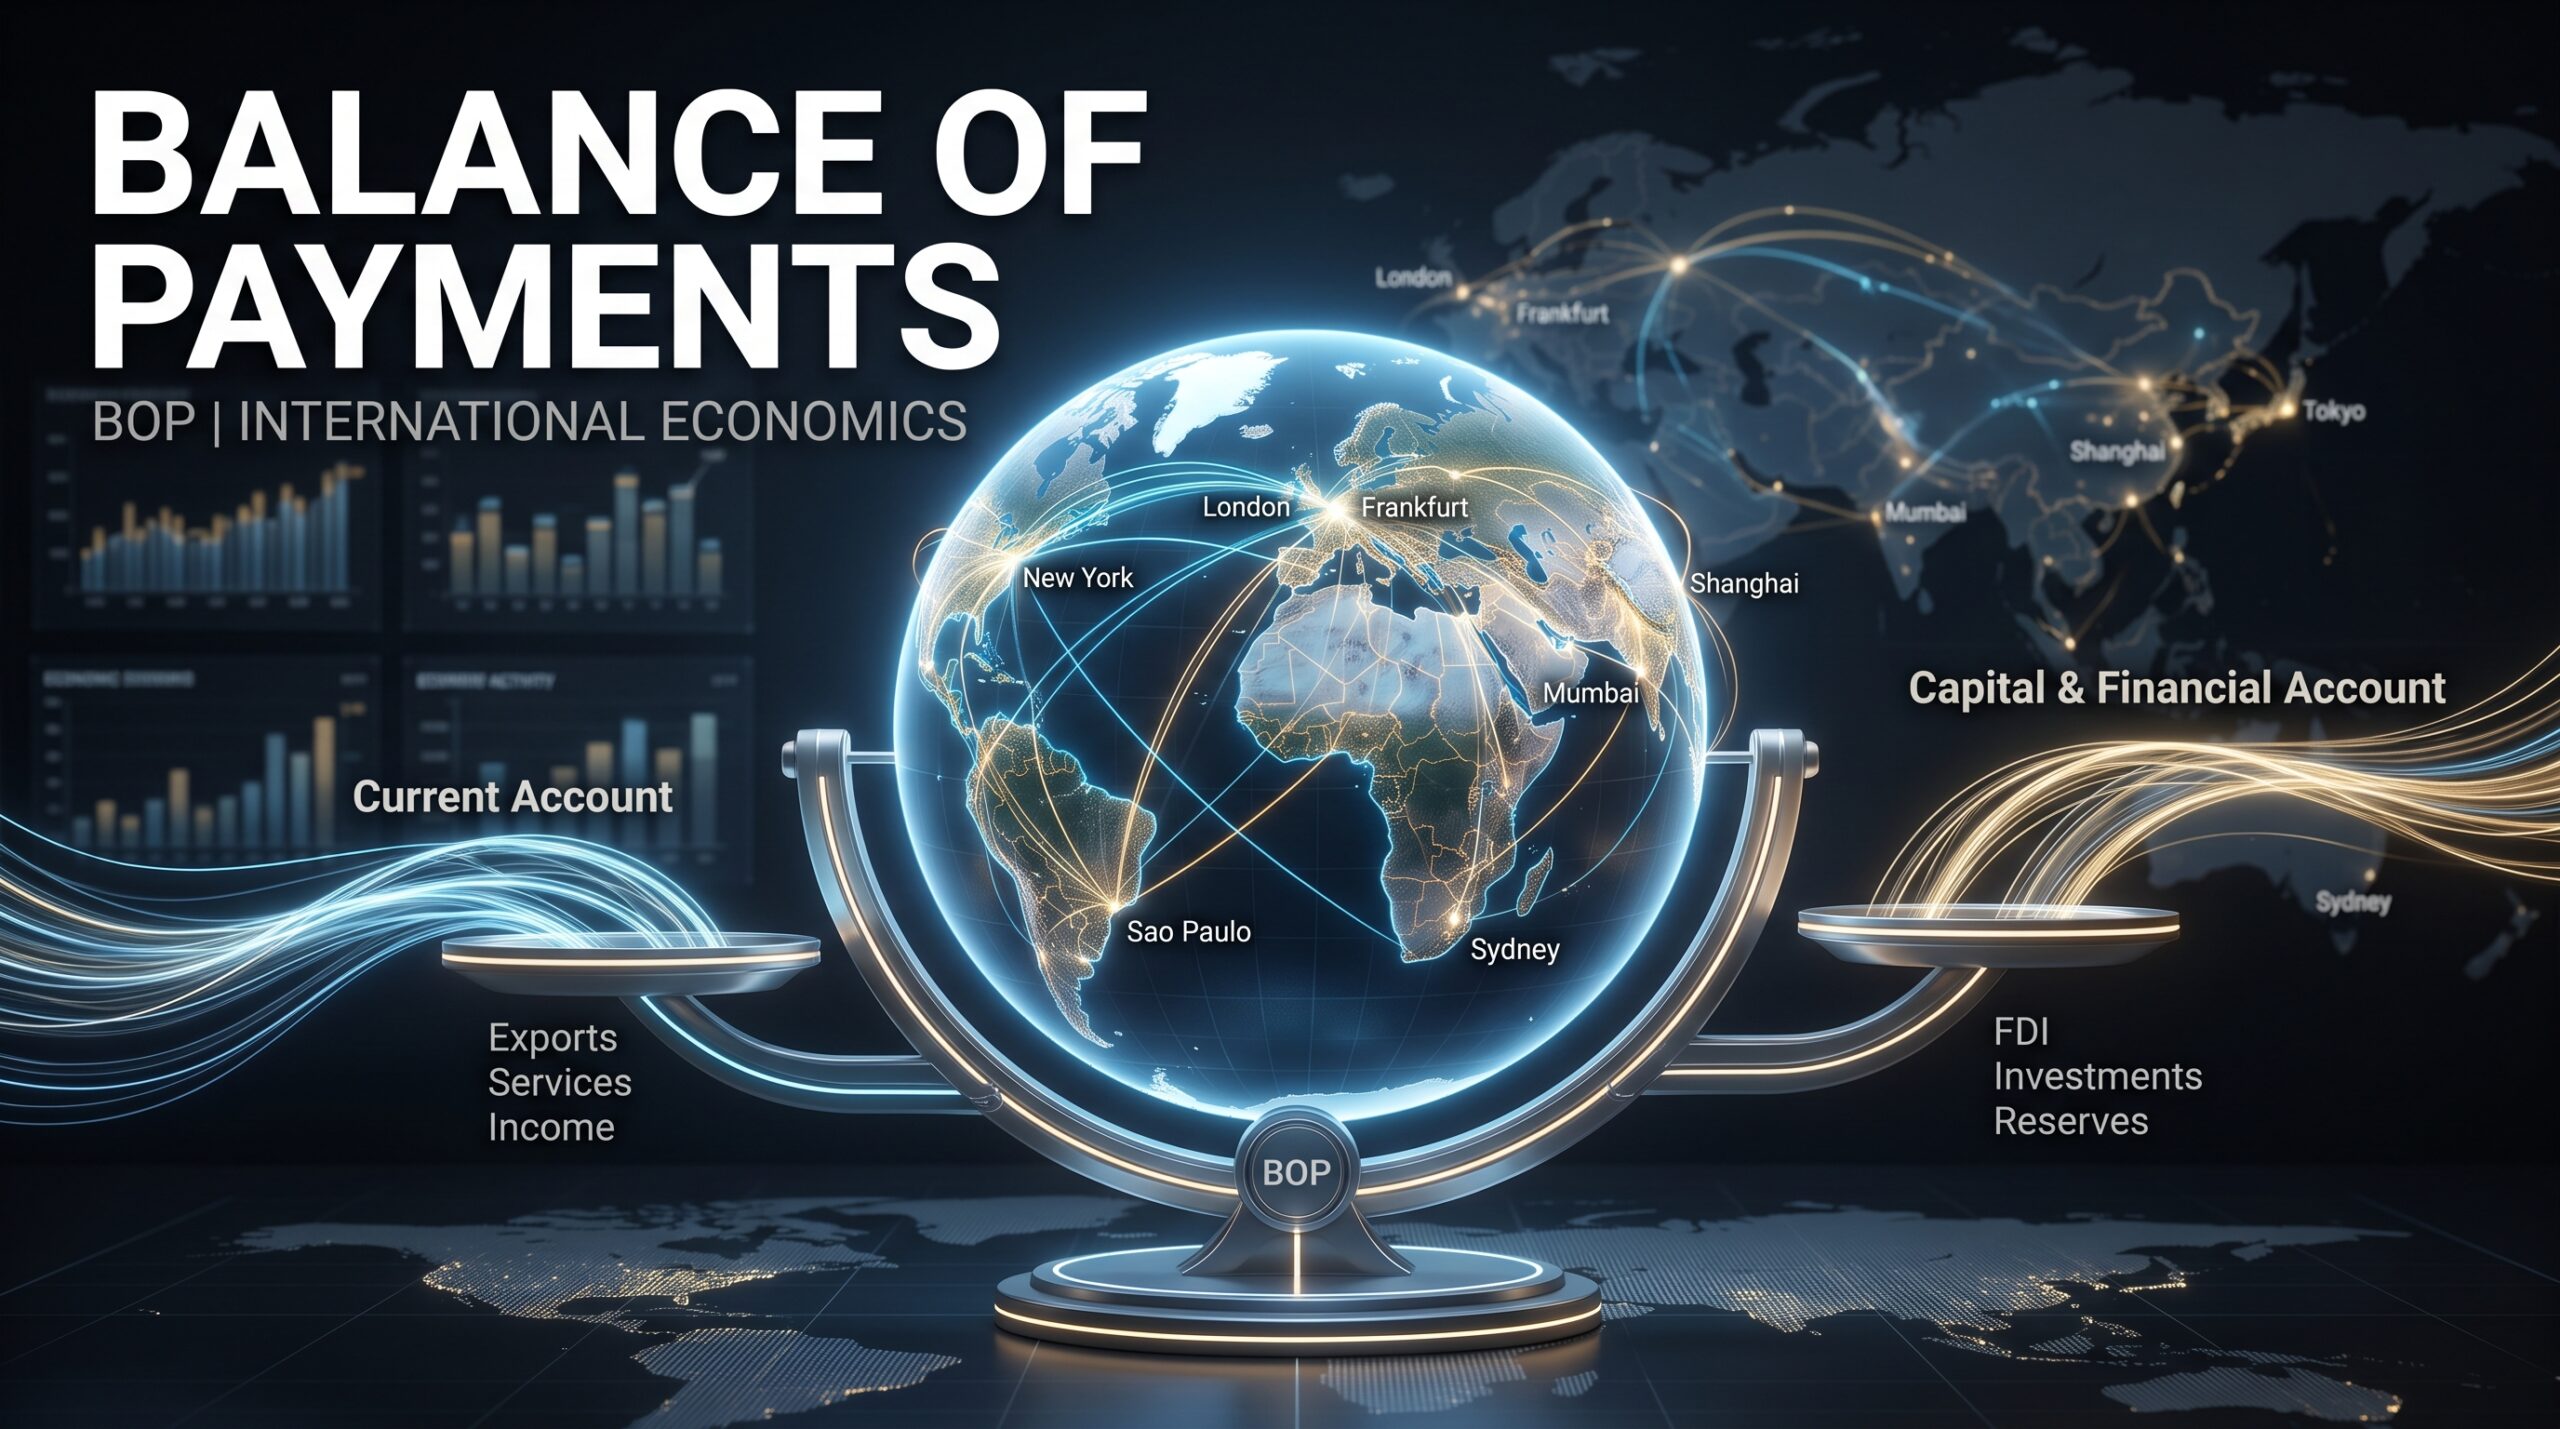
The fundamental rule of Balance of Payments accounting is that it operates on a double-entry bookkeeping system. Every international transaction results in two entries: a credit and a debit. Theoretically, the sum of all elements in the BOP must always equal zero.
$$\text{Current Account} + \text{Capital Account} + \text{Financial Account} + \text{Net Errors and Omissions} = 0$$
In reality, because data collection from thousands of trade ports, banks, and remittance channels is prone to discrepancies, central banks use a balancing item called Net Errors and Omissions to make the ledger balance. When economists talk about a “BOP surplus” or a “BOP deficit,” they are not referring to the entire ledger summing to zero; rather, they are looking at specific sub-accounts—most notably the current account and official reserve assets.
The Three Core Components of the BOP
The Balance of Payments is officially structured into three primary accounts:
1. The Current Account
The Current Account records the flow of goods, services, primary income, and secondary income. It represents the most tangible part of international trade.
- Trade in Goods (Visible Trade): Physical merchandise exports (e.g., textiles, agricultural products) and imports (e.g., machinery, crude oil, electronics).
- Trade in Services (Invisible Trade): Non-physical services such as IT exports, shipping logistics, tourism, insurance, and financial services.
- Primary Income: Compensation paid to non-resident workers and investment income (dividends, interest earned on foreign investments or paid on foreign debt).
- Secondary Income: Current transfers such as worker remittances, foreign aid, and international grants where no direct good or service is received in return. For developing economies like Pakistan, this sub-category—specifically worker remittances—acts as a vital economic cushion.
2. The Capital Account
The Capital Account is relatively small in most economies. It records non-market, non-produced, and intangible asset transfers. This includes the acquisition or disposal of non-produced, non-financial assets (such as patents, copyrights, trademarks, and franchises), as well as debt forgiveness granted by foreign governments.
3. The Financial Account
The Financial Account records international monetary transactions involving financial assets and liabilities. It tracks how a country finances its current account imbalances and invests its surplus capital. It is broken down into four main components:
- Foreign Direct Investment (FDI): Long-term investments where a foreign entity acquires a lasting interest or managerial control in a domestic enterprise (e.g., building a manufacturing plant or acquiring a local telecom company).
- Portfolio Investment: Transactions in financial securities like stocks and bonds. Unlike FDI, portfolio investment is liquid and can enter or leave a country rapidly based on market sentiment.
- Other Investment: Trade credits, loans, currency deposits, and transactions with the International Monetary Fund (IMF).
- Reserve Assets: Foreign currency reserves, gold holdings, and special drawing rights (SDRs) held by the central bank. Changes in reserve assets reflect how the central bank intervened to stabilize the currency.
Why a BOP Crisis Occurs
A Balance of Payments crisis (often referred to as an exchange rate crisis or currency crisis) happens when a country cannot pay for its essential imports or service its external debt obligations because its foreign exchange reserves have been completely depleted.
This typically unfolds through a predictable chain reaction:
- Persistent Current Account Deficits: The country imports vastly more goods and services than it exports, and remittances fail to cover the gap.
- Depleting Reserves: To defend the local currency from crashing, the central bank sells off its foreign exchange reserves (US Dollars, Euros) in the open market.
- Capital Flight: Foreign and domestic investors, sensing economic instability, pull their money out of local stocks and bonds (portfolio investments).
- Exhaustion: Foreign reserves hit critically low levels (sometimes falling below a few weeks’ worth of import cover).
- IMF Bailout: The government is forced to approach international lenders like the IMF for an emergency stabilization program, which usually comes with harsh conditions, including massive interest rate hikes, tax increases, and currency devaluation.
The Strategic Value of BOP Data
For readers of economist.media, monitoring the quarterly BOP statements published by the central bank provides a crystal ball into future economic policy. If the financial account fails to attract enough FDI or loans to cover a widening current account deficit, the writing is on the wall: currency depreciation and policy tightening are imminent. Conversely, a healthy BOP surplus allows a central bank to build up robust foreign reserves, stabilize inflation, and foster investor confidence.
Key Takeaways:
- The Balance of Payments is a complete ledger of all economic transactions between a country and the rest of the world.
- It consists of three main segments: the Current Account, the Capital Account, and the Financial Account.
- Worker remittances and international trade make up the core of the current account in developing nations.
- A BOP crisis occurs when foreign exchange reserves are depleted, forcing nations to seek emergency IMF bailouts.
Authoritative Sources & Further Reading:
- International Monetary Fund (IMF): Balance of Payments Manual (BPM6)
- World Bank: Global Financial Development and BOP Data
- State Bank of Pakistan (SBP): External Sector Statistics
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

For most of the past decade, the “digital gold” thesis held that Bitcoin would eventually absorb gold’s role as the world’s preferred crisis hedge. In 2026, the data tells a more complicated story — and for now, a less flattering one for Bitcoin. Gold is trading near $4,400/oz, up roughly 32% over the trailing year, supported by record central bank accumulation. Bitcoin, trading near $77,000–$79,000, is down nearly 40% from its October 2025 all-time high of $126,073. JPMorgan’s own institutional-positioning data — derived from CME futures open interest — shows hedge funds actively reducing direct Bitcoin exposure while rotating into gold for defensive purposes through much of this year.
This is the central question for any financial advisor or institutional allocator heading into Q4: is 2026 a temporary setback for crypto’s safe-haven ambitions, or a more durable repricing of what Bitcoin actually is?
Key Takeaways
- Gold has clearly outperformed Bitcoin as a defensive asset in 2026, with stronger one-year returns, lower drawdowns, and continued central bank accumulation.
- Institutional flow data (JPMorgan, Bloomberg) shows a rotation away from direct Bitcoin exposure and toward gold for hedge fund defensive positioning.
- Gold ETF outflows (nearly $15 billion since March, per some tracking) have actually been larger in absolute terms than Bitcoin ETF outflows, complicating a simple “money is fleeing gold for crypto” narrative — the picture is one of broad de-risking, not a clean rotation.
- Even crypto-native institutions are diversifying into gold: Tether’s own treasury held roughly 146 metric tons of gold alongside ~98,933 BTC as of Q2 2026, adding 14 tons of gold in the quarter.
- The most credible institutional framework for 2026 is not “gold or Bitcoin” but a blended allocation — gold for systemic, slow-burning risk; Bitcoin for long-duration, higher-conviction asymmetric upside.
The 2026 Scorecard: Gold vs. Bitcoin by the Numbers
| Metric | Gold | Bitcoin |
|---|---|---|
| Approx. price (Sept 2026) | $4,400–$4,450/oz | $77,000–$79,000 |
| Change from 2026 all-time high | Down from $5,597 (Jan 2026) | Down ~38–40% from $126,073 (Oct 2025) |
| Trailing 1-year performance | +~32% | Down roughly 46% at Aug 2026 lows before partial recovery |
| Trailing 3-year performance | +~132% | +~117% |
| Institutional flow trend (2026) | Central bank buying remains structural; ETF outflows reflect profit-taking | Hedge funds reducing direct exposure per JPMorgan |
| Volatility character | Lower drawdowns, more stable in crisis | High-beta, correlated with broader risk-asset liquidity |
The three-year comparison is instructive: Bitcoin’s long-run annualized outperformance versus gold — historically a factor of 10x or more over a full decade — has compressed dramatically when measured over the most recent three-year window. That compression is the core evidence for the “safe haven” debate: an asset behaving as true portfolio insurance should not be down nearly 40% from a 12-month-old high while gold sits near record territory.
Why Institutions Are Choosing Gold Over Bitcoin for Defensive Positioning in 2026
1. Central Bank Demand Has No Bitcoin Analog
Gold’s structural bid comes from an actor class that simply does not exist for Bitcoin at comparable scale: sovereign central banks, which have been net buyers of gold for reserve diversification since 2022–2023 and have continued accumulating through 2026’s volatility. No G20 central bank is running a comparable Bitcoin reserve-accumulation program, meaning gold retains a buyer of last resort that is largely insulated from retail sentiment swings — a critical distinction when advising institutional clients on crypto trading platforms allocation sizing.
2. Liquidity Has Deteriorated Differently
Earlier in 2026, JPMorgan flagged that gold’s liquidity (measured via CME futures market depth) had actually deteriorated below Bitcoin’s during a period of heavy ETF outflows and position unwinds — a genuinely counterintuitive finding that briefly supported the “Bitcoin as the more resilient hedge” narrative in Q1. That dynamic has since reversed: by mid-2026, hedge funds were once again favoring gold for defensive positioning as macro conditions (renewed Middle East escalation, Fed policy uncertainty) intensified — suggesting gold’s liquidity advantage reasserts itself specifically during genuine crisis conditions, which is exactly when a hedge needs to work.
3. Bitcoin ETF Flows Tell a More Nuanced Story Than the Headlines Suggest
It would be a mistake to read 2026 purely as “money leaving crypto for gold.” Bitcoin ETFs (led by products like IBIT) have continued to absorb net inflows through multiple stretches of the year — at one point logging six consecutive weeks of positive flows, the longest streak since mid-2025. The more accurate read is that both asset classes have experienced volatility and periods of outflow, but gold’s structural, non-discretionary buyer (central banks) has provided a floor that Bitcoin — dependent entirely on discretionary institutional and retail demand — does not yet have.
Where Institutional Investors Are Actually Positioning Capital
| Investor Type | 2026 Behavior | Implication |
|---|---|---|
| Central banks | Continued net gold accumulation | Structural gold demand floor |
| Hedge funds (per JPMorgan) | Reducing direct BTC exposure; favoring gold | Defensive positioning rotation |
| Bitcoin ETF investors (IBIT, FBTC) | Mixed — periods of strong inflows offset by outflow stretches | Bitcoin remains a discretionary, sentiment-driven allocation |
| Crypto-native institutions (e.g., Tether) | Diversifying treasury into physical gold alongside BTC holdings | Even “crypto-first” balance sheets see value in bullion |
| Sovereign wealth funds | Selective silver/gold accumulation; limited public BTC allocation | Traditional havens remain the default sovereign posture |
A Practical Hedging Framework for 2026–2027
For a financial advisor building institutional or high-net-worth portfolios into year-end, the evidence supports a barbell rather than a binary choice:
- Gold as the core systemic hedge (5–10% of portfolio). Use for protection against dollar debasement, fiscal deficit risk, and geopolitical escalation — the slow-burning, structural risks gold has always been purpose-built to absorb.
- Bitcoin as a smaller, conviction-sized growth allocation (2–5%). Size it to what the portfolio can absorb if it corrects another 30% before resuming any longer-term adoption-driven climb — treat it as a call option on continued institutional adoption, not as portfolio insurance.
- Physical silver or silver ETFs as a tactical overlay (0–3%). Useful for investors wanting additional torque to the broader precious-metals thesis without full crypto-market volatility exposure.
- Monitor institutional flow data, not just price. CME futures open interest and ETF flow reports (JPMorgan, Bloomberg’s Eric Balchunas commentary, and issuer-level fund flow data) are more reliable leading indicators of where “smart money” is actually positioned than headline price action alone.
FAQ
Is gold or Bitcoin the better hedge in 2026?
Based on 2026 data, gold has been the more reliable defensive asset — supported by structural central bank buying, lower drawdowns, and renewed institutional preference during periods of genuine macro stress. Bitcoin continues to behave more like a high-volatility growth asset than a stable hedge this year.
Are institutions abandoning Bitcoin entirely?
No. Bitcoin ETFs have continued to see meaningful inflow periods throughout 2026, and crypto-native institutions like Tether continue to hold and grow substantial BTC treasuries. What’s changed is that hedge funds specifically reducing defensive exposure are rotating toward gold, not that institutional interest in Bitcoin overall has collapsed.
Why do central banks buy gold but not Bitcoin?
Central banks’ mandate around reserve assets prioritizes deep liquidity, multi-century price history, and political/regulatory neutrality — characteristics gold has accumulated over millennia that Bitcoin, still under two decades old and subject to evolving regulatory treatment, has not yet established at sovereign-reserve scale.
What percentage of a portfolio should be allocated to crypto in 2026?
Most institutional frameworks in 2026 suggest a conviction-sized allocation of roughly 2–5% for investors comfortable with high volatility, treating Bitcoin as an asymmetric-upside growth position rather than a core defensive holding.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Cryptocurrency
Bitcoin Merchant Services: The BRICS De-Dollarization and Tokenized Cross-Border Payments
Global trade settlement is undergoing a structural revolution. With sovereign public debt reaching unprecedented highs and traditional fiat rails encumbered by geopolitical friction, merchants and multinational corporations are aggressively adopting Bitcoin and tokenized payment gateways. The accelerating de-dollarization trend led by emerging economic blocs has made decentralized merchant services a commercial necessity rather than a speculative alternative.
Integrating Bitcoin merchant services allows businesses to bypass legacy correspondent banking fees, eliminate chargeback fraud, and settle international transactions instantly.
Advantages of Bitcoin Merchant Infrastructure
Zero-Fee Lightning Network Settlements
Modern Bitcoin payment gateways utilize Layer-2 Lightning Network architecture, enabling micro-transactions and enterprise-scale invoices to settle in milliseconds for fractions of a cent. This eliminates the 2% to 4% merchant fees traditionally levied by credit card processors.
Hedging Against Sovereign Currency Devaluation
Operating in emerging markets with volatile local currencies exposes exporters to severe devaluation risk. By automatically converting incoming revenue into Bitcoin or stablecoins, businesses protect their balance sheets against inflationary shocks.
| Payment Gateway | Settlement Layer | Transaction Fee | Best Suited For |
| BitPay Enterprise | On-chain & Lightning | 1% flat fee | E-commerce & B2B Invoicing |
| OpenNode API | Lightning Network Only | 0.5% flat fee | SaaS & Digital Subscriptions |
| BTCPay Server (Self-Hosted) | Direct Node / Zero Intermediary | 0% (Self-hosted) | High-Volume Global Merchants |
Implementing Crypto Merchant Services Securely
Transitioning your business to accept Bitcoin requires careful technical and accounting preparation.
Choose Non-Custodial Infrastructure: Opt for self-hosted payment nodes whenever possible to retain complete sovereign control over your funds.
Automate Accounting Compliance: Integrate crypto tax and bookkeeping plugins to track cost basis and capital gains in real-time.
Establish Clear Refund Policies: Define how crypto price fluctuations are handled during returns or order cancellations.
“Fintech Analyst Note: As international trade fragments along geopolitical lines, Bitcoin merchant rails provide neutral, censorship-resistant settlement infrastructure that no single nation can freeze or manipulate.”
Adopting Bitcoin merchant services positions forward-thinking businesses at the vanguard of the new global digital economy, ensuring frictionless cross-border growth.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Elon Musk’s Boring Company Hits $23B Valuation After UAE-Led $3 Billion Series D

Middle East War Economics 2026: Oil Prices & Energy Markets

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Asian Markets Outlook 2026: China, Japan & Singapore Stocks

Global Economy 2026: IMF Growth, Inflation & Private Credit

Current Account Deficit (CAD) : Causes and Impact

Balance of Payments (BOP)

The Falkland Islands Dispute: Sovereign Wealth, Offshore Drilling, and Market Impacts

Gross Domestic Product (GDP): Nominal vs. Real

What is Inflation and the Consumer Price Index (CPI)?

US-China Trade Competition 2026: Supply Chain Relocation Guide

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

South-South Trade Expansion: Digital Integration and Emerging Market Growth

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Gold’s Wild 2026: From a Record $5,600 Peak to a 24% Crash and Back Toward $4,500

Oil Surges as Strait of Hormuz Traffic Collapses Again

The Rocket That Won’t Quit: Inside SpaceX’s Falcon 9 Launch Machine

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Retail Earnings Week: What Home Depot, Target & Walmart Reveal

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

Tween Back-to-School Trends 2026: What’s Driving the $85B Season
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025