
Fintech & Global Finance
Technology News 2026: Inside the $1.3T AI Chip Boom

How big is the AI chip industry in 2026? Global semiconductor revenue is projected to exceed $1.3 trillion in 2026 — a 64% increase and the fastest growth the industry has recorded in more than 20 years, according to research firm Gartner. That would mark a third consecutive year of double-digit growth for the sector, driven by surging demand for AI processing, data-center infrastructure, and rising memory prices, per Gartner senior principal analyst Rajeev Rajput.
That single statistic captures why “technology news” in 2026 is really one story told through dozens of companies: an unprecedented, sustained capital-spending cycle built around artificial intelligence infrastructure.
Hyperscalers Are the Engine
The chip boom is being funded almost entirely by a handful of technology giants. Alphabet, Amazon, Microsoft, and Meta — the hyperscalers building the cloud infrastructure that AI models run on — have collectively committed more than $700 billion in 2026 capital spending, according to reporting relayed through Yahoo Finance’s technology desk. Alphabet alone spent $35.67 billion on capital expenditure in a single quarter — more than double the prior year’s pace — while its Google Cloud backlog nearly doubled to over $460 billion. Amazon led quarterly spending at $44.2 billion as AWS grew 28%, and Microsoft’s fiscal third-quarter capex rose 84% year-over-year to $30.88 billion as its AI revenue run rate surpassed $37 billion annually.
Featured Snippet Target: The four largest U.S. hyperscalers — Alphabet, Amazon, Microsoft, and Meta — are on pace to spend over $700 billion combined on AI infrastructure in 2026, a figure Reuters’ Morning Bid podcast described as rising “all the time” and directly responsible for surging demand for AI chips and data-center equipment.
That spending has increasingly shifted from being funded purely by operating cash flow to relying on debt and equity markets. Alphabet’s June 2026 equity raise — combining Class A common stock, Class C capital stock, and mandatory convertible preferred shares — ranks as the largest single AI-funding capital raise in market history, according to market commentary circulated via KuCoin’s research desk. Goldman Sachs has characterized this as a structural shift from a low-cost-of-capital “Modern” cycle to a higher-volatility “Post-Modern” one, in which markets increasingly reward capital expenditure over share buybacks — S&P 500 companies posted 24% year-on-year capex growth in the second quarter of 2026 alongside a 1% decline in gross buybacks.
Nvidia’s Next Move — and Who’s Chasing It
Nvidia remains the chip industry’s dominant supplier, and its next-generation product cycle is central to 2026’s technology narrative. The company introduced its Rubin CPX GPU — built for massive-context AI workloads capable of handling million-token software coding and generative-video tasks — with availability expected by the end of 2026, according to trade coverage from DigiTimes. Competitors are racing to diversify the supply chain around Nvidia’s dominance: AMD is preparing new product launches with OpenAI as a customer, Broadcom and OpenAI are targeting mass production of custom AI silicon in 2026, and Broadcom separately secured a $10 billion custom-chip production order from a major new customer, according to the same industry reporting.
China’s chip ecosystem is developing along a parallel, more insulated track. Huawei and Cambricon Technologies are together projected to ship over a million AI chips by 2026, with JPMorgan forecasting Huawei alone shipping 600,000 to 650,000 units, as Beijing pushes to reduce reliance on U.S.-made chips amid ongoing export restrictions.
Where the Growth Is Concentrated
Analysts covering the sector point to datacenter accelerators as the single largest growth pocket within the broader chip market — that segment alone is projected to exceed $300 billion in 2026, according to industry analysis from TechInsights, with knock-on effects spanning process technology (including the industry’s push toward 2-nanometer manufacturing), advanced packaging techniques, and power infrastructure needed to run increasingly energy-intensive AI data centers.
That last point — power — has become a genuine bottleneck rather than a footnote. Industry commentary increasingly frames electricity supply and cooling capacity, not chip fabrication itself, as the binding constraint on how quickly AI infrastructure can scale, positioning data-center operators and power-infrastructure companies as unexpected beneficiaries of the AI boom alongside the chipmakers themselves.
The Risk Beneath the Boom
Not every voice in the technology sector is unreservedly bullish on the pace of spending. Analysis circulated through Charles Schwab’s market commentary notes that three hyperscalers — Alphabet, Amazon, and Meta — now account for roughly 70% of the S&P 500’s expected 2026 earnings growth, meaning the index’s apparent 500-company diversification offers less real downside protection than investors might assume if AI capital spending fails to convert into earnings at the pace currently priced in.
That concentration risk has already produced volatility. Mid-September market commentary from CNBC noted bond yields spiking and AI-linked stocks selling off even as broader investor sentiment stayed constructive on equities overall — an early signal that markets are starting to price a wider range of outcomes for the AI capex cycle than the unbroken bull run of the year’s first half suggested.
The Bottom Line
Technology news in 2026 is dominated by a single, self-reinforcing cycle: hyperscaler capital spending is driving record semiconductor demand, chipmakers are racing to keep pace with that demand through new architectures and expanded manufacturing, and financial markets are increasingly rewarding — and increasingly questioning — the sustainability of spending at this scale. Whether that questioning turns into a genuine correction depends on whether AI infrastructure investment converts into earnings growth fast enough to justify the capital already committed.
Next step: Track quarterly hyperscaler capex guidance alongside chipmaker order backlogs — the gap between the two, more than any single product launch, is the clearest early signal of whether 2026’s AI infrastructure boom is accelerating or beginning to plateau.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Goldman Sachs wins on profit and returns. In the second quarter of 2026 it reported net earnings of $6.63 billion on net revenues of $20.34 billion. By our math, that is roughly 33 cents of profit per revenue dollar.
- Citigroup wins on sheer revenue. Citi booked $24.8 billion of revenue and $5.8 billion of net income in the same quarter. That works out to about 23 cents of profit per revenue dollar.
- They are different kinds of bank. Goldman is a markets, advisory and asset-management house. Citi is a global transaction bank with a wealth arm, a markets desk and a U.S. consumer business.
- Returns separate the two. Goldman’s return on tangible common equity was 21.3% in the first quarter, while Citi was running at about 13% in the second quarter and still guiding to 10% to 11% for the full year.
- “Leads” depends on the yardstick. Profitability points to Goldman. Global payments plumbing, balance-sheet breadth and turnaround upside point to Citi.
Ask ten bankers which of these two firms leads global finance and you will get ten answers, usually shaped by which floor they work on. A trader at Goldman and a treasury specialist at Citi are, in practice, living in different industries that happen to share a zip code.
So let’s settle it with a scoreboard instead of a debate. This guide compares the two banks using their own filings for the quarter ended June 30, 2026, then adds the context raw numbers can’t carry: strategy, capital return and the unfinished business sitting inside Citi’s turnaround.
One caution before the table. Per-share figures are not comparable across the two firms. Goldman’s $20.98 earnings per share and Citi’s $3.15 reflect very different share prices and share counts, not a seven-fold gap in quality. Compare margins, growth and returns instead.
The Q2 2026 Scorecard
| Metric (Q2 2026) | Goldman Sachs | Citigroup |
|---|---|---|
| Revenue | $20.34B (up 39% year over year) | $24.8B (up 14%) |
| Net income | $6.63B | $5.8B (up 45%) |
| Earnings per share | $20.98 | $3.15 (vs. $1.96 a year ago) |
| Profit per revenue dollar (our calculation) | About 33 cents | About 23 cents |
| Latest return on tangible common equity cited | 21.3% (Q1 2026) | 13% (Q2 2026) |
| Headline capital return | Quarterly dividend raised to $5.00 per share | $30B buyback commitment; dividend increase of about 12% |
Sources: Goldman Sachs Q2 2026 earnings release, Citigroup’s Q2 2026 Form 10-Q and Citi’s Q2 earnings-call highlights. The Goldman return figure comes from the first quarter, the latest in our sources, so treat the ROTCE gap as directional rather than a perfect like-for-like comparison.
How Goldman Sachs Makes Its Money
Goldman’s second quarter was loud. Net revenues rose 39% from a year earlier and 18% from the first quarter. The filing credits the jump primarily to Global Banking & Markets, which produced $15.52 billion, up 53% year over year.
The second engine, Asset & Wealth Management, added $4.60 billion, up 20%. Across the first half of 2026, Goldman generated $37.57 billion of net revenues and $12.26 billion of net earnings.
What does that mix tell you?
- Trading and advisory income is cyclical. It tends to swell when volatility is high and clients are repositioning, which describes much of 2026 so far.
- Asset and wealth management is steadier. Management fees and client inflows give Goldman a base that doesn’t depend on any single week of market chaos.
- The model is capital-light relative to a deposit-funded bank. That is part of why profit per revenue dollar looks so strong, and part of why earnings can swing harder than Citi’s.
The board also lifted the quarterly dividend to $5.00 per share for the third quarter. That is the kind of move a firm makes when it feels good about its earnings power, though dividends are never guaranteed.
How Citigroup Makes Its Money
Citi is built differently. It reports five interconnected businesses (Services, Markets, Banking, Wealth and U.S. Personal Banking) plus a set of legacy franchises being wound down or sold.
In the second quarter, net interest income reached $17.1 billion, up 13%, while non-interest revenue was $7.6 billion, up 18%. One detail stands out: Markets non-interest revenue was $3.0 billion against $3.2 billion a year earlier, so the growth did not come from the trading floor. It came from deposits, fees and the transaction-banking machinery underneath.
That machinery is Services, Citi’s treasury, trade and securities-services franchise. CEO Jane Fraser said it delivered its highest quarterly revenue ever and a return above 30%, per the earnings-call recap.
Think of Services as the plumbing of cross-border commerce. When a multinational moves cash between 90 countries, Citi often sits in the middle. That position is slow to build, hard to replicate and surprisingly sticky.
Profitability and Returns: The Gap That Matters
Return on tangible common equity (ROTCE) measures how much profit a bank earns on the shareholder capital that isn’t tied up in goodwill and intangibles. Analysts lean on it because it translates “how big is the bank” into “how well does the bank use its capital.”
Here is how the two stack up against peers, using first-quarter 2026 figures from Banking Dive:
- JPMorgan: 23%
- Goldman Sachs: 21.3%
- Bank of America: 16%
- Wells Fargo: 14.5%
- Citigroup: 13.1%
Citi is improving fast, with second-quarter net income up 45%, but it is still catching up to the pack. Goldman sits near the top of the table.
Citi’s Unfinished Business
If Goldman’s story is “keep executing,” Citi’s story is “finish the rebuild.” Four items matter.
1. A long runway of return targets
Citi still guides to 10% to 11% ROTCE for 2026. At its May investor day it set a path of 11% to 13% for 2027 and 2028, then 14% to 15% across 2029 to 2031, according to Reuters. Some investors wanted a bolder near-term number, and RBC analysts called the near-term target underwhelming. Management keeps describing 2026 as a waypoint, not a destination.
2. The Banamex exit
Citi has now sold 49% of Banamex, its Mexican consumer franchise. It does not expect further sales in 2026, plans to deconsolidate early in 2027, and will pursue an IPO when markets allow.
3. Capital return
The $30 billion buyback commitment and the planned dividend increase signal confidence, and they shrink the share count, which helps per-share math over time.
4. The transformation program
Fraser said a large body of work passed internal-audit validation during the quarter. For a bank that has spent years under regulatory pressure to fix its controls, that is quiet but meaningful progress.
Which Bank Leads? Seven Lenses
| Lens | Edge | Why |
|---|---|---|
| Profitability and returns | Goldman | Higher profit per revenue dollar and a much higher ROTCE |
| Revenue scale (Q2 2026) | Citi | $24.8B versus $20.34B |
| Cross-border transaction banking | Citi | Services is a record-setting, 30%-plus-return franchise |
| Advisory and capital-markets brand | Goldman | Global Banking & Markets revenue up 53% |
| Earnings stability | Citi, narrowly | Deposit and fee income is less tied to deal and trading cycles |
| Turnaround upside | Citi | More room to close the returns gap if targets are hit |
| Earnings momentum (net income growth) | Goldman | Revenue up 39% year over year in Q2 |
If you force a single verdict, Goldman “leads” on the metric Wall Street weighs most, which is returns on capital. Citi “leads” on the breadth of its global footprint. Neither answer is wrong. They just answer different questions.
What to Watch Next
If you follow bank stocks, three things deserve a spot on your calendar. This is general information, not investment advice.
- Third-quarter earnings. Both banks typically report in mid-October, so check each firm’s investor-relations calendar for exact dates.
- Citi’s ROTCE path. The gap between roughly 13% today and the 14% to 15% medium-term target is the whole equity story.
- Goldman’s trading durability. A quarter of revenue up 39% sets a high bar for the next one.
Asked & Answered
Is Goldman Sachs more profitable than Citigroup?
On the latest quarterly numbers, yes. Goldman earned $6.63 billion on $20.34 billion of revenue, while Citi earned $5.8 billion on $24.8 billion. Goldman converts more of each revenue dollar into profit.
What is ROTCE, and why do analysts care so much?
ROTCE is return on tangible common equity. It shows how efficiently a bank turns shareholder capital into profit, excluding goodwill and intangibles. It is the cleanest single yardstick for comparing banks of different sizes.
Are Goldman and Citi direct competitors?
Partly. They overlap in investment banking and markets trading. Beyond that, Citi is also a global payments, custody, wealth and credit-card business, while Goldman is far more focused on markets, advisory and asset management.
Does the Banamex sale matter for investors?
It does. Selling Banamex releases capital, simplifies the company and clears a long-running distraction. Deconsolidation is expected early in 2027, with an IPO to follow when conditions are right.
When do Goldman and Citi report next?
Both normally publish third-quarter results in mid-October. Confirm the exact dates on each company’s investor-relations page before you plan around them.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
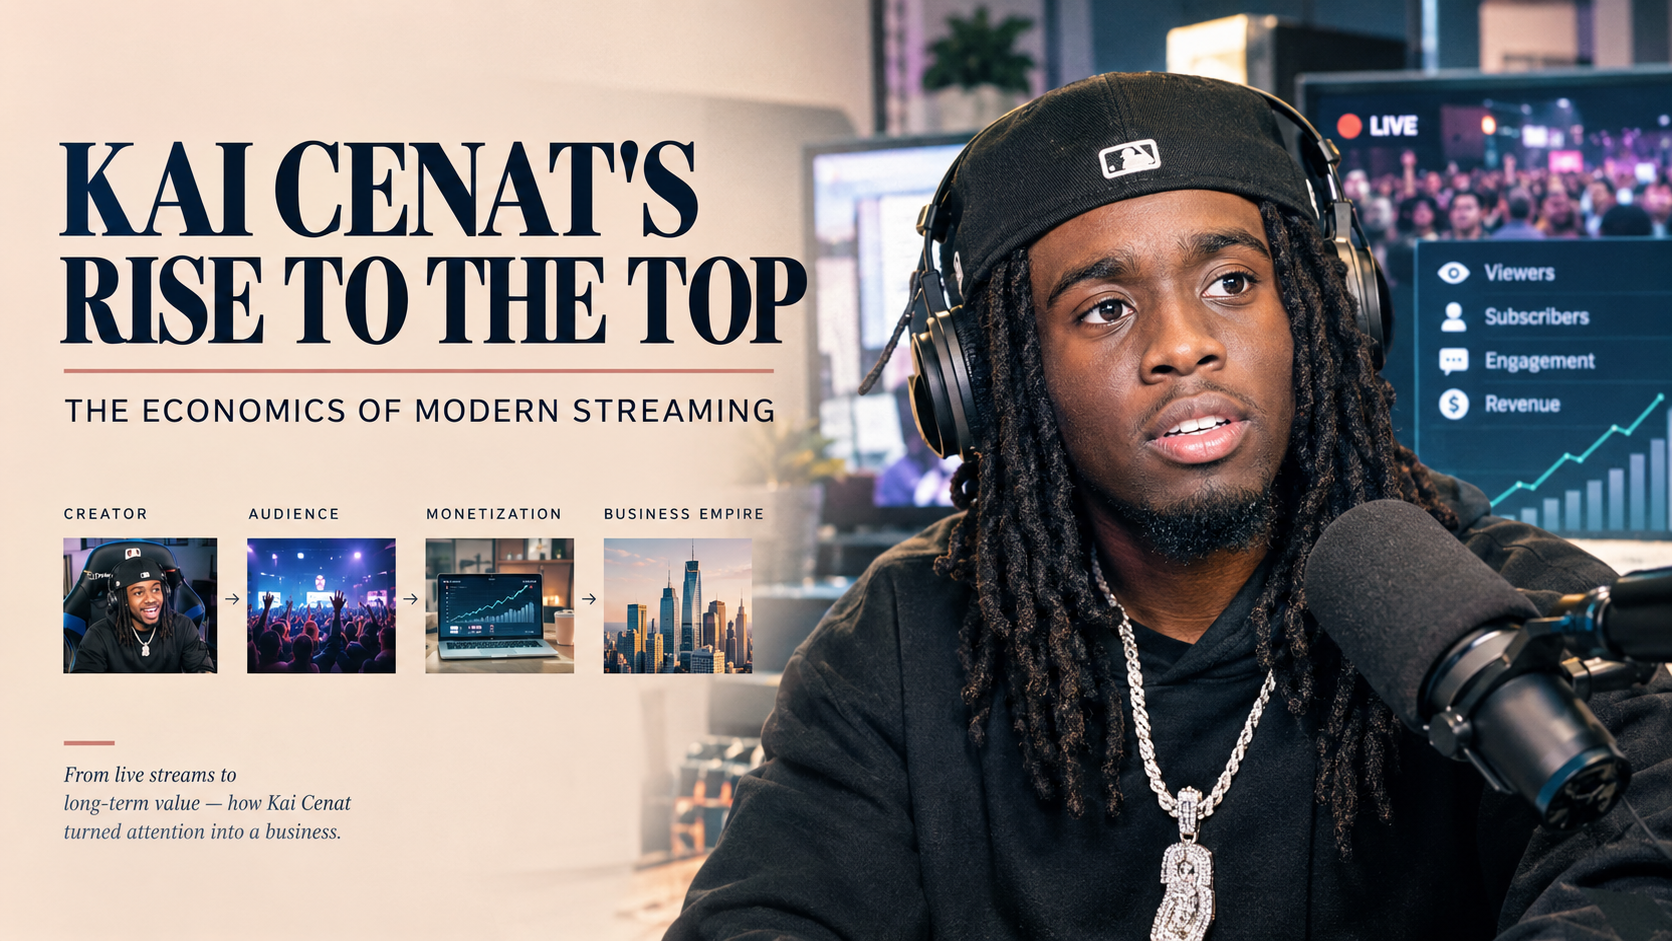
Kai Cenat turned a month of non-stop livestreaming into the biggest subscriber haul in Twitch history, and the business model underneath it is stranger and more lucrative than it looks.
Key Takeaways
- First to 1 million. On September 28, 2025, Cenat became the first Twitch streamer to pass one million active subscribers, during his third “Mafiathon” subathon (Influencer Marketing Hub).
- Record trajectory. His Mafiathon 2 in November 2024 hit roughly 728,000 subscribers, topping the previous record of 326,250 held by VTuber Ironmouse (Yahoo Tech).
- Scale of attention. Mafiathon 3 tallied 82.5 million hours watched and a peak above one million concurrent viewers (Influencer Marketing Hub).
- Revenue engine. Subscriptions are only one layer; sponsorships, celebrity-driven reach, and brand deals multiply the value of each record.
| Event | Date | Subscribers | Notes |
|---|---|---|---|
| Mafiathon 1 | 2023 | ~306,600 | Overtook Ludwig’s record (Wikipedia) |
| Mafiathon 2 | Nov 2024 | ~728,000 | Beat Ironmouse; ~50M unique viewers reported (Yahoo Tech) |
| Mafiathon 3 | Sept 2025 | 1,000,000+ | First streamer past 1M; 82.5M hours watched |
How a Subathon Makes Money
A subathon is a livestream marathon where each new subscription adds time to the clock. The mechanism is simple and powerful:
- Viewers subscribe (a Tier 1 sub costs $4.99 a month).
- Each sub extends the stream, giving fans a stake in the outcome.
- Gift subs spread the effect, letting communities pool money to push the number higher.
- Celebrity guests drive news cycles, pulling in casual viewers who may subscribe once.
Cenat’s 2024 event featured guests such as Snoop Dogg, Kevin Hart, Serena Williams, Lizzo, and SZA, per People of Color in Tech, which also reported the stream was staffed to continue while he slept.
The Revenue Math
Platform splits vary, but Twitch has been reported to keep between 30% and 50% of subscription fees (Yahoo Tech). Using that range, here is an illustrative (not reported) calculation for one month of one million Tier 1 subscriptions:
| Step | Amount |
|---|---|
| Gross at $4.99 × 1,000,000 | ~$4.99 million |
| Streamer share at 50% | ~$2.5 million |
| Streamer share at 70% | ~$3.5 million |
Reality differs: many subscriptions are discounted, gifted in bundles, or on other tiers, and the figure excludes sponsorships and other income. For Mafiathon 2, Yahoo Tech reported an estimated $3.6 million in subscription revenue, a model-based estimate rather than a disclosed number.
Why the Model Works
Attention as an asset
Cenat is the most-followed Twitch streamer, with about 21 million followers, according to Wikipedia. He began streaming on Twitch in February 2021 after moving from YouTube.
Community ownership
Subscribers are not passive; they help set the stream’s length. That participation turns a purchase into an identity.
Event scarcity
Mafiathon happens rarely, so each edition is treated as a cultural moment rather than routine content.
Records as marketing
Every new record generates press coverage that serves as free advertising for the next event.
The Risks Behind the Records
- Concentration risk. One person is the product. Health, burnout, or a platform ban would hit income directly. Cenat was temporarily suspended from Twitch in April 2023 (Wikipedia).
- Platform dependence. Twitch controls the revenue split, rules, and discoverability.
- Subscriber decay. Subathon spikes fade; subscribers often lapse after the event. As of January 6, 2026, Cenat’s channel was listed at about 1.11 million all-time peak subscribers (Wikipedia list), a record, but not a baseline.
- Competition. Streamers such as Jynxzi, IShowSpeed, and others continue to compete for the same audience.
What Marketers and Creators Can Learn
- Design participation, not just content. Let the audience affect the outcome.
- Make events rare and recognizable.
- Use guests as distribution, not just entertainment.
- Diversify income across subscriptions, brand deals, and owned products.
- Treat records as campaigns, with a clear narrative arc.
Frequently Asked Questions
How many subscribers does Kai Cenat have?
He passed 1,000,000 active subscribers on September 28, 2025, the first on Twitch to do so (Influencer Marketing Hub).
How much did Mafiathon make?
Mafiathon 2 was estimated at about $3.6 million in subscription revenue, per Yahoo Tech; official figures were not disclosed.
What is a subathon?
A livestream where each new subscription adds time to the broadcast.
How much does Twitch take from subscriptions?
Reported at 30% to 50%, depending on the streamer’s agreement.
Is Kai Cenat the biggest streamer?
He is described as the most-subscribed and most-followed Twitch streamer as of 2026 (Wikipedia).
Kai Cenat did not just build an audience. He built a machine that converts attention into a countdown clock, and then sold the countdown.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Asset Managment companies
MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion
The Monetary Authority of Singapore (MAS) has appointed five asset managers — Amundi, Franklin Templeton, HSBC Asset Management, M&G Investments and Natixis Investment Managers — under the third batch of its Equity Market Development Programme (EQDP), deploying a further S$1.45 billion into Singapore’s equity market.
The announcement, made by Minister for National Development and MAS Deputy Chairman Chee Hong Tat at the SuperReturn Asia conference on 29 September 2026, takes total EQDP allocations to S$5.4 billion across 14 managers — 83% of the programme’s expanded S$6.5 billion war chest, following its top-up at Budget 2026.
Alongside the appointments, MAS committed S$20 million from the Financial Sector Development Fund to a new GEMS Market Making Grant aimed at tightening bid-ask spreads in roughly 80 small and mid-cap stocks outside the Straits Times Index.
What is the EQDP? A quick recap
The EQDP was launched in February 2025 as a flagship demand-side measure of the Equities Market Review Group, which MAS convened in August 2024 to revive the Singapore Exchange (SGX). Its twin objectives: develop Singapore’s local fund management industry, and channel sustained institutional capital into Singapore-listed equities — including cornerstone participation in IPOs.
EQDP deployment: the full picture so far
Table
| Batch | Date | Managers | Allocation |
|---|---|---|---|
| Batch 1 | July 2025 | Avanda Investment Management, Fullerton Fund Management, JPMorgan Asset Management | S$1.1 billion |
| Batch 2 | November 2025 | Amova Asset Management, AR Capital, BlackRock, Eastspring Investments, Lion Global Investors, Manulife Investment Management | S$2.85 billion |
| Batch 3 | September 2026 | Amundi, Franklin Templeton, HSBC Asset Management, M&G Investments, Natixis Investment Managers | S$1.45 billion |
| Total | 14 managers | S$5.4 billion |
The third batch brings a notably more international flavour than earlier rounds. In his SuperReturn Asia speech, Chee said these managers “bring with them global distribution networks, sources of capital, and expertise that strengthen the depth and dynamism of our public markets” — meaning EQDP money is now explicitly designed to pull in foreign capital alongside domestic allocations.
S$20 million GEMS Market Making Grant: liquidity for the “missing middle”
The second announcement targets a chronic weakness of the SGX: thin trading in its small and mid-cap segment. The new GEMS Market Making Grant will:
- Fund appointed market makers providing liquidity for an initial group of around 80 eligible stocks outside the STI, plus newly listed counters
- Run until 31 December 2028
- Aim for tighter bid-ask spreads, lower execution costs and stronger price discovery
- Review and expand the eligible list regularly
Chee described the target as the “middle segment” — stocks with sufficient trading activity to benefit from market-making support, but not the large, liquid STI constituents. Early signs suggest the broader reform push is working: average daily turnover in Q3 2025 rose 16% year-on-year to S$1.53 billion, the highest since Q1 2021, with IPO fundraising topping S$2 billion, according to MAS data cited by The Straits Times.
The bigger play: anchoring S$7 trillion of asset management in Singapore
Tuesday’s announcements were bookended by measures targeting Singapore’s asset management industry, which now oversees close to S$7 trillion across more than 1,300 managers — growing 7.5% annually over the past five years, per MAS’s August 2026 package:
- Investment Management Track under the ONE Pass (from late January 2027, with the Ministry of Manpower) — applicants can meet the S$30,000 qualifying salary through a minimum S$15,000 fixed monthly salary plus variable, performance-linked components, reflecting industry compensation norms. Further details are expected at Budget 2027.
- Tax exemption for profit-related returns from fund management services to qualifying funds, effective from Year of Assessment 2027.
- A new MAS Hedge Fund Investment Programme to anchor leading hedge fund managers and their ecosystems (prime brokerages, ancillary services) in Singapore.
On licensing, Chee revealed MAS has received more than 500 fund management licence applications over the past three years, with a median approval time of 4.5 months in Q2 2026 — and the fastest approved in just 12 weeks — while pledging to streamline further without lowering standards.
What happens next?
- Batch 4: MAS is reviewing proposals now and expects to announce the next group of EQDP managers in 2027 — S$1.1 billion of the programme remains unallocated.
- Budget 2027: Details of the ONE Pass Investment Management Track, tax exemption and hedge fund programme.
- Market structure reforms: The SGX-Nasdaq dual listing bridge, reduced board lot sizes and the modernised post-trade custody model round out the Review Group’s implementation agenda.
Frequently Asked Questions
Which five asset managers were appointed in the third EQDP batch?
Amundi, Franklin Templeton, HSBC Asset Management, M&G Investments and Natixis Investment Managers, sharing S$1.45 billion.
How much of the EQDP has been allocated?
S$5.4 billion of S$6.5 billion across 14 managers in three batches. A fourth batch is under review for announcement in 2027.
What is the GEMS Market Making Grant?
A S$20 million grant (until end-2028) funding market makers in roughly 80 non-STI small and mid-cap stocks to narrow spreads and improve liquidity.
Can retail investors benefit?
Indirectly — tighter spreads and better price discovery lower trading costs for everyone, and EQDP managers’ funds may include counters retail investors already own.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025