
FED
US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

A US government bond can change the required return on a Pakistani investment without a single dollar physically crossing the border. The link runs through a basic idea: when a benchmark asset yields more, investors demand a stronger reason to take additional currency, liquidity and credit risks elsewhere.
The yield on the US 10-year Treasury stood near 5.00% on October 23, 2026, after reaching about 5.24% on October 9, according to historical Treasury-yield data. The user-friendly phrase above 5% should therefore be treated as a description of much of October, not a guaranteed quote for every moment of the latest trading day.
A bond yield is not a savings-account rate
A government-bond yield is the return implied by its market price and promised cash flows, assuming the relevant payment and holding assumptions. When investors sell an existing fixed-coupon bond and its price falls, its yield typically rises. That inverse relationship is central to interpreting the US Treasury market.
The 10-year yield reflects a mixture of expected short-term policy rates, expected inflation and a term premium for holding longer-dated debt. It can fall even while central-bank inflation concerns persist, for example if growth fears rise or investor demand for safe securities strengthens. Reading any single yield move as a pure Fed forecast is a mistake.
Four ways it reaches Pakistan
1. Dollar funding becomes a tougher benchmark. Investors weighing dollar-denominated assets may compare emerging-market returns with those available in US government debt. Pakistani external bonds must compensate for additional sovereign and market risk, although observed spreads change independently of benchmark yields.
2. Currency calculations shift. A domestic bond offering a high rupee yield can still disappoint a foreign investor if depreciation erodes converted returns. For Pakistani investors with future dollar obligations, currency exposure is similarly relevant.
3. Valuations face a higher discount rate. Equity valuations are sensitive to the interest rate used to discount expected future earnings. Companies promising distant profits may be more exposed than businesses generating cash immediately, but there is no perfect sector rule.
4. Sovereign refinancing risk draws scrutiny. Global debt investors assess not only current yields but also how costly it will be for governments to refinance existing obligations. Local T-bills and PIBs are nevertheless priced mainly by Pakistan-specific inflation, liquidity, central-bank policy and credit conditions; US yields do not mechanically set auction cutoffs.
The price-risk example
Imagine a fixed-coupon bond with a duration of seven years. A one-percentage-point increase in yields would imply an approximate 7% price decline, all else equal, using the basic duration approximation. That is not a prediction and not an exact valuation; convexity, yield-curve changes and cash-flow structure matter. It illustrates why holding a bond fund is different from locking in a bank deposit.
Duration risk also works in reverse: bond prices can rise when market yields fall. An investor buying only because the quoted coupon looks attractive may discover later that the resale price has moved against them.
What the latest global backdrop adds
The Federal Reserve raised its policy range to 3.75%–4.00% in September, amid persistent inflation concerns. At the same time, oil-market instability has made imported inflation a more acute concern for Pakistan. The IMF’s October World Economic Outlook forecasts 3.1% world growth for 2026 and highlights downside risks from conflict and financing strains.
This combination means bond yields may be high for reasons that are not benign. A superficially attractive yield could reflect inflation anxiety, fiscal uncertainty or a global risk premium. Investors need to ask why the yield is high, not just how high it is.
A useful comparison table
| Asset | Return quoted in | Main extra risk to examine |
|---|---|---|
| US 10-year Treasury | USD | Duration, inflation, reinvestment |
| Pakistan T-bill | PKR | Domestic rate/inflation, reinvestment |
| Pakistan Investment Bond | PKR | Duration, inflation, liquidity |
| Pakistan dollar bond | USD | Sovereign credit spread, liquidity, duration |
| PSX equity | PKR | Earnings, valuation, currency and market risk |
Currency hedging is not a free lunch
A Pakistani saver comparing foreign-currency investments with domestic government paper must think about more than headline yield. Converting rupees to dollars and back can involve spreads, banking charges, legal requirements and foreign-exchange movement. A hedging instrument, where available and suitable, usually embeds a cost related to interest-rate differences and market conditions. It cannot simply erase currency risk without consequence.
Tax treatment also matters. A quoted yield before withholding tax, custody expense or fund fees is not comparable with an after-tax return from another product. Similarly, a dollar asset can generate a positive dollar return but a different return in rupees. The investor should calculate both if future expenses are split between currencies.
For institutional portfolios, bond duration and liquidity become central. A long-maturity bond may have an attractive yield to maturity but be unsuitable for liabilities due next month. For individuals, the ability to meet an emergency expense without selling at a loss may be worth more than an extra percentage point of advertised return.
The sound comparison is liability-matched, not headline-driven: decide when the money is needed, in what currency and how much market-price movement is tolerable before selecting an asset.
Does a 5% US yield mean Pakistan must offer 5% plus a fixed margin?
No. Each instrument differs in currency, maturity, credit, liquidity and taxation; spreads vary with markets and policy.
Are US Treasuries risk-free?
They are commonly treated as a benchmark for dollar credit risk, but their market prices are not risk-free. Inflation and interest-rate changes can erode purchasing power and resale value.
What should a Pakistani retail investor do first?
List liabilities by currency and timing, then compare instruments on an after-tax, after-inflation and liquidity-adjusted basis. Seek licensed guidance where suitable.
The takeaway: a 5% US benchmark changes the world’s price of patience. Pakistani investors should respond by measuring real cash flows and risks, not by chasing whichever country advertises the biggest nominal yield.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The Federal Reserve’s next interest-rate decision is scheduled for October 28, 2026, at the conclusion of a two-day Federal Open Market Committee meeting. For investors in Karachi, New York or Kuala Lumpur, the question is bigger than whether the Fed raises rates by another quarter point. It is whether persistent inflation and an energy shock will keep global financing conditions restrictive for longer.
The Federal Reserve’s September 16 statement confirmed a 25-basis-point increase in the federal funds target range to 3.75%–4.00%. The official October calendar fixes the next announcement for Wednesday, October 28. Predictions about the decision remain predictions until the statement is published.
Why the market cannot simply assume a hold
The Fed faces two forces pulling in different directions. A resilient US economy can withstand tighter financial conditions better than a slowing one, while high energy prices can feed inflation expectations. At the same time, tightening further risks increasing pressure on rate-sensitive sectors and debt-servicing costs. The September meeting minutes describe concern about elevated inflation and the geopolitical backdrop.
Traders often express their expectations through futures pricing, but a specific percentage quoted earlier in October may no longer be representative on October 25. A responsible preview should avoid presenting an old implied probability as a live market estimate. The announcement, accompanying statement and press conference deserve more attention than any one probability screen.
The three policy scenarios
Hold, with a hawkish message. The Fed leaves its target at 3.75%–4.00% but stresses persistent inflation. Treasury yields and the dollar could remain firm if investors infer that further increases are possible. A hold is not necessarily dovish.
Another 25-basis-point rise. A new increase could push short-term dollar funding costs higher, depending on whether it is already priced in. For emerging markets, this may sharpen competition for capital and raise the hurdle rate for risky assets.
Hold, with a softer outlook. If the language signals growing confidence on inflation, longer yields might ease and investors could reassess the attractiveness of emerging-market equities and bonds. Any such response would also depend on earnings, geopolitics and risk appetite.
How the Fed reaches the Pakistan Stock Exchange
The direct transmission is limited by Pakistan’s domestic policy and market structure, but there are real channels. The first is the US dollar: a stronger dollar can raise the local price of imports and influence emerging-market currency expectations. The second is global yields: investors compare returns across sovereign debt markets and require compensation for currency and credit risks. The third is equity valuation: higher discount rates can reduce the present value of future corporate earnings, particularly for expensive growth assets.
For Pakistan, imported energy complicates that picture. If a Fed hike reflects sticky US inflation linked to oil, local investors must evaluate both international monetary tightening and Pakistan’s own fuel-import exposure. The World Bank’s Pakistan Development Update reports improving macroeconomic conditions but also acknowledges conflict-related pressure.
Bonds versus stocks: the difference matters
Pakistan Treasury bills and investment bonds primarily respond to domestic rates, inflation expectations, liquidity and sovereign risk. Their yields need not mirror US Treasuries day for day. PSX sectors also differ: banks, exporters, highly leveraged firms and energy producers can react quite differently to the same exchange-rate or interest-rate surprise.
A simplistic Fed hikes, PSX falls formula misses positioning. Prices often move on the gap between expectations and the actual decision. Even a rate hike can coincide with a stock rally if the market expected a larger move or welcomes clarity.
A practical announcement-day checklist
| Watch | Why |
|---|---|
| Fed funds target range | Immediate policy decision |
| Statement language on inflation | Signal for coming meetings |
| Treasury yield reaction | Changing dollar discount rates |
| Dollar index and EM currencies | Cross-border risk sentiment |
| Brent crude | Separate but powerful inflation channel |
| Pakistan KIBOR, rupee and SBP communications | Local transmission |
The IMF’s October outlook cautions that energy importers outside the AI investment value chain have a difficult growth outlook. This makes risk diversification and the distinction between nominal yields and real returns especially relevant.
Why the press conference may matter more than the quarter-point move
Central-bank announcements bundle several messages. A policy-rate decision tells markets what the committee did today. The statement signals which risks officials emphasise. The chair’s subsequent explanations can change expectations about the next several meetings. Traders may initially react to the rate itself, then reverse direction as they digest the path implied by the language.
For emerging-market investors, that distinction is crucial. A 25-basis-point increase accompanied by confidence that inflation pressure is subsiding may prove less restrictive for global risk appetite than an unchanged rate accompanied by warnings of more tightening. The yield curve, dollar and market-implied path are useful contemporaneous checks, although each has competing drivers.
Pakistan-based investors should also consider market hours. US decisions may arrive after domestic exchanges have closed, while other Asian markets trade the following session. A next-day index move can reflect overnight global earnings or geopolitical events as well as the Fed. Attribution requires comparing the timing of all material news.
For a rigorous post-meeting update, include the exact target range, vote, key wording changes and a timestamped Treasury yield. Replace the scenarios with the actual decision rather than leaving the preview to masquerade as a live result.
When will the Fed decision be released?
The Fed lists the October 27–28 meeting and a 2 p.m. Eastern announcement on October 28. Verify time conversion and possible schedule changes before publishing a live ticker.
Is a rate hike guaranteed?
No. September’s action and October’s risks do not predetermine the committee’s vote.
Should Pakistani investors sell stocks because of the Fed?
There is no universal answer. Investment time horizon, portfolio concentration, company balance sheets and currency exposure matter more than a one-day headline.
Bottom line: October 28 is a test of the Fed’s inflation tolerance. For Pakistan, the most important signal will be how the decision reshapes the dollar, energy costs and global demand for emerging-market risk—not the label hike or hold alone.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
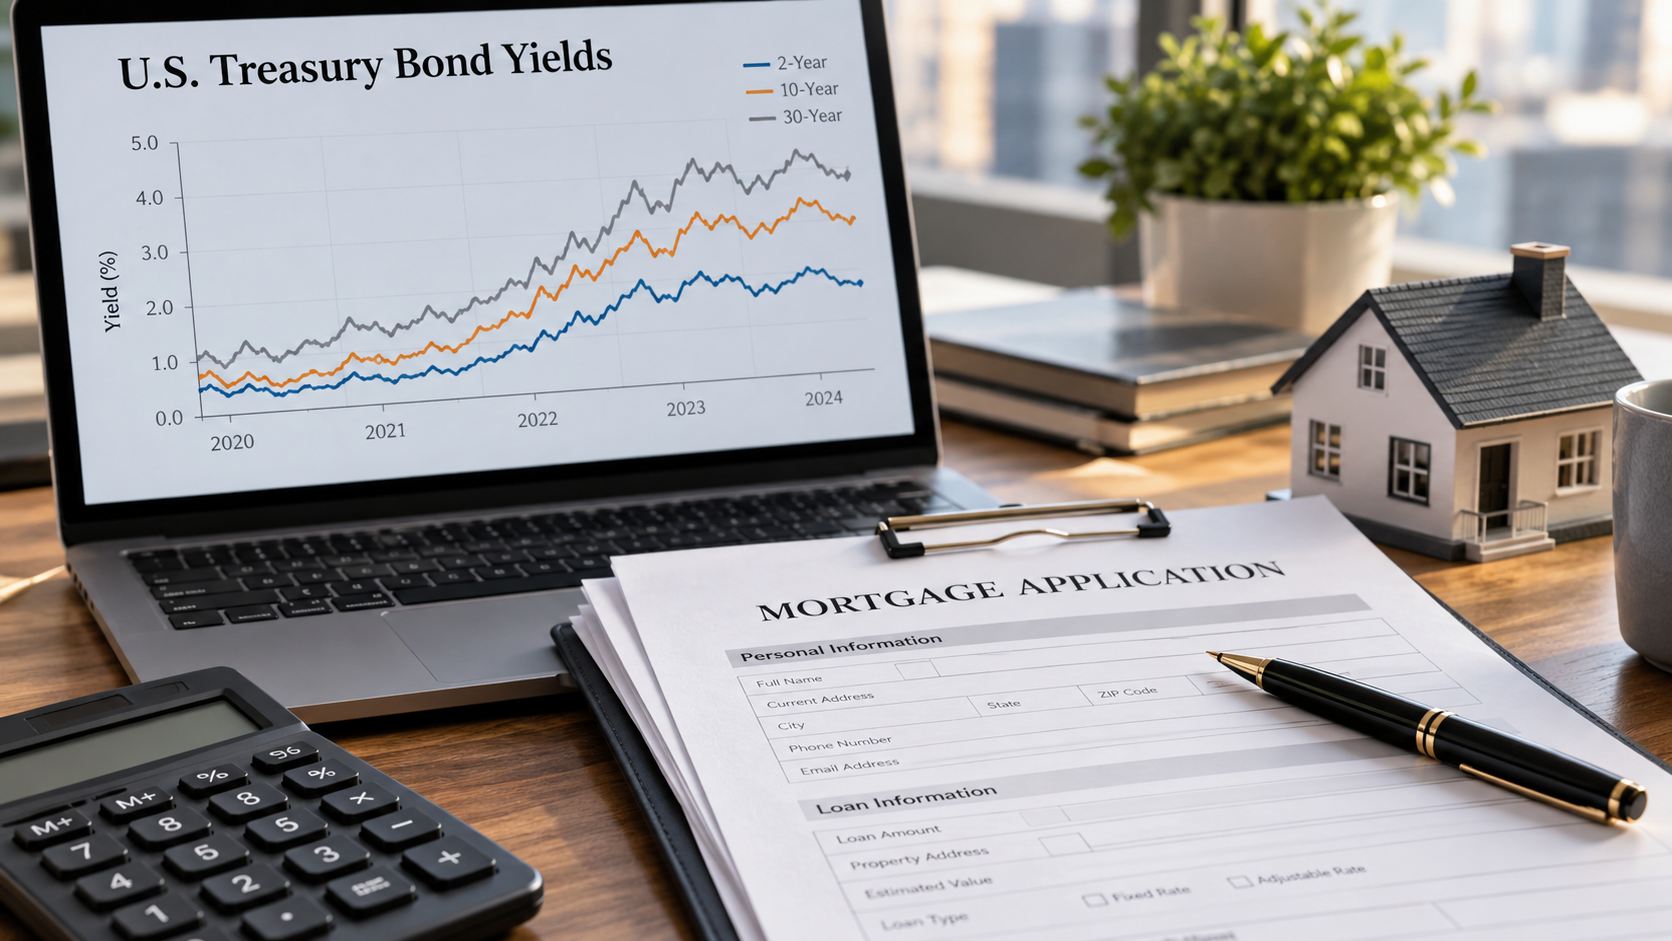
Long-term Treasury yields are the price signal linking government borrowing, mortgages, growth-stock valuations and the return available on safer assets. Reuters has highlighted an unusual 2026 divergence: shares near highs while longer-term bond yields have climbed. A bond yield is not the same as the Federal Reserve policy rate, and a large move in either can affect people differently depending on whether they borrow, save or invest. Sources: Reuters bond market analysis and Reuters market breadth.
The important context competitors can overlook
Bond prices generally fall when market yields rise. That inverse relationship explains why holders of long-duration bond funds can suffer losses even as the yields offered to new buyers become more attractive. Mortgage rates also reflect lending spreads, credit risk and other factors, so a single Treasury number cannot predict a specific home-loan offer. Companies with distant expected cash flows may be particularly sensitive to higher discount rates. For primary-source checks and current reporting, see Reuters bond market analysis and Investor.gov. The key distinction is translate bond math into household decisions.
Long-term Treasury yields connect bond markets to household borrowing and asset values. Higher yields can benefit new savers while hurting some borrowers and existing bondholders. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
Compare yields at consistent maturities rather than mixing two-year and ten-year readings. A homebuyer should assess monthly payment affordability at an actual lender quote. A saver choosing between a short-term bill and a long-term fund should consider liquidity needs and interest-rate risk. For an investor, the useful question is what rate assumptions are embedded in a company valuation, not whether “6%” makes a dramatic headline.
A simple rate-shock example
Imagine an existing long-duration bond fund whose duration is eight years. A simplified duration approximation suggests a one-percentage-point increase in yield could mean about an 8% price decline, before convexity, income and other effects. This is illustrative, not a forecast for a named fund. A short-term Treasury instrument with far lower duration usually reacts less to the same yield shock.
That distinction makes a practical difference for readers considering an emergency fund versus retirement money they can invest for a decade. The current market narrative described by Reuters should prompt a discussion of time horizon, not a blanket instruction to abandon bonds.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Are higher Treasury yields always bad?
No. New fixed-income savers may earn more, while existing long-duration bond prices can decline.
Does the Fed set the ten-year Treasury yield?
No. It influences conditions, but market expectations and term premiums also matter.
Why the ten-year yield influences everyday borrowing
The 10-year U.S. Treasury yield is an important benchmark for longer-term financing because it reflects the return investors require to hold government debt with that maturity. Mortgage rates do not equal the 10-year yield, but lenders consider Treasury markets, mortgage-backed securities, credit risk, servicing costs and competition when setting offers. If investors demand a higher return across long-term bonds, mortgage borrowing can become more expensive even without an immediate increase in the Federal Reserve’s short-term policy rate.
Suppose a buyer finances $300,000 over 30 years with a fixed-rate mortgage. At an illustrative 6% annual interest rate, principal and interest are roughly $1,799 per month; at 7%, they are roughly $1,996. The difference of about $197 per month excludes taxes, insurance, fees and other ownership costs. It demonstrates why a change in borrowing conditions can outweigh a modest change in a home’s asking price. Real quotes depend on the borrower’s circumstances and market conditions, not merely the Treasury yield reported in a news article.
Why bond prices and bond yields move in opposite directions
A conventional fixed-coupon bond promises specified payments. When newly issued securities offer higher yields, an existing bond with a lower coupon generally must trade at a lower price to attract buyers. The opposite happens when market yields fall. Duration measures a bond’s sensitivity to interest-rate changes. As an approximate illustration, a portfolio with an effective duration of seven years could lose about 7% in price if relevant yields rise by one percentage point, before other effects. The relationship is approximate and can vary with convexity, changing spreads and portfolio holdings.
For savers, a higher yield can be welcome if they are buying newly issued securities and can hold them under suitable circumstances. For owners of existing long-duration bonds, the same move can produce mark-to-market losses. Investors seeking near-term stability should understand the distinction between a bond’s redemption terms and the market price they might receive if they must sell before maturity. Credit risk also differs between Treasury securities and corporate or municipal bonds.
The yield curve tells a story, but not one prediction
The yield curve plots interest rates across maturities. Its shape can reflect expectations for growth, inflation, monetary policy and compensation for holding longer bonds. An inverted curve has often been studied as a recession signal, yet neither inversion nor steepening guarantees a specific economic outcome. A steepening curve may arise because investors expect stronger future activity, higher inflation or greater long-term borrowing supply. The underlying cause matters more than the shape alone.
Distinguish nominal yields from real yields after expected inflation. If a nominal Treasury yield rises because inflation expectations rise, the investor’s purchasing-power return may not improve nearly as much as the headline suggests. Treasury Inflation-Protected Securities provide another reference point, though their market prices and practical suitability also require care. Useful analysis compares inflation expectations, real yields and nominal yields rather than describing all higher rates as a sign of healthy growth.
A decision framework for households
Borrowers should compare multiple complete loan offers, including interest rate, annual percentage rate, closing costs and applicable points. A lower headline rate with very large upfront fees may not be cheaper for someone planning to move or refinance. Depositors should distinguish variable savings-account APYs from yields locked by certain fixed-term products. Bond-fund investors should review duration, credit quality, expenses and possible withdrawals. Stock investors should consider how higher discount rates affect the value assigned to future profits, particularly where profits are expected many years ahead.
No single financial product becomes universally best because yields reach a round number. A retiree seeking predictable cash flow, a first-time homebuyer and a technology-company investor face different tradeoffs. Their financial decisions are better guided by time horizon, liquidity and risk tolerance than by a prediction of where the yield will be next week.
The key variables to monitor
For a coherent market story, compare the 2-year and 10-year Treasury yields, current Fed communications, the latest inflation data and changes in bond-market liquidity. Track the time at which each observation was made. Also distinguish a policy announcement from a market-implied forecast; futures pricing can change significantly with new information. Where a report cites a historic high, specify the exact maturity and comparison period. Generalized phrases such as “rates hit their highest level” can conceal important differences.
Relevant data and explanations are available from the U.S. Treasury and Federal Reserve. Those are appropriate baselines for an article readers may use to understand mortgages, bonds and savings decisions.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
It is tempting to talk about “interest rates” as though there is one number moving the entire U.S. economy. In reality, the short-term policy rate set by the Federal Reserve and the market yield on a 10-year Treasury note can tell different stories. The first is a direct monetary-policy instrument. The second embeds investor expectations for future short-term rates, inflation, bond supply, economic uncertainty and compensation for holding long-duration debt.
In September, the Fed raised its target for the federal funds rate by a quarter percentage point to 3.75%–4.00%. That is a significant factual anchor for the October debate: the central bank was not simply holding policy unchanged. The official statement described resilient domestic activity and inflation that remained elevated. Federal Reserve September 16 statement.
On October 9, reporting placed the 10-year Treasury yield near 5.24% after a volatile week. For readers, the gap between these rates is more informative than either number alone. Associated Press market close.
Why a 10-year yield can exceed the policy rate
A bond yield reflects the price investors demand for a stream of future cash flows. When the price of an existing bond falls, its yield generally rises. Long-term yields may remain high even if investors think the Fed could eventually reduce short-term rates, because long-term inflation uncertainty, federal debt supply or term premiums may still justify additional compensation.
The opposite also happens. A central bank can raise its short-term rate while long-dated yields decline if bond investors believe tighter policy will bring inflation under control or weaken future growth. Therefore “the Fed hiked so all Treasury yields must rise” is an inaccurate shortcut. Market analysts need a time series and an explanation of which component changed.
What the Fed’s official data can—and cannot—say
The Federal Reserve publishes daily selected interest-rate data through its H.15 release. During the October 8 session, the listed 10-year constant-maturity Treasury rate was 5.22%; the later Friday market closing figures cited in news coverage were slightly different, reflecting observation timing and methodology. Federal Reserve H.15.
These values should not be presented as interchangeable real-time quotes. A daily Treasury constant-maturity series, an intraday cash-bond trade and a news-service closing yield can differ. High-quality financial reporting labels the instrument, source and timestamp. A difference of a few basis points can be normal even when all figures are independently correct.
The Fed also publishes economic projections and participant expectations. The September summary included elevated inflation projections, but these are not commitments by the committee or a binding timetable. Federal Reserve September economic projections.
Where SGOV fits into the story
The iShares 0–3 Month Treasury Bond ETF (SGOV) holds a portfolio of very short-dated U.S. Treasury securities. It is often discussed as an alternative to leaving uninvested money in a brokerage account because it seeks to earn short-term Treasury income with limited interest-rate sensitivity. The fund does not behave like a long-duration Treasury ETF, whose price can swing substantially when longer yields move.
As of the October 5 information visible on the issuer’s product page, SGOV displayed a 3.71% 30-day SEC yield and 0.09% expense ratio. These are dated metrics, not a promise of the rate a future investor will receive. Its income distribution changes with short-term market conditions, and the ETF can trade at a small premium or discount to net asset value. iShares SGOV facts.
Low duration is not the same as zero risk
Short-dated Treasury securities generally expose investors to far less interest-rate sensitivity than 10- or 30-year bonds, but several risks remain. ETF shares change price, market spreads exist, distributions fluctuate and inflation can erode the purchasing power of returns. A fund also differs legally from a bank deposit. Investors should not describe an ETF as FDIC-insured cash or assume the absence of a meaningful mark-to-market loss under every conceivable market condition.
Currency matters for international readers as well. A Pakistan-based investor considering a U.S. dollar Treasury product faces exchange-rate movements in addition to the securities’ dollar returns. Taxes, account access, fund structure and local regulation can also alter the practical outcome. A quoted U.S. dollar yield is not equivalent to a guaranteed local-currency gain.
Why different Treasury ETFs can move in opposite directions
Compare short Treasury bills with bonds maturing in 10 or more years. When yields rise, the longer bond’s existing fixed payments become less attractive, and its market price generally declines more because its cash flows are further in the future. This sensitivity is measured by duration, a useful—but approximate—way to compare rate risk.
A fund holding nearly maturing bills repeatedly reinvests at new yields, so changes in short rates can affect future income relatively quickly. A long Treasury fund can experience substantial price moves before the income change becomes visible. This is why an investor discussing “bond yields” should specify maturity and exposure rather than treating all fixed-income products as interchangeable.
The 2026 inflation question behind higher yields
Inflation changes the value of fixed payments in the future. Investors demand compensation when they think price growth will remain elevated or volatile. Energy shocks can reinforce this concern because higher diesel, shipping and manufacturing costs may work through supply chains. Yet not every energy-price move becomes a lasting increase in core inflation; monetary policy depends on broader evidence and expectations.
A September Fed projection showed its participants anticipating inflation remaining above target in the near term. Federal Reserve projections. Readers should not interpret that as an assurance of more rate increases. The future policy path depends on economic developments and FOMC decisions. Market-implied odds, if used, require a verified source and a timestamp.
Why stock investors care about the yield curve
When safer government securities offer competitive yields, investors may require greater potential returns to justify risky assets. Higher discount rates also reduce the present value of distant projected corporate profits. Those effects can be especially relevant for high-growth businesses whose market valuations depend on results many years away. Companies that refinance debt frequently can also feel direct interest expense pressure.
The relationship is not perfectly mechanical. Stocks may rise alongside Treasury yields when both are reacting to stronger expected growth. A central bank may tighten because corporate activity is resilient rather than because the economy is on the verge of recession. To interpret the market, ask whether the yield move reflects optimism about growth, inflation anxiety, government borrowing or a genuine change in policy expectations.
What to monitor in the coming weeks
Watch the next inflation reports, FOMC communications, Treasury auctions, 2-year and 10-year yields, investment-grade credit spreads and market pricing of future policy moves. Pair those signals with earnings releases, business investment and labor-market data. One factor can offset another: stronger earnings may cushion stocks against higher yields, while slowing sales and rising borrowing costs together can create more serious stress.
Readers should also check short-term fund yields directly with issuers because SGOV’s distribution profile can change without the fund’s ticker changing. Avoid stale “best cash yield” headlines. A product’s risk, liquidity, expenses and tax characteristics matter as much as a single yield snapshot.
The central takeaway
The Fed’s September hike and the elevated 10-year yield show that the cost of money remains a defining market issue in October 2026. SGOV illustrates why short-term Treasury products attract attention when yields are meaningful, but the fund cannot reveal a guaranteed future Fed decision. The sound approach is to distinguish policy rates, market yields and investment-product mechanics—then update each using its own official data source.
Frequently asked questions
What is the Fed’s target range in October 2026?
Following the September 16 decision, the target range was 3.75%–4.00% as of this article’s reporting cutoff.
Is the 10-year Treasury yield the Fed rate?
No. The 10-year yield is determined in bond markets and reflects several expectations beyond current policy.
Does SGOV have a fixed guaranteed yield?
No. Its published 30-day SEC yield is a dated standardized measure, not a guarantee of future distributions.
Why do long-term Treasury bonds fall when yields rise?
Existing fixed coupons become less attractive relative to newer higher-yielding securities, so market prices typically decline.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Energy Security Is the New Economic Security

Can Global Tourism Survive Geopolitical Shocks?

Global Maritime Hegemony: How China Secured Over 81% of All New Shipbuilding Orders

The Coming Battle Over AI, Jobs and Wages

Why Developing Economies Face a Sharper Inflation Problem

The New Geography of Trade: Are Supply Chains Coming Home?

Is AI Saving Global Growth or Creating the Next Bubble?

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025