
Interest Rate Policy
SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

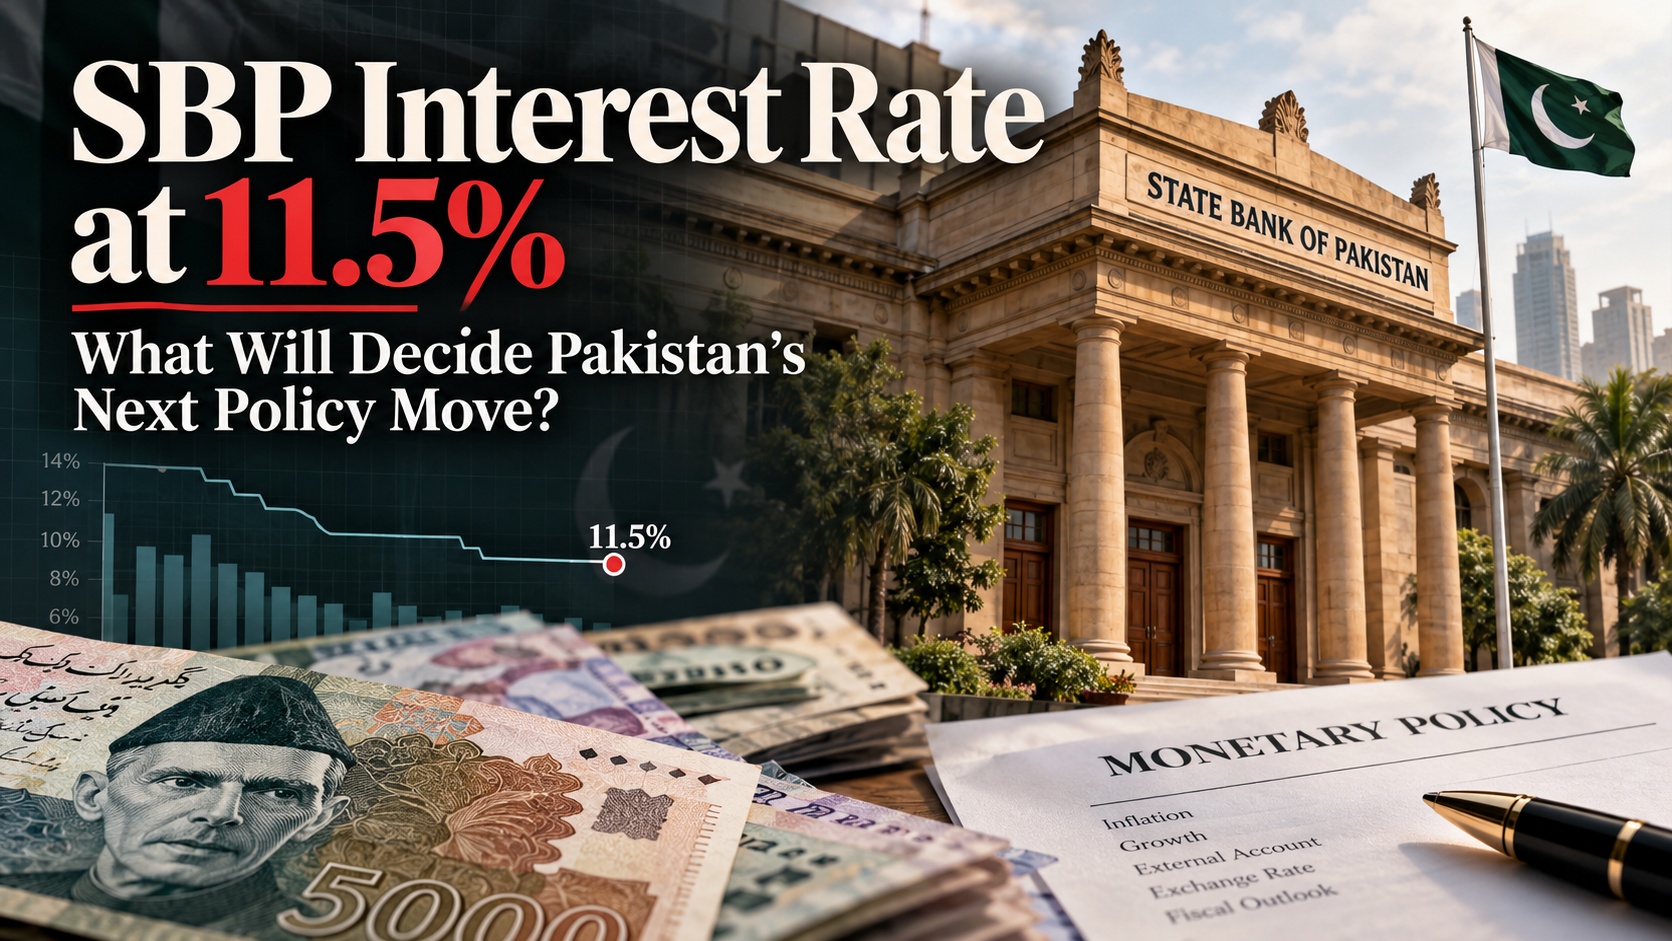
Pakistan’s interest-rate debate has shifted. After an extended period in which households and businesses waited for borrowing costs to fall, a more uncomfortable question is taking shape: how much room does the State Bank of Pakistan have to support growth when energy prices and global borrowing costs are rising?
The State Bank of Pakistan confirmed that its Monetary Policy Committee kept the policy rate at 11.5% on September 14, 2026. That is the established starting point, not a prediction about what the bank will do next. The next decision will depend on inflation momentum, exchange-rate stability, government financing requirements and the external account—not simply on whether consumers would prefer cheaper loans.
The oil-price complication
Pakistan imports a substantial share of the energy it consumes. Oil therefore affects more than petrol-station signs: it changes transport costs, power generation expenses, industrial margins and the amount of foreign currency importers must buy. International Brent crude was above $100 per barrel in October, a sharp risk for an import-dependent economy. The World Bank’s October Pakistan Development Update says stabilization has advanced despite the Middle East conflict, but that is not the same as immunity to another energy shock.
The key for policy is persistence. A one-week spike in crude can be absorbed partly by inventories and pricing lags. Several months of elevated crude can reach the consumer price index, import payments and inflation expectations. If households begin setting wages and prices around another round of cost increases, the central bank becomes less willing to ease.
Four signals worth watching before the next MPC
Headline versus core inflation. Headline inflation reflects food and fuel moves; core readings help judge whether price increases are spreading more widely. A calm headline number alongside rising core inflation is not an easy case for a rate cut.
The rupee and reserve buffers. An exchange-rate shock can raise the local-currency price of imported inputs even when foreign prices are unchanged. The sustainability of remittance inflows, export receipts and foreign financing matters as much as the spot exchange rate.
Market rates: KIBOR, T-bills and PIBs. KIBOR benchmarks bank lending. Treasury-bill auctions indicate near-term sovereign financing costs; longer-dated Pakistan Investment Bonds embed expectations about inflation, future rates and duration risk. These yields may move before the MPC changes its policy rate. None is a guaranteed predictor of a decision.
Growth and credit. A financing squeeze can delay inventories, construction, machinery purchases and hiring. Policymakers must balance these costs against the inflationary damage of lowering rates too soon. The World Bank reported real GDP growth of 3.7% for fiscal 2026, after 3.2% in fiscal 2025; that recovery raises the stakes of a policy mistake in either direction.
What an unchanged rate means on the ground
For a company with floating-rate debt, a policy-rate hold does not guarantee an unchanged interest bill. The actual loan may reprice from KIBOR plus a fixed spread, while repayment schedules and bank fees add complexity. Families considering mortgages should ask for an amortization table under several interest-rate scenarios instead of extrapolating from a single headline.
For savers, quoted deposit returns should be compared after tax, fees and inflation. A nominal return of 11% is not an 11% gain in purchasing power if living costs rise sharply. For government-bond buyers, a high coupon does not eliminate price risk: fixed-rate securities generally lose market value when yields rise.
Three plausible outcomes—not a false forecast
| Scenario | What would make it more plausible | Likely market response |
|---|---|---|
| Hold | Sticky inflation, expensive energy, manageable growth | Short-term yields may remain elevated; borrowers wait |
| Cut | Sustained disinflation, stable reserves and rupee, softer demand | Floating-rate financing could gradually become cheaper |
| Hike | Renewed imported inflation or currency instability | Higher financing cost, but stronger anti-inflation signal |
These are conditions, not assigned probabilities. An accurate forecast must be updated when fresh CPI, reserve, auction and external-account data arrive. The IMF’s October 2026 outlook expects global inflation of 4.7% in 2026, underscoring the difficult international setting.
Practical questions readers are asking
The policy transmission lag that forecasts overlook
A cut announced by the central bank would not instantly reset every Pakistani mortgage, business loan and deposit. Some contracts reprice periodically using an agreed KIBOR tenor; others remain fixed until a renewal date. Banks also consider liquidity and credit risk, which can prevent lending rates from falling as quickly as the benchmark. Borrowers should obtain a written repricing schedule rather than infer savings from the policy-rate headline alone.
Similarly, the MPC must interpret economic data that arrive with delays. A monthly inflation print may be affected by base effects—a comparison with unusually high or low prices one year earlier. Headline disinflation therefore does not necessarily mean that prices are falling, merely that they are increasing more slowly. For businesses, the distinction determines whether inventory and wage costs are genuinely easing.
The quality of the government’s financing programme also matters. If Treasury-bill auctions show that investors demand high returns, a monetary-policy easing cycle may not translate cleanly into cheaper public borrowing. Policymakers must evaluate expectations alongside the immediate inflation rate.
Editorial watchpoint: before describing any meeting as a turning point, publish the newest CPI release date, exchange-rate observation and actual T-bill auction cutoffs. Clear sourcing makes a forecast useful even when it proves wrong.
Is 11.5% the same as a bank’s loan rate?
No. It is the SBP policy rate. A specific loan can be priced using KIBOR, a spread, collateral risk and contractual terms.
Does a rate hold mean petrol and food prices will stop rising?
No. Monetary policy influences demand and financing conditions; it cannot directly reverse a supply shock, an oil-price increase or weather damage.
What should investors check first?
Compare the latest SBP statement, CPI releases, KIBOR quotations, recent T-bill auction results and the timing of the next official MPC announcement. Avoid treating a market rumour as a decision.
Bottom line: The next rate move is a contest between the need to protect a fragile recovery and the need to avoid imported inflation becoming embedded. For Pakistan, the path of oil, the rupee and inflation expectations matters more than any single commentator’s rate-cut call.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The Global Interest rates have great Importance in 2026 because global economic growth is becoming more uneven, capital is increasingly sensitive to financing costs, and investors must distinguish a convincing story from an investable price. This guide focuses on research methods and risks rather than predictions of guaranteed returns. The IMF October 2026 outlook projects 3.1% global growth and 4.7% inflation for 2026, while the IMF financial-stability assessment warns that market resilience coexists with important vulnerabilities.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind how global interest rates affect investments is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
Why policy rates affect ordinary households
Central banks influence short-term financing conditions through monetary policy, but retail deposit and lending rates do not adjust one-for-one. Banks account for liquidity, funding costs, credit risk and competition. A rising benchmark may improve yields on new deposits while increasing the repayment burden on floating-rate loans. Compare effective annual rates, not advertising slogans. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Bonds and the price-yield relationship
Existing fixed-rate bonds usually lose market value when comparable yields rise; their coupons are unchanged, but new bonds become more attractive. The longer the duration, the larger the approximate price sensitivity. A two-percentage-point yield jump has different implications for a one-year bill than for a long-duration bond fund. Credit quality also matters: a high quoted yield may compensate for meaningful default risk. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Stocks: discounted profits, uneven sector effects
Higher discount rates can reduce the present value of expected future profits, particularly for expensive long-duration growth companies. Yet banks may benefit from some rate changes, while heavily indebted businesses face refinancing pressure. No single rule predicts stock prices because earnings expectations, inflation and risk appetite move simultaneously. Compare valuations against sustainable rather than peak profits. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
The exchange-rate channel for Pakistan
Differences between global and Pakistani interest rates can influence capital flows and currency expectations, but the rupee also depends on trade, remittances, reserves and policy credibility. A stronger dollar can increase local-currency import and foreign-debt costs even when domestic prices seem stable. Investors should calculate returns in the currency in which future expenses will occur. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
A practical decision checklist
Separate emergency cash, short-term commitments and long-term investments. Match fixed-income maturity to spending needs; compare fixed versus floating loan terms; avoid funding speculative investments with expensive debt. Revisit assumptions when policy statements change, but resist making portfolio decisions from one central-bank headline. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Opinion
Federal Reserve Defies White House Pressure: Inside Trump’s Demand for Sub-1% Interest Rates After Historic 2026 Rate Hike
The Eccles Building in Washington, D.C., home to the Federal Reserve Board of Governors.
Executive Summary
- The Decision: The Federal Open Market Committee (FOMC) voted 12–0 to raise the benchmark federal funds rate by 25 basis points to a target range of 3.75%–4.00%—marking the central bank’s first rate increase in over three years.
- The Presidential Rebuttal: President Donald Trump posted a sharp criticism on Truth Social, declaring that U.S. borrowing costs should be “1%, or less,” asserting that America’s credit standing warrants the lowest interest rates in the world.
- The Fed’s Stance: Federal Reserve Chair Kevin Warsh defended the policy tightening as a “sober, serious, responsible decision,” pointing to stubborn inflation driven by elevated geopolitical energy shocks and structural supply-side pressures.
- Market Projection: The updated FOMC “dot plot” reveals that 16 out of 18 policymakers anticipate at least one additional rate increase before the end of 2026.
1. The Rate Hike: Why the FOMC Acted
In a move that surprised some dovish market participants, the Federal Open Market Committee unanimously voted to raise the target range for the federal funds rate by 25 basis points to 3.75%–4.00%. According to official reporting from Livemint Monetary Coverage, this decision represents the first upward adjustment in borrowing costs since mid-2023.
President Donald Trump has repeatedly called for aggressive monetary easing to stimulate domestic capital investment.
Speaking at a post-meeting press conference, Fed Chair Kevin Warsh emphasized that persistent inflationary pressures leave central bankers with little room to ease monetary policy. Recent Bureau of Labor Statistics readings showed underlying consumer price inflation hovering consistently above the Fed’s 2% annual target.
“The plain fact is that inflation is too high and has been for too long. Summer inflation readings do not tell me that underlying trends have improved sufficiently to pause our stabilization efforts.”
— Kevin Warsh, Chair of the Federal Reserve Board
Economic headwinds contributing to sticky inflation include:
- Geopolitical Energy Shocks: High global crude oil and liquefied natural gas (LNG) prices linked to Middle Eastern conflict zones.
- Tariff Impacts: Import duties continuing to feed into intermediate manufacturing costs.
- Capital Spending Inflows: Heavy corporate investment in artificial intelligence infrastructure maintaining high credit demand across domestic capital markets.
2. Trump’s Escalating Criticism & The “1% or Less” Target
Within hours of the Fed’s announcement, President Trump issued a strongly worded response on social media, criticizing the FOMC’s policy direction and renewing his demand for radical rate reductions as reported by Economic Times.
Key Quotations from President Trump
- On Rates: “Interest Rates in the United States should be 1%, or less, because we are the Best Credit in the World — BY FAR.”
- On Speed: “LOWER THE INTEREST RATES FOR THE UNITED STATES OF AMERICA, AND FAST!”
- On Trade Deficits: “The word ‘Deficit’ is nothing more than a fancy word for LOSS. We are ‘carrying’ almost every country in the World, and that cannot go on any longer.”
Trump linked monetary policy directly to international trade balances, arguing that higher U.S. interest rates place domestic manufacturers at a competitive disadvantage against foreign trading partners with lower cost-of-capital environments.
3. White House Growth Mandate vs. Federal Reserve Inflation Control
The debate over the ideal path for interest rates reflects fundamentally different perspectives on macroeconomic priorities:
| Dimension | White House Economic Stance | Federal Reserve Policy Framework |
| Primary Goal | Maximize GDP expansion & capital investment | Maintain price stability (2% inflation target) & employment |
| Target Rate Range | 1.00% or lower (Aggressive Easing) | 3.75% – 4.00% (Restrictive / Neutral) |
| Inflation Assessment | Supply-side deregulation & tariffs offset price risks | Sticky Core CPI requires tight borrowing conditions |
| View on Trade Deficits | High rates strengthen dollar, worsening trade deficit | Trade balances are driven by savings-investment balances, not policy rates |
| Rate Outlook (2026) | Immediate multi-percentage-point cuts | Dot plot signals 1 additional 25 bps hike |
Institutional policy research published by the Center for American Progress underscores that central bank independence is crucial for maintaining long-term bond market stability and preventing inflation expectations from becoming unanchored.
4. Market Reaction & Consumer Economic Impact
Financial markets responded with elevated volatility following the policy decision and subsequent presidential statements, as detailed in market summaries by TradingView Financial Markets.
Consumer Borrowing Costs
- Mortgage Rates: The 30-year fixed mortgage rate remains anchored above 6.5%–7.0%, dampening residential housing turnover.
- Credit Cards & Consumer Loans: Average commercial credit card APRs remain near multi-decade highs above 21%, increasing debt service obligations for revolving balance holders.
- Savings Yields: High-yield savings accounts (HYSAs) and short-term U.S. Treasury bills continue offering cash holders yields between 3.5% and 4.0%.
Institutional Analysis on Rate Easing
In a comprehensive macroeconomic review, researchers at the Washington Center for Equitable Growth note that cutting the federal funds rate down to 1% in an economy operating near full employment would risk re-igniting double-digit wage-price spirals last seen in the late 1970s. Economists stress that rate cuts of that magnitude are historically reserved for deep recessions or systemic financial crises.
5. Looking Ahead: What to Watch at the Next FOMC Meeting
As the central bank approaches its upcoming policy gathering, three indicators will determine whether Chair Warsh and the FOMC proceed with another rate increase:
- Monthly Consumer Price Index (CPI) & PCE Deflator: Any persistent month-over-month increases above 0.3% in core indexes will lock in another 25 bps hike.
- Labor Market Tightness: Unemployment claims and non-farm payroll growth will reveal whether elevated borrowing costs are successfully cooling labor demand.
- Treasury Yield Dynamics: The spread between short-term 2-year Treasury notes and 10-year Treasury bonds will signal bond market expectations regarding future rate policy and economic growth.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Interest Rate Policy
How Rising Interest Rates Impact Gig Economy Apps: DoorDash, Uber, and Urban Services
The Fed hiked to 3.75%-4% with gas above $4. See how rates, fuel and consumer spending transmit into DoorDash unit economics and gig platform margins.The standard model says rising rates hurt gig platforms because they are long-duration growth assets and because discretionary spending contracts. Both halves of that model are currently being contradicted by the data.
Executive Summary / Key Takeaways
- The Federal Reserve raised rates to 3.75%–4.00% on 16 September 2026, with 16 of 18 FOMC participants projecting at least one more hike this year.
- The transmission into gig platforms runs through three channels, and only one is the discount rate: consumer discretionary spending, courier input costs, and the cost of capital for long-duration investment.
- DoorDash guided take rate to decline in Q4 2026 on seasonal Dasher cost increases, an insurance step-up and higher winter delivery complexity — margin compression that is structural, not cyclical.
- The company absorbed a gross cost of over $50 million for a Dasher gas relief programme in Q2 2026, a direct macro-to-margin transfer with national pump prices above $4 a gallon.
- The counterintuitive finding: DashPass subscriptions grew more in twelve months than the prior twenty-four combined, suggesting convenience platforms may function as household cost-management tools rather than pure discretionary spend.
The Fed raised its target range by a quarter point to 3.75%–4.00% on 16 September 2026, describing economic activity as expanding at a solid pace with domestic spending resilient, productivity growth strong and capital investment robust, while noting that inflation remains elevated. Sixteen of eighteen participants expect at least one further increase before year-end.
Yet on the day of the hike, the Dow fell more than 600 points while the Nasdaq finished close to flat, with the damage concentrated in cyclicals, transport and energy-exposed names — J.B. Hunt Transport fell 12.64% on an earnings warning citing rising operating costs — according to market coverage. The rate-sensitive damage landed on physical logistics, not on technology platforms.
For gig economy analysis, that is the tell. The binding constraint in 2026 is not the discount rate. It is the cost of moving things.
2. Core Analysis: Three Transmission Channels
2.1 Channel one — courier input costs
This is the dominant channel and the most direct.
DoorDash anticipated the gross cost of its Dasher gas relief programme at over $50 million for Q2 2026, expecting to fund it at least partly by adjusting investment elsewhere, per its Q1 disclosure. That is a macro variable landing straight on the income statement: the national average for regular gasoline was $4.329 a gallon on 15 September 2026, against $3.14 a year earlier.
The seasonal effect compounds it. Management guided take rate to remain flattish in Q3 before declining in Q4 due to seasonal increases in Dasher costs, an insurance step-up and higher delivery complexity during winter months, per the earnings call summary.
Translated for investors: courier supply is price-elastic, weather-sensitive and fuel-cost-exposed, and the platform absorbs the gap rather than fully passing it to consumers. Rising rates do not cause this. Rising energy prices do — and the same energy shock is what drove the Fed to hike, which is why the two appear correlated.
2.2 Channel two — consumer discretionary spending
Here the data contradicts the thesis.
In Q2 2026, DoorDash grew total orders 27% year-on-year to 970 million, Marketplace GOV 36% to $33.1 billion and revenue 36% to $4.45 billion — 17%, 23% and 24% respectively excluding the Deliveroo acquisition, per company results. US paid DashPass members increased more in the twelve months through Q2 2026 than in the previous twenty-four months combined.
Subscription penetration accelerating during a period of elevated food and fuel inflation is not the behaviour of a discretionary category under pressure. Management’s stated logic is that membership reduces transactional friction through affordability, driving retention and engagement. The plausible reading is that for a meaningful cohort, a delivery subscription functions as a cost-management instrument — a fixed fee that caps variable delivery expense — rather than as a luxury.
2.3 Channel three — cost of capital for long-duration bets
| Metric | Q2 2026 | Signal |
|---|---|---|
| Adjusted EBITDA | $914m (+40%) | Core profitability strong |
| GAAP net income | $200m (-30%) | Legal and regulatory expense drag |
| Operating cash flow | $944m (from $504m) | Self-funding capacity improving |
| 2026 stock comp | $1.2–1.3bn | Dilution cost of talent retention |
| 2026 D&A | $1.1–1.2bn | Including ~$450m acquired intangibles |
With operating cash flow at $944 million in a single quarter, DoorDash is largely self-funding its autonomy, AI and infrastructure investment. Higher rates raise the opportunity cost of that spending but do not gate it. The platforms that higher rates genuinely constrain are the sub-scale, cash-burning ones — and the rate environment therefore accelerates consolidation toward the profitable incumbents rather than damaging them.
3. Structural Drivers and Competitor Gaps
The correlation most analyses get backwards. Fed funds and gig platform margins are correlated in 2026, but not causally in the direction usually assumed. Both are downstream of the same energy shock: elevated crude drove gasoline up 27.4% year-on-year in the August CPI, which drove headline inflation, which drove the Fed to hike, and independently drove courier fuel costs up. Modelling gig margins as a function of the policy rate will produce a fitted relationship with no predictive validity once energy normalises.
Autonomy is a rate-environment bet. DoorDash Dot is expected to reach high single-digit penetration in test markets by year-end, scaling from Phoenix. If seasonal courier cost inflation is the recurring drag on Q4 take rate, autonomous capacity attacks that line directly. Higher-for-longer rates raise the hurdle rate on that investment while simultaneously increasing its payoff — which is why the company is accelerating rather than deferring it.
The regulatory tail risk is larger than the rate risk. DoorDash’s filing names an unresolved California Employment Development Department audit over payroll-tax liabilities tied to Dasher classification, with an amount accrued and resolution uncertain, per the 10-Q. GAAP net income fell 30% partly on higher legal and regulatory expenses. A classification ruling would reprice unit economics sector-wide in a way no plausible rate path would.
Consolidation is the visible second-order effect. DoorDash completed its Deliveroo acquisition in October 2025 for $3.72 billion. In a higher-rate environment, platforms with positive operating cash flow acquire those without it. The gig sector’s competitive structure in 2027 will be shaped more by that dynamic than by demand.
4. Key Implications for Stakeholders
Tech equity investors. Strip the acquisition before modelling — 24% organic revenue growth against 36% headline is the number the multiple should reflect. Then treat Q4 take rate against guidance as the cleanest available test of whether courier cost inflation is cyclical or permanent.
Consumer analysts. Subscription growth during an inflation squeeze is the most interesting datapoint in the sector. If delivery membership is behaving as a household hedge rather than a luxury, the standard discretionary-spending framework misclassifies the entire category.
Gig workers. Fuel relief programmes are discretionary platform spending, funded by reallocating investment elsewhere. They are not contractual, and they are most likely to be trimmed precisely when platform margins compress — which is Q4.
Policy analysts. The combination of an energy shock, a tightening cycle and an unresolved worker-classification case creates unusual conditions for gig regulation. Rising courier costs strengthen the platforms’ argument for flexibility and the workers’ argument for guaranteed earnings simultaneously.
5. Frequently Asked Questions
Q1: Do higher interest rates hurt gig economy apps?
Less directly than assumed. The larger 2026 pressure is energy costs feeding into courier pay — DoorDash spent over $50 million gross on Dasher gas relief in one quarter — while its core profitability and subscription growth both accelerated despite tightening.
Q2: Why is DoorDash’s take rate expected to fall in Q4?
Management cited seasonal increases in Dasher costs, an insurance step-up and higher delivery complexity during winter months. Courier supply is weather- and price-sensitive, and the platform absorbs the cost gap rather than fully passing it to consumers.
Q3: Is consumer spending on delivery falling with rates?
Not on current data. DoorDash grew orders 27% year-on-year to 970 million in Q2 2026, and US paid DashPass members grew more in twelve months than in the prior twenty-four combined.
Q4: What is the biggest risk to gig platform economics right now?
The unresolved California worker-classification audit, which carries payroll-tax implications that would affect the entire sector’s cost structure — a larger exposure than any plausible interest-rate path.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Energy Security Is the New Economic Security

Can Global Tourism Survive Geopolitical Shocks?

Global Maritime Hegemony: How China Secured Over 81% of All New Shipbuilding Orders

The Coming Battle Over AI, Jobs and Wages

Why Developing Economies Face a Sharper Inflation Problem

The New Geography of Trade: Are Supply Chains Coming Home?

Is AI Saving Global Growth or Creating the Next Bubble?

Global Banking Trends 2026: Digital Banks, AI and Compliance

Gold vs US Dollar vs Bitcoin in 2026: Inflation Hedge Compared

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

World’s Largest Economies: Ranking the Top Global Powers

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025