
Banks
2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

The IRS has published its 2027 inflation adjustments. Here are the brackets, deductions and the crucial difference between marginal and effective tax rates.
The IRS has published its 2027 inflation adjustments. Here are the brackets, deductions and crucial difference between marginal and effective tax rates. This analysis draws on primary documents and contemporaneous reports available on November 6, 2026; subsequent market movements or policy announcements may change the outlook.
The Internal Revenue Service announced tax-year 2027 inflation adjustments on November 5, 2026. Most of these changes affect income earned during 2027 and tax returns generally filed in 2028—not the 2026 return filed in 2027. The top marginal individual rate remains 37%. The standard deduction rises to $16,600 for single filers, $33,200 for married couples filing jointly and $24,925 for heads of household.
A tax bracket is a rate applied to a layer of taxable income, not to every dollar someone earns. Confusing marginal and effective rates is among the most common errors in public explanations of U.S. federal income taxes.
The 2027 rates for single filers
For single taxpayers the IRS schedule applies a 10% rate up to $12,800 of taxable income; 12% above $12,800 through $52,025; 22% above $52,025 through $109,125; 24% above $109,125 through $208,325; 32% above $208,325 through $264,550; 35% above $264,550 through $661,375; and 37% above $661,375. These are taxable-income thresholds, not gross salary levels.
The determination of taxable income can involve the standard deduction or itemized deductions, as well as other adjustments and credits. An employer’s paycheck withholding is not the same as final federal income-tax liability.
A worked marginal-rate example
Consider an illustrative single filer with $80,000 of taxable income in 2027, after deductions and adjustments. The first $12,800 is taxed at 10%, generating $1,280. The next $39,225—from $12,800 to $52,025—is taxed at 12%, generating $4,707. The remaining $27,975—from $52,025 to $80,000—is taxed at 22%, generating $6,154.50. Total regular federal income tax before credits or other applicable adjustments would be $12,141.50 under this simplified bracket-only example.
The marginal rate is 22%, but the example’s effective rate on taxable income is approximately 15.18%. Effective tax as a share of gross income would be different. These calculations exclude special taxes, credits, alternative minimum tax issues and state taxes.
Other changes that matter
The IRS announcement lists a 2027 maximum child tax credit of $2,300, with up to $1,800 refundable subject to eligibility. The annual gift exclusion rises to $20,000, and the basic estate-tax exclusion increases to $15.48 million. These figures have different functions; an exclusion is not the same as a refundable credit.
The IRS also increased various limits associated with the earned income tax credit, medical savings arrangements and employer-sponsored benefits. Readers should consult the relevant official provisions, because maximum amounts can be subject to income phaseouts and eligibility rules.
Why inflation indexing is not a tax cut for everyone
Indexing tax brackets helps prevent nominal wage increases from pushing income into higher marginal brackets purely because of inflation. But individual outcomes vary with earnings, deductions, household changes and credits. A taxpayer whose nominal wages rise faster than indexed thresholds can still owe more; a taxpayer with changing family circumstances may face a different result.
Do not use tax brackets alone to estimate withholding changes or an expected refund. Tax software and professional advisers incorporate the broader return, including employment income, dependents, capital gains and relevant state provisions. This article offers general information, not personalised tax advice.
What a closer look at the source record shows
The available record supports a useful separation between confirmed developments and interpretation. The first column below identifies the type of evidence; the second explains the analytical use, not an independently measured market statistic.
| Research focus | How it informs this story |
|---|---|
| Confirmed evidence | IRS official 2027 adjustments |
| Interpretive opportunity | Full thresholds and worked example |
| Secondary question | Correct tax-year distinction |
| Next verification | Check any later legislation, correction or filing instructions before tax advice or publication. |
The research priority is relevance rather than sheer citation volume. Repeated references to the same press release do not represent independent confirmation, and authoritative data can support a narrower claim than an ambitious headline suggests. Wherever a numerical fact is used, the source date and stated coverage should travel with it.
How to interpret the evidence without overclaiming
A bracket is applied in layers. Progressive rates apply to successive ranges of taxable income. The highest applicable marginal rate is not applied to a taxpayer’s entire income. In this article’s subject—2027 tax brackets—that distinction prevents superficially precise figures from becoming misleading conclusions. A credible account should explain exactly which evidence supports each inference and what would change the analysis.
Timing and filing status matter. A taxpayer’s filing category, deductions and the distinction between earning year and filing year can change the calculation materially. Check any later legislation, correction or filing instructions before tax advice or publication. These checks are important because individual data points can be correct while the story assembled from them is incomplete.
Three specific tests make the coverage stronger:
- Full thresholds and worked example. Ask what the underlying observation actually measures, which population or companies it covers, and how recent it is. A relevant primary document outweighs a popular unsourced claim.
- Correct tax-year distinction. Compare plausible explanations and resist attributing every market or policy movement to one event. When an observed change has several possible causes, explain which are supported and which remain hypotheses.
- Marginal versus effective rate. Describe what new fact would falsify the prevailing interpretation. Reporting that cannot be revised in the face of new evidence is advocacy, not analysis.
How three taxpayers could experience the same 2027 brackets differently
A single filer who takes the standard deduction. The $16,600 standard deduction reduces income considered for the regular federal income-tax calculation, subject to applicable rules. A worker’s gross salary is not automatically equal to taxable income. A promotion that raises taxable income into a higher bracket would normally expose only the additional portion to that higher marginal rate.
A married couple filing jointly. The joint standard deduction is $33,200, and the bracket thresholds differ from those for single filers. Combining two incomes affects the applicable brackets, but child-related credits, itemised deductions, investment income and other household facts can change the final bill. The official IRS schedule is the starting point, not a personalised return.
A household with credits or irregular income. A freelancer with large quarterly variations, a family eligible for dependent-related benefits or an investor realising capital gains cannot calculate final tax from the ordinary wage-income brackets alone. Tax liability can be affected by estimated payments, special capital-gain rates and credit phaseouts. The correct tax year also matters: the 2027 schedule generally belongs on returns filed in 2028.
A practical research checklist
A reader evaluating this issue should first open the primary sources linked in the article and check their publication dates. Next, identify the specific claim being tested, its units and its geographic or institutional scope. Then compare that evidence with at least one independent account, asking whether the sources are reporting the same underlying data or repeating one another. Finally, distinguish a dated observation from a prediction and note the developments that would demand an update.
For a working editorial desk, this sequence is equally important. A clearly dated article can remain valuable after prices or politics change if its explanations endure and its volatile numbers are identified as snapshots. An article that quietly presents yesterday’s quote as today’s fact, by contrast, loses credibility even when the broader argument is sensible.
Questions readers are asking
When are 2027 tax brackets used?
They apply to tax year 2027, with returns generally filed in 2028.
What is the 2027 standard deduction for a single filer?
$16,600, according to the IRS announcement.
Does moving into the 22% bracket tax all income at 22%?
No. Only the taxable income within that bracket is taxed at 22% under the progressive schedule.
What is the top federal individual rate in 2027?
The top marginal rate remains 37%, with IRS-published thresholds depending on filing status.
The judgement
The IRS has published its 2027 inflation adjustments. Here are the brackets, deductions and crucial difference between marginal and effective tax rates. The most responsible conclusion is conditional: Check any later legislation, correction or filing instructions before tax advice or publication. The argument should evolve when new source material is published, rather than being defended simply because it made a compelling headline on November 6. For readers, the value is a clearer distinction among what has already happened, what remains uncertain and what developments would actually change the decision.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Spot gold traded around $4,020 to $4,035 an ounce on Thursday 29 October, down roughly 1% on the day, and moved briefly close to $3,983 later, according to Kitco’s live quote. Reuters reported bullion on track for a second straight monthly decline. The metal remains roughly 27-28% below its 2026 record of about $5,600, set in late January.
In Pakistan, one local market report put gold at about Rs423,436 per tola on 26 October. Tola prices also depend on the dollar-rupee rate and local premiums, so check the day’s rate.
Why Gold Is Under Pressure
A hawkish Fed hold. The Fed held rates at 3.75%-4.00% on 28 October, but Governor Lisa Cook and Cleveland Fed President Beth Hammack voted for a hike. On Thursday, Reuters reported markets pricing about a 90% chance of a December hike on the CME FedWatch tool.
Strong US data. Q3 GDP grew 3.4% and core PCE inflation rose to 2.5%, per Kitco, reinforcing the case for restrictive policy. The 10-year yield stayed near 5%.
Why this matters for gold. Gold pays no interest, so higher yields raise the opportunity cost of holding it, and a firmer dollar makes it costlier for non-US buyers. TDS strategist Bart Melek called the Fed’s stance a hawkish pause and expects gold to stay vulnerable in a $3,900-$4,250 range; Sucden Financial warned of a possible fall to $3,900.
Spot gold fell to about $4,020-4,035 an ounce on 29 October 2026 as strong US growth (3.4% in Q3) and higher core inflation kept a December Fed rate hike in play. Higher rates raise the opportunity cost of holding gold, which pays no interest.
What Could Push Gold Back Up
- A softer Fed: TDS expects the Fed to eventually turn toward its employment mandate, which could lift gold, though not immediately.
- Geopolitical shocks: Reuters quoted an analyst noting markets are wary of another spike in tensions after the 3 November US midterms.
- Oil, a double-edged factor: an oil spike raises inflation fears and hawkish expectations, which hurts gold in the short run. The same analyst said gold could post a fresh yearly low if oil revisits $120 and above.
Technical Levels Traders Watch
Kitco’s technical commentary points to $4,000 as a pivot, with downside objectives near $4,024 on a break lower and $3,986 beyond, and resistance in the $4,084-$4,146 zone. Treat these as trader reference points, not predictions.
What It Means for Pakistani Buyers
- Dollar-rupee matters as much as the gold price. If the rupee weakens, local gold can stay firm even when dollar gold falls.
- Time horizon. Analysts quoted expect volatility in a range over the coming weeks; long-term holders and short-term traders face different risks.
- Compare with alternatives. With the SBP policy rate at 12%, yield-bearing assets compete with gold for savings.
- Mind premiums and purity. Jewellery carries making charges; bars and coins track the spot price more closely.
Gold is stuck between a hawkish Fed and geopolitical risk. The $4,000 level has become the focus, and the next US inflation data and Iran’s response on the Qatari deal are the nearest catalysts.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
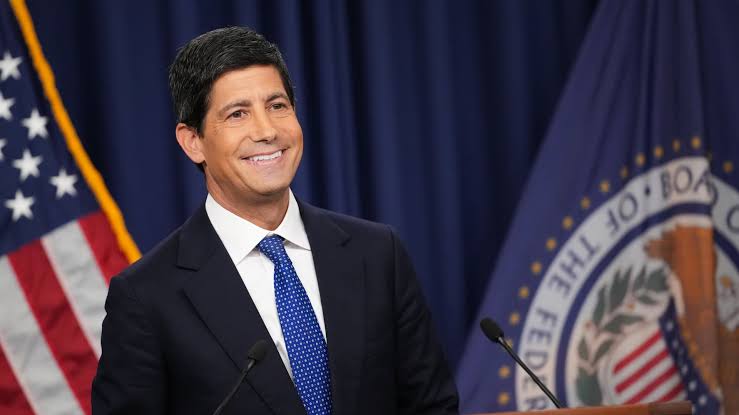
The Federal Open Market Committee left its target range unchanged at 3.75%-4.00% on Wednesday 28 October, according to Admiral Markets’ FOMC summary. The vote was 10-2. The two dissenters, Governor Lisa Cook and Cleveland Fed President Beth Hammack, wanted to raise rates by 25 basis points. A committee that is split towards tightening rather than easing is a notable shift in tone.
The statement pointed to strong economic growth and elevated inflation. Chair Kevin Warsh said the committee held to gather more information, and he floated cutting the number of rate decisions from eight to six a year, per Trading Economics.
Why the Dissents Matter More Than the Hold
A hold was expected. The significance is the direction of dissent. Two voters wanting a hike signals that part of the committee sees inflation risks, aggravated by energy prices from the Middle East conflict, as large enough to justify tightening now. FXStreet and MUFG Research both framed the outcome as a hold with a hawkish edge, with the committee not explicitly committing to further hikes but not ruling them out.
MUFG’s read is that a December hike remains live, with more of another move priced by March. On Thursday, Reuters reported the CME FedWatch tool showing roughly a 90% chance of a December hike. That pricing, rather than the unchanged rate, is what moved currencies and precious metals around the decision.
The Inflation Problem Is an Energy Problem
The Fed’s challenge is that the inflation pressure is not purely domestic demand. Brent oil has climbed to around $115, a six-month high, as attacks on tankers and Saudi infrastructure keep supply worries alive, and Iran is weighing a Qatari draft deal that could ease or inflame the market depending on the answer. Central banks cannot lower oil prices with interest rates, but they can stop an energy shock from becoming embedded in wages and expectations, which is the argument the hawkish dissenters appear to be making.
Market Reaction
Crude oil barely moved on the decision, according to FXStreet, as traders waited on Iran’s response to the Qatari proposal. Gold slid toward $4,000 an ounce on Thursday after US Q3 growth printed at 3.4% and core PCE at 2.5%, per Kitco, with the 10-year yield near 5%.
What It Means Beyond the US
- Emerging markets: a Fed leaning hawkish tightens global financial conditions and raises the bar for easing elsewhere. Pakistan’s central bank raised its policy rate to 12% two days before the Fed meeting for domestic inflation reasons, but a firmer dollar adds pressure to the rupee.
- Gulf central banks: several Gulf central banks held rates after the decision, since their currencies are pegged to the dollar.
- Asia-Pacific: officials such as RBNZ’s governor have said another hike is plausible if inflation does not ease.
What to Watch Before December
- Inflation data: the next PCE and CPI prints will decide whether the dissenters gain allies.
- Oil: Iran’s reply on the Qatari draft, due by the end of the week, is the biggest swing factor. A deal would remove part of the hawks’ case; a breakdown would strengthen it.
- Chair Warsh’s messaging: his comments on the balance between AI-driven productivity and inflation risk.
- Labour market data ahead of the December meeting.
The Fed held, but the committee is no longer debating how fast to cut. It is debating whether to hike. Unless oil retreats, the December meeting is genuinely open.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
A US government bond can change the required return on a Pakistani investment without a single dollar physically crossing the border. The link runs through a basic idea: when a benchmark asset yields more, investors demand a stronger reason to take additional currency, liquidity and credit risks elsewhere.
The yield on the US 10-year Treasury stood near 5.00% on October 23, 2026, after reaching about 5.24% on October 9, according to historical Treasury-yield data. The user-friendly phrase above 5% should therefore be treated as a description of much of October, not a guaranteed quote for every moment of the latest trading day.
A bond yield is not a savings-account rate
A government-bond yield is the return implied by its market price and promised cash flows, assuming the relevant payment and holding assumptions. When investors sell an existing fixed-coupon bond and its price falls, its yield typically rises. That inverse relationship is central to interpreting the US Treasury market.
The 10-year yield reflects a mixture of expected short-term policy rates, expected inflation and a term premium for holding longer-dated debt. It can fall even while central-bank inflation concerns persist, for example if growth fears rise or investor demand for safe securities strengthens. Reading any single yield move as a pure Fed forecast is a mistake.
Four ways it reaches Pakistan
1. Dollar funding becomes a tougher benchmark. Investors weighing dollar-denominated assets may compare emerging-market returns with those available in US government debt. Pakistani external bonds must compensate for additional sovereign and market risk, although observed spreads change independently of benchmark yields.
2. Currency calculations shift. A domestic bond offering a high rupee yield can still disappoint a foreign investor if depreciation erodes converted returns. For Pakistani investors with future dollar obligations, currency exposure is similarly relevant.
3. Valuations face a higher discount rate. Equity valuations are sensitive to the interest rate used to discount expected future earnings. Companies promising distant profits may be more exposed than businesses generating cash immediately, but there is no perfect sector rule.
4. Sovereign refinancing risk draws scrutiny. Global debt investors assess not only current yields but also how costly it will be for governments to refinance existing obligations. Local T-bills and PIBs are nevertheless priced mainly by Pakistan-specific inflation, liquidity, central-bank policy and credit conditions; US yields do not mechanically set auction cutoffs.
The price-risk example
Imagine a fixed-coupon bond with a duration of seven years. A one-percentage-point increase in yields would imply an approximate 7% price decline, all else equal, using the basic duration approximation. That is not a prediction and not an exact valuation; convexity, yield-curve changes and cash-flow structure matter. It illustrates why holding a bond fund is different from locking in a bank deposit.
Duration risk also works in reverse: bond prices can rise when market yields fall. An investor buying only because the quoted coupon looks attractive may discover later that the resale price has moved against them.
What the latest global backdrop adds
The Federal Reserve raised its policy range to 3.75%–4.00% in September, amid persistent inflation concerns. At the same time, oil-market instability has made imported inflation a more acute concern for Pakistan. The IMF’s October World Economic Outlook forecasts 3.1% world growth for 2026 and highlights downside risks from conflict and financing strains.
This combination means bond yields may be high for reasons that are not benign. A superficially attractive yield could reflect inflation anxiety, fiscal uncertainty or a global risk premium. Investors need to ask why the yield is high, not just how high it is.
A useful comparison table
| Asset | Return quoted in | Main extra risk to examine |
|---|---|---|
| US 10-year Treasury | USD | Duration, inflation, reinvestment |
| Pakistan T-bill | PKR | Domestic rate/inflation, reinvestment |
| Pakistan Investment Bond | PKR | Duration, inflation, liquidity |
| Pakistan dollar bond | USD | Sovereign credit spread, liquidity, duration |
| PSX equity | PKR | Earnings, valuation, currency and market risk |
Currency hedging is not a free lunch
A Pakistani saver comparing foreign-currency investments with domestic government paper must think about more than headline yield. Converting rupees to dollars and back can involve spreads, banking charges, legal requirements and foreign-exchange movement. A hedging instrument, where available and suitable, usually embeds a cost related to interest-rate differences and market conditions. It cannot simply erase currency risk without consequence.
Tax treatment also matters. A quoted yield before withholding tax, custody expense or fund fees is not comparable with an after-tax return from another product. Similarly, a dollar asset can generate a positive dollar return but a different return in rupees. The investor should calculate both if future expenses are split between currencies.
For institutional portfolios, bond duration and liquidity become central. A long-maturity bond may have an attractive yield to maturity but be unsuitable for liabilities due next month. For individuals, the ability to meet an emergency expense without selling at a loss may be worth more than an extra percentage point of advertised return.
The sound comparison is liability-matched, not headline-driven: decide when the money is needed, in what currency and how much market-price movement is tolerable before selecting an asset.
Does a 5% US yield mean Pakistan must offer 5% plus a fixed margin?
No. Each instrument differs in currency, maturity, credit, liquidity and taxation; spreads vary with markets and policy.
Are US Treasuries risk-free?
They are commonly treated as a benchmark for dollar credit risk, but their market prices are not risk-free. Inflation and interest-rate changes can erode purchasing power and resale value.
What should a Pakistani retail investor do first?
List liabilities by currency and timing, then compare instruments on an after-tax, after-inflation and liquidity-adjusted basis. Seek licensed guidance where suitable.
The takeaway: a 5% US benchmark changes the world’s price of patience. Pakistani investors should respond by measuring real cash flows and risks, not by chasing whichever country advertises the biggest nominal yield.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

Australia’s AI-Driven Economic Strategy Is Redefining National Resilience

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

Democrats Won Congress. Can They Fix the U.S. Economy

Stock Market Crash 2026? What the November Rout Actually Tells Us

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

Asian Stock Markets: Why the AI Rout Is Dividing the Region

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Global Finance 2027: Debt, Inflation and AI Are Pulling the Economy Apart

Brian Kemp’s Georgia Legacy: Economic Growth, Elections and the Costs of His Policy Choices

Dow Futures vs Dow Jones: What E-mini Contracts Really Tell You Before Wall Street Opens

China Tape Maker Stock Debut: Crown New Materials Soared 787%

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

US–China Critical Minerals Competition: Why a Trade Deal Cannot Fix Every Supply Risk

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

SSI November 2026 Payment: Why Benefits Arrive October 30

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

Jeff Bezos Three-Day Workweek View: What He Really Said

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025