
Global Trade
Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Executive Summary
- Trade Truce Extension: Washington and Beijing extended the Busan economic truce by two months to January 10, 2027, establishing a bilateral Board of Trade mechanism with a $30 billion cap on tariff reductions for non-sensitive goods.
- Taiwan Policy Stance: President Xi Jinping pressed the U.S. administration to shift from “not supporting” to explicitly “opposing” Taiwan independence, while a U.S. $14 billion arms package to Taipei remains on hold.
- AI & Governance Divergence: Trump advocated for minimal federal AI regulation relying on existing legal channels, whereas Xi emphasized international norm-setting and human-controlled AI governance.
- Conflict Prevention: Both leaders highlighted shared WWII historical ties, but underlying systemic friction over technology controls and critical supply chains remains unhedged.
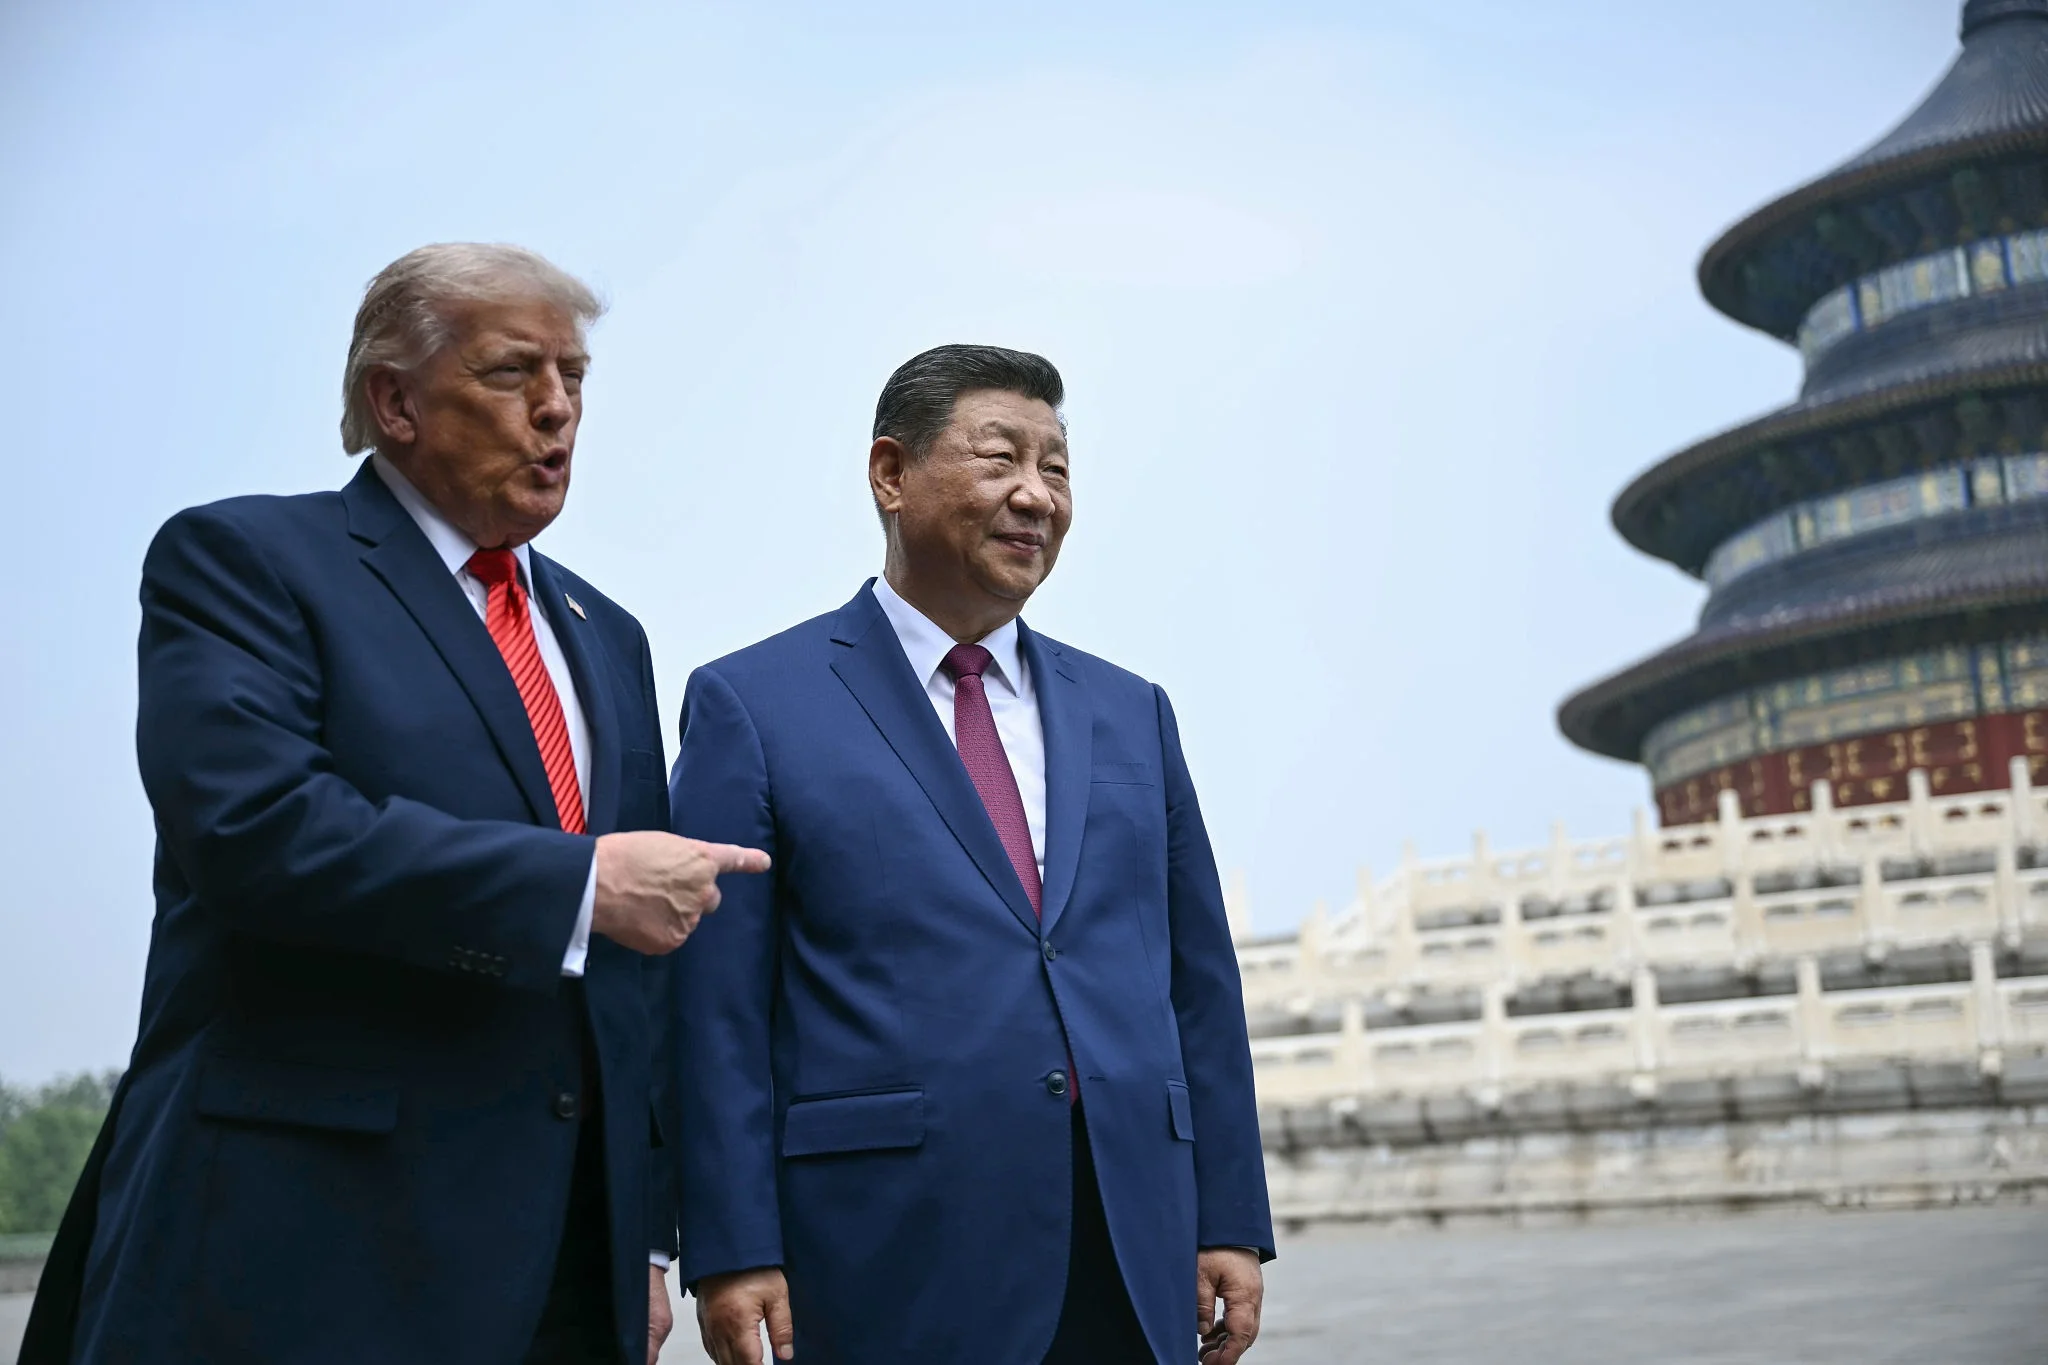
Presidents Xi Jinping and Donald Trump met in Washington, D.C., marking President Xi’s first official state visit to the United States in over a decade. The 43-hour diplomatic engagement combined high-profile ceremonial gestures with intense negotiations over economic policy, regional security, and emerging technologies.
1. Trade Deliverables & Managed Economic Detente
The core economic outcome of the summit was a mutual decision to extend the trade truce originating from the Busan agreements by an additional two months, pushing the negotiation window to January 10, 2027. According to analysis published by The Business Times, this temporal buffer buys critical space for both economies to formalize structured frameworks before political shifts take hold following the U.S. midterm elections.
Key Economic Components:
- Board of Trade Framework: Establishing a structured mechanism to oversee managed bilateral commerce.
- Tariff Cap Reductions: A planned mutual tariff reduction capped at US$30 billion per side, targeting non-sensitive consumer and industrial goods.
- Agricultural Commitments: China continues to meet its baseline commitments for purchasing 25 million metric tons of U.S. soybeans.
However, friction points persist below the surface. U.S. trade officials noted that Beijing remains behind on its broader pledge to purchase $17 billion in other U.S. agricultural exports. Furthermore, delivery quotas for critical rare-earth elements—essential for high-tech manufacturing—have fallen short of target allocations. As detailed by the Chicago Council on Global Affairs, reliance on personalistic leader-to-leader negotiations creates short-term pauses but leaves structural trade imbalances and supply chain dependencies unaddressed.
2. The Taiwan Question & Strategic Security
Diplomatic maneuvering over Taiwan represented the most sensitive geopolitical dynamic of the summit. President Xi reiterated Beijing’s core stance, urging Washington to handle the Taiwan issue with “extreme prudence” and asking the U.S. to actively oppose Taiwan independence rather than maintaining its traditional diplomatic posture of simply “not supporting” it.
Strategic assessments from the Institute for the Study of War indicate that Beijing views the current economic detente as a key window to influence U.S. security commitments in the Indo-Pacific. A planned U.S. $14 billion arms transfer package to Taiwan remains paused, delivering a tactical diplomatic win for Beijing ahead of upcoming multilateral regional gatherings.
3. Divergent Visions on AI Governance & High-Tech Competition
The summit exposed contrasting philosophies regarding the regulation of Artificial Intelligence and advanced computing capabilities. While both leaders acknowledged AI’s transformative influence on global power balances, their proposed paths forward reflect fundamental governance differences.
| Dimension | United States Stance | China Stance |
| Regulatory Model | Market-driven with minimal federal intervention; oversight through existing DOJ frameworks. | State-directed guardrails emphasizing central oversight and alignment with national strategy. |
| Global Governance | Defense of competitive edge and strict export controls on advanced hardware. | Multilateral norm-setting under international organizations (“AI for Good”). |
| Core Objective | Commercial freedom, innovation velocity, and technological superiority. | Human control, risk mitigation, and preventing technological decoupling. |
Reporting from The Federal highlighted that while Xi urged joint international responsibility to ensure AI remains under human control, the U.S. side favored preserving flexibility for domestic technological developers without introducing international regulatory mechanisms.
4. “Thucydides Trap” Avoidance & Strategic Guardrails
Throughout the summit, President Xi repeatedly warned against falling into the “Thucydides Trap”—the historical tendency toward conflict when a rising power challenges an established power. Calling for “constructive strategic stability,” Xi emphasized that global competition should resemble a “race of catching up with one another, not a wrestle in which one wins and the other loses.”
Institutional Takeaways:
- Regular Military Communications: Reaffirming bilateral crisis-prevention channels to prevent miscalculations in air and maritime corridors.
- Historical Commemoration: Leveraging shared World War II history during visits to national monuments to emphasize foundational ties.
- Corporate Engagement: Hosting state dinners with executive leadership to reinforce commercial interdependencies as a stabilizing buffer.
Strategic Outlook
While the 43-hour Washington summit succeeded in projecting stability and securing short-term economic extensions, fundamental strategic competition remains unresolved. The coming months will test whether temporary trade truces and managed tariff caps can withstand broader geopolitical rivalries in technology supply chains, semiconductor export policies, and Pacific security dynamics.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The IMF’s July 2026 update projects global growth of 3.0% for 2026 and 3.4% for 2027 — a modest slowdown from the 3.5% average of 2024–25, driven by the economic drag of the Middle East conflict being partly offset by an accelerating AI-driven technology cycle. In short: the world economy is being carried by one trade, and it is concentrated in a handful of companies.
That single sentence captures the defining tension of the 2026 economy. Two forces are pulling in opposite directions, and which one wins will determine whether this is remembered as the year markets shrugged off geopolitical risk, or the year they didn’t see the correction coming.
The IMF’s Divergent World
According to the IMF’s World Economic Outlook Update, the growth slowdown is not evenly distributed. Economies deeply integrated into the AI and technology value chain — chiefly the United States and parts of Asia — are absorbing the benefits of the technology boom, while energy-importing and conflict-adjacent economies are absorbing most of the damage. That divergence has been the throughline of every IMF release this year: the April 2026 edition, published as the Middle East conflict first erupted, had cut its forecast to 3.1% for 2026 under a “reference forecast” that assumed the war would stay limited in scope and duration, while warning that a longer or broader conflict — or a reassessment of AI-driven productivity expectations — could meaningfully weaken growth.
For content targeting “IMF reports” and “world economy” search intent, the practical takeaway is this: growth forecasts have been revised four times in twelve months, each revision hinging on two swing factors — the war’s duration and the durability of the AI capital-spending cycle. Anyone publishing on this topic needs to track both, because either one turning could flip the entire growth story.
Wall Street’s AI Concentration Problem
Featured Snippet Target: Three companies — Alphabet, Amazon, and Meta — are now expected to drive roughly 70% of the S&P 500’s 2026 earnings growth, according to Charles Schwab’s market analysis, with combined 2026 capital expenditure guidance exceeding $500 billion. That concentration means the index’s headline diversification is largely cosmetic; its performance now rides on whether a handful of hyperscalers convert AI spending into earnings.
This is the risk hiding inside every “stock market today” headline. Reuters reported the S&P 500 climbing to a record high in early January 2026, powered by gains in Nvidia and Alphabet, with one Tulsa-based fund manager summing up the prevailing mood as a repeat of the prior year’s approach — buy the AI leaders and hold. Since then, hyperscaler capital spending has only accelerated: Alphabet, Amazon, and Microsoft each posted capex increases of well over 25% year-on-year in recent quarters, and combined hyperscaler AI spending commitments for 2026 have topped $700 billion, according to reporting relayed through Yahoo Finance’s technology coverage.
That spending is no longer being funded purely out of free cash flow. A growing share is debt-financed — Macquarie’s Investment Strategy Insights noted that consensus hyperscaler capex estimates for FY26–FY28 were revised up from roughly $2.5 trillion to $2.8 trillion during the reporting season, with gross debt issuance expected to peak near $460 billion in FY28, or about a third of total capex. Analysts have started describing this shift as a change in market character altogether — a move from an era where buybacks reliably supported share prices to one where capital expenditure, not shareholder returns, is what the market rewards.
That has two implications for markets content this year. First, market concentration has hit levels not seen since the dot-com era — roughly two dozen stocks now account for over half of the S&P 500’s total value, which is a comparable concentration level to the 32-stock peak reached during the 2000 bubble. Second, volatility has already started creeping back in: CNBC flagged in mid-September that bond yields were spiking and AI-linked names were selling off even as broader investor sentiment stayed constructive on equities — a split market where the AI trade and the rest of Wall Street are no longer moving in lockstep.
Why the Divergence Matters for Every Asset Class
The IMF’s macro divergence and Wall Street’s AI concentration are, in effect, the same story told twice — a bet on a narrow slice of the global economy carrying the rest. Energy importers and low-income developing economies are absorbing the geopolitical shock the IMF describes, just as the “average” S&P 500 stock is absorbing less of the earnings growth than the concentration numbers suggest. Both dynamics raise the same underlying question for 2026 planning: what happens to growth, and to equity valuations, if either pillar — the ceasefire holding, or hyperscaler capex converting into real earnings — gives way.
For now, neither has. The IMF’s reference forecast still assumes the conflict stays contained, and hyperscaler earnings, so far, have largely met or beaten the market’s demanding bar: Alphabet’s April quarter, for instance, saw earnings per share and Google Cloud growth both come in well ahead of consensus. But both are assumptions, not certainties, and the 2026 economy is being priced as though they will hold indefinitely.
The Bottom Line
Global growth of 3.0% sounds unremarkable in isolation. What makes 2026 distinctive is how much of that growth — and how much of the corresponding equity market gains — is concentrated in AI infrastructure spending by a small number of companies and countries. Investors, policymakers, and anyone allocating capital this year need to treat the AI capex cycle not as a side story to the macro picture, but as the macro picture’s main engine.
Next step: Track the IMF’s next World Economic Outlook update alongside hyperscaler earnings season — the two releases, taken together, are now the single best gauge of where the 2026 global economy is actually heading.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The International Monetary Fund has revised its view of the world economy three times in nine months, and the direction of travel is clear.
Global growth is now projected at 3.0% for 2026 and 3.4% for 2027 — down from the 3.5% average recorded across 2024–25.
The headline number, though, is the least interesting part of the report. What matters is why the Fund revised, and which economies it thinks will absorb the damage.
Key Takeaways
- The July 2026 forecast: 3.0% growth in 2026, 3.4% in 2027, broadly unchanged cumulatively from April.
- Two opposing forces. The Middle East war drags; the AI-driven technology cycle lifts.
- The split is not rich versus poor. It is energy exposure and position in the technology value chain.
- Inflation reversed course. The Fund projected headline inflation rising to 4.4% in its April assessment.
- Risks remain tilted downside. Longer conflict, AI expectation resets and fragmentation dominate the risk register.
The Forecast Trajectory Through 2026
| Report | 2026 Growth | 2027 Growth | Framing |
|---|---|---|---|
| October 2025 WEO | ~3.2% | 3.2% | Steady resilience |
| January 2026 Update | 3.3% | 3.2% | Revised slightly up |
| April 2026 WEO | 3.1% | 3.2% | “Reference forecast” under war |
| July 2026 Update | 3.0% | 3.4% | War drag vs AI lift |
Read as a sequence, this tells a story that a single data point cannot. January was optimistic: the Fund saw technology investment, fiscal and monetary support and accommodative financial conditions offsetting trade policy shifts.
Then war broke out.
April: The Reference Forecast
The April 2026 WEO abandoned the traditional baseline entirely. It presented instead a reference forecast predicated on the assumption that the war would have limited duration, intensity and scope, with disruptions fading by mid-2026, consistent with commodity futures prices as of 10 March.
That is an unusual methodological choice and worth understanding. The Fund was explicitly saying: we cannot forecast this, so here is a conditional projection plus scenarios.
Chief Economist Pierre-Olivier Gourinchas framed the reversal directly: the global economy had been on a steady trajectory around 3.3% and the Fund was looking to upgrade its projections before the war stopped that momentum, with inflation rising to 4.4%.
He identified three transmission channels: higher energy and food prices themselves; persistence in wage and price inflation; and a confidence shock.
The adverse scenario modelled oil prices rising 80% and gas prices 160% from the second quarter of 2026 relative to January assumptions.
July: The AI Offset
The July Update introduced the year’s most important analytical point. The modest slowdown reflects the effects of the Middle East war being partly offset by accelerated demand-driven momentum in the global technology cycle, thanks to advances in artificial intelligence and its adoption.
Critically, the impact varies by two dimensions at once:
- Energy exporters outside the conflict zone benefit from favourable terms of trade.
- Economies plugged into the technology-led upturn experience stronger activity even if they are energy importers.
- Energy importers with limited participation in the technology value chain see activity weaken.
That third category is where the damage concentrates. It captures much of South Asia, Sub-Saharan Africa and parts of Latin America — economies paying more for energy without the AI export revenues to offset it.
This is the single most actionable framework in the 2026 IMF reporting. It explains why Japan and Korea have outperformed while frontier importers have stalled.
What the Reports Say About Major Economies
The January Update projected advanced economy growth of 1.8% in 2026 and 1.7% in 2027, with the United States expanding 2.4% in 2026 supported by fiscal policy and a lower policy rate, before settling at 2.0% in 2027 with a near-term boost from corporate investment tax incentives.
On inflation dynamics, the Fund noted inflation in China rising from low levels, while inflation in India was expected to return to near-target levels after a 2025 decline driven by subdued food prices.
Russia was projected to maintain growth of 1.1%.
Why Investors Should Read IMF Reports Differently
Most market participants treat the WEO as a headline number. Three better uses:
- The revision direction beats the level. A forecast cut from 3.3% to 3.0% tells you more about policy trajectory than the absolute figure does.
- The scenarios are the real content. The April adverse scenario’s 80% oil assumption is a stress test you can apply to your own portfolio.
- The country tables are underused. Annex Table 1’s selected-economy real GDP growth figures cover economies accounting for approximately 83% of world output.
How the IMF and World Bank Differ
The two institutions use different methodologies and produce different numbers for the same year. The IMF projects 3.0% global growth for 2026 on purchasing-power-parity weights. The World Bank projects 2.5% using market exchange rate weights.
Neither is wrong. PPP weighting gives more weight to faster-growing emerging economies. Market-rate weighting reflects actual dollar-denominated output. Quote the one that matches your analytical frame — and never compare the two headline figures directly.
Risks the Fund Flags
- Longer or broader conflict. The reference forecast assumes containment. It is an assumption, not a projection.
- AI expectation reset. A reassessment of expectations surrounding AI-driven productivity could significantly weaken growth and destabilise financial markets.
- Geoeconomic fragmentation. Trade and technology bloc formation raises costs structurally.
- Elevated public debt. Combined with eroding institutional credibility, this heightens vulnerabilities.
- Defence spending trade-offs. The Fund specifically warns policies must carefully manage the trade-offs involved in ramping up defence expenditure.
What This Means for the Global Market in 2027
3.4% in 2027 is a recovery forecast, not a boom. It sits well below the 2000–19 historical average of 3.7%, and the Fund expects growth to settle near that lower rate in the medium term.
The AI offset is a concentrated bet. If the technology cycle disappoints, there is no second offsetting force in the model. The war drag remains; the lift disappears.
Inflation persistence is the policy trap. Rising headline inflation alongside slowing growth limits how far central banks can cut, which in turn limits the equity valuation support markets have priced.
Energy-importing frontier economies face a structural squeeze. Pakistan, Bangladesh, Sri Lanka, Kenya and similar economies sit precisely in the Fund’s worst-affected category.
Watch the October 2026 WEO. It will be the first full report to assess whether the war disruptions actually faded on the assumed timeline. If they did not, the reference forecast framework collapses and forecasts move materially lower.
Frequently Asked Questions
What is the IMF’s global growth forecast for 2026?
The IMF projects 3.0% global growth in 2026 and 3.4% in 2027, down from the 3.5% average recorded in 2024–25.
Why did the IMF cut its 2026 forecast?
The Middle East war raised energy prices and inflation while denting confidence. This drag is only partly offset by AI-driven demand in the global technology cycle.
How often does the IMF publish the World Economic Outlook?
Twice yearly as full reports (April and October), with shorter Updates in January and July.
Do the IMF and World Bank forecasts agree?
They differ by methodology. The IMF’s 3.0% for 2026 uses PPP weights; the World Bank’s 2.5% uses market exchange rates. The two headline numbers are not directly comparable.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
When the benchmark 10-year U.S. Treasury yield crosses the 5.0% threshold, financial markets undergo a structural paradigm shift. Far beyond a routine spike in borrowing costs, a 5% yield alters the hurdle rate for global capital, re-prices risk across every asset class, and exposes systemic sovereign debt fragilities.
1. The 5.0% Benchmark: Why the “Risk-Free” Rate Reshapes Equities
The 10-year U.S. Treasury note is the foundational anchor of global finance. Its yield represents the risk-free rate ($R_f$) utilized in the Capital Asset Pricing Model (CAPM) and Discounted Cash Flow (DCF) models worldwide.
When $R_f$ rises from 2%–3% to over 5%, the present value of future corporate earnings contracts exponentially.
$$\text{Present Value} = \sum_{t=1}^{n} \frac{CF_t}{(1 + WACC)^t}$$
As the Weighted Average Cost of Capital ($WACC$) climbs alongside Treasury yields:
- Growth Stocks & Big Tech: Long-duration growth equities—where the majority of projected cash flows sit far in the future—suffer the sharpest valuation multiple compressions.
- Equity Risk Premium (ERP) Squeeze: With risk-free Treasury bills yielding 5%, the additional premium required to hold volatile equities shrinks dramatically, prompting institutional capital to migrate from stocks to bonds.
- Corporate Liquidity Crunch: Corporate debt refinancing costs double or triple compared to pre-2022 issuance levels, directly eroding net profit margins reported to the U.S. Securities and Exchange Commission.
2. Macroeconomic Catalysts: What Is Driving the Bond Sell-Off?
The surge to 5%+ yields is driven by three primary structural forces rather than a single economic data point:
┌─────────────────────────────────────────────────────────────────────────┐
│                      DRIVER 1: FISCAL EXPANSION                         │
│  U.S. national debt interest + mandatory entitlement outlays now absorb │
│  ~98% of federal tax revenues (Source: U.S. Treasury Department).       │
└────────────────────────────────────┬────────────────────────────────────┘
                                     │
                                     ▼
┌─────────────────────────────────────────────────────────────────────────┐
│                     DRIVER 2: ISSUANCE MISMATCH                         │
│  84% of 12-month Treasury debt issuance concentrated in short-term T-   │
│  Bills, creating severe rollover sensitivity to rate hikes.             │
└────────────────────────────────────┬────────────────────────────────────┘
                                     │
                                     ▼
┌─────────────────────────────────────────────────────────────────────────┐
│                     DRIVER 3: CAPITAL COMPETITION                       │
│  Corporate AI CAPEX spending (~$700B–$900B/yr) competes with sovereign  │
│  bond issuance for global institutional capital reserves.               │
└─────────────────────────────────────────────────────────────────────────┘
Sovereign Debt & Supply Shock
As documented by the U.S. Department of the Treasury, massive fiscal deficit spending has accelerated net bond issuance. Because traditional central bank buyers engaged in quantitative tightening (QT) while foreign sovereign buyers reduced purchases, price discovery has shifted to price-sensitive private institutional investors who demand higher yields (term premium) to absorb debt supply.
Global Central Bank Tightening Synchronicity
Monetary policy decisions from the Federal Reserve System and global partners—such as the Bank of Japan raising interest rates—have reinforced elevated global rate floors. Official global debt perspectives from the International Monetary Fund highlight how high real yields strain emerging market borrowing capacity.
3. Sector Impact Analysis & Asset Class Vulnerabilities
| Asset Class / Sector | Impact Level | Primary Vulnerability / Opportunity |
| Mega-Cap Big Tech | Moderate to High | CAPEX borrowing costs rise; DCF discount rate expansion reduces forward P/E multiples. |
| Commercial & Residential Real Estate | Severe Headwind | Mortgage rates track 10-year yields; refinancing resets create valuation pressure. |
| Short-Term T-Bills & Money Market | Highly Favorable | Yields above 5% offer competitive risk-adjusted real returns without duration risk. |
| Hard Assets (Gold / Precious Metals) | Strategic Hedge | Fiscal deficit concerns and dollar devaluation risks enhance gold’s monetary status. |
| Asian & Emerging Market Equities | Selective Upside | Valuations in South Korea, Japan, and India trade at significant discounts relative to U.S. multiples. |
4. Tactical Asset Allocation Framework
Navigating a 5%+ Treasury yield environment requires balancing yield capture, capital preservation, and equity growth.
Core Portfolio Takeaways
- The Cash-Equivalent Shield: Allocating 35% to short-dated T-Bills mimics Warren Buffett’s liquidity strategy at Berkshire Hathaway, locking in 5%+ yields while preserving optionality for market corrections as reported by CNBC Markets.
- Selective Equity Quality: Focus equity exposure on companies with pristine balance sheets, low debt-to-equity ratios, and pricing power capable of outrunning inflation.
- Monetary Hedges: Gold and hard assets provide downside protection against potential currency weakness if central banks step in to cap bond yields through yield curve intervention. Further macroeconomic debt analysis is regularly updated by Bloomberg Markets and Reuters Financial News.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Apply for a Bank Account Online: What You Need and How Long It Actually Takes

World’s Largest Economies: Ranking the Top Global Powers

Business Loan: A Complete 2026 Guide to Rates, Types, and Qualifying

Fast Invoice Factoring: How to Turn Unpaid Invoices Into Cash Within 24 Hours

Investment Banking Services: What They Cost and How to Choose the Right Firm in 2026

Structured Settlement Loan: What “Cash Now” Offers Actually Cost You

DUI Attorney: Why Your First Call After an Arrest Should Never Be to the Court

Personal Injury Lawyer: A Complete Guide to Filing Your Claim in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025