
Mortgage
How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

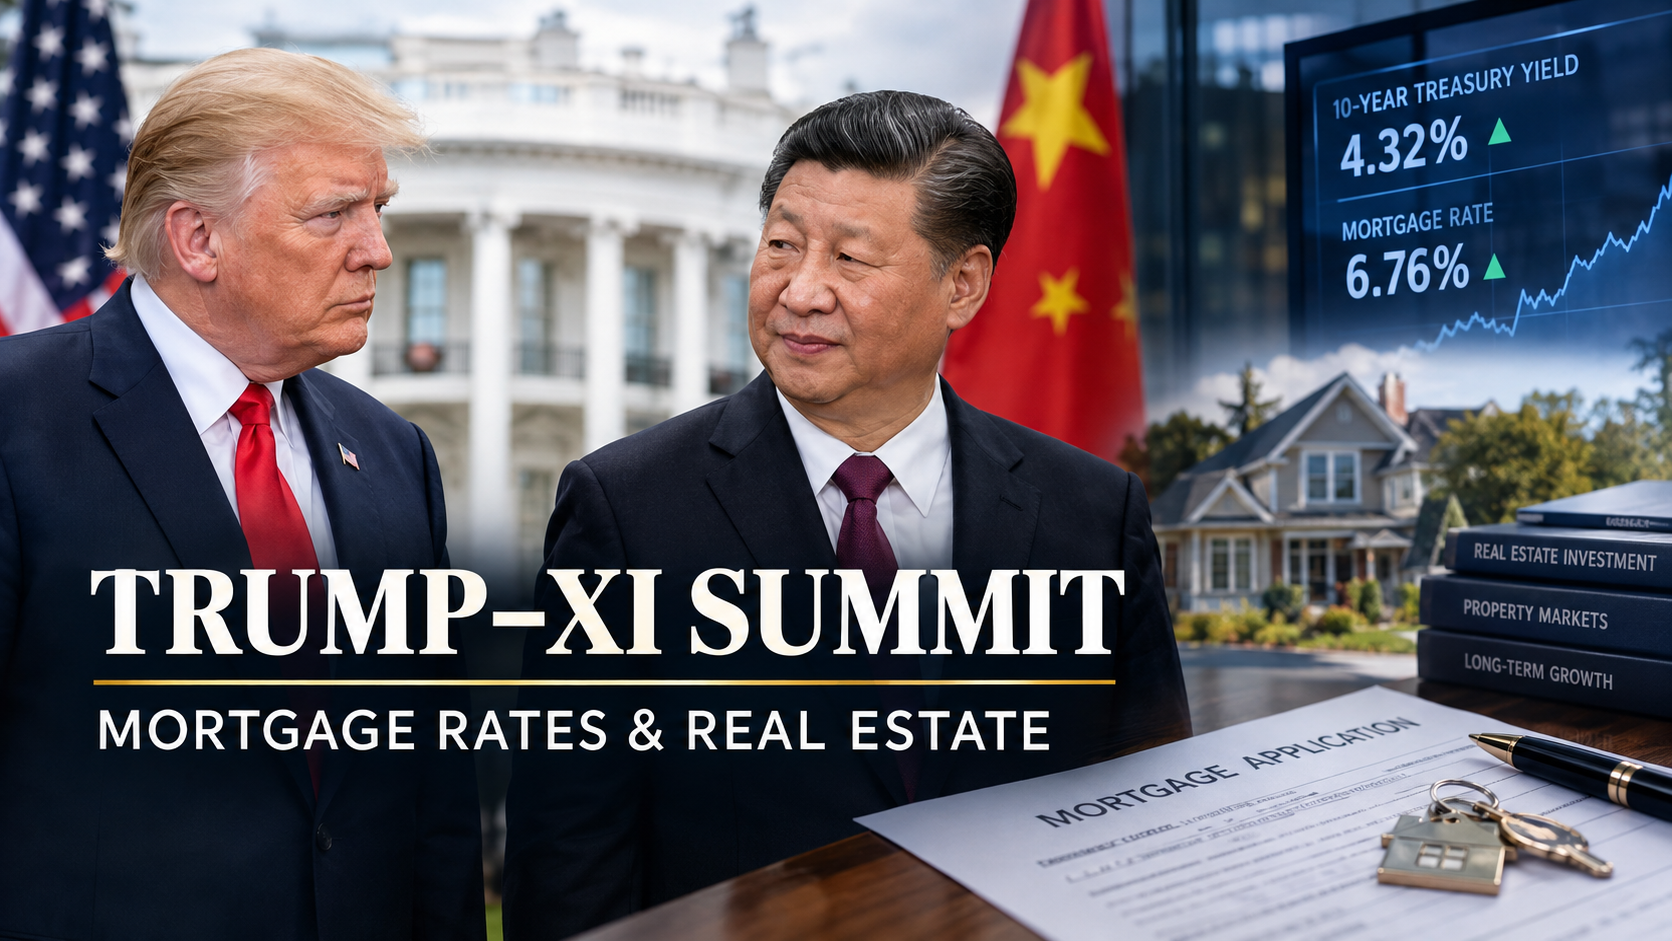
The September 24 Trump-Xi summit produced a two-month trade-truce extension rather than a durable deal — and that ambiguity, not a headline breakthrough, is what’s now keeping the 10-year Treasury yield elevated and mortgage rates parked near 7% heading into the fourth quarter.
Mortgage Rates Today: The Q4 2026 Baseline
Freddie Mac’s benchmark survey put the 30-year fixed-rate mortgage at 6.95% for the week of September 17, 2026 — the fourth consecutive weekly increase and the highest reading since January 2025. The 15-year fixed climbed in tandem to 6.26%. A year earlier, the 30-year average sat more than half a point lower, near 6.26%.
| Loan Type | Rate (week of Sept. 17, 2026) | Rate (1 year prior) |
|---|---|---|
| 30-year fixed | 6.95% | 6.26% |
| 15-year fixed | 6.26% | 5.41% |
| 5/1 ARM | ~6.8%–7.0% | — |
| 30-year VA | ~6.2%–6.3% | — |
Source: Freddie Mac Primary Mortgage Market Survey; Zillow daily rate tracker.
The proximate driver is the bond market, not the housing market. Mortgage pricing tracks the 10-year Treasury yield, and that yield has been climbing toward the high-4% range through September on a combination of heavy government issuance and a Federal Reserve that has signaled it is in no hurry to cut. Layer geopolitical risk on top — oil above $90 a barrel amid Middle East disruption, plus unresolved US-China friction — and lenders are pricing in a wider risk premium.
Why the Summit Matters to Your Rate Lock
Real estate investors tend to treat foreign policy as background noise. That’s a mistake in Q4 2026. The Trump-Xi relationship is now the single largest swing factor in how bond markets price forward risk, because it touches three things that feed directly into Treasury yields: tariff policy, rare-earth and technology export controls, and the credibility of the disinflation narrative the Fed needs to justify future rate cuts.
What Actually Happened at the September 24 Summit
Xi Jinping’s September 24 visit to the White House was the second Trump-Xi meeting of 2026, following a May 14–15 state visit to Beijing where the two sides agreed to pursue what they termed a “constructive, strategically stable relationship.” The Washington leg was shorter on ceremony and shorter on breakthroughs. According to Reuters’ pool reporting, Treasury Secretary Scott Bessent confirmed the two sides extended their trade truce — originally due to lapse in November — by roughly two months, buying time rather than locking in a structural agreement.
That is the detail markets are trading on. An extension without resolution leaves tariff rates, Chinese purchasing commitments, rare-earth export licenses, and technology restrictions all still in play heading into the new year. For bond investors, unresolved trade risk is inflationary risk: tariffs raise input costs, and rare-earth bottlenecks squeeze manufacturers that feed into consumer prices. Both push against the case for near-term Fed easing, and Fed policy is the single biggest lever on where mortgage rates land.
Three Summit Threads With Direct Rate Impact
- The 60-day trade truce clock. With the new deadline now sometime in early 2026’s first quarter, expect renewed rate volatility as that date approaches — mortgage desks should treat any lock decision inside that window as elevated-risk.
- AI and export-control friction. Both sides used the September summit to air disagreements over AI development and chip/technology export controls, an area CSIS analysts have flagged as the least-resolved dimension of the relationship. Unresolved tech friction keeps a geopolitical risk premium baked into yields.
- No durable tariff resolution. Core tariff and purchasing questions were pushed into the next round of talks, meaning the inflation uncertainty that has kept the Fed cautious remains unresolved.
Featured Snippet: What Is the Average Mortgage Rate Today?
As of mid-to-late September 2026, the average 30-year fixed mortgage rate in the US is running just under 7%, per Freddie Mac’s weekly survey — the highest level since January 2025, driven by rising Treasury yields tied to heavy government borrowing and unresolved US-China trade risk following the September 24 Trump-Xi summit.
Asian Growth and the Global Rate Picture
The mortgage story doesn’t stop at the US border. The Asian Development Bank’s September 2026 outlook nudged developing Asia’s 2026 growth forecast up slightly to 5.0%, even as regional inflation stays elevated near 4.2%. Stronger Asian growth alongside sticky inflation is broadly consistent with the “higher for longer” global rate environment that’s keeping US mortgage rates elevated — it’s not just a domestic story.
Q4 2026 Predictive Outlook
- Base case: 30-year fixed rates hold in the 6.7%–7.1% band through year-end, with volatility clustering around the new US-China truce deadline and the next two Fed meetings.
- Upside risk (higher rates): A breakdown in the truce, renewed tariff escalation, or a hawkish surprise from the Fed pushes the 30-year toward 7.25%–7.5%.
- Downside risk (lower rates): A durable trade framework or a faster-than-expected inflation cooldown could pull rates back toward the low 6% range, though nothing in current Fed communication points to that in Q4.
FAQ
Will mortgage rates go down before the end of 2026?
Most forecasters, including those tracked by Freddie Mac and major bank research desks, see rates holding near current levels through Q4 2026 absent a clear resolution to US-China trade tensions or a faster Fed pivot.
How does the Xi-Trump summit affect US mortgage rates?
It affects rates indirectly, through Treasury yields. Unresolved trade and tech-export issues keep an inflation and geopolitical-risk premium in bond markets, which raises the yields that mortgage-backed securities are priced against.
What is a good mortgage rate right now?
Relative to the current national average near 6.9%–7.0%, well-qualified borrowers securing rates half a point or more below the weekly Freddie Mac average are getting a comparatively strong deal in today’s market.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Business
US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors
Key Takeaways
- Historic Highs: The US 10-year Treasury yield closed at 5.244%, a peak not seen since the prelude to the 2008 global financial crisis.
- Fed Rate Tightening: Markets are pricing in a 70% chance of another Federal Reserve rate hike at the late-October FOMC meeting following September’s shift to a 3.75%–4.00% target range.
- Borrowing Costs Surge: 30-year fixed mortgage rates are spiking past multidecade highs, suppressing real estate transaction volumes.
- Asset Reallocation: Bond yields above 5% create substantial headwind for growth stocks while elevating cash-equivalent instruments to prime investment status.
The Macroeconomic Catalyst: Why Yields Are Surging
The sudden acceleration in benchmark sovereign yields comes on the heels of persistent inflationary pressures driven by global energy disruptions and resilient labor data. When the Federal Reserve raised rates in September to the 3.75%–4.00% range, institutional bond traders initially anticipated a pause. However, hawkish central bank commentary coupled with persistent federal debt issuance has pushed the 10-year Treasury note to 5.244%, a level last recorded in 2007.
According to real-time market tracking from Trading Economics, global fixed-income markets are undergoing a fundamental repricing. High yields mean the government must offer higher returns to attract buyers for its expanding deficit, directly competing with private sector risk assets.
            US 10-Year Treasury Yield Trajectory
   5.5% |                                       * (5.244%)
   5.0% |                                *-----*
   4.5% |                         *-----*
   4.0% |                  *-----*
   3.5% |           *-----*
        +---------------------------------------------------
          Jan 2026    Apr 2026   Jul 2026    Sep 2026
Mortgage Rate Forecast 2026 & Real Estate Impact
The primary transmission mechanism of the benchmark yield spike into the everyday economy is through mortgage lending rates. Because mortgage-backed securities (MBS) are priced relative to the 10-year yield plus a risk spread, residential borrowing costs have responded immediately.
As detailed by financial coverage on CNBC, the spread between the 10-year yield and 30-year fixed mortgage rates remains historically wide due to secondary market volatility.
Housing Market Stress Points:
- Buyer Purchasing Power Reduction: Every 50-basis-point surge in mortgage rates reduces homebuyer purchasing capacity by approximately 5%.
- The “Lock-In” Effect: Existing homeowners with 3%–4% legacy mortgage rates refuse to list properties, driving inventory down to structural lows.
- Commercial Real Estate (CRE) Refinancing: Over $1.2 trillion in commercial debt requires refinancing before year-end, now facing interest expense shocks that threaten regional bank balance sheets.
Fed Rate Hike October Odds & Wall Street Strategy
Derivatives pricing monitored by Bloomberg indicates that money markets are placing roughly a 70% probability on an additional 25-basis-point rate hike at the late-October Federal Open Market Committee (FOMC) meeting.
Financial Sector Asset Class Comparison
| Asset Class | Yield / Return Outlook | Risk Profile | Strategic Investor Positioning |
| US 10-Year Treasury | $5.24\%$ Fixed Return | Low (Sovereign) | Strong buy for income locking; duration risk if yields hit 5.5% |
| S&P 500 Equities | $4.2\%$ Earnings Yield | Moderate / High | Overweight value/cash-flow; underweight non-profitable tech |
| 30-Year Fixed Mortgage | $7.85\% – 8.20\%$ Cost | Low (Consumer Credit) | Refinance freeze; shift toward adjustable-rate structures (ARMs) |
| Gold (Spot) | $-3.71\%$ ($4,127/oz) | Moderate | Tactical buy on dip if real yields stabilize |
Investor Playbook: Navigating a 5%+ Yield Environment
When baseline risk-free cash yields exceed 5%, traditional investment models like the classic 60/40 equity-to-bond portfolio demand recalibration.
- Short-Duration Fixed Income: Capitalize on elevated yield-to-maturity metrics by allocating into 1-to-3 year Treasuries or high-grade corporate debt without locking up capital in long-duration securities.
- Dividend Dividend Aristocrats over Growth: Shift equity exposure toward dividend-paying value stocks possessing robust balance sheets and low net-debt-to-EBITDA ratios.
- Hedging Rate Volatility: Institutional allocators are utilizing interest rate swaps and inverse Treasury ETFs to insulate equity gains against sustained yield spikes.
Frequently Asked Questions (FAQ)
How does the US 10-year yield affect home mortgage rates?
The 10-year Treasury yield serves as the benchmark for 30-year fixed-rate mortgages. Lenders add a spread (typically 1.5% to 3.0%) over the 10-year yield to cover credit risk and servicing costs. When the yield rises to 5.24%, mortgage rates naturally trend upward toward 7.5%–8.2%.
Why are yields rising if the Fed only raised rates to 3.75%-4%?
While the Fed controls short-term overnight rates, the 10-year yield is determined by market demand for long-term government debt. Factors like heavy Treasury debt supply, long-term inflation fears, and international central bank selloffs drive up long-term yields independently of overnight rate levels.
What happens to stock prices when bond yields hit multi-year highs?
Rising bond yields make risk-free fixed income more attractive compared to stocks. Higher discount rates are applied to future corporate earnings calculations, which tends to depress stock valuations, particularly for high-growth tech companies reliant on future earnings.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
As of the week ending September 10, 2026, the average 30-year fixed-rate mortgage in the United States stood at 6.76%, up from 6.71% the prior week, according to Freddie Mac’s Primary Mortgage Market Survey reported via Trading Economics. The 15-year fixed-rate mortgage averaged 6.09% over the same period, up from 6.04% a week earlier. A year ago, the 30-year rate averaged 6.35% — meaning today’s borrowers are paying roughly 40 basis points more than they were twelve months prior.
| Loan Type | Recent Average Rate | Prior Week | One Year Ago |
|---|---|---|---|
| 30-year fixed | 6.76% | 6.71% | 6.35% |
| 15-year fixed | 6.09% | 6.04% | 5.50% |
Freddie Mac’s chief economist, Sam Khater, has consistently urged borrowers not to accept the first quote they receive, noting that shopping around and collecting multiple offers can save thousands of dollars over the life of a loan.
Why Rates Are Stuck Near 7%
Three forces have kept mortgage rates elevated through the back half of 2026, and understanding each one helps explain why “wait for rates to drop” has been bad advice for most of the year.
1. The 10-year Treasury yield. Mortgage rates track the 10-year Treasury yield closely, and that yield climbed toward the 4.77%–4.78% range in early September as the U.S. government’s continued heavy borrowing pushed investors to demand higher compensation, according to rate coverage from The Mortgage Reports.
2. Fed policy under a new chair. Fed Chair Kevin Warsh signaled a tougher anti-inflation stance at the Jackson Hole gathering than markets had priced in, pushing the 30-year fixed rate to 6.91% by September 14 — near the psychologically important 7% threshold — as rate-cut expectations were pushed back.
3. Oil and geopolitical risk. Renewed U.S.-Iran tensions pushed oil prices above $93 a barrel in early September, adding inflationary pressure that works against any near-term easing in borrowing costs.
The combined effect has weighed on affordability: the median existing home price hit a record $434,100 in July 2026, meaning a buyer putting 20% down at prevailing rates faces a monthly payment of roughly $2,255 — nearly a quarter of the average family’s annual income, based on figures compiled by NoradaRealEstate’s rate-tracking series.
Credit Acceptance: Why Your Score Still Moves the Needle
The rates quoted above are national averages — what any individual borrower actually pays depends heavily on credit profile, down payment size, and loan type. This is where “credit acceptance” as a search term becomes relevant: lenders price risk on a sliding scale, and the gap between a top-tier borrower’s rate and an average borrower’s rate can run a full percentage point or more.
Featured Snippet Target: Credit acceptance in a mortgage context refers to a lender’s willingness to approve and price a loan based on a borrower’s credit profile — score, debt-to-income ratio, and payment history — with stronger profiles typically qualifying for rates 0.25% to 1% below the published national average, translating into thousands of dollars in savings over a 30-year term.
Government-backed loan programs continue to price meaningfully below conventional rates for borrowers who qualify. As of early September, 30-year VA loans were averaging 6.14%, and 15-year VA loans 5.91% — roughly half a point below their conventional counterparts, based on the same Zillow-sourced data used in NoradaRealEstate’s daily rate tracker. FHA loans have shown a similar discount, reflecting the government guarantee that reduces lender risk regardless of an individual borrower’s score.
Where Rates Might Go From Here
Forecasters remain split. The Mortgage Bankers Association’s own projections, cited in earlier 2025 coverage from Yahoo Finance, expected rates to hold at or just above 6% through 2026 — a forecast that has proven optimistic given the current mid-to-high 6% range. Some housing-market analysts covering the September data have gone further, warning rates could climb above 7% before the year is out if the Fed holds firm on inflation and Treasury yields keep climbing.
For context, rates have swung significantly within 2026 alone: the 30-year fixed dipped as low as 5.98%–6.07% in late February and early March, before climbing back through the summer and into the high 6% range by September. That volatility is itself the headline for borrowers trying to time a purchase — waiting for a “better moment” has not been a reliably successful strategy this year.
Practical Takeaways for Borrowers
- Rate-lock timing matters more than usual in 2026. With daily and weekly swings of 5–15 basis points common, locking a rate the same day you get pre-approved reduces exposure to short-term Treasury-yield volatility.
- VA and FHA borrowers are getting a real discount right now — roughly half a point below conventional rates as of September, per the sources above.
- Improving credit acceptance odds before applying pays off. Paying down revolving debt and avoiding new credit inquiries in the 60–90 days before applying remains the most reliable lever borrowers control directly, even as the broader rate environment stays out of their hands.
- “Marry the house, date the rate” — the idea of buying now and refinancing later when rates fall — has become a talking point in 2026 coverage, but it assumes a refinancing window that may not materialize on any predictable timeline.
The Bottom Line
Mortgage rates today sit in a stubborn mid-to-high 6% band, driven by Treasury-yield pressure, a hawkish Fed stance, and oil-price-linked inflation risk. Credit acceptance — how a borrower’s individual profile is priced against that national backdrop — remains the single biggest lever within a buyer’s control, with government-backed loan programs currently offering the clearest path to a below-average rate.
Next step: Pull rate quotes from at least three lenders before locking, and specifically ask each one to price both a conventional and a government-backed (FHA/VA) option side by side — the spread between the two has been unusually wide in 2026’s rate environment.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Key Takeaways
- The benchmark 10-year US Treasury yield briefly touched 5.014% on Monday, September 14, 2026 — its first move above the psychologically important 5% threshold since October 2023, and only its second time above that level since the 2007-2008 financial crisis.
- The move came just two days before the Federal Reserve’s September policy meeting, with markets now pricing roughly a 90% probability of a rate hike rather than a cut, according to CME Group’s FedWatch tool.
- The catalyst combines several forces at once: Brent crude topping $109/barrel, a hotter-than-expected August CPI report, swelling government and corporate borrowing needs, and a possible unwinding of the Japanese yen carry trade as Japanese rates climb.
- The 30-year Treasury yield reached 5.386%, directly affecting mortgage pricing, while 10-year yields in the UK and Australia have also climbed above 5% — signaling this is a global, not purely American, bond-market phenomenon.
- Veteran market strategist Ed Yardeni notes that neither the yield spike nor the global bond selloff has “broken” the stock market’s bull run so far, crediting continued strength in corporate earnings.
For the first time in nearly three years, the interest rate that anchors global borrowing costs — the US 10-year Treasury yield — has crossed the symbolically important 5% threshold. The move, which arrived just 48 hours before the Federal Reserve’s September policy decision, is rippling through mortgage markets, equity valuations, and central bank calculations from Washington to Tokyo. Here’s what actually happened, why, and what it means for anyone watching the stock market today.
What Happened
The 10-year Treasury yield climbed as high as 5.014% intraday on Monday, September 14, 2026, before paring the move back to around 4.94–4.99% by afternoon trading. It marked the first time the yield had crossed 5% during a trading session since October 23, 2023, and — as several outlets noted — only the second time it has traded this high since July 2007, just before the global financial crisis. A close above 5.02% would represent the highest level since that pre-crisis period.
The move wasn’t isolated to the 10-year note. The 2-year Treasury yield, which is more directly sensitive to near-term Fed policy, climbed to 4.679%, surpassing its previous July 2024 high. The 30-year yield — the benchmark most directly tied to fixed mortgage rates — touched 5.386% before paring some of its gains.
Why Yields Are Spiking: Four Forces Converging
1. Oil-driven inflation fears. Brent crude climbed to a session high past $109 a barrel as fighting between the US and Iran escalated, directly feeding into bond investors’ inflation expectations. Rising energy costs erode the fixed returns bondholders receive, pushing yields higher to compensate.
2. A hotter-than-expected inflation print. Friday’s August CPI report showed inflation running hotter than markets had anticipated. Goldman Sachs’ chief economist David Mericle wrote that while the report didn’t change the bank’s underlying inflation view, it pushed market pricing of a Fed rate hike this week to nearly 90% — a striking reversal from earlier-year expectations of continued rate cuts.
3. Swelling government and corporate borrowing. The yield spike is also being driven by basic supply-and-demand dynamics in the bond market: both the federal government and major corporations are issuing substantial new debt to fund spending, adding to the overall supply of bonds competing for investor capital.
4. A potential yen carry-trade unwind. Yardeni Research has floated a more technical explanation with global implications: as Japanese interest rates rise and the yen strengthens (partly on Japan’s own defense-spending and monetary-policy shifts), the long-popular “carry trade” — in which investors borrow cheaply in yen and invest in higher-yielding assets elsewhere — becomes less attractive. Unwinding those positions could be contributing to selling pressure across global bond markets, not just US Treasuries.
Global Context: This Isn’t Just an American Story
The yield surge isn’t confined to the US. Ten-year yields in both Australia and the UK have also climbed above 5%, reinforcing that this is a broader global bond-market repricing rather than a US-specific event. Yardeni’s assessment captures the moment’s tension well: a global yield spike of this magnitude “would normally be enough to break a global bull market in stocks. Neither has so far” — crediting resilient corporate earnings for equities’ relative calm despite the bond turmoil.
Rate Decision Timing: Why This Matters So Much Right Now
The timing amplifies the significance considerably. The yield spike landed just two days ahead of the Federal Reserve’s September policy meeting, transforming what might otherwise be a notable but contained bond-market move into a live variable in the Fed’s own deliberations. According to CME Group’s FedWatch tool, the probability of a rate hike this week has climbed above 90%, while Polymarket bettors have priced the same outcome at around 80%. Some market watchers are also monitoring rising tension between President Trump and Fed Chair Kevin Warsh as a wildcard factor in how the central bank navigates the decision.
Yield Snapshot
| Maturity | Peak Yield (Sept 14, 2026) | Significance |
|---|---|---|
| 2-year Treasury | 4.679% | Highest since July 2024; most Fed-sensitive |
| 10-year Treasury | 5.014% | First above 5% since October 2023 |
| 20-year Treasury | 5.426% | Sensitive to geopolitical risk |
| 30-year Treasury | 5.386% | Benchmark for mortgage rates |
Why This Matters: Mortgages, Portfolios, and the Fed’s Next Move
For everyday borrowers, the 30-year yield’s climb toward 5.4% translates fairly directly into higher fixed mortgage rates, making home purchases and refinancing meaningfully more expensive than earlier in 2026. For equity investors, the key question is whether corporate earnings can continue outrunning the drag from higher borrowing costs — the dynamic Yardeni credits for the stock market’s calm so far. And for the Fed, Wednesday’s decision now carries outsized weight: a hike would validate the bond market’s current pricing, while a hold could trigger further yield volatility if investors interpret it as the central bank falling behind an inflation trend that oil prices and geopolitical tension are actively worsening.
Frequently Asked Questions
Why did the 10-year Treasury yield cross 5% in September 2026?
The move was driven by a combination of surging oil prices tied to the escalating US-Iran conflict, a hotter-than-expected August CPI report, heavy government and corporate bond issuance, and a possible unwinding of the yen carry trade as Japanese rates rise.
How does a 5% Treasury yield affect mortgage rates?
The 30-year Treasury yield, which climbed to 5.386% alongside the 10-year’s move, is the most direct benchmark for 30-year fixed mortgage rates, meaning this yield spike is likely pushing mortgage borrowing costs higher for US homebuyers.
Will the Federal Reserve raise interest rates this week?
As of the yield spike, markets were pricing roughly a 90% probability of a rate hike at the Fed’s September meeting, according to CME Group’s FedWatch tool — a sharp reversal from earlier expectations of rate cuts.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025