
Cryptocurrency
British Man Recovers £3.3M Lost Bitcoin After 12 Years

A British investor known only as Chris has recovered 61 Bitcoin worth approximately £3.3 million ($4.7 million), twelve years after the collapse of an early UK crypto exchange froze him out of his own wallet — proving that “lost” Bitcoin isn’t always gone for good, and that legal recovery, not just technical recovery, is now a viable path back to a vanished fortune.
The £1,500 Bet That Nearly Vanished Forever
In December 2011, Chris put £1,500 into Bitcoin through Britcoin, one of the United Kingdom’s first cryptocurrency exchanges, after a friend convinced him the technology could become “a massive thing.” At the time, Bitcoin traded at roughly £2.94 a coin, so his stake bought him 61 BTC. Britcoin later rebranded as Intersango, and by 2014 Chris’s small investment had appreciated to around £4,000 on paper. Then the exchange collapsed, taking more than 5,000 customer accounts — including his — down with it.
For most of the following decade, Chris assumed the money was simply gone. He described watching Bitcoin’s price climb year after year as “a punch in the stomach.” In 2018, two of Intersango’s co-founders emailed former customers asking them to get in touch, but Chris deleted the messages, convinced they were a scam. It wasn’t until his wife pushed him to try again this year that the story changed direction.
How Crypto Wallet Recovery Actually Worked in This Case
Chris’s case is a useful reminder that not every “lost Bitcoin” story is a seed phrase recovery or lost hard drive bitcoin problem. His private keys were never destroyed — they were held by a defunct exchange’s operators, meaning the obstacle was legal ownership, not technical access. That distinction matters enormously for anyone trying to recover crypto locked in a collapsed platform.
Encouraged by his wife, Chris approached CEL Solicitors, a UK firm specializing in digital-asset recovery. Ryan Sweetnam, the firm’s Director of Financial Litigation, assembled documentation establishing Chris’s ownership of the Bitcoin and prepared to pursue proceedings in the United States, where some of Intersango’s former operators are believed to reside. According to Sweetnam, the matter was ultimately resolved through negotiation rather than a courtroom hearing. Within months, 61 Bitcoin were transferred into an FCA-regulated account under Chris’s control.
“It’s a punch in the stomach watching Bitcoin go up and up,” Chris told LBC of the years he spent believing the money was unrecoverable — a feeling that has since given way to disbelief. He says he still checks the balance in his app “every single day, 20 times a day.”
Why This Story Matters Beyond One Lucky Investor
Chris’s recovery stands in sharp contrast to the far more famous case of James Howells, the Newport, Wales, IT engineer who accidentally threw a hard drive containing 8,000 Bitcoin — now worth roughly $900 million — into a landfill in 2013. Howells has spent over a decade fighting Newport City Council for permission to excavate the site, offering the council tens of millions of pounds and even proposing to buy the landfill outright. A UK High Court judge dismissed his case in January 2025, ruling it had no realistic prospect of success, and as of mid-2026 his hard drive remains buried under hundreds of thousands of tonnes of waste at the Docksway site.
The difference between the two outcomes is instructive:
| Case | Type of Loss | Recovery Method | Outcome |
|---|---|---|---|
| Chris (Intersango) | Exchange collapse, keys held by third party | Legal negotiation via solicitors | Recovered, ~£3.3M |
| James Howells | Hard drive discarded, keys destroyed/inaccessible | Litigation for landfill excavation rights | Denied by High Court, still unresolved |
Howells’ keys are physically inaccessible unless the hard drive is located and its platters remain readable — a task complicated by twelve years of decomposition, compaction, and mixed waste. Chris’s keys, by contrast, always existed intact on a server; the fight was over who had the legal right to access them. That single distinction explains why one man is now a millionaire and the other is still negotiating with a local council.
What This Means for Anyone With “Lost” Crypto From a Defunct Exchange
Chris’s case has drawn attention from crypto forensics specialists because it suggests a wider pool of dormant funds may still be reachable. According to reporting on the case, one of Intersango’s co-founders is believed to still hold roughly 5,500 Bitcoin — potentially worth hundreds of millions of pounds at current prices — some of which may belong to other former customers who assumed their holdings were lost forever.
If you believe you have Bitcoin or other cryptocurrency trapped in a collapsed exchange, the practical playbook looks different depending on your situation:
- Exchange collapse with keys held by a third party: This is a legal ownership problem. Specialist solicitors can assemble historical account records, transaction logs, and correspondence to prove entitlement, then pursue negotiation or litigation against the individuals who control the wallets.
- Lost hardware or forgotten passwords: This is a technical recovery problem. Data recovery specialists may be able to extract keys from damaged drives, and password-cracking services exist for certain wallet formats — though success rates fall sharply the older and more damaged the device.
- Seed phrase partially remembered: Specialized brute-force tools exist for recovering wallets when a seed phrase is incomplete, though costs and success rates vary widely by wallet type and how many words are missing.
Cold Storage Lessons From a Near-Miss
Security researchers point to this case as a renewed argument for treating exchange-held crypto as fundamentally different from self-custodied crypto. Bitcoin held on an exchange is only as safe as that exchange’s solvency and governance — a lesson borne out repeatedly from Mt. Gox to FTX. Hardware security modules and cold wallets remove counterparty risk but introduce a different failure mode entirely, as Howells’ landfill saga demonstrates: physical loss can be just as final as institutional collapse, and sometimes more so, since there’s no company or individual left to negotiate with.
For long-term holders, the practical takeaway from both cases is the same: document everything. Chris’s recovery only became possible because CEL Solicitors could reconstruct a clear paper trail of his original purchase and account ownership. Anyone holding crypto on an exchange, however small the amount, should retain purchase confirmations, account statements, and any correspondence indefinitely — it may be the only proof of ownership available if the platform later disappears.
Key Takeaways
- A British investor recovered 61 Bitcoin (£3.3 million) twelve years after the UK exchange Intersango collapsed, via legal action rather than technical recovery.
- The case succeeded because his private keys were held by identifiable former operators, not physically destroyed.
- James Howells’ separate, far larger landfill case remains unresolved after the UK High Court dismissed his claim in January 2025.
- Legal recovery of exchange-held crypto is increasingly viable with proper documentation and specialist solicitors.
- Cold storage and exchange custody carry fundamentally different risk profiles, and both can result in years-long recovery battles.
Frequently Asked Questions
Is it actually possible to recover Bitcoin lost on a collapsed exchange?
Yes, if the private keys still exist and are held by identifiable individuals or entities. Recovery in these cases is typically a legal process involving documentation of ownership rather than a technical hack or password crack.
How is this different from the James Howells landfill case?
Howells’ hard drive containing his private keys was physically discarded and is believed to be buried in a landfill; his keys are not held by any accessible third party, making his case a physical retrieval problem rather than a legal ownership dispute.
What should I do if I think I have crypto trapped in a defunct exchange?
Gather all historical records — account statements, purchase confirmations, correspondence — and consult a solicitor or firm specializing in digital-asset recovery to assess whether legal action against former operators is viable.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


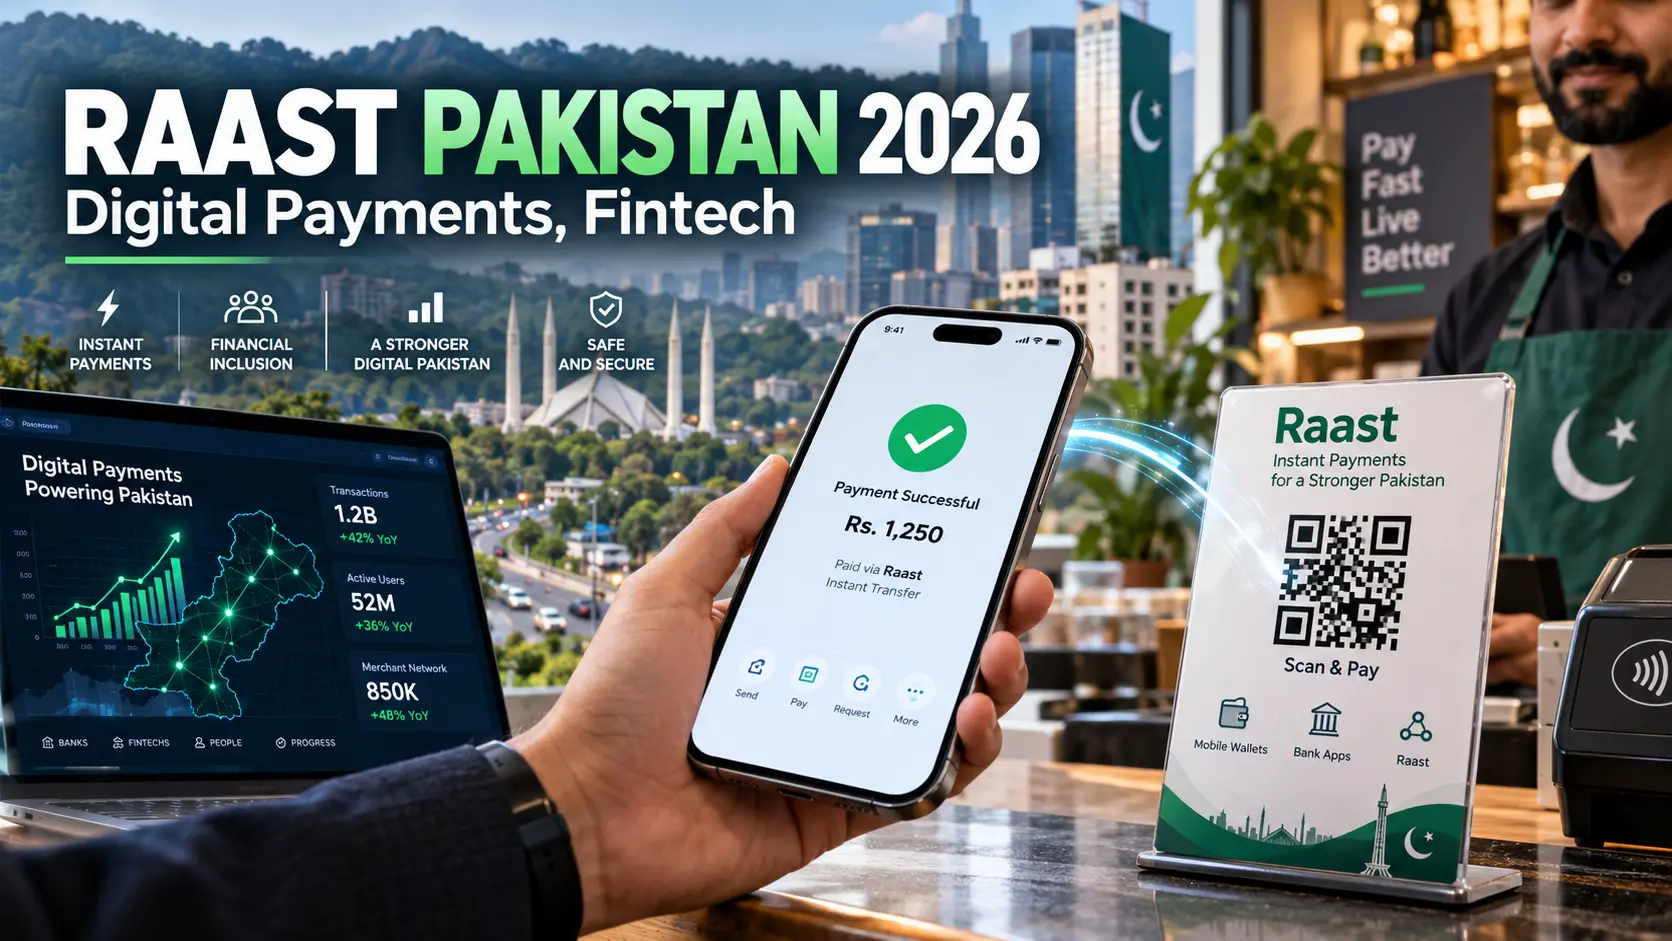
Understand Raast, QR payments and Pakistan’s digital-rupee debate. See what works now, what remains unverified and how merchants can reduce cash costs.
Key Takeaways
- The SBP’s payment-system publications include an FY2025–26 annual review announced on 6 October 2026, providing a formal basis for tracking digital adoption.
- Raast supports instant-payment use cases and domestic merchant collection; that does not mean a universally available Pakistani retail central-bank digital currency has launched.
- The SBP announced financial-inclusion index results on 7 October 2026; access and actual usage should be treated as different measures.
- For shops and households, transparent fees, fraud protection, reliable acceptance and dispute resolution matter more than the label cashless.
A shopkeeper in Rawalpindi may receive dozens of electronic transfers in one day and still prefer cash because he cannot reconcile the payments quickly at closing time. That tension explains the promise and the limits of Raast Pakistan 2026. A modern payment network can move money rapidly, but it does not automatically fix weak accounting, cybercrime or trust between merchants and customers.
Pakistan’s digital ecosystem now includes bank applications, e-money wallets, card terminals and Raast payment services. Meanwhile, the idea of a digital rupee attracts attention that sometimes confuses an existing transfer system with a hypothetical new form of central-bank money. The distinction matters. Here is how the technologies work, what the current evidence shows and what would make digital adoption useful for ordinary businesses rather than another regulatory slogan.
What is Raast Pakistan 2026, and how does it work?
Raast is a payment infrastructure system designed to allow eligible financial institutions and users to move money quickly. It supports different services, including person-to-person transfers and merchant payments as supported by participating institutions. It is not itself a bank account or a digital token that users can hold independently of their payment provider.
A customer typically interacts through a banking or participating payments application. The service connects to the regulated payment system; the money moves between accounts under the rules of the participating financial institutions. Merchant QR acceptance can simplify collection when the payer and receiver have compatible services and usable connectivity.
The State Bank’s payments-review reports are the source to consult for payment volumes, value and user adoption. The regulator announced its FY2025–26 Annual Payment Systems Review on 6 October 2026, and the report period should not be confused with the current FY2026–27 first quarter.
The difference between a payment rail and an account
A rail is the infrastructure that transmits and settles a payment instruction. An account stores a customer’s legally recognised balance. A QR code typically provides the recipient information that the application uses to initiate a payment; it is not proof by itself that the merchant has been paid. Sellers should confirm the transaction inside their own provider’s authenticated interface.
How far has digital adoption actually gone?
Digital retail transactions have grown significantly within Pakistan’s regulated banking and payment ecosystem. The SBP quarterly and annual publications document that growth across mobile applications, electronic-money institutions, internet banking and merchant payments. But a crucial statistical caveat often disappears from headlines: transactions outside the formal banking system are not necessarily counted in those reported digital-versus-cash shares.
That means a statement such as ‘most bank-channel retail payments are digital’ cannot be rewritten as ‘most spending in Pakistan is digital’. A vegetable purchase made with physical cash, an undocumented informal loan or a family payment outside participating institutions may not appear in the denominator.
| Measure | What it indicates | What it cannot prove |
|---|---|---|
| Digital retail transaction count | Formal electronic payments processed | Total cash spending nationwide |
| Digital transaction value | Rupee amount passing through recorded channels | Number of unique households |
| Registered users | Access or enrolment at an institution | Regular active use |
| Merchant QR registrations | Potential acceptance points | Payments successfully completed |
| Complaints or fraud losses | Some consumer-protection risks | All incidents, including unreported fraud |
The SBP financial-inclusion announcement of 7 October 2026 reinforces the importance of distinguishing having access to financial services from using them reliably. The stronger policy question is whether more people can pay and be paid at a lower real cost with fewer unresolved disputes.
Why do small businesses still rely on cash?
Cash has no app login, does not require battery power and can be accepted by a customer who lacks a smartphone. Those are genuine advantages for a rural vendor or a small urban business. Cash also carries risks: theft, miscounting, travel time, expensive physical handling and a limited audit trail.
Digital acceptance introduces a different cost set. A merchant needs an account or wallet, working connectivity, a trained employee and a reliable way to verify transactions. Some payments involve provider fees or settlement issues. A shopkeeper may also fear customer chargebacks or scams that impersonate an approved payment notification.
The correct question is therefore not ‘How can cash be abolished?’ but ‘Which payments are safer and cheaper when digitised?’ A business with repetitive supplier payments may benefit from electronic records even if small over-the-counter sales remain mixed.
The World Bank framework for Pakistan links stronger private-sector conditions to inclusion and productivity. For merchant payments, adoption should be judged by practical saved time, lower cash-handling loss and better access to formal finance, rather than installation targets alone.
Is Pakistan launching a digital rupee, and is it the same as Raast?
A central-bank digital currency (CBDC) would be a form of digital central-bank money governed by a defined legal and technical design. A wallet balance held with a commercial provider and a payment transfer using Raast are different things. Neither becomes a retail CBDC simply because a phone screen shows rupees.
Policy debate and exploration are not equivalent to a public rollout. The SBP press-release record and official economic-data and operations portal are appropriate sources for verified details of any pilot, eligibility, licensing or public launch. In this research, a generally available retail digital rupee as of 19 October 2026 was not independently verified; this article therefore does not present one as operating.
A digital rupee would raise policy questions beyond payment speed: privacy, offline access, fraud liability, bank funding, transaction limits and compatibility with existing accounts. The eventual design could matter more than its name. For example, a system without practical safeguards for stolen phones might exclude users who need easy redress.
Raast already solves a different problem: getting authorised payment instructions between participating institutions. Its performance can be evaluated now without assuming the future architecture of central-bank digital money.
What are the risks of a more digital financial system?
Payment fraud can move as quickly as legitimate money. Criminals may impersonate banks, send false payment screenshots or persuade a user to reveal a PIN. Shop employees sometimes release goods before the actual credit appears in the authenticated merchant interface.
Consumer protection requires clear transaction confirmations, liability rules and accessible complaints. A fraud victim should be able to report an incident promptly and receive a tracking number. Data protection is equally important: a payment history should not become an unrestricted record available to unrelated businesses or agencies without lawful safeguards.
Operational resilience is another issue. During a network outage, a small merchant needs a practical fallback. Dependence on a single payment app or provider can create concentration risk. Merchants may benefit from more than one lawful acceptance option, while regulators should define common standards for security and interoperability.
The SBP regulatory announcements and payment-system reviews should be monitored for changing operating rules and fraud trends. A large transaction count is not a measure of trustworthiness unless the system can also show how failures are handled.
How can digital payments improve access to credit and tax compliance?
A business with consistent customer payments can create evidence of turnover. That evidence may help a responsible lender assess seasonality and repayment prospects. A new shop can begin with a simple daily record: opening cash, digital sales, refunds, supplier purchases and closing balance. When records match bank activity, the owner has a more credible business profile.
The SBP’s July 2026 SME definitions classify micro, small and medium firms by turnover for banking-regulatory purposes. Digital receipts could help corroborate turnover, but they do not automatically qualify the business for financing. The lender still has to examine profit margin, debt and expected cash flows.
A broader formal record can also make tax filings easier. Yet coercion without convenience can push small merchants toward avoidance. Start with inexpensive acceptance, understandable reporting and a fair correction process for mistaken records. The World Bank-supported FBR revenue reforms are relevant to the wider goal of increasing voluntary formal compliance.
For a household, digital transfers can help document rent or school fees. For a freelancer, domestic instant payments may make it easier to pay local subcontractors. Cross-border customer receipts, however, still require appropriate international settlement mechanisms and compliance.
What This Means for You
Merchant: Confirm a payment on your own banking or wallet application, not a customer screenshot. Reconcile digital receipts with sales daily and keep access credentials separate from ordinary employees’ devices where possible.
Household: Use strong account protection, never share one-time codes and record transaction references for payments that might later be disputed. Verify the recipient carefully before confirming a large transfer.
Freelancer: Use regulated cross-border receipt channels for foreign invoices and local digital rails for compliant domestic payments. Do not confuse a domestic Raast identifier with an international bank account.
Policymaker: Publish consistent measures of active use, merchant success rates, fraud complaints and outages. Include offline and low-connectivity consumers rather than treating app downloads as universal financial inclusion.
Raast is Pakistan’s instant-payment infrastructure connecting participating financial institutions and payment services for authorised transfers, including supported person-to-person and merchant-payment use cases. Customers access it through eligible banking or payment interfaces. It is not itself a separate bank account or a central-bank digital currency.
What to Watch Next
- 26 October 2026: The State Bank monetary-policy decision and any revision to its inflation assessment; verify any schedule change with the SBP.
- Early November 2026, exact release date to be confirmed: Pakistan Bureau of Statistics October inflation and merchandise-trade releases.
- Late October–November 2026, date not yet confirmed: Any IMF Executive Board announcement on the October staff-level agreement; staff agreement is not Board approval.
- Throughout FY2026–27: Updated SBP monthly balance-of-payments and remittance statistics; compare cumulative results rather than one month alone.
Frequently Asked Questions
What is Raast in Pakistan?
Raast is Pakistan’s instant-payment infrastructure connecting participating financial institutions and payment services for authorised transfers, including supported person-to-person and merchant-payment use cases. Customers access it through eligible banking or payment interfaces. It is not itself a separate bank account or a central-bank digital currency.
Is a digital rupee available to everyone in Pakistan in October 2026?
A generally available retail central-bank digital rupee was not independently verified from the official sources consulted as of 19 October 2026. Policy exploration and pilots should not be mistaken for a public launch. Use official SBP announcements for changes to legal status or availability.
Can a small shop receive money through Raast QR payments?
A shop can use supported merchant-payment services through a participating provider, subject to onboarding, eligibility and the provider’s current operating rules. Merchants should verify settlement in their authenticated app or account rather than accepting a screenshot as proof.
Will digital payments eliminate cash in Pakistan?
Not automatically. Cash remains useful where smartphone access, connectivity and digital literacy are limited. Digital channels can reduce some cash-handling costs, but consumers and businesses need choice, reliable fallback options and clear fraud protections. Bank-channel transaction statistics do not measure all cash spending nationwide.
Can Raast transaction history help a business get a loan?
A documented payment history may help demonstrate turnover when it is reconciled with genuine invoices and business expenses. It is not an automatic loan qualification. Banks still examine cash flow, profitability, debt obligations and applicable SBP rules.
Pakistan will become more digitally capable when a street vendor can accept a payment, verify it and resolve a mistake without specialist help. Raast is useful infrastructure. A future digital rupee may add something different. Neither deserves to be judged by the logo alone
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Social Security
Social Security $90 Payment Claims: What’s Real, What’s a Scam, and What Your 2027 COLA Could Be
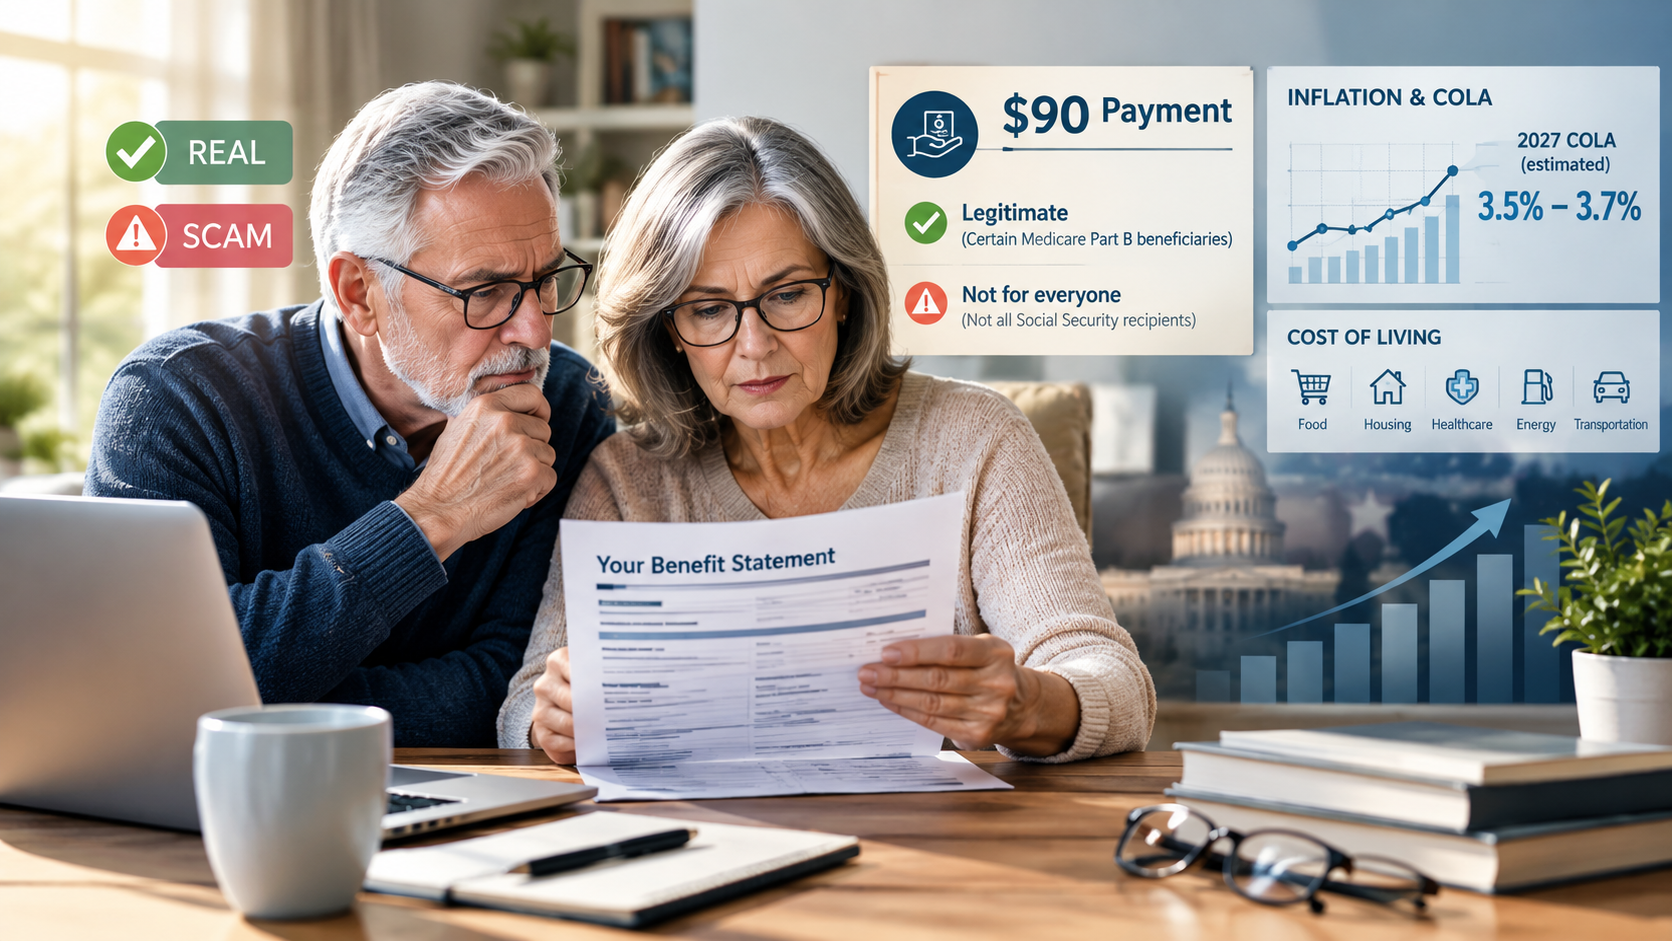
No official $90 Social Security payment exists. Here’s how to spot the claim, check your real payment date, and estimate the 2027 COLA increase.
Key Takeaways
- We found no official Social Security program that pays a $90 benefit. Viral claims about special Social Security payments have repeatedly been debunked as scams.
- Regular benefits follow a birth-date schedule, with most payments on a Wednesday. The Social Security Administration publishes the full calendar at ssa.gov.
- The 2026 cost-of-living adjustment was 2.8%. Forecasts for the 2027 COLA cluster around 3.2% to 3.6%, but the official figure is not announced until October 14, 2026.
- The Social Security Administration will never ask you to pay a fee or share your bank details to receive a benefit or adjustment.
Search Intent Summary
Readers searching for a “$90 Social Security payment” usually want one of three things: to know whether they’re owed money, when their next check arrives, or how much their benefit will rise. This guide answers all three and flags the claims that are not real.
Why the “$90 Payment” Claim Doesn’t Hold Up
We could not find any government announcement, Social Security Administration notice, or credible news report describing a $90 payment to beneficiaries. The pattern is familiar. Social Security scam posts frequently promise a sudden payment or boost, then send readers to a link that asks for personal information.
The same playbook has appeared before. In 2022, a Facebook post claimed people born before 1957 were getting a $1,728 boost to their checks. USA Today’s fact-check found that no such benefit had been announced, and the promoted page was a non-government site. PolitiFact reached the same conclusion, and the Social Security Administration told reporters to check its website for accurate information.
In 2024, a rumored $600 increase spread online. The Social Security Administration’s Office of the Inspector General warned that people were seeking personal information in exchange for a cost-of-living adjustment that does not work that way.
If you saw a $90 claim, ask three questions. Does it appear on ssa.gov? Does it require you to pay a fee, enter your Social Security number, or click a link to “claim” money? Is it described by a news outlet that cites the agency directly? If the answer to the first and third is no, or the second is yes, treat it as a scam.
The Social Security Administration’s scam awareness page lists the warning signs. Legitimate contact from the agency is limited, and it never threatens you or demands payment by gift card or wire transfer.
How Your Regular Payment Date Works
Most people receive their benefit on a schedule tied to their birth date. Social Security pays on the second, third, or fourth Wednesday of the month:
- Birth dates from the 1st to the 10th: second Wednesday
- Birth dates from the 11th to the 20th: third Wednesday
- Birth dates from the 21st to the 31st: fourth Wednesday
Two groups follow different timing. People who began receiving benefits before May 1997 are paid on the 3rd of each month. People who receive both Social Security and Supplemental Security Income are also paid on the 3rd, while SSI alone is paid on the 1st.
When a payment date falls on a weekend or federal holiday, payment comes on the previous business day. Some months have no regular payment in the normal sense because the schedule shifts. Check your exact dates in your my Social Security account rather than relying on a third-party calendar.
If your payment is late, the agency suggests waiting three business days before you report it. Most beneficiaries now receive direct deposit, and the Social Security Administration no longer mails checks to most new recipients.
The 2027 COLA: What to Expect
The cost-of-living adjustment is the one increase that does reach every beneficiary’s check. The Social Security Administration calculates it from the CPI-W, an inflation measure for wage earners and clerical workers. The agency compares the average CPI-W for July, August, and September with the same three months a year earlier.
For 2026, the adjustment was 2.8%. Forecasts for 2027 have moved in a narrow range this year. The Committee for a Responsible Federal Budget projected 3.2%, and The Senior Citizens League projected 3.6% in its latest update, down from 3.8% earlier in the summer.
To see what those numbers mean in dollars, take the average retirement benefit of $2,086 reported for July 2026. A 3.6% increase would raise it by about $75 a month, to roughly $2,161. A 3.2% increase would add about $67 a month.
Those are estimates. Official figures become final only after the September inflation data is released, which means the 2027 COLA could still shift. The agency announces the official figure on October 14, 2026, and that announcement is the number to plan around.
What Could Change Your Check
The COLA is not the only factor. Three other items commonly affect what you receive.
Medicare Part B premiums are usually deducted from Social Security benefits, so a premium increase can offset part of a COLA. Check the Medicare announcement alongside the COLA.
Federal income tax may apply to part of your benefit if your combined income crosses certain thresholds. Those thresholds are set in law and are not indexed to inflation in the same way.
Overpayments and withholding changes also affect the net amount. If the agency tells you that you were overpaid, it typically recovers the money through reduced future payments. Contact the agency if you believe a notice is wrong.
A Practical Checklist
Start by logging into your my Social Security account to confirm your payment date, deposit method, and mailing address. Set up deposit alerts from your bank if you want an early warning when a payment posts.
Compare any unexpected payment offer against ssa.gov before you act. If a message asks for your Social Security number, bank login, or a payment to “release” funds, stop and contact the agency directly through its official number or website.
After the October 14 COLA announcement, use the new figure to update your household budget. Expect the increase to appear in your January 2027 payment.
Future Outlook
Social Security will keep producing these claims for as long as there is money and a large audience to exploit. The real benefit changes will be announced through official channels, with the COLA the most predictable of them. Program financing and any changes to benefit formulas are subject to ongoing policy debate, so watch the agency’s own announcements rather than secondhand summaries.
Frequently Asked Questions
Is there a $90 Social Security payment?
We could not find any official Social Security program paying a $90 benefit. Claims of special payments, boosts, or stimulus-style checks have repeatedly been debunked. Check ssa.gov or contact the agency directly before acting on any offer.
When will I get my Social Security payment?
Most beneficiaries are paid on the second, third, or fourth Wednesday, based on birth date. People who started before May 1997 and those receiving both Social Security and SSI are paid on the 3rd. Your exact date appears in your my Social Security account.
When is the 2027 COLA announced?
The Social Security Administration will announce the 2027 cost-of-living adjustment on October 14, 2026. Forecasts currently cluster between 3.2% and 3.6%, but the official figure may differ.
How do I avoid Social Security scams?
Never pay a fee to claim a benefit, and never share your Social Security number or bank details with someone who contacted you unexpectedly. Verify any claim on ssa.gov, and report suspicious contact through the agency’s scam reporting channels.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
A business sitting on $100,000 of unpaid invoices with 60-day payment terms isn’t actually short on revenue — it’s short on timing, and fast invoice factoring exists specifically to close that gap without taking on debt.
Unlike a traditional business loan, invoice factoring isn’t borrowing at all: it’s selling your unpaid invoices to a factoring company at a discount in exchange for immediate cash, often within 24 to 48 hours. For businesses with long customer payment cycles — staffing agencies, trucking companies, manufacturers, government contractors — this speed can be the difference between making payroll and missing it.
This guide covers exactly how fast invoice factoring works, what it actually costs once every fee is accounted for, and how to evaluate a factoring company before signing an agreement.
How Fast Invoice Factoring Works
The mechanics are straightforward, but the details in the agreement determine whether it’s a smart short-term financing tool or an expensive drag on margins.
Key takeaway: Factoring companies typically advance 70% to 90% of an invoice’s value immediately, then release the remaining balance — minus fees — once your customer pays in full. The “fast” part of fast invoice factoring refers to that initial advance, not the full resolution of the transaction.
Step-by-Step: How the Transaction Proceeds
- You deliver goods or services and issue an invoice to a creditworthy business customer.
- You sell the invoice to a factoring company, which evaluates your customer’s creditworthiness — not primarily yours — since they’re the ones ultimately responsible for payment.
- The factoring company advances a percentage of the invoice value, commonly 70% to 90%, often within 24 to 48 hours of approval.
- The factoring company collects payment directly from your customer according to the invoice’s original terms.
- You receive the remaining balance, minus fees, once your customer pays in full.
Recourse vs. Non-Recourse Factoring
Recourse factoring is generally cheaper but leaves repayment risk with your business if your customer never pays; non-recourse factoring costs more but shifts that default risk to the factoring company. Most small business factoring arrangements are recourse, making customer creditworthiness screening a critical part of choosing which invoices to factor.
Financial and Strategic Implications: What Fast Factoring Actually Costs
The advertised “factor rate” rarely tells the whole story. Total cost depends on the base fee, how long the invoice remains unpaid, and any additional charges layered on top.
| Cost Component | Typical Range | Notes |
|---|---|---|
| Base factoring fee | 1%–5% of invoice value per 30 days | The longer your customer takes to pay, the more this compounds |
| Advance rate | 70%–90% of invoice value upfront | Higher-risk industries or customers may see lower advance rates |
| Origination/setup fee | $150–$500, sometimes up to 1% of the advance | One-time cost with some providers |
| Monthly minimum fee | Varies by provider | Applies if factored volume falls below a contractual threshold |
| Wire/ACH transfer fee | Typically small, flat fee | Charged per advance in some agreements |
Expert insight: Some fast factoring providers structure fees on 30-day payment terms but charge additional increments for every extra 10–15 days the invoice remains outstanding — meaning a slow-paying customer can quietly turn a 2% fee into an effective 6% or more over 90 days. Always ask for the total cost at 30, 60, and 90 days before signing.
Why Speed Comes at a Premium
Fast invoice factoring providers that promise same-day or next-day funding typically charge toward the higher end of the fee range in exchange for expedited underwriting and same-day wire transfers. Businesses with predictable, high-volume invoicing can often negotiate meaningfully better rates than the advertised “starting at” figures by committing to a longer-term contract or higher monthly volume.
Industry Adoption Remains Relatively Niche — By Design
Invoice factoring isn’t the default financing choice for most small businesses, and that’s informative in itself: according to the 2023 Small Business Credit Survey, only about 2% of employer-based businesses used factoring on a regular basis. It tends to concentrate in industries with structurally long payment cycles — trucking, staffing, government contracting, and manufacturing — rather than serving as general-purpose working capital for every small business.
How to Choose the Right Fast Invoice Factoring Company
- Confirm the true total cost, not just the headline factor rate — request a full fee schedule including origination, monthly minimums, and long-payment-term increments.
- Ask whether the arrangement is recourse or non-recourse, and understand what happens if a factored customer fails to pay.
- Check for contract length and volume commitments — some providers require minimum monthly factoring volume or long-term contracts with early termination fees.
- Evaluate customer-facing collection practices — since the factoring company will contact your customers directly, an aggressive or unprofessional collections approach can damage your client relationships.
- Compare industry specialization — providers focused on your specific industry (trucking, staffing, manufacturing) often better understand typical payment cycles and price accordingly.
- Confirm actual funding speed with references, not just marketing claims, since “fast” funding timelines vary meaningfully between providers.
Key takeaway: The real cost comparison isn’t factoring versus a bank loan in the abstract — it’s the factoring fee versus the actual cost of the cash-flow gap it closes, whether that’s a missed early-payment discount from your own suppliers, a payroll shortfall, or a lost growth opportunity.
Future Outlook: Invoice Factoring Trends Through 2027
- Software-integrated factoring is expanding rapidly. More providers now sync directly with accounting platforms like QuickBooks, letting businesses select and factor individual invoices without manual paperwork, meaningfully compressing approval timelines.
- Rate compression continues among direct lenders. As more specialized, technology-driven factoring companies enter the market, some providers now advertise factoring fees starting as low as 0.8%, pressuring legacy factoring firms to become more competitive.
- Sector specialization is deepening. Trucking- and staffing-specific factoring providers continue to build out fuel-card integrations, payroll-funding add-ons, and other vertical-specific services beyond basic invoice advances.
- Non-recourse factoring demand is rising amid economic uncertainty, as businesses increasingly value shifting customer-default risk to the factoring company even at a higher fee, particularly when working with newer or less-established customers.
Frequently Asked Questions
How fast can I actually get funded through invoice factoring?
Many fast factoring providers advance funds within 24 to 48 hours of approving an invoice, though first-time setup with a new provider typically takes longer due to initial underwriting.
Does invoice factoring hurt my credit like a loan would?
Generally no. Because factoring is a sale of an asset rather than a loan, it typically doesn’t appear on your business credit report the way a traditional loan would, though this can vary by provider and structure.
What percentage of my invoice will I actually receive?
Most factoring companies advance 70% to 90% of the invoice value upfront, releasing the remaining balance — minus fees — once your customer pays.
Is invoice factoring based on my credit or my customer’s credit?
Primarily your customer’s. Because the factoring company is ultimately relying on your customer to pay the invoice, your customer’s creditworthiness matters more than your own business credit history.
What happens if my customer never pays the invoice?
It depends on whether your agreement is recourse or non-recourse. Under recourse factoring, your business remains responsible for the unpaid amount; under non-recourse factoring, the factoring company generally absorbs that risk.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Global Banking Trends 2026: Digital Banks, AI and Compliance

Gold vs US Dollar vs Bitcoin in 2026: Inflation Hedge Compared

How Global Interest Rates Affect Savings, Loans and Investments

How to Invest During High Inflation: A Global Guide

Best Global Stocks to Watch in 2026: Four Sectors to Research

Pakistan’s 2027 Growth Strategy: Exports, AI, Energy and Jobs

Pakistan Economy FY2027: IMF Reform, Debt and Recovery Outlook

Global Interest Rates 2027: Risks for Pakistan’s Rupee and Debt

Energy Shock 2026–2027: Oil, Gas and Pakistan’s Economy

World Trade 2027: Tariffs, Supply Chains and Pakistan Exports

AI Investment Boom 2026–2027: Can Pakistan Capture the Upside?

Global Economy 2026–2027: What Slower Growth Means for Pakistan

Why Global Inflation Is Rising Again in 2026, and What It Means for Pakistan

Raast Pakistan 2026: Digital Payments, Fintech

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

World’s Largest Economies: Ranking the Top Global Powers

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

SpaceX IPO 2026: History’s Biggest Stock Debut?

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Is AI a Stock Bubble in 2026? What the Data Shows

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025