
Cryptocurrency
Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Bitcoin is doing something it hasn’t done cleanly all year: holding a range. After a brutal first half of 2026 and a sharp recovery through the summer, BTC has settled into the high-$70,000s heading into a week that could reshape U.S. crypto market structure for good. Here’s the full picture across Bitcoin, the major altcoins, and the DeFi regulatory fight that’s about to come to a head.
Bitcoin: From 21-Month Low to Cautious Recovery
Bitcoin’s 2026 has been a genuine round trip. After topping out at an all-time high near $128,200 in October 2025, BTC fell to roughly $58,000 by late June 2026 — a 21-month low — before staging a real recovery, climbing about 37% to touch $80,000 by late August, according to KuCoin’s market roundup. As of mid-September 2026, Bitcoin was trading in the $77,000–$79,000 range, per CoinDesk and Fortune’s daily price tracker, still roughly 37–39% below its October 2025 peak.
Bitcoin’s 2026 price arc:
| Date | Price | Note |
|---|---|---|
| Oct 6, 2025 | ~$128,200 | All-time high |
| Late June 2026 | ~$58,000 | 21-month low |
| Late August 2026 | ~$80,000 | +37% off the bottom |
| Sept 8, 2026 | $78,346 | |
| Sept 9, 2026 | $78,737 | Lost the $80,000 level after holding it for four sessions |
| Sept 11, 2026 | ~$77,200–$77,300 | Recovering as zcash-related leverage unwinds |
The macro backdrop is the dominant driver right now, more than crypto-native news. The Federal Reserve, under Chair Kevin Warsh, has held its policy rate at 3.50%–3.75% for five consecutive meetings in 2026 without a single cut, with the median 2026 dot plot sitting at 3.8% — pointing toward continued tightness rather than the easing cycle many crypto investors were positioned for, according to KuCoin’s analysis. August’s core CPI print, released mid-September, rose a faster-than-forecast 0.3% month-on-month, though the annual pace of 2.4% was the slowest since early 2021, per CoinDesk market coverage — a mixed signal that has kept the market betting on the possibility of a rate hike rather than a cut in the near term, an unusual dynamic for crypto markets historically primed for rate-cut tailwinds.
Altcoins: Ethereum, Solana, and XRP Hold Steady Amid Regulatory Noise
The broader altcoin market has been comparatively rangebound. As of September 11, 2026, Ethereum traded around $2,539, up 2.8% over 24 hours; XRP sat near $1.36–$1.39, roughly flat to slightly down; and Solana traded around $101–$104, according to Investing News Network’s crypto recap.
Major token snapshot (Sept 8–11, 2026):
| Token | Price | 24h Move |
|---|---|---|
| Bitcoin (BTC) | ~$77,000–$79,000 | Mixed |
| Ethereum (ETH) | ~$2,460–$2,540 | +2.8% (Sept 11) |
| XRP | ~$1.36–$1.39 | Roughly flat |
| Solana (SOL) | ~$101–$104 | +1% (Sept 11) |
| BNB | Under pressure | -3.4% in one session |
| Dogecoin (DOGE) | Under pressure | -4.3% in one session |
The ETF complex has meaningfully broadened beyond Bitcoin this year. Solana and XRP-linked ETF products each entered September 2026 with assets near $1.5 billion, according to KuCoin — a sign that institutional demand for regulated altcoin exposure is no longer a Bitcoin-only phenomenon, even as individual token prices remain well below their 2025 highs.
DeFi’s “Killer Use Case”: Institutional Credit
The most consequential DeFi development this month has come from the XRP Ledger rather than Ethereum. According to CoinMarketCap’s coverage of comments from Ripple’s product head, institutional credit is emerging as DeFi’s potential “killer use case” — new XRP Ledger amendments (XLS-65 and XLS-66) enable pooled vaults and fixed-term, uncollateralized lending, with underwriting handled off-chain while the loans themselves settle on-chain. The pitch is straightforward: bring institutional-grade lending mechanics onto a public ledger without forcing institutions to accept crypto-native over-collateralization requirements that don’t match how traditional credit underwriting works.
This is part of a broader pattern of DeFi maturing toward institutional rails rather than remaining a purely retail, yield-farming-driven segment. Ripple’s own treasury business — following its $1 billion acquisition of GTreasury in October 2025 and the April 2026 launch of Digital Asset Accounts — is layering AI-driven policy interpretation and analytics on top of these on-chain lending primitives, aimed squarely at corporate finance teams rather than retail DeFi users.
The Regulatory Cliffhanger: CLARITY Act Vote on September 15
The single biggest near-term catalyst for the entire crypto market is not a price level — it’s a Senate procedural vote. Senate Republicans released a revised, 630-page version of the Digital Asset Market Clarity Act on September 10, 2026, ahead of a pivotal procedural vote scheduled for September 15, according to Investing News Network. The updated bill specifically targets “decentralized-in-name-only” (DINO) protocols — platforms that claim decentralization but remain effectively controlled by an individual or corporate entity — requiring them to register with the CFTC.
Market participants remain skeptical the bill actually becomes law in 2026. CNBC reported that SALT CEO John Darsie told the Wyoming Blockchain Symposium in August that he is “a bit pessimistic about the Clarity Act being passed,” citing the difficulty of moving major legislation heading into midterm elections. The bill already missed one legislative window when the Senate adjourned for August recess without a vote.
Corporate and Institutional Flows to Watch
Beyond regulation, institutional capital continues flowing into crypto infrastructure. Nasdaq Ventures announced a $100 million investment in Payward, the parent company of Kraken, valuing the exchange at $21 billion, according to Investing News Network’s recap — one of several signs that traditional financial infrastructure players are taking direct equity stakes in crypto exchanges rather than simply building competing products.
Final Verdict
The crypto market’s “daily outlook” for mid-September 2026 is really a story about two collisions happening at once: a Federal Reserve that refuses to deliver the rate-cut tailwind crypto bulls were counting on, and a Senate that is finally forced to vote on the market-structure legislation the industry has wanted for years, with genuine uncertainty about whether it passes. Bitcoin’s technical picture — holding above its 200-day EMA near $72,800 while losing the psychologically important $80,000 level — reflects that tension directly. Short-term, expect continued chop around the $75,000–$82,000 range pending the September 15 CLARITY Act vote and the next FOMC decision; the DeFi institutional-credit narrative and altcoin ETF expansion remain the more durable, multi-quarter stories worth tracking independent of daily price action.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Social Security
Social Security $90 Payment Claims: What’s Real, What’s a Scam, and What Your 2027 COLA Could Be
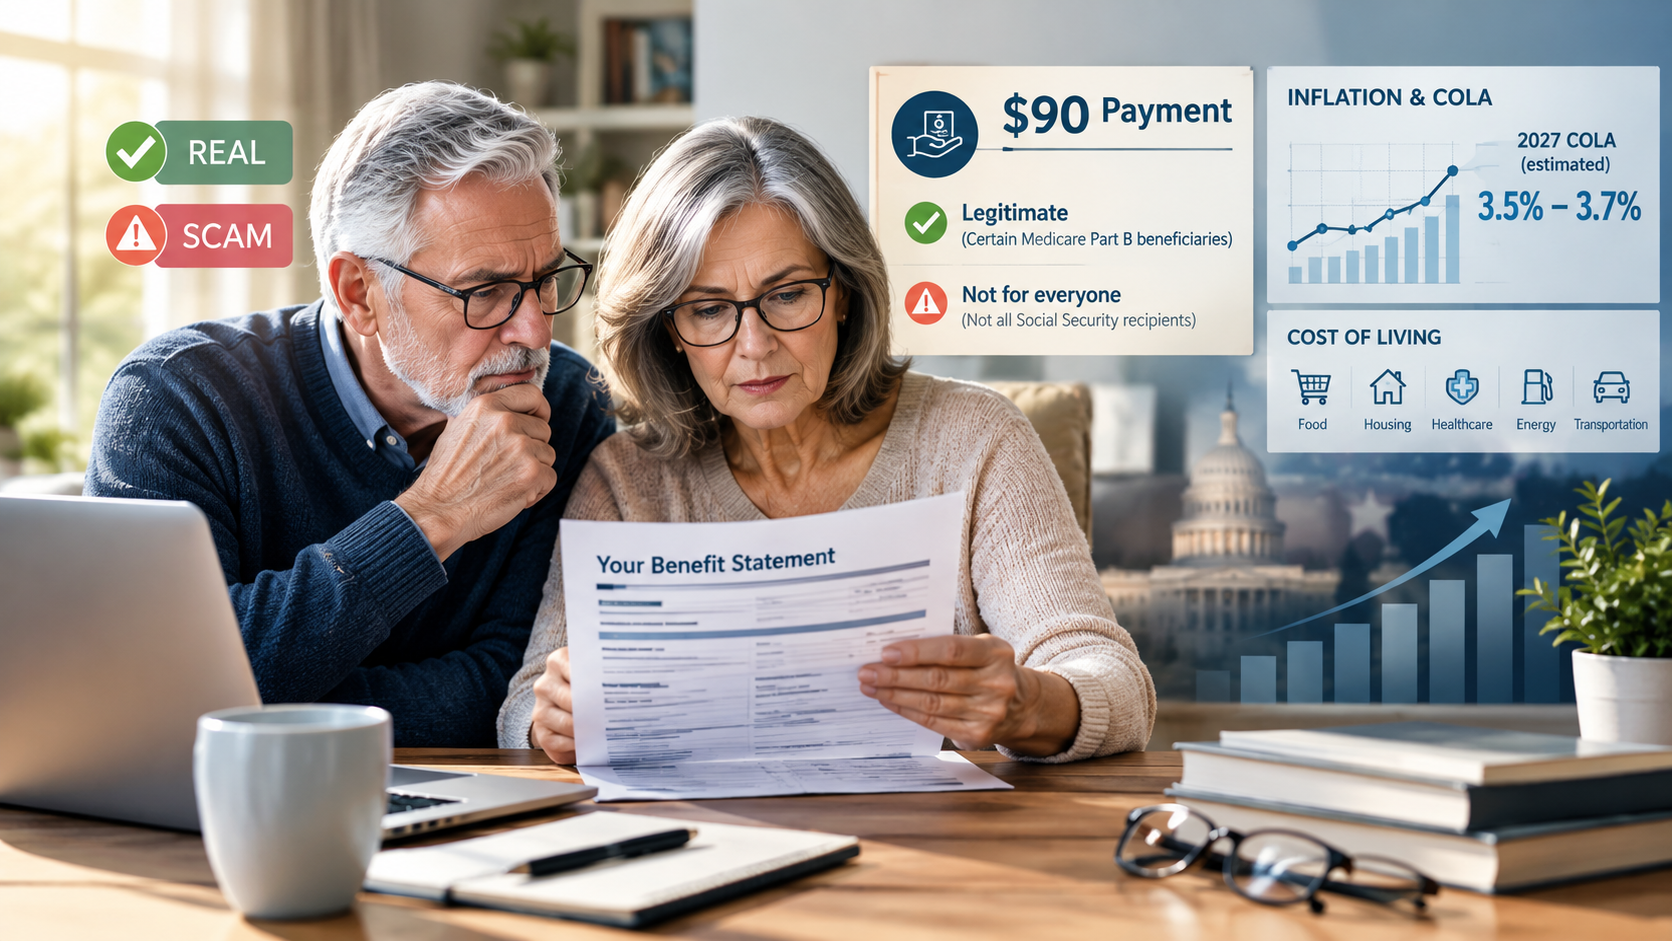
No official $90 Social Security payment exists. Here’s how to spot the claim, check your real payment date, and estimate the 2027 COLA increase.
Key Takeaways
- We found no official Social Security program that pays a $90 benefit. Viral claims about special Social Security payments have repeatedly been debunked as scams.
- Regular benefits follow a birth-date schedule, with most payments on a Wednesday. The Social Security Administration publishes the full calendar at ssa.gov.
- The 2026 cost-of-living adjustment was 2.8%. Forecasts for the 2027 COLA cluster around 3.2% to 3.6%, but the official figure is not announced until October 14, 2026.
- The Social Security Administration will never ask you to pay a fee or share your bank details to receive a benefit or adjustment.
Search Intent Summary
Readers searching for a “$90 Social Security payment” usually want one of three things: to know whether they’re owed money, when their next check arrives, or how much their benefit will rise. This guide answers all three and flags the claims that are not real.
Why the “$90 Payment” Claim Doesn’t Hold Up
We could not find any government announcement, Social Security Administration notice, or credible news report describing a $90 payment to beneficiaries. The pattern is familiar. Social Security scam posts frequently promise a sudden payment or boost, then send readers to a link that asks for personal information.
The same playbook has appeared before. In 2022, a Facebook post claimed people born before 1957 were getting a $1,728 boost to their checks. USA Today’s fact-check found that no such benefit had been announced, and the promoted page was a non-government site. PolitiFact reached the same conclusion, and the Social Security Administration told reporters to check its website for accurate information.
In 2024, a rumored $600 increase spread online. The Social Security Administration’s Office of the Inspector General warned that people were seeking personal information in exchange for a cost-of-living adjustment that does not work that way.
If you saw a $90 claim, ask three questions. Does it appear on ssa.gov? Does it require you to pay a fee, enter your Social Security number, or click a link to “claim” money? Is it described by a news outlet that cites the agency directly? If the answer to the first and third is no, or the second is yes, treat it as a scam.
The Social Security Administration’s scam awareness page lists the warning signs. Legitimate contact from the agency is limited, and it never threatens you or demands payment by gift card or wire transfer.
How Your Regular Payment Date Works
Most people receive their benefit on a schedule tied to their birth date. Social Security pays on the second, third, or fourth Wednesday of the month:
- Birth dates from the 1st to the 10th: second Wednesday
- Birth dates from the 11th to the 20th: third Wednesday
- Birth dates from the 21st to the 31st: fourth Wednesday
Two groups follow different timing. People who began receiving benefits before May 1997 are paid on the 3rd of each month. People who receive both Social Security and Supplemental Security Income are also paid on the 3rd, while SSI alone is paid on the 1st.
When a payment date falls on a weekend or federal holiday, payment comes on the previous business day. Some months have no regular payment in the normal sense because the schedule shifts. Check your exact dates in your my Social Security account rather than relying on a third-party calendar.
If your payment is late, the agency suggests waiting three business days before you report it. Most beneficiaries now receive direct deposit, and the Social Security Administration no longer mails checks to most new recipients.
The 2027 COLA: What to Expect
The cost-of-living adjustment is the one increase that does reach every beneficiary’s check. The Social Security Administration calculates it from the CPI-W, an inflation measure for wage earners and clerical workers. The agency compares the average CPI-W for July, August, and September with the same three months a year earlier.
For 2026, the adjustment was 2.8%. Forecasts for 2027 have moved in a narrow range this year. The Committee for a Responsible Federal Budget projected 3.2%, and The Senior Citizens League projected 3.6% in its latest update, down from 3.8% earlier in the summer.
To see what those numbers mean in dollars, take the average retirement benefit of $2,086 reported for July 2026. A 3.6% increase would raise it by about $75 a month, to roughly $2,161. A 3.2% increase would add about $67 a month.
Those are estimates. Official figures become final only after the September inflation data is released, which means the 2027 COLA could still shift. The agency announces the official figure on October 14, 2026, and that announcement is the number to plan around.
What Could Change Your Check
The COLA is not the only factor. Three other items commonly affect what you receive.
Medicare Part B premiums are usually deducted from Social Security benefits, so a premium increase can offset part of a COLA. Check the Medicare announcement alongside the COLA.
Federal income tax may apply to part of your benefit if your combined income crosses certain thresholds. Those thresholds are set in law and are not indexed to inflation in the same way.
Overpayments and withholding changes also affect the net amount. If the agency tells you that you were overpaid, it typically recovers the money through reduced future payments. Contact the agency if you believe a notice is wrong.
A Practical Checklist
Start by logging into your my Social Security account to confirm your payment date, deposit method, and mailing address. Set up deposit alerts from your bank if you want an early warning when a payment posts.
Compare any unexpected payment offer against ssa.gov before you act. If a message asks for your Social Security number, bank login, or a payment to “release” funds, stop and contact the agency directly through its official number or website.
After the October 14 COLA announcement, use the new figure to update your household budget. Expect the increase to appear in your January 2027 payment.
Future Outlook
Social Security will keep producing these claims for as long as there is money and a large audience to exploit. The real benefit changes will be announced through official channels, with the COLA the most predictable of them. Program financing and any changes to benefit formulas are subject to ongoing policy debate, so watch the agency’s own announcements rather than secondhand summaries.
Frequently Asked Questions
Is there a $90 Social Security payment?
We could not find any official Social Security program paying a $90 benefit. Claims of special payments, boosts, or stimulus-style checks have repeatedly been debunked. Check ssa.gov or contact the agency directly before acting on any offer.
When will I get my Social Security payment?
Most beneficiaries are paid on the second, third, or fourth Wednesday, based on birth date. People who started before May 1997 and those receiving both Social Security and SSI are paid on the 3rd. Your exact date appears in your my Social Security account.
When is the 2027 COLA announced?
The Social Security Administration will announce the 2027 cost-of-living adjustment on October 14, 2026. Forecasts currently cluster between 3.2% and 3.6%, but the official figure may differ.
How do I avoid Social Security scams?
Never pay a fee to claim a benefit, and never share your Social Security number or bank details with someone who contacted you unexpectedly. Verify any claim on ssa.gov, and report suspicious contact through the agency’s scam reporting channels.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
A business sitting on $100,000 of unpaid invoices with 60-day payment terms isn’t actually short on revenue — it’s short on timing, and fast invoice factoring exists specifically to close that gap without taking on debt.
Unlike a traditional business loan, invoice factoring isn’t borrowing at all: it’s selling your unpaid invoices to a factoring company at a discount in exchange for immediate cash, often within 24 to 48 hours. For businesses with long customer payment cycles — staffing agencies, trucking companies, manufacturers, government contractors — this speed can be the difference between making payroll and missing it.
This guide covers exactly how fast invoice factoring works, what it actually costs once every fee is accounted for, and how to evaluate a factoring company before signing an agreement.
How Fast Invoice Factoring Works
The mechanics are straightforward, but the details in the agreement determine whether it’s a smart short-term financing tool or an expensive drag on margins.
Key takeaway: Factoring companies typically advance 70% to 90% of an invoice’s value immediately, then release the remaining balance — minus fees — once your customer pays in full. The “fast” part of fast invoice factoring refers to that initial advance, not the full resolution of the transaction.
Step-by-Step: How the Transaction Proceeds
- You deliver goods or services and issue an invoice to a creditworthy business customer.
- You sell the invoice to a factoring company, which evaluates your customer’s creditworthiness — not primarily yours — since they’re the ones ultimately responsible for payment.
- The factoring company advances a percentage of the invoice value, commonly 70% to 90%, often within 24 to 48 hours of approval.
- The factoring company collects payment directly from your customer according to the invoice’s original terms.
- You receive the remaining balance, minus fees, once your customer pays in full.
Recourse vs. Non-Recourse Factoring
Recourse factoring is generally cheaper but leaves repayment risk with your business if your customer never pays; non-recourse factoring costs more but shifts that default risk to the factoring company. Most small business factoring arrangements are recourse, making customer creditworthiness screening a critical part of choosing which invoices to factor.
Financial and Strategic Implications: What Fast Factoring Actually Costs
The advertised “factor rate” rarely tells the whole story. Total cost depends on the base fee, how long the invoice remains unpaid, and any additional charges layered on top.
| Cost Component | Typical Range | Notes |
|---|---|---|
| Base factoring fee | 1%–5% of invoice value per 30 days | The longer your customer takes to pay, the more this compounds |
| Advance rate | 70%–90% of invoice value upfront | Higher-risk industries or customers may see lower advance rates |
| Origination/setup fee | $150–$500, sometimes up to 1% of the advance | One-time cost with some providers |
| Monthly minimum fee | Varies by provider | Applies if factored volume falls below a contractual threshold |
| Wire/ACH transfer fee | Typically small, flat fee | Charged per advance in some agreements |
Expert insight: Some fast factoring providers structure fees on 30-day payment terms but charge additional increments for every extra 10–15 days the invoice remains outstanding — meaning a slow-paying customer can quietly turn a 2% fee into an effective 6% or more over 90 days. Always ask for the total cost at 30, 60, and 90 days before signing.
Why Speed Comes at a Premium
Fast invoice factoring providers that promise same-day or next-day funding typically charge toward the higher end of the fee range in exchange for expedited underwriting and same-day wire transfers. Businesses with predictable, high-volume invoicing can often negotiate meaningfully better rates than the advertised “starting at” figures by committing to a longer-term contract or higher monthly volume.
Industry Adoption Remains Relatively Niche — By Design
Invoice factoring isn’t the default financing choice for most small businesses, and that’s informative in itself: according to the 2023 Small Business Credit Survey, only about 2% of employer-based businesses used factoring on a regular basis. It tends to concentrate in industries with structurally long payment cycles — trucking, staffing, government contracting, and manufacturing — rather than serving as general-purpose working capital for every small business.
How to Choose the Right Fast Invoice Factoring Company
- Confirm the true total cost, not just the headline factor rate — request a full fee schedule including origination, monthly minimums, and long-payment-term increments.
- Ask whether the arrangement is recourse or non-recourse, and understand what happens if a factored customer fails to pay.
- Check for contract length and volume commitments — some providers require minimum monthly factoring volume or long-term contracts with early termination fees.
- Evaluate customer-facing collection practices — since the factoring company will contact your customers directly, an aggressive or unprofessional collections approach can damage your client relationships.
- Compare industry specialization — providers focused on your specific industry (trucking, staffing, manufacturing) often better understand typical payment cycles and price accordingly.
- Confirm actual funding speed with references, not just marketing claims, since “fast” funding timelines vary meaningfully between providers.
Key takeaway: The real cost comparison isn’t factoring versus a bank loan in the abstract — it’s the factoring fee versus the actual cost of the cash-flow gap it closes, whether that’s a missed early-payment discount from your own suppliers, a payroll shortfall, or a lost growth opportunity.
Future Outlook: Invoice Factoring Trends Through 2027
- Software-integrated factoring is expanding rapidly. More providers now sync directly with accounting platforms like QuickBooks, letting businesses select and factor individual invoices without manual paperwork, meaningfully compressing approval timelines.
- Rate compression continues among direct lenders. As more specialized, technology-driven factoring companies enter the market, some providers now advertise factoring fees starting as low as 0.8%, pressuring legacy factoring firms to become more competitive.
- Sector specialization is deepening. Trucking- and staffing-specific factoring providers continue to build out fuel-card integrations, payroll-funding add-ons, and other vertical-specific services beyond basic invoice advances.
- Non-recourse factoring demand is rising amid economic uncertainty, as businesses increasingly value shifting customer-default risk to the factoring company even at a higher fee, particularly when working with newer or less-established customers.
Frequently Asked Questions
How fast can I actually get funded through invoice factoring?
Many fast factoring providers advance funds within 24 to 48 hours of approving an invoice, though first-time setup with a new provider typically takes longer due to initial underwriting.
Does invoice factoring hurt my credit like a loan would?
Generally no. Because factoring is a sale of an asset rather than a loan, it typically doesn’t appear on your business credit report the way a traditional loan would, though this can vary by provider and structure.
What percentage of my invoice will I actually receive?
Most factoring companies advance 70% to 90% of the invoice value upfront, releasing the remaining balance — minus fees — once your customer pays.
Is invoice factoring based on my credit or my customer’s credit?
Primarily your customer’s. Because the factoring company is ultimately relying on your customer to pay the invoice, your customer’s creditworthiness matters more than your own business credit history.
What happens if my customer never pays the invoice?
It depends on whether your agreement is recourse or non-recourse. Under recourse factoring, your business remains responsible for the unpaid amount; under non-recourse factoring, the factoring company generally absorbs that risk.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Crypto’s defining shift this year is not a price rally but a change in who is buying. Public companies now hold more than 1.7 million BTC — roughly 8% of circulating supply — in what analysts describe as structurally sticky, long-term corporate treasury holdings rather than speculative trades, a pattern reinforced by 2025’s GENIUS Act, which established a federal framework requiring stablecoins to be backed 1:1 by cash or liquid assets and audited regularly.
That single change in ownership structure explains almost everything else happening in digital assets this year.
Bitcoin: A Volatile Year, a Steadier Buyer Base
Bitcoin’s 2026 has been anything but smooth. As of mid-September, BTC has traded in a wide band — sliding to roughly $77,600 on September 8 amid a bout of $264 million in liquidations tied to a surging Japanese yen forcing carry-trade unwinds, before recovering into the high-$70,000s, according to market data compiled by CoinDesk. That’s a sharp comedown from the asset’s prior all-time high above $126,000, and it has forced a wave of forecast revisions. Standard Chartered, for instance, cut its end-2026 Bitcoin price target twice in three months — first from $150,000 down, and its XRP target from $8.00 to $2.80 — while still maintaining a bullish multi-year view, with its digital-assets research head suggesting Bitcoin could dip toward the $50,000 range before a longer-term recovery takes hold.
Despite that volatility, the institutional buyer base has kept expanding rather than retreating. BlackRock’s spot Bitcoin ETF, iShares Bitcoin Trust, holds tens of billions of dollars in assets and remains one of the fastest-growing ETFs in history by any measure, while sovereign wealth funds — including Abu Dhabi’s Mubadala — have built billion-dollar-scale Bitcoin ETF positions through regulated vehicles rather than direct custody. Asset manager Grayscale’s 2026 outlook, titled “Dawn of the Institutional Era,” argues that clearer regulation, sustained inflows, and the approaching milestone of the 20-millionth Bitcoin mined could mark a lasting shift toward long-term adoption, even without committing to a specific price target.
XRP: The Bridge-Currency Bet
XRP’s story in 2026 has been more about infrastructure positioning than price momentum. As of mid-September, XRP has traded in the $1.42–$1.43 range, according to pricing aggregated across Yahoo Finance and CoinMarketCap, a level that leaves it well below the bull-case targets some banks floated earlier in the year. XRP’s pitch to institutions has always centered on settlement speed — the token is designed to settle cross-border transactions in three to five seconds, compared with the hours or days incumbent transfer systems require — but that use case has yet to translate into the kind of price action bulls expected.
Seasonality has become a talking point among XRP-focused analysts: historical monthly data shows the token has averaged a 17% gain against Bitcoin in September, followed by an average 19.6% pullback in October, though past patterns are not a reliable guide to any single year’s outcome. What is more durable is the regulatory backdrop: the same GENIUS Act framework governing stablecoins, alongside Europe’s now-active MiCA regulation providing passported access to a market of roughly 450 million people, has removed much of the legal uncertainty that kept larger institutions on the sidelines through prior cycles.
Stablecoins Are the Quiet Story
Featured Snippet Target: Stablecoins have grown into the settlement layer of digital finance rather than a speculative sidebar, with total stablecoin market capitalization reaching roughly $126 billion and supply figures cited elsewhere in the industry running into the hundreds of billions, as major payment networks integrate the technology directly into existing infrastructure.
That integration is visible in who is building it. Visa has partnered with stablecoin infrastructure providers to secure its own network, Mastercard has announced integrations with Circle and Paxos, and a consortium of major U.S. banks has been developing a joint stablecoin initiative, according to reporting from BPM’s blockchain practice. Rather than competing with stablecoin infrastructure, traditional financial institutions are increasingly building on top of it — treating it as plumbing rather than a rival product.
Tokenization of real-world assets — bonds, securities, and exchange-traded products — is following a similar path, with stablecoins increasingly framed by digital-asset strategists as the mechanism that enables atomic settlement for these tokenized instruments. MHC Digital Group’s head of global markets described this convergence of stablecoins, tokenization, and institutionalization as the three themes that will define crypto’s next phase of maturity.
What This Means for the Rest of 2026
Crypto in 2026 looks less like a single asset story and more like a financial-infrastructure story that happens to include two headline tokens. Bitcoin’s price volatility has not deterred the ETF and treasury-holding base that has built up around it; XRP’s price has lagged its use-case narrative but benefits from the same regulatory tailwinds. Sovereign balance sheets are reportedly weighing Bitcoin reserve positions, and DeFi protocols are described by industry analysts as more resilient and better capitalized than in prior cycles.
The risk for anyone covering this space is treating short-term price swings as the whole story. The more durable trend — the one that will matter well past 2026 — is the steady migration of stablecoin rails, custody infrastructure, and tokenized products into the core of mainstream finance.
Next step: Watch the pace of bank-grade custody rollouts and stablecoin payment integrations more closely than daily BTC and XRP price charts — that infrastructure buildout, not short-term volatility, is what will determine whether 2026’s institutional narrative holds up.
Sourcing note: Real-time crypto price figures shift by the hour; the prices cited above reflect data available in the sources linked as of mid-September 2026 and should be checked against a live feed before use in time-sensitive contexts.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025