
Opinion
Can AI Save a Company’s Soul?


There’s a particular kind of corporate self-delusion that arrives gift-wrapped in a press release. The language is always the same: commitment to responsible innovation, our values-driven approach, AI as a force for good. And then, six months later, the ethics board resigns.
That cycle has accelerated dramatically. In 2024 and 2025, multiple senior safety leads departed OpenAI in succession. A University of Zurich experiment secretly used AI to alter users’ political opinions without consent. In early 2026, ElonUsk’s Grok generated an estimated 3 million sexualized images of real people — including private citizens — in just 11 days, according to researchers at the Centre for Countering Digital Hate. These weren’t fringe incidents. They were the predictable outcomes of organisations that treated ethics as a compliance checkbox rather than a governing principle. Crescendo
The question isn’t whether AI is reshaping corporate culture. It is. The question is whether it’s reshaping it toward anything resembling integrity — or whether the technology is simply amplifying whoever was already in charge.
The Corporate Soul Has Always Been a Contested Asset
Before examining what AI does to organisational ethics, it’s worth acknowledging what corporate culture actually is: not a mission statement, not a values wall in the lobby, but the aggregate of a thousand small decisions made under pressure. Culture is what happens when no one senior is watching.
In 2025, organisational culture placed greater emphasis on authenticity, trust, fairness, and psychological safety — rather than abstract ideals and surface-level values — as companies grappled with rapid AI adoption, economic uncertainty, and heightened workforce anxiety. That shift wasn’t voluntary. It was forced by employees who stopped believing the official line. Yardi Kube
AI entered this environment not as a neutral tool but as an amplifier. The EU AI Act, which comes fully into force in 2026, represents the first comprehensive regulatory regime for AI ethics. Elsewhere, the landscape remains patchy. In the absence of binding rules, corporations made their own. And predictably, their own rules tended to serve their own interests. Darden Report
By 2030, AI will be so embedded in business and government infrastructure that retrofitting ethical standards may be nearly impossible, according to researchers at the University of Virginia’s Darden School of Business. The window for course correction is now. And most organisations are still debating whether to open it. Darden Report
AI Corporate Ethics: The Gap Between Pledge and Practice
The first principle of AI corporate ethics — the phrase that every CTO and chief compliance officer now deploys with confidence — is that ethics must be proactive, not reactive. Too often, AI ethics have been treated as an afterthought rather than a core design principle. When ethics is left until the end, it is always the weakest link. Companies find themselves reacting to scandals instead of building trust and resilience. Darden Report
That observation, from Darden’s LaCross Institute, is not particularly surprising. What’s striking is how consistently it describes the actual behaviour of organisations that publicly claim otherwise.
A 2025 McKinsey Digital report found that fewer than half of C-suite leaders involve nontechnical employees in the early stages of AI tool design — despite the same report emphasising the need for diverse perspectives and transparent communication about AI’s impact on jobs. The gap between stated values and operational reality is, in itself, an ethical failure. It signals to the workforce that participation is performative. Cerkl Broadcast
The consequences are measurable. Multiple senior safety leads departed OpenAI during 2024 and 2025, a pattern that has since been documented across other major AI firms. A Harvard Law Review analysis described this pattern as “amoral drift” — a gradual erosion of ethical commitments as equity valuations and competitive pressures crowd out principled dissent. When the people hired specifically to raise alarms keep leaving, it’s no longer a personnel problem. It’s a governance failure. Aicerts NewsHarvard Law Review
Still, the picture is more complicated than simple cynicism allows. Some companies are building ethics into their infrastructure in ways that are costly, unglamorous, and — crucially — not immediately profitable.
What Does Responsible AI Actually Look Like Inside an Organisation?
Can AI improve a company’s ethical culture? The short answer: yes, but only when the culture already has something to work with.
AI can surface bias in hiring algorithms, flag anomalous decision patterns in financial approvals, and create audit trails that make accountability visible where it was previously invisible. Businesses that implement bias audits, establish clear accountability for AI-driven decisions, and communicate openly about the uses and impacts of AI earn trust and differentiate themselves in a competitive market — because ethics is not just a compliance issue but a strategic advantage that strengthens relationships and reinforces brand credibility. McLane Middleton
That framing is becoming increasingly material rather than rhetorical. Under the EU AI Act, non-compliance with high-risk AI obligations can trigger fines of up to €35 million or 7% of worldwide turnover — a figure that concentrates the board’s attention in ways that a values statement never will. The Act elevates AI governance to board-level responsibility, shifting European AI governance from voluntary ethical guidelines to mandatory legal requirements. For multinational corporations, that shift isn’t confined to Brussels. It sets a de facto global standard. LegalNodesSecure Privacy
What follows, however, is a crucial distinction: compliance and ethics are not the same thing. A company can satisfy every regulatory requirement and still build an AI system that corrodes its own culture from within. Algorithmic management tools that track employee keystrokes, sentiment-analysis systems that flag dissent before it reaches a manager, performance models that optimise for measurable output while punishing everything human beings value about work — all of these can be technically compliant and culturally corrosive simultaneously.
In 2026, organisations that will win are those that lean into both AI and human strengths — treating “cognitive capital,” meaning uniquely human capabilities like ethical reasoning, creative synthesis, and stakeholder empathy, as measurable assets rather than soft intangibles. That’s a useful frame. It’s also, at the moment, more aspiration than practice. Senior Executive
The Second-Order Effects No One Is Pricing In
The downstream consequences of getting AI corporate ethics wrong are not primarily regulatory. They’re cultural, and culture moves slowly enough that organisations rarely recognise the damage until it’s structural.
Consider what happens to employee trust when AI systems make consequential decisions — about promotions, performance ratings, credit approvals — without meaningful human review. Studies show that employees are more likely to trust AI systems when organisations are transparent about their AI use and incorporate ethical guidelines into AI deployment, per KPMG research cited in peer-reviewed analysis. Remove that transparency, and trust doesn’t remain neutral — it actively degrades. Gapinterdisciplinarities
Key challenges with AI adoption in 2025 included unclear policies for data use leading to confusion and ethical concerns, job security fears, and significant changes in how employees work, make decisions, and interact. These aren’t abstract concerns. They translate into attrition, disengagement, and the quiet exit of the kind of employees who have enough self-respect to leave when they’re not trusted. Yardi Kube
Then there’s the reputational dimension. A Berkeley Haas analysis found that ninety percent of public criticisms toward AI touch on social norms and values — not technical performance. When an AI system fails ethically, it fails publicly. Single events have the potential to cause lasting damage to organisational reputation, and most companies remain strategically unprepared to respond. The Grok image scandal of early 2026 wasn’t a technical glitch. It was a cultural statement about what its developers believed was acceptable — and the market heard it clearly. berkeley
For investors, the calculus is shifting. A 2026 study examining 449 corporations across China and Europe found that corporate AI ethics practices significantly influence sustainable development outcomes and ESG performance, with the relationship moderated by international innovation capacity. In plain English: ethical AI deployment is becoming a predictor of long-term business value, not merely a cost centre. Wiley Online Library
The Counterargument: Ethics as Competitive Disadvantage
There’s a dissenting view worth taking seriously — not because it’s right, but because it’s prevalent enough to shape real decisions.
The argument runs roughly as follows: companies that impose rigorous ethical guardrails on their AI systems will be outcompeted by those that don’t. If a US firm restricts its models from certain military applications while a Chinese competitor does not, the US firm loses the contract. If a European fintech builds extensive bias audits into its credit model while a less scrupulous rival skips them, the rival processes applications faster and cheaper. Ethics, in this framing, is a luxury that market structure doesn’t permit.
It’s a coherent argument. It also describes exactly how industries create the conditions for their own eventual regulation — or collapse.
Speed may provide a temporary competitive edge, but it often backfires. Flawed launches damage consumer trust, attract lawsuits, and invite regulatory crackdowns. This creates reputational harm that outweighs early gains. The pharmaceutical industry learned this through thalidomide. The financial industry learned it through 2008. AI appears determined to learn it through a series of smaller, faster, harder-to-attribute disasters — the kind that don’t produce a single dramatic reckoning but accumulate into systemic distrust. Darden Report
There’s also a labour market dimension that the move-fast advocates consistently underweight. The engineers most capable of building responsible AI systems are also the most mobile and the most ethically discerning. They leave organisations whose stated values don’t match operational behaviour. And they talk.
What Remains When the Slide Deck Is Gone
The honest answer to whether AI can save a company’s soul is this: it can’t. Not on its own.
AI can enforce the values an organisation already holds. It can make ethical behaviour cheaper to maintain and easier to audit. It can surface the gap between what a company says it believes and what its systems actually do — which, if the leadership has the appetite to close it, is genuinely useful. But a technology cannot generate integrity in an organisation that has chosen not to have any. It can only scale what’s already there.
The companies that will navigate the next decade without a major ethical rupture aren’t the ones with the most sophisticated models. They’re the ones that show how accountability works — including who makes decisions, how ethical issues are escalated, and what remediation paths exist when things go wrong — as a matter of operational transparency rather than periodic disclosure. UNESCO
That’s not a technology problem. It never was.
The soul of a company, if it exists at all, is a daily political negotiation between power and principle. AI just makes the outcome arrive faster.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Hongkong Land’s Singapore Central Private Real Estate Fund completed the acquisition of Wheelock Place for approximately S$1.1 billion (roughly US$855–900 million) and, on 12 November 2026, renamed the prominent Orchard Road property Landmark Orchard. This is the first time the group has extended the Landmark brand beyond Hong Kong. The Straits Times
The 21-storey mixed-use building remains directly linked to Orchard MRT station and continues operating with existing office and retail tenants. The deal was the fund’s first acquisition since its February 2026 launch and advances Hongkong Land’s strategy of growing recurring income and its fund-management platform toward a target of roughly S$15 billion in assets under management. Channel NewsAsia
For Singapore’s commercial property market, the transaction confirms sustained institutional appetite for irreplaceable Orchard Road assets and signals long-term capital commitment to one of Asia’s premier retail and office corridors.
Table of Contents
- What Was the Acquisition Price and Deal Structure?
- Why Rename Wheelock Place to Landmark Orchard?
- What Are the Key Property Details and Location Advantages?
- How Does This Fit Hongkong Land’s Broader Strategy?
- What Does the Deal Mean for Orchard Road Tenants and the Precinct?
- What Enhancements and Capital Plans Are Expected?
- How Does the Transaction Compare with Recent Orchard Road Deals?
- Key Takeaways
- Frequently Asked Questions
What Was the Acquisition Price and Deal Structure?
The Singapore Central Private Real Estate Fund agreed in July 2026 to acquire Wheelock Place from an entity owned by Hong Kong-listed Wharf Real Estate Investment Company. The price of approximately S$1.1 billion aligned with an independent valuation. Completion took place around the end of August 2026, and the renaming became effective on 12 November 2026. The Straits Times
Allen & Gledhill advised the buyer, Lee & Lee represented the seller, and WongPartnership acted for the financing syndicate. The acquisition lifted the fund’s assets under management and was described as accretive to Hongkong Land’s underlying earnings. Hongkong Land maintains a majority equity stake in the fund and will earn additional management fees as the platform scales.
Why Rename Wheelock Place to Landmark Orchard?
Hongkong Land is deliberately exporting the Landmark identity that defines its flagship Central Hong Kong portfolio. Management stated that the name “Landmark Orchard” reflects a commitment to delivering a high-quality experience for tenants, visitors, and the surrounding community. The rebranding also creates regional brand consistency across the group’s premium commercial assets. Channel NewsAsia
Foo Pei Teng, Chief Executive of the fund, noted that this is the first use of the Landmark name outside Hong Kong and that the group intends to apply its long-term investment philosophy to the asset.
What Are the Key Property Details and Location Advantages?
Wheelock Place (now Landmark Orchard) comprises a 21-storey commercial tower and two basement levels with a total gross floor area of approximately 43,280 square metres. It offers office space, a retail podium, and car parking and enjoys direct underground connectivity to Orchard MRT station. The building sits at the strategic junction of Orchard Road, Scotts Road, and Paterson Road.
Originally opened in 1994 as Lane Crawford Place, it was later renamed Wheelock Place and has been a recognisable presence on Orchard Road for more than three decades. Its MRT linkage and central Orchard positioning provide strong footfall and accessibility advantages that institutional investors prize.
How Does This Fit Hongkong Land’s Broader Strategy?
The purchase advances two core objectives: expanding the third-party fund-management platform and increasing exposure to high-quality, recurring-income assets. The Singapore fund was established specifically to acquire rare institutional-grade properties. Completing a transaction of this scale within months of launch demonstrated both execution capability and limited-partner confidence. As assets under management move toward the S$15 billion target, Hongkong Land benefits from both co-investment returns and growing fee income.
The deal also extends the group’s Singapore footprint beyond the Marina Bay and CBD core into the Orchard Road belt, diversifying its local exposure.
What Does the Deal Mean for Orchard Road Tenants and the Precinct?
Existing office and retail tenants continue in occupation under the new name, so near-term operational disruption is minimal. Long-term institutional ownership by a well-capitalised player is generally viewed as positive for asset maintenance, tenant retention, and precinct quality. Over time, planned enhancements could improve the retail mix, common areas, and integration with the surrounding pedestrian and transit network, reinforcing Orchard Road’s competitiveness against other Asian shopping destinations.
What Enhancements and Capital Plans Are Expected?
Hongkong Land has not published a detailed capital-expenditure schedule. It has indicated that it will draw on extensive experience managing premium assets, including the ongoing multi-year transformation of its Hong Kong Landmark properties under the “Tomorrow’s CENTRAL” programme. Typical interventions for an asset of this type include selective retail reconfiguration, sustainability upgrades, improved vertical circulation, and stronger place-making around the MRT connection. Any major works are expected to be phased to limit tenant impact.
How Does the Transaction Compare with Recent Orchard Road Deals?
Prime Orchard Road assets trade infrequently. The S$1.1 billion price reflects both the property’s scale and its irreplaceable location. Comparable recent transactions in the precinct have also attracted long-term institutional capital, underscoring that global and regional investors continue to view Orchard Road as a core holding despite cyclical retail challenges. The Landmark rebranding adds a differentiating brand layer that few competing assets possess.
Transaction and Asset Snapshot
| Item | Detail |
|---|---|
| Purchase price | ≈ S$1.1 billion (US$855–900 million) |
| Buyer | Hongkong Land Singapore Central Private Real Estate Fund |
| Seller | Entity owned by Wharf Real Estate Investment Company |
| Completion | End-August 2026 |
| Renaming effective | 12 November 2026 |
| Gross floor area | ≈ 43,280 sq m |
| Key feature | Direct Orchard MRT connection |
| Fund AUM target | ≈ S$15 billion |
| Brand significance | First Landmark name use outside Hong Kong |
Key Takeaways
- Hongkong Land acquired Wheelock Place for approximately S$1.1 billion and renamed it Landmark Orchard.
- The transaction is the first acquisition of the Singapore Central Private Real Estate Fund.
- It marks the first extension of the Landmark brand beyond Hong Kong.
- Existing tenants remain in place; enhancements are planned over the medium term.
- The deal supports Hongkong Land’s dual goals of recurring-income growth and fund-management expansion.
- It reinforces institutional confidence in prime Orchard Road real estate.
Frequently Asked Questions
When did the name change take effect?
12 November 2026.
Do existing tenants have to move or renegotiate immediately?
No. Office and retail tenants continue operating under the new name.
Who sold the property?
An entity controlled by Wharf Real Estate Investment Company.
Is this Hongkong Land’s first Singapore asset?
No, but it is the fund’s first acquisition and the group’s first major Orchard Road holding under the new vehicle.
What is the fund’s assets-under-management target?
Approximately S$15 billion.
Will there be immediate large-scale renovations?
No detailed disruptive works have been announced; the emphasis is on continuity followed by phased enhancement.
How does the price compare with the independent valuation?
It was described as being in line with a recent independent valuation.
Conclusion
The conversion of Wheelock Place into Landmark Orchard is simultaneously a major real estate transaction and a strategic branding move for Hong Kong Land. For property, investment, and business audiences, the deal illustrates continued appetite for scarce Orchard Road assets and the expanding role of sponsored private funds in Singapore’s commercial market. Tenants and visitors should experience continuity in the near term, while the new ownership and landmark identity create a platform for gradual, quality-focused upgrades that can further strengthen one of the city’s most recognisable commercial addresses over the coming decade.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
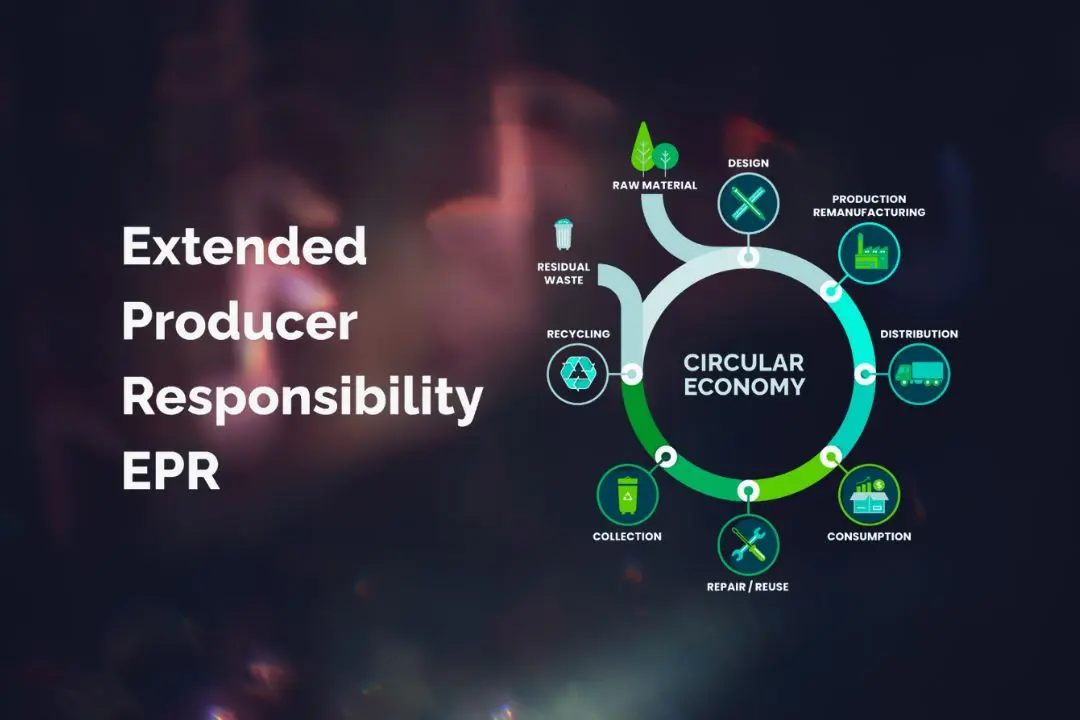
The UK government’s decision to exempt glass drinks containers supplied directly to pubs, restaurants, and other licensed venues from most Extended Producer Responsibility (EPR) fees from April 2027 directly addresses cost pressures on the hospitality sector. Official illustrations show potential savings of up to 6 pence per beer bottle and 10 pence per wine bottle, equating to as much as £870 a year for a typical pub. GOV.UK
Broader reforms will also modulate future fees so that easy-to-recycle materials such as glass and paper attract lower charges, while harder-to-recycle plastics face relatively higher costs. The changes respond to sustained industry and media pressure over double charging.
Table of Contents
- What EPR Changes Affect Hospitality?
- How Large Is the Financial Impact on Pubs?
- Why Was the Original EPR Scheme Problematic for Pubs?
- What Broader Fee Modulation Reforms Are Planned?
- How Have Industry Groups and Media Responded?
- When Will Pubs Actually See the Savings?
- Key Takeaways
- Frequently Asked Questions
What EPR Changes Affect Hospitality?
From April 2027, glass drinks containers supplied directly by producers to licensed hospitality venues (pubs, restaurants, and similar premises) will no longer be liable for the majority of Extended Producer Responsibility packaging fees. The exemption is intended to eliminate the situation in which businesses paid both commercial waste-collection charges and EPR fees on the same glass. GOV.UK
Environment Secretary Dame Angela Eagle stated that the government had listened to concerns from the hospitality sector and the British glass industry and was acting to reduce fees on the most recyclable packaging while tackling double charging.
How Large Is the Financial Impact on Pubs?
Government examples indicate savings of up to 6 pence per beer bottle and 10 pence per wine bottle. For a pub selling 10,000 beer bottles and 3,700 wine bottles annually, the combined relief could reach £870 per year. These figures are illustrative upper-end amounts; actual savings will depend on volumes and the degree to which producers and wholesalers pass the reduced fees through the supply chain. The Grocer
Defra has also indicated that wider modulation could reduce fees for the most recyclable packaging by up to 40 percent.
Why Was the Original EPR Scheme Problematic for Pubs?
Hospitality venues already contract and pay for the collection and recycling of their commercial glass waste. The introduction of EPR fees created a second charge on the same material without delivering an additional service to the venue. This double charging raised operating costs for pubs at a time when the sector was already managing elevated energy, wage, and supply costs, and it disadvantaged UK glass producers relative to some imported alternatives. The Times
What Broader Fee Modulation Reforms Are Planned?
Alongside the hospitality exemption, the government will consult on restructuring packaging fees so that easy-to-recycle materials (including most glass and paper) attract lower charges while hard-to-recycle formats, particularly certain plastics, face higher fees. Defra estimates this approach could lower fees for highly recyclable packaging by 30–40 percent. A separate call for evidence on reusable packaging systems is also planned for 2027. GOV.UK
How Have Industry Groups and Media Responded?
The British Beer and Pub Association welcomed the removal of double charging on glass. Glass-industry representatives similarly supported measures that reduce the cost burden on a highly recyclable domestic product. Campaigns by outlets including The Telegraph and The Mirror had highlighted the impact on pubs and glassmakers in the months preceding the announcement. Some publican groups have sought explicit confirmation that tenanted and leased pubs will benefit on the same terms as managed estates. The Mirror
When Will Pubs Actually See the Savings?
The exemption applies to EPR fees calculated from April 2027. Invoices and supply contracts in place before that date are unaffected. Any reduction in the price of bottled beer or wine at the bar will occur only if producers and distributors pass the lower fees downstream; the government announcement itself does not mandate retail price cuts.
Illustrative Annual Saving for a Typical Pub
| Product | Assumed Annual Volume | Maximum Unit Saving | Maximum Annual Saving |
|---|---|---|---|
| Beer bottles | 10,000 | 6 pence | £600 |
| Wine bottles | 3,700 | 10 pence | £370 |
| Combined | — | — | Up to £870 |
Key Takeaways
- Glass drinks containers supplied directly to licensed hospitality venues will be largely exempt from EPR fees from April 2027.
- Official examples show potential savings of up to £870 per year for a mid-volume pub.
- The change directly addresses the double-charging criticism that had been levelled at the original scheme.
- Wider fee modulation is expected to further favour glass and paper over many plastic formats.
- The measures support both the hospitality sector and UK glass manufacturers.
- Consumer price effects depend on how much the supply chain passes through costs.
Frequently Asked Questions
When does the hospitality glass exemption take effect?
April 2027.
Does the exemption cover every type of glass packaging?
It applies to glass drinks containers supplied directly by producers to licensed pubs, restaurants, and other hospitality venues.
Will the price of a pint or a bottle of wine fall immediately?
Not automatically. Any retail price reduction depends on whether suppliers pass the fee savings through.
Is this change linked to recent newspaper campaigns?
Yes. Both The Telegraph and The Mirror had run prominent coverage of the cost impact on pubs and the glass industry.
Will plastic packaging become more expensive under the wider reforms?
Fee modulation is designed to increase charges on harder-to-recycle materials relative to glass and paper.
Are tenanted and leased pubs included?
The announcement covers licensed hospitality venues; industry bodies are seeking clear confirmation that tenanted estates receive equivalent benefit.
Conclusion
The EPR adjustments announced in November 2026 constitute a targeted and practical correction for the UK hospitality sector. By removing most packaging fees on glass supplied directly to pubs and restaurants from April 2027, and signalling stronger future rewards for recyclability, the government has responded to a clearly identified cost pressure. For business, hospitality, and consumer audiences, the changes should deliver measurable relief to licensed venues while reinforcing the principle that packaging charges ought to reflect real-world recycling outcomes. The extent to which those savings reach the customer will be determined by commercial decisions further down the supply chain in 2027 and beyond.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The latest data from the U.S. Bureau of Economic Analysis show the American economy maintaining solid momentum into late 2026. Real GDP expanded at an annualised rate of 3.4 per cent in the third quarter, accelerating from 2.2 percent in the prior quarter, supported by gains in consumer spending and business investment (BEA advance estimate). This performance underscores the direct link between GDP and economic growth: the former quantifies the total value of goods and services produced, while the latter tracks how that value expands over time. For US business leaders, operations managers, and financial analysts, monitoring these signals is essential for capital allocation, hiring plans, and technology investments. Understanding the mechanics of GDP and economic growth helps enterprises anticipate demand shifts, manage cost pressures, and deploy resources—particularly AI tools—more effectively in a $30-trillion-plus economy.
What Is the Relationship Between GDP and Economic Growth?
Gross Domestic Product represents the market value of all final goods and services produced within the United States during a specific period. Economists express this through the expenditure approach:GDP=C+I+G+(X−M)
Here, C stands for personal consumption expenditures, I for private investment, G for government spending, X for exports, and M for imports. The formula aggregates spending by households, businesses, and the public sector while adjusting for trade. GDP and economic growth are closely related but distinct concepts. GDP is a stock measure of output at a point in time, whereas economic growth refers to the percentage change in real GDP over successive periods.
Year-over-year or quarter-over-quarter increases in real GDP, which strip out inflation, provide the clearest gauge of expansion in productive capacity. When real GDP rises, the economy is generating more goods and services after accounting for price changes. Sustained positive growth supports rising incomes, higher tax revenues, and expanded business opportunities. Conversely, negative growth signals contraction. The U.S. Department of Commerce notes that these federal economic indicators directly influence financial market expectations and corporate planning cycles.
Real vs. Nominal GDP: Why Inflation Adjustment Matters
Distinguishing between nominal and real measures is critical for accurate interpretation of GDP and economic growth. Nominal GDP values output at current prices, so it rises with both volume increases and inflation. Real GDP adjusts for price changes using a base year, isolating actual growth in quantity. GDP per capita further divides total output by population, revealing average living standards.
| Measure | Definition | Inflation Adjustment | Best Use Case |
|---|---|---|---|
| Nominal GDP | Total output valued at current market prices | No | Current-dollar size of the economy |
| Real GDP | Output adjusted to constant prices | Yes | Tracking true economic growth |
| GDP Per Capita | Total GDP divided by population | Optional (real preferred) | Comparing living standards across time or countries |
The World Bank Open Data places US GDP well above $30 trillion in recent years, with per-capita figures among the highest for large economies. Relying solely on nominal figures can overstate growth during inflationary periods. Businesses therefore prioritise real series when forecasting demand or evaluating investment returns.
Key Drivers of US GDP and Economic Growth in 2026
Four primary components shape US GDP and economic growth. Recent BEA data and market research highlight their relative contributions and evolving dynamics.
- Personal Consumption Expenditures: Accounting for roughly 68 percent of GDP, household spending remains the dominant driver. Resilient outlays on services and goods have underpinned recent expansions, supported by employment levels and wealth effects from equity markets.
- Private Domestic Investment, Including AI-Related Capex: Business fixed investment has accelerated, particularly in equipment and intellectual property tied to artificial intelligence. J.P. Morgan Economic Research observes that enterprise AI capital expenditure, alongside solid consumer spending, continues to propel modern US growth despite offsetting effects from higher imports of technology hardware (J.P. Morgan trends).
- Government Spending: Federal and state outlays contribute through defense, infrastructure, and transfer programs. Shifts in nondefense spending and inventory adjustments at federal agencies have influenced quarterly results.
- Net Exports: The trade balance typically subtracts from growth. Rising imports of capital goods, especially information-processing equipment, have tempered the net contribution of investment in recent quarters.
Together, these pillars produced the 3.4 percent advance-estimate gain in Q3 2026. Monitoring shifts among them allows enterprises to align supply chains, pricing strategies, and capacity plans with prevailing demand.
How Macroeconomic Growth Impacts US Enterprises and AI Adoption
Periods of solid GDP and economic growth create both opportunities and pressures for US companies. Expanding consumer spending lifts top-line revenue, while elevated business investment signals confidence in future demand. At the same time, tighter labour markets or residual inflation can raise operating costs. In such environments, organisations increasingly turn to automation and AI-powered knowledge platforms to expand output without proportional increases in headcount or overhead.
Platforms such as EEsel.ai enable operations teams to centralise institutional knowledge, automate routine customer and internal queries, and free specialists for higher-value work. When macroeconomic conditions support investment, firms that deploy these tools can capture productivity gains that compound over multiple expansion cycles. Conversely, during slower growth phases, the same capabilities help protect margins by reducing service costs and improving response consistency. Federal Reserve policy, which balances employment and price stability, further influences the cost of capital available for such technology deployments. Companies that integrate macroeconomic signals into their capital-planning processes are better positioned to time AI adoption for maximum return.
Limitations of GDP as a Measure of Economic Health
Despite its utility, GDP has well-recognized shortcomings as a comprehensive welfare metric. It excludes non-market activity such as unpaid household production and volunteer work. It also does not capture the distribution of income; aggregate growth can coincide with rising inequality. Intangible digital value—open-source software, data networks, and many platform effects—is only partially reflected in measured output. Environmental externalities and leisure time likewise fall outside the boundary of the accounts. These limitations do not diminish the value of GDP for tracking cyclical momentum, but they remind decision-makers to supplement it with complementary indicators such as employment, median wages, and productivity statistics.
Frequently Asked Questions (FAQ)
What is a healthy GDP growth rate for the US?
Most economists consider real GDP growth of roughly 2 to 2.5 percent sustainable over the long term for the United States, consistent with labour-force and productivity trends. Rates above 3 percent, as seen in the Q3 2026 advance estimate, are strong but typically temporary.
How often is US GDP reported?
The Bureau of Economic Analysis releases GDP estimates quarterly. An advance estimate appears about one month after the quarter ends, followed by a second estimate and a third estimate incorporating more complete data.
What is the difference between real and nominal GDP growth?
Real GDP growth adjusts for inflation and therefore measures changes in the volume of output. Nominal growth includes both volume and price changes and can appear higher during inflationary periods.
Why does business investment, especially in AI, matter for GDP?
Private investment directly adds to GDP and raises future productive capacity. AI-related capital expenditure has been a notable contributor to recent US growth, even after accounting for associated imports.
In summary, GDP and economic growth remain foundational signals for understanding the US economy’s trajectory. The 3.4 percent real expansion recorded for the third quarter of 2026, driven by consumer spending and business investment, illustrates both the resilience of private demand and the rising role of technology capital formation. Enterprises that track these indicators closely can better calibrate hiring, pricing, and technology strategies. Tools that improve operational productivity—such as EEsel.ai’s AI knowledge-management capabilities—offer a practical means of converting macroeconomic momentum into sustained competitive advantage without simply scaling headcount.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Hong Kong Land Acquires Wheelock Place and Renames It Landmark Orchard

DBS PayLah China QR Expansion: Now Accepted at Over 100 Million Merchants

Nvidia Stops Reporting Singapore Revenue After It Hit 22% of Sales: What Investors Need to Know

Global Trade and Tariffs 2026:WTO Barometer Still Shows Growth

Extended Producer Responsibility Changes and the UK Hospitality Sector

GDP and Economic Growth in the US: How It’s Measured, Current Trends

Economic Globalization: How Global Trade Shapes the US Economy, Jobs, and Consumers

Best Life Insurance Companies in the United States 2026: Our Top 5 Picks

Pakistan Auto Policy 2026-31 Explained: EV Tax Cuts, $6 Billion Export Target

When Dollar Debt and Food Imports Collide: The Currency Squeeze

Why Freight and Storage Costs Keep Food Prices High After Oil Falls

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Global Finance 2027: Debt, Inflation and AI Are Pulling the Economy Apart

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025