
Analysis
How Private Credit, AI, and Geopolitics Are Rewriting the Rules of Global Capital at Milken 2026

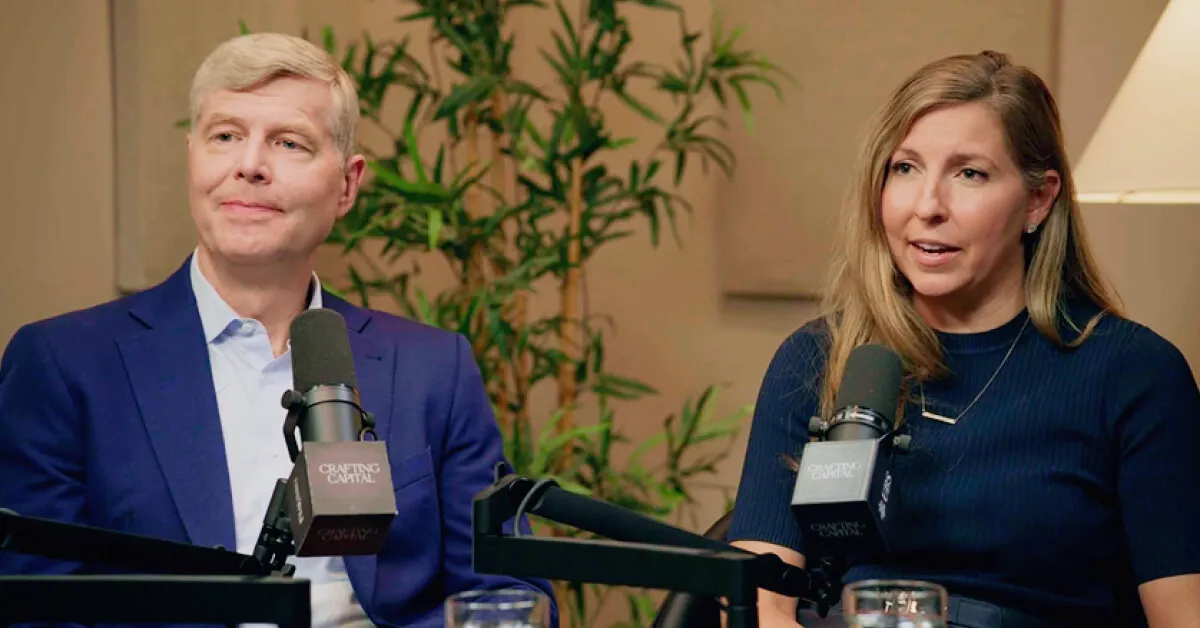
The Beverly Hills Hotel has hosted countless conversations that quietly moved markets. But something about the atmosphere at the Milken Institute Global Conference 2026 — held May 3–6 at the Beverly Hilton — felt different, less celebratory and more reckoning. The sprawling terrace lunches and panel rooms buzzed not with the intoxicating optimism of a bull market, but with the slightly anxious energy of people who can see the next chapter being written in real time and are not entirely sure they like the font.
Across four days, the world’s most consequential allocators, executives, and policymakers gathered under the California sun to wrestle with a trio of forces that are, in concert, dismantling the investment playbook that served the past two decades. Private credit has become too large to ignore and perhaps too crowded to trust blindly. Artificial intelligence is delivering genuine productivity gains even as it hollows out entire lending verticals. And geopolitics — once the polite concern of foreign policy wonks — has migrated squarely onto the spreadsheet.
The central thesis that emerged from Beverly Hills was both clarifying and unsettling: capital is not simply flowing faster; it is flowing differently, toward new instruments, new geographies, and new risk frameworks that most institutional portfolios were never designed to accommodate. The investors who understand this structural rewiring, several panelists argued, will define the next era of wealth creation. Those who mistake cyclicality for seismology will not.
The Private Credit Colossus: Opportunity, Overcrowding, and a Coming Reckoning
Chart suggestion: Private Credit Global AUM Growth, 2018–2030E (bar chart)
No asset class dominated the conversation at Milken 2026 quite like private credit, and the numbers explain why. The global private credit market has surpassed $2 trillion in assets under management as of early 2026, according to data from BlackRock and corroborated by estimates from McKinsey’s Global Private Markets Report 2026. Projections from JPMorgan Asset Management place the market on a trajectory toward $3–4 trillion before 2030, a figure that would have seemed fantastical a decade ago, when private credit was a niche instrument deployed by a handful of specialist funds.
The story of how we arrived here is, at its core, a story about regulatory displacement. Post-2008 capital requirements pushed traditional banks away from middle-market lending, creating a vacuum that private credit managers were only too glad to fill. For years, the trade worked beautifully: borrowers got flexible, covenant-light financing; lenders earned spreads that looked magnificent against a near-zero rate backdrop. The question that hung unspoken over several Milken sessions was whether the trade still works as cleanly in a world of structurally higher rates, AI-driven credit disruption, and maturing loan books.
Harvey Schwartz, CEO of The Carlyle Group, was characteristically measured in his assessment. Speaking on the Alpha in an Era of Uncertainty panel, Schwartz acknowledged the “extraordinary growth” of private credit but urged allocators to distinguish between asset classes within the broader label. “Asset-backed finance — infrastructure debt, real estate credit, specialty finance — retains genuinely attractive risk-adjusted returns,” he noted. “But direct lending to software companies whose revenue models are being disrupted by AI? That’s a different conversation entirely.”
That granular distinction is one sophisticated investors are only beginning to make. The IMF’s April 2026 Global Financial Stability Report flagged private credit’s opacity and interconnection with bank balance sheets as an emergent systemic risk, noting that stress-testing in the sector remains inadequate relative to its scale. The concern is not an imminent collapse but a slow-motion reckoning: vintages of loans written in 2021–2023 against buoyant software valuations may face quiet but painful restructuring as AI compresses the unit economics of the very companies backing them.
The more resilient corners of the private credit universe drew consistent praise. Infrastructure debt — financing the data centers, energy transition assets, and logistics networks that underpin the AI economy — was repeatedly cited as a structural opportunity with genuine demand-pull rather than financial engineering as its engine. “The denominator problem is real for equities right now,” one senior allocator told me between sessions, requesting anonymity. “But the numerator problem for infrastructure debt is also real — there simply isn’t enough of it to go around.”
“Private credit at $2 trillion is not the same animal it was at $500 billion. Scale changes everything — liquidity assumptions, default correlation, systemic importance.” — Senior sovereign wealth fund allocator, Milken 2026
AI at the Enterprise: Productivity Gospel and Its Uncomfortable Prophets
Chart suggestion: AI Capex Investment by Sector vs. Productivity Gain Estimates, 2024–2027E
If private credit represented the financial world’s most discussed asset class at Beverly Hills, artificial intelligence was its most discussed force — invoked in nearly every session, from healthcare to supply chains to the future of knowledge work itself.
The productivity gospel was preached with conviction. Panel discussions citing Nvidia’s Jensen Huang, whose recent public communications have emphasized the transformative compression of software development cycles, noted that AI-enabled coding tools are allowing companies to build in months what previously required years. For CFOs and CIOs in the audience, this represents a genuine cost structure revolution — and for some, an existential pricing event for legacy software vendors.
Schwartz of Carlyle framed the AI opportunity in capital allocation terms with particular clarity: “We are in the early stages of a productivity cycle that has not yet been fully priced into either public or private markets. The capex buildout — semiconductors, power infrastructure, data centers — is the easy part to identify. What’s harder to underwrite is the second-order disruption: which incumbent business models become structurally uneconomic in three years?”
That question carries direct implications for credit markets. Software-as-a-service businesses, which underwrote a significant share of the private credit boom of 2020–2023 on the basis of recurring revenue predictability, face a new competitive landscape in which AI-native competitors can replicate their functionality at a fraction of the cost. Several credit managers at Milken privately acknowledged conducting stress tests on software-heavy portfolio companies for the first time — a discipline that was considered unnecessary when the sector enjoyed near-monopoly pricing power.
The workforce dimension of AI disruption received thoughtful, if occasionally uncomfortable, treatment. Rather than the usual techno-optimist platitudes, multiple panelists acknowledged the distributional asymmetry of AI productivity gains: the capital owners and highly-skilled technologists who deploy AI will capture the vast majority of productivity upside, while mid-level knowledge workers in sectors like financial analysis, legal research, and software development face genuine structural displacement. The World Economic Forum’s Future of Jobs Report projects net job displacement in professional services of approximately 12–15 percent over five years — a figure that sounds manageable in aggregate but represents millions of individual economic disruptions.
For investors, the practical implication is a bifurcation in human capital value that mirrors the bifurcation in asset quality. “The premium on judgment — on genuinely novel, contextual thinking — is going up dramatically,” one panel moderator observed. “The premium on pattern recognition and information retrieval is going to zero.” This has direct consequences for how financial services firms structure their own operations and, by extension, their cost bases and competitive moats.
Geopolitics as Portfolio Risk: Capital Realignment in a Fracturing World
Chart suggestion: Gulf Sovereign Wealth Fund Allocation Shifts by Region, 2020 vs. 2026
Ron O’Hanley, chairman and chief executive of State Street Corporation, offered perhaps the conference’s most sobering macro-level observation when discussing the behavior of sovereign capital in an era of geopolitical fracture. Speaking with rare directness, O’Hanley noted that Gulf sovereign wealth funds — which collectively manage upward of $3.5 trillion in assets — are undergoing a “meaningful realignment” of portfolio exposures, driven partly by elevated oil revenues, partly by domestic Vision-economy diversification mandates, and partly by the shifting geopolitical calculus surrounding U.S.-Iran tensions and broader Middle Eastern stability.
“When sovereign capital moves, it does not do so quietly,” O’Hanley observed. “And when it moves in response to geopolitical signals rather than purely financial ones, the destination choices tell you something important about how the world is being repriced.”
The implications run in multiple directions. On one side, Gulf capital is increasingly active in European infrastructure, Asian technology assets, and African natural resources — a geographic diversification that reflects both opportunity and a deliberate hedge against U.S.-centric portfolio concentration. On the other, the withdrawal or reorientation of this capital from certain Western markets creates genuine liquidity effects that smaller allocators must monitor carefully.
The Economist Intelligence Unit’s 2026 Global Risk Outlook identifies geopolitical fragmentation as the single largest systemic risk to global investment flows, ahead of inflation persistence and financial system stress. The mechanism is not primarily one of direct conflict disruption — though that remains a tail risk — but of the steady, structural rewiring of supply chains, technology licensing, and capital account openness that accompanies sustained great-power competition.
Several Milken sessions addressed the investment implications of what has become known as “friend-shoring” — the deliberate relocation of supply chains toward politically aligned geographies. For institutional investors, this creates a novel class of assets: domestic manufacturing facilities, allied-nation infrastructure debt, and critical minerals operations that are explicitly government-backed. The returns are often modest by private-equity standards; the strategic defensibility, by contrast, is considerable.
The technology sovereignty dimension adds a further layer of complexity. U.S. export restrictions on advanced semiconductors and the European Union’s evolving approach to data localization are creating investment environments where the regulatory framework — rather than purely commercial logic — determines viable asset classes. “I’ve spent thirty years doing cross-border investing,” one veteran allocator told the audience during a particularly candid open-question session. “This is the first time I’ve genuinely had to think about whether my investment thesis is legal in five years.”
“Geopolitics is no longer a risk factor in the footnotes. It has become the thesis itself — the organizing principle around which everything else must be structured.” — Ron O’Hanley, Chairman & CEO, State Street Corporation, Milken 2026
The Intersection: When Three Tectonic Forces Collide
The most intellectually generative moments at Milken 2026 occurred not when panelists addressed any single force in isolation, but when they traced the connections between all three.
Consider the interaction between AI disruption and private credit. AI-native companies require enormous upfront capital — primarily for compute infrastructure — but generate cash flows on timelines and with volatility profiles that traditional private credit models struggle to underwrite. Meanwhile, the incumbent software companies that do have the clean credit profiles private lenders prefer are exactly the businesses most exposed to AI-driven revenue disruption. The private credit market is, in essence, confronting a simultaneous opportunity and obsolescence problem within its most familiar asset class.
Or consider the geopolitics-private credit nexus. The infrastructure assets most favored by geopolitically motivated capital — energy transition projects, domestic semiconductor fabs, allied-nation logistics networks — require the kind of long-duration, patient capital that private credit can supply but that requires very different underwriting frameworks than middle-market corporate lending. This is not simply product extension; it is a fundamental reconceptualization of what private credit is and does.
For allocators attempting to navigate this convergence, several senior investors at Milken offered practical frameworks:
- Disaggregate “private credit” as a label. Asset-backed infrastructure finance, direct corporate lending, and venture debt are three different risk profiles that happen to share a regulatory category. Treat them as such.
- Build AI exposure through picks-and-shovels, not pure-play. The infrastructure layer — power, cooling, connectivity, data storage — is more defensible than individual AI application companies, whose competitive moats are being re-evaluated monthly.
- Geopolitical hedging is now a first-order portfolio construction decision, not a risk management afterthought. This means explicit exposure to allied-nation assets, domestic infrastructure, and supply-chain-critical commodities.
- Liquidity premium reassessment. In a world of higher structural rates and more complex redemption dynamics, the illiquidity premium offered by private markets needs to be evaluated more rigorously against investors’ actual cash flow needs.
The Outlook: What 2026 and Beyond Demands From Capital
The forward-looking consensus at Milken 2026 — to the extent such conferences produce consensus — was one of cautious constructivism. The world is not ending; it is restructuring. And restructurings, as every distressed investor knows, tend to produce both significant losses for those who misread the situation and significant gains for those who position correctly ahead of the resolution.
Private credit will continue to grow, but its composition will shift materially toward hard-asset collateral and away from cash-flow lending to software businesses. AI infrastructure investment — from Nvidia’s chip architecture to the grid upgrades required to power data centers — represents one of the most defensible multi-year capital deployment opportunities in a generation, provided investors can tolerate the valuation volatility that accompanies secular growth stories. And geopolitical fragmentation, while creating real friction, also creates real alpha opportunities for managers with the expertise to navigate the new topology of allied-nation capital markets.
The Milken Institute’s own research arm has repeatedly documented the relationship between capital access and economic resilience. The coming years will test that relationship under conditions of unprecedented complexity — technological disruption compressing incumbent business models, geopolitical fracture constraining capital mobility, and a private credit market large enough to have systemic consequences if its stress-testing culture does not mature alongside its asset base.
Conclusion: Leadership in the Age of Productive Uncertainty
There is a particular quality of leadership that distinguishes the best investors from the merely competent: the ability to hold complexity without collapsing it prematurely into a simple narrative. The finance leaders gathered in Beverly Hills this week demonstrated, in their most candid moments, that they are genuinely grappling with the scale of what is changing.
The seismic forces identified at Milken 2026 — private credit’s maturation, AI’s dual role as productivity miracle and credit risk, geopolitics as portfolio architecture — are not discrete events to be managed sequentially. They are simultaneous and interactive, producing outcomes that no single model can reliably predict. That is not a counsel of paralysis; it is a recognition that the analytical frameworks and the teams that employ them need to be as dynamic as the environment they are attempting to read.
The investors who will thrive in this new era, several of Beverly Hills’ most thoughtful voices suggested, will be those who treat uncertainty not as an obstacle to decision-making but as the very medium in which genuine alpha is generated. Capital, after all, has always flowed toward courage paired with rigor. The geography of where it flows next is simply being redrawn in real time.
Key Data Points Referenced in This Article
- Global Private Credit AUM: ~$2T+ (2026), projected $3–4T by 2028–2030 (BlackRock, McKinsey Global Private Markets 2026)
- Gulf SWF Total AUM: ~$3.5 trillion under active reallocation (State Street / Milken 2026 commentary)
- Professional services job displacement from AI: ~12–15% over five years (WEF Future of Jobs Report 2025)
- IMF classification: Private credit flagged as emergent systemic risk in April 2026 Global Financial Stability Report
Sources
- BlackRock — Global Private Credit Outlook 2026
- McKinsey Global Private Markets Review 2026
- JPMorgan Asset Management — Market Insights 2026
- IMF Global Financial Stability Report, April 2026
- World Economic Forum — Future of Jobs Report 2025
- Economist Intelligence Unit — Global Risk Outlook 2026
- State Street Global Advisors — Capital Realignment Analysis
- Milken Institute — Research & Reports
- World Bank — Capital Flow Dynamics 2026
- Financial Times — Private Credit Special Report 2026
- Reuters — Milken Institute Conference 2026 Coverage
- Carlyle Group — Annual Investor Letter 2026
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Apply for a Bank Account Online: What You Need and How Long It Actually Takes

World’s Largest Economies: Ranking the Top Global Powers

Business Loan: A Complete 2026 Guide to Rates, Types, and Qualifying

Fast Invoice Factoring: How to Turn Unpaid Invoices Into Cash Within 24 Hours

Investment Banking Services: What They Cost and How to Choose the Right Firm in 2026

Structured Settlement Loan: What “Cash Now” Offers Actually Cost You

DUI Attorney: Why Your First Call After an Arrest Should Never Be to the Court

Personal Injury Lawyer: A Complete Guide to Filing Your Claim in 2026

Commercial Vehicle Accident Lawyer: Holding Companies Accountable Beyond the Driver

Inside the White House Feud: How Trump’s Allies Are Painting Anthropic’s Dario Amodei as the Face of ‘AI Doomerism’

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025