
IMF
Pakistan IMF Program 2026: Inside the Push Toward an Interest-Free Economy

Pakistan is running two demanding reform programs at once, and they don’t obviously fit together. On one track, the IMF is pressing for stricter fiscal controls, expanded tax collection, and continued tight monetary policy under its Extended Fund Facility. On the other, Pakistan’s own constitution now mandates the removal of “riba” — interest — from the economy entirely, with a deadline set for January 2028, following a constitutional amendment passed in October 2024, according to IMF Country Report 25/109.
The IMF’s side of the ledger
Pakistan’s economic recovery gained real momentum in the first half of FY26, with GDP growth averaging 3.8% year-on-year, driven by the auto, construction, and garment industries, even as flooding in July-August weighed on output, according to IMF staff reporting. Inflation, however, climbed to 7.3% year-on-year in March as higher global commodity prices passed through to domestic energy costs. Foreign reserves have been rebuilding steadily — from $14.5 billion at end-June 2025 to $16 billion by end-December — while the primary fiscal surplus is expected to reach 1.6% of GDP in FY26, in line with IMF targets.
In May 2026, the IMF Executive Board completed the third review of Pakistan’s Extended Fund Facility and second review of its Resilience and Sustainability Facility, unlocking roughly $1.1 billion and $220 million respectively and bringing total disbursements under the two programs to about $4.8 billion, according to the IMF’s official press release. The Fund explicitly credited Pakistan’s “strong implementation” for maintaining stability despite the disruption from the Middle East war.
The parallel Islamic finance transformation
Running alongside that fiscal program is a structural transformation few outside Pakistan are tracking closely: the State Bank of Pakistan is required to develop a full financial sector strategy detailing the legal, regulatory, and strategic path to a riba-free economy, addressing monetary policy implementation, public debt management, and bank supervision — with a strategy deadline the IMF set for end-June 2026, per the same country report. Parliament has already moved on a related front, approving the Virtual Assets Bill in March 2026 and formally establishing the Pakistan Virtual Assets Regulatory Authority.
Why the IMF is watching this transition warily
The IMF’s own language signals concern about execution risk: publishing the riba-free transition plan “will help align the expectations of market participants, investors, and regulators… and mitigate concerns about any possible cliff effect,” according to the country report language. That is diplomatic phrasing for a real structural risk — an abrupt, poorly sequenced transition away from conventional interest-based finance could destabilize a banking sector the IMF has spent years helping stabilize.
The tax reform Pakistan still owes
Beyond monetary policy, Pakistan has committed to finalizing a new audit manual and centralizing taxpayer audit selection by August 2026, accelerating its Retailer Tax Registration Scheme, and making its Tax Policy Office fully operational, according to ProPakistani’s summary of IMF commitments. The Federal Board of Revenue has continued missing collection targets, prompting the IMF to propose making FBR revenue goals a formal Quantitative Performance Criteria — a stricter enforcement mechanism than before.
Why this matters for Gulf and global investors
Pakistan’s dual reform track — IMF-style fiscal orthodoxy alongside a constitutionally mandated Islamic finance transition — is unusual among IMF program countries and is drawing renewed Gulf capital interest, visible in DIFC’s decision to bring its Dubai FinTech Summit to Pakistan for the first time in August 2026 (see our companion report). Investors assessing Pakistan’s banking sector need to model both trajectories simultaneously, not just the more familiar IMF fiscal metrics.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


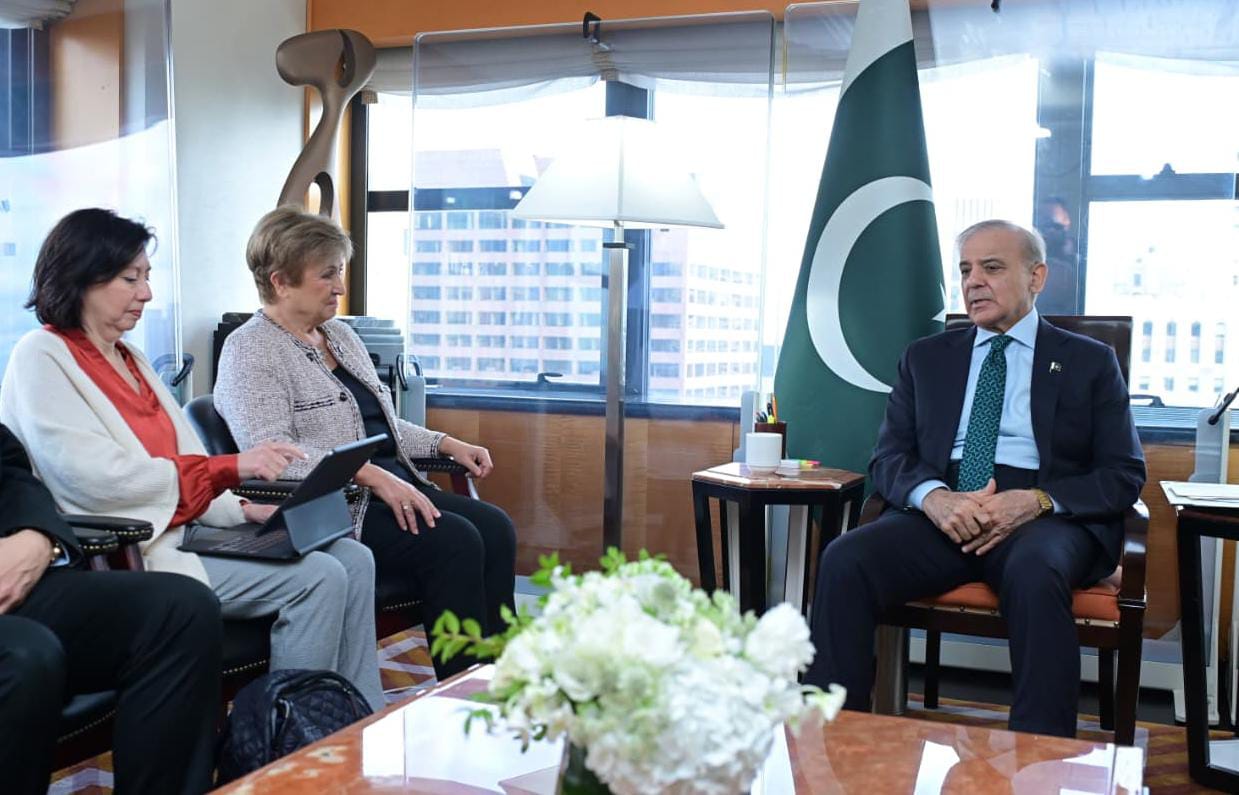
Pakistan is entering a new phase of its economic program, with Prime Minister Shehbaz Sharif saying the country is moving from macroeconomic stabilization toward recovery while reaffirming Islamabad’s commitment to IMF-backed reforms.
The statement came during Sharif’s meeting with International Monetary Fund Managing Director Kristalina Georgieva on the sidelines of the 81st United Nations General Assembly in New York.
The discussion comes at an important point for Pakistan’s economy. After a period dominated by efforts to restore fiscal and external stability, the government’s focus is increasingly shifting toward investment, productivity, exports and longer-term economic growth.

6
PM Shehbaz Sharif Reaffirms Pakistan’s Reform Commitment
According to the government and Radio Pakistan, Sharif told Georgieva that Pakistan was progressing from macroeconomic stabilization toward economic recovery despite regional conflict and external inflationary pressures.
The prime minister pointed to improvements in fiscal discipline, external buffers and investor confidence, while highlighting the National Tariff Regime, domestic revenue mobilization and privatization as important elements of the reform agenda.
Sharif also reiterated that Pakistan intends to remain committed to the IMF-supported reform program.
That commitment matters because the country’s recent economic stabilization has been closely connected to the IMF program and the government’s efforts to meet fiscal and structural targets.
IMF Says Stabilization Efforts Are Producing Results
The IMF’s own assessment provides important context to the government’s claims.
In its May 2026 review, the Fund said strong policy implementation had helped maintain economic stability and improve financing and external conditions. The IMF also approved approximately $1.1 billion under the Extended Fund Facility and about $220 million under the Resilience and Sustainability Facility, taking total disbursements under the two arrangements to about $4.8 billion.
The Fund identified several continuing priorities, including:
- strengthening public finances;
- broadening the tax base;
- improving competition and productivity;
- reforming state-owned enterprises;
- improving energy-sector viability;
- strengthening social protection;
- rebuilding foreign-exchange reserves; and
- improving public-service delivery.
This means Pakistan’s transition to recovery is not simply a question of higher GDP growth. The next phase depends heavily on whether stabilization measures can be converted into sustained productivity, investment and private-sector growth.
Pakistan’s Growth Has Improved, but the Recovery Remains Vulnerable
Pakistan recorded 3.7% GDP growth in FY2026, according to figures cited by the Finance Ministry and the Asian Development Bank. The ADB’s July 2026 outlook also puts Pakistan’s growth forecast at 3.7% for 2026 and 2027.
The ADB, however, has highlighted significant risks surrounding the outlook.
Its July forecast said Pakistan’s 2026 growth was being supported by the recovery in economic activity, but higher energy costs and pressure related to the Middle East conflict represented important downside risks. The ADB projects Pakistan’s inflation at 7.2% in 2026 and 8.3% in 2027.
That distinction is important.
Stabilization does not automatically mean a broad-based economic recovery. Pakistan still needs stronger investment, productivity and export performance to generate durable growth.
What Has Changed in Pakistan’s Economy?
Pakistan’s recent economic story has involved a combination of fiscal consolidation, monetary discipline, external financing and structural reforms.
The IMF reported that Pakistan’s reserves had increased, while fiscal performance remained strong. Its assessment also noted that the country’s economic recovery had gained momentum, although the Middle East conflict had complicated the near-term outlook.
The government’s current economic strategy is therefore moving beyond simply preventing another balance-of-payments crisis.
Finance Minister Muhammad Aurangzeb recently described the next stage as a move toward investment, capital formation, exports and private-sector-led growth. The government has identified macroeconomic stability, structural reforms, investment, exports and improved access to finance among its key priorities.
Why the IMF Review Matters
The upcoming IMF review is one of the most important tests for Pakistan’s reform program.
The IMF-supported Extended Fund Facility was approved in September 2024 and is designed to strengthen macroeconomic resilience while creating conditions for sustainable growth. The program includes fiscal reforms, reserve accumulation, tax-base expansion, SOE restructuring, energy-sector reforms and measures to improve competitiveness.
The forthcoming review will therefore provide an important assessment of whether Pakistan is continuing to meet the commitments associated with the program.
For financial markets and investors, successful implementation can influence perceptions of Pakistan’s external financing position and policy credibility. For households and businesses, however, the more important question is whether stabilization eventually translates into lower economic volatility, stronger investment and sustainable job creation.
Tariff and Revenue Reforms Could Reshape the Business Environment
The government’s National Tariff Regime is another significant component of the reform agenda.
The IMF’s latest Pakistan documentation says authorities are working to reduce tariffs and simplify non-tariff barriers while also pursuing broader regulatory reforms intended to reduce uncertainty and transaction costs for businesses.
The reform agenda also includes changes involving special economic zones and other fiscal incentives.
The objective is to gradually move away from policies that create distortions and toward a more competitive environment in which investment decisions depend more heavily on productivity and market conditions.
Privatization Remains Another Major Test
Privatization is also central to Pakistan’s structural-reform agenda.
The IMF has noted progress on the privatization agenda, including the agreement involving Pakistan International Airlines, while identifying additional SOE and electricity-distribution reforms as part of the broader program.
The government’s challenge will be to demonstrate that privatization and restructuring produce lasting improvements in efficiency rather than simply short-term fiscal relief.
External Financing Remains a Key Vulnerability
Pakistan’s recovery is also taking place against a complicated external backdrop.
Reuters reported in September that Pakistan was seeking an expansion of its 30 billion yuan currency swap arrangement with China when it comes up for renewal in 2027. Finance Minister Muhammad Aurangzeb also said Islamabad was awaiting a US decision concerning a proposed exchange-stabilization facility.
The report underscores an important reality: even as Pakistan’s macroeconomic indicators improve, the country continues to depend on external financing and bilateral and multilateral support to maintain reserves and meet debt obligations.
That makes continued reform implementation particularly important.
Energy Prices Could Complicate the Recovery
Higher energy costs represent another major challenge.
Reuters reported that Pakistan introduced austerity measures in September as rising fuel prices associated with the Gulf conflict increased pressure on the country’s economy. The measures included restrictions on official fuel use, government vehicle purchases and certain official expenditures.
The ADB has similarly warned that higher energy prices could increase inflationary pressure and weaken growth across the region, with Pakistan particularly exposed because of its external energy requirements.
This creates a difficult policy balance: authorities need to preserve fiscal and external stability while preventing higher energy costs from disproportionately affecting households and businesses.
What the Recovery Phase Means for Pakistan
The phrase “from stabilization to recovery” describes a shift in economic priorities.
The stabilization phase focused heavily on preventing external financing crises, controlling inflationary pressures, improving fiscal discipline and rebuilding reserves.
The recovery phase requires something broader:
more private investment + higher productivity + stronger exports + sustainable public finances + structural reform.
The ADB’s 2026–2030 country strategy for Pakistan similarly emphasizes private-sector development, inclusion, resilience and sustainability as key pathways toward longer-term growth.
That suggests the next stage of Pakistan’s economic story will be judged less by emergency stabilization and more by whether the country can turn improved macroeconomic conditions into sustained productive activity.
The Road Ahead
Pakistan has made measurable progress in restoring macroeconomic stability, and international institutions have acknowledged improvements in several areas.
But the economic recovery remains exposed to external shocks, particularly energy prices, geopolitical disruptions, financing conditions and inflation.
The government’s commitment to continued reforms therefore faces a critical test: whether stabilization can be maintained while investment, productivity, exports and private-sector activity expand.
For now, the latest meeting between Shehbaz Sharif and Kristalina Georgieva reinforces the government’s stated intention to remain on the reform path. The IMF review and the implementation of structural measures will provide more concrete evidence of how successfully Pakistan can turn stabilization into sustainable growth.
Key facts at a glance
| Indicator | Latest available information |
|---|---|
| FY2026 GDP growth | 3.7% |
| ADB 2026 Pakistan growth forecast | 3.7% |
| ADB 2027 Pakistan growth forecast | 3.7% |
| ADB 2026 inflation forecast | 7.2% |
| ADB 2027 inflation forecast | 8.3% |
| IMF EFF | 37-month program approved Sept. 2024 |
| IMF/RSF disbursements reported May 2026 | About $4.8 billion combined |
| Major reform areas | Taxation, SOEs, energy, tariffs, competition, reserves |
Sources:IMF
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The IMF’s July 2026 update projects global growth of 3.0% for 2026 and 3.4% for 2027 — a modest slowdown from the 3.5% average of 2024–25, driven by the economic drag of the Middle East conflict being partly offset by an accelerating AI-driven technology cycle. In short: the world economy is being carried by one trade, and it is concentrated in a handful of companies.
That single sentence captures the defining tension of the 2026 economy. Two forces are pulling in opposite directions, and which one wins will determine whether this is remembered as the year markets shrugged off geopolitical risk, or the year they didn’t see the correction coming.
The IMF’s Divergent World
According to the IMF’s World Economic Outlook Update, the growth slowdown is not evenly distributed. Economies deeply integrated into the AI and technology value chain — chiefly the United States and parts of Asia — are absorbing the benefits of the technology boom, while energy-importing and conflict-adjacent economies are absorbing most of the damage. That divergence has been the throughline of every IMF release this year: the April 2026 edition, published as the Middle East conflict first erupted, had cut its forecast to 3.1% for 2026 under a “reference forecast” that assumed the war would stay limited in scope and duration, while warning that a longer or broader conflict — or a reassessment of AI-driven productivity expectations — could meaningfully weaken growth.
For content targeting “IMF reports” and “world economy” search intent, the practical takeaway is this: growth forecasts have been revised four times in twelve months, each revision hinging on two swing factors — the war’s duration and the durability of the AI capital-spending cycle. Anyone publishing on this topic needs to track both, because either one turning could flip the entire growth story.
Wall Street’s AI Concentration Problem
Featured Snippet Target: Three companies — Alphabet, Amazon, and Meta — are now expected to drive roughly 70% of the S&P 500’s 2026 earnings growth, according to Charles Schwab’s market analysis, with combined 2026 capital expenditure guidance exceeding $500 billion. That concentration means the index’s headline diversification is largely cosmetic; its performance now rides on whether a handful of hyperscalers convert AI spending into earnings.
This is the risk hiding inside every “stock market today” headline. Reuters reported the S&P 500 climbing to a record high in early January 2026, powered by gains in Nvidia and Alphabet, with one Tulsa-based fund manager summing up the prevailing mood as a repeat of the prior year’s approach — buy the AI leaders and hold. Since then, hyperscaler capital spending has only accelerated: Alphabet, Amazon, and Microsoft each posted capex increases of well over 25% year-on-year in recent quarters, and combined hyperscaler AI spending commitments for 2026 have topped $700 billion, according to reporting relayed through Yahoo Finance’s technology coverage.
That spending is no longer being funded purely out of free cash flow. A growing share is debt-financed — Macquarie’s Investment Strategy Insights noted that consensus hyperscaler capex estimates for FY26–FY28 were revised up from roughly $2.5 trillion to $2.8 trillion during the reporting season, with gross debt issuance expected to peak near $460 billion in FY28, or about a third of total capex. Analysts have started describing this shift as a change in market character altogether — a move from an era where buybacks reliably supported share prices to one where capital expenditure, not shareholder returns, is what the market rewards.
That has two implications for markets content this year. First, market concentration has hit levels not seen since the dot-com era — roughly two dozen stocks now account for over half of the S&P 500’s total value, which is a comparable concentration level to the 32-stock peak reached during the 2000 bubble. Second, volatility has already started creeping back in: CNBC flagged in mid-September that bond yields were spiking and AI-linked names were selling off even as broader investor sentiment stayed constructive on equities — a split market where the AI trade and the rest of Wall Street are no longer moving in lockstep.
Why the Divergence Matters for Every Asset Class
The IMF’s macro divergence and Wall Street’s AI concentration are, in effect, the same story told twice — a bet on a narrow slice of the global economy carrying the rest. Energy importers and low-income developing economies are absorbing the geopolitical shock the IMF describes, just as the “average” S&P 500 stock is absorbing less of the earnings growth than the concentration numbers suggest. Both dynamics raise the same underlying question for 2026 planning: what happens to growth, and to equity valuations, if either pillar — the ceasefire holding, or hyperscaler capex converting into real earnings — gives way.
For now, neither has. The IMF’s reference forecast still assumes the conflict stays contained, and hyperscaler earnings, so far, have largely met or beaten the market’s demanding bar: Alphabet’s April quarter, for instance, saw earnings per share and Google Cloud growth both come in well ahead of consensus. But both are assumptions, not certainties, and the 2026 economy is being priced as though they will hold indefinitely.
The Bottom Line
Global growth of 3.0% sounds unremarkable in isolation. What makes 2026 distinctive is how much of that growth — and how much of the corresponding equity market gains — is concentrated in AI infrastructure spending by a small number of companies and countries. Investors, policymakers, and anyone allocating capital this year need to treat the AI capex cycle not as a side story to the macro picture, but as the macro picture’s main engine.
Next step: Track the IMF’s next World Economic Outlook update alongside hyperscaler earnings season — the two releases, taken together, are now the single best gauge of where the 2026 global economy is actually heading.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The International Monetary Fund has revised its view of the world economy three times in nine months, and the direction of travel is clear.
Global growth is now projected at 3.0% for 2026 and 3.4% for 2027 — down from the 3.5% average recorded across 2024–25.
The headline number, though, is the least interesting part of the report. What matters is why the Fund revised, and which economies it thinks will absorb the damage.
Key Takeaways
- The July 2026 forecast: 3.0% growth in 2026, 3.4% in 2027, broadly unchanged cumulatively from April.
- Two opposing forces. The Middle East war drags; the AI-driven technology cycle lifts.
- The split is not rich versus poor. It is energy exposure and position in the technology value chain.
- Inflation reversed course. The Fund projected headline inflation rising to 4.4% in its April assessment.
- Risks remain tilted downside. Longer conflict, AI expectation resets and fragmentation dominate the risk register.
The Forecast Trajectory Through 2026
| Report | 2026 Growth | 2027 Growth | Framing |
|---|---|---|---|
| October 2025 WEO | ~3.2% | 3.2% | Steady resilience |
| January 2026 Update | 3.3% | 3.2% | Revised slightly up |
| April 2026 WEO | 3.1% | 3.2% | “Reference forecast” under war |
| July 2026 Update | 3.0% | 3.4% | War drag vs AI lift |
Read as a sequence, this tells a story that a single data point cannot. January was optimistic: the Fund saw technology investment, fiscal and monetary support and accommodative financial conditions offsetting trade policy shifts.
Then war broke out.
April: The Reference Forecast
The April 2026 WEO abandoned the traditional baseline entirely. It presented instead a reference forecast predicated on the assumption that the war would have limited duration, intensity and scope, with disruptions fading by mid-2026, consistent with commodity futures prices as of 10 March.
That is an unusual methodological choice and worth understanding. The Fund was explicitly saying: we cannot forecast this, so here is a conditional projection plus scenarios.
Chief Economist Pierre-Olivier Gourinchas framed the reversal directly: the global economy had been on a steady trajectory around 3.3% and the Fund was looking to upgrade its projections before the war stopped that momentum, with inflation rising to 4.4%.
He identified three transmission channels: higher energy and food prices themselves; persistence in wage and price inflation; and a confidence shock.
The adverse scenario modelled oil prices rising 80% and gas prices 160% from the second quarter of 2026 relative to January assumptions.
July: The AI Offset
The July Update introduced the year’s most important analytical point. The modest slowdown reflects the effects of the Middle East war being partly offset by accelerated demand-driven momentum in the global technology cycle, thanks to advances in artificial intelligence and its adoption.
Critically, the impact varies by two dimensions at once:
- Energy exporters outside the conflict zone benefit from favourable terms of trade.
- Economies plugged into the technology-led upturn experience stronger activity even if they are energy importers.
- Energy importers with limited participation in the technology value chain see activity weaken.
That third category is where the damage concentrates. It captures much of South Asia, Sub-Saharan Africa and parts of Latin America — economies paying more for energy without the AI export revenues to offset it.
This is the single most actionable framework in the 2026 IMF reporting. It explains why Japan and Korea have outperformed while frontier importers have stalled.
What the Reports Say About Major Economies
The January Update projected advanced economy growth of 1.8% in 2026 and 1.7% in 2027, with the United States expanding 2.4% in 2026 supported by fiscal policy and a lower policy rate, before settling at 2.0% in 2027 with a near-term boost from corporate investment tax incentives.
On inflation dynamics, the Fund noted inflation in China rising from low levels, while inflation in India was expected to return to near-target levels after a 2025 decline driven by subdued food prices.
Russia was projected to maintain growth of 1.1%.
Why Investors Should Read IMF Reports Differently
Most market participants treat the WEO as a headline number. Three better uses:
- The revision direction beats the level. A forecast cut from 3.3% to 3.0% tells you more about policy trajectory than the absolute figure does.
- The scenarios are the real content. The April adverse scenario’s 80% oil assumption is a stress test you can apply to your own portfolio.
- The country tables are underused. Annex Table 1’s selected-economy real GDP growth figures cover economies accounting for approximately 83% of world output.
How the IMF and World Bank Differ
The two institutions use different methodologies and produce different numbers for the same year. The IMF projects 3.0% global growth for 2026 on purchasing-power-parity weights. The World Bank projects 2.5% using market exchange rate weights.
Neither is wrong. PPP weighting gives more weight to faster-growing emerging economies. Market-rate weighting reflects actual dollar-denominated output. Quote the one that matches your analytical frame — and never compare the two headline figures directly.
Risks the Fund Flags
- Longer or broader conflict. The reference forecast assumes containment. It is an assumption, not a projection.
- AI expectation reset. A reassessment of expectations surrounding AI-driven productivity could significantly weaken growth and destabilise financial markets.
- Geoeconomic fragmentation. Trade and technology bloc formation raises costs structurally.
- Elevated public debt. Combined with eroding institutional credibility, this heightens vulnerabilities.
- Defence spending trade-offs. The Fund specifically warns policies must carefully manage the trade-offs involved in ramping up defence expenditure.
What This Means for the Global Market in 2027
3.4% in 2027 is a recovery forecast, not a boom. It sits well below the 2000–19 historical average of 3.7%, and the Fund expects growth to settle near that lower rate in the medium term.
The AI offset is a concentrated bet. If the technology cycle disappoints, there is no second offsetting force in the model. The war drag remains; the lift disappears.
Inflation persistence is the policy trap. Rising headline inflation alongside slowing growth limits how far central banks can cut, which in turn limits the equity valuation support markets have priced.
Energy-importing frontier economies face a structural squeeze. Pakistan, Bangladesh, Sri Lanka, Kenya and similar economies sit precisely in the Fund’s worst-affected category.
Watch the October 2026 WEO. It will be the first full report to assess whether the war disruptions actually faded on the assumed timeline. If they did not, the reference forecast framework collapses and forecasts move materially lower.
Frequently Asked Questions
What is the IMF’s global growth forecast for 2026?
The IMF projects 3.0% global growth in 2026 and 3.4% in 2027, down from the 3.5% average recorded in 2024–25.
Why did the IMF cut its 2026 forecast?
The Middle East war raised energy prices and inflation while denting confidence. This drag is only partly offset by AI-driven demand in the global technology cycle.
How often does the IMF publish the World Economic Outlook?
Twice yearly as full reports (April and October), with shorter Updates in January and July.
Do the IMF and World Bank forecasts agree?
They differ by methodology. The IMF’s 3.0% for 2026 uses PPP weights; the World Bank’s 2.5% uses market exchange rates. The two headline numbers are not directly comparable.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

SpaceX IPO 2026: History’s Biggest Stock Debut?
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025