
Human Resourcs
July Jobs Shock: Why the Fed’s September Rate Decision Just Flipped (2026 Analysis)

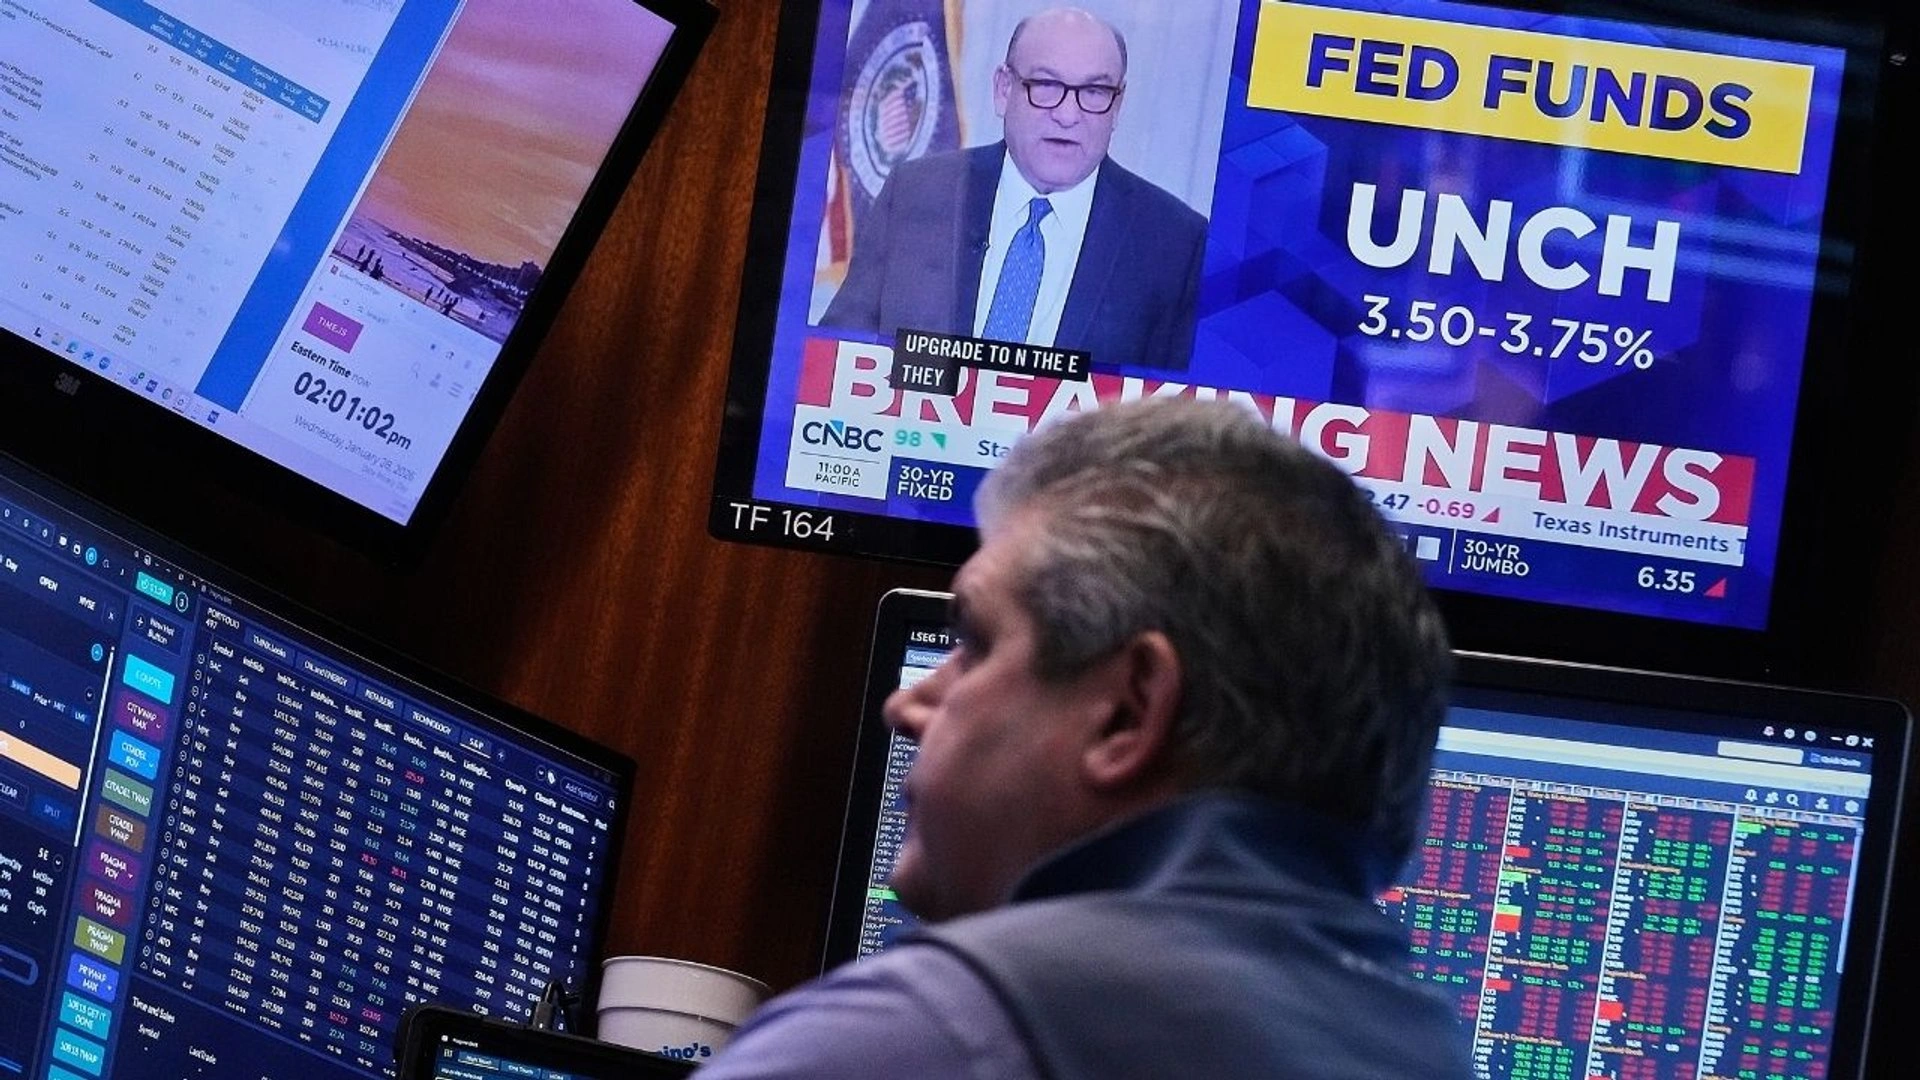
For most of the summer, Wall Street’s working assumption was simple: the US labor market was cooling gently, inflation was easing more slowly than the Fed wanted, and September’s meeting would be a coin-flip between holding steady and one final quarter-point hike. That assumption did not survive contact with the July jobs report.
The Bureau of Labor Statistics reported that US employers cut 23,000 jobs in July — a stark reversal from Wall Street forecasts that had called for a gain of roughly 80,000 positions. It was not an isolated miss. The agency simultaneously slashed its estimates for May and June by a combined 103,000 jobs, meaning the true state of hiring over the past three months is more than a quarter-million jobs weaker than markets believed as recently as Thursday.
The unemployment rate ticked down to 4.1% from 4.2%, but that headline improvement is misleading: it was driven by workers leaving the labor force rather than new hiring, a distinction economists watch closely because it signals discouragement rather than strength.
Why This Report Landed Differently
Soft jobs numbers are not new in 2026 — hiring has been decelerating for months. What makes July’s release different is the scale of the surprise combined with its timing, arriving weeks after the Federal Reserve’s July meeting, where policymakers held rates steady and some officials were still openly discussing the case for a hike given elevated energy costs tied to the ongoing Middle East conflict.
That posture is now obsolete. Within hours of the release, odds on the CME FedWatch tool for the Fed holding rates steady in September jumped sharply, while prediction market Kalshi showed traders assigning roughly a two-thirds probability to a steady-rate outcome — a complete reversal from the near coin-flip odds that prevailed just 24 hours earlier. Separately, Morgan Stanley’s economics team shifted its own call following Fed Chair Jerome Powell’s Jackson Hole remarks, now forecasting a quarter-point cut in September followed by a steady quarterly easing cycle through 2026, targeting a terminal rate near 2.75%–3.00% — down from the current 3.50%–3.75% range.
The reversal wasn’t confined to rates. The 10-year Treasury yield fell as investors priced in a materially weaker growth outlook, while the dollar index came under renewed selling pressure as traders concluded the Fed’s easing runway had just gotten longer, not shorter.
The Sectoral Story: Not All Weakness Is Equal
The composition of the July losses matters as much as the headline. Weakness concentrated in local government education, which cut roughly 50,000 positions, and retail trade, down close to 19,000 — both areas sensitive to seasonal hiring patterns and consumer-facing budget pressure. Healthcare, by contrast, continued adding jobs, extending a multi-year pattern in which medical and social-assistance employment has been the most reliable source of US job growth. Wage growth also missed expectations, with average hourly earnings rising 3.2% year-over-year against a forecast of 3.5% — a sign that whatever residual inflationary pressure exists in the labor market is easing faster than anticipated.
What August 28 and September 4 Mean for Markets
Two dates now sit on every trading desk’s calendar. On August 28, the BLS will release its preliminary annual benchmark revision, using state unemployment insurance tax records to recheck the entire prior year of payroll data — a technical exercise that in past cycles has meaningfully reshaped the market’s understanding of how strong or weak hiring actually was. On September 4, the August jobs report lands just twelve days before the Fed’s September 16 decision, effectively serving as the last major data point policymakers will have in hand.
Richmond Fed President Thomas Barkin offered a measured read following the release, describing the labor market as neither loose nor tight — language that suggests the Fed is not yet panicking, but is clearly recalibrating. Inflation Insights president Omair Sharif cautioned that officials have signaled for months that they view the “breakeven” pace of job growth — the number of jobs the economy needs to add just to keep the unemployment rate flat — as unusually low right now, meaning a soft headline number doesn’t automatically imply outright labor-market distress.
The Global Transmission Channel
For readers outside the US, the mechanics matter more than the headline. A more dovish Fed typically means:
- A softer dollar, which eases imported-inflation pressure for import-heavy economies like the UK and Pakistan but complicates export competitiveness for economies pegged or quasi-pegged to the dollar, including the UAE and much of the Gulf.
- Lower US Treasury yields, which tend to push global capital toward higher-yielding emerging-market and Gulf sovereign debt — a dynamic already visible in DIFC-based fixed-income flows.
- Cheaper dollar-denominated debt servicing for economies like Pakistan and Indonesia that carry significant external, dollar-denominated obligations.
- A complicating factor for the Bank of England and other central banks now weighing their own policy paths against a Fed that appears to be moving faster than expected toward easing, even as UK inflation remains above target.
The Bottom Line
The July jobs report did not just move a single data series — it rewired the market’s central assumption about where US monetary policy is headed into year-end. A Fed that spent mid-2026 debating whether it had room to hike is now managing expectations for a cutting cycle, with September 16 as the first test. For businesses, investors, and policymakers from London to Dubai to Jakarta, the practical question shifts from “will the Fed hike” to “how fast, and how far, will it cut” — and the answer will shape currency, capital-flow, and borrowing-cost decisions well into 2027.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


As rapid demographic aging, falling birth rates, and rising national debt pressures converge, governments worldwide face an unprecedented retirement security crisis. According to comprehensive benchmark research from the Mercer CFA Institute Global Pension Index, national pension architectures vary dramatically in their capacity to deliver adequate retirement income, long-term financial viability, and institutional trust.
While top-performing European and Asian nations have built resilient, multi-pillar retirement models, several major economies lag significantly behind, leaving millions of future retirees exposed to poverty and financial volatility.
The Global Evaluation Framework: How Pensions Are Measured
Comparative pension research published by the Monash University Centre for Financial Studies evaluates national retirement frameworks using 50+ individual indicators divided into three sub-indices:
- Adequacy (40% Weighting): Assesses base benefit levels, net pension replacement rates, tax incentives, homeownership rates, and personal savings structures.
- Sustainability (35% Weighting): Evaluates demographic dependency ratios, mandatory retirement ages, state debt levels, labor force participation among older workers, and economic growth potential.
- Integrity (25% Weighting): Examines regulatory oversight, governance standards, plan communication, operational transparency, and systemic trust.
Systems earning an A-Grade (Score > 80) feature first-class, robust retirement frameworks that deliver comprehensive benefits with strong future viability. Conversely, systems receiving a D-Grade (Score 35–50) exhibit structural vulnerabilities that threaten future retiree welfare without urgent reform.
Global Pension Systems Index Comparison
| Country | Overall Grade | Index Score | Adequacy Score | Sustainability Score | Integrity Score | Primary Architecture Type |
| Netherlands | A | 85.4 | 85.6 | 82.4 | 89.1 | Quasi-Mandatory Occupational / Public State |
| Iceland | A | 83.5 | 82.7 | 84.6 | 86.0 | Universal Mandatory Occupational & State |
| Denmark | A | 81.6 | 81.1 | 82.5 | 81.4 | Fully Funded Mandatory Occupational (ATP) |
| Singapore | A | 80.5 | 79.8 | 74.0 | 88.5 | Central Provident Fund (CPF) Mandatory Savings |
| Israel | A | 80.2 | 73.6 | 76.1 | 83.9 | Mandatory Pension Law & State Safety Net |
| United Kingdom | B | 72.2 | 68.5 | 65.2 | 87.1 | Auto-Enrolment Workplace & State Pension |
| United States | C+ | 61.1 | 63.9 | 60.1 | 59.5 | Social Security + Voluntary 401(k)/IRA |
| Japan | C | 56.3 | 60.2 | 46.5 | 68.1 | Two-Tier Public System & Corporate Plans |
| Argentina | D | 45.5 | 50.7 | 40.0 | 50.0 | Pay-As-You-Go Public Pension |
| Philippines | D | 42.7 | 38.9 | 52.5 | 35.0 | Social Security System (SSS) & Private Plans |
| India | D | 43.8 | 33.5 | 41.8 | 61.0 | National Pension System (NPS) & Provident Fund |
The World’s Top 5 Pension Frameworks (Grade A)
[Level 1: Universal Basic State Safety Net]
                 ↓
[Level 2: Mandatory Occupational / Workplace Pensions]
                 ↓
[Level 3: Voluntary Private Supplemental Savings]
1. Netherlands (Overall Score: 85.4)
The Dutch retirement system consistently sets the benchmark for global excellence. Combining a collective basic state pension (AOW) with quasi-mandatory, industry-wide occupational plans, the Netherlands yields net income replacement rates exceeding 80% for long-term workers. Extensive collective risk-sharing and stringent regulation by the Central Bank ensure high solvency and trust.
2. Iceland (Overall Score: 83.5)
Iceland’s system excels in long-term financial viability and labor participation. It relies on a multi-tiered framework comprising a basic state pension alongside mandatory occupational pension funds where both employers (minimum 11.5%) and employees (4%) contribute. Iceland maintains high labor force participation among workers aged 55 to 74, reinforcing systemic sustainability.
3. Denmark (Overall Score: 81.6)
Denmark relies on a basic public pension supplemented by fully funded occupational schemes (ATP) negotiated through collective labor agreements. High national savings rates, income redistribution for lower-wage earners, and transparent governance yield high marks across all three sub-indices.
4. Singapore (Overall Score: 80.5)
Reaching A-grade status for the first time in recent index evaluations, Singapore’s model centers around the state-administered Central Provident Fund (CPF). Mandatory contribution rates—up to 37% of wages split between employer and employee—are channeled into dedicated accounts for retirement, housing, and healthcare, delivering a high integrity rating.
5. Israel (Overall Score: 80.2)
Israel’s pension infrastructure combines a universal state old-age allowance with mandatory contributions to pension funds, provident funds, or insurance policies established under its Mandatory Pension Law. Strong capital accumulation and clear participant reporting underpin its top-tier status.
The World’s Struggling Pension Frameworks (Grade D)
India (Overall Score: 43.8)
India’s low score stems primarily from limited coverage within its large informal labor force. While the formal sector is served by the Employees’ Provident Fund Organisation (EPFO) and the National Pension System (NPS), the vast majority of workers lack access to formal retirement savings. According to World Bank Pension Data, expanding social pension safety nets for unorganized workers remains an urgent policy challenge.
The Philippines (Overall Score: 42.7)
The Philippine system, governed by the Social Security System (SSS) for private-sector workers and the Government Service Insurance System (GSIS) for public employees, faces challenges regarding benefit adequacy and regulatory integration. Low voluntary savings rates and limited coverage among self-employed individuals constrain its performance.
Argentina (Overall Score: 45.5)
Argentina’s pay-as-you-go (PAYGO) public pension structure has been heavily affected by high inflation, currency devaluation, and fiscal instability. Macroeconomic headwinds periodically erode the real purchasing power of monthly payouts, impacting its overall sustainability score.
Macro Trends Reshaping Retirement Security
   Demographic Aging           DB-to-DC Shift          Economic Volatility
(Higher Dependency Ratio)   (Risk Moves to Worker)    (Inflation & Debt)
           │                         │                         │
           └─────────────────────────┼─────────────────────────┘
                                     ▼
                     [Heightened Longevity & Savings Risk]
Data from the OECD Pensions at a Glance Report highlights three overarching structural pressures impacting pension systems worldwide:
- Shift from Defined Benefit (DB) to Defined Contribution (DC): Governments and employers continue transitioning away from guaranteed DB pensions toward DC plans (like 401(k)s and superannuation). While this reduces liabilities for employers, it transfers market investment, inflation, and longevity risks directly to individual retirees.
- Demographic Aging & Population Inversion: Extended life expectancies paired with declining fertility rates are compressing old-age dependency ratios. In many developed nations, the ratio of active workers supporting each retiree is projected to drop from 3.5:1 down to nearly 1.5:1 over the coming decades.
- The Gender Pension Gap: Policy analysis by the World Economic Forum reveals that women face retirement benefit gaps of 20% to 35% compared to men globally. Career breaks for caregiving, lower lifetime earnings, and part-time employment patterns contribute to lower accumulated retirement balances.
Strategic Blueprint: Policy Recommendations for Reform
To enhance long-term retirement security, policy experts recommend five key structural interventions:
- Implement Auto-Enrolment: Introduce mandatory or auto-enrolment workplace pension schemes to broaden coverage among private and gig-economy workers.
- Increase Retirement Ages: Align statutory retirement ages with life expectancy projections to support system sustainability.
- Protect Minimum Benefits: Establish non-contributory basic pensions to protect low-income and informal workers from poverty in old age.
- Promote Financial Literacy: Provide accessible financial advice and clear, mandatory benefit statements to empower employees in managing Defined Contribution accounts.
- Phase Out Early Withdrawal Provisions: Restrict access to retirement funds prior to official retirement age to prevent capital depletion.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The boutique fitness studio segment is valued at $51.6 billion and growing at approximately 7.6% annually, according to 2026 Fitness Industry Insights — a segment growing faster than the broader $270 billion global fitness market it sits within, and doing so specifically by selling the personalized, community-focused, lower-intensity experience that large commercial gyms structurally cannot replicate. For enterprise investors and premium wellness operators, boutique low-impact training has evolved from a niche urban trend into a defined, monetizable segment with a specific and expanding customer base.
The Demographic Engine Driving Boutique Growth
Two distinct demographic cohorts are converging to drive boutique fitness demand, and understanding both is essential to monetization strategy. Millennials and Gen Z remain the primary volume drivers — 79% of millennials prioritize health and wellness spending, according to 2026 Fitness Industry Insights. But the more commercially significant signal for luxury wellness specifically is the 45+ age group, identified as one of the fastest-growing gym-membership segments and representing a significant, still largely untapped opportunity, per the same source.
This 45+ cohort is precisely the demographic for whom low-impact training — a positioning built around joint-friendly, recovery-oriented, sustainable-intensity programming rather than high-intensity commercial-gym models — carries genuine product-market fit, not just marketing framing.
Gyms and Health Clubs Remain the Volume Leader, But Boutique Commands the Growth Premium
Gyms and health clubs remain the largest single fitness-market segment, accounting for 40% of the global fitness market and an estimated $110.4 billion in 2026, according to 2026 Fitness Industry Insights. But scale and growth rate are different questions — the boutique segment’s 7.6% annual growth reflects consumers actively selecting personalized, community-focused experiences over undifferentiated commercial-gym access, even at a premium price point.
The survival strategy for large commercial operators is instructive by contrast: hybrid models combining in-person membership with digital access, allowing members to train both at the facility and at home, according to 2026 Fitness Industry Insights — an implicit acknowledgment that pure commercial-gym positioning alone is losing ground to more differentiated models.
The AI-Personalization Layer as a Boutique Monetization Tool
Boutique and luxury wellness operators are increasingly deploying the same AI-personalization infrastructure reshaping mass-market fitness — but applied to premium retention and upsell rather than volume acquisition. Gym operators using AI-powered churn-prediction tools have reported check-ins rising 8% year-over-year and new member joins jumping 27%, with Gen Z driving much of that growth, according to Glofox. For boutique operators specifically, AI churn-prediction functions as a high-leverage retention tool given that boutique studios’ unit economics depend far more heavily on member lifetime value than high-volume commercial gyms.
Monetization Model Comparison: Commercial Gym vs. Boutique Low-Impact Studio
| Dimension | Commercial Gym | Boutique Low-Impact Studio |
|---|---|---|
| 2026 market size | $110.4B (40% of global market) | $51.6B |
| Growth rate | Slower, hybrid-model-dependent | 7.6% annually |
| Primary monetization | Volume membership, low per-member ARPU | Premium per-session/membership, high per-member ARPU |
| Key demographic | Broad, price-sensitive | Millennials (79% prioritize wellness) + fast-growing 45+ cohort |
| Retention lever | Facility access breadth, hybrid digital add-ons | Community, personalization, AI-driven churn prediction |
| Differentiation strategy | Scale, convenience, price | Positioning, low-impact/recovery focus, curated experience |
Sources: 2026 Fitness Industry Insights (Fabglassandmirror), Glofox — see citations above.
The Broader Wellness-Tech Infrastructure Boutique Operators Are Riding
Boutique low-impact studios are not monetizing in isolation — they sit within a rapidly scaling AI-and-wellness technology ecosystem. The AI-in-fitness-and-wellness market specifically is valued at $10.68 billion in 2025, projected to reach $57.8 billion by 2035 at a 19.3% CAGR, according to InsightAce Analytic. The virtual fitness market — the hybrid digital layer boutique studios increasingly bundle with in-person sessions — is projected to grow from $43.78 billion in 2026 to $311.91 billion by 2034, a 27.82% CAGR, according to Fortune Business Insights.
Consumer adoption data confirms this infrastructure has genuine pull-through demand: 49% of consumers use AI-powered fitness and wellness apps daily, and 61% of active fitness consumers use AI fitness-tracking apps, per Glofox — meaning boutique operators layering AI-driven personalization into premium low-impact programming are meeting genuine, already-established consumer technology expectations rather than introducing novel friction.
A Monetization Framework for Premium Wellness Operators
- Price for personalization, not access. Boutique unit economics depend on premium per-session or membership pricing justified by curated, low-impact programming — commodity gym-access pricing models undermine the segment’s core value proposition.
- Build explicit 45+ programming and marketing tracks, distinct from the millennial/Gen Z acquisition funnel — this is the fastest-growing, least-saturated membership segment and responds to distinctly different positioning (recovery, longevity, joint health) than younger-cohort messaging.
- Deploy AI churn-prediction as a retention-economics tool, not just an operational nicety — given boutique studios’ high per-member lifetime-value dependency, the documented 8% check-in and 27% new-member-join improvements from AI tooling translate disproportionately into premium-segment revenue protection.
- Bundle hybrid digital access without diluting in-person premium positioning. The virtual fitness market’s 27.82% CAGR signals genuine consumer demand for digital-physical hybrid models — but boutique operators should structure this as a premium-tier extension, not a discount substitute, to preserve the segment’s pricing power.
- Treat community and curation as the defensible moat. Unlike commercial gyms competing on facility breadth and price, boutique studios’ structural advantage — community-focused, personalized experience — is precisely what large operators’ hybrid pivot cannot fully replicate, and should anchor both product design and premium pricing justification.
The Bottom Line
Luxury wellness and boutique low-impact training have moved beyond lifestyle-trend status into a quantifiable $51.6 billion segment growing faster than the broader fitness market, powered by a genuine demographic tailwind — the underserved, fast-growing 45+ cohort — and increasingly monetized through AI-driven personalization and retention tooling rather than facility scale. For premium wellness investors and operators, the highest-conviction opportunity is explicit 45+-focused programming layered with AI-driven retention economics, positioned and priced as a differentiated experience rather than a discount alternative to commercial gym access.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
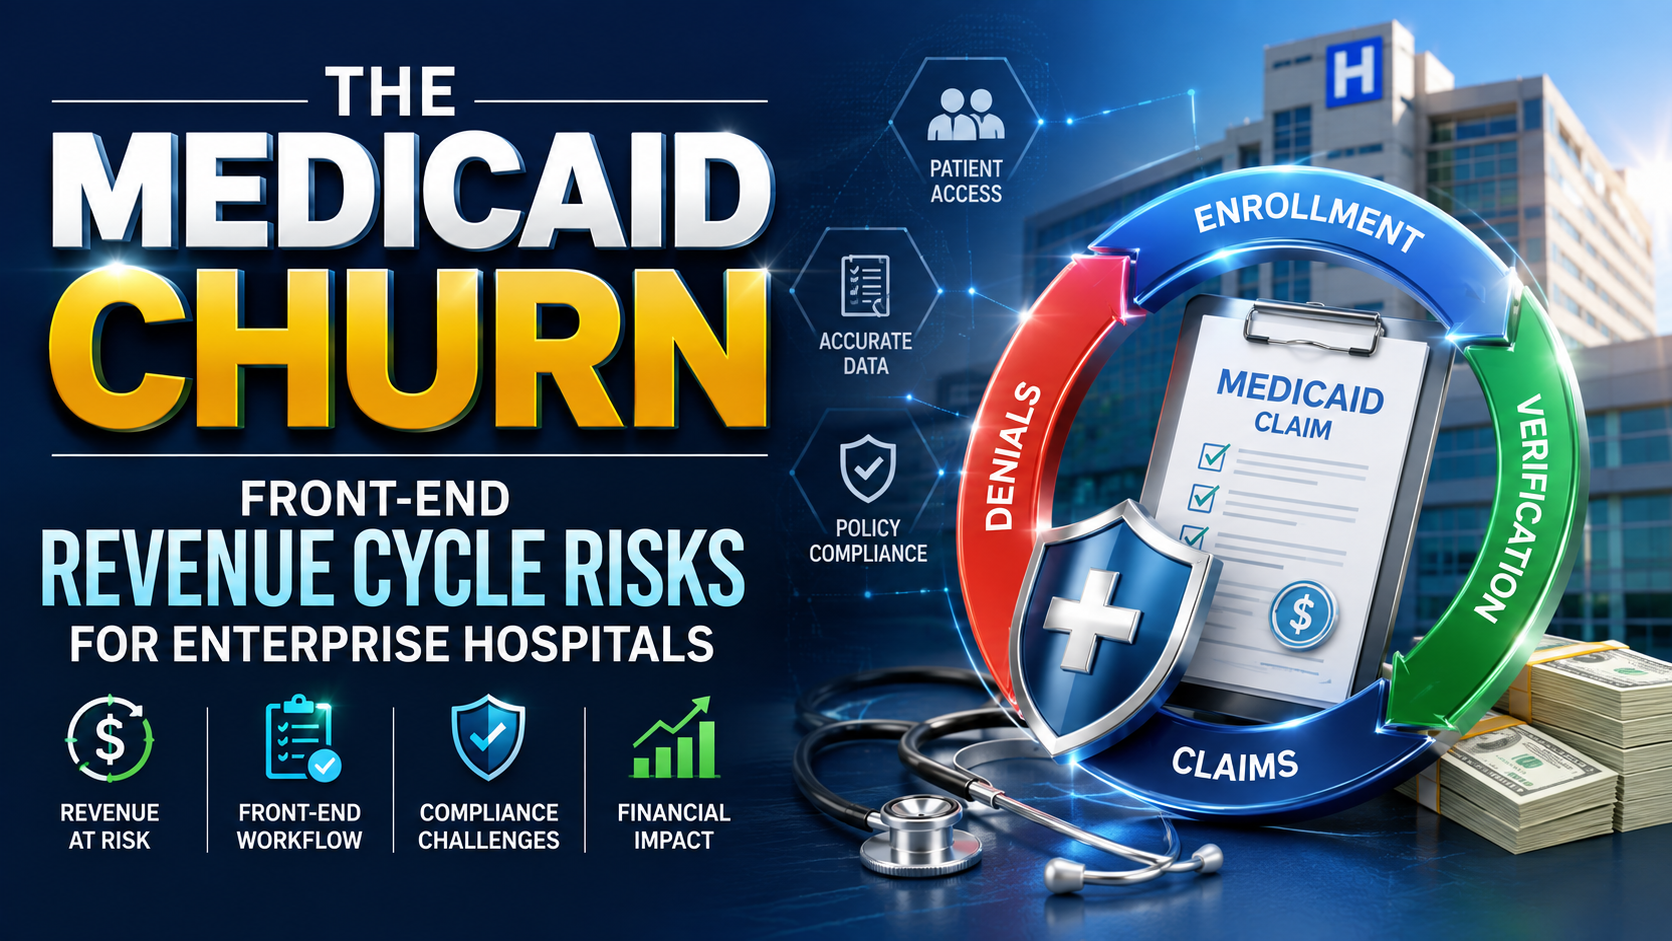
CMS published an interim final rule on June 3, 2026, requiring adult Medicaid enrollees aged 19–64 to meet an 80-hour-per-month work or community-engagement threshold as a condition of continued eligibility, according to Exactrx. The rule took effect July 31, 2026, with full state compliance required by January 1, 2027, per contractingproviders.com. For enterprise hospital systems and revenue-cycle leaders, this is not a distant policy abstraction — it is a payer-mix event with a known start date, a projected enrollment impact, and a direct, quantifiable path into accounts-receivable performance.
The Regulatory Timeline Enterprise Finance Teams Need
| Date | Milestone | Source |
|---|---|---|
| July 4, 2025 | Section 71119 of H.R. 1 (One Big Beautiful Bill Act) signed into law, establishing statutory basis | contractingproviders.com |
| June 3, 2026 | CMS publishes interim final rule detailing 80-hour/month work requirement | Exactrx |
| July 31, 2026 | Work-requirement rule takes effect | contractingproviders.com |
| September 2026 (est.) | Patient inquiries about coverage status begin increasing, per ContinuumCloud | ContinuumCloud |
| December 31, 2026 | Deadline for redetermination workflows to be fully operational | PointCare |
| January 1, 2027 | Full state compliance required; twice-yearly (semiannual) redeterminations begin for expansion adults | PointCare, ContinuumCloud |
Sources: Exactrx, contractingproviders.com, ContinuumCloud, PointCare — see citations above.
The Enrollment-Loss Numbers, Reconciled
Multiple projections exist, and enterprise finance teams should understand why they differ:
- CMS’s own interim final rule projects approximately 2.3 million fewer Medicaid enrollees in fiscal year 2027, rising to over 3 million in subsequent years, per Exactrx.
- The Congressional Budget Office’s earlier, broader estimate projects a reduction of 5.2 million adults by 2034 — a longer time horizon than CMS’s near-term figure, per definitivehc.com.
- A separate CBO estimate cited elsewhere projects 4.8 million people losing coverage over the next decade, per ContinuumCloud — broadly consistent with the CBO’s longer-horizon figures.
- These sit within a larger estimated 15 million people losing health insurance overall under the OBBBA, according to the CBO figures cited by HFMA.
The reconciliation: CMS’s 2.3–3 million figure is the near-term (FY2027) work-requirement-specific impact; the CBO’s 4.8–5.2 million figures represent longer-horizon (through 2034) cumulative effects; and the 15 million figure captures the full scope of the broader legislative package beyond Medicaid work requirements alone.
The Structural Problem: Doubled Administrative Burden, Same Headcount
The operational core of the churn problem is that redetermination frequency is doubling — from annual to semiannual reviews — without a corresponding doubling of enrollment-team headcount, according to PointCare. This structural mismatch is the direct driver of increased “administrative churn” — patients losing and regaining coverage due to paperwork friction rather than genuine eligibility changes.
The scale of this administrative-churn problem is already documented: according to the Commonwealth Fund, cited by RSM, one in ten Medicaid enrollees loses and regains coverage within 12 months, often due to administrative hurdles rather than true eligibility changes — a pattern semiannual redeterminations are projected to intensify.
Quantified Financial Exposure at the Provider Level
A mid-sized provider managing 25,000 Medicaid patients could see an 18% jump in claim denials and a 12% rise in patient churn, potentially resulting in up to $2.4 million in annual uncompensated care losses, according to ContinuumCloud. This is compounded by a broader industry baseline problem: hospitals collectively spent $18 billion fighting claim denials in 2025, with average AR days rising 5.2% despite that spending, per Exactrx.
Beyond Hospitals: The ASC and Outpatient Blind Spot
Revenue-cycle leaders at ambulatory surgery centers and outpatient practices often assume Medicaid churn is primarily a safety-net-hospital and federally-qualified-health-center problem — an assumption worth interrogating, per Exactrx. Medicaid-covered patients represent a meaningful share of elective and semi-elective procedure volume at ASCs in expansion states, and when coverage disappears, those patients don’t vanish from the practice’s patient population — they either shift to commercial/marketplace coverage (requiring new 90–150-day credentialing cycles) or become uninsured, generating direct uncompensated-care exposure regardless of facility type.
An Enterprise Revenue-Cycle Risk Framework
- Verify eligibility at every visit, not just at registration. Point-of-registration-only verification is structurally inadequate under semiannual redetermination cycles; per-visit CHAMPS/HIPAA 270-271 eligibility transactions are becoming operationally necessary, per medsolercm.com.
- Automate re-verification workflows now, ahead of the 2027 deadline. Automated re-verification every five months, aligned to the semiannual cycle, can cut 30–45 days off enrollment-timeline exposure, per ContinuumCloud.
- Diversify payer mix ahead of the enrollment decline, not after. Because commercial-payer credentialing takes 90–150 days, practices waiting until 2027 volume declines materialize will face a revenue gap during the credentialing lag itself, per contractingproviders.com.
- Build patient-facing coverage-retention infrastructure, not just back-office redetermination workflows. Verifying coverage before scheduled services, flagging unconfirmed eligibility, and connecting patients quickly to financial counselors are explicitly recommended proactive steps, per RSM.
- Track license/sanction status continuously. Automated alerts on provider license and sanction changes, aligned to 2026 standards, can materially compress enrollment timelines and reduce compliance risk, per ContinuumCloud.
The Bottom Line for Enterprise Healthcare Finance
Medicaid churn has structurally shifted from an eligibility/enrollment-department problem into a CFO-level revenue-cycle risk with quantified, near-term financial exposure. With semiannual redeterminations doubling administrative workload without a corresponding staffing increase, and CMS’s own projections showing 2.3+ million enrollees losing coverage by FY2027, hospital systems, ASCs, and outpatient practices across all 41 Medicaid-expansion states have a defined, dated window — through December 31, 2026 — to build the automated verification and payer-mix-diversification infrastructure the post-2027 environment will require.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Is AI a Stock Bubble in 2026? What the Data Shows

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

Gold Price 2026: Inside the Wildest Rally in Decades

Federal Reserve 2026: Inside Kevin Warsh’s First Year

Fox Corp 2026: Record Revenue, Tubi Growth & Roku Deal

Wendy’s Stock 2026: Inside the Turnaround Plan

Technology News 2026: Inside the $1.3T AI Chip Boom

UK Stocks 2026: Inside the FTSE 100’s Record Run

Asian Stock Markets 2026: Japan, China, Pakistan & More

Mortgage Rates Today 2026: Full Rate Guide & Forecast

Beyond Paper Wealth: Unpacking Donald Trump’s Multibillion-Dollar Liquidity and Legal Crisis

Bitcoin & XRP 2026: Inside Crypto’s Institutional Era

Global Economy 2026: IMF Growth, AI Stocks & Market Risk

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

BRICS+ Cross-Border Payments 2026: Interoperability Explained

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

Leveraging Viral AI & Climate Hashtags for Brand Growth on X
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025