
Policy
Commercial vs Residential Real Estate: Which Wins in 2026?

The traditional framing of this question — commercial for yield, residential for appreciation — has broken down completely in 2026.
Residential appreciation has stalled at roughly 0.5% annually. Commercial returns are now driven by income rather than appreciation, with cap rates expected to compress only 5 to 15 basis points.
Both asset classes are now income plays. The real question is which income stream you can actually access, finance and manage.
Key Takeaways
- Cap rates tell the story. Mid-2026 core ranges sit near 5.2% for multifamily and industrial, 6.4–6.9% retail, 7.4% office, 8.5% hospitality.
- Commercial is bifurcating, not recovering uniformly. Class A tightens while Class B and C trade at double-digit cap rates.
- Data centres lead on demand. Preleasing on projects under construction sits near 80%.
- Residential is frozen, not falling. 6.76% mortgages suppress both buying and selling.
- Capital is returning. 74% of institutional investors plan to increase acquisitions in 2026, with volume up 16%.
The Head-to-Head Comparison
| Factor | Commercial | Residential |
|---|---|---|
| Typical yield | 5.2%–8.5% by sector | 4%–7% gross rental yield |
| Entry capital | High; REITs offer low-cost access | Moderate; 20–25% down typical |
| Financing | Shorter terms, recourse varies | 30-year fixed, government-backed |
| Lease length | 3–15 years | 12 months typical |
| Tenant risk | Concentrated, credit-rated | Diversified, harder to underwrite |
| Management burden | Professional, often delegated | Hands-on or 8–10% to a manager |
| Liquidity | Low; weeks to months | Moderate; days to weeks |
| Valuation driver | Net operating income ÷ cap rate | Comparable sales |
| 2026 tailwind | AI/logistics demand, income stability | Wage growth outpacing prices |
| 2026 headwind | Rate volatility, maturity wall | Affordability, frozen inventory |
The valuation difference is the one most retail investors underestimate. Residential property is priced by what the neighbour’s house sold for. Commercial property is priced by its own cash flow. You can create value in commercial real estate by raising NOI. In residential, you are largely a passenger on the comps.
Where Commercial Stands in 2026
The market has moved past survival mode into selective opportunity — but “selective” is the operative word.
Cap Rates by Sector
CBRE’s H1 2026 survey, drawing on 3,600 estimates across more than 50 US markets, showed flat average cap rates amid rate volatility, with improving liquidity and growing confidence that yields are past their peak.
Colliers’ Q2 2026 data puts core ranges at approximately 5.2% for multifamily and industrial, 6.4–6.9% for retail, 7.4% for office and 8.5% for hospitality. Eastern US markets compressed more than other regions, and Class B/C value-add assets compressed more than stabilised Class A product.
The spread between property types is wider than it has been in years. That is the real pricing story of 2026.
Sector by Sector
Industrial. Net absorption hit 62.1 million square feet in Q2 2026, up 21% quarter-on-quarter, with national vacancy easing to 6.9%. Leasing is on pace for a record near 1 billion square feet. Rent growth has moderated from 20%-plus peaks in 2022 to a sustainable 4–8% annually.
Data centres. Strong demand from AI-driven workloads with projected revenue growth around 7% CAGR. The binding constraint has shifted: power availability, not land, now determines site selection, with grid interconnection delays of several years in many markets.
Office. Genuinely two-track. Performance varies greatly between newer prime and older secondary space, with even more scarcity of prime space expected by year-end. Lagging markets including Chicago and Los Angeles are bottoming out, with Boston, Seattle and Denver expected to follow. Class B and C stock increasingly heads toward redevelopment or conversion.
Retail. Vacancy holding near historic lows at 4.4% nationally on years of restrained new supply. Net lease retail continues to see strong demand from 1031 exchange buyers and family offices.
Multifamily. Working through supply overhang in many Sun Belt markets, with cap rates near the industrial level.
Where Residential Stands in 2026
Residential investing faces a different problem entirely: the entry cost.
At a 6.76% mortgage rate against a median price of $410,700, debt service consumes a far larger share of gross rent than it did in 2021. Many previously viable rental markets no longer cash-flow on conventional financing.
The offsetting factor is the rental market. A 7.30% vacancy rate indicates ample supply giving renters negotiating power — which caps rent growth precisely when landlords need it most.
Where Residential Still Wins
- Financing terms. A 30-year fixed-rate, non-recourse-in-practice loan is a product commercial borrowers simply cannot obtain.
- Tenant diversification. Ten units with ten tenants beats one building with one anchor tenant on risk-adjusted terms.
- Inflation pass-through. Twelve-month leases reprice annually. A 10-year commercial lease with fixed escalators does not.
- Exit liquidity. A single-family rental sells to owner-occupiers. An office building sells only to other investors.
How to Actually Access Each
Commercial, without buying a building:
- Listed REITs. Listed real estate provides access to higher-growth property types versus the NCREIF index, including senior housing, towers and data centres. Public markets also priced higher debt costs earlier than private ones, creating a valuation gap.
- Non-traded REITs and private funds. Higher fees, lower liquidity, potentially better access.
- Direct ownership. Realistic at the small end: single-tenant net lease, small retail strips, flex industrial.
Residential:
- Direct rental purchase with conventional or DSCR financing.
- Residential REITs for passive exposure without management.
- Short-term rental operations, which behave more like a hospitality business than a real estate investment.
The Decision Framework
Ask four questions in order:
- How much capital, and how liquid must it stay? If you may need it within three years, choose listed REITs over direct ownership in either class.
- Do you want a job or an asset? Direct residential is an operating business. REITs are not.
- What is your financing cost? If your borrowing rate exceeds the asset’s cap rate, leverage works against you. At 6.76% mortgages against 5.2% multifamily cap rates, that inversion is live right now.
- What is your inflation view? Short leases favour residential in inflationary periods; long leases with credit tenants favour commercial in disinflationary ones.
What This Means for the Global Market in 2027
Income, not appreciation, defines this cycle. Total returns will largely be driven by income rather than appreciation, making asset selection and management more important than market timing. That is a fundamental regime change from 2015–2021.
Cap rate compression is not coming broadly. With the 10-year Treasury expected to hold near 4% and yields potentially staying at current levels or slightly higher, the 5–15 basis point compression is concentrated almost entirely in premium assets.
The maturity wall is the unresolved risk. Loans originated at 2020–2021 rates continue to reset. Bank lending standards were basically unchanged in Q1 2026, which helps — but refinancing at double the original coupon still impairs equity.
Power becomes a real estate asset class. Grid interconnection rights are now more valuable than land in data centre markets. That reprices utility-adjacent industrial land in ways no traditional model captures.
Public-private valuation gaps close eventually. Listed REITs repriced debt costs first. If private valuations follow, entry points in public vehicles may prove better than direct ownership on a look-back basis.
Frequently Asked Questions
Is commercial real estate better than residential in 2026?
Neither dominates. Commercial offers higher headline cap rates (5.2%–8.5%) and professional management; residential offers superior financing terms and tenant diversification. The choice depends on capital, liquidity needs and management appetite.
What are cap rates in 2026?
Mid-2026 core cap rates sit near 5.2% for multifamily and industrial, 6.4–6.9% for retail, 7.4% for office and 8.5% for hospitality, with wide variation by asset quality.
Which commercial real estate sector is performing best?
Industrial and data centres lead on capital interest and income stability, with data centre preleasing near 80% and industrial leasing on pace for a record near 1 billion square feet.
Can you invest in commercial real estate with little money?
Yes, through listed REITs, which provide access to data centres, towers and senior housing at minimal capital outlay with daily liquidity.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


US Treasury yields have climbed to multi-year highs, pushing corporate financing costs higher and creating a growing refinancing challenge for American companies. The immediate pressure is concentrated among weaker borrowers, but a prolonged high-rate environment could eventually affect investment, mergers, buybacks and economic growth across corporate America.
The US bond market has entered a more difficult phase for corporate borrowers.
A sharp rise in Treasury yields is increasingly feeding into the cost of corporate debt, forcing companies to reconsider when and how they borrow. The impact is most severe for highly leveraged and lower-rated businesses, but even investment-grade companies are facing a more expensive capital market than they enjoyed during the ultra-low-rate era of the early 2020s.
The issue is no longer simply whether the Federal Reserve raises or cuts short-term interest rates. The bigger question for corporate America is how long long-term borrowing costs remain elevated.
That distinction matters because companies refinancing debt today are replacing old financing obtained at substantially lower rates with new debt priced in a very different market.
The Treasury market is setting a tougher price for corporate debt
The starting point is the US government bond market.
The 10-year Treasury yield has climbed to levels not seen in more than two decades, increasing the baseline rate against which much of the corporate bond market is priced. Recent market reporting has put the 10-year yield above 5%, with investors demanding greater compensation for holding long-duration government debt.
The Federal Reserve has warned that higher interest rates can increase debt-servicing costs for businesses with substantial leverage and upcoming refinancing requirements. The central bank has also noted that the corporate sector entered 2026 with relatively strong investment-grade credit quality, meaning the current environment should not automatically be interpreted as an economy-wide credit crisis.
That distinction is crucial.
The problem is increasingly concentrated in companies that have some combination of high leverage, weak cash flow, floating-rate liabilities or large amounts of debt coming due.
Federal Reserve financial-stability analysis supports the view that corporate credit vulnerabilities remain uneven rather than universal.
Why refinancing is becoming the central risk
Many companies borrowed heavily when interest rates were exceptionally low.
As those bonds mature, companies must either repay the debt from existing cash, refinance it at prevailing rates, sell assets, raise equity or reduce spending.
The refinancing arithmetic can be painful.
Suppose a company borrowed $10 billion at an average interest rate of 3%. Its annual interest bill would be approximately $300 million.
If that debt has to be refinanced at 6%, the annual interest expense rises to approximately $600 million.
The company has not borrowed another dollar, yet its annual financing burden has doubled.
That is why refinancing can become a hidden earnings shock.
Reuters estimates that approximately $4.3 trillion of US non-financial corporate bonds will mature between 2027 and 2031. Annual maturities are expected to rise from roughly $572 billion in 2027 to approximately $1.03 trillion in 2030.
This creates what investors increasingly describe as a corporate refinancing wall.
The weakest companies are feeling the pressure first
The deterioration is not evenly distributed.
Companies with investment-grade balance sheets can generally access capital markets more easily and often have diversified sources of funding.
Highly leveraged companies have fewer options.
According to the Financial Times, borrowing costs for companies rated CCC or lower have risen to approximately 17%, while their risk premium has reached about 12 percentage points.
That level of financing can fundamentally change corporate decision-making.
A project that looked profitable when money cost 5% may no longer make economic sense when financing costs move substantially higher.
This can lead companies to postpone:
- acquisitions;
- share buybacks;
- expansion projects;
- capital expenditure;
- hiring;
- new factories;
- technology investments;
- refinancing transactions.
The consequences can therefore spread beyond bond investors into the real economy.
Corporate America is not facing one uniform debt crisis
One of the most important nuances missing from many discussions about higher borrowing costs is that corporate America is highly divided.
At one end are highly profitable technology companies and other large investment-grade borrowers with enormous cash flows and strong access to capital markets.
At the other are highly leveraged companies whose earnings leave relatively little room to absorb a major increase in interest expense.
The Federal Reserve’s 2026 Financial Stability Report found that investment-grade corporate credit quality remained robust, although some riskier firms, particularly those dependent on private credit, were experiencing greater debt-servicing challenges.
That suggests the current environment is better described as a credit-selection problem than a generalized corporate solvency crisis.
The longer yields remain elevated, however, the greater the probability that today’s refinancing pressure becomes tomorrow’s default problem.
The corporate bond market is already sending signals
Market pricing provides an important window into this transition.
FRED data show Moody’s seasoned Baa corporate bond yield at approximately 6.73% on October 1, 2026. The Baa spread over the 10-year Treasury was about 1.49 percentage points at the beginning of October.
This distinction is important.
Corporate borrowing costs consist broadly of two components:
Treasury yield + corporate credit spread = corporate borrowing yield
The Treasury component compensates investors for the time value of money and government interest-rate risk.
The credit spread compensates investors for taking corporate credit risk.
When both rise simultaneously, companies experience a much more powerful increase in financing costs.
So far, much of the pressure has come from the Treasury side, although credit spreads for weaker borrowers have also widened substantially.
Paramount’s enormous financing illustrates the new reality
The Paramount Skydance transaction provides a particularly useful case study.
Paramount disclosed plans for tens of billions of dollars of debt financing connected with its acquisition of Warner Bros. Discovery. Its SEC filings show that the transaction involved substantial debt commitments, including a large bridge financing facility that was expected to be replaced or reduced through permanent financing.
The transaction demonstrates a broader challenge facing corporate finance teams.
When financing costs are uncertain, companies increasingly have to think about:
How much should we borrow?
For how long?
At what fixed rate?
How much floating-rate exposure should we accept?
Should we refinance now or wait?
Can the acquisition generate enough additional cash flow to justify the higher financing expense?
Those questions become especially important for highly leveraged mergers and acquisitions.
Why companies are shortening maturities
One logical response to high long-term interest rates is to avoid locking in today’s expensive financing for decades.
Companies may therefore prefer shorter maturities.
The strategy has an obvious advantage: if rates fall later, the company can refinance at a lower cost.
But it also creates another risk.
Shorter maturities mean more refinancing requirements in the future.
If interest rates remain high, companies could find themselves repeatedly refinancing debt at elevated rates.
That creates a difficult trade-off between paying more today for long-term certainty and accepting refinancing risk in exchange for shorter-term flexibility.
AI is creating an important exception
One of the most interesting features of the current credit market is the enormous borrowing associated with artificial intelligence infrastructure.
Technology companies are spending unprecedented amounts on data centres, chips, networking infrastructure and electricity capacity.
The Financial Times has reported estimates that hyperscalers could borrow around $1 trillion through 2030 to support AI infrastructure expansion.
For these companies, the calculation is different.
If management believes that failing to invest in AI infrastructure would result in losing a strategic position, higher financing costs may be treated as the price of maintaining competitive advantage.
This creates a strange two-speed corporate credit market.
AI-related investment can remain aggressive while other companies cut capital spending.
That divergence could become one of the defining characteristics of the next phase of the US corporate bond market.
The refinancing wall could become an earnings problem
The most important transmission mechanism is straightforward:
Higher Treasury yields → higher corporate borrowing costs → higher interest expense → lower free cash flow → reduced investment or weaker credit quality.
For companies with strong margins, the increase may be manageable.
For companies operating with thin margins, it can be decisive.
Consider a company generating $1 billion in annual operating cash flow and paying $300 million in interest.
If refinancing raises annual interest expense to $500 million, the company’s interest burden consumes a much larger share of its cash flow.
Management then has fewer resources available for investment, acquisitions, dividends and buybacks.
If revenues simultaneously weaken, the problem becomes more serious.
Could this trigger a wave of corporate defaults?
Not necessarily.
The Federal Reserve’s earlier 2026 assessment showed that corporate bond issuance remained strong and investment-grade credit quality was generally solid.
That provides an important cushion.
Large corporations have also had years to prepare for higher rates by extending maturities and locking in fixed-rate financing.
But the risk is asymmetric.
A stable economy can allow heavily indebted companies to refinance successfully.
A combination of high interest rates, slowing economic growth and falling corporate profits would be much more dangerous.
That is when refinancing pressure can turn into covenant breaches, distressed exchanges, restructurings and defaults.
The Federal Reserve has explicitly warned that higher rates can amplify vulnerabilities associated with leverage and upcoming refinancing needs.
What investors should watch next
Investors should focus on five indicators rather than Treasury yields alone.
1. The 10-year Treasury yield
A sustained move above current levels would increase the baseline cost of corporate financing.
2. High-yield credit spreads
A sharp widening would indicate that investors are demanding substantially greater compensation for corporate credit risk.
3. Corporate refinancing volumes
If companies begin delaying bond issuance, it could signal that borrowers consider market pricing too expensive.
4. Interest coverage ratios
Companies with declining earnings and rising interest expense are particularly vulnerable.
5. Default and distressed-debt indicators
A sustained increase in defaults would suggest that the refinancing problem is becoming a solvency problem.
The bigger issue is the cost of capital
The most important consequence of the bond sell-off may not be a sudden wave of bankruptcies.
It may be a gradual repricing of corporate decision-making.
For more than a decade, exceptionally low interest rates encouraged companies to borrow cheaply, refinance frequently, acquire competitors and return capital to shareholders.
That model becomes less attractive when the cost of capital rises substantially.
The result could be a more disciplined corporate environment in which companies demand higher returns from acquisitions and capital projects.
That may ultimately be healthy.
But the transition could be painful for companies that built their business models around cheap debt.
A new test for corporate America
The US economy has already demonstrated considerable resilience in the face of higher rates.
The question now is whether that resilience extends to a corporate sector facing a large refinancing cycle.
The numbers suggest that the pressure will build gradually rather than arrive as a single shock.
The immediate danger is concentrated among highly leveraged and lower-rated companies. Investment-grade borrowers remain considerably better positioned.
But the refinancing calendar means the issue cannot simply be dismissed.
With roughly $4.3 trillion of non-financial corporate bonds coming due between 2027 and 2031, the cost of money over the next several years will matter enormously.
If Treasury yields eventually decline, many companies could refinance more comfortably.
If yields remain elevated while earnings weaken, the pressure could move steadily up the credit spectrum.
That makes the current bond-market sell-off more than a story about government debt.
It is becoming a test of how much corporate America can adapt to a world in which capital is no longer cheap.
Bottom line
The US corporate sector is not yet facing a systemic debt crisis. The stronger borrowers retain substantial market access, while investment-grade credit quality remains relatively resilient.
But the refinancing cycle is creating a growing divide between companies that can absorb higher interest costs and those that cannot.
The crucial variable is therefore not simply whether the Federal Reserve raises or lowers its policy rate.
It is whether long-term borrowing costs remain high long enough for the refinancing wall to become an earnings and solvency problem.
For investors, the next phase of the credit cycle will be about separating companies that can grow their cash flows faster than their financing costs from those whose balance sheets were built for the era of cheap money.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
When Washington doubles down on reshoring corporate capital, export-reliant trade partners typically prepare for impact. However, Ireland’s Prime Minister Micheál Martin is turning trade pressure into bilateral leverage—using U.S. “America First” incentives to sharpen Irish competitiveness while securing high-profile tariff rollbacks for staple Irish exports.
Following a landmark pledge from President Donald Trump to eliminate the 10% U.S. duty on Irish whiskey, Irish diplomats have locked their sights on the next major trade concession: Kerrygold butter, a commodity generating over $1 billion in annual U.S. retail sales.
The Bilateral Investment Balance Sheet
Contrary to popular belief that transatlantic trade flows primarily benefiting European exporters, the economic relationship between the U.S. and Ireland operates as a two-way investment engine. Official data from the U.S. Bureau of Economic Analysis ranks Ireland among the top five foreign direct investment (FDI) contributors to the U.S. economy.
| Economic Metric | U.S. Capital in Ireland | Irish Investment in the U.S. |
| Total Investment Position | ~$460+ Billion | ~$390+ Billion |
| Employment Footprint | ~210,000 Irish workers | ~200,000 U.S. workers |
| Key Industries | Pharmaceuticals, Tech, MedTech | Agrifood, Health Sciences, Tech Services |
| Enterprise Presence | ~950 U.S. Multinationals | ~800 Irish Companies |
Data supported by Enterprise Ireland demonstrates that Irish-owned firms expanded their U.S. payrolls significantly across regional manufacturing and tech hubs, creating a dual-dependency that insulates Dublin from hostile tariff measures.
From Doonbeg to Distilleries: The Whiskey Breakthrough
The political momentum behind recent tariff exemptions crystallized during President Trump’s visit to his Doonbeg golf resort in County Clare, Ireland. Following direct representations by Taoiseach Micheál Martin and Irish golfer Shane Lowry, the administration committed to stripping away duties on Irish spirits.
As reported by Global Banking & Finance, the announcement removed a 10% import tariff that had been applied to EU spirits, returning Irish whiskey exports toward a zero-for-zero trade parity.
“He’s certainly had success in terms of the investments that companies are making in the U.S.,” stated Micheál Martin. “In a way, it makes us more competitive. We’ve analyzed it and said, ‘OK, that’s a new challenge. How do we double down, make ourselves more competitive, and stay agile?'”
Kerrygold in the Crosshairs: The Next $1 Billion Trade Target
With spirits secured, Ireland’s diplomatic and commercial apparatus is pivoting toward agricultural exports—specifically dairy products managed by Irish dairy cooperative Ornua.
- Market Scale: Kerrygold stands as the second-largest butter brand by value in the United States, crossing the $1 billion retail sales threshold in 2025.
- Economic Stake: Food and drink exports form the backbone of Ireland’s rural economy. Agricultural tariffs directly impact primary producers across all 26 counties.
- Regulatory Leverage: As Ireland leads discussions during its presidency of the Council of the European Union, reducing regulatory friction and bureaucracy for U.S. technology imports serves as potential bargaining leverage for agricultural parity.
EU Bureaucracy vs. Transatlantic Competitiveness
A central theme in ongoing U.S.-EU discussions is European regulation. American MNEs routinely cite European red tape as a primary barrier to capital deployment.
According to official briefings from the European Commission, the EU and U.S. have been working on reciprocal tariff reductions across industrial goods, aerospace, and generic pharmaceuticals while streamlining sanitary certification processes. Ireland is using its influence within the EU Council to prioritize deregulation, aligning European business practices more closely with U.S. capital efficiency.
By framing American domestic investment pushes not as a threat, but as a benchmark for national agility, Ireland maintains its position as the premier European bridgehead for U.S. multinationals while methodically clearing tariff hurdles for its own flagship exports.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global Economy
Battle for the Farm Belt: How Tariff Pressures and Fuel Costs Are Reshaping Iowa’s 2026 Midterms
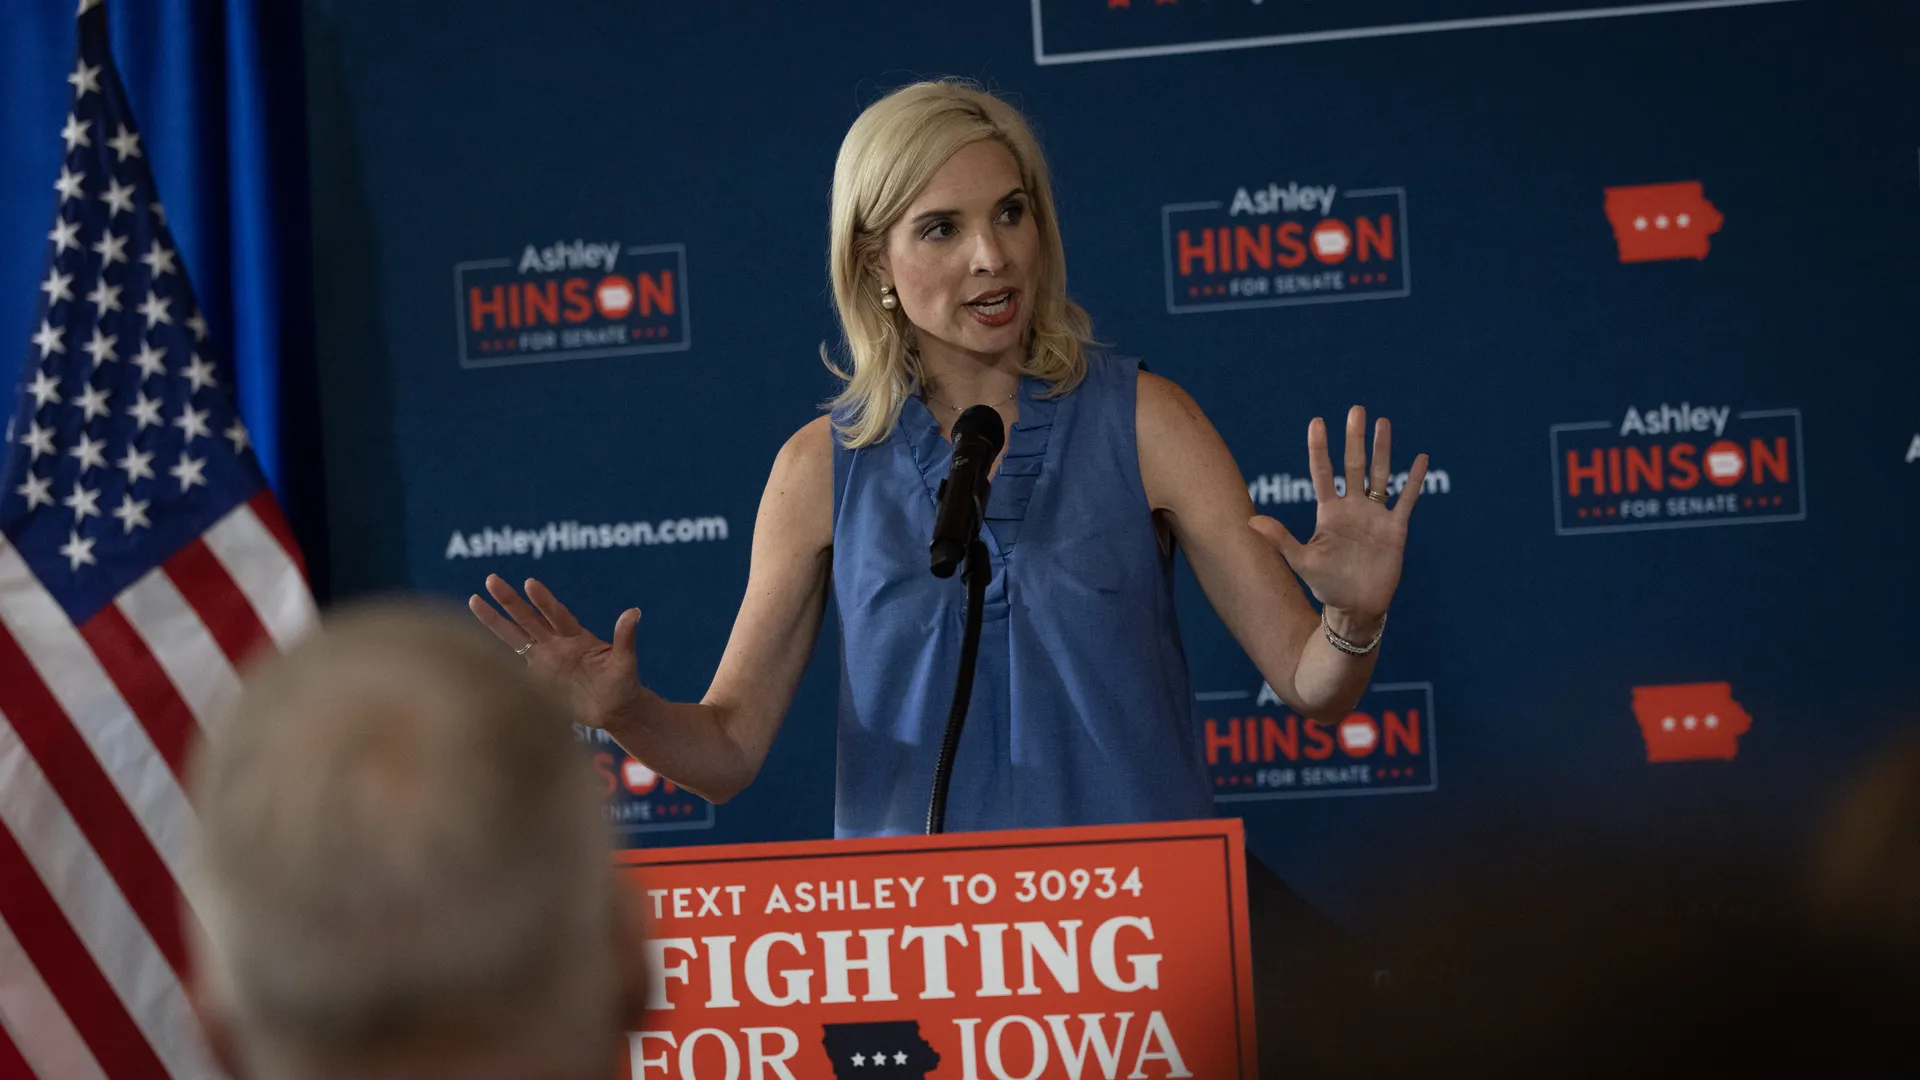
DES MOINES, Iowa — In America’s agricultural heartland, the political landscape heading into the 2026 midterm elections is undergoing its most significant realignment in a decade. Surging fuel overhead, escalating global trade frictions, and rising input costs are convergence points putting traditional Republican strongholds in Iowa under intense electoral pressure.
1. The Economic Squeeze in Rural Iowa
At the center of Iowa’s political shift is a dual economic pressure hitting family farms and agricultural enterprises:
- Energy and Transportation Overhead: Following energy market disruptions, diesel prices across the Midwest surged past $6.50 per gallon, representing a nearly 76% increase year-over-year. For producers managing heavy machinery, grain haulage, and supply chain logistics, fuel overhead has eroded operational margins.
- Trade and Commodity Price Suppression: Retaliatory tariffs on major American exports—specifically soybeans and corn—have created volatility in key foreign markets. Soybean prices have faced downward pressure, directly reducing farm incomes across 95% of Iowa’s primary crop-producing counties.
- Compound Input Inflation: Higher costs for nitrogen-based fertilizers, commercial seeds, and equipment financing have compounded household financial strain.
According to financial impact studies published in the Associated Press Midterm Report, agricultural producers across the Midwest are facing a sharp pinch between fixed operational costs and suppressed market yields, turning economic survival into a core campaign issue.
2. Polling Breakdown: Marist Survey Highlights Key Shifts
Political dynamics in Iowa—long viewed as a stable red baseline—have tightened dramatically across statewide contests.
Data compiled in the Marist Poll September 2026 Survey highlights significant headwinds for incumbent political alignments:
| Electoral Measure | Current Polling Metric | Key Demographic / Breakdown |
| U.S. Senate Race | Josh Turek (D): 50% Ashley Hinson (R): 42% | Independent voters favoring Turek; cost-of-living cited as primary issue. |
| Gubernatorial Race | Rob Sand (D): 54% Zach Lahn (R): 42% | Sand holding a 57%–33% advantage among independent statewide voters. |
| Generic Congressional Ballot | Democrat: 50% Republican: 45% | Shift in suburban and mixed rural-suburban congressional districts. |
| Presidential Job Approval | Disapprove: 58% Approve: 41% | Plurality of voters (43%) report their ballot is a vote against current federal policies. |
| Household Financial Sentiment | Worse Off: 46% Unchanged: 39% / Better: 15% | High fuel prices and grocery inflation drive negative financial sentiment. |
3. The Re-Alignment of the Rural Swing Vote
In previous election cycles, agricultural state voters historically prioritized regulatory relief and federal tax incentives. However, the 2026 midterm cycle demonstrates that affordability and cost containment have superseded traditional party loyalties.
Analysis from the Brookings Institution Midterm Governance Report indicates that when Presidential approval ratings dip among agricultural constituents, down-ballot candidates face immediate fallout:
- The Independent Pivot: Independent voters in Iowa, who previously split evenly or favored conservative candidates, are breaking toward candidates offering specific cost-relief and trade stabilization policies.
- The Tariff Dilemma: While agricultural subsidies offer temporary liquidity, farm leaders increasingly advocate for open export markets over government bailouts, citing long-term market access as vital for generational farms.
- Turnout Dynamics: High-dollar national ad spending from both political parties is pouring into Iowa’s media markets, reflecting the strategic importance of the state in deciding national control of the U.S. Senate.
What to Watch Next
- Farm Bill & Subsidy Appropriations: How federal agricultural relief programs are structured prior to November will directly influence late-deciding agricultural voters.
- Energy Overhead & Diesel Spot Prices: Any stabilization or further spike in harvest-season fuel costs will serve as an economic bellwether for rural voter sentiment.
- Turnout in All 99 Counties: Ground mobilization efforts across Iowa’s rural townships will determine whether the polling shift translates into turnout at the ballot box.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025