
Global Economy
Beyond Rhetoric: How the EU Is Deploying ‘All Tools’ to Rebalance Its €1 Billion-a-Day Trade Deficit with China

Key Takeaways
- The Tipping Point: European Commission President Ursula von der Leyen has declared that Europe’s trade deficit with China has reached an “unsustainable” €1 billion per day, pushing bilateral trade relations to a historical tipping point.
- Enforcement Over Engagement: Signaling a fundamental shift in doctrine, von der Leyen issued a direct ultimatum: “Words are good. But deeds are better.”
- The Defensive Arsenal: Brussels is escalating beyond traditional anti-dumping tariffs, actively deploying the Foreign Subsidies Regulation (FSR), the International Procurement Instrument (IPI), and establishing a centralized European Critical Raw Materials Corporation under the RESourceEU framework.
- Supply Chain Exposure: European and Asian enterprises face heightened compliance scrutiny, potential market access restrictions, and supply chain realignment risks across green-tech, automotive, and critical mineral sectors.
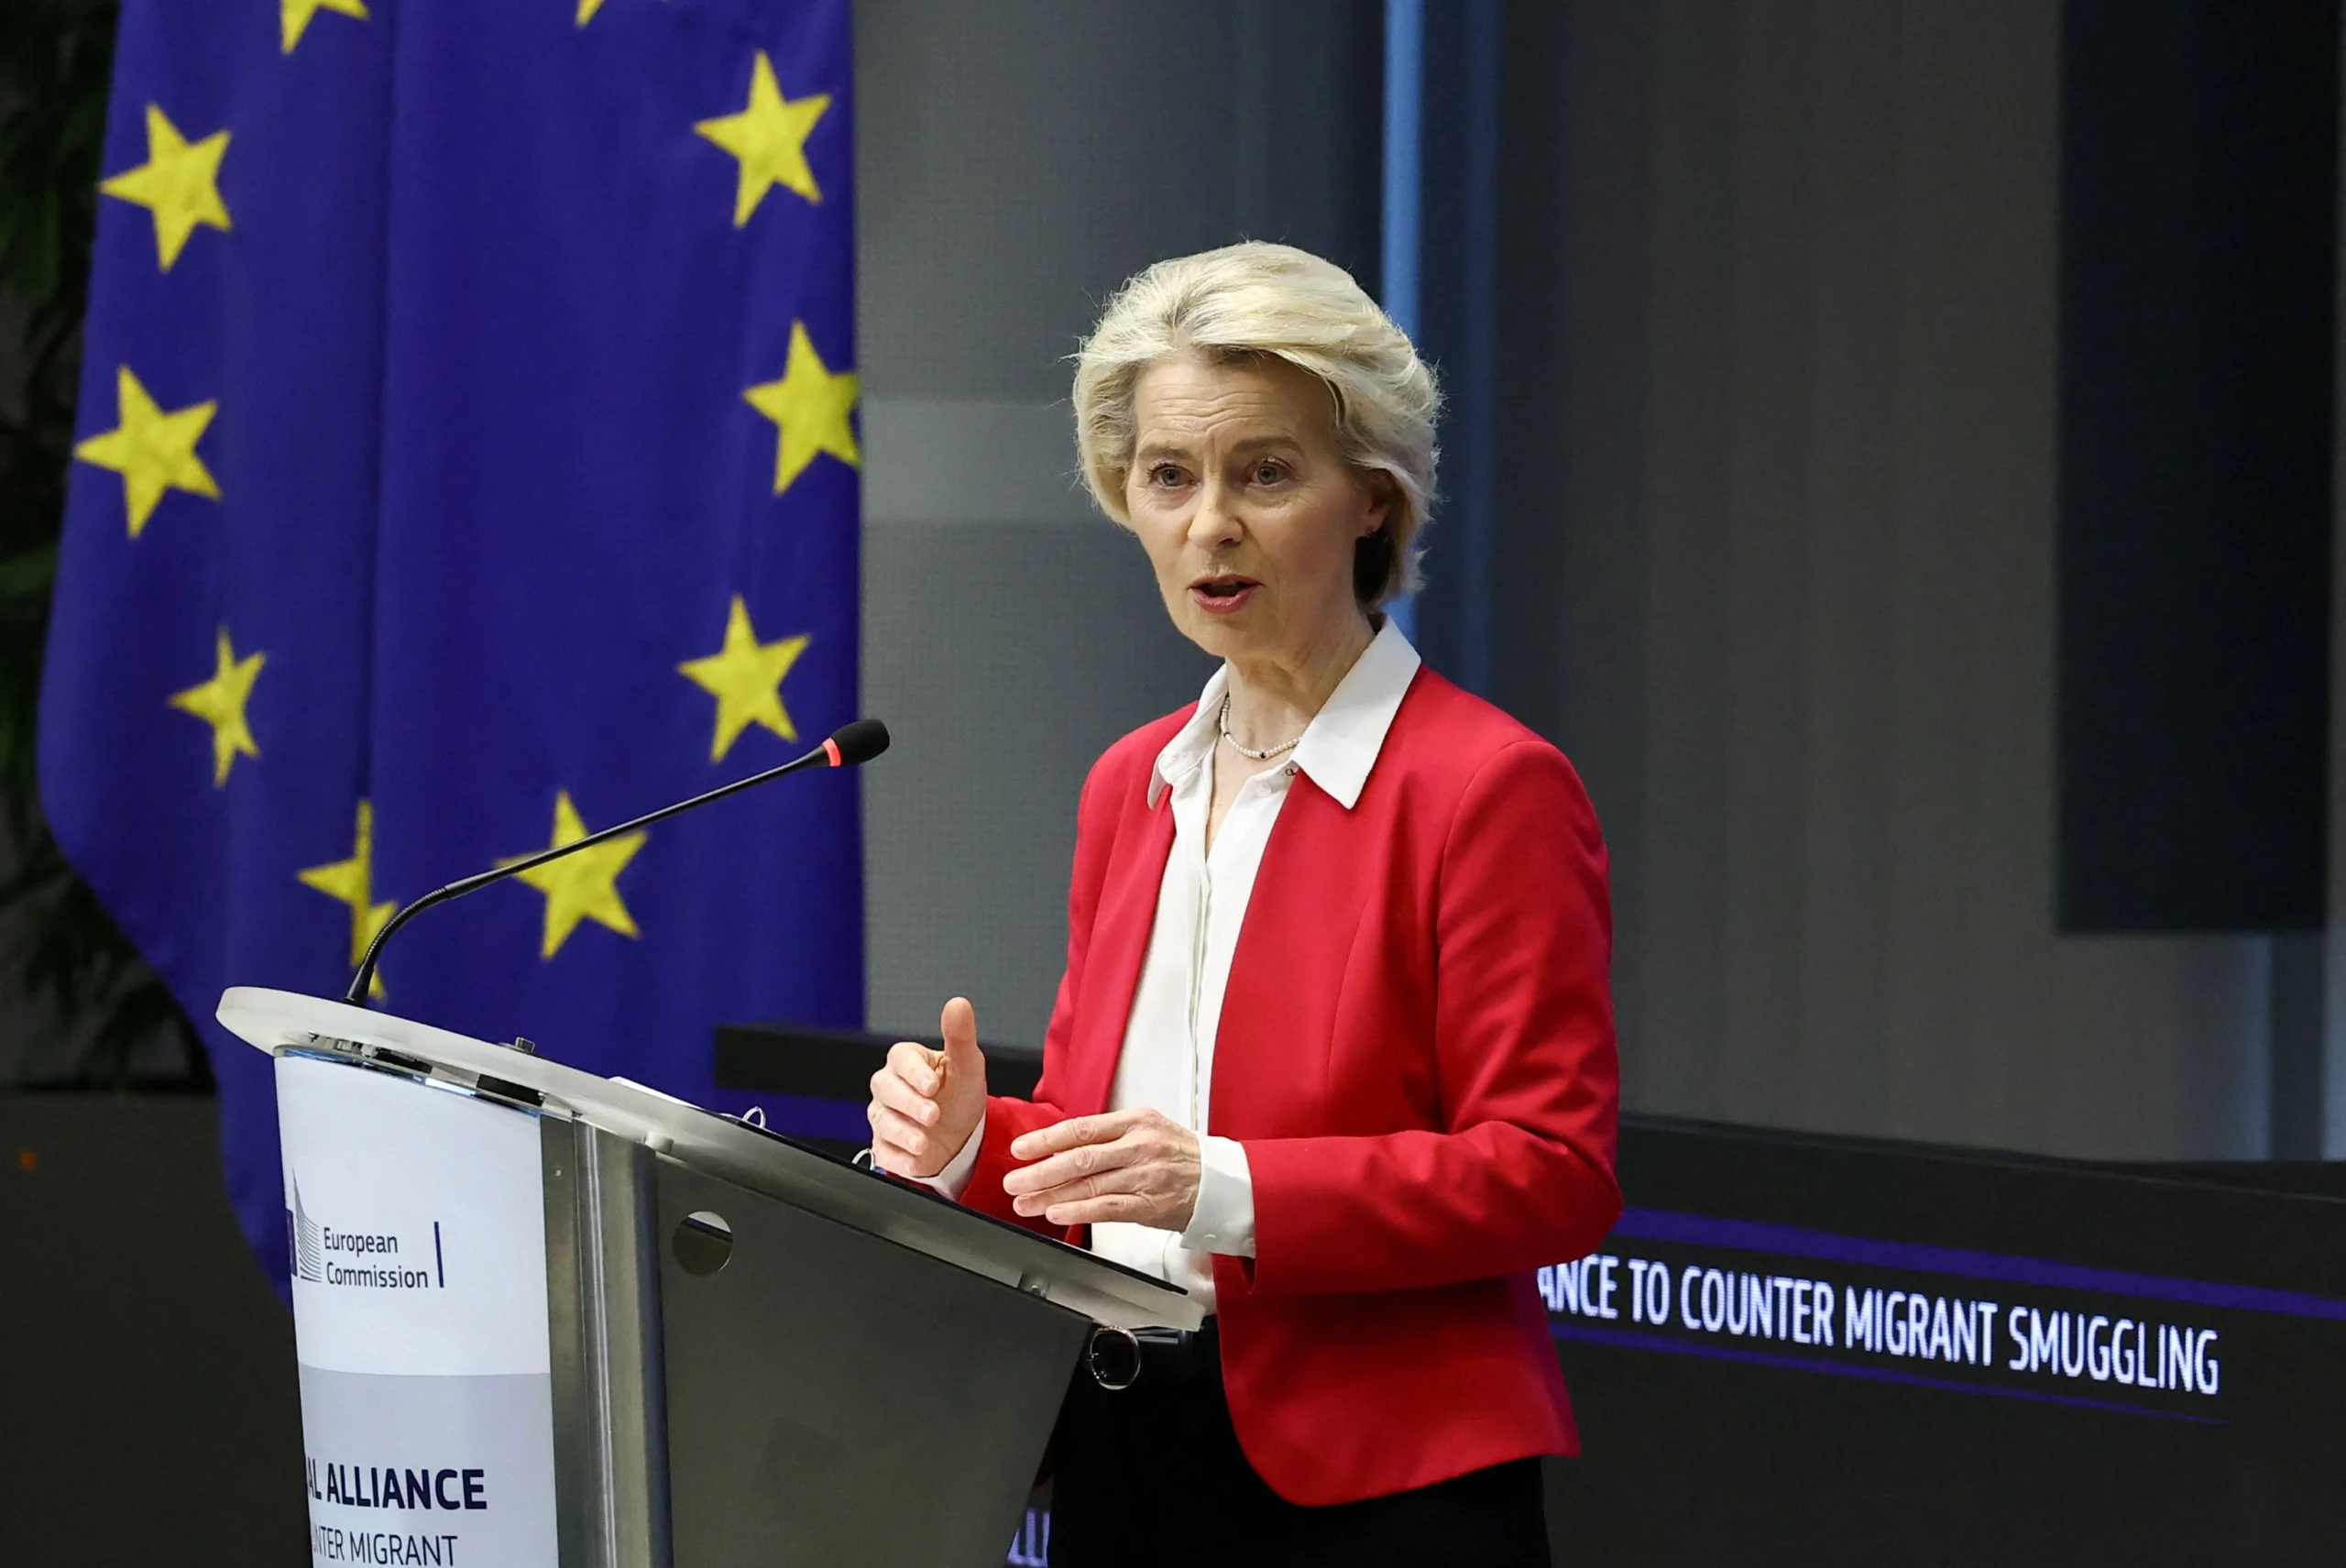
Commission President von der Leyen outlining EU trade policy in Brussels. Source: Yves Herman / REUTERS
The €1 Billion-a-Day Dilemma: Inside Brussels’ Trade Ultimatum
In her 2026 State of the Union address, European Commission President Ursula von der Leyen delivered her sternest warning to date regarding economic relations with Beijing. Citing structural industrial overcapacity in China and subsidized export dumping into the Single Market, von der Leyen emphasized that Europe’s trade deficit with China—now running at approximately €1 billion every single day—has crossed a critical threshold.
While reaffirming that diplomatic dialogue remains open, von der Leyen signaled that Brussels’ patience with protracted negotiations has expired:
“Words are good. But deeds are better. If market imbalances persist and level-playing-field conditions are not restored, the European Union will use all tools at its disposal to rebalance trade.” — Ursula von der Leyen, President of the European Commission
According to official data released alongside the address by the European Union External Action Service, the EU’s merchandise trade deficit with China has expanded sharply over the past decade. The expansion is driven by state-directed investments in clean technology, advanced industrial machinery, and automotive manufacturing, combined with persistent market barriers facing European exporters in mainland China.
Deconstruction of the EU’s Trade-Defence Arsenal
To move beyond political warnings, the European Commission is mobilizing a multi-layered regulatory architecture designed to shield European industries from non-market practices.
| Trade Defence Instrument | Legal Basis & Focus | Operational Impact on Chinese Exports |
|---|---|---|
| Foreign Subsidies Regulation (FSR) | EU Regulation 2022/2560 | Allows Brussels to inspect and block foreign state-subsidized companies from bidding on EU public tenders or acquiring European firms. |
| International Procurement Instrument (IPI) | EU Regulation 2022/1031 | Restricts access to EU public procurement markets for companies from countries that discriminate against EU businesses. |
| Anti-Subsidy & Anti-Dumping Duties | EU Regulation 2016/1037 | Enables retroactive tariffs on subsidized goods (e.g., Electric Vehicles, solar modules, wind turbines). |
| Critical Raw Materials Corporation (RESourceEU) | 2026 Industrial Strategy | Co-finances joint purchasing, strategic stockpiling, and processing of rare earth elements to reduce single-source dependency. |
As highlighted by macroeconomic analysis from Reuters Global Economic News, the Commission’s strategy represents a transition from reactive tariff enforcement to proactive market access restriction.
EU and China trade relations face growing regulatory and tariff barriers. Source: Bloomberg / Bloomberg via Getty Images
De-Risking in Action: Critical Minerals & the RESourceEU Imperative
A core pillar of von der Leyen’s strategic agenda is severing Europe’s vulnerable supply chain dependencies. China currently controls over 70% of global lithium refining, 85% of rare earth processing, and a dominant share of permanent magnet manufacturing.
To counter this vulnerability, von der Leyen confirmed the formal launch of the European Critical Raw Materials Corporation under the broader RESourceEU initiative. This entity will serve as a centralized buyer and investor, co-funding strategic mining, processing, and recycling projects within the EU, North America, and partner nations across Africa and Latin America.
Key objectives of the mineral security framework include:
- Extraction Mandates: At least 10% of the EU’s strategic raw materials extracted domestically by 2030.
- Processing Sovereignty: At least 40% of the EU’s annual consumption of strategic raw materials processed within the bloc.
- Diversification Caps: No more than 65% of any strategic raw material sourced from a single third country.
Economic reporting by the Financial Times Trade Analysis notes that these targets represent one of the most aggressive state-supported supply chain realignment efforts in modern European history.
Geopolitical Fallout & Beijing’s Countermeasures
Beijing’s Ministry of Commerce (MOFCOM) has expressed strong opposition to Brussels’ hardening stance, warning that increased trade barriers risk destabilizing global recovery and violating World Trade Organization (WTO) principles.
In response to European investigations under the FSR and anti-subsidy rules, China has initiated targeted anti-dumping probes into European exports, including brandy, dairy products, and agricultural machinery. Analysts anticipate that further unilateral measures by Brussels could prompt reciprocal restrictions on European automotive and chemical majors operating in mainland China.
+-----------------------------------------------------------------------+
|                 EU-CHINA TRADE TENSION CASCADE MATRIX                  |
+-----------------------------------------------------------------------+
| 1. EU Measures: FSR Inspections, Tariff Escalation, Raw Material Caps |
|    │                                                                  |
|    ▼                                                                  |
| 2. Chinese Countermeasures: Target Agribusiness, Spirits, Luxury Goods|
|    │                                                                  |
|    ▼                                                                  |
| 3. Corporate Impact: Supply Chain Realignment, Dual-Hub Production    |
+-----------------------------------------------------------------------+
Strategic Playbook for Global Business Leaders
For corporate executive teams and supply chain planners navigating this evolving landscape, the European Union Trade Policy Framework recommends three strategic adjustments:
- Audit State Subsidy Exposure: European subsidiaries of non-EU firms must conduct thorough audits of parent company subsidies, tax credits, and state grants to avoid disqualification under FSR procurement reviews.
- Diversify Critical Mineral Sourcing: Manufacturers reliant on graphite, neodymium, lithium, or cobalt should secure secondary supply contracts outside China ahead of 2027 compliance deadlines.
- Adopt “China + 1” Regionalization: Multinationals serving both European and Asian markets should decouple supply chains into distinct regional hubs to insulate operations from tariff hikes and export controls.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The global economy is entering a period in which geopolitical conflict, artificial intelligence, energy markets, trade policy and public debt are increasingly moving together.
That was one of the central messages emerging from the Forbes Global CEO Conference 2026 in Singapore, where business leaders gathered under the theme “Speed of Change.” The conference discussion highlighted a world in which tariffs, military conflicts, volatile energy prices and the rapid expansion of artificial intelligence are changing how companies plan for growth.
But the bigger story extends beyond the conference room.
Recent assessments from the World Bank, OECD, IMF and Bank for International Settlements point to an economy that remains surprisingly resilient while becoming more exposed to simultaneous shocks.
The result is a new operating environment for companies and investors: growth is still possible, but the sources of growth—and the risks surrounding it—are changing rapidly.
1. Geopolitics Is Becoming an Economic Variable
For years, businesses often treated geopolitics as an external risk. In 2026, that distinction is becoming increasingly difficult to maintain.
Trade restrictions, military conflicts, sanctions, shipping disruptions and energy-market volatility can now affect corporate earnings almost immediately.
The World Bank says the Middle East conflict has contributed to sharp increases in energy prices and renewed inflationary pressure, while its latest global outlook projects global growth at 2.5% in 2026 under its current assessment. It also warns that additional geopolitical escalation and commodity disruptions could push growth lower.
That means companies are increasingly being forced to consider questions that previously belonged primarily to governments and foreign-policy specialists:
- Where should critical production be located?
- Which trade routes are vulnerable?
- How dependent is the business on imported energy?
- Which markets could be affected by sanctions?
- Can suppliers be replaced quickly?
- How much inventory is necessary to protect against disruption?
For investors, geopolitical risk is therefore becoming part of fundamental analysis rather than simply a headline risk.
2. AI Is Both a Growth Engine and a Financial Risk
Artificial intelligence may be the most important structural force supporting global investment.
The OECD says strong AI-related activity helped sustain investment, production and trade during the first half of 2026. Its September interim outlook projects global GDP growth of 2.9% in 2026 and 3.0% in 2027.
The AI boom is creating demand for semiconductors, data centers, electricity, cloud infrastructure, networking equipment and advanced computing.
But there is a second side to the story.
The Bank for International Settlements has warned that AI-related investment is increasingly debt-financed and that stretched valuations could create financial vulnerabilities if expectations around AI earnings or investment weaken.
This creates an unusual economic dynamic.
AI can simultaneously:
Boost growth → increase investment → raise productivity → strengthen markets
while also potentially:
Increase valuations → encourage leverage → create concentrated exposure → amplify a market correction.
The implication for businesses is straightforward: adopting AI is no longer simply a technology decision. It is increasingly a capital-allocation and competitiveness decision.
3. The Next Phase of Globalization May Be More Regional
One of the most important developments highlighted at the Singapore conference is that globalization is not necessarily disappearing—it is changing shape.
Forbes reported that FedEx executive Richard Smith pointed to continuing global trade growth and opportunities for smaller Southeast Asian economies, while Biocon chair Kiran Mazumdar-Shaw highlighted India’s efforts to position itself as a technology partner through strategic trade and technology relationships.
That suggests the next phase of globalization could be less about one integrated production system and more about multiple interconnected regional networks.
Southeast Asia is particularly important.
Manufacturing diversification, digital infrastructure, strategic trade agreements and rising investment are creating opportunities for countries positioned between major economic powers.
The World Bank’s latest South Asia outlook similarly highlights the region’s resilience, projecting 6.9% growth in 2026, although it warns that elevated energy prices, weather shocks and a reversal in AI investment could create downside risks.
For multinational companies, this could mean a greater emphasis on:
- China+1 manufacturing strategies
- India and Southeast Asian supply chains
- Regional technology corridors
- Multiple sourcing locations
- Localized production
- Cross-border digital infrastructure
The globalization debate is therefore moving from “globalization versus deglobalization” toward “which regions will capture the next wave of globalization?”
4. Energy Prices Could Become the Inflation Wild Card
Energy remains one of the most important transmission channels between geopolitics and inflation.
A military escalation that affects oil production, refining capacity or shipping can increase costs across the economy—from transportation and manufacturing to food and consumer goods.
The OECD notes that renewed disruptions to production and exports in the Gulf have pushed energy prices higher, while elevated refining margins are adding pressure to consumer prices and business costs.
This creates a difficult policy problem.
Central banks may want to support economic growth, but persistent energy-driven inflation can limit their ability to loosen monetary policy.
For companies, higher energy prices can squeeze margins even when revenues remain stable.
For investors, the important question is no longer simply whether oil prices rise. It is whether an energy shock becomes persistent enough to change inflation expectations, interest rates and corporate investment decisions.
5. Public Debt Is Becoming a Constraint on Governments
Another structural challenge is the enormous amount of public debt accumulated across major economies.
The IMF has warned that global public debt is approaching historically elevated levels, while rising borrowing costs can make fiscal management increasingly difficult.
That creates a complicated environment for governments.
During an economic slowdown, governments may want to spend more to support households and businesses. But higher debt-servicing costs reduce the room available for fiscal stimulus.
The pressure is particularly important when an energy shock simultaneously increases inflation and weakens growth.
The IMF has also urged governments to rebuild fiscal space and maintain credible policies as economic risks accumulate.
For markets, this matters because government borrowing affects bond yields, currency markets, investment costs and ultimately equity valuations.
The era in which investors could treat fiscal policy as a secondary consideration may be ending.
6. Financial Markets Are More Vulnerable to an AI-Driven Repricing
The AI investment boom has helped support equity markets and corporate capital expenditure, but it has also created concentration risks.
The BIS has highlighted concerns surrounding stretched AI-related valuations, increased leverage and growing interconnectedness between banks and non-bank financial institutions.
That does not mean an AI crash is inevitable.
Instead, it means investors should distinguish between:
AI as a transformational technology
and
AI-related assets priced for extremely optimistic outcomes.
Those are two very different propositions.
A company can benefit enormously from AI while its stock can still be vulnerable if expectations have moved too far ahead of earnings.
The same principle applies to infrastructure.
Data centers, power generation, semiconductor facilities and cloud infrastructure may have long-term economic value. But if capacity expands faster than sustainable demand, investors could eventually face lower returns or stranded assets.
That concern was also raised during the Forbes conference, where speakers warned that excessive AI infrastructure investment could create stranded assets if the current boom fades.
7. Resilience May Become More Valuable Than Maximum Efficiency
The most important lesson for corporate leaders may be the simplest: the cheapest operating model is not necessarily the safest operating model.
For decades, globalization encouraged companies to optimize supply chains around efficiency, specialization and cost.
The new environment puts greater value on resilience.
That can mean maintaining alternative suppliers, holding strategic inventories, diversifying energy sources, developing cybersecurity capabilities and ensuring that critical technology systems can operate during disruptions.
The BIS has identified AI-related financial risks, leverage, private credit and cyber risks as important areas of financial-stability concern.
This creates a new corporate calculation:
Efficiency reduces costs. Resilience reduces catastrophic risk.
The companies that succeed in the next economic cycle may be those capable of balancing both.
What the 2026 Global Economy Means for Investors
For investors, the changing global landscape suggests that traditional macroeconomic indicators should be combined with a wider set of signals.
Five areas deserve particular attention:
Interest rates
Energy-driven inflation could keep monetary policy tighter for longer than markets expect.
Oil and energy
Sudden changes in energy prices can affect inflation, corporate margins and consumer spending simultaneously.
AI investment
AI remains a major growth opportunity, but valuation and leverage risks need to be monitored.
Geopolitical developments
Trade restrictions, wars, sanctions and shipping disruptions can rapidly alter market expectations.
Regional growth
South Asia and Southeast Asia remain important beneficiaries of supply-chain diversification and technology investment, although both regions remain exposed to energy and global financial conditions.
Why Southeast Asia and South Asia Matter More
The geographic center of global growth is also becoming more important.
Southeast Asia is attracting capital as companies diversify production and supply chains, while South Asia continues to record comparatively strong growth.
The World Bank’s latest South Asia assessment expects regional growth of 6.9% in 2026, with domestic demand and remittance inflows providing important support.
At the same time, the World Bank says Europe and Central Asia face slower growth amid higher energy prices and weaker external demand, although AI adoption could improve productivity and offset demographic pressures.
This reinforces a broader investment theme: the global economy is becoming more fragmented, but opportunities are also becoming more geographically diverse.
The New Economic Equation
The message emerging from Singapore is not that globalization is ending, AI is creating a bubble or the global economy is heading inevitably toward recession.
The more important conclusion is that the rules of economic decision-making are changing.
Companies must now think simultaneously about technology, geopolitics, energy, capital costs, supply chains and regulation.
Investors face a similar challenge.
The winning strategy may not be predicting exactly when the next crisis arrives. It may be identifying businesses, countries and sectors that can remain competitive when the assumptions behind the current economic system change.
The World Bank sees meaningful downside risks from geopolitical escalation and commodity disruptions, while the OECD expects continued but moderate global growth. The IMF has emphasized the need to rebuild fiscal resilience, and the BIS is highlighting vulnerabilities associated with AI valuations, leverage and financial interconnectedness.
Taken together, these assessments point to an economy that is resilient—but increasingly expensive to destabilize.
Bottom Line
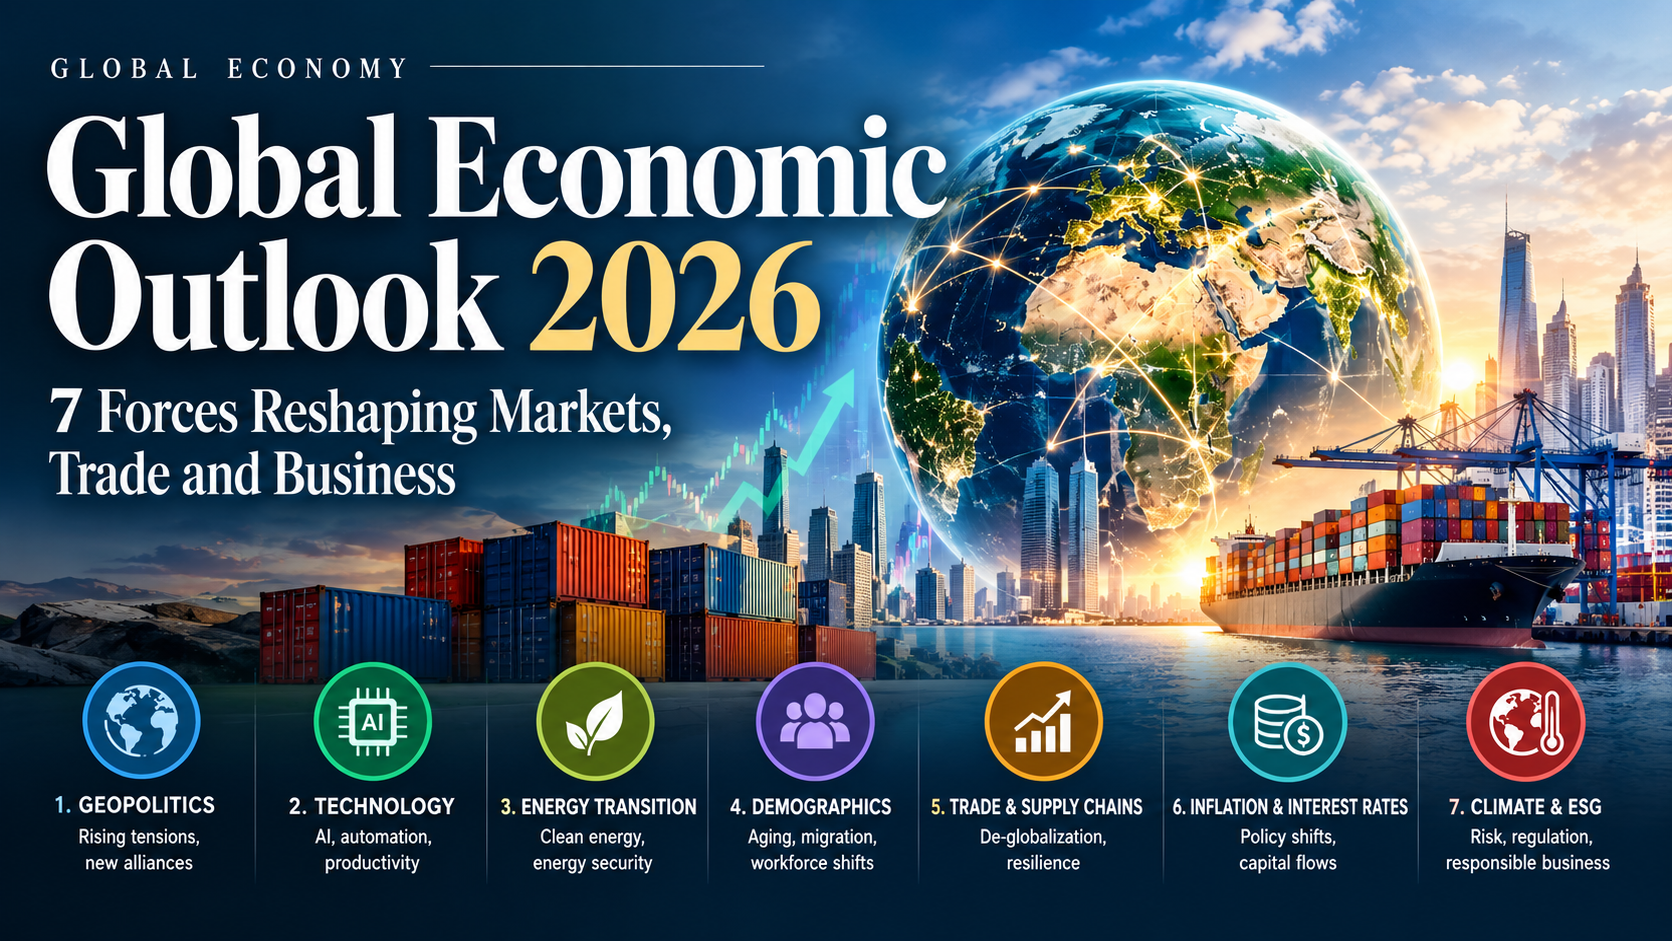
The 2026 global economy is being shaped by seven forces: geopolitical fragmentation, AI investment, regionalized globalization, energy volatility, public debt, financial-market concentration and the growing value of resilience.
The opportunity is significant.
So is the risk.
For business leaders, the priority is adaptability. For investors, it is diversification and disciplined valuation. For governments, it is restoring fiscal and financial buffers before the next shock arrives.
The central economic question for the years ahead may therefore be less “How fast will the global economy grow?”
It may be:
“Which economies, companies and investors are best prepared for a world where the rules keep changing?”
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Key Takeaways
- Geopolitical risk is a measurable drag, not just a headline. A widely cited Federal Reserve study finds that higher geopolitical risk foreshadows lower investment and employment, and that the damage comes from both the threat of events and the events themselves.
- 2026 broke a familiar hedge. With oil driven higher by the Iran war, the U.S. 10-year Treasury yield briefly touched about 5.34%, its highest since 2002, so bonds did not cushion stocks the way textbooks promise.
- Energy is the transmission belt. Roughly a fifth of the world’s oil normally sails through the Strait of Hormuz, which is why a regional conflict becomes a global inflation story.
- Indexes can look calm while the market underneath is not. The S&P 500 sits within a couple of percent of its August record, yet market breadth is weak.
- The practical response is structural, not tactical. Diversification, a sensible time horizon and a plan for rebalancing do more than guessing the next headline.
Every few years a news story makes investors feel that the world has changed overnight. A tanker stops moving. A central bank surprises the room. A border closes. Then your portfolio app lights up red, and the temptation to do something becomes almost physical.
This guide is about doing the right something. It explains how international affairs actually reach your investments, what the evidence says about geopolitical shocks, what has happened in 2026 so far, and how to build a portfolio that can absorb the next surprise without a panic sale. It is general information, not personalized financial advice.
How a Distant Conflict Ends Up in Your Account
Geopolitics doesn’t touch prices directly. It moves through a few well-worn channels.
- Commodities. War and sanctions disrupt supply of oil, gas, grain and fertilizer. Prices jump, and costs ripple through transport, food and manufacturing.
- Inflation and interest rates. Higher energy prices push inflation up, which can force central banks to raise rates or delay cuts.
- Currencies and capital flows. Money rotates toward perceived safe havens and away from import-dependent economies.
- Corporate planning. Executives delay investment when the outlook is murky, which is exactly the effect researchers measure.
- Sentiment. Fear alone can reprice risk assets, even before any physical disruption shows up in the data.
The academic backbone here is the geopolitical risk index built by Fed economists Dario Caldara and Matteo Iacoviello. Their paper, published in the American Economic Review, finds that higher geopolitical risk is associated with lower investment and employment and with a greater probability of disasters and larger downside risks. Industries and firms more exposed to those risks cut investment more.
What 2026 Has Looked Like So Far
Start with the shock. Iran’s reported closure of the Strait of Hormuz in early March sent Brent crude sharply higher, as Yahoo Finance reported at the time, and Treasury yields rose on bets that inflation would run hotter. Within about a week, an AP report cited Rystad Energy estimating that more than 12 million barrels of oil equivalent per day had been taken offline.
Since then, the conflict has produced a pattern of hope and disappointment. Brent fell more than 7% in one early-August week on signals of a deal to reopen the strait, per CNBC, then rebounded as the prospects faded. By October 1, Brent was back above $100.
The knock-on effects reached everyday costs. U.S. on-highway diesel averaged $6.382 a gallon in the week of September 28, about $2.63 more than a year earlier.
Where markets stood on October 5
| Indicator | Level | What it signals |
|---|---|---|
| S&P 500 | About 7,720 | Near records, but narrow leadership |
| Nasdaq Composite | About 27,190 | Tech still carrying the index |
| U.S. 10-year Treasury yield | About 5.28% | Borrowing costs near two-decade highs |
| WTI crude | About $90 | Energy still priced for disruption |
| Gold | About $4,190 an ounce | Elevated, but not a one-way bet |
| U.S. Dollar Index | About 102 | A firm dollar tightens conditions abroad |
Figures are from Schwab’s market update and are rounded. Schwab also noted that the S&P 500 Equal Weight Index had posted its seventh straight weekly loss, a sign that gains are concentrated in a small group of large stocks.
The Hedge That Didn’t Hedge
For decades, investors assumed bonds would rise when stocks fell. A geopolitical energy shock can break that assumption, because the problem isn’t weak growth. It’s inflation, and inflation pushes bond yields up and prices down.
You can see it in 2026. The 10-year Treasury hit highs not seen since 2023 in early September, according to CNBC, and then climbed past 5.3% by October 1, a level last seen decades ago. The Federal Reserve raised rates in September to a 3.75% to 4.00% range, its first hike since 2023, and its next meeting is October 27 to 28.
The UK shows the same pattern. Its 10-year gilt yield hovered near 5.4% and the 30-year yield approached 6%, according to Trading Economics, as a global bond sell-off hit one market after another.
The lesson isn’t that bonds are broken. It’s that which kind of shock you face determines which assets protect you. A growth scare favors long-duration government bonds. An inflation scare punishes them.
How Different Assets Tend to React
| Asset | Typical behavior in a Gulf supply shock | Caveat from 2026 |
|---|---|---|
| Energy stocks and commodities | Often benefit as prices rise | Prices can reverse fast on peace headlines |
| Broad equities | Dip on the shock, then recover if growth holds | Leadership can be narrow and fragile |
| Long-term government bonds | Normally a safe haven | Fell when the shock was inflationary |
| Gold | Traditional geopolitical hedge | Highly volatile; forecasts miss often |
| Cash and short-term bills | Stable, with rising yields | Loses ground if inflation persists |
| Import-dependent currencies | Pressured by a higher oil bill | Depends on reserves and policy credibility |
On gold, remember how hard it is to time. JPMorgan was reported in March forecasting gold at $6,300 an ounce by the end of 2026. In early October it traded near $4,190. A gold gain of 7.1% in a single August week was its best weekly performance since January, which also shows how violently it can move in both directions.
Why Your Home Market Matters
Geopolitics hits countries unevenly. An oil shock is a windfall for some and a bill for others.
| Exposure type | Typical pressure points | Examples |
|---|---|---|
| Net energy importers | Higher import bills, weaker currencies, inflation | Pakistan, China |
| Major energy exporters | Stronger trade balances, sanction and logistics risk | Canada, Russia |
| Trade and finance hubs | Shipping costs, risk-off capital flows | Singapore, UK |
| Mixed commodity economies | Depends on the commodity mix | Malaysia, Indonesia |
If most of your income, spending and savings sit in one currency and one market, a geopolitical shock that hurts that economy hits you three times. Spreading exposure across regions and currencies is the cheapest protection available.
A Practical Framework for Investors
None of this requires predicting the next headline. It requires a plan you can follow when the headline arrives.
1. Decide what job each asset does
Equities for growth. Government bonds for stability in growth scares. Real assets or inflation-linked instruments for inflation scares. Cash for liquidity. If you can’t name the job, you probably don’t understand the risk.
2. Match your horizon to your holdings
Money you need within a few years shouldn’t sit in assets that can fall sharply during a crisis. Money you won’t touch for decades can ride out volatility that would be unbearable on a shorter clock.
3. Rebalance by rule, not by mood
Set thresholds in advance, such as reviewing when an asset class drifts five percentage points from target. Rebalancing forces you to trim what has run up and add to what has fallen, which feels wrong in the moment and works over time.
4. Check your inflation sensitivity
Ask what your portfolio does if energy prices stay high for a year. Long-duration bonds, rate-sensitive stocks and thin-margin businesses tend to struggle. Companies with pricing power tend to cope better.
5. Watch the transmission, not the noise
Four numbers tell you more than most cable-news segments: oil prices, bond yields, the dollar and central-bank decisions. If they are calm, the headline is probably just a headline.
Mistakes to Avoid
- Selling after the drop. Geopolitical selloffs are often sharpest early, so panic exits tend to lock in losses.
- Treating gold or any single asset as a guarantee. Hedges are probabilities, not promises.
- Ignoring currency risk. A foreign investment can rise in local terms and still lose in yours.
- Overreacting to forecasts. Price targets and scenario headlines are guesses, as the gold example shows.
Asked & Answered
Do wars always crash the stock market?
No. Research finds that higher geopolitical risk tends to weigh on investment, employment and stock returns, but the size and duration vary widely. Markets often absorb a shock and recover if the economy underneath stays healthy.
Why did bonds fall when stocks were under pressure in 2026?
Because the shock was inflationary. Higher oil prices raised inflation expectations, which pushed yields up and bond prices down, even while equities wobbled.
Is gold a reliable geopolitical hedge?
It can help, but it is volatile and hard to time. Gold moved sharply in both directions this year, and forecasts have repeatedly missed.
How does a Strait of Hormuz disruption affect everyday costs?
Roughly a fifth of the world’s oil normally passes through the strait. When that flow is disrupted, crude, diesel and shipping costs rise, which feeds into transport, food and manufacturing prices.
What should I do with my portfolio when conflict flares?
Start with your plan, not the news. Confirm your asset allocation matches your goals and time horizon, rebalance if you’ve drifted, and avoid large moves made in a hurry. For decisions specific to your situation, talk to a qualified financial adviser.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Key Takeaways
- The “Planet Labs and Goldman” link is research coverage, not a partnership. We found no public announcement of a commercial deal. Goldman Sachs analysts cover Planet Labs (NYSE: PL) with a Neutral rating and have raised their price target at least twice this year, first to $18 and then to $20.
- The business is growing fast. Planet’s second-quarter fiscal 2027 revenue hit a record $116.1 million, up 58% year over year, with backlog of about $814.9 million.
- The stock has been a roller coaster. It peaked at $51.76 on May 28, according to TheStreet, and is now down roughly 11% for the year.
- Satellite data has been a Wall Street edge for over a decade. Academic work on parking-lot imagery shows funds have profited from it, and that the advantage stayed concentrated among a select few large investors.
- The next chapter is defense, sovereign demand and AI in orbit. Those are lumpier, bigger-ticket revenue streams than retail parking lots ever were.
Type “Planet Labs Goldman” into a search bar and you’ll find a jumble of analyst notes, price targets and stock-move headlines. It’s natural to assume the two companies are working together. As far as the public record shows, they aren’t.
The real connection is more interesting. Planet Labs is one of the clearest examples of a company turning pictures of Earth into financial-grade information, and Goldman Sachs is one of the institutions deciding what that business is worth. Meanwhile, the broader market for satellite imagery in investing has been quietly maturing for more than a decade.
This guide separates the signal from the noise: who Planet is, what Goldman thinks, how Wall Street has used satellite data, and what to track if you want to evaluate the opportunity yourself. It’s information, not investment advice.
What Planet Labs Actually Sells
Planet Labs PBC, based in San Francisco, operates a large fleet of Earth-observation satellites. The company provides near-daily imagery of the planet’s landmass and sells it, along with analytics, to governments and commercial customers in agriculture, energy, environmental monitoring and defense.
Three product ideas matter for this story:
- Daily, wide-area imagery. Frequency is the product. A picture that updates every day reveals change, and change is what investors and intelligence analysts pay for.
- Specialized sensors. Planet’s Tanager spacecraft targets greenhouse gases such as methane, which turns an environmental question into a measurable data feed.
- Satellite services for sovereign customers. Governments increasingly want their own dedicated capability, and Planet builds and operates it for them.
The Latest Scorecard
Planet reported second-quarter fiscal 2027 results (quarter ended July 31, 2026) in early September. Here is how the numbers looked, from the company’s earnings release and the earnings-call recap.
| Metric | Result | Why it matters |
|---|---|---|
| Revenue | $116.1M, up 58% year over year | A record quarter, well above what analysts expected |
| Net loss | $9.4M, versus $22.6M a year earlier | Losses are shrinking |
| Adjusted EBITDA | $13.9M profit | Operating leverage is showing up |
| Backlog | About $814.9M; roughly half converts within 12 months | Gives forward visibility |
| Cash and short-term investments | $865.4M | Funds capital-intensive satellite builds |
| Defense and intelligence revenue | Up more than 90% | The fastest-growing customer group |
| Third-quarter guidance | $101M to $105M | Below the roughly $114M analysts expected |
| Fiscal 2027 revenue guidance | $430M to $441M, up 40% to 43% | Raised at the low end |
Two things deserve a flag. First, about 12% of second-quarter revenue was “point-in-time” revenue from a satellite handover, versus 1% a year earlier. That kind of revenue is real, but lumpy. Second, the soft third-quarter guide is exactly why the stock reacted so sharply, as 247WallSt noted.
Where Goldman Sachs Fits In
Goldman’s role in this story is as an evaluator. Its equity-research team rates Planet Neutral, which generally signals that the analysts don’t expect the shares to meaningfully beat or lag their coverage group.
The firm’s price-target path tells you how its view evolved:
- March 23, 2026: target raised to $18 from $16.40 after quarterly results beat expectations, driven by defense, intelligence and civil government demand.
- April 20, 2026: target raised to $20 from $18, reflecting improved confidence in the commercial outlook.
In the March note, the analyst said Planet was seeing strong demand signals and making sensible long-term investments. In other words, Goldman liked the business but wasn’t sold on the price. That’s the common story with a stock that had already climbed about 793% over the prior year, according to Investing.com.
The Stock: Boom, Bust, Rebuild?
Planet shares rode a speculative wave early in 2026, peaked at $51.76 in May and have corrected since. TheStreet reports the stock is down about 11% year to date but up nearly 18% over twelve months.
Recent catalysts include:
- A successful launch of 20 satellites, including 18 SuperDove imaging satellites, a Tanager-2 hyperspectral satellite, and an experimental space-based AI computing node developed with Alphabet.
- A record quarter and a growing backlog.
- Sovereign wins such as a seven-figure contract with the Greek government, reported by Investing.com.
The risks are just as concrete. Capital spending is heavy, GAAP profitability remains out of reach, revenue timing can be uneven, and the sector’s enthusiasm can evaporate quickly.
How Wall Street Has Used Satellite Data
Long before Planet was a public company, investors figured out that pictures from orbit could predict earnings.
The best-known example is the parking lot. Companies began selling analysis of retailers’ car counts in the early 2010s. Researchers at UC Berkeley examined 4.8 million images covering 67,000 U.S. stores and found the strategy could indeed deliver an edge, and that the data hadn’t spread much beyond hedge funds. Their warning was blunt: the practice may disadvantage everyday investors who can’t see the same data.
A CNBC feature on alternative data explained the basic logic. Consistently empty parking lots can signal weak store traffic, giving a fund reason to bet against a retailer before the quarterly report lands.
Satellite data has since widened well beyond retail:
- Commodities: crop health, soil moisture and storage activity.
- Energy: tank levels, flaring and shipping patterns.
- Supply chains: port congestion, factory activity and construction progress.
- Climate and ESG: methane plumes, deforestation and land-use change.
A Simple Framework for Judging a Geospatial Stock
| Question | What to look for | Planet today |
|---|---|---|
| Is demand durable? | Backlog and recurring contracts | About $815M backlog; 98% of annual contract value is recurring |
| Is growth profitable? | Adjusted EBITDA and free cash flow | Adjusted EBITDA positive in Q2, guided to a loss in Q3 |
| How concentrated is the customer base? | Government vs. commercial mix | Defense and intelligence growing fastest |
| Is the balance sheet strong? | Cash versus capex needs | $865M cash against $100M to $115M of planned capex |
| Is revenue predictable? | Share of lumpy, point-in-time sales | 12% in Q2, up sharply from a year ago |
Three Risks the Headline Numbers Don’t Show
Strong quarters can hide structural questions. If you’re weighing Planet or any rival, put these three on your checklist.
- Competition. Earth observation is crowded, and governments can choose among several suppliers. One Seeking Alpha analysis argues that the business is strong but that competition remains a long-term risk and valuation may cap future returns.
- Deal conversion. Large sovereign contracts move the needle, but they arrive on irregular timelines. Coverage of the September report pointed out that Planet’s conversion rate on bigger sovereign deals is still being established, which leaves room for guidance to slip if timing moves.
- Narrative dependence. Space stocks trade as a group. When enthusiasm around the sector fades, even companies with improving fundamentals can fall hard, which is part of what the 2026 round trip from $51.76 looks like.
None of these cancel the growth story. They explain why a 58% revenue increase and a falling share price can show up in the same month, and why a Neutral rating from an analyst can be perfectly consistent with a rising business.
The Compliance Question
Is it fair for a fund to trade on satellite imagery? Generally, publicly observable data processed legally is a legitimate research input. The sensitive lines involve how data is collected, what contracts permit, and whether any of it amounts to material nonpublic information. Investors should treat the source as an essential part of due diligence.
Asked & Answered
Does Goldman Sachs partner with Planet Labs?
We found no public announcement of a commercial partnership. Goldman’s visible connection is analyst coverage: a Neutral rating with price targets raised in March and April of 2026.
What does a Neutral rating mean?
It signals that the analysts don’t expect the stock to meaningfully outperform or underperform the companies they cover. It is not a sell call.
Is Planet Labs profitable?
Not on a GAAP basis. It posted a $9.4 million net loss in the latest quarter, though adjusted EBITDA was positive at $13.9 million and losses have narrowed from a year earlier.
How do hedge funds use satellite imagery?
Typical uses include counting cars at retailers, estimating crop yields, tracking oil storage and monitoring shipping. The goal is to see change before it appears in company reports.
Is trading on satellite data legal?
Using lawfully obtained, publicly observable information is generally accepted. Problems arise with misrepresented sourcing or confidential information, so funds typically run these datasets past compliance teams.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025