
Human Resourcs
Fed Rate Cut Bets Surge After Shock US Jobs Report Exposes Labor Market Cracks

A labor market that looked resilient just weeks ago has cracked, and traders are now wagering the Federal Reserve will have no choice but to cut interest rates as soon as next month.
The US Bureau of Labor Statistics reported on August 7 that nonfarm payrolls fell by a seasonally adjusted 23,000 in July — a stunning miss against the Dow Jones consensus forecast of an 83,000 gain, according to CNBC. Worse, the agency slashed prior estimates for May and June by a combined 103,000 jobs, dragging the trailing 12-month average payroll gain down to just 34,000 — among the weakest stretches outside a recession in over a decade.
A Report That Rewrites the Narrative
For much of 2026, the prevailing story on Wall Street was that the US economy had shrugged off tariff shocks and geopolitical turbulence. That narrative is now under serious strain. The unemployment rate ticked down to 4.1%, but for the wrong reason: the Bureau of Labor Statistics confirmed the labor force participation rate slid to 61.4%, its lowest level in more than five years outside the pandemic, as hundreds of thousands of Americans simply stopped looking for work.
Household employment — the survey used to calculate the jobless rate — actually fell by 87,000, even as the official rate declined. That divergence is a red flag economists watch closely, because it signals discouraged-worker dynamics rather than genuine labor market strength.
“The July employment report solidified that the labor market is not out of the woods quite yet,” ZipRecruiter labor economist Nicole Bachaud told CNBC.
Where the Damage Is Concentrated
The sectoral breakdown tells a story of an economy bifurcating under pressure. According to a detailed Spokesman-Review analysis of the BLS release:
- Leisure and hospitality employment fell to its lowest level in nearly a year, with restaurants and bars shedding staff — a particularly bitter disappointment given forecasters had expected a boost from the FIFA World Cup, which concluded July 19.
- Financial activities payrolls dropped to a four-year low, with the BLS confirming losses concentrated in credit intermediation (-9,000) and insurance carriers (-7,000). The sector — seen as among the most exposed to AI-driven automation — is now down 121,000 jobs since its May 2025 peak.
- Retail trade shed jobs at warehouse clubs, supercenters and general merchandise stores (-21,000), alongside a smaller decline at gasoline stations.
- Manufacturing and construction, by contrast, continued to climb, a trend economists partly attribute to the ongoing AI data-center build-out even as high interest rates keep homebuilding subdued.
The month also arrived alongside a wave of high-profile layoff announcements from Microsoft, Uber and Visa, reinforcing the sense that white-collar hiring caution has broadened beyond tech.
Why the Iran War Keeps Showing Up in Economic Data
Bloomberg’s economics desk framed the report bluntly: a surprise drop in US payrolls has renewed worries about the health of the world’s largest labor market, with employers growing cautious “amid rising prices and fallout from the Iran war,” according to Bloomberg. Elevated energy costs stemming from Middle East supply disruption have fed directly into hiring plans, compounding the drag from tariff-related input cost inflation that has squeezed margins across retail and manufacturing since early in the year.
Notably, the US is not alone. The same Bloomberg dispatch pointed to the UK, where private-sector employment surveys are even more negative — a downturn now rivaling the length of the 2008-09 financial crisis in the country’s dominant services sector.
What It Means for the Federal Reserve
Markets moved fast. Futures pricing shifted decisively toward a September rate cut in the hours following the release, as traders concluded the Fed’s dual mandate now tilts firmly toward the employment side of the ledger. A weakening labor market, combined with a participation rate at generational lows, gives the Federal Open Market Committee cover to ease even with inflation still running above target — a trade-off that will be closely watched at the Fed’s next meeting.
The revisions matter as much as the headline. A downward adjustment of 103,000 jobs across just two months suggests the “resilient” labor market story that dominated the first half of 2026 was, in part, a statistical mirage. Economists now widely expect the upcoming preliminary benchmark revision — due August 28 from the BLS — to confirm further softness in the annual payroll count.
The Investor Playbook
For traders and portfolio managers across the nine markets this publication tracks, the implications cascade quickly:
- Rate-sensitive equities — regional banks, homebuilders, and small caps — are best positioned to benefit from a confirmed dovish pivot.
- The dollar faces downward pressure as rate-cut expectations firm, a dynamic that matters directly for emerging-market currencies from the Pakistani rupee to the Indonesian rupiah, both of which import inflation partly through dollar-denominated debt and energy costs.
- Treasury yields have room to fall further if the September cut is confirmed, which would ease financing costs for governments and corporates globally.
- Gold and other haven assets typically firm on rate-cut expectations paired with geopolitical risk — a combination now squarely in play.
The Bottom Line
The July jobs report did not show a labor market in freefall, but it did puncture the illusion of a soft landing achieved without cost. Falling participation, deep downward revisions, and sector-specific stress in finance and hospitality point to an economy where headline resilience is increasingly propped up by fewer people working, not more people finding jobs. With the Fed’s September meeting now the market’s central focus, the coming weeks of data — including the August 28 benchmark revision — will determine whether this was a one-month air pocket or the start of a genuine slowdown.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The boutique fitness studio segment is valued at $51.6 billion and growing at approximately 7.6% annually, according to 2026 Fitness Industry Insights — a segment growing faster than the broader $270 billion global fitness market it sits within, and doing so specifically by selling the personalized, community-focused, lower-intensity experience that large commercial gyms structurally cannot replicate. For enterprise investors and premium wellness operators, boutique low-impact training has evolved from a niche urban trend into a defined, monetizable segment with a specific and expanding customer base.
The Demographic Engine Driving Boutique Growth
Two distinct demographic cohorts are converging to drive boutique fitness demand, and understanding both is essential to monetization strategy. Millennials and Gen Z remain the primary volume drivers — 79% of millennials prioritize health and wellness spending, according to 2026 Fitness Industry Insights. But the more commercially significant signal for luxury wellness specifically is the 45+ age group, identified as one of the fastest-growing gym-membership segments and representing a significant, still largely untapped opportunity, per the same source.
This 45+ cohort is precisely the demographic for whom low-impact training — a positioning built around joint-friendly, recovery-oriented, sustainable-intensity programming rather than high-intensity commercial-gym models — carries genuine product-market fit, not just marketing framing.
Gyms and Health Clubs Remain the Volume Leader, But Boutique Commands the Growth Premium
Gyms and health clubs remain the largest single fitness-market segment, accounting for 40% of the global fitness market and an estimated $110.4 billion in 2026, according to 2026 Fitness Industry Insights. But scale and growth rate are different questions — the boutique segment’s 7.6% annual growth reflects consumers actively selecting personalized, community-focused experiences over undifferentiated commercial-gym access, even at a premium price point.
The survival strategy for large commercial operators is instructive by contrast: hybrid models combining in-person membership with digital access, allowing members to train both at the facility and at home, according to 2026 Fitness Industry Insights — an implicit acknowledgment that pure commercial-gym positioning alone is losing ground to more differentiated models.
The AI-Personalization Layer as a Boutique Monetization Tool
Boutique and luxury wellness operators are increasingly deploying the same AI-personalization infrastructure reshaping mass-market fitness — but applied to premium retention and upsell rather than volume acquisition. Gym operators using AI-powered churn-prediction tools have reported check-ins rising 8% year-over-year and new member joins jumping 27%, with Gen Z driving much of that growth, according to Glofox. For boutique operators specifically, AI churn-prediction functions as a high-leverage retention tool given that boutique studios’ unit economics depend far more heavily on member lifetime value than high-volume commercial gyms.
Monetization Model Comparison: Commercial Gym vs. Boutique Low-Impact Studio
| Dimension | Commercial Gym | Boutique Low-Impact Studio |
|---|---|---|
| 2026 market size | $110.4B (40% of global market) | $51.6B |
| Growth rate | Slower, hybrid-model-dependent | 7.6% annually |
| Primary monetization | Volume membership, low per-member ARPU | Premium per-session/membership, high per-member ARPU |
| Key demographic | Broad, price-sensitive | Millennials (79% prioritize wellness) + fast-growing 45+ cohort |
| Retention lever | Facility access breadth, hybrid digital add-ons | Community, personalization, AI-driven churn prediction |
| Differentiation strategy | Scale, convenience, price | Positioning, low-impact/recovery focus, curated experience |
Sources: 2026 Fitness Industry Insights (Fabglassandmirror), Glofox — see citations above.
The Broader Wellness-Tech Infrastructure Boutique Operators Are Riding
Boutique low-impact studios are not monetizing in isolation — they sit within a rapidly scaling AI-and-wellness technology ecosystem. The AI-in-fitness-and-wellness market specifically is valued at $10.68 billion in 2025, projected to reach $57.8 billion by 2035 at a 19.3% CAGR, according to InsightAce Analytic. The virtual fitness market — the hybrid digital layer boutique studios increasingly bundle with in-person sessions — is projected to grow from $43.78 billion in 2026 to $311.91 billion by 2034, a 27.82% CAGR, according to Fortune Business Insights.
Consumer adoption data confirms this infrastructure has genuine pull-through demand: 49% of consumers use AI-powered fitness and wellness apps daily, and 61% of active fitness consumers use AI fitness-tracking apps, per Glofox — meaning boutique operators layering AI-driven personalization into premium low-impact programming are meeting genuine, already-established consumer technology expectations rather than introducing novel friction.
A Monetization Framework for Premium Wellness Operators
- Price for personalization, not access. Boutique unit economics depend on premium per-session or membership pricing justified by curated, low-impact programming — commodity gym-access pricing models undermine the segment’s core value proposition.
- Build explicit 45+ programming and marketing tracks, distinct from the millennial/Gen Z acquisition funnel — this is the fastest-growing, least-saturated membership segment and responds to distinctly different positioning (recovery, longevity, joint health) than younger-cohort messaging.
- Deploy AI churn-prediction as a retention-economics tool, not just an operational nicety — given boutique studios’ high per-member lifetime-value dependency, the documented 8% check-in and 27% new-member-join improvements from AI tooling translate disproportionately into premium-segment revenue protection.
- Bundle hybrid digital access without diluting in-person premium positioning. The virtual fitness market’s 27.82% CAGR signals genuine consumer demand for digital-physical hybrid models — but boutique operators should structure this as a premium-tier extension, not a discount substitute, to preserve the segment’s pricing power.
- Treat community and curation as the defensible moat. Unlike commercial gyms competing on facility breadth and price, boutique studios’ structural advantage — community-focused, personalized experience — is precisely what large operators’ hybrid pivot cannot fully replicate, and should anchor both product design and premium pricing justification.
The Bottom Line
Luxury wellness and boutique low-impact training have moved beyond lifestyle-trend status into a quantifiable $51.6 billion segment growing faster than the broader fitness market, powered by a genuine demographic tailwind — the underserved, fast-growing 45+ cohort — and increasingly monetized through AI-driven personalization and retention tooling rather than facility scale. For premium wellness investors and operators, the highest-conviction opportunity is explicit 45+-focused programming layered with AI-driven retention economics, positioned and priced as a differentiated experience rather than a discount alternative to commercial gym access.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
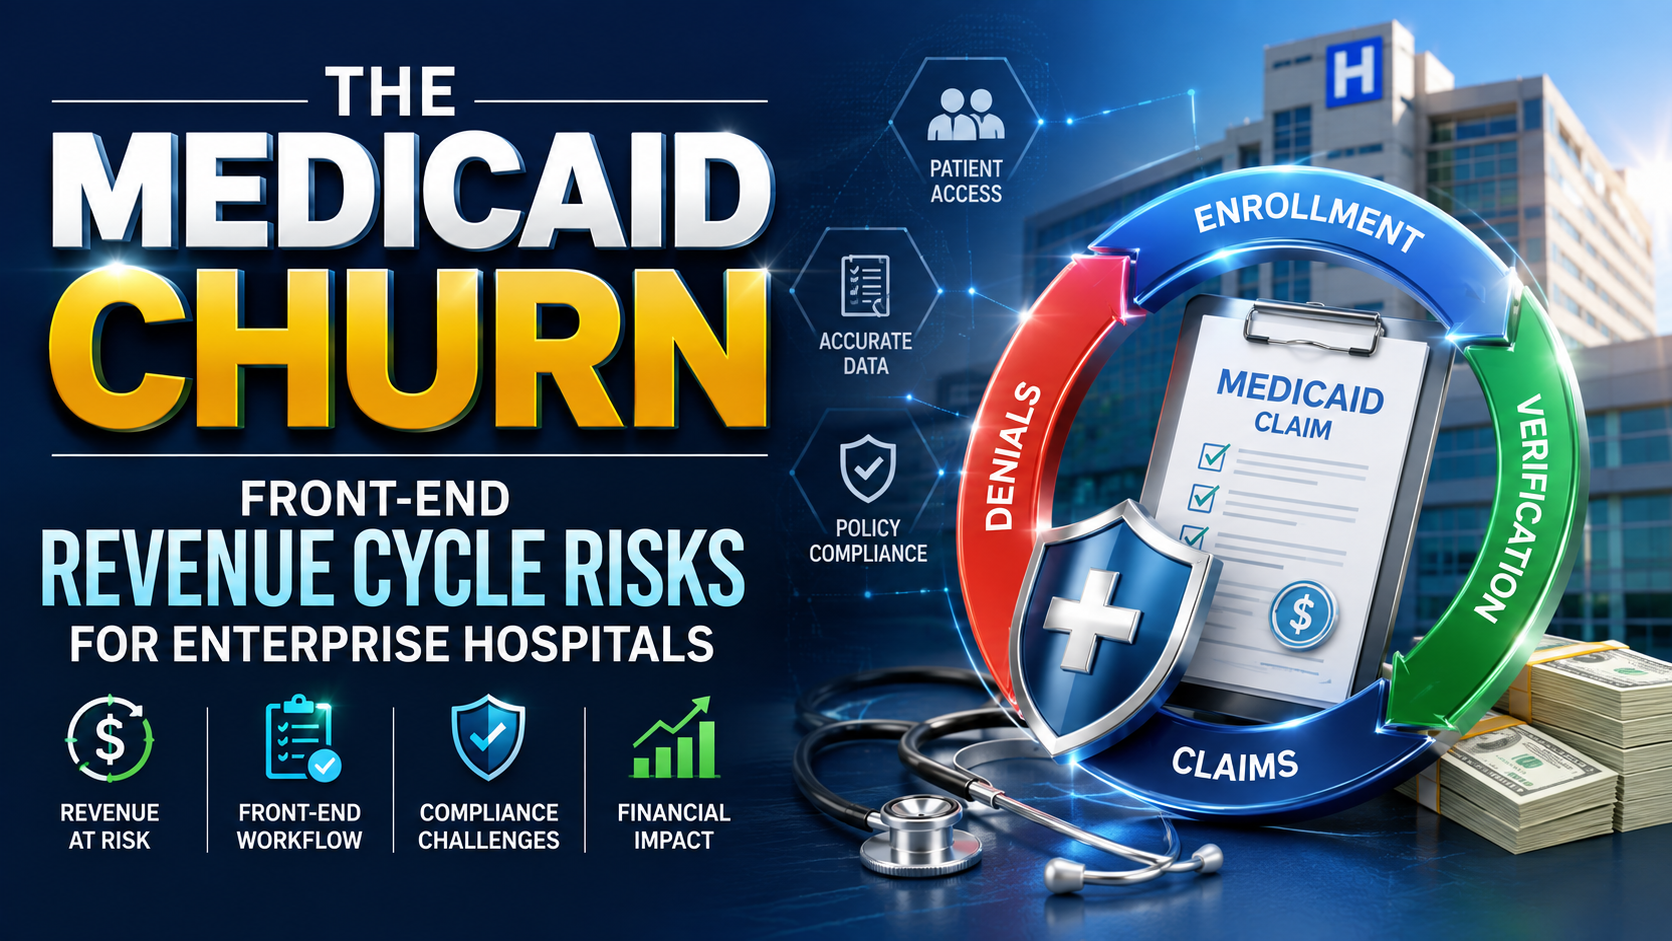
CMS published an interim final rule on June 3, 2026, requiring adult Medicaid enrollees aged 19–64 to meet an 80-hour-per-month work or community-engagement threshold as a condition of continued eligibility, according to Exactrx. The rule took effect July 31, 2026, with full state compliance required by January 1, 2027, per contractingproviders.com. For enterprise hospital systems and revenue-cycle leaders, this is not a distant policy abstraction — it is a payer-mix event with a known start date, a projected enrollment impact, and a direct, quantifiable path into accounts-receivable performance.
The Regulatory Timeline Enterprise Finance Teams Need
| Date | Milestone | Source |
|---|---|---|
| July 4, 2025 | Section 71119 of H.R. 1 (One Big Beautiful Bill Act) signed into law, establishing statutory basis | contractingproviders.com |
| June 3, 2026 | CMS publishes interim final rule detailing 80-hour/month work requirement | Exactrx |
| July 31, 2026 | Work-requirement rule takes effect | contractingproviders.com |
| September 2026 (est.) | Patient inquiries about coverage status begin increasing, per ContinuumCloud | ContinuumCloud |
| December 31, 2026 | Deadline for redetermination workflows to be fully operational | PointCare |
| January 1, 2027 | Full state compliance required; twice-yearly (semiannual) redeterminations begin for expansion adults | PointCare, ContinuumCloud |
Sources: Exactrx, contractingproviders.com, ContinuumCloud, PointCare — see citations above.
The Enrollment-Loss Numbers, Reconciled
Multiple projections exist, and enterprise finance teams should understand why they differ:
- CMS’s own interim final rule projects approximately 2.3 million fewer Medicaid enrollees in fiscal year 2027, rising to over 3 million in subsequent years, per Exactrx.
- The Congressional Budget Office’s earlier, broader estimate projects a reduction of 5.2 million adults by 2034 — a longer time horizon than CMS’s near-term figure, per definitivehc.com.
- A separate CBO estimate cited elsewhere projects 4.8 million people losing coverage over the next decade, per ContinuumCloud — broadly consistent with the CBO’s longer-horizon figures.
- These sit within a larger estimated 15 million people losing health insurance overall under the OBBBA, according to the CBO figures cited by HFMA.
The reconciliation: CMS’s 2.3–3 million figure is the near-term (FY2027) work-requirement-specific impact; the CBO’s 4.8–5.2 million figures represent longer-horizon (through 2034) cumulative effects; and the 15 million figure captures the full scope of the broader legislative package beyond Medicaid work requirements alone.
The Structural Problem: Doubled Administrative Burden, Same Headcount
The operational core of the churn problem is that redetermination frequency is doubling — from annual to semiannual reviews — without a corresponding doubling of enrollment-team headcount, according to PointCare. This structural mismatch is the direct driver of increased “administrative churn” — patients losing and regaining coverage due to paperwork friction rather than genuine eligibility changes.
The scale of this administrative-churn problem is already documented: according to the Commonwealth Fund, cited by RSM, one in ten Medicaid enrollees loses and regains coverage within 12 months, often due to administrative hurdles rather than true eligibility changes — a pattern semiannual redeterminations are projected to intensify.
Quantified Financial Exposure at the Provider Level
A mid-sized provider managing 25,000 Medicaid patients could see an 18% jump in claim denials and a 12% rise in patient churn, potentially resulting in up to $2.4 million in annual uncompensated care losses, according to ContinuumCloud. This is compounded by a broader industry baseline problem: hospitals collectively spent $18 billion fighting claim denials in 2025, with average AR days rising 5.2% despite that spending, per Exactrx.
Beyond Hospitals: The ASC and Outpatient Blind Spot
Revenue-cycle leaders at ambulatory surgery centers and outpatient practices often assume Medicaid churn is primarily a safety-net-hospital and federally-qualified-health-center problem — an assumption worth interrogating, per Exactrx. Medicaid-covered patients represent a meaningful share of elective and semi-elective procedure volume at ASCs in expansion states, and when coverage disappears, those patients don’t vanish from the practice’s patient population — they either shift to commercial/marketplace coverage (requiring new 90–150-day credentialing cycles) or become uninsured, generating direct uncompensated-care exposure regardless of facility type.
An Enterprise Revenue-Cycle Risk Framework
- Verify eligibility at every visit, not just at registration. Point-of-registration-only verification is structurally inadequate under semiannual redetermination cycles; per-visit CHAMPS/HIPAA 270-271 eligibility transactions are becoming operationally necessary, per medsolercm.com.
- Automate re-verification workflows now, ahead of the 2027 deadline. Automated re-verification every five months, aligned to the semiannual cycle, can cut 30–45 days off enrollment-timeline exposure, per ContinuumCloud.
- Diversify payer mix ahead of the enrollment decline, not after. Because commercial-payer credentialing takes 90–150 days, practices waiting until 2027 volume declines materialize will face a revenue gap during the credentialing lag itself, per contractingproviders.com.
- Build patient-facing coverage-retention infrastructure, not just back-office redetermination workflows. Verifying coverage before scheduled services, flagging unconfirmed eligibility, and connecting patients quickly to financial counselors are explicitly recommended proactive steps, per RSM.
- Track license/sanction status continuously. Automated alerts on provider license and sanction changes, aligned to 2026 standards, can materially compress enrollment timelines and reduce compliance risk, per ContinuumCloud.
The Bottom Line for Enterprise Healthcare Finance
Medicaid churn has structurally shifted from an eligibility/enrollment-department problem into a CFO-level revenue-cycle risk with quantified, near-term financial exposure. With semiannual redeterminations doubling administrative workload without a corresponding staffing increase, and CMS’s own projections showing 2.3+ million enrollees losing coverage by FY2027, hospital systems, ASCs, and outpatient practices across all 41 Medicaid-expansion states have a defined, dated window — through December 31, 2026 — to build the automated verification and payer-mix-diversification infrastructure the post-2027 environment will require.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Britain’s labour market has now been shedding jobs for as long as it did during the depths of the global financial crisis — and this time, employers are explicitly naming artificial intelligence as a reason for the cuts.
The closely watched S&P Global/CIPS Purchasing Managers’ Index showed services firms and the wider private sector reducing headcount for a 22nd consecutive month in July 2026, according to data reported by Bloomberg. That run now equals the length of the downturn seen during the 2008-09 crash in the dominant services sector, and is just one month short of matching it across the wider economy.
A Downturn Two Years in the Making
Unlike the 2008 crisis, which was triggered by a sudden banking collapse, this slump has crept up gradually. The survey shows the pace of job losses easing slightly in July compared with prior months, but the cumulative duration — nearly two full years of continuous headcount reduction — is what has alarmed economists watching the data, as detailed by Staffing Industry Analysts.
Crucially, firms surveyed gave two distinct explanations for the cuts: general cost-reduction efforts, and — increasingly — a reduced need for workers after investing in AI tools to boost productivity. That second factor marks a shift from earlier phases of the downturn, when cost pressure alone dominated employer commentary.
The PMI Numbers Behind the Story
The deterioration has been building for months. Earlier readings from S&P Global’s official PMI release showed the sector losing momentum steadily through the spring, with survey respondents explicitly citing the fallout from the US-Iran conflict as a drag on client confidence, layered on top of already-elevated domestic political uncertainty.
Separate flash data tracked by FX.co showed the UK Services PMI slipping to 48.7 in June — below the 50.0 threshold that separates expansion from contraction, and short of the 50.5 markets had expected. That marked the sharpest downturn since January 2023, driven by weaker new business volumes, shrinking order backlogs and further job cuts, even as input cost inflation — from transport to IT equipment surcharges — continued to squeeze margins.
The survey’s own methodology notes are telling: data collected in June found “a sustained reduction in backlogs of work across the service economy, largely reflecting a lack of pressure on business capacity due to weak demand,” according to the official S&P Global report. In plain terms, companies have less work to do, and they are responding by not replacing staff who leave rather than launching mass redundancy rounds — a slower but more persistent form of labour market erosion.
The Political Backdrop
The prolonged downturn deepens pressure on the Labour government, which took office in the summer of 2024 promising to reinvigorate growth. Nearly two years of continuous private-sector job losses is a difficult data point for any incumbent administration to explain away, particularly as it now sits alongside separately reported gilt market volatility and scrutiny of the Bank of England’s policy path.
Why AI Is a Different Kind of Headwind
What distinguishes this downturn from previous UK labour market slumps is the structural, rather than purely cyclical, nature of some of the job losses. Employers citing AI-driven productivity gains as a reason for not replacing departing staff suggests that even a rebound in demand may not translate into a proportional rebound in hiring — a dynamic that echoes concerns raised in the US, where financial-sector employment — an industry widely seen as exposed to AI adoption — has fallen to a four-year low.
Economists warn this creates a harder policy problem than a conventional cyclical downturn. Interest rate cuts and fiscal stimulus can revive demand, but they do less to reverse a structural shift in how many workers a given level of output requires.
What to Watch Next
Three data points will determine whether Britain’s labour market stabilises or deteriorates further into autumn:
- The August PMI releases, which will show whether July’s slight easing in the pace of job cuts was a genuine inflection point or a one-month pause.
- Bank of England commentary on how much weight it assigns to labour market weakness versus persistent inflation in setting the path for interest rates.
- Sector-level AI adoption data, particularly in financial and professional services, where the productivity-driven hiring freeze appears most entrenched.
The Bottom Line
Two years of continuous UK private-sector job cuts is no longer a temporary post-pandemic adjustment — it has become the longest sustained labour market downturn since the financial crisis. With employers now openly citing AI adoption alongside cost discipline as drivers of headcount reduction, the shape of any eventual recovery may look very different from past cycles: output could recover well before payrolls do.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Elon Musk’s Boring Company Hits $23B Valuation After UAE-Led $3 Billion Series D

Middle East War Economics 2026: Oil Prices & Energy Markets

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Asian Markets Outlook 2026: China, Japan & Singapore Stocks

Global Economy 2026: IMF Growth, Inflation & Private Credit

Current Account Deficit (CAD) : Causes and Impact

Balance of Payments (BOP)

The Falkland Islands Dispute: Sovereign Wealth, Offshore Drilling, and Market Impacts

Gross Domestic Product (GDP): Nominal vs. Real

What is Inflation and the Consumer Price Index (CPI)?

US-China Trade Competition 2026: Supply Chain Relocation Guide

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

South-South Trade Expansion: Digital Integration and Emerging Market Growth

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Gold’s Wild 2026: From a Record $5,600 Peak to a 24% Crash and Back Toward $4,500

Oil Surges as Strait of Hormuz Traffic Collapses Again

The Rocket That Won’t Quit: Inside SpaceX’s Falcon 9 Launch Machine

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Retail Earnings Week: What Home Depot, Target & Walmart Reveal

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

Top 30 Stocks for Investment in PSX for Massive ROI in 2026
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025