
Analysis
Grinding the Already Ground: Pakistan’s Inflation Crisis

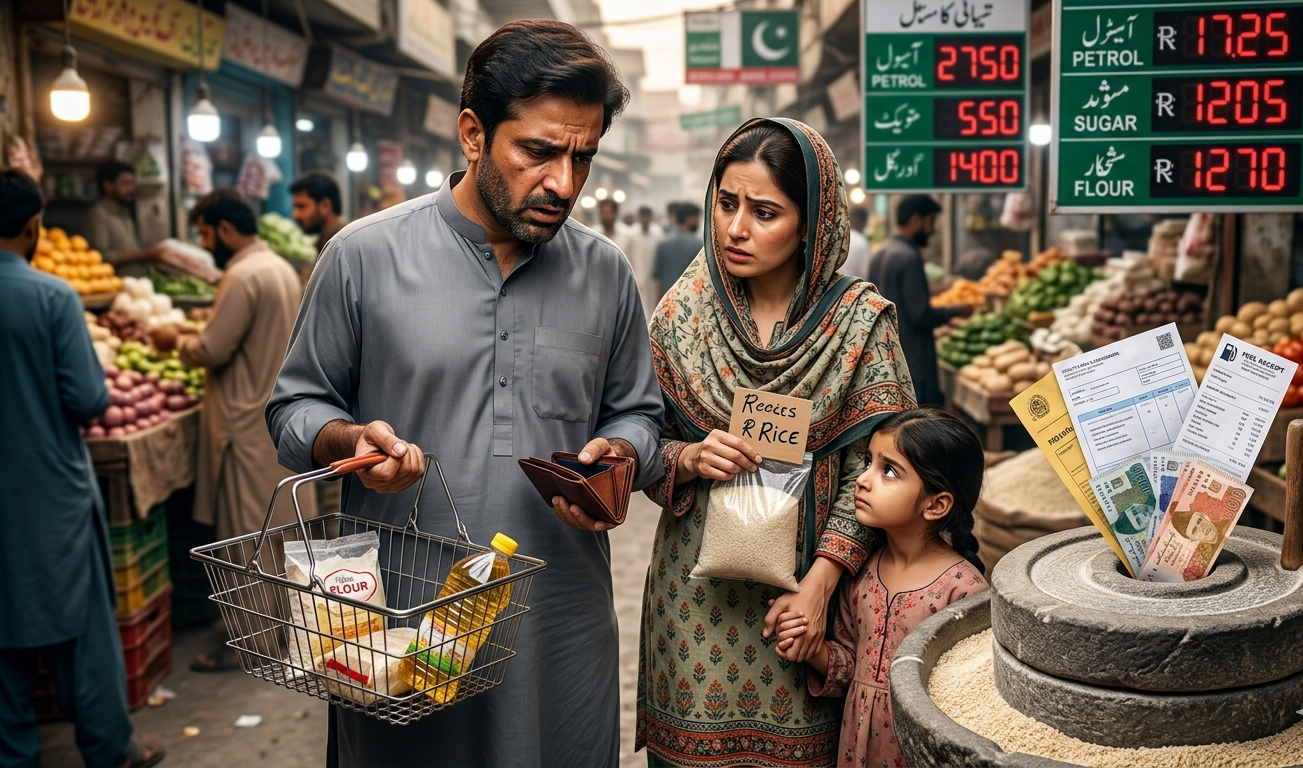
Pakistan’s finance minister Mohammad Aurangzeb presented a budget of Rs 18.77 trillion to the National Assembly on June 12, 2026 with claims that it was a people friendly budget . While the Motorcycle-rickshaw drivers in Sohrab Goth, Karachi, a few kilometers distant, were doing more straightforward math: petrol was now priced at Rs 377.81 per litre, up from Rs 266.17 prior to February, against prices that hadn’t changed in four months. Pakistan’s inflation crisis, lit by a war 1,800 kilometres to the west, had already cost commuters and small traders more than any tax bracket Aurangzeb was about to unveil.
The headline numbers explain the mood.
The data from Pakistan Bureau of Statistics shows that the consumer prices increased 11.7% year over year in May 2026, the highest level since June 2024. Inflation was only 3.5% in the same month last year. Geopolitics is a vast ocean removed from the immediate cause. The war that ensued after the United States and Israel attacked Iranian military and nuclear-related targets on February 28, 2026, closed the Strait of Hormuz to the majority of tanker traffic and sent Brent crude above $100 a barrel for the first time in over three years. With Tehran retaliating against Gulf states and US Central Command attacking Iranian sites on June 11, merchants were preparing for a protracted period of grinding uncertainty rather than a swift conclusion. For an economy that imports nearly all of its crude, the arithmetic was brutal and immediate.
Pakistan’s inflation crisis is, at its core, an energy crisis wearing a grocery bill. Petrol stood at Rs 266.17 a litre on February 1, 2026. By March 7, the government had raised it by Rs 55 in a single notification — the largest one-off increase on record — taking it to Rs 321.17. Three weeks later, with Brent trading above $115 a barrel and the Strait of Hormuz effectively closed, petrol jumped a further 42.7% to Rs 458.40 a litre and diesel rose 54.9% to Rs 520.35, the steepest two-month run-up the country has recorded. Petroleum Minister Ali Pervaiz Malik said at the time that with no resolution to the war in sight, the government could no longer sustain a blanket subsidy.
Five fortnightly cuts followed as Brent eased back from its peak, but the relief has been partial. Petrol and diesel remain roughly 40% above their February 1 baseline even after those reductions. LPG, the cylinder fuel that millions of households use for cooking where piped gas doesn’t reach, sits at Rs 308.76 per kilogram — every adjustment here lands directly on a family’s stove.
The knock-on effect runs through the entire consumption basket. Pakistan’s freight fleet runs almost entirely on diesel, so every increase at the pump arrives a second time at the vegetable stall, the flour mill and the cement yard. In May 2026, the Sensitive Price Indicator, which measures the weekly cost of necessities for lower-income households, increased 12% year over year. This is quicker than the headline CPI and indicates that the burden is falling most heavily on those with the least capacity to absorb it. In response to the deteriorating data, the State Bank’s Monetary Policy Committee raised its policy rate by 100 basis points to 11.50% in April. This was a hawkish indication that the rate reduction that had provided borrowers with some respite during the preceding two years are now off the table for the foreseeable future.Three years ago, in FY2023, headline inflation reached 30.77%; this spike is smaller in percentage terms but is landing on a price level that had already climbed sharply since then, leaving real incomes nowhere close to recovery.
Budget 2026-27 and Pakistan’s Salaried Class: Relief on Paper, Pressure in Practice
Inflation is running high because a war-driven oil shock hit an economy with almost no fiscal cushion. The US-Israel-Iran conflict pushed global energy prices sharply higher just as Pakistan’s IMF programme required it to pass those costs straight through to consumers via fuel, electricity and gas tariffs, with no room for new subsidies under a primary-surplus target.
On paper, the Rs 18.77 trillion budget Aurangzeb presented does try to soften the blow for one group. The salaried class, whose members paid Rs 605 billion in income tax during FY2024–2025—a 55% year-over-year increase driven solely by withholding that provides no opportunity to conceal income—gets four updated slabs and the elimination of the 9% surcharge that had been imposed on higher earnings. The rate decreases from 23% to 20% for those who earn between Rs 2.2 million and Rs 3.2 million per year, and from 30% to 25% for those who earn between Rs 3.2 million and Rs 4.1 million. The minimum wage increases by 10% to Rs 40,700 per month, while government salaries and pensions increase by 7%.
Set against an FBR revenue target of Rs 15.267 trillion — roughly Rs 1.84 trillion, or 14%, higher than the revised FY26 collection — the relief looks smaller. That gap has to be closed somewhere, and general sales tax applies whether a household earns Rs 40,700 or Rs 4 million a month. Meanwhile, the same budget abolished super tax entirely for businesses with annual sales between Rs 15 crore and Rs 50 crore, and cut the rate from 10% to 8% for firms above that threshold — relief that, unlike the salaried class’s slab adjustments, applies regardless of how the broader cost-of-living squeeze plays out at the till.
The energy side compounds the squeeze rather than offsetting it. As part of the same IMF Extended Fund Facility review, Islamabad has assured the Fund that electricity and gas tariffs will keep rising for all but “protected” consumers, with quarterly tariff adjustments and monthly fuel-charge revisions continuing without delay. NEPRA had already layered an additional Rs 3.82-per-unit surcharge onto bills between March and June 2026 — nearly nine times the Rs 0.43 surcharge it replaced — and a further increase to the basic tariff is scheduled for January 2027. The Central Power Purchasing Agency, meanwhile, has recommended a national power-purchase price for FY27 of between Rs 25.69 and Rs 26.69 per unit, a figure that flows almost directly into household bills if NEPRA approves it. Pakistan’s circular debt — the gap between what distribution companies bill and what they actually collect — had already crossed Rs 2.7 trillion before this round of adjustments, and the programme’s preferred fix runs through tariffs rather than through the theft, line losses and collection failures that built the debt in the first place.
The squeeze isn’t confined to fuel and food. Budget 2026-27 layers a new Environmental Levy onto vehicles above 2,000cc — 10% for engines between 2001cc and 3000cc, and 19.5% beyond that — alongside a Federal Excise Duty revision that pushes the Toyota Corolla’s top variant toward Rs 8 million. Electric vehicles were supposed to be the escape route. Instead, with exemptions under the Automotive Industry Development and Export Policy 2021-26 expiring on June 30, imported EVs face sales tax of up to 25%, even as locally assembled units retain a narrower concession — a distinction that means little to a buyer choosing between a used Civic and an EV that, for most households, remains aspirational.
Smartphones tell a similar story. A proposal to cut the PTA’s regulatory duty on premium imported phones from 25% to 18% — championed publicly by IT Minister Shaza Fatima Khawaja, who raised placards on the floor of the National Assembly — was dropped from the final budget after pushback from domestic assembly plants. The total effective tax burden on a $700 smartphone in Pakistan now exceeds 50%, among the highest of any market in the region.
Then there’s solar, the one technology that let households partially opt out of an unreliable and expensive grid. Budget 2026-27 proposes an 18% general sales tax on imported solar panels, reversing years of exemptions that had driven a boom in rooftop installations. The timing compounds an earlier blow: in February 2026, NEPRA replaced unit-for-unit net metering with “net billing,” cutting the buy-back rate for surplus solar power from roughly Rs 26-27 per unit to Rs 10-11, and adding a Rs 1,000-per-kilowatt connection fee for new on-grid systems. For middle-class families who borrowed to install panels specifically to escape Karachi’s Rs 65-per-unit K-Electric tariff and routine 12-hour load-shedding, the rules changed after the investment was already made.
The contrast with the region sharpens the picture. Between February and May 2026, Pakistan’s petrol price rose 64%, even as India kept retail fuel prices frozen and cut its own fuel duties — slashing the petrol levy from Rs 13 to Rs 3 per litre and scrapping the diesel duty altogether — while Bangladesh limited itself to a single roughly 16% increase in April before freezing rates again. Of Pakistan’s immediate neighbours, none absorbed the shock as directly as Islamabad did.
Against that backdrop, the growth numbers look modest. The government’s own FY27 target is 4% GDP growth, itself a step down from the 4.2% goal set for the year now ending — a target the economy missed, expanding by 3.7% instead. The Asian Development Bank projects 4.5% growth for FY27, but notes that downside risks remain significant — language that, with an active regional war still unresolved, may understate the exposure.
The government’s defence rests on a genuine turnaround. The State Bank’s policy rate decreased from 22.5% to 11% over about two years; foreign exchange reserves surpassed $17 billion, up nearly 50% year over year; Pakistan reported a primary surplus equal to 3.2% of GDP in the first three quarters of FY26; and inflation, which peaked near 38% in 2023, had dropped to single digits prior to this year’s shock. throughout the budget presentation, Prime Minister Shehbaz Sharif thanked the public for their patience throughout years of high prices while bluntly acknowledging the cost and informing his cabinet that the new measures will bring challenges and hardship for the average person.
That acknowledgement is precisely what critics seize on. As one analysis weighing the budget against the preceding Economic Survey put it, stabilisation does not equate to development, it merely removes an impediment. Economists note that much of FY26’s fiscal improvement came from a one-off Rs 2,428 billion profit transfer from the State Bank, not from a broadened tax base — meaning the structural problem persists even as headline numbers improve. Salaried workers are taxed at source down to the rupee, while large segments of retail, wholesale and real-estate income remain lightly documented. Indirect taxes such as GST apply uniformly regardless of income, which means a rupee of relief in the withholding tables can be erased many times over by a single increase in the price of flour, fuel or electricity. For the motorcycle-rickshaw drivers of Sohrab Goth, the distinction between cyclical stabilisation and structural reform is academic. What they know is that the fare hasn’t moved and the pump price has.
Pakistan’s 2026 numbers support two honest readings at once. The macro story — reserves rebuilt, a primary surplus posted, a regional war absorbed without a balance-of-payments crisis — is real, and represents progress that looked close to impossible only a few years ago. The household story — an 11.7% inflation print, a fuel bill still roughly 40% above its February baseline, electricity surcharges layered on by IMF design, and now a solar tax that closes off one of the few workarounds millions of families had found — is equally real. The honest path forward runs through the parts of the economy this budget left largely untouched: a tax base still anchored to salaried withholding and indirect levies while retail and property income stay lightly taxed, and an energy sector where “cost recovery” has so far meant recovery from consumers rather than from the circular debt, line losses and IPP arrears that created the bill in the first place. Until that changes, every fiscal year risks becoming an exercise in grinding flour that was already ground.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Despite decades of bans and strict handling mandates, asbestos remains a silent killer across legacy manufacturing plants, shipyards, and modern green-energy infrastructure retrofits. In 2026, regulatory changes by the EPA and tightened occupational health standards have triggered a fresh wave of mesothelioma litigation. Manufacturers attempting to fast-track industrial transitions are encountering catastrophic oversight, exposing workers to legacy toxins and opening corporate parent companies to unprecedented liability.
Navigating a mesothelioma claim in 2026 requires understanding how modern industrial supply chains intersect with historical exposure. Trusts established decades ago are being audited under stricter transparency laws, altering payout ratios and accelerating fast-track settlements for terminally ill plaintiffs.
Modern Industrial Exposure Hotspots
Green Retrofitting and Renewable Energy Infrastructure
A primary source of 2026 asbestos exposure occurs during the decommissioning and retrofitting of older industrial facilities for renewable energy production. Workers insulating electrical grids, modernizing HVAC systems, or upgrading manufacturing floors frequently disturb encapsulated asbestos materials that were improperly documented or ignored during facility audits.
Automotive and Aerospace Supply Chains
With advanced manufacturing booming, workers handling specialized friction materials, gaskets, and heat shields face ongoing risks. Supply chain tracing has become more sophisticated, allowing legal teams to pinpoint exact corporate entities responsible for raw material distribution across multinational borders.
| Industry Sector | Primary Exposure Risk | Legal Venue / Trust | Avg. Claim Value Range |
| Green Energy Retrofit | Disturbed insulation, pipe lagging | Federal Tort / Manufacturer Trust | $1.2M – $3.5M |
| Shipbuilding & Marine | Boiler insulation, structural seals | Asbestos Bankruptcy Trusts | $800K – $2.4M |
| Automotive Manufacturing | Brake components, high-heat gaskets | Third-Party Product Liability | $600K – $1.8M |
Securing Maximum Compensation: Steps for Plaintiffs
Time is of the essence in mesothelioma cases. Plaintiffs and their families must act decisively to secure financial recovery before statutes of limitations expire.
Retain Specialized Counsel: Work exclusively with national mesothelioma law firms possessing deep historical databases of asbestos-containing products.
Audit Employment History: Document every job site, supervisor name, and equipment brand encountered throughout your career.
Expedite Medical Filings: Secure a formal pathological diagnosis quickly to qualify for expedited trust fund distribution and priority trial settings.
“Expert Insight: Modern asbestos litigation is no longer just about historical tracking; it is about holding modern corporations accountable for failing to conduct rigorous environmental safety audits before initiating industrial retrofits.”
By combining meticulous work history reconstruction with aggressive multi-trust filings, victims can secure substantial financial relief to cover specialized immunotherapy and family support.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

10-Year Treasury Yield Tops 5%: What It Means for Mortgages, Stocks, and the Fed

Ceasefire Negotiations in 2026: Predicting the Rebound of European and Asian Economies

Emerging Markets Update: The Impact of World Bank Policies on PSX Stability

Costco Oil Shortage 2026: Will Prices Double for All Synthetic Motor Oils?

Trump’s $5,000 Promise: The Hidden Tax Implications for Retail Investors

Global Economy Outlook 2026: What Ceasefire Talks Mean for the Tech Sector

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Stock Market Crash 2026? How the Trump $5,000 Dividend Impacts Global Inflation

Tax-to-GDP Ratio Explained: Global Benchmarks, Fiscal Sovereignty & 2026 Insights

Trade Deficit & Terms of Trade Explained: Global Impact, Real-World Examples, and 2026 Insights

Supply vs Demand Shocks Explained: Market Equilibrium, Inflation Risks & Policy Responses in 2026

Microeconomics vs. Macroeconomics Explained: Key Differences, Interdependence & Global Impact

Devaluation vs Depreciation: Clear Differences, Causes, and Economic Impact

Purchasing Power Parity (PPP) Explained: Global Rankings, Living Standards & Why Nominal Exchange Rates Mislead in 2026

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Gold’s Wild 2026: From a Record $5,600 Peak to a 24% Crash and Back Toward $4,500

Oil Surges as Strait of Hormuz Traffic Collapses Again

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Global Chip Selloff Deepens: What’s Driving the Aug. 19 Semiconductor Rout

Shein Clothes Quality & Safety in 2026: What Lab Tests Show
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025