
Markets & Finance
Indonesia’s $121 Billion Nickel Bet Is Facing a Battery Chemistry

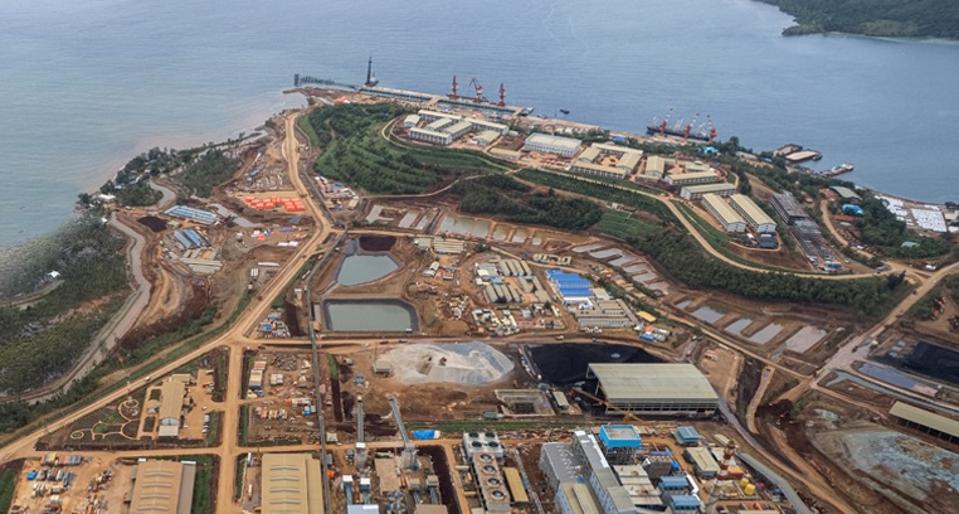
Indonesia is pitching an estimated $121 billion in investment opportunities to build an integrated national EV battery ecosystem, with officials arguing the country is uniquely positioned because four of the six main materials needed for EV batteries are found in abundance domestically, according to ANTARA News coverage of the June 2026 Korea-Indonesia Economic Partnership Forum. The ministry’s long-term downstream strategy could eventually drive total investment to $618 billion, with export value reaching $857 billion and more than 3 million new jobs.
The Policy That Built the Boom
The foundation is a 2020 ban on raw nickel ore exports, designed to force foreign capital into domestic processing rather than allowing Indonesia to remain a raw-material exporter, according to a policy analysis published by CETEX. The strategy has worked at the smelting stage: by 2025, Indonesia had 49 Rotary Kiln Electric Furnace nickel smelters operating domestically, turning raw saprolite ore into nickel pig iron, ferronickel and refined nickel, according to The Jakarta Post. Major automakers have followed the processing capacity: BYD is building a $1.3 billion EV plant targeting 150,000 vehicles annually, Vietnam’s VinFast has committed roughly $1.2 billion for similar capacity, and Chinese firm Huayou has invested $8.8 billion in industrial parks spanning Weda Bay, Morowali and Pomalaa, per Caixin Global reporting cited in the CETEX analysis.
The Chemistry Problem
The risk sits one layer deeper than smelting. According to Asia Times’ contrarian analysis, Indonesia’s downstreaming plan is built almost entirely around nickel-based battery chemistries (NMC and NCA), which offer higher energy density — but the global EV market, especially the mass-market segment, increasingly rewards price over performance. Lithium iron phosphate (LFP) batteries use no nickel or cobalt at all, and the IEA found LFP batteries were roughly 40% cheaper than NMC batteries in 2025. If LFP continues gaining global market share, Indonesia’s core resource advantage becomes structurally less relevant to where the EV industry is actually heading.
Asia Times’ analysis goes further, warning that if Indonesia keeps domestic nickel artificially cheap to support its own battery producers, the country loses part of its resource rent — reserves deplete faster, fiscal revenue falls, environmental costs rise, and the largest economic benefits may ultimately flow to downstream investors and foreign EV producers rather than Indonesia itself.
A Peak Already Passed?
There are signs Indonesia’s own policymakers see the upstream phase maturing. A senior member of Indonesia’s National Economic Council told the DBS Metals & Mining Indonesia Forum that the pace of capital injection into upstream nickel extraction is already settling down, with focus shifting to capitalizing on processing capacity already built, according to Caixin Global. Notably, nickel mining accounted for roughly 9% of downstreaming-sector investment in 2024-2025 while the entire EV ecosystem accounted for just 0.1% of that same investment in 2024, according to the CETEX policy paper — illustrating how early-stage the actual battery and vehicle build-out remains relative to the raw-material processing that preceded it.
The Structural Read
The Lowy Institute frames the overall record as mixed: downstreaming has produced fast, highly concentrated growth in nickel processing and made Indonesia a genuinely significant FDI destination in critical minerals — but the EV industry itself remains immature, with lacklustre domestic adoption and questionable import-substitution assumptions still unresolved as the country pushes toward its next investment wave.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- The U.S. government holds an approximately 10% passive equity stake in Intel, acquired around $20.47/share in August 2025 as part of a finalized CHIPS Act arrangement — a stake now up tens of billions of dollars on paper.
- Intel shares are reportedly up over 160% year-to-date in 2026, driven by pricing changes, AI partnerships, and manufacturing progress.
- Wall Street’s median 12-month price target sits near $110, though the full analyst range spans roughly $75–$200 — an unusually wide dispersion reflecting genuine disagreement about the foundry bet.
- Intel’s 18A manufacturing node is now in high-volume production, with Panther Lake as the first shipping product and external customers reportedly engaging Intel Foundry for next-generation nodes.
- Intel plans to raise PC CPU prices roughly 10% starting in early October 2026 — a margin-protection move rather than a volume play.
Why the Government Is a Shareholder
Following disruptions to the domestic chip supply chain and the 2022 CHIPS Act, Washington took the unusual step of converting some of Intel’s federal support into direct equity — around a 10% stake — with conditions that Intel keep its foundry business intact for at least five years. The rationale: a viable, U.S.-based advanced-logic manufacturer is treated as a national security asset, not just a commercial one, given how concentrated advanced chip manufacturing has become in Taiwan.
That backing functions as a floor under the stock in a way few other semiconductor names have — Intel effectively carries “national champion” status, with preferential access to defense and classified workloads as part of the arrangement.
The Foundry Turnaround, By the Numbers
| Metric | Status (2026) |
|---|---|
| 18A node | In high-volume production; Panther Lake shipping |
| U.S. government stake | ~10%, acquired ~$20.47/share |
| YTD stock performance | Reportedly +160%+ |
| Analyst price target range | $75–$200 (median ~$110) |
| Planned CPU price increase | ~10%, effective early October 2026 |
Intel’s Foundry division has posted multi-billion-dollar operating losses in recent years as external customer revenue continues to lag internal demand — the central risk in the bull case.
The Bull Case
- Intel is targeting roughly 20% of the world’s most advanced logic manufacturing capacity by late 2026, positioning it as the only credible U.S.-based alternative to Taiwan-concentrated advanced-node production.
- Government backing (CHIPS Act equity, SoftBank investment, NVIDIA partnership signals) de-risks the multi-year capital intensity of the foundry buildout.
- Rising global chip demand — the World Semiconductor Trade Statistics organization has projected sharp growth in overall chip sales, with memory pricing acting as a particular tailwind — supports the broader sector even if Intel-specific execution lags.
The Bear Case
- Foundry losses remain large, and external customer revenue — the metric that would validate the “TSMC-style” foundry model — still lags well behind internal Intel demand.
- Heavy, sustained capital expenditure (north of $20 billion annually) pressures free cash flow regardless of top-line improvement.
- The wide analyst target dispersion ($75–$200) itself signals that Wall Street has not reached consensus on whether the turnaround is durable or a government-subsidized reprieve.
Is Intel stock a buy in 2026?
Analyst opinion is split: Intel’s median 12-month price target is roughly $110, but targets range from $75 to $200, reflecting disagreement over whether its government-backed foundry turnaround (18A node, external customer wins) offsets continued foundry losses and heavy capital spending.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Key Takeaways
- Bitcoin has traded in a roughly $76,000–$82,000 range through early-to-mid September 2026, well off its prior cycle highs.
- Long-term holder behavior flipped positive in late August after a month of distribution — a signal some analysts read as accumulation, not capitulation.
- Prediction markets assign meaningfully higher odds to Bitcoin testing lower support ($70,000–$77,500) than to a breakout above $85,000 in the near term.
- Bitcoin’s correlation to risk assets (tech stocks) has remained the dominant pattern in 2026, undercutting the “digital gold” safe-haven narrative during this year’s Middle East-driven volatility.
- Leverage remains elevated on both sides of the trade — Binance alone shows billions in liquidation exposure clustered just below and above current price, meaning sharp moves in either direction are structurally likely.
The Case for “Safe Haven”
Proponents argue Bitcoin’s fixed supply and lack of counterparty risk make it a natural hedge against currency debasement and geopolitical shocks — the same argument made for gold. Some data supports this framing in 2026:
- Long-term holder net position change turned positive on August 31 after four weeks of distribution, suggesting accumulation rather than panic-selling into the year’s volatility.
- The number of large wallets (holding meaningful BTC) has declined only modestly even during a 25% rally, implying existing whales aren’t dumping into strength.
The Case for “High-Risk Tech Play”
The counterargument is that Bitcoin has behaved far more like a leveraged tech stock than gold throughout 2026’s geopolitical stress:
- Bitcoin fell alongside — not against — equities during the sharpest Middle East-driven risk-off sessions in September, the opposite of how gold or the yen typically trade in a flight to safety.
- Seasonality has historically been unkind: Bitcoin closed August green only twice since 2020, and both times September followed with 7%+ declines. (The last three Septembers broke that pattern, so the “worst month” label is contested.)
- Prediction-market pricing as of early September gave roughly a 90% probability to price staying below $77,500 in the near term, with real weight on scenarios down at $65,000–$70,000 — hardly the profile of an asset behaving as ballast.
Where Bitcoin Actually Sits Right Now
| Metric | Reading (Sept 2026) |
|---|---|
| Spot price | ~$77,000–$79,000 range |
| Key support | ~$77,000 |
| Key resistance | ~$82,600–$91,700 |
| Fear & Greed Index | Mid-50s (Greed) |
| 30-day volatility | ~7% |
Levels are illustrative of the mid-September 2026 range and move daily — verify against a live feed before publishing.
What This Means for Portfolio Construction
The honest answer is that Bitcoin in 2026 has functioned as both, depending on the time horizon: a long-term accumulation story for holders who aren’t reacting to daily headlines, and a high-beta risk asset on any given volatile trading day. Treating it as a guaranteed geopolitical hedge — the way this year’s Middle East conflict might tempt some investors to — has not been supported by its actual price behavior during the conflict’s most volatile weeks.
Is Bitcoin a safe haven asset in 2026?
Not consistently. While long-term holder data suggests accumulation rather than panic-selling, Bitcoin’s price has moved in line with — not against — risk assets during 2026’s sharpest geopolitical sell-offs, undermining the “digital gold” thesis in the short term even as some structural bullish signals persist.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global Economy
Dow Jones vs. Middle East Tensions: How Wall Street Is Pricing In a 2026 Conflict Nobody Saw Coming
Key Takeaways
- The Dow Jones Industrial Average has swung by 400–1,200+ points in single sessions through September 2026 as fighting between the U.S. and Iran escalated and Brent crude broke through $100/barrel.
- Energy has been the standout sector; health care and rate-sensitive growth names have lagged.
- The 10-year Treasury yield has pushed to multi-year highs, pressuring the Fed’s rate-cut timeline.
- Semiconductor and AI-infrastructure names (Qualcomm, Intel) have decoupled from the broader sell-off on unrelated AWS chip deals — a reminder that not all volatility is geopolitical.
- Institutional allocators are rotating toward energy, defense, and inflation-hedged assets rather than exiting equities outright.
“Investors worry about additional inflation coming down the road. The main concern is that oil prices go to over $100 a barrel and stay there.” — a senior portfolio manager quoted on the sell-off, paraphrased from market coverage
Snapshot: The Dow’s Middle East Whiplash (September 2026)
| Date | Dow Move | Driver |
|---|---|---|
| Sept 2 | -628 pts (-1.2%) | Post-holiday risk-off, US-Canada trade friction, Brent nearing $100 |
| Sept 8 | -1.2% | Renewed geopolitical focus, rising crude |
| Sept 9 | -195 to -403 pts | Fighting escalation, Brent tops $100/bbl |
| Sept 10 | Four-day losing streak | Yields and oil both surging |
| Sept 11 | Rebound | Cooler inflation print, oil eases |
| Sept 14–15 | Renewed weakness | Fed meeting begins, 10-yr yield hits multi-year highs |
How is the Dow Jones reacting to 2026 Middle East tensions?
The Dow has posted volatile single-session swings of 200 to over 1,200 points since escalation began, driven primarily by Brent crude’s move past $100/barrel, rising Treasury yields, and a delayed Fed rate-cut timeline. Energy and defense stocks have outperformed; rate-sensitive and health care sectors have lagged.
Why the Middle East Is Moving Markets Again
Fighting between U.S. forces and Iran has stretched into its seventh month as of mid-September 2026, and the conflict has now drawn in shipping through the Strait of Hormuz — the corridor that carries roughly a fifth of global oil supply. Brent crude crossing $100 a barrel is the headline number, but the more important story for portfolio construction is what that price level does to the inflation and rate-cut calculus:
- Inflation pressure returns. Higher energy costs feed directly into headline CPI, complicating the Fed’s path toward further cuts.
- Treasury yields climb. The 10-year has touched its highest levels since 2023 as markets price in a “higher for longer” scenario.
- Sector rotation, not capitulation. Energy stocks have led the S&P 500’s 11 sectors on down days, while health care and long-duration growth names have underperformed.
Sectors Winning and Losing
Winners
- Energy majors — direct beneficiaries of the Brent/WTI spike.
- Defense and aerospace — reinforced by the Pentagon’s parallel disclosure of on-orbit space-control weapons (see our companion piece on defense stocks).
- Select semiconductor names — Qualcomm and Intel have rallied on AWS custom-silicon deals that are unrelated to the conflict, showing the market can compartmentalize.
Losers
- Rate-sensitive growth and health care — squeezed by higher-for-longer yield expectations.
- Consumer discretionary — vulnerable if elevated pump prices erode spending power heading into the holiday season.
What This Means for a 2026 Portfolio
For investors asking “should I sell,” the more useful frame is allocation, not timing:
- Energy exposure (equities or sector ETFs) has functioned as the clearest hedge against the conflict’s direct market channel — oil.
- Short-duration fixed income has become more attractive as yields rise, reducing duration risk.
- Diversification across defense, energy, and traditional blue chips — a theme we cover in depth in our companion piece on building a 2026 portfolio around Dow blue chips, crypto, and alternative assets.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Beyond Rhetoric: How the EU Is Deploying ‘All Tools’ to Rebalance Its €1 Billion-a-Day Trade Deficit with China

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

INTC Stock Forecast 2026: Can Intel’s Government-Backed Turnaround Hold?

Bitcoin Price Action in Q4 2026: Safe-Haven Asset or High-Risk Tech Play?

The Target Pokémon x Owala Drop: Everything to Know Before It Sells Out

The U.S. Just Confirmed It Has Weapons in Space — Here’s What It Means for Defense Stocks

IRS 2027 Tax Bracket Projections: How to Get Ahead of Bracket Creep

Dow Jones vs. Middle East Tensions: How Wall Street Is Pricing In a 2026 Conflict Nobody Saw Coming

Bank of England’s September 17 Decision: Will UK Interest Rates Finally Move?

Inflation Is Outpacing Wage Growth Again: What It Means for Your Paycheck

10-Year Treasury Yield Tops 5%: What It Means for Mortgages, Stocks, and the Fed

Ceasefire Negotiations in 2026: Predicting the Rebound of European and Asian Economies

Emerging Markets Update: The Impact of World Bank Policies on PSX Stability

Costco Oil Shortage 2026: Will Prices Double for All Synthetic Motor Oils?

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Gold’s Wild 2026: From a Record $5,600 Peak to a 24% Crash and Back Toward $4,500

Oil Surges as Strait of Hormuz Traffic Collapses Again

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Global Chip Selloff Deepens: What’s Driving the Aug. 19 Semiconductor Rout

Shein Clothes Quality & Safety in 2026: What Lab Tests Show
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025