
Markets & Finance
Indonesia’s $121 Billion Nickel Bet Is Facing a Battery Chemistry

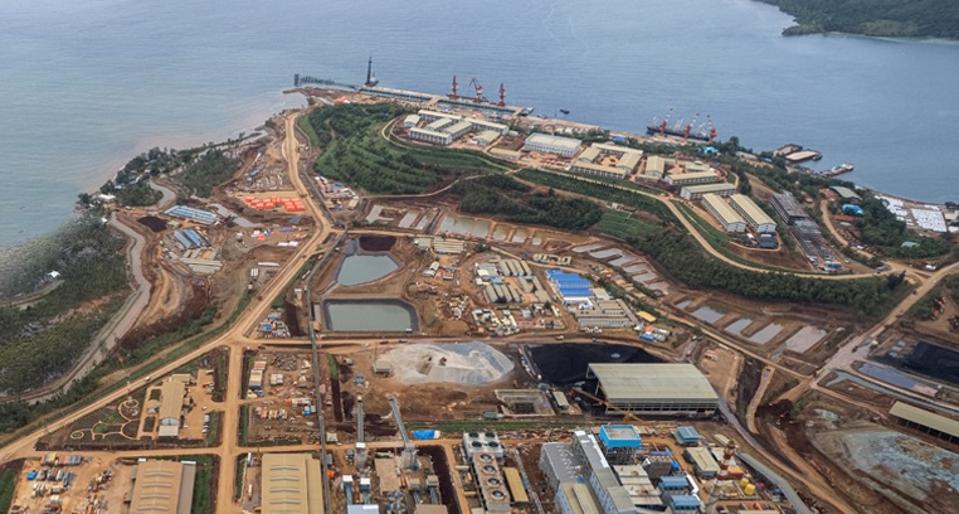
Indonesia is pitching an estimated $121 billion in investment opportunities to build an integrated national EV battery ecosystem, with officials arguing the country is uniquely positioned because four of the six main materials needed for EV batteries are found in abundance domestically, according to ANTARA News coverage of the June 2026 Korea-Indonesia Economic Partnership Forum. The ministry’s long-term downstream strategy could eventually drive total investment to $618 billion, with export value reaching $857 billion and more than 3 million new jobs.
The Policy That Built the Boom
The foundation is a 2020 ban on raw nickel ore exports, designed to force foreign capital into domestic processing rather than allowing Indonesia to remain a raw-material exporter, according to a policy analysis published by CETEX. The strategy has worked at the smelting stage: by 2025, Indonesia had 49 Rotary Kiln Electric Furnace nickel smelters operating domestically, turning raw saprolite ore into nickel pig iron, ferronickel and refined nickel, according to The Jakarta Post. Major automakers have followed the processing capacity: BYD is building a $1.3 billion EV plant targeting 150,000 vehicles annually, Vietnam’s VinFast has committed roughly $1.2 billion for similar capacity, and Chinese firm Huayou has invested $8.8 billion in industrial parks spanning Weda Bay, Morowali and Pomalaa, per Caixin Global reporting cited in the CETEX analysis.
The Chemistry Problem
The risk sits one layer deeper than smelting. According to Asia Times’ contrarian analysis, Indonesia’s downstreaming plan is built almost entirely around nickel-based battery chemistries (NMC and NCA), which offer higher energy density — but the global EV market, especially the mass-market segment, increasingly rewards price over performance. Lithium iron phosphate (LFP) batteries use no nickel or cobalt at all, and the IEA found LFP batteries were roughly 40% cheaper than NMC batteries in 2025. If LFP continues gaining global market share, Indonesia’s core resource advantage becomes structurally less relevant to where the EV industry is actually heading.
Asia Times’ analysis goes further, warning that if Indonesia keeps domestic nickel artificially cheap to support its own battery producers, the country loses part of its resource rent — reserves deplete faster, fiscal revenue falls, environmental costs rise, and the largest economic benefits may ultimately flow to downstream investors and foreign EV producers rather than Indonesia itself.
A Peak Already Passed?
There are signs Indonesia’s own policymakers see the upstream phase maturing. A senior member of Indonesia’s National Economic Council told the DBS Metals & Mining Indonesia Forum that the pace of capital injection into upstream nickel extraction is already settling down, with focus shifting to capitalizing on processing capacity already built, according to Caixin Global. Notably, nickel mining accounted for roughly 9% of downstreaming-sector investment in 2024-2025 while the entire EV ecosystem accounted for just 0.1% of that same investment in 2024, according to the CETEX policy paper — illustrating how early-stage the actual battery and vehicle build-out remains relative to the raw-material processing that preceded it.
The Structural Read
The Lowy Institute frames the overall record as mixed: downstreaming has produced fast, highly concentrated growth in nickel processing and made Indonesia a genuinely significant FDI destination in critical minerals — but the EV industry itself remains immature, with lacklustre domestic adoption and questionable import-substitution assumptions still unresolved as the country pushes toward its next investment wave.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Quick answer: The Chinese tape maker attracting global attention is Crown New Materials Technology Co., Ltd., which began trading on the Shenzhen Stock Exchange on November 3, 2026, under stock code 001381. Its offering price was 16.98 yuan a share. The stock touched 150.58 yuan, approximately 787% above that price, but closed at 84.55 yuan, a gain of approximately 398% from the IPO price. The difference between the day’s high and its close is essential to understanding the story, according to the company’s official exchange listing document and November 3 trading record.
A manufacturer of industrial adhesive tape has become one of the most remarkable stock-market stories of the week. It is tempting to frame Crown’s debut entirely around the fortune created for its founders or the astonishing percentage gain. Both are newsworthy. Neither tells investors why a business built around adhesive materials can attract such intense demand—or whether a first-day valuation can survive contact with its earnings.
The more revealing story is about the difference between a company’s economic value, the limited number of shares available to trade, and the very public excitement surrounding a newly listed stock. Crown’s filings provide enough information to begin disentangling those forces, although they cannot establish exactly why individual buyers paid particular prices.
Crown New Materials IPO: The essential numbers
| Measure | Verified figure | Why it matters |
|---|---|---|
| Exchange and ticker | Shenzhen main board, 001381 | Identifies the actual listed company |
| Listing date | November 3, 2026 | The first session of trading |
| IPO offer price | 16.98 yuan | The baseline for quoted first-day returns |
| Intraday high | 150.58 yuan | Approximately 786.8% above offer price |
| First-day closing price | 84.55 yuan | Approximately 397.9% above offer price |
| Shares outstanding after issue | 468,980,000 | Basis for indicative equity valuation |
| Shares issued in IPO | 56,304,768 | New shares sold to investors |
| Shares freely tradable at listing | 44,097,241 | Just 9.40% of post-IPO share capital |
| Approximate gross IPO proceeds | 956.1 million yuan | Money raised by the new-share offering |
The share counts, listing details and pricing come from Crown’s Shenzhen Stock Exchange listing announcement. The trading high and close are corroborated by the November 3 quote record and contemporary Forbes reporting carried by Yahoo Finance.
These are first-session historical figures, not a live quote. Any article describing the stock as trading ‘today’ must retrieve a fresh, timestamped market price.
What happened on November 3?
Crown completed its public offering at 16.98 yuan and entered the Shenzhen main board with an ordinary industrial business that suddenly looked extraordinary on trading screens. At its session peak, a share cost nearly nine times the issue price. Two trading interruptions were reported amid the volatility, according to a contemporary market report.
Yet the closing price tells a second story. At 84.55 yuan, shares ended the day 66.03 yuan below the intraday peak. Someone who bought at that peak and hypothetically valued the position at the close would have faced an approximately 43.9% decline from their purchase price. That is not the same calculation as the IPO gain, and it does not describe any individual investor’s realized loss. It illustrates how one stock can simultaneously produce a spectacular headline gain and substantial short-term downside for late buyers.
Using the official post-issue total of 468.98 million shares, the closing price implies an equity market value of roughly 39.65 billion yuan. Applying the session high to all outstanding shares produces an illustrative peak valuation near 70.62 billion yuan, although very few shares may have changed hands at the highest price. Neither figure represents proceeds received by the company: Crown raised roughly 956 million yuan from the offering itself.
What kind of company is Crown?
Calling Crown a ‘tape maker’ is accurate but incomplete. Its prospectus describes a manufacturer of functional composite materials, including industrial-grade adhesive products, electronics-grade adhesives and specialized functional films. These materials are engineered to stick, shield, protect, insulate, release or otherwise perform specific roles in industrial applications.
A roll of ordinary stationery tape offers little insight into materials used to assemble delicate consumer electronics, protect optical surfaces or accommodate heat and vibration in vehicles. The value proposition in those markets depends on formulations, coating precision, manufacturing consistency and customer qualification—not simply the number of meters of tape sold.
The Guangdong-based company has described its products as reaching end-use supply chains associated with brands such as Apple, Google, Tesla and BYD. That wording needs careful treatment. A material used in the supply chain of a major brand does not automatically mean that the brand buys directly from Crown, contributes a disclosed share of Crown’s revenue, or has endorsed its investment prospects. The company discusses those end-use applications in its IPO prospectus; any stronger claim about a direct contract needs separate documentation.
From a schoolteacher to a paper billionaire
The human-interest angle has helped propel the story internationally. Forbes’ account identifies chairman and chief executive Mai Michael, also identified in the company’s Chinese filing as Mai Huiquan, as a former elementary-school teacher. It estimated his holdings at about $2.5 billion during the IPO excitement and those of his sister, vice-chairwoman Mai Huixia, at approximately $2 billion.
Those estimates describe paper wealth, calculated from shareholdings and quoted market prices. They do not mean the founders received those sums in cash. Large founder positions are typically subject to lockups, and selling a large position into a thin market could affect its price. The official listing announcement describes multiple lockup periods and a relatively small initial public float.
It is a compelling entrepreneurial story. But the investment case should not depend on its protagonist’s change of profession.
The overlooked number: Only 9.4% was freely tradable
Crown’s filing says 44,097,241 shares, or 9.40% of total post-IPO shares, were free of sale restrictions at listing. This matters because the market price is established at the margin—where the available sellers meet eager buyers—not by simultaneous trading in all 468.98 million shares.
When newly available supply is scarce, even relatively modest incremental demand can produce outsized price movements. The result can be an equity valuation that looks spectacular when multiplied across every share, despite much less money changing hands in the market. This is a plausible mechanism for IPO volatility, not definitive proof of Crown’s specific order-book dynamics.
The company explicitly warned in its listing risk disclosures about irrational speculation, concentrated tradable supply and the risks of widened price bands during the early sessions. It also said there is no guarantee its shares will remain above the issue price.
An investor comparing Crown with an established listed manufacturer therefore needs to account for both fundamental valuation and float-related volatility. A first-day close is a price discovery event, not a long-term estimate of intrinsic value.
The business was growing—but profit momentum was weaker
Here lies the most useful contrast with the headline gain. Crown reported 2025 revenue of approximately 3.408 billion yuan, compared with 3.159 billion yuan in 2024 and 2.895 billion yuan in 2023. Its attributable net profit was approximately 309.18 million yuan in 2025, compared with 302.29 million yuan and 277.54 million yuan in the preceding two years, according to its prospectus financial statements.
The more recent picture was less straightforward. For January–September 2026, revenue increased 11.75% year over year, to roughly 2.779 billion yuan, while attributable net profit fell 7.89%, to approximately 225.04 million yuan, according to the company’s pre-listing financial update. Crown attributed the margin pressure partly to higher raw-material costs and a production base that had not yet reached its intended operating scale.
The same disclosure projected 2026 full-year attributable net profit of 263.64 million–278.26 million yuan, a decline of approximately 10%–14.73% against 2025. Management cautioned that this was a preliminary estimate, not a binding earnings forecast.
A stock whose price approaches five times its issue price while projected earnings are falling is not necessarily overvalued: investors may expect future expansion, stronger product mix or recovering margins. But it certainly requires more explanation than the phrase ‘strong growth’.
What the first-day valuation implies
At the 84.55-yuan close, Crown’s approximately 39.65-billion-yuan market capitalization divided by its 2025 attributable profit of 309.18 million yuan produces a rough trailing price-to-earnings multiple of 128 times. This simple calculation is not a substitute for fully adjusted financial analysis, but it establishes the magnitude of expectations embedded in the price.
At 16.98 yuan, the same method suggests roughly 25.8 times 2025 profit—close to the 25.87-times issue multiple disclosed in the listing documentation, which uses a specified adjusted earnings basis. The differences in definitions and rounding explain why calculated figures need not match exactly.
The point is not that a high multiple guarantees a crash. It is that long-term returns at that valuation depend heavily on whether Crown can convert new capacity, customer qualifications and research spending into significantly higher sustainable earnings.
Why the adhesive-materials opportunity is real
Functional adhesives occupy an easily overlooked position in technology and industrial supply chains. Electronics need materials for assembly, protection, sealing and thermal management; advanced batteries and electric vehicles impose demanding requirements around durability, heat, vibration and safety. Specialized films can carry different margins, know-how requirements and qualification processes from commodity tape.
Crown plans to invest IPO funds in functional-material capacity, semiconductor-related materials, optical films and a research center. Its IPO project plan lists approximately 918.68 million yuan of intended funding uses across the projects and working capital.
But opportunity and revenue are different categories. New facilities can take time to ramp up, and advanced-materials products must meet demanding technical specifications before customer orders scale. Investors need to assess qualification delays, production yields, competitive pricing and capital spending—not just the relevance of a product to artificial intelligence, electric vehicles or smartphones.
Three risks that deserve more attention
Raw materials. Crown disclosed that direct materials represented roughly 80% of its main operating costs across the reporting periods. Resins, solvents and other petrochemical inputs expose it to energy-market volatility. The company estimated that a 5%–10% raw-material cost increase, under the modeled conditions, could materially reduce gross margin. The assumptions and risk language appear in the listing document.
Competition. Industrial adhesives are not a monopoly. Crown itself identifies major international players including 3M, Nitto and tesa, alongside Chinese manufacturers, in its prospectus. Winning a customer program does not guarantee pricing power indefinitely.
Market structure. A small free float, lockups and early-session volatility can exaggerate price swings. A high share price may also make future disappointing earnings more painful because investors have already priced in exceptional success.
What to watch after the debut
The next useful data will be operating results and disclosures, not another viral percentage. Investors should monitor the company’s official disclosure page for updated earnings, shareholding notices, capacity milestones, customer concentration details and risks. They should compare gross margins across reporting periods, verify actual product-mix changes and distinguish scheduled lockup expirations from real share sales.
For coverage of Chinese IPOs generally, it is also important to separate exchange-regulator decisions, media reports about listing-policy changes and company-specific performance. A report about the wider IPO pipeline does not establish that Crown’s listing was exceptional because of a particular new policy.
Frequently asked questions
Which Chinese tape maker surged in its stock debut? Crown New Materials Technology, listed on Shenzhen’s main board under code 001381 on November 3, 2026.
Did its shares finish up 787%? No. The approximately 787% figure refers to the intraday peak relative to the IPO price. Shares ended their first session approximately 398% above the offering price.
How much did Crown raise? Roughly 956 million yuan gross through the sale of 56.3 million newly issued shares priced at 16.98 yuan each, before offering expenses.
Does Crown sell directly to Apple and Tesla? Its prospectus identifies end-use applications associated with major brands. That statement alone does not establish direct purchasing relationships or revenue concentration.
Is Crown a good investment after its IPO? The first-day performance cannot answer that question. Price, earnings quality, future margins, customer concentration, trading liquidity and individual risk tolerance all matter.
Why did its founders become billionaires? Media wealth estimates used their equity stakes and the newly quoted stock price. Such gains are unrealized and subject to market movements and share-sale restrictions.
Crown’s debut reveals two different phenomena: an industrial-materials company with a genuine technology-supply-chain business, and an IPO market capable of valuing a relatively small free float at startling prices. The 787% intraday gain made the headline. The 398% closing gain, 9.4% free float and weakening near-term profit outlook provide the better starting point for investors trying to understand it.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Why investors punished Google while largely sparing Microsoft—and what the historic sell-off reveals about the economics of artificial intelligence.
Wall Street has spent years rewarding technology companies for promising an artificial intelligence revolution. On October 29, it sent one of the revolution’s largest financiers a brutally different message: innovation may be impressive, but investors still expect a return on their money.
In a single trading session, approximately $500 billion evaporated from Alphabet’s stock market valuation. Shares in Google’s parent company plunged 12.6 percent, their worst one-day performance since the company’s public listing in 2004.
The extraordinary sell-off came after a quarter that, by many conventional measures, should have been cause for celebration. Alphabet reported revenue of $127.6 billion, a 25 percent increase from a year earlier. Its cloud division more than doubled its revenue. Operating income rose 30 percent.
Yet investors responded not with applause but with alarm.
The explanation lies in a troubling contradiction at the heart of the AI economy. The industry’s technological ambitions are accelerating faster than its capacity to translate those ambitions into cash.
What happened to Alphabet was not simply an earnings disappointment. It was a warning that the financial rules governing Silicon Valley’s AI investment boom may be changing.
And the contrasting treatment of Microsoft, which reported results on the same evening, offers an illuminating explanation.
The $500 Billion Warning
Alphabet’s financial results, released on October 28, exposed an uncomfortable imbalance.
The company generated $42.3 billion in operating cash flow during the third quarter. But it spent $51.4 billion on capital expenditure, primarily technical infrastructure. That left negative free cash flow of approximately $9.1 billion.
The previous quarter had produced a free-cash-flow deficit of $5.9 billion.
Two consecutive quarters in which capital investment exceeded internally generated operating cash represent a significant change in the financial profile of a business long celebrated for converting digital advertising into enormous amounts of cash.
The numbers are particularly striking because Alphabet’s investment programme shows little sign of slowing.
Management maintained its capital-expenditure forecast of $195 billion to $205 billion for 2026 and warned that spending would rise significantly again in 2027.
For investors, this raises a question that no amount of enthusiasm about large language models can easily answer: How much investment will be required before the financial rewards become commensurate with the costs?
The market was not reacting merely to the size of the expenditure. It was reacting to the possibility that infrastructure commitments could continue rising faster than the cash available to finance them.
There is, however, an essential distinction.
Alphabet is not a financially distressed company. According to its third-quarter regulatory filing, it held approximately $265 billion in cash, cash equivalents and marketable securities at the end of September, although that total included substantial equity holdings, including restricted SpaceX shares.
Its free cash flow over the preceding 12 months remained positive at $19.7 billion.
Moreover, an approximately $8.7 billion loss on equity securities—largely associated with SpaceX—depressed reported earnings without representing an equivalent quarterly operating cash outflow.
These distinctions matter. A temporary cash-flow deficit is not proof of impending insolvency, just as a large accounting profit is not proof that every investment creates economic value.
Alphabet has the resources to continue financing its ambitions. What investors are questioning is the price shareholders must pay for those ambitions, and the returns they will ultimately receive.
The market’s message is therefore more subtle than a rejection of AI: extraordinary financial capacity no longer guarantees unlimited investor patience.
Why Microsoft Escaped the Same Punishment
Microsoft’s earnings announcement provided a revealing contrast.
The company reported quarterly revenue of $92.3 billion, up 19 percent, while Azure revenue grew 48 percent.
It generated approximately $58 billion in operating cash flow and recorded $18.6 billion in positive free cash flow, despite capital expenditures of $45.2 billion.
Microsoft’s share price finished October 29 almost unchanged, declining approximately 0.2 percent.
That relative resilience was not because Microsoft had abandoned infrastructure spending. Nor was its investment programme fundamentally modest.
The company was continuing to commit extraordinary sums to data centres, processors and cloud infrastructure. Management projected approximately $170 billion in capital expenditures for calendar 2026, with some capacity deliveries delayed.
The distinction was that Microsoft’s operating cash generation continued to cover its cash capital investment, providing a financial cushion that Alphabet lacked during the latest quarter.
Microsoft also presented investors with a more immediately visible commercial connection between infrastructure and revenue.
Azure sells computing capacity directly to business customers. Microsoft can monetize AI through cloud consumption, enterprise software, development platforms and productivity subscriptions.
The relationship between customer demand, computational capacity and revenue is not perfectly transparent, but it is relatively straightforward.
When a business buys additional Azure computing capacity, Microsoft can demonstrate the associated revenue. That does not guarantee attractive returns on capital, but it offers investors a clearer path toward measuring them.
Alphabet faces a more complicated challenge.
Its infrastructure must support cloud customers, AI-model development and a vast collection of consumer services. Much of the expenditure is directed toward transforming products that users already access, including Search.
In those businesses, greater AI usage does not automatically produce a corresponding increase in revenue.
Nevertheless, the argument that Microsoft can finance its AI expansion entirely from internally generated cash also requires qualification.
On October 29, Microsoft priced a $25 billion offering of senior unsecured notes, with proceeds available for general corporate purposes, potentially including capital expenditure.
Even one of the industry’s strongest cash generators has chosen to supplement its financial resources through capital markets.
The real distinction is therefore not between companies that borrow and those that do not.
It is between companies whose investors remain confident in the relationship between investment, operating cash generation and future returns—and those for which that relationship has become harder to forecast.
Google’s Most Dangerous AI Problem Is Its Greatest Business
The more consequential challenge may lie beneath Alphabet’s capital expenditure.
Google’s search engine remains one of the most profitable commercial platforms ever created. For decades, its advertising model has depended on a remarkably efficient transaction: users express an intention, advertisers compete for their attention, and Google collects revenue.
Artificial intelligence threatens to alter that relationship.
Alphabet reported that Google Search and other advertising revenue grew 12 percent to approximately $63.4 billion in the third quarter, down from 17 percent growth in the preceding quarter.
The slowdown was not solely attributable to AI. Company executives pointed to currency effects and changing advertising patterns in specific industries, with foreign exchange identified as the largest factor.
But they also acknowledged that lower monetization in Google’s AI Mode was contributing to the deceleration.
This is the economic dilemma at the centre of Google’s transformation.
Traditional search presents users with advertisements alongside links to external websites. AI-powered search increasingly attempts to answer questions within Google’s own interface.
These experiences can be more useful, more conversational and more engaging. But the established commercial architecture does not transfer automatically.
A user who receives a comprehensive AI-generated answer may have less reason to click on conventional search results. Advertisers may need different formats to reach that user. Google must discover how to generate sufficient revenue from those interactions without compromising their usefulness.
Chief Executive Sundar Pichai has said AI investments are helping produce the fastest year-over-year growth in search queries in five years.
He has also reported that queries in AI Mode are, on average, three times longer than traditional searches.
Longer queries do not necessarily mean three times the computational cost. But they illustrate how significantly the product is changing.
The crucial question is whether this increased engagement can become sufficiently profitable engagement.
If Google’s new AI services attract greater usage but generate less advertising revenue per interaction, the company faces a double challenge: increasing infrastructure costs alongside uncertainty about monetization.
That possibility makes Alphabet’s situation different from a conventional infrastructure investment cycle.
Google is not merely building a new business. It is spending heavily to reinvent an existing one, partly to defend it against technologies that could undermine its established advantages.
And that creates a difficult strategic calculation.
Moving too slowly risks allowing competitors to redefine how consumers discover information. Moving too quickly could weaken the economics of the search business that finances Google’s technological ambitions.
For Alphabet, therefore, the cost of AI is not limited to servers, chips and electricity.
It also includes the possibility of disrupting one of the world’s most successful advertising models before an equally profitable successor is firmly established.
The Case Against Wall Street’s Verdict
There is a powerful counterargument to the market’s reaction.
Alphabet’s latest earnings contained evidence that its AI investments are already producing substantial commercial results.
Google Cloud revenue increased 103 percent to $30.7 billion, while the division’s operating income climbed from approximately $3.6 billion to $11.1 billion.
These are not the financial results of a business experiencing a collapse in AI demand.
They suggest that Alphabet is gaining meaningful commercial traction.
Importantly, the company said sales of its tensor processing unit systems made a significant contribution to Cloud’s expansion. Such hardware sales are not economically identical to recurring cloud-service revenue, and investors should distinguish between them when evaluating future growth.
Even so, the improvement in operating income is difficult to dismiss.
Alphabet has also built substantial expertise across semiconductor design, AI models, cloud infrastructure and consumer distribution.
Its ability to combine these capabilities may ultimately create advantages that narrower competitors struggle to replicate.
And large infrastructure investments frequently require cash long before their economic benefits become visible.
Data centres may take years to build and operate at full capacity. Customers may increase their spending gradually as applications move beyond experimentation into widespread deployment.
Judging a multiyear investment programme solely by two quarters of negative free cash flow would be shortsighted.
Indeed, if Alphabet’s investments strengthen its cloud business, improve the economics of inference and preserve Google’s position in search, the present spending surge could ultimately appear justified.
The difficulty is that investors must evaluate these possibilities before the returns become fully measurable.
That is what makes the debate so consequential.
The question is not whether Alphabet possesses valuable technology or whether demand for AI infrastructure exists. Its latest cloud results provide compelling evidence of both.
The question is whether today’s investment will earn sufficient returns to justify the company’s valuation after allowing for operating costs, depreciation, financing requirements and technological obsolescence.
That is a substantially higher standard than simply demonstrating rapid revenue growth.
The AI Boom Has Entered Its Financing Era
Alphabet’s experience is part of a much broader transformation in the economics of America’s largest technology companies.
The industry’s leading platforms are committing sums once associated with national infrastructure programmes.
Meta expects capital expenditures of $135 billion to $145 billion in 2026. It also reported negative free cash flow of approximately $2.1 billion in the third quarter.
Amazon’s October 29 results revealed a $42.4 billion free-cash-flow outflow over the preceding 12 months, despite AWS revenue growing 39 percent in the third quarter. Amazon maintained plans for approximately $220 billion in cash capital expenditures in 2026.
The enormous scale of these commitments suggests that AI is moving from a software-led innovation cycle into something closer to an industrial investment cycle.
Building the infrastructure requires land, electricity, cooling systems, semiconductors, financing and years of planning.
It also introduces risks unfamiliar to investors accustomed to the exceptional profitability of asset-light internet businesses.
An AI accelerator purchased today may become less economically competitive as newer processors arrive. Data-centre capacity must attract customers at prices sufficient to recover its cost. Electricity and cooling requirements can place lasting pressure on operating margins.
Accounting profits may remain strong while cash is tied up in new infrastructure.
Nor is the industry insulated from the cost of capital.
When borrowing becomes more expensive, when investors demand higher returns or when economic uncertainty affects enterprise spending, projects that once appeared compelling can become less attractive.
This does not mean an AI investment bubble must inevitably burst. Technological revolutions can deliver extraordinary productivity gains and create profitable businesses.
But history offers no guarantee that every company financing a technological revolution will capture a proportionate share of its economic benefits.
Railways transformed trade. Telecommunications transformed communication. The internet transformed commerce.
In each case, society’s long-term gains and the financial returns available to particular investors were not always the same thing.
Artificial intelligence may prove no different.
The Next Test Is Not Revenue Growth. It Is Return on Capital.
Investors should now demand more useful answers from technology companies than ever-larger announcements of capital expenditure.
How much additional revenue is generated by each dollar invested in computing infrastructure?
How quickly does new capacity reach commercially productive utilization?
Are businesses earning attractive margins after accounting for depreciation, energy, financing and maintenance?
And perhaps most importantly for Alphabet, can AI-powered search eventually produce revenue per user interaction comparable to—or better than—the traditional model it is replacing?
These questions matter more than headline declarations about model capabilities or user engagement.
Alphabet’s forthcoming fourth-quarter results, including further guidance on 2027 capital expenditure, will provide another opportunity to assess whether spending is beginning to stabilize relative to cash generation.
Microsoft will face similar scrutiny, especially as delayed GPU capacity becomes available and its own financing requirements increase.
The market’s relative tolerance toward Microsoft should not be mistaken for permanent immunity.
If AI revenue growth disappoints, or if capital requirements continue escalating faster than cash flow, even the strongest balance sheets will be tested.
There is another possibility, of course.
If AI adoption accelerates, infrastructure becomes more efficient and companies successfully develop profitable products, today’s expenditure could support years of earnings growth.
That outcome remains plausible.
But the burden of proof is shifting from technological promise to financial performance.
The End of Silicon Valley’s Blank Cheque
Alphabet’s historic sell-off may ultimately be remembered not as the moment Wall Street abandoned artificial intelligence, but as the moment it began taking the technology’s economics seriously.
The company did not lose roughly $500 billion in market value because its engineers had failed to build compelling AI products. It lost that value because investors became less confident about how much future cash shareholders would receive from the investments required to commercialize them.
Microsoft’s comparative resilience demonstrates the importance of that distinction. Investors were more willing to tolerate enormous capital commitments when supported by strong operating cash flow and clearer monetization prospects.
But Microsoft is not exempt from the same arithmetic, and Alphabet is far from defeated by it.
The real reckoning lies ahead.
Silicon Valley has successfully convinced the world that artificial intelligence will reshape how businesses operate and how people live.
Now it must prove that the economics of building that future will reward those paying for it.
For years, the defining question of the AI boom was who could build the most powerful technology. The defining question now is who can turn that technology into sustainable cash returns.
That is not the end of the AI revolution.
It may be the beginning of its financial maturity.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Spot gold traded around $4,020 to $4,035 an ounce on Thursday 29 October, down roughly 1% on the day, and moved briefly close to $3,983 later, according to Kitco’s live quote. Reuters reported bullion on track for a second straight monthly decline. The metal remains roughly 27-28% below its 2026 record of about $5,600, set in late January.
In Pakistan, one local market report put gold at about Rs423,436 per tola on 26 October. Tola prices also depend on the dollar-rupee rate and local premiums, so check the day’s rate.
Why Gold Is Under Pressure
A hawkish Fed hold. The Fed held rates at 3.75%-4.00% on 28 October, but Governor Lisa Cook and Cleveland Fed President Beth Hammack voted for a hike. On Thursday, Reuters reported markets pricing about a 90% chance of a December hike on the CME FedWatch tool.
Strong US data. Q3 GDP grew 3.4% and core PCE inflation rose to 2.5%, per Kitco, reinforcing the case for restrictive policy. The 10-year yield stayed near 5%.
Why this matters for gold. Gold pays no interest, so higher yields raise the opportunity cost of holding it, and a firmer dollar makes it costlier for non-US buyers. TDS strategist Bart Melek called the Fed’s stance a hawkish pause and expects gold to stay vulnerable in a $3,900-$4,250 range; Sucden Financial warned of a possible fall to $3,900.
Spot gold fell to about $4,020-4,035 an ounce on 29 October 2026 as strong US growth (3.4% in Q3) and higher core inflation kept a December Fed rate hike in play. Higher rates raise the opportunity cost of holding gold, which pays no interest.
What Could Push Gold Back Up
- A softer Fed: TDS expects the Fed to eventually turn toward its employment mandate, which could lift gold, though not immediately.
- Geopolitical shocks: Reuters quoted an analyst noting markets are wary of another spike in tensions after the 3 November US midterms.
- Oil, a double-edged factor: an oil spike raises inflation fears and hawkish expectations, which hurts gold in the short run. The same analyst said gold could post a fresh yearly low if oil revisits $120 and above.
Technical Levels Traders Watch
Kitco’s technical commentary points to $4,000 as a pivot, with downside objectives near $4,024 on a break lower and $3,986 beyond, and resistance in the $4,084-$4,146 zone. Treat these as trader reference points, not predictions.
What It Means for Pakistani Buyers
- Dollar-rupee matters as much as the gold price. If the rupee weakens, local gold can stay firm even when dollar gold falls.
- Time horizon. Analysts quoted expect volatility in a range over the coming weeks; long-term holders and short-term traders face different risks.
- Compare with alternatives. With the SBP policy rate at 12%, yield-bearing assets compete with gold for savings.
- Mind premiums and purity. Jewellery carries making charges; bars and coins track the spot price more closely.
Gold is stuck between a hawkish Fed and geopolitical risk. The $4,000 level has become the focus, and the next US inflation data and Iran’s response on the Qatari deal are the nearest catalysts.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

China Tape Maker Stock Debut: Crown New Materials Soared 787%

Apple’s Earnings Beat Had a Catch: Look Past the Tariff Refund

Social Security Payments in November 2026: The Full Calendar and Two Important Changes

Johor–Singapore SEZ’s $21.8 Billion Bet: The Hard Part Starts Now

China’s 175 Trillion AI Tokens Reveal a Bigger Shift: The AI Boom

The Philippines’ Stagflation Trap: Higher Interest Rates

Alphabet’s $500 Billion Reckoning: Wall Street Is Losing Patience With the AI Boom

4 Reasons Why China’s Trade Concessions to Europe Will Not Solve the Crisis

The AI Revolution Needs Atomic Power. Southeast Asia Is Ready to Build It.

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

The $8 Billion Runway: China’s Strategic Bet on Guangzhou and the Future of Aviation

The Sandbox Imperium: Why Beijing’s Digital Yuan Needs Hong Kong

Gold at the $4,000 Line: Possible December Fed Hike

Oil at $100+: Hormuz, a Qatari Peace Draft and the Iran Deadline

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

US–China Critical Minerals Competition: Why a Trade Deal Cannot Fix Every Supply Risk
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025