
Analysis
HSBC Global Market Access for Mainland Investors: The 2026 Shift

The shifting tectonic plates of global finance are rarely announced with a megaphone. Instead, they are revealed through quiet, bureaucratic approvals and the strategic repositioning of capital corridors. For years, domestic savers in the world’s second-largest economy have found themselves trapped in a low-yield environment, boxed in by a structural real estate slowdown and an erratic domestic equity market. Now, a critical valve is opening. The push to facilitate HSBC global market access for mainland investors represents one of the most consequential wealth transfers in recent memory. It’s a calculated gamble by both the bank and Beijing.
The macroeconomic reality driving this shift is stark. As of mid-2026, Chinese household deposits have swelled to record levels, yet the traditional engines of wealth creation—namely, Tier 1 property and domestic tech stocks—remain paralyzed by regulatory hangovers and demographic headwinds.
According to recent data published by the World Bank, China’s domestic consumption remains stubbornly tepid, forcing a vast pool of private capital to seek yield elsewhere. HSBC Bank (China) Company Limited has positioned itself at the vanguard of this exodus. By expanding its offshore wealth management offerings, the institution is essentially serving as a sanctioned bridge over the People’s Bank of China (PBOC)’s formidable capital control wall. That said, this is not an unregulated free-for-all; it is a highly choreographed release of pressure. Analysis from the Financial Times confirms that foreign exchange regulators are cautiously expanding quotas, terrified of sparking a destabilizing run on the renminbi while simultaneously recognizing that domestic capital desperately needs diversification.
The Architecture of Capital Flight: Legal and Managed
The core development hinges on a massive expansion of the Cross-boundary Wealth Management Connect (WMC) scheme and expanded allocations under the Qualified Domestic Institutional Investor (QDII) framework. HSBC has not merely launched new products; they’ve re-engineered their wealth distribution network across the Greater Bay Area (GBA).
Since the latest regulatory easing in March 2026, HSBC’s regional hubs in Shenzhen and Guangzhou have reported a surge in account activations. The bank’s strategy relies on a dual-track system. First, it targets high-net-worth individuals (HNWIs) with bespoke advisory services linked directly to offshore hubs in Hong Kong and Singapore. Second, it offers standardized, pre-approved mutual funds to the emerging mass-affluent class. Reporting by Reuters notes that outward bound investment quotas for major foreign banks have increased by 15% year-over-year, signaling tacit approval from the State Administration of Foreign Exchange (SAFE).
The numbers tell a compelling story about pent-up demand. In the first quarter of 2026 alone, retail flows into offshore fixed-income products through foreign bank channels in the GBA topped $12 billion. This isn’t speculative capital chasing high-risk tech unicorns in Silicon Valley. Instead, mainland money is aggressively targeting high-yield US Treasuries, Japanese dividend-paying equities, and European infrastructure funds. The priority is capital preservation and steady yield, a stark departure from the aggressive property speculation that defined the previous decade of Chinese wealth accumulation.
Offshore Asset Allocation for China: The Analytical View
To understand the magnitude of this shift, one must look beyond the immediate corporate victory for HSBC. This is a profound structural realignment of Chinese private wealth.
For decades, the social contract implicitly mandated that domestic wealth remain captive to fund domestic infrastructure and state-owned enterprises. The controlled facilitation of offshore asset allocation fundamentally alters this dynamic. By allowing a premier foreign institution to act as the primary conduit, Beijing is outsourcing the complex machinery of global portfolio management while retaining strict oversight of the spigot.
How are capital corridors structured?
Mainland Chinese investors access global markets through HSBC primarily via the Cross-boundary Wealth Management Connect and QDII programs. These frameworks allow eligible individuals to legally bypass strict capital controls, investing offshore yuan into approved mutual funds, fixed-income securities, and global equities.
This structure creates a fascinating paradox. The Chinese state is opening doors, but only to highly regulated, transparent rooms. The funds cannot be easily diverted into opaque offshore trusts or utilized for tax evasion. Every transaction is digitally tracked, cross-referenced against individual quotas, and monitored for sudden anomalies.
Global Implications and Downstream Effects
The second-order effects of this capital migration will inevitably ripple through global asset prices. If the current trajectory holds, the steady drip of mainland wealth into international markets could act as a structural pillar for Western fixed-income securities.
Consider the sheer scale of dormant capital. If even two percent of China’s estimated $18 trillion in household bank deposits finds its way into global markets over the next five years, it would rival the total assets under management of sovereign wealth funds. According to Bloomberg Intelligence, an influx of this magnitude has already begun compressing yields on prime European corporate debt, as Chinese investors prioritize blue-chip stability over emerging market volatility.
For global policymakers, this presents a dual-edged sword. On one hand, Western markets benefit from a fresh injection of deep liquidity. On the other hand, it increases the financial entanglement between the West and Beijing at a time of heightened geopolitical friction. Should diplomatic relations deteriorate sharply, these vast pools of cross-border investments could become weaponized, subject to sudden freezes or forced repatriations.
The Dissenting View: A Trap Door, Not an Open Door
The picture is more complicated than a simple narrative of financial liberalization. Skeptics argue that HSBC’s expanded mandate is built on a fragile regulatory foundation that could crack the moment domestic economic indicators flash red.
Some prominent voices in the financial community view this not as an opening, but as a temporary pressure release valve that will be slammed shut at the first sign of severe capital flight. Victor Shih, an expert on China’s political economy, has repeatedly warned that Beijing’s tolerance for capital outflows is highly conditional. “The PBOC is essentially running a beta test,” notes a recent policy paper from the Peterson Institute for International Economics. “If the domestic property market faces a deeper systemic shock, these wealth connect programs will be suspended overnight, leaving investors trapped in illiquid offshore structures.”
Furthermore, there is the persistent risk of localized regulatory arbitrage. While HSBC maintains rigorous compliance standards, the broader ecosystem of third-party wealth advisors operating on the fringes of the GBA may push the boundaries of what SAFE permits. If Beijing detects systemic abuse or widespread circumvention of individual QDII limits, the resulting crackdown would likely ensnare foreign institutions, severely damaging their operational standing on the mainland.
HSBC’s maneuver to channel Chinese domestic wealth into global markets is a definitive hallmark of the 2026 financial landscape. It represents a delicate equilibrium between an institution’s hunger for asset management fees and a sovereign state’s need to manage a profound domestic economic transition.
The success of this operation relies entirely on the continuation of a brittle truce between capital mobility and state control. If managed correctly, it promises a lucrative new era for global asset managers and a vital lifeline for Chinese savers. Yet, the underlying truth remains inescapable: in mainland China, the door to global finance is never truly unlocked; it is merely left ajar, held by a hand that can pull it shut without a moment’s notice.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


For decades, the global dominance of the U.S. dollar has rested on two primary pillars: deep, unencumbered liquid capital markets and an indispensable global financial messaging protocol known as SWIFT. When Beijing launched its e-CNY initiative, Western observers initially framed it as a central bank digital currency (CBDC) designed primarily for domestic surveillance, retail convenience, and financial inclusion.
However, recent strategic moves highlight a far more ambitious objective. As documented by the South China Morning Post, Beijing is actively leveraging Hong Kong as its central offshore laboratory to establish the infrastructure required for international cross-border digital yuan adoption.
The crucial strategic question is no longer whether China can engineer robust distributed ledger architecture, but whether an offshore financial hub operating under “One Country, Two Systems” can bridge the gap between rigid domestic capital controls and global institutional acceptance. To succeed, China must resolve the fundamental tension between absolute monetary sovereignty and the open networks required for international currency adoption.
1. The Paradox of the Offshore Laboratory
China’s monetary expansion faces a well-documented structural paradox. According to macroeconomic research from the Carnegie Endowment for International Peace, no currency can achieve true international reserve status without offering open capital accounts and deep, freely convertible liquidity. Yet, completely relaxing capital controls would expose China’s domestic banking system to volatile international capital flows and speculative pressures.
Hong Kong serves as the pressure valve and testing ground for this paradox:
- Legal & Regulatory Buffer: Hong Kong maintains a trusted common law judicial system and an independent monetary authority (Hong Kong Monetary Authority).
- Convertibility Bridge: It allows mainland authorities to test e-CNY settlement, cross-border retail links, and digital asset integration without opening mainland financial markets directly to global speculative shocks.
- Institutional Liquidity: As the world’s premier offshore renminbi hub, Hong Kong provides the institutional counterparties necessary to build real-world transaction volume.
“The digital yuan’s true test lies not in domestic retail adoption, but in whether foreign counterparties can settle cross-border trade without taking on unacceptable regulatory or capital risks.”
2. Wholesale Settlement and Project mBridge
While retail consumer wallets attract considerable media attention, the real geopolitical shift is occurring at the wholesale institutional level. Strategic initiatives like Project mBridge—developed in partnership with the Bank for International Settlements (BIS), the People’s Bank of China, and regional central banks—demonstrate how multi-CBDC platforms can streamline international trade.
As reported in market analyses by Bloomberg and trade finance studies covered by Reuters, multi-lateral CBDC platforms offer significant operational advantages:
- Elimination of Intermediaries: Direct ledger-to-ledger transactions bypass traditional correspondent banking networks.
- Speed and Efficiency: Cross-border settlement times are reduced from days to seconds.
- Cost Reduction: Transaction costs and foreign exchange spreads across regional trade corridors in Asia and the Middle East are dramatically lowered.
If commercial enterprises operating in Hong Kong can settle trade directly in e-CNY with instant finality, Beijing creates a compelling economic incentive for trade partners that operates independently of Western clearing networks.
3. Geopolitical Implications & The Road Ahead
Western policymakers and central bankers are monitoring these developments closely. Recent congressional testimony and Treasury reviews highlighted by Reuters reflect growing concern in Washington that alternative settlement rails could gradually erode the reach and enforcement of Western financial sanctions.
However, technological capability alone does not guarantee global currency dominance. Until foreign corporate treasuries and central banks have full confidence in converted currency liquidity, property rights, and transparent legal protections, the digital yuan will serve primarily as an efficient alternative mechanism for bilateral trade rather than an immediate replacement for the U.S. dollar.
Institutional Summary & Comparison
| Dimension | Conventional Retail Focus | Wholesale / Strategic Reality |
| Primary Mechanism | Retail e-CNY wallets for tourists & merchants | Multi-CBDC corridors (Project mBridge) & Project Ensemble |
| Core Objective | Domestic payments & payment app competition | Disintermediation of correspondent banking and SWIFT rails |
| Primary Barrier | Consumer habituation & merchant readiness | Capital controls, currency convertibility, and institutional trust |
Sources & Citations
- South China Morning Post: Beijing wants Hong Kong to sow the seeds for the digital yuan
- Bank for International Settlements (BIS): Central Bank Digital Currency (CBDC) & Cross-Border Payments Research
- Carnegie Endowment for International Peace: China’s Financial System and Capital Account Dynamics
- Bloomberg Financial Analysis: Global Macro & Digital Currency Integration
- Reuters News & Analysis: Cross-Border Settlement and Global Trade Finance
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
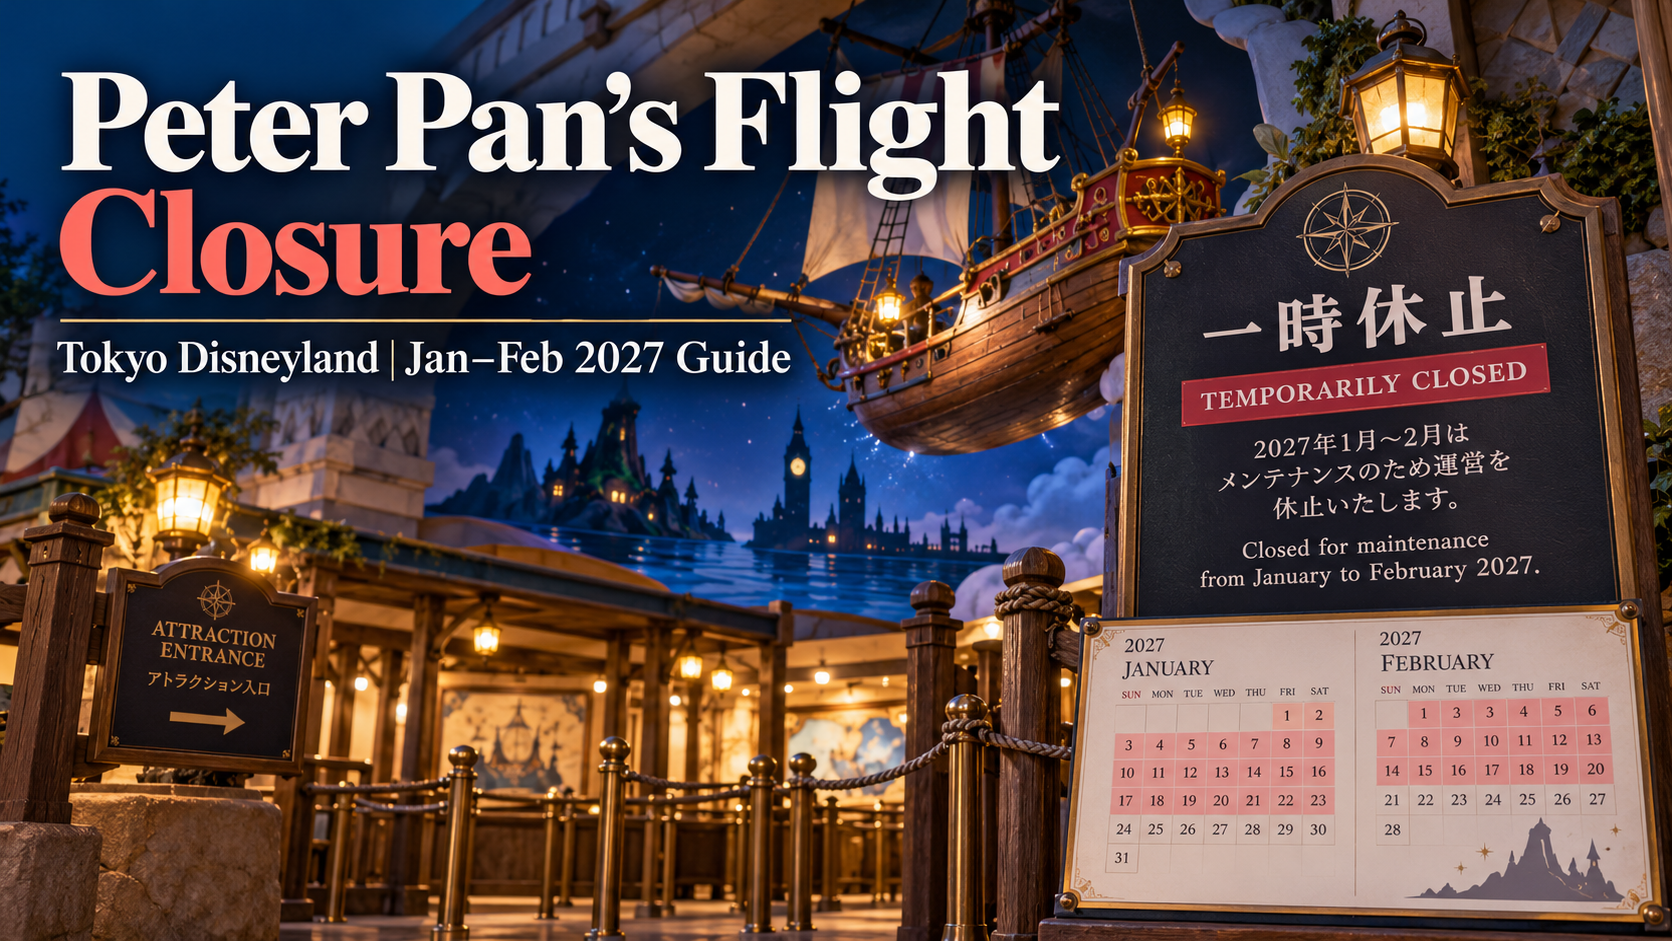
Guests planning a visit to Tokyo Disneyland in early 2027 should put one easily missed detail on their itinerary: Peter Pan’s Flight is scheduled to be temporarily closed from January 6 through February 2, 2027. The operator lists the dates both on its official attraction page and in the Tokyo Disneyland closure schedule. This is a scheduled interruption, not an announcement that the classic ride is being removed permanently. Travelers visiting on dates inside that window should assume the attraction will not be available unless Tokyo Disney Resort publishes a change.
The distinction matters because online references to “Peter Pan closing at Tokyo Disney” can confuse two different parks and two different experiences. Tokyo Disneyland’s Peter Pan’s Flight is a compact Fantasyland ride. Tokyo DisneySea has a separate, newer attraction called Peter Pan’s Never Land Adventure, with its own planned March 2027 maintenance period. The first planning step is making sure the information applies to the ticket you actually bought.
At a glance: what the operator currently says
| Planning question | Verified answer |
|---|---|
| Which attraction? | Peter Pan’s Flight |
| Which park? | Tokyo Disneyland, Fantasyland |
| Scheduled closure starts | January 6, 2027 |
| Scheduled closure ends | February 2, 2027 |
| Reopening expectation | After the listed closure window, subject to operator changes |
| Type of notice | Temporary closure; not announced as permanent |
| Where to recheck | Official attraction listing |
The dates are explicitly labeled as a temporary closure by Tokyo Disney Resort. Do not treat February 3 as an unconditional reopening guarantee: an operator may update maintenance information or temporarily suspend operations for other reasons. Check again shortly before travel and on the day you enter the park.
What is Peter Pan’s Flight?
Peter Pan’s Flight is a dark ride based on the familiar journey from London to Never Land. Guests sit in a flying pirate-ship vehicle that travels through a storybook environment. According to the operator’s ride information, it is in Fantasyland, lasts about two and a half minutes and carries two people per vehicle. It operates indoors and includes dark spaces. These details make it particularly appealing to families who want a gentle, classic Disney experience rather than a high-speed thrill ride.
There are restrictions worth noting even on operating days. The published guidance says a guest must be able to maintain a stable seated position independently and that children may not be held on an adult’s lap during the ride. If your group includes young children, anyone needing seating assistance or visitors uncomfortable with darkness, read the official description and accessibility guidance rather than assuming that the attraction suits everyone because it is short.
Short ride duration is not the same as short waiting time. Demand for well-known classics can vary with crowds, operating conditions and holiday schedules, so it is unwise to schedule a tight sequence of unrelated bookings around a predicted queue. The operator’s app and in-park staff can provide current operating information when the ride is available.
The dates around the closure are not interchangeable
A guest visiting January 5 has a fundamentally different planning position from someone arriving January 6. January 5 falls before the currently listed closure, while January 6 is its opening day. A February 2 visit falls on the final listed day of the maintenance window; February 3 is the earliest day after that window, not a contractual promise that the ride will run.
For a family staying at the resort for multiple days, the difference might be worth changing which day is assigned to Tokyo Disneyland. If one day is before January 6 and another is inside the closure, put Disneyland first if the classic Peter Pan ride is a must-do. But do not swap a park ticket or hotel reservation until you understand the applicable change and cancellation conditions. The economic cost of reshuffling an entire trip can exceed the benefit of experiencing one short ride.
A visitor traveling from overseas may be choosing between a single Disneyland day and a DisneySea day. In that case, consider the trip’s overall priorities. Someone who values vintage Fantasyland attractions may still prefer Disneyland even during the closure. Someone traveling expressly for an immersive Peter Pan adventure could be more interested in the DisneySea attraction—but must buy admission to that different park and verify its own operating schedule.
Other Tokyo Disneyland closures during the same period
The official park maintenance listing shows other attractions with early-2027 closure windows that may overlap your visit. At the time of this review, it lists Jungle Cruise: Wildlife Expeditions from January 6 through March 31, Splash Mountain from January 7 through February 4, and Haunted Mansion from January 8 through February 4. These are operator-published schedules, not independent predictions about refurbishment completion.
This makes the Peter Pan closure more significant for certain visitors than a single unavailable ride might suggest. A group that expected several classic experiences in one afternoon could find multiple priorities temporarily inaccessible. Conversely, the park contains many other attractions and entertainment offerings, and the attractions that remain open should be evaluated on their own current descriptions rather than guessed from historical schedules.
It is worth making a small “must ride / would enjoy / optional” list. Mark each attraction against the closure page. Then build flexibility around weather, performance calendars and queue variation. A plan with alternatives is more resilient than a rigid minute-by-minute schedule.
Better alternatives for different kinds of visitors
If the attraction’s appeal is gentle fantasy storytelling, explore other Fantasyland offerings listed in the official Tokyo Disneyland attraction directory. Filter for ride type and height or access restrictions, and read the current operating details. Do not assume that a neighboring attraction will be open merely because it is not listed in an older travel blog.
If the main attraction is Disney character immersion, devote time to character experiences, themed areas, shopping or scheduled entertainment that is actually available on your day. These can preserve the spirit of the trip without pretending they are substitutes for the ride itself. Some guests will prefer to spend the recovered time on a longer headliner; others may value an unhurried lunch and a park exploration that is less vulnerable to queues.
If the trip is built around Peter Pan specifically, Tokyo DisneySea’s Never Land Adventure may appear attractive. But it is not the same ride: it is a 3D boat-based experience in Fantasy Springs, with different restrictions and a different length. Tokyo Disney Resort’s DisneySea attraction page is the reliable way to compare them. Admission, access arrangements and the day’s capacity remain separate questions.
Parents should also avoid overstating the value of a replacement to children. “Another attraction has pirates” does not make it the planned Peter Pan experience. Setting expectations before entering the park is often more effective than negotiating disappointment in a crowded queue area.
Are refunds or ticket changes automatic?
The announcement of an attraction’s temporary closure does not itself demonstrate that every guest is entitled to a ticket refund or a date change. Theme-park tickets ordinarily grant admission subject to operating conditions, not a binding guarantee that every individual ride will operate. Actual ticket terms, package conditions and any operator-specific accommodation policy govern what can be changed.
Before buying or modifying a pass, review the official Tokyo Disney Resort ticket and reservations guidance and any reseller’s terms. A third-party package might combine transport, hotel rooms and tickets under separate cancellation rules. You should not rely on the statement “ride closed” as a universal reason for a penalty-free cancellation.
If your booking is complex, write down the name of the supplier, reservation reference, exact park date and type of admission. Seek a written answer before paying a change fee. This is particularly important if you plan to move only one day of a multi-day trip and keep the remainder unchanged.
Does Disney Premier Access help during the closure?
No paid queue-management product can make an attraction operate while it is closed. Disney Premier Access is a separate, paid tool for eligible operating experiences; eligibility and availability can change. The official Premier Access guide explains that places may sell out and that the price does not include park admission. It should not be marketed to families as a guaranteed workaround for a published maintenance closure.
The app can nevertheless be useful for other attractions and live operating information. If a ride is unavailable, remove it from the day’s queue-management plan and redirect attention to attractions genuinely offered that day. Check the current product terms before purchasing any additional access.
How to build a more reliable 2027 itinerary
Start with the official attraction closure list rather than the social-media version of it. Choose a date, read the list for the correct park, then check the pages for the two or three attractions most important to your group. If several favorites overlap with closures, compare another travel day, but preserve buffer time and cost limits.
Once you have a provisional itinerary, check whether your whole group can experience the alternatives. A family with a toddler and grandparents may have different needs from a group of teenagers. Ride seating rules, dark environments, height restrictions and walking distances deserve attention before buying optional upgrades.
A week before departure, look at the operator’s park calendar and attraction pages again. On the morning of your visit, follow current app information and staff instructions. Write down a backup plan that does not depend on a single ride reopening on the first conceivable day.
Quick visitor questions
Is Peter Pan’s Flight shutting permanently? The published notice says temporary closure January 6–February 2, 2027. It does not announce permanent removal.
Is it in Tokyo Disneyland or DisneySea? Peter Pan’s Flight is in Tokyo Disneyland’s Fantasyland. DisneySea has the separate Never Land Adventure.
Can I ride on February 2? The current listing includes February 2 in the closure window. Do not plan on riding that day.
Is February 3 the official reopening day? It is the first day after the presently announced closure period, assuming the dates are unchanged. Confirm the park’s live information rather than treating operation as guaranteed.
Should I change my trip? That depends on how important this specific ride is compared with hotel, flights, admission and other attractions. For most travelers, adjusting priorities within the same park is the lower-risk first option.
Final planning advice
This news is not a farewell to Peter Pan’s Flight. It is a defined, temporary gap in the operating calendar. The useful response is to check your exact visit date, compare the rides your family actually cares about and keep a realistic alternative ready. Tokyo Disneyland can still be an appealing destination during the listed closure; the difference between an enjoyable trip and a frustrating one may simply be accurate expectations.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

The $8 Billion Runway: China’s Strategic Bet on Guangzhou and the Future of Aviation

The Sandbox Imperium: Why Beijing’s Digital Yuan Needs Hong Kong

Gold at the $4,000 Line: Possible December Fed Hike

Oil at $100+: Hormuz, a Qatari Peace Draft and the Iran Deadline

The Fed’s 10-2 Hold: Why Two Dissenters Wanted a Rate Hike

SBP Raises Policy Rate to 12%: What It Means for Your Loans, Savings and Business

IMF’s $1.2bn Staff-Level Deal: What Pakistan Promised on Surplus

Decoding the DBS–BCA Merger Rumour: Market Volatility, Strategic Realities

New Xbox Games October 26–30, 2026: Releases and Game Pass

Tokyo Disneyland Peter Pan’s Flight Closure: January–February 2027 Guide

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025