
Analysis
Decoding the Relationship Between Gold and Bitcoin Will Be Vital for Institutional Portfolios in 2026

As gold trades near record highs and Bitcoin consolidates after a brutal 50% drawdown, the Bitcoin-gold correlation has broken down. Here is why the barbell strategy—gold for left-tail protection, Bitcoin for right-tail growth—is the defining institutional allocation of 2026.
There is a temptation, in moments of market violence, to reach for simple narratives. Bitcoin fell by more than half from its all-time high. Gold surged to historic levels. Therefore, one is broken and the other is unassailable. It is a clean story. It is also wrong.
What has unfolded in the 2025–2026 cycle is not a verdict on the relative merits of these two assets. It is a stress test—and both have passed, in entirely different ways, which is precisely the point. The relationship between gold and Bitcoin in 2026 is no longer one of convergence or competition. It is a story of elegant divergence: two assets, shaped by different forces, doing different jobs in a portfolio. For pension funds, endowments, and family offices navigating a world of persistent inflation, geopolitical fracture, and compressed real yields, understanding this divergence is no longer optional. It is an institutional imperative.
Why the 50% Bitcoin Drawdown Was a Feature, Not a Bug
Let us begin with the uncomfortable facts. After peaking in late 2025—specifically October, when it hit an all-time high above US$126,000—Bitcoin, the world’s largest digital asset, slid sharply, briefly testing US$60,000 in February before clawing its way back to US$70,000 later that month. From peak to trough, the drawdown reached roughly 50 to 52 per cent at the lows.
The immediate temptation is to interpret any violent sell-off as an existential threat to institutional adoption of Bitcoin, and even to the prospect of a rally past all-time highs. Yet, history suggests otherwise. Mid-cycle retracements of this magnitude have been a recurring feature of Bitcoin’s bull markets rather than their obituary. In 2013, Bitcoin fell 83% during its bull cycle before resuming upward. In 2017, it shed over 40% mid-run before ultimately quintupling in value. The 2020–2021 cycle featured two separate corrections exceeding 50% before Bitcoin reached its then-record near US$69,000.
New entrants to the space will fixate on the speed of the fall, but having experienced multiple cycles, seasoned analysts are paying attention to the character of the rebound. The sharp bounce from near US$60,000 hints that long-term holders and institutions remain willing to absorb supply at stress levels. As of late March 2026, Bitcoin has stabilised in the US$66,000–US$71,000 range, trading around US$69,000—a consolidation zone that suggests the market is digesting, not disintegrating.
The supply dynamics are equally instructive. Miners exiting the space amid declining mining profitability created a persistent supply overhang as they liquidated Bitcoin holdings. Data from on-chain analytics shows that long-term holder net selling, which reached a 30-day rolling figure of nearly −243,737 BTC in early February 2026, collapsed to just −31,967 BTC by March—an 87% reduction in selling pressure. Weaker hands, particularly newer entrants, likely capitulated as prices fell below “Liberation Day” (April 2, 2025) levels. What remains, in institutional parlance, is a reset toward longer-term holders.
This is not a collapsing market. It is a market being repriced from retail to institutional ownership.
The Decoupling: Bitcoin–Gold Correlation Hits Multi-Year Lows in 2026
The most consequential structural shift of this cycle is one that headline writers have almost entirely ignored: the Bitcoin–gold correlation in 2026 has broken down.
From late 2022 through to mid-2024, the two assets moved in reasonably tight tandem. Both were perceived as hard-money alternatives, scarce assets beyond central bank control, natural beneficiaries of fiat debasement. CME Group analysis confirms that over this period, gold gained roughly 67% while Bitcoin surged nearly 400%, with analysts widely expecting continued co-movement.
That relationship has since fractured. The 90-day rolling correlation between Bitcoin and gold has declined to near zero or low-positive territory—approximately 0.29 or below—and has at times flipped negative. Meanwhile, the correlation between Bitcoin and the Nasdaq 100 has risen to a range of 0.75–0.85, according to market risk analysis published in early 2026. Bitcoin is increasingly being traded as a high-beta risk asset, not a monetary hedge. Gold, conversely, has absorbed the geopolitical shock premium almost entirely on its own.
This is not a flaw in Bitcoin’s investment thesis. It is a clarification of it—and a profound one for portfolio construction.
Gold climbed from roughly US$3,000 per ounce in early 2025 to a record high of approximately US$5,595 in January 2026, before correcting to the US$4,370–US$4,500 range by late March as a stronger US dollar exerted pressure. The metal has risen over 25% since the start of 2025, driven by a combustible mix of geopolitical uncertainty, central bank accumulation from non-Western nations, and persistent inflation expectations. As Fortune’s daily gold reporting notes, gold has surged to record levels, fuelled by conditions that gold has historically absorbed: war risk, monetary stress, and institutional flight to safety.
Bitcoin, meanwhile, has done something different. It has absorbed liquidity flows, ETF-driven demand, and the institutional product buildout—all of which are less correlated with geopolitical shocks and more correlated with risk appetite and technology sector sentiment. These are, in portfolio terms, entirely separate return streams.
The Great Decoupling: Two Assets, Two Mandates
The divergence can be understood through a simple framework: gold absorbs geopolitical shocks; Bitcoin captures liquidity and ETF flows.
When the Middle East escalation intensified in early 2026, gold initially rallied as expected. Bitcoin, weighed by its high Nasdaq correlation and macro headwinds from a strong US dollar, declined. This apparent contradiction is actually the barbell working as designed. An investor who held both assets in the same portfolio owned a geopolitical hedge and a liquidity and technology-beta instrument—two entirely different risk premia. The portfolio as a whole absorbed shock without abandoning upside optionality.
This structural duality defines the gold Bitcoin institutional portfolio thesis of 2026. It is not a question of which asset wins. Both are winning, just at different times and for different reasons. BlackRock has explored this diversification dynamic, examining how Bitcoin alongside gold and traditional alternatives can provide complementary exposures in multi-asset portfolios. The world’s largest asset manager treating the two assets as portfolio complements—not substitutes—is itself an endorsement of the barbell logic.
Institutional Evidence: ETFs, Sovereigns, and the Normalisation of Bitcoin Allocation
The institutional allocation gold Bitcoin story has moved from aspiration to architecture over the past eighteen months.
Fidelity’s Digital Assets research has documented that over 80% of institutional investors now see digital assets as portfolio-worthy, with most preferring ETF-style exposure. Grayscale’s 2026 Digital Asset Outlook continues to frame Bitcoin as a scarce monetary asset with asymmetric upside characteristics distinct from traditional risk assets. BlackRock’s iShares Bitcoin Trust (IBIT) attracted US$888 million in net inflows in January 2026 alone—before the drawdown accelerated—demonstrating that institutional demand is not simply a function of price momentum.
More revealing is what institutions did during the correction. According to blockchain analytics data reported by Yahoo Finance, BlackRock and Fidelity together purchased close to US$400 million of Bitcoin during the March selloff week, even as they simultaneously sold US$250 million—resulting in net purchases of approximately US$150 million. This is dip-buying of the highest conviction. When the world’s largest asset managers step in as buyers at stress levels, the signal is unambiguous: the drawdown was an entry opportunity, not an exit event.
The sovereign dimension is accelerating. Fidelity’s 2026 research identifies Brazil and Kyrgyzstan as having passed legislation enabling Bitcoin as part of national reserves, with Fidelity’s vice president of research noting that competitive pressure may compel additional nations to follow. VanEck’s head of digital assets research, Matthew Sigel, has argued that Bitcoin’s historical four-year cycle remains intact, and VanEck recommends 1–3% Bitcoin allocations for client portfolios. Morgan Stanley’s filing for a spot Bitcoin Trust in early 2026, alongside plans for crypto trading on E*Trade in the first half of the year, marks the moment when crypto exposure migrated from the specialist desk to the mainstream wealth management platform.
The Bitcoin ETF market, now exceeding US$123 billion in assets, represents a structural demand floor that did not exist in prior cycles. As 247 Wall Street analysis notes, ETF-era Bitcoin flows “reflect portfolio allocation decisions rather than speculative impulse.” Spot ETF volume records were broken multiple times in early 2026, with March 2 setting the single-largest day of ETF trading activity in the instrument’s history at US$31.6 billion. Institutions are not abandoning the asset class. They are calibrating their positions within it.
Historical Cycle Parallels: The Mid-Cycle Reset Playbook
For those with institutional memory extending beyond three years, the 2025–2026 drawdown follows a remarkably familiar script.
In every prior Bitcoin bull market, a mid-cycle correction of 40–55% has served as the reset that cleared leveraged and speculative positions before the final phase of appreciation. The 2013 cycle featured an intermediate 83% drawdown. The 2017 bull run included a sustained correction from US$3,000 to US$1,800—a 40% fall—before Bitcoin eventually reached its then-record near US$20,000. The 2020–2021 cycle included a 54% correction in May 2021 before the asset resumed its upward trajectory to near US$69,000.
The pattern is not coincidental. Each mid-cycle reset performs a structural function: it transfers supply from weak hands to strong hands, exhausts short-term speculative leverage, and resets funding rates in futures markets. On-chain data from March 2026 confirms this process is well advanced. Long-term holder selling has collapsed. Miner capitulation has eased substantially. The market is being rebuilt on a foundation of patient institutional capital rather than speculative retail momentum.
The question is not whether this cycle’s dynamics are similar to prior ones. They are. The question is whether the character of the rebound—driven by ETF infrastructure, sovereign adoption, and institutional product normalisation—provides a more durable foundation than prior cycles. The preponderance of evidence suggests it does.
Institutional Playbook: Barbell Allocations for 2026 Portfolios
The barbell strategy gold Bitcoin framework is the most intellectually coherent response to the current environment. The logic is straightforward: gold provides left-tail protection against geopolitical shocks, currency debasement, and inflation spikes; Bitcoin provides right-tail exposure to monetary system evolution, liquidity cycles, and the institutional adoption premium.
The following allocation frameworks represent a practical taxonomy for institutional investors, calibrated by risk tolerance:
| Risk Profile | Gold Allocation | Bitcoin Allocation | Rationale |
|---|---|---|---|
| Conservative (pension funds, endowments) | 7–10% | 0.5–1.5% | Capital preservation priority; Bitcoin as satellite position |
| Balanced (family offices, diversified funds) | 4–8% | 1–3% | Barbell construction; VanEck-endorsed range |
| Growth-oriented (hedge funds, SWFs) | 3–6% | 3–5% | Maximum diversification across monetary regimes |
Several institutional principles bear emphasis. First, size matters less than construction. A 1% Bitcoin allocation in a US$10 billion endowment represents a US$100 million commitment—sufficient to achieve meaningful portfolio impact without disproportionate risk concentration. Second, rebalancing frequency matters. Given Bitcoin’s volatility, quarterly rebalancing back to target weights is preferable to annual adjustment, as it systematically captures mean-reversion premia. Third, product choice matters. ETF exposure through vehicles such as BlackRock’s IBIT or Fidelity’s FBTC provides regulatory clarity, custodial assurance, and institutional governance compatibility that direct ownership does not.
The digital gold thesis of 2026 has evolved beyond the simple rhetorical comparison. Bitcoin is not digital gold in the sense of behavioural mimicry—it does not replicate gold’s geopolitical shock absorption. It is, rather, a distinct monetary primitive: the world’s first natively digital scarce asset, with asymmetric return characteristics, a structurally shrinking supply post-halving, and a growing institutional adoption premium baked into its risk profile. Gold provides the portfolio’s defensive ballast. Bitcoin provides its asymmetric accelerant.
Risks and Rewards: Gold as Anchor, Bitcoin as Accelerator
No institutional analysis is complete without an honest accounting of the risks on both sides of the barbell.
Gold’s immediate headwind is the US dollar. With the DXY index near 108 in late March 2026, a strong dollar constrains gold’s global demand by making it more expensive in non-dollar currencies. JPMorgan analysts have maintained a cautious near-term target of US$4,350 per ounce by end of April 2026, even as Goldman Sachs has set a more constructive target of US$4,600. Should the Federal Reserve signal a pivot to rate cuts in the second quarter—a scenario with meaningful probability given cooling growth and persistent tariff headwinds—gold would likely resume its uptrend as real yields compress.
Bitcoin’s principal risks are macroeconomic rather than structural. Its high correlation with Nasdaq means that a sustained equity bear market would exert significant downward pressure, irrespective of Bitcoin’s own fundamental developments. A DXY above 112—a scenario JPMorgan assigns roughly 15% probability—would represent an unusually powerful dollar headwind that could overwhelm ETF-related demand. Regulatory risk, while substantially reduced by the SEC’s approval of spot ETFs and the EU’s MiCA framework, remains a tail risk in less-developed jurisdictions.
Yet the Bitcoin safe haven 2026 argument does not require Bitcoin to behave identically to gold. It requires only that Bitcoin deliver uncorrelated, positive expected returns over a medium-to-long time horizon. Galaxy Digital’s research has estimated roughly equal market-implied probability of Bitcoin reaching US$130,000 or US$70,000 by mid-2026, with a year-end distribution spanning US$50,000 to US$250,000. The asymmetry of this distribution—where the upside is multiples of the downside from current levels—is precisely the characteristic that justifies inclusion in a diversified institutional portfolio. The expected value of a small Bitcoin allocation is positive even under conservative assumptions about adoption.
Forward 2026 Outlook: A Tale of Two Monetary Regimes
Looking ahead to the second and third quarters of 2026, the macro environment supports both legs of the barbell, albeit through different transmission mechanisms.
Gold benefits from continued central bank buying from non-Western sovereigns, from any Fed pivot that compresses real yields, and from persistent geopolitical risk premiums in energy and credit markets. The structural case for gold Bitcoin portfolio diversification has rarely been stronger: a world of fiscal dominance, multipolar currency competition, and deglobalisation rewards hard assets across the monetary spectrum.
Bitcoin benefits from the structural reduction in new supply post-halving, from continued ETF-driven demand accumulation, and from the still-early-stage sovereign adoption cycle. Fidelity Research forecasts that competitive pressure between nations to acquire Bitcoin reserves could accelerate in 2026 and beyond, compressing the available float further. If Bitcoin participates in even a fraction of the institutional re-allocation away from bonds—currently still the dominant defensive asset—the demand implications are substantial.
For the most sophisticated allocators, the question in 2026 is not whether to own gold or Bitcoin. It is how to size the barbell, when to rebalance it, and through which vehicles to express it. The answer will vary by mandate, liability structure, and governance framework. But the underlying logic is durable: in a world where no single monetary system commands uncontested authority, owning the hardest available assets on both the analogue and digital dimensions of the monetary spectrum is not speculation. It is prudence.
Conclusion: The Institutional Imperative of the Great Decoupling
The Bitcoin vs gold 2026 narrative has matured beyond a binary contest. Gold is not under threat from Bitcoin. Bitcoin is not a failed gold substitute. They are, in the current market structure, genuinely distinct instruments fulfilling complementary roles in a sophisticated multi-asset portfolio.
Gold, at US$4,400 per ounce in late March 2026, is performing exactly as designed: absorbing geopolitical shock, preserving purchasing power, and providing institutional ballast against a macro backdrop that remains deeply uncertain. Bitcoin, consolidating in the US$66,000–US$71,000 range after its mid-cycle reset, is also performing as its structure implies: transferring ownership from weak hands to long-term institutional holders, building a more durable demand foundation through ETF infrastructure, and preserving the asymmetric upside that justifies its inclusion in growth-oriented allocations.
The institutional portfolio managers who will navigate 2026 most effectively are those who resist the temptation to crowd into whichever asset has performed most recently, and instead embrace the structural logic of the barbell: gold as left-tail protection, Bitcoin as right-tail acceleration. The two assets are not converging. They are decoupling. And that decoupling, properly understood, is not a problem to be solved. It is an opportunity to be exploited.
For pension funds, endowments, and family offices managing long-duration liabilities in a world of structural monetary uncertainty, the message is clear: position the barbell now, rebalance it deliberately, and hold both legs with conviction. The great decoupling has only just begun.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
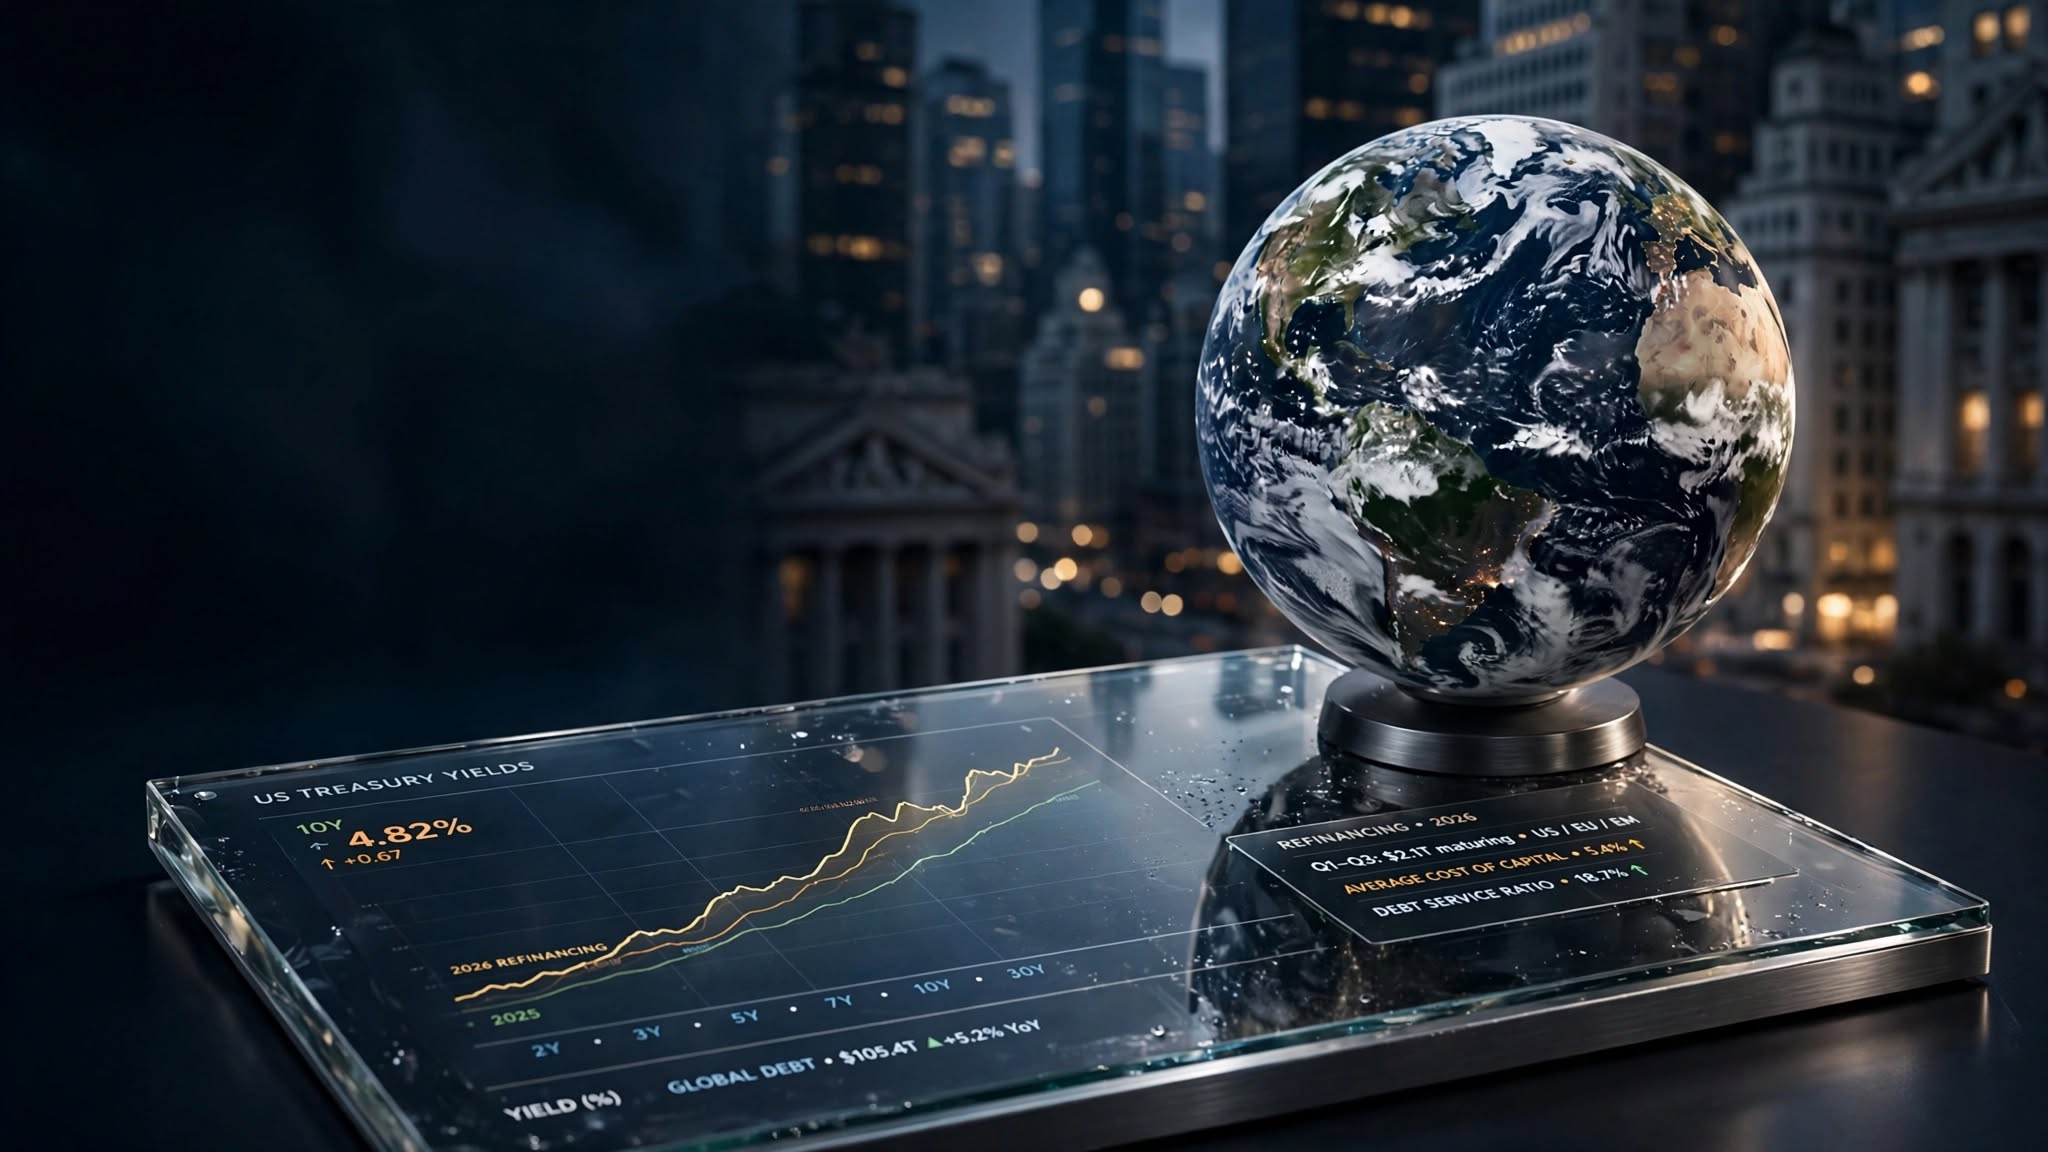
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
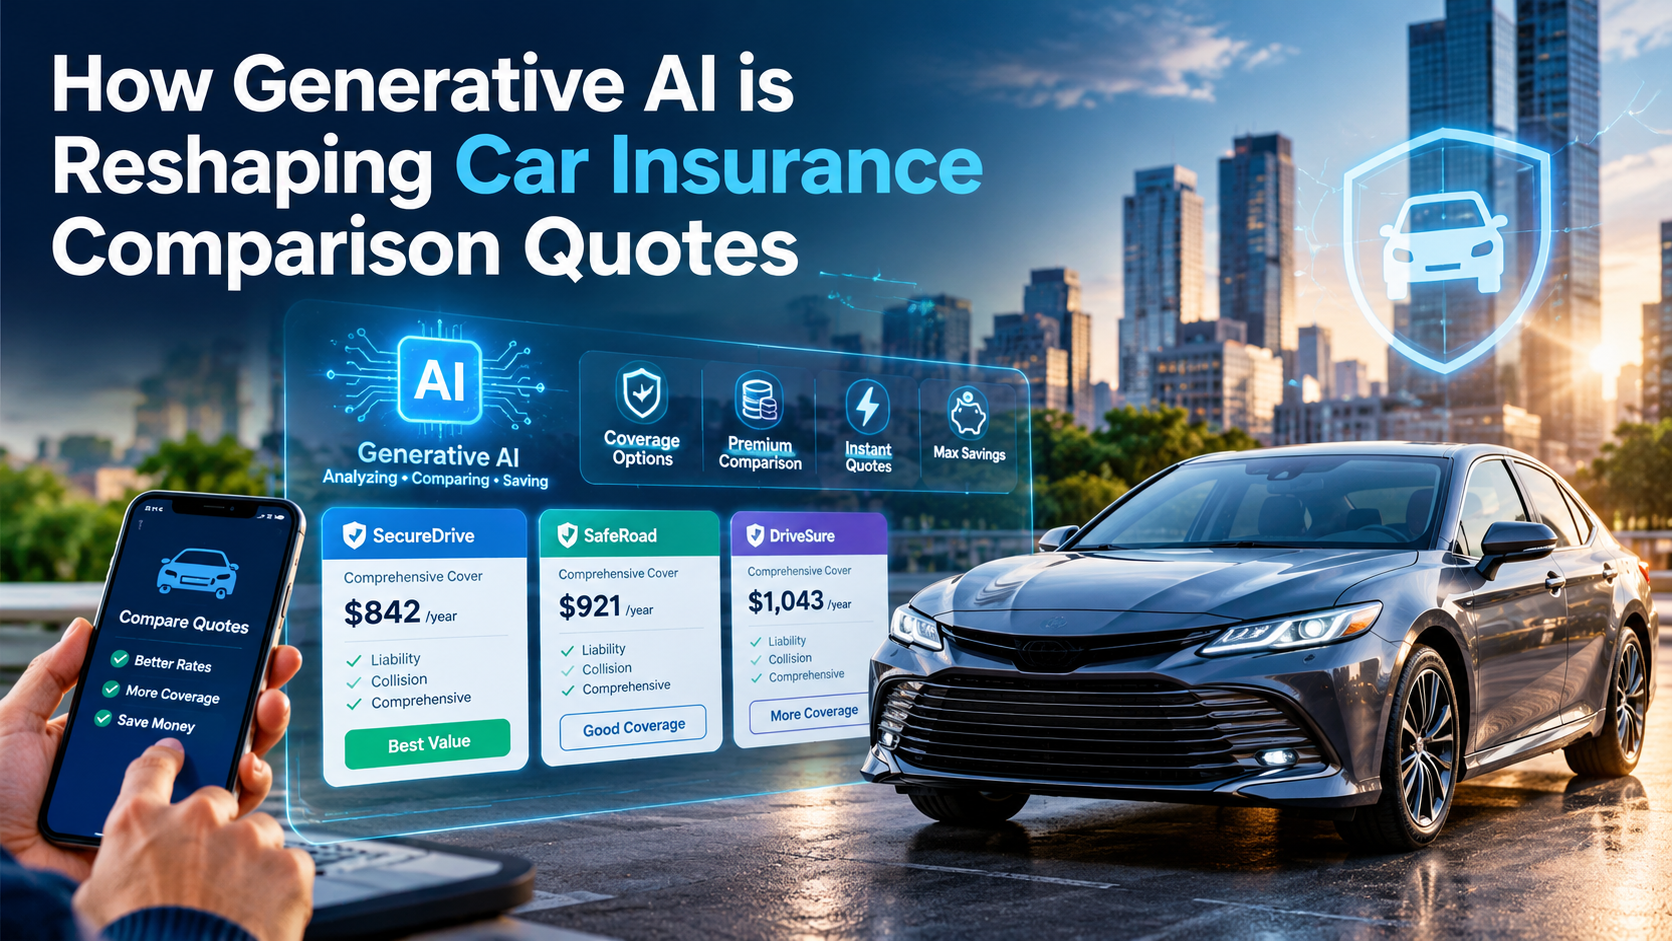
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

SpaceX Starship Achieves First Full Orbit on Historic 10-Hour Test Flight 14

Google’s $15B Finland AI Investment: Data Centers, Nuclear Power & Jobs

Fast Invoice Factoring: Rates, APR Math & Contract Traps

SOC 2 Type II Guide: Cost, Timeline & Compliance Companies

Hong Kong Wages Surge 3.4% in June: Sector Data & Analysis

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Social Security Trust Fund 2032: OASI Depletion Timeline Explained
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025