
Analysis
Offshore Finance: Why Tax Havens Are Thriving Despite Crackdowns

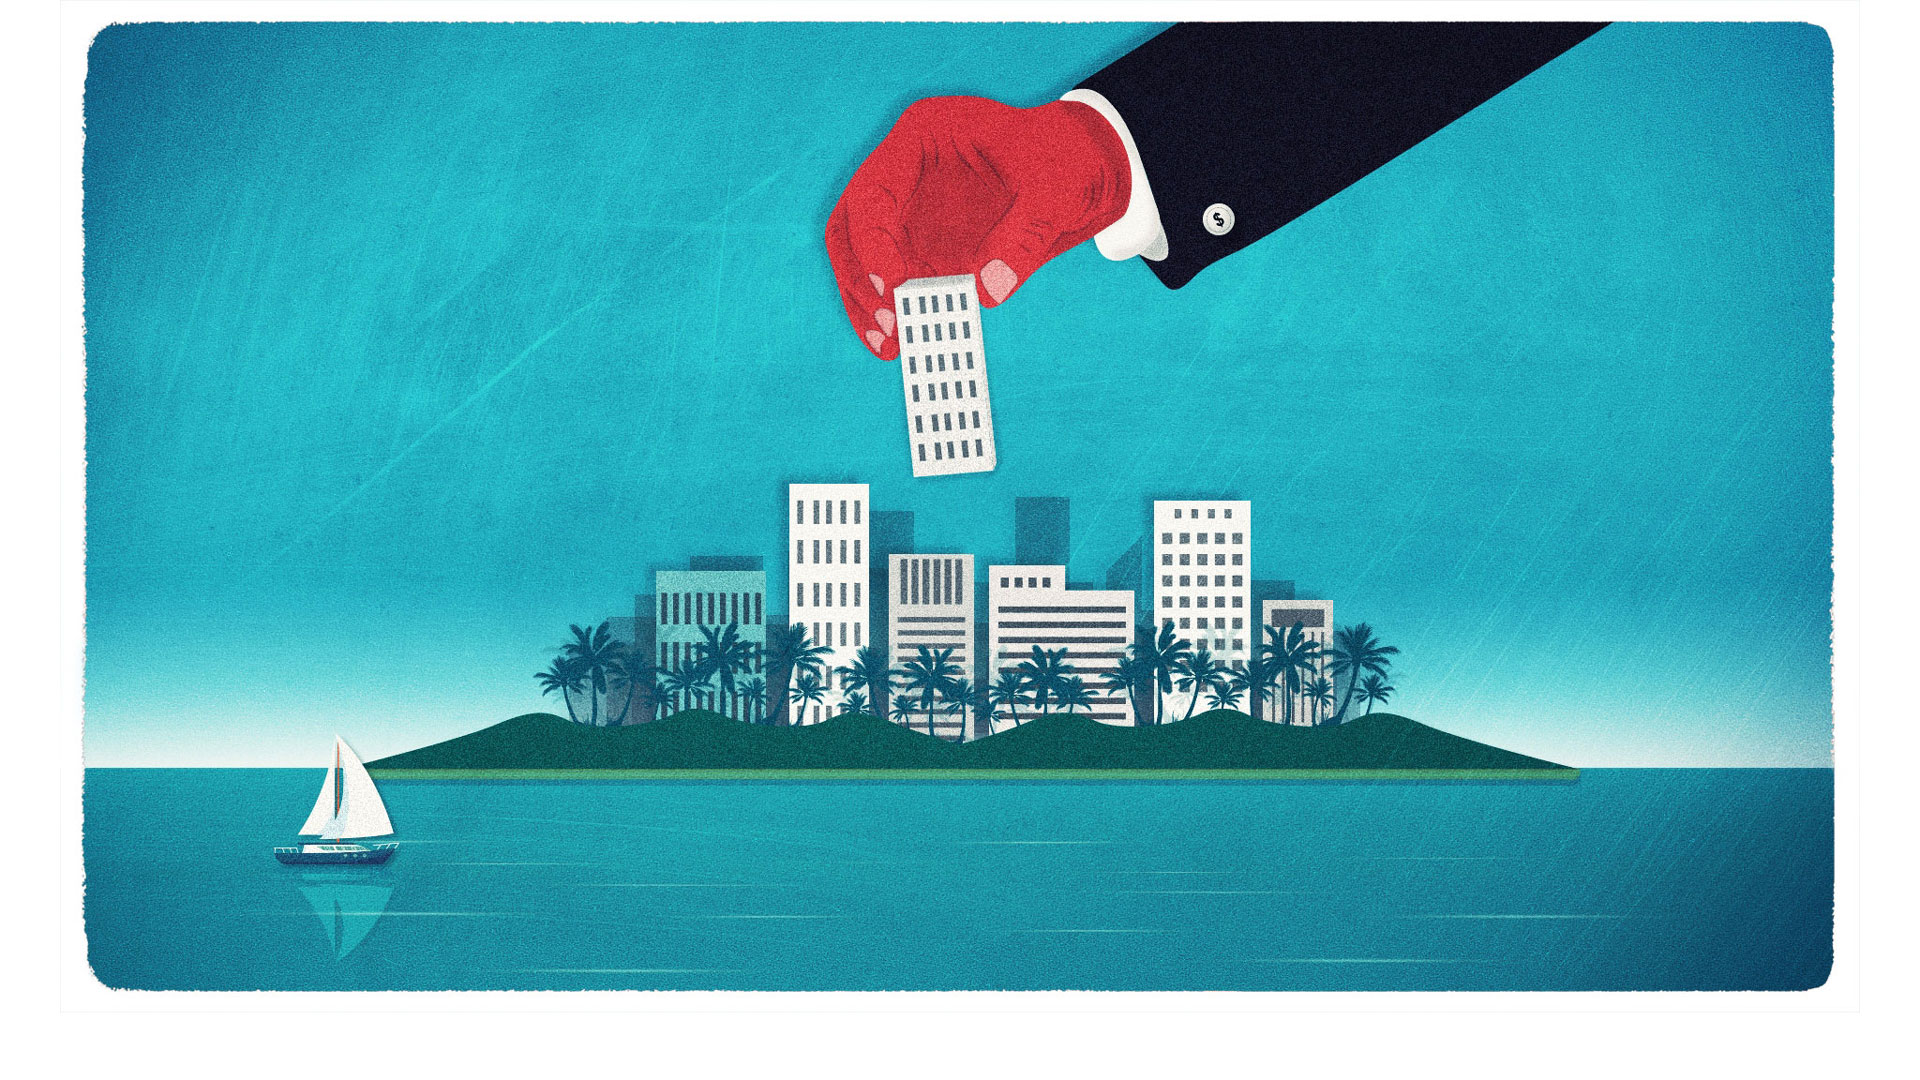
There is a lot more to havens than crystal-clear waters and a promise of opacity
In June 2025, a deadline passed that was supposed to mark a turning point. The United Kingdom had demanded that its Overseas Territories — the British Virgin Islands, the Cayman Islands, Bermuda — establish publicly accessible registers of beneficial ownership by that date. All three missed it. A Foreign Office minister called the outcome “progress.” He welcomed the compliance of St Helena and the Falkland Islands, two territories with a combined handful of registered companies. The three jurisdictions that actually matter — that between them host trillions of dollars in offshore structures — simply carried on. The offshore finance industry, it turns out, is extremely good at absorbing pressure while changing remarkably little.
The reforms were real. The pressure was genuine. Since the 2009 G20 summit in London, governments have pushed hard for a more transparent global financial system, deploying everything from automatic information exchange to blacklists and the sweeping architecture of the OECD’s Base Erosion and Profit Shifting (BEPS) project. The 15% global minimum corporate tax under Pillar Two began applying from January 2024, with over 135 jurisdictions formally signed up.
Yet the money kept moving offshore. According to the EU Tax Observatory, $12 trillion — equivalent to roughly 12% of world GDP — was held offshore by households at the end of 2022, a figure that excludes real assets such as art, yachts, or real estate. A more recent Oxfam analysis suggests global offshore wealth reached $13.25 trillion in 2023, with as much as $3.55 trillion potentially concealed from tax authorities. These are not numbers heading in the right direction for reformers. TaxobservatoryBreezyScroll
Why Are Offshore Tax Havens Still Thriving Despite Global Crackdowns?
Offshore finance thrives because the industry does not resist change — it incorporates it. The offshore financial centres of 2025 are no longer selling secrecy as a primary product. They are selling legal compliance infrastructure, governance structures, and regulatory arbitrage that operates entirely within the letter of international rules. The crackdowns made havens evolve; they did not make them disappear.
The Core Development: Adaptation, Not Extinction
The template of the classic tax haven — a sun-drenched island, a brass-plate company, an anonymous numbered account, and an absolute refusal to answer questions — is largely gone. What replaced it is more sophisticated and, crucially, harder to attack.
The Cayman Islands offers the clearest illustration. The Cayman Islands’ Beneficial Ownership Transparency Act and its accompanying regulations came into force on 31 July 2024, replacing the previous beneficial ownership regime and creating a consolidated legal framework that, on paper, aligns with international standards set by the Financial Action Task Force (FATF). In the BVI, sweeping changes to beneficial ownership reporting came into effect on 2 January 2025, requiring entities to file details of their beneficial owners directly with the Registry of Corporate Affairs rather than with private registered agents — a structural shift in accountability that would have been unthinkable a decade ago. OgierOgier
That is the glass-half-full reading. The glass-half-empty version matters more.
Compliance and transparency, in this context, are not the same thing. Historically, beneficial ownership information in the BVI remained largely confidential, with only competent authorities and law enforcement agencies able to access beneficial ownership information — and even the July 2025 amendments merely extended access to third parties demonstrating “legitimate interest,” a term whose definition remains contested and narrow. A journalist, a civil society researcher, or an ordinary citizen cannot freely search who owns what. Ogier
Professor Jason Sharman of Cambridge, one of the world’s leading authorities on offshore finance, is blunt about the overall picture: “Offshore financial centres in general are doing fine. There is probably more money offshore than ever before — subject to the caveat that it is harder than it might seem to distinguish ‘offshore’ from ‘onshore.'” World Finance
That caveat contains a story of its own.
The Structural Shift: From Secrecy to Substance — and Why It Changes Less Than You’d Think
The OECD’s Pillar Two global minimum tax is the most ambitious piece of international tax architecture in a generation. By imposing a 15% effective rate on multinational enterprise groups with revenues above €750 million, it was designed to sever the link between where profits are booked and where taxes are paid. Many jurisdictions have taken steps to implement these rules into domestic law, with the global minimum tax starting to apply from the beginning of 2024 through the Income Inclusion Rule. OECD
Yet the architecture has a structural weakness: it targets large multinationals, not the vast majority of offshore finance activity. Private wealth held through trusts and family offices, the preferred vehicles of the ultra-rich, sits largely outside Pillar Two’s scope. Offshore structures remain useful for governance, asset protection, and operational flexibility — not just tax optimisation. Substance, transparency, and banking acceptance now play a bigger role than ever. Structures that are clear, explainable, and aligned with real activity are far more resilient under Pillar Two rules. Q Wealth Report
What this means, in practice, is that the industry shifted its sales pitch. The pitch is no longer “hide your money.” It is “structure your money correctly.” The distinction sounds lawyerly because it is — and that is precisely the point.
Why does offshore wealth keep growing despite transparency rules? Offshore finance persists because transparency frameworks and tax rules address different problems imperfectly. Automatic information exchange catches declared accounts in cooperating jurisdictions but cannot easily reach trust structures, real assets, or entities layered across multiple non-cooperating jurisdictions. Pillar Two covers large corporations but not private wealth. Each reform closes one gap and, inadvertently, signals where the remaining gaps are.
Implications: The Geography of Money Is Being Redrawn
The most consequential second-order effect of the crackdown era isn’t that offshore finance shrank. It’s that it moved — to places with better reputations, better infrastructure, and better lawyers.
Singapore is the most important beneficiary. HSBC’s 2025 Affluent Investor Snapshot, drawing on data from nearly 11,000 investors across 12 markets, confirmed Singapore’s emergence as the top choice in Asia for affluent investors opening overseas accounts, ranking alongside the United States and Hong Kong as one of the three most preferred destinations globally. Singapore is not conventionally understood as a tax haven. It has a corporate tax rate of 17%, maintains FATF compliance, and participates in automatic information exchange. It is also a jurisdiction where private wealth management operates with a level of discretion, regulatory clarity, and legal sophistication that rival jurisdictions cannot match. It combines the appearance of legitimacy with the functionality of a haven. Hsbc
The UAE is the even more striking case. According to Henley & Partners, the UAE is forecast to attract a net inflow of around 9,800 millionaires in 2025, bringing an estimated $63 billion in investable wealth, as the Dubai International Financial Centre emerges as the jurisdiction of choice for international families and corporates. The UAE’s zero income tax, residency-by-investment programmes, and modern trust law make it simultaneously a lifestyle destination and an offshore finance hub — a combination that is extraordinarily difficult for regulators to target. Alpadis
Then there is the United States. South Dakota, by 2025, has accumulated trust assets running into hundreds of billions of dollars, shielded by perpetual trust laws and among the loosest disclosure requirements of any developed jurisdiction. Delaware incorporations continue to offer minimal transparency to non-US inquirers. The country that leads the charge against offshore abuse is itself, by any objective measure, one of the world’s significant offshore finance destinations. That contradiction is not lost on reformers — and it substantially weakens Washington’s moral authority when pressing smaller jurisdictions to comply.
Gabriel Zucman of the EU Tax Observatory proposed in 2024, at the G20 Finance Ministers’ meeting in Brazil, that billionaires be required to pay a minimum of 2% of their wealth in taxes annually. The proposal targets around 3,000 billionaires globally and is estimated to raise an additional $250 billion a year in revenues, primarily in the richest countries where the great majority of billionaires reside. In November 2024, the G20 leaders gave it lukewarm endorsement. The Trump administration’s posture toward global tax coordination has since complicated the picture considerably. Tax Justice Network
The Counterargument: Reformers Have Made Real Gains
It would be a mistake to dismiss the last decade of reform as theatrical. The progress is genuine — partial, incomplete, but real.
The OECD’s Common Reporting Standard, now operating across more than 100 jurisdictions, has transformed the baseline of financial transparency. Nearly 100 countries are now automatically exchanging information on accounts worth $11 trillion — a scale of data-sharing that was unimaginable before 2013. Tax authorities in France, Germany, Australia, and elsewhere have used that data to collect billions in previously unpaid taxes. Several classic bank-secrecy jurisdictions — Switzerland chief among them — have fundamentally altered their operating models. Tax Justice Network
Pascal Saint-Amans, the former director of the OECD’s tax policy division who ran much of the reform programme, has argued that the normative shift matters as much as the technical one. Before 2009, he observed, jurisdictions openly defended secrecy as a legitimate policy. Nobody defends it in those terms today.
Still, critics are right to push back on triumphalism. The Tax Justice Network estimates offshore wealth at between $24 trillion and $36 trillion when a broader range of asset classes is included, dwarfing the OECD’s narrower figure. The gap between information exchange agreements signed and enforcement action taken remains wide. And the beneficial ownership registers that do exist are frequently incomplete, filed with inaccuracies, or practically inaccessible to the investigators who most need them.
The offshore finance industry did not survive a decade of unprecedented regulatory pressure by being fragile.
Closing
The central tension in offshore finance is not between the havens and the reformers. It is between the pace of legal architecture and the velocity of capital. Regulations are drafted, debated, passed, implemented, and tested — a process that takes years. Capital moves in seconds, guided by lawyers and advisers who have read every proposed amendment before it becomes law, and who have already begun stress-testing the structures that will operate within the new rules the moment they take effect.
The crackdowns are real. So is the $13 trillion. The offshore world isn’t thriving in spite of transparency reforms — it’s thriving, in significant part, because of them. Every new compliance framework creates a premium for jurisdictions that can credibly offer both legitimacy and discretion. The more the rules tighten, the more valuable expert navigation of those rules becomes.
Opacity used to be free. Now it’s expensive, sophisticated, and dressed in a compliance report.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Despite decades of bans and strict handling mandates, asbestos remains a silent killer across legacy manufacturing plants, shipyards, and modern green-energy infrastructure retrofits. In 2026, regulatory changes by the EPA and tightened occupational health standards have triggered a fresh wave of mesothelioma litigation. Manufacturers attempting to fast-track industrial transitions are encountering catastrophic oversight, exposing workers to legacy toxins and opening corporate parent companies to unprecedented liability.
Navigating a mesothelioma claim in 2026 requires understanding how modern industrial supply chains intersect with historical exposure. Trusts established decades ago are being audited under stricter transparency laws, altering payout ratios and accelerating fast-track settlements for terminally ill plaintiffs.
Modern Industrial Exposure Hotspots
Green Retrofitting and Renewable Energy Infrastructure
A primary source of 2026 asbestos exposure occurs during the decommissioning and retrofitting of older industrial facilities for renewable energy production. Workers insulating electrical grids, modernizing HVAC systems, or upgrading manufacturing floors frequently disturb encapsulated asbestos materials that were improperly documented or ignored during facility audits.
Automotive and Aerospace Supply Chains
With advanced manufacturing booming, workers handling specialized friction materials, gaskets, and heat shields face ongoing risks. Supply chain tracing has become more sophisticated, allowing legal teams to pinpoint exact corporate entities responsible for raw material distribution across multinational borders.
| Industry Sector | Primary Exposure Risk | Legal Venue / Trust | Avg. Claim Value Range |
| Green Energy Retrofit | Disturbed insulation, pipe lagging | Federal Tort / Manufacturer Trust | $1.2M – $3.5M |
| Shipbuilding & Marine | Boiler insulation, structural seals | Asbestos Bankruptcy Trusts | $800K – $2.4M |
| Automotive Manufacturing | Brake components, high-heat gaskets | Third-Party Product Liability | $600K – $1.8M |
Securing Maximum Compensation: Steps for Plaintiffs
Time is of the essence in mesothelioma cases. Plaintiffs and their families must act decisively to secure financial recovery before statutes of limitations expire.
Retain Specialized Counsel: Work exclusively with national mesothelioma law firms possessing deep historical databases of asbestos-containing products.
Audit Employment History: Document every job site, supervisor name, and equipment brand encountered throughout your career.
Expedite Medical Filings: Secure a formal pathological diagnosis quickly to qualify for expedited trust fund distribution and priority trial settings.
“Expert Insight: Modern asbestos litigation is no longer just about historical tracking; it is about holding modern corporations accountable for failing to conduct rigorous environmental safety audits before initiating industrial retrofits.”
By combining meticulous work history reconstruction with aggressive multi-trust filings, victims can secure substantial financial relief to cover specialized immunotherapy and family support.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Stagflation Explained: Causes, Global Impact & 2026 Economic Outlook

Understanding Foreign Exchange Reserves: Key Purposes and Global Impact

The Business of Gaming and Tech: How Global Economies Are Driven by Digital Consumerism

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Anthony Scaramucci’s Crypto Prediction: Why MicroStrategy’s Move Is Bitcoin’s “iPhone Moment”

Best Dividend Stocks 2026: European & Asian Blue Chips

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Elon Musk’s Boring Company Hits $23B Valuation After UAE-Led $3 Billion Series D

Middle East War Economics 2026: Oil Prices & Energy Markets

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Asian Markets Outlook 2026: China, Japan & Singapore Stocks

Global Economy 2026: IMF Growth, Inflation & Private Credit

Current Account Deficit (CAD) : Causes and Impact

Balance of Payments (BOP)

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Gold’s Wild 2026: From a Record $5,600 Peak to a 24% Crash and Back Toward $4,500

Oil Surges as Strait of Hormuz Traffic Collapses Again

The Rocket That Won’t Quit: Inside SpaceX’s Falcon 9 Launch Machine

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

Retail Earnings Week: What Home Depot, Target & Walmart Reveal

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Tween Back-to-School Trends 2026: What’s Driving the $85B Season
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025