
Markets & Finance
Global Stock Markets 2026: S&P 500 at Record Highs Amid War, Inflation & Rate Risk

The S&P 500 is trading near 7,400. The Nasdaq Composite sits above 25,000. The Dow Jones Industrial Average has traded above 51,000. Germany’s DAX is near record levels. European bourses broadly have recovered from the shock of the Middle East conflict.
None of this is supposed to make sense. The United States is managing the aftermath of a war with Iran. Inflation is at a three-year high. The Federal Reserve has just delivered its most hawkish signal in years. Oil inventories are at their lowest levels since 2003. And yet equities are — by most historical valuation measures — significantly overvalued and refusing to reflect the risks that seem obvious from the headlines.
How is this possible? And more importantly for investors: how long can it last?
The Paradox of the Resilient Market
To understand why global equity markets are elevated in 2026, the conventional frameworks need updating. The pre-war, pre-AI-boom mental model — where high inflation leads to rate hikes which lead to multiple compression which leads to market declines — is too linear.
What 2026 markets are doing is more complex: they are simultaneously pricing AI-driven earnings optimism and geopolitical risk relief, while discounting the slow-moving structural risks that have not yet crystallised into specific negative events.
This is not irrational. Markets are discounting mechanisms. They do not price what is visible in today’s headlines; they price what investors collectively believe will be visible in earnings, rates, and economic conditions 12–18 months from now. In 2026, the collective bet appears to be:
- The US-Iran ceasefire holds and oil prices remain subdued
- AI capex generates genuine earnings growth in the technology sector
- The Fed’s hawkish signal does not translate into aggressive tightening that chokes growth
- Consumer spending slows but does not collapse
- The AI bubble deflates gradually rather than popping catastrophically
If all five of those things are true simultaneously, the current market valuation is defensible — though stretched. If any one of them fails materially, the downside repricing could be sharp.
The AI Premium: Real or Illusory?
The single most important driver of US equity market performance since 2023 has been the AI premium embedded in technology sector valuations. The Magnificent Seven — Apple, Microsoft, Alphabet, Amazon, Nvidia, Meta, and Tesla — have collectively driven a disproportionate share of S&P 500 returns.
The valuation premium they carry is based on a belief that AI will generate secular earnings growth that justifies current multiples. This is not pure speculation — there is real revenue evidence:
- Microsoft‘s Azure cloud business is growing rapidly on AI-driven demand
- Alphabet is monetising AI through search and cloud
- Meta has seen significant advertising efficiency gains from AI-driven targeting
- Nvidia‘s AI chip revenue has exceeded all prior forecasts
But the premium also contains genuine speculative excess. According to GuruFocus, the S&P 500 as represented by the SPY ETF was priced at approximately $754.83 in mid-June 2026, while its GF Value — a fundamental intrinsic value estimate — stood at $650.66. That represents approximately 16% overvaluation on a fundamental basis.
Sixteen percent overvaluation is not a bubble by historical standards. The peak of the dot-com bubble involved overvaluations an order of magnitude larger. But 16% above intrinsic value, combined with the macro risks described above, implies limited margin of safety.
European Markets: The Recovery That Surprised
European equity markets have been among the more surprising performers in 2026. Germany’s DAX closed 1.59% higher in the week of June 16, France’s CAC 40 rose 1.40%, and Italy’s FTSE MIB gained 2.31% — all strong weekly performances in an uncertain macro environment.
The UK’s FTSE 100 was the notable outlier, slipping 0.69% in the same period — weighed down by political uncertainty following reports that presumptive next prime minister Andy Burnham intends to reassign Chancellor Rachel Reeves to a more junior role. The BBC and Financial Times reports prompted a sharp currency and equity reaction, underscoring how much political risk premium UK assets carry ahead of a potential change in government.
Europe’s resilience despite weak fundamentals is partly explained by composition. The major European indices have lower technology weighting and higher exposure to financial services, industrials, and energy — sectors that have benefited from the rate environment and, in energy’s case, from the elevated commodity price environment.
The eurozone trade deficit — which swung to a EUR 1 billion deficit in April against expectations of a EUR 7.8 billion surplus — is a concerning signal about European competitiveness. The surprise deficit was driven by a growing energy trade deficit and a shrinking machinery and vehicles surplus. Germany’s wholesale prices rose 5.9% year-over-year in May, down from 6.3% in April — still elevated, with petroleum products and nonferrous metals leading increases.
The ZEW Indicator of Economic Sentiment rose sharply in June 2026 to its first positive reading since the start of the Middle East conflict — a sign that European investor confidence is recovering as energy prices ease, even if the underlying data remains mixed.
Emerging Markets: Divergent Fortunes
Emerging market equity performance in 2026 has been shaped primarily by three variables: commodity prices, US rate expectations (which drive dollar strength and capital flow dynamics), and geopolitical proximity to the Middle East conflict.
South Korea had one of the most dramatic EM stories — a near-100% Kospi rally through mid-2026, driven by semiconductor and AI supply chain positioning, followed by a sharp 10% correction as global tech sentiment shifted.
Brazil is navigating a genuine policy dilemma. The central bank cut its benchmark Selic rate by 25 basis points to 14.25% — its third consecutive cut — but delivered a cautious statement acknowledging that both economic activity and inflation have accelerated. The Selic rate remains among the highest real interest rates of any major economy, a legacy of Brazil’s own inflation challenge.
Indonesia remains under watch from index providers, with the MSCI Indonesia review a key near-term catalyst for the Jakarta Composite. A potential upgrade or downgrade from MSCI — depending on market accessibility improvements and foreign ownership rule changes — could drive significant capital flows into or out of Indonesian equities.
China presents the most complex EM story, as detailed elsewhere: a property sector in structural contraction, a technology sector in aggressive expansion, and a PBOC navigating carefully between domestic stimulus needs and external currency management constraints.
The Rotation Trade: Away From Growth, Toward Value
One of the defining equity market dynamics of 2026 has been the rotation from growth to value — from high-multiple technology stocks to financials, industrials, healthcare, and consumer staples.
This rotation is classically associated with the late phase of an economic expansion: when growth expectations moderate, when rates are elevated or rising, and when investors are seeking earnings certainty over earnings optionality.
The rotation does not require a market crash. It can proceed while the overall index trades sideways or grinds modestly lower. But it does imply that passive index investing in the S&P 500 — with its heavy technology weighting — faces a structural headwind as long as the rotation continues.
Active managers with the flexibility to overweight financials, healthcare, and defensive sectors relative to technology may outperform in this environment. The case for active management versus passive is stronger in late-cycle environments than at any other point in the economic cycle.
The Three Scenarios for 2H 2026
Scenario 1: Soft Landing (Base Case — 50% Probability)
The ceasefire holds, oil prices stabilise in the $70–$85 range, the Fed hikes once or twice but growth remains positive, consumer spending muddles through, and AI earnings broadly meet elevated expectations. Markets grind sideways to modestly higher. S&P 500 ends 2026 in the 7,200–7,600 range.
Scenario 2: Hawkish Shock (Elevated Probability — 30%)
The Fed hikes three times as BofA forecasts, pushing the federal funds rate to 4.25%–4.50%. Mortgage rates rise, consumer spending contracts, and the AI premium compresses on rate-driven multiple contraction. S&P 500 pulls back to 6,400–6,800. Technology and growth stocks underperform defensives significantly.
Scenario 3: Geopolitical Escalation (Tail Risk — 20%)
The 60-day ceasefire framework breaks down, oil prices spike above $100, inflation expectations become unanchored, and the Fed faces the impossible choice of fighting inflation in a stagflationary environment. S&P 500 could fall to 5,800–6,200 in an acute shock scenario. Gold surges, bonds rally as the growth scenario deteriorates, and defensives outperform sharply.
The Bottom Line
Global stock markets are elevated not because investors are ignoring the risks of 2026 — inflation, war, tariffs, AI bubble concerns, and an uncertain Fed path — but because they are betting the good scenarios outweigh the bad.
That bet may be correct. The US economy has demonstrated remarkable resilience. AI infrastructure investment is real and growing. The ceasefire has provided oil price relief. Corporate earnings, while not accelerating, have not collapsed.
But the margin of safety has been consumed by three years of AI-driven multiple expansion. Markets that are 16% above intrinsic value, with a hawkish Fed, geopolitical uncertainty, and consumers under pressure, do not crash automatically — but they do not recover easily from negative surprises.
Investors who position for resilience — through diversification, defensive sector exposure, fixed-income duration management, and commodity hedging — are better placed for 2H 2026 than those who extrapolate the last three years of AI momentum indefinitely forward.
FAQ
Q: Why is the stock market so high in 2026?
A: Markets remain elevated primarily due to AI-driven earnings optimism in the technology sector, geopolitical relief from the US-Iran ceasefire, and resilient corporate earnings. However, valuations are approximately 16% above fundamental intrinsic value, leaving limited margin of safety.
Q: Is the S&P 500 overvalued in 2026?
A: By GF Value estimates, the S&P 500 is approximately 16% overvalued as of mid-June 2026. This is not an extreme overvaluation by historical standards, but it does imply limited margin of safety against macro risks including a Fed tightening cycle, geopolitical escalation, or AI earnings disappointment.
Q: What could cause a stock market crash in 2026?
A: The primary downside scenarios include: a resumption of Middle East conflict pushing oil back above $100; an aggressive Fed tightening cycle compressing technology multiples; a rapid AI bubble deflation if leading AI companies miss earnings expectations; or a consumer spending contraction driven by debt exhaustion and rising borrowing costs.
Q: What is driving global stock market gains in 2026?
A: The primary driver is AI-related technology sector performance. Secondary drivers include geopolitical risk relief from the US-Iran ceasefire, resilient corporate earnings, and accommodative financial conditions in parts of Europe and emerging markets.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


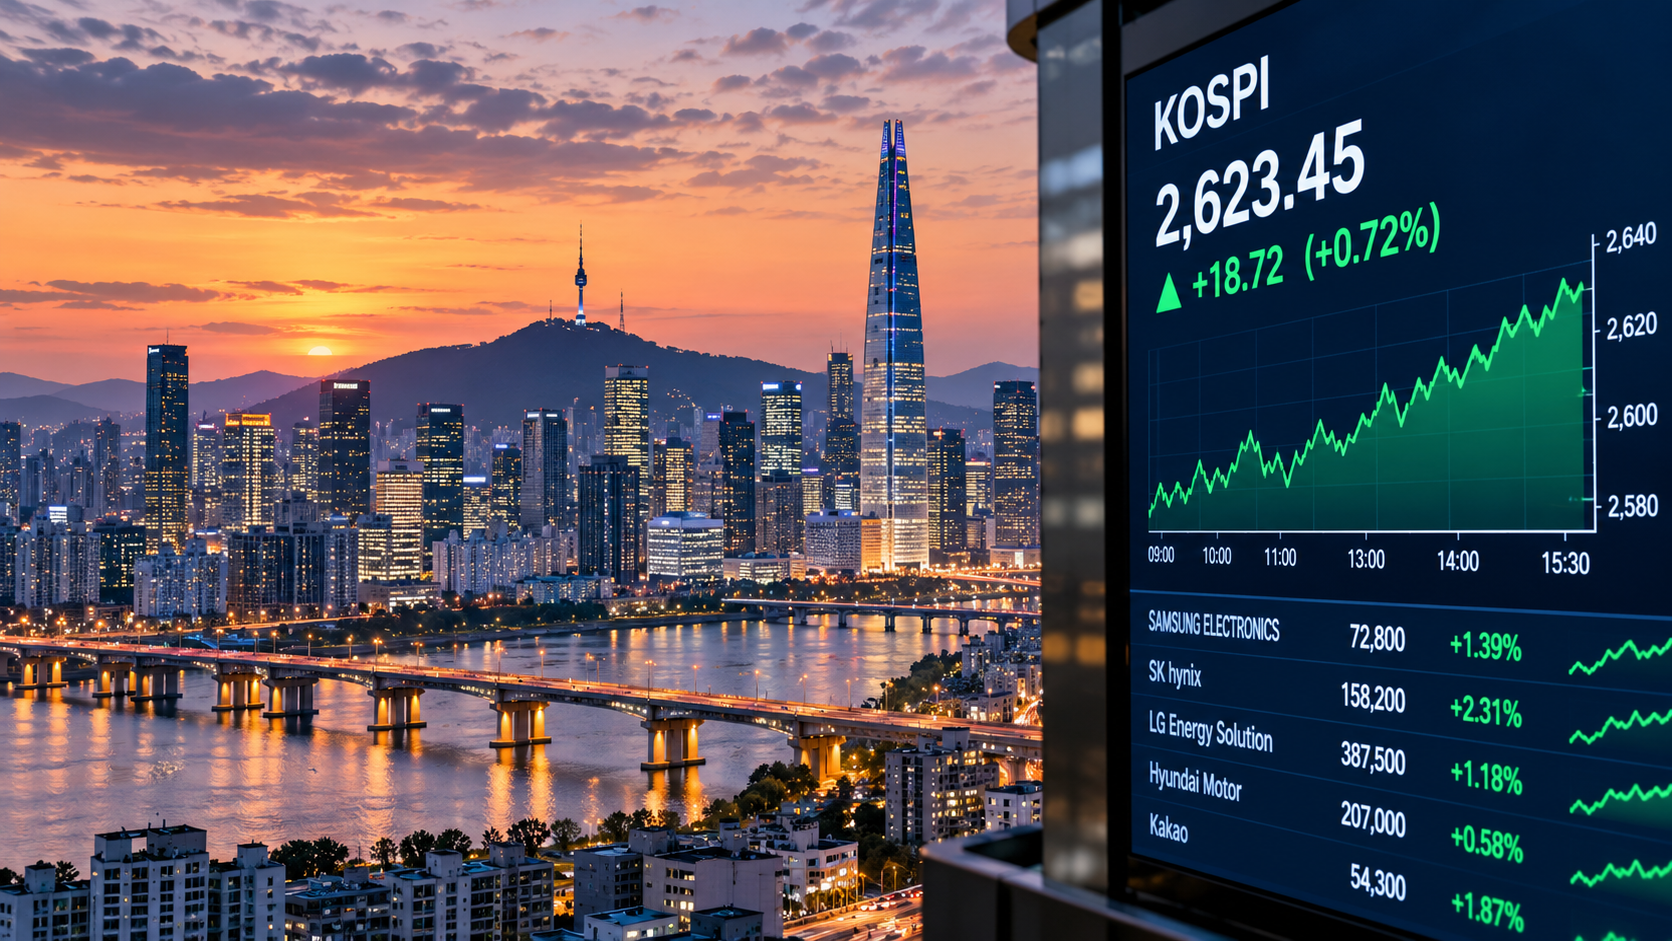
The KOSPI is sensitive to major Korean semiconductor companies but is not solely a technology index. Currency, sector weights and market timing all matter. Original research October 12; updated October 15, 2026. Verify newer developments before publication.
On October 15 the KOSPI closed 7.57% lower at 5,554.22 amid an AI-linked chip stock selloff. Reuters reported that the exchange invoked its circuit breaker during the session. This verified update supersedes earlier articles dated October 12. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
On October 15 the KOSPI closed 7.57% lower at 5,554.22 amid an AI-linked chip stock selloff. Reuters reported that the exchange invoked its circuit breaker during the session. This verified update supersedes earlier articles dated October 12. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
South Korea’s KOSPI has become a vivid measure of the rewards and risks of the AI hardware trade. October 12 coverage described a sharp retracement following an exceptionally strong first-half rally, with Samsung Electronics and SK Hynix central to market moves. Such reporting should be read in context: a dramatic fall after a large rise can coexist with a positive year-to-date performance. Sources: Business Insider KOSPI analysis and Barron’s chip market coverage.
The important context competitors can overlook
KOSPI is a stock-market index, not an ETF or an individual security. Investors considering exposure must distinguish the benchmark from specific Korea funds, currency hedges and concentrated semiconductor holdings. Global demand for high-bandwidth memory matters, but so do chip pricing, inventory cycles, capital spending and the Korean won. A profitable technology cycle can still produce volatile stock returns when valuations already anticipate perfection. For primary-source checks and current reporting, see Business Insider KOSPI analysis and Reuters chip demand report. The key distinction is explain memory-chip concentration and cross-market exposures.
A practical way to use this information
When comparing KOSPI with Taiwan’s Taiex or the Nasdaq, choose the same observation window and clearly state whether figures are measured in local currency or dollars. Look at index sector weights and market breadth, not simply at a sensational one-day percentage. For an American investor, foreign-market trading hours and fund tracking error also complicate any quick “buy the dip” narrative.
Three comparisons KOSPI commentary should not mix
First, a single-session decline measures the change from yesterday’s close, not the loss from a peak. Second, a drawdown from the year’s high measures market turbulence even if the year-to-date return stays positive. Third, an unhedged foreign investor’s return includes the Korean won against the investor’s home currency. The three numbers can point in different directions without contradiction.
The October 12 Barron’s chip coverage highlights why semiconductor movements deserve separate treatment. Do not infer exact index performance from the percentage declines of two chipmakers.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Why does KOSPI move when AI chips move? Large South Korean technology and memory-chip companies have a significant influence on the index.
Can an index decline while remaining up for the year? Yes; the result depends on the starting point and the comparison period.
Why the KOSPI is not simply a technology index
The Korea Composite Stock Price Index tracks a broad share market, but its largest constituents can make semiconductor news disproportionately important. Changes in expectations for memory-chip prices, AI servers and electronics demand can therefore move the benchmark even when many other domestic businesses are relatively stable. Investors should distinguish an index-weighting effect from evidence that every Korean company is experiencing the same change. A semiconductor downturn may hurt export earnings while benefiting downstream buyers from lower component costs.
South Korea also has globally connected manufacturing companies in automobiles, batteries, chemicals, shipbuilding and industrial equipment. Domestic policy, currency trends and global trade conditions can influence those industries differently. An accurate KOSPI explainer identifies which sector is moving the index on a particular day and whether the move is broad or concentrated. It does not describe a drop in two heavyweight stocks as proof that the entire economy has entered a recession.
The role of memory chips and AI infrastructure
High-bandwidth memory, often discussed as HBM, supports demanding AI workloads by providing fast data movement near computing accelerators. Demand for HBM can benefit qualified suppliers, but profitability depends on manufacturing yields, product mix, competition and customer pricing. Traditional DRAM and NAND markets have different end uses and inventory cycles. Consequently, a headline saying “AI chip prices are rising” may be too broad to explain a specific company’s quarter. Investors should read product-level commentary rather than infer that every semiconductor shipment is equally profitable.
Semiconductor investment is cyclical. Producers commit to costly factories and equipment well before their output reaches the market. Strong prices may encourage capacity expansion; later, oversupply can compress margins. Conversely, constrained manufacturing capacity can support pricing for some products while limiting volume growth. Supply contracts and technical qualifications can smooth these fluctuations, but they do not eliminate them. A balanced market note includes both demand and the possibility of supply catching up.
Currency and foreign-investor flows
A U.S. investor buying a Korean equity fund has at least two kinds of exposure: share-price changes and the won-dollar exchange rate, unless the investment vehicle hedges currency. Imagine Korean shares rise 8% in local currency while the won weakens against the dollar. The dollar return can be lower than 8%; if the currency move is sufficiently large, the investor could lose money in dollars despite positive local share performance. Conversely, won appreciation can amplify a local gain. Actual fund returns also reflect fees and tracking differences.
Foreign investors may shift exposure because of global interest rates, geopolitical developments or a change in the perceived risk of Asian hardware companies. Those flows can intensify short-term price moves. They are not evidence of a permanent change in Korea’s long-run technological position. Readers should use closing data in the correct time zone and avoid comparing Seoul’s closing prices with a U.S. market snapshot several hours later as if the observations were simultaneous.
A five-indicator KOSPI dashboard
Track the index’s performance both year to date and from its recent peak; those windows answer different questions. Review market breadth to see whether small and medium-sized companies are sharing the move. Compare major semiconductor companies’ operating outlooks, particularly memory product mix and capacity plans. Note the won-dollar rate and the direction of foreign-investor flows. Finally, monitor relevant global AI capital-spending announcements—but distinguish an announced customer budget from actual Korean supplier orders.
For long-term investors, the right comparison may be a diversified Asian equity portfolio rather than an individual semiconductor name. Country, sector and currency concentration can compound one another. A fund that appears to provide “international diversification” may still be heavily exposed to the global technology investment cycle. Review the fund’s holdings and benchmark methodology rather than relying on the label alone.
What the index cannot tell you
A sharp daily selloff is a price signal, not a direct measurement of factory production, employment or household welfare. Nor does a strong rally guarantee that companies will meet aggressive earnings expectations. The meaningful question is whether the latest market price embeds assumptions about AI demand, semiconductor margins and currency conditions that remain plausible. Different investors will answer that question differently depending on horizon and tolerance for losses.
For a useful daily update, record the exact KOSPI close, its point and percentage change, the date in Korea, and the principal named contributors. Without that basic timestamp discipline, even an otherwise informed global-market article can unintentionally misstate what happened.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
CoreWeave shares have become a direct test of how investors value artificial-intelligence infrastructure when the cost of capital rises. An October 14 Reuters report described a severe selloff across AI-related stocks after unexpectedly strong U.S. inflation data and singled out CoreWeave’s financing exposure. The central investing question is not whether AI demand exists. It is whether the company’s contracted demand, operating cash generation and available funding can support the speed and cost of construction implied by its expansion plans. For primary-source background, consult Reuters October 14 AI selloff; Financial Times CoreWeave funding; CoreWeave investor relations. In a fast-moving topic, publication time and information cutoff matter: subsequent events may require updating the figures or legal status, not merely changing the date in the footer.
What triggered the latest CoreWeave attention
The October inflation surprise raised investors’ expectations for interest rates and the price of financing long-duration projects. Reuters reported sharp declines in AI-infrastructure names, including CoreWeave, during the October 14 session. A one-day stock move is an observed price reaction, not evidence that its customers have canceled contracts. But the selloff makes funding structure newly important. Businesses that must invest cash today to earn revenue over years are highly sensitive to financing rates, payment schedules and equipment-value assumptions. Investors should confirm the trading session, percentage return and share class from an exchange or market-data service before republishing a price snapshot.
CoreWeave shares have become a direct test of how investors value artificial-intelligence infrastructure when the cost of capital rises.
Why AI infrastructure differs from an ordinary software company
CoreWeave supplies compute infrastructure, including GPU-intensive capacity used for AI workloads. Unlike a software business that can sell more subscriptions with limited marginal hardware investment, a compute provider may need expensive servers, electricity arrangements, networking, cooling systems and leases before customer revenue arrives. This can create a timing mismatch between contracted demand and free cash flow. Contract backlog can indicate future business, but it should never be substituted for cash already received. Terms for delivery, termination, prepayments and customer concentration can matter as much as the top-line headline number.
Debt, leases and the financing sensitivity
The Financial Times described CoreWeave seeking institutional financing for a large infrastructure build-out. Debt and lease obligations create fixed or contractual costs even when equipment utilization fluctuates. Investors should distinguish balance-sheet borrowings, lease liabilities, securitized equipment financing and contingent commitments; simplistic claims that all financing is identical distort risk. The cost of debt can rise sharply if lenders demand more compensation for uncertainty. At the same time, long-duration enterprise contracts can reduce revenue uncertainty. A sensible analysis weighs both sides and studies repayment schedules rather than judging the company by one leverage ratio.
Demand quality and customer concentration
AI companies and enterprise customers can require substantial compute, but customer contracts differ in reliability and profitability. A long agreement with a strong counterparty may support asset-backed financing more effectively than several short contracts with uncertain collection. Yet dependence on a few large buyers creates negotiating power and renewal risks. Look for disclosure about remaining performance obligations, revenue recognition, prepayments, utilization and customer concentration. An impressive backlog can coincide with negative free cash flow because building the capacity to fulfill those obligations is costly. The investment case strengthens only when large demand translates into economic returns after depreciation, interest and maintenance.
What valuation methods tell different stories
Price-to-sales ratios focus on revenue growth but ignore the cost required to deliver it. Enterprise value to EBITDA can obscure heavy capital replacement costs if depreciation is particularly meaningful. Free cash flow, measured consistently, makes investment intensity visible but may temporarily penalize a fast-growing construction phase. No single metric is decisive. Compare the company with infrastructure providers facing similar capital needs rather than only with asset-light software companies. Then stress-test outcomes under higher borrowing rates, slower installations, lower GPU pricing and changes in customer demand. These are scenarios, not assertions about what management will do.
Worked example: how to interpret a difficult headline
Imagine two AI-cloud projects with identical contracted revenue. Project A finances infrastructure at a lower fixed rate and launches on time; Project B faces a financing reset, a construction delay and higher electricity costs. The revenue headline may look the same, but cash generation and equity value could differ considerably. This is why debt maturity, deployment timing and customer collection are better questions than the size of an announced deal alone. This is a deliberately illustrative comparison unless explicit documented numbers are identified. It should not be mistaken for a real person’s financial circumstances, an unverified event, or a guaranteed forecast. Its purpose is to show how a reader can apply the underlying principle and identify which information still needs to be checked.
Three concepts that are often confused
| Concept | What it actually establishes |
|---|---|
| Revenue growth | Describes delivered services; does not equal net cash generation. |
| Backlog or contract value | Indicates potential future work subject to conditions and timing. |
| Cash flow after capital spending | Tests whether expansion economics can sustain funding obligations. |
These distinctions are more than technical niceties. They change the answer to the reader’s question. An estimate does not carry the same evidentiary weight as a final rule; an announcement does not have the same practical consequence as a completed transaction; and a provisional interpretation should not be presented as a confirmed event. Wherever a live source supplies a new fact, the editor should check whether the old text still describes the right stage of the process.
A reader’s verification workflow
Start by recording the precise claim and the date it was allegedly true. Open the primary announcement or filing rather than a social-media screenshot. Ask whether the source has an incentive to present only the most favorable interpretation, and corroborate material facts with reputable independent reporting where available. For numerical claims, note the denominator, timeframe and whether the number is a stock, a flow, a forecast or a realized result. For legal claims, note the court, agency, stage of proceedings and exact published document.
Next, separate information useful for immediate decisions from context that merely explains the headline. A person may need to act on a deadline even when the long-run political debate remains unresolved. Someone evaluating a security may need financing details, while a customer comparing technology products needs a tested specification and local warranty terms. The same headline can matter for different reasons; the article should therefore provide an actionable answer without implying that every reader faces the same circumstances.
Indicators and developments worth monitoring
- Company quarterly financial filings and debt footnotes.
- Interest rates and spreads on financing vehicles.
- Capacity construction and customer-service activation.
- New customer agreements and changes in utilization.
Avoid treating these signals as a checklist that mechanically predicts the future. Some are leading indications and others are lagging measurements. A change becomes significant only after its magnitude, source and comparison period are understood. If two reputable sources disagree, explain the source of the difference—definitions, timing, jurisdiction, measurement or uncertainty—instead of selecting whichever number makes the strongest headline. That practice strengthens both reader trust and the article’s usefulness in search features that surface isolated paragraphs.
The specific information advantage of this article
Growth forecasts grab attention but often hide the cost of building the revenue-generating assets. Treat contract backlog and installed capacity as distinct measures, then compare them with borrowing needs, lease liabilities and cash returns. This is the difference between an AI-demand story and a credible investment-risk story.
Frequently asked questions
Is CoreWeave stock the same as buying Nvidia?
No. CoreWeave operates compute infrastructure with financing and customer risks unlike a semiconductor designer. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Why did rising rates matter?
More expensive capital can reduce the present value of future cash flows and make funding new servers costlier. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does backlog guarantee profit?
No. Contracts must be fulfilled, and expenses, financing and accounting recognition determine profitability. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
What is the biggest unresolved question?
Whether contracted capacity can generate durable cash returns after equipment, power and financing costs. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Bottom line
CoreWeave shares have become a direct test of how investors value artificial-intelligence infrastructure when the cost of capital rises. An October 14 Reuters report described a severe selloff across AI-related stocks after unexpectedly strong U.S. inflation data and singled out CoreWeave’s financing exposure. The central investing question is not whether AI demand exists. It is whether the company’s contracted demand, operating cash generation and available funding can support the speed and cost of construction implied by its expansion plans. The best next step is to identify which of the monitored developments could change this answer and use a current, authenticated record before acting. Clear distinctions between confirmed facts, estimates, proposals and contested claims are more valuable than dramatic certainty.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Markets & Finance
Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices
The Strait of Hormuz connects Persian Gulf exporters with global sea routes, making uncertainty around maritime passage a global cost issue. Recent October 2026 reporting linked Middle East tensions with elevated energy prices. That is a reason to analyze shipping risk; it is not evidence that every reported confrontation caused an enduring closure of the waterway. Sources: Associated Press energy coverage and International Monetary Fund.
The important context competitors can overlook
The transmission mechanism runs through multiple channels: cargo delays, tanker insurance, longer voyages, available ships, refinery feedstock and energy prices. Diesel, jet fuel and petrochemicals may respond differently. High transport costs can also affect importers that do not buy oil directly from the Gulf because global fleets and commodity prices are interconnected. For primary-source checks and current reporting, see Associated Press energy coverage and World Trade Organization. The key distinction is explain chokepoint transmission without predicting incidents.
Hormuz shipping risk can raise costs even without a sustained closure. Distinguish maritime warnings from confirmed supply interruptions. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
When covering an incident, check time, coordinates, vessel identity and independent verification. Distinguish a threat, a temporary diversion, a passage restriction and a sustained closure. For readers, show how businesses might respond with inventory buffers, alternative suppliers or freight surcharges, but avoid quoting a precise inflation impact without a defensible model.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Why is Hormuz important beyond crude oil?
Refined-fuel supply chains, ship insurance and freight costs can spread impacts across industries.
Is a shipping incident proof the strait is closed?
No. Specific passage restrictions require separate verification.
Why the geography creates outsized economic exposure
The Strait of Hormuz is a maritime passage connecting the Persian Gulf with the Gulf of Oman and onward sea routes. Energy producers, importers, ship operators and insurers pay attention because a disruption in a narrow passage can affect many cargoes at once. Its importance does not require the claim that the strait has been closed. Even elevated uncertainty can change how shipowners price voyages or how refiners plan inventories. The actual effect depends on severity, duration, geography and whether commercial vessels can continue operating safely.
Not every barrel that leaves a Gulf producer has exactly the same destination or transport option. Some infrastructure can reduce reliance on particular routes, but it does not imply that all cargoes have an easy substitute path. The availability of alternatives depends on product type, pipeline and port capacity, contracts and political circumstances. Articles should avoid unverified claims about the share of all world oil that travels through the waterway without citing a dated primary-energy assessment.
The difference between a threat and a closure
A reported warning, a temporary security incident, a route diversion and a sustained interruption are materially different events. An isolated confrontation may raise perceived risk without stopping most commercial traffic. A major insurance repricing can occur even when vessels continue sailing. Conversely, a prolonged interruption could reduce shipments and force changes in procurement. Journalists should establish what is confirmed, including location, time, vessel identities, official notices and independent maritime evidence, before describing an incident as a shipping blockade.
Vessel-tracking displays are useful but imperfect. Ships can have delayed reporting, technical gaps or intentionally limited signals. One missing tracking point is not proof that a tanker was seized or attacked. When incident claims circulate, prioritize corroboration from shipping operators, maritime authorities and credible reporting. Time-zone conversion and ship-name accuracy are important because a single voyage may appear under different timestamps in public databases.
Insurance, freight rates and refinery feedstock
Ship operators may face higher war-risk premiums, charter rates or security costs when a route becomes dangerous. Those costs can be passed into freight contracts depending on commercial terms. A longer journey uses ship capacity for more days and can tighten fleet availability beyond the immediate route. Refineries may also pay more for feedstock or seek substitute grades if usual supply becomes uncertain. All of these adjustments can change delivered costs before any final consumer-price effect is visible.
Energy markets also distinguish crude oil, refined diesel, gasoline, aviation fuel and liquefied natural gas. Cargo routes and supply buffers are not identical. A single oil futures chart therefore cannot measure the exposure of every importing country. A chemical manufacturer worried about feedstock, an airline worried about jet fuel and a utility worried about gas supplies may need separate analysis despite sharing concern about the same shipping region.
How the shock might reach household budgets
The transmission path can run from transport disruption to higher wholesale energy prices, then to logistics, manufacturing and certain retail costs. The size and speed of pass-through depend on inventories, contracts, taxes, domestic competition and currency values. Import-dependent countries may feel a stronger immediate effect than producers with ample domestic supply, but outcomes are not uniform. Central banks may monitor whether energy volatility changes inflation expectations; that does not establish an automatic interest-rate response.
Food prices can be affected indirectly through agricultural fuel, fertilizer and freight, yet blaming a given grocery-price change on Hormuz requires evidence. Weather, local production and retail competition also matter. An explanatory article should trace the mechanism without claiming a precise household inflation effect when no suitable model or data is available.
A practical risk dashboard
Track verified maritime advisories, commercial-traffic continuity, freight and insurance developments, crude and product benchmarks, inventory data and the relevant government’s policy response. Mark each indicator with a date and distinguish confirmed conditions from forecasts. For a business importing critical inputs, the operational questions include alternate suppliers, shipment buffers and exposure under freight contracts. For households, generalized resilience may involve budgeting for energy volatility rather than reacting to unverified predictions of imminent shortages.
The central lesson is proportionality: a narrow maritime passage can create global risk without every tense incident automatically becoming a global supply shutdown. The article should reflect that difference every time a new headline arrives.
Hormuz risk scenarios and the evidence each requires
A temporary maritime warning: Confirm the issuing authority, geographic scope and duration. Such a warning can raise concern without stopping ordinary passage. Report what commercial operators are actually doing, rather than treating a warning itself as proof that all shipping has ceased.
A measurable freight-cost increase: Obtain a dated freight or insurance measure and establish whether the movement is linked to the relevant route. Shipping prices also respond to global fleet supply, fuel costs and seasonal trade, so a single increase may have multiple causes. Explain whether the quoted charge applies per ship, cargo value or voyage.
A prolonged physical disruption: Verify evidence of sustained passage restrictions and the duration. Consider inventory buffers, substitute routes, refinery demand and government responses before estimating economic effects. A hypothetical supply-loss scenario can help readers understand risk, but must be labeled clearly and not reported as an observed event.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

SpaceX IPO 2026: History’s Biggest Stock Debut?
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025