
Energy Economy
Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

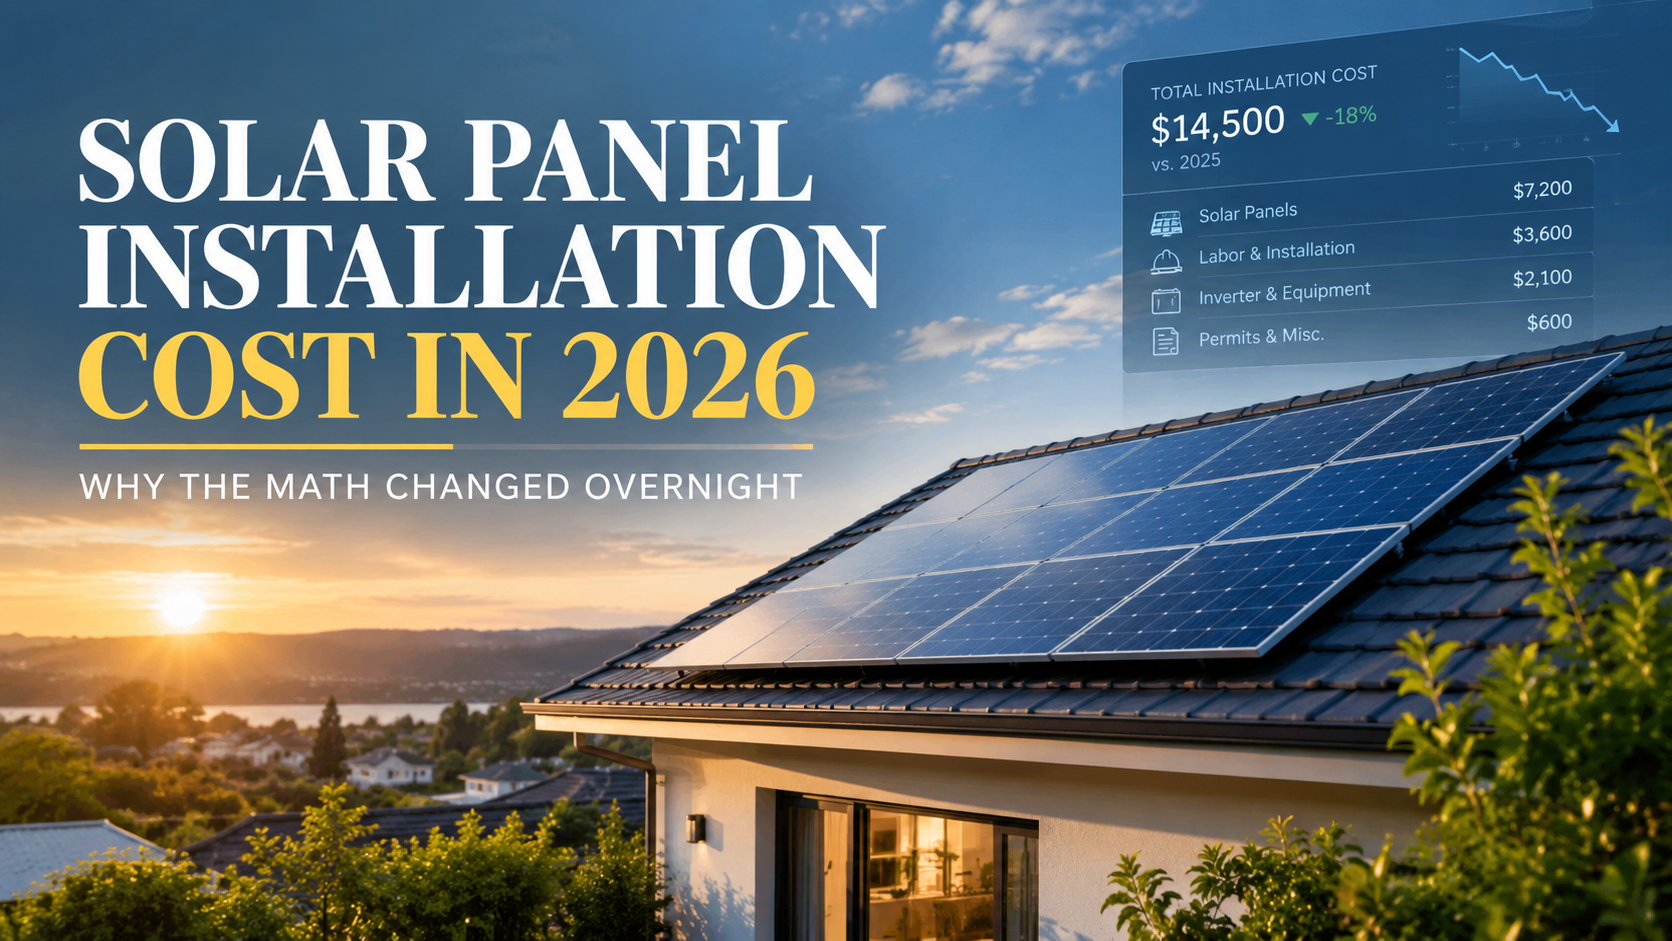
The 30% federal solar tax credit that made rooftop solar affordable for millions of American homeowners is gone. It isn’t phasing out, and it wasn’t reduced—it was abruptly terminated for anyone who didn’t have a residential system installed, inspected, and placed in service by December 31, 2025.
Solar panel installation has always required careful math, but 2026 marks the first year homeowners are shopping for solar entirely without the safety net of the federal Investment Tax Credit (Section 25D). With the passage of the One Big Beautiful Bill Act (OBBBA), the industry’s primary affordability pitch for the last two decades has been stripped away.
Understanding the real, un-subsidized price of a system—and which alternative incentives still apply where you live—is now the single most important step before signing a contract.
Here is what solar panels actually cost in 2026 without the federal credit, how the “third-party loophole” is changing the market, and how to evaluate a solar quote in this new landscape.
How Solar Pricing Actually Works in 2026
The core pricing unit in the solar industry is cost per watt (installed). When multiplied by your system’s size in watts, this gives you the gross project cost before any remaining state or local incentives are applied.
Key Policy Shift: The Residential Clean Energy Credit (Section 25D) was terminated for systems placed in service after December 31, 2025, under the OBBBA, with no phase-down period. This accelerated the credit’s originally planned 2034 expiration by nearly a decade. (Note: If you installed a system in 2025 and have unused credit, you can still carry it forward to reduce your 2026 tax liability).
What a Solar Quote Actually Includes
- Solar Panels: Typically 25% to 35% of total installed cost, varying by panel efficiency and brand tier.
- Inverter(s): Converts DC power from panels to usable AC power; a meaningful cost and reliability factor.
- Mounting & Racking: The structural and electrical components securing panels to your roof.
- Permits & Interconnection: Required paperwork and utility inspections that vary heavily by municipality.
- Labor & Soft Costs: Customer acquisition, overhead, and installation labor. With hardware costs bottoming out, soft costs now make up 50% to 65% of total project expenses.
- Battery Storage (Optional): Adding a home battery typically adds $8,000 to $15,000 to the installed cost, though it is increasingly necessary in states with volatile grid reliability.
Financial Realities: What Solar Costs Without the Federal Credit
Understanding current gross pricing—without assuming a federal credit that no longer exists for new residential installations—is essential for realistic budgeting.
| System Size | Gross Installed Cost Range (2026) | Estimated Cost Per Watt |
| 5 kW | $12,500 – $17,500 | ~$2.50 – $3.50 |
| 8 kW | $20,000 – $28,000 | ~$2.50 – $3.50 |
| 10 kW | $25,000 – $35,000 | ~$2.50 – $3.50 |
| 15 kW | $37,500 – $52,500 | ~$2.50 – $3.50 |
Figures reflect gross cost before any state, local, or utility incentives. The federal 30% residential tax credit no longer applies.
Industry Insight: In 2025, U.S. homeowners claimed billions in federal tax credits. Without it, analysts project a 20% to 30% drop in residential direct-purchases in 2026 as the true, un-subsidized cost becomes the new baseline.
The “Loophole”: Third-Party Leases and PPAs
While homeowners buying systems with cash or standard loans are locked out of federal credits, there is a major caveat driving the 2026 market.
Homeowners who choose a third-party lease or Power Purchase Agreement (PPA) can still access savings. Under these models, the solar company technically owns the equipment, allowing them to claim the commercial clean energy tax credit (Section 48E), which survived the OBBBA cuts.
The leasing company can, in principle, pass those tax savings through to the homeowner via lower monthly rates. However, the value of that pass-through varies significantly by provider. Contracts must be scrutinized carefully to ensure the savings are actually reaching you.
How to Evaluate a Quote in the Post-Credit Era
- Check for “Phantom Credits”: Every solar cost calculator, payback estimate, or sales pitch you encounter should be checked against a single question: Does this figure still assume the 30% federal tax credit? Many outdated online resources and aggressive sales materials have not yet been updated.
- Verify State and Local Incentives: Do not rely solely on installer claims. Program availability varies wildly by state and now carries the primary weight of your ROI.
- Compare Cost Per Watt: Always evaluate cost per watt across quotes for similarly sized systems. A lower total price on a smaller system doesn’t necessarily represent better value.
- Model a Realistic Payback Period: Model your break-even timeline using current, un-subsidized pricing. Older payback estimates built around the expired 30% credit will severely understate how long it takes to recoup your investment.
- Understand Your Net Metering Policy: How your utility compensates you for excess solar production significantly affects the ongoing value of your system, sometimes mattering just as much as the upfront installation cost.
Future Outlook: Trends Through 2027
- Market Contraction & Stabilization: Installation volume will likely decline in the near term as consumer sticker shock sets in, before stabilizing at a new, lower baseline demand level.
- The Rise of PPAs: Because of the commercial tax credit loophole, third-party ownership models will likely dominate the residential market over direct cash or loan purchases.
- State Programs Take the Wheel: Expect massive migration of solar development to states that maintain strong local incentive programs and favorable net metering laws.
- Battery Attach Rates Will Climb: Despite higher overall costs, grid instability and unfavorable time-of-use rates will continue pushing homeowners to bundle battery storage with their solar panels.
Frequently Asked Questions
Is the federal solar tax credit still available in 2026?
No, not for homeowner-owned residential systems. The 30% Residential Clean Energy Credit (Section 25D) was terminated for systems placed in service after December 31, 2025, under the OBBBA. However, unused credits generated from a 2025 installation can be carried forward into 2026.
How much does a solar panel installation cost in 2026 without the tax credit?
A typical residential system costs $2.50 to $3.50 per watt installed before any remaining state or local incentives. This means an average 8 kW system runs roughly $20,000 to $28,000 gross.
Can I still get any tax benefit from going solar in 2026?
While direct purchases no longer qualify for the federal residential credit, you can opt for a third-party lease or PPA. Because the solar company owns the system, they can claim the related commercial tax credit (Section 48E) and potentially pass those savings on to you through lower energy rates.
Why did the federal solar tax credit end so abruptly?
The One Big Beautiful Bill Act, signed into law in July 2025, terminated the residential credit effective December 31, 2025, accelerating what was originally scheduled as a gradual phase-out ending in 2034.
Should I still get multiple solar quotes even without the federal credit?
Yes, arguably more than ever. Prices commonly vary 20% to 40% between installers for functionally identical systems. With the federal subsidy gone, locking in a competitive baseline price is the only way to ensure a reasonable payback period.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Analysis
Singapore’s Growth Beat Hides a Harder Question: Can MAS Keep Tightening Into a War-Driven Inflation Shock?
Singapore’s economy grew 5.7% year-on-year in Q2 2026, beating consensus forecasts of 5.5% but decelerating from Q1’s revised 6.3% pace. Manufacturing, powered by an AI-related semiconductor “supercycle,” was the standout driver. The deceleration, however, arrives just as the Monetary Authority of Singapore prepares a policy decision complicated by rising inflation risk tied to the Iran conflict.
The Headline Numbers
Singapore’s Ministry of Trade and Industry reported advance Q2 2026 GDP growth of 5.7% year-on-year, ahead of the 5.5% Reuters consensus but down from a revised 6.3% in Q1 (IBTimes Singapore). On a quarter-on-quarter seasonally adjusted basis, GDP rose 1.1%, following 1.3% growth in Q1. Manufacturing expanded 12.2% year-on-year, up sharply from 8.0% in the prior quarter and the clearest evidence yet of how central Singapore has become to the global AI hardware supply chain (CNBC).
Forecasters have responded by upgrading their outlooks. UOB Global Economics and Markets Research raised its full-year 2026 GDP forecast to 4.8% from 4%, citing sustained AI-related demand, while Nomura pointed to a broadening “semiconductor super cycle” as a key driver of upside risk to its own 4.6% forecast (Xinhua).
The MAS Dilemma
Singapore does not set monetary policy through interest rates but by managing the Singapore dollar’s trading band against a basket of currencies — the S$NEER framework. In April 2026, MAS raised the rate of appreciation of that band, tightening policy in response to inflation risk tied to the Iran conflict, and simultaneously raised its 2026 inflation forecast range to 1.5–2.5%, up from 1.0–2.0% (IBTimes Singapore).
The central bank’s next policy review, due before the end of July, arrives at an awkward moment: growth is decelerating from its Q1 peak even as inflation risk from the Gulf conflict remains elevated. CPI inflation held at 1.8% in May 2026, its joint-highest reading since September 2024 (CNBC).
A Region Serving as Shipping’s Overflow Valve
One underreported dimension of Singapore’s exposure to the Hormuz conflict: the city-state has seen increased vessel traffic as ships reroute around Africa or use Singapore as a stopover hub for displaced shipping, according to the Monetary Authority of Singapore’s own macroeconomic review (MAS Macroeconomic Review, April 2026). This gives Singapore a curious dual exposure to the conflict: it benefits from increased logistics and trans-shipment activity even as it absorbs higher energy import costs.
Growth Forecast Range Holds — For Now
The Ministry of Trade and Industry has maintained its official 2026 growth forecast at 2.0–4.0%, explicitly citing elevated downside risk from the US-Israel-Iran conflict even as it acknowledges that actual growth has been tracking well above that range in the first half of the year (MTI). That gap between the official forecast band and independent economists’ more bullish revisions reflects genuine uncertainty about how durable the AI-driven manufacturing boom will prove if geopolitical risk intensifies again.
Why This Matters for Global AI Supply Chains
Singapore’s position at the center of the “semiconductor supercycle” narrative connects directly to the broader AI chip investment story unfolding in the US and China (see our companion coverage). As a hub for both electronics manufacturing and financial services, Singapore’s growth trajectory functions as a leading indicator for global AI hardware demand more broadly.
Key Takeaways
- Singapore’s Q2 2026 GDP grew 5.7% year-on-year, beating forecasts but decelerating from Q1, driven by a 12.2% surge in manufacturing output.
- MAS tightened monetary policy in April 2026 specifically in response to Iran-conflict-linked inflation risk, and faces a delicate policy call later this month.
- Singapore has a dual exposure to the Hormuz conflict — benefiting from rerouted shipping traffic while absorbing higher energy costs.
- Independent forecasters have raised 2026 growth estimates to as high as 4.8%, well above the MTI’s official 2.0–4.0% range.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
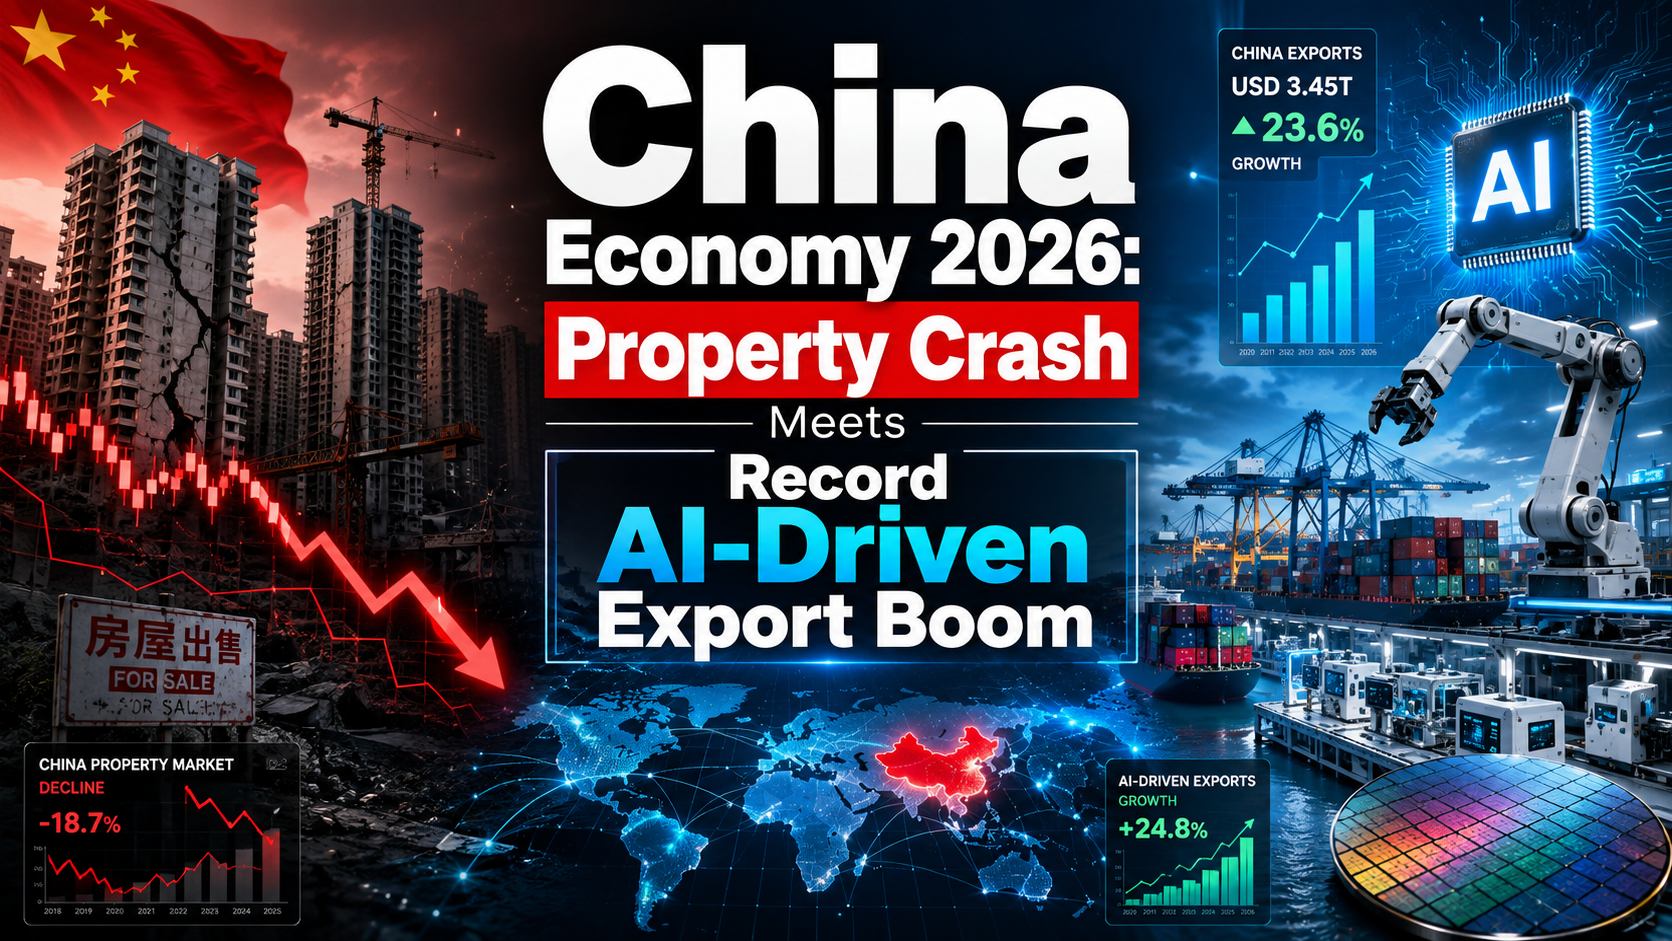
China’s economy is being pulled in two directions at once. Fixed-asset investment fell 4.1% year-on-year in the first five months of 2026 — the steepest decline since May 2020 — while exports surged 19.6% in May alone, powered overwhelmingly by semiconductor and AI-hardware demand, according to Deloitte’s Weekly Global Economic Update.
The Property Sector’s Deepening Slide
Property investment within that fixed-asset figure fell 16.2% year-on-year, the sharpest drop recorded in the current downturn. Roughly two-thirds of Chinese household wealth is held in property, so the sustained decline in home values is pushing consumers toward higher savings and lower spending as they attempt to rebuild balance sheets, per Deloitte’s analysis from chief global economist Ira Kalish. Government efforts to stabilize the housing market have so far failed to reverse the trend, with the excess capacity built during the prior debt-fueled construction boom still working through the system.
Exports Riding the Global AI Supercycle
The export side of the ledger tells a starkly different story. Semiconductor exports rose 110% year-on-year in May, mobile phone exports climbed 44%, and exports of automatic data-processing machines — the category covering computer and data-storage components — increased 66%. The May export growth of 19.6% was the second-largest year-on-year increase since January 2022, trailing only the 39.6% surge recorded in January–February 2026. Part of that strength reflects inventory build-up by global buyers anticipating further supply-chain disruption from the ongoing Middle East conflict.
Tariff Investigations Add a New Layer of Risk
Even as exports boom, the trade environment China and its partners face is becoming more adversarial. The US administration has launched an investigation into 60 countries — including the European Union — to determine whether they are importing goods made with forced labor, with the goal of imposing tariffs ranging from 10% to 12.5%. The move sets the stage for renewed friction even after the US and EU reached a trade agreement approved by the European Parliament the previous year, according to Deloitte’s tracking of the administration’s tariff strategy.
The China-Russia Financial Relationship Under New Strain
China’s export strength has not shielded it from secondary pressure tied to its economic relationship with Russia. US Treasury sanctions actions have begun targeting cross-border payment channels between Russian and Chinese entities used to facilitate sensitive-goods transactions, and Chinese banks have reportedly started refusing payments from Russian counterparties amid the threat of US secondary sanctions, according to CEPA’s analysis of the sanctions squeeze. China has supplied more than 90% of Russia’s semiconductor imports since the Ukraine war began, per CSIS’s research on sanctions reshaping Russia’s economy, making Beijing’s compliance posture a critical swing factor for Moscow’s continued access to Western-branded technology.
What It Means for the Regional Outlook
Asia House projects China’s growth easing modestly from 4.8% in 2025 to 4.6% in 2026, a relatively soft landing given the scale of tariffs imposed on Chinese exports, reflecting redirected trade flows toward Asian and European markets and a weaker real effective exchange rate, according to Asia House’s Annual Outlook. For ASEAN economies plugged into China’s supply chains — Malaysia and Vietnam in particular — the divergence between China’s property drag and export strength will remain a key variable shaping regional growth through the rest of 2026.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Russia’s federal budget collected less revenue in 2025 than originally planned for the first time since the pandemic, a shortfall that has pushed the Kremlin to raise its value-added tax rate from 20% to 22% starting January 1 and pull far more small businesses into the VAT system, according to The Moscow Times’ assessment of the country’s 2026 fiscal trajectory.
The Oil Money Is Drying Up
The core of Russia’s budget problem is straightforward: oil and gas revenue, the traditional backbone of Kremlin finances, has fallen by more than 25% as a stronger ruble and tightening Western sanctions squeeze what Moscow can earn from crude exports, according to the New Eurasian Strategies Centre’s analysis. When the 2025 budget was set, revenues were projected at 40.3 trillion rubles; updated forecasts now suggest actual collections closer to 36.6 trillion rubles, a gap of roughly $46 billion at current exchange rates, per The Moscow Times.
The World Bank expects a global oil supply surplus to push Brent crude prices down from an average of $68 a barrel in 2025 to around $60 in 2026, the lowest level in five years, further squeezing the discount Russia must already offer buyers willing to purchase sanctioned crude. With GDP estimated at 217.3 trillion rubles in 2025, total defense spending of around 15.86 trillion rubles, more than $198 billion, now represents a share of the economy that leaves little room for the civilian investment that might otherwise support long-term growth, The Moscow Times reports.
A Central Bank Fighting Inflation on Its Own
Against this fiscal backdrop, the Bank of Russia has pursued an unusually consistent disinflation campaign under Governor Elvira Nabiullina, cutting its key rate eight consecutive times from a record 21% last June down to 14.25% by its June 2026 decision, according to the central bank’s own rate announcement. That June cut of just 25 basis points came in below the market’s median expectation of a 50-basis-point reduction, with the central bank citing persistent pro-inflationary risks tied to higher energy prices from the Middle East war, refinery damage from Ukrainian strikes, and wage growth that continues to outpace productivity, per Trading Economics’ tracking of the decisions.
Annual inflation stood at 5.6% as of mid-June, still well above the Bank of Russia’s 4% target, though down meaningfully from the 9.5% rate recorded in 2025, according to the central bank’s own data. The Moscow Times’ longer analysis of the anti-inflation campaign notes that Russia’s consumer price index rose 39% across the four full wartime years from 2022 to 2025, compared with 61% in Ukraine over the same period, and a staggering 200%-plus in Iran, framing Nabiullina’s inflation-targeting approach as unusually disciplined by wartime standards, per The Moscow Times’ longer profile of the policy.
The Cost of That Discipline
That discipline has not come free. The New Eurasian Strategies Centre describes Russia as moving through the final phase of a familiar economic cycle: downturn, fiscal stimulus, inflation, interest rate rises, downturn again, disinflation, rate cuts, and eventually recovery, a sequence the think tank says has suppressed economic activity across many sectors as interest-rate pressure compounds the drag from sanctions and wartime resource reallocation, according to its analysis of key rate dynamics. Growth forecasts for both 2025 and 2026 now cluster around just 1%, according to Russia’s own Economic Forecasting Institute and the IMF alike, a marked slowdown from the wartime stimulus-driven expansion of earlier years.
A potential end to the war in Ukraine, paradoxically, could increase short-term recession risk by reducing output in defense-related industries and lowering household incomes tied to military production, the New Eurasian Strategies Centre’s analysis notes, underscoring how deeply the war economy has become embedded in Russia’s growth model.
New Taxes on Everything From Laptops to Small Firms
Beyond the VAT increase, Russian authorities are lowering the annual revenue threshold for mandatory VAT registration from 60 million rubles to just 10 million rubles, sweeping far more small and medium-sized enterprises into the tax system, according to The Moscow Times’ January analysis. The government also plans a new levy on finished electronic goods including laptops, smartphones, and lighting products. The head of Russia’s New People party has publicly warned that lowering the VAT threshold will disproportionately hit small and medium-sized enterprises in the regions, according to reporting cited in the same Moscow Times analysis, a rare instance of intra-establishment pushback on fiscal policy.
What to Watch Next
The Bank of Russia’s next key rate decision falls on July 24, with a summary of the prior meeting’s discussion published July 1, according to the central bank’s own communications calendar. Nabiullina has reaffirmed that inflation should return to the 4% target sometime in 2026, a view broadly shared by Prime Minister Mikhail Mishustin and Finance Minister Anton Siluanov, though The Moscow Times notes that even Defense Minister Andrei Belousov has, with some reservations, supported the anti-inflation policy, a rare point of consensus across an otherwise divided Russian economic leadership. Whether that consensus survives a second consecutive year of budget shortfalls and rising consumer taxes is the question shaping Russia’s economic trajectory through the remainder of 2026.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Apply for a Bank Account Online: What You Need and How Long It Actually Takes

World’s Largest Economies: Ranking the Top Global Powers

Business Loan: A Complete 2026 Guide to Rates, Types, and Qualifying

Fast Invoice Factoring: How to Turn Unpaid Invoices Into Cash Within 24 Hours

Investment Banking Services: What They Cost and How to Choose the Right Firm in 2026

Structured Settlement Loan: What “Cash Now” Offers Actually Cost You

DUI Attorney: Why Your First Call After an Arrest Should Never Be to the Court

Personal Injury Lawyer: A Complete Guide to Filing Your Claim in 2026

Commercial Vehicle Accident Lawyer: Holding Companies Accountable Beyond the Driver

Inside the White House Feud: How Trump’s Allies Are Painting Anthropic’s Dario Amodei as the Face of ‘AI Doomerism’

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025