
Industory
Musk’s SpaceX Lines Up Retail Investors for Record IPO Allocation

For nearly two decades, the world’s most valuable private aerospace corporation operated as an exclusive playground for sovereign wealth funds, high-net-worth family offices, and elite venture capital consortiums. Regular retail investors looking for a piece of the cosmos were left staring from behind the velvet rope, watching employee tender offers pass them by.
That architecture is now cracking open. Internal planning documents circulating through top-tier Manhattan brokerages reveal that Elon Musk is preparing a structural shift that could democratize access to private equity. SpaceX is actively designing a specialized mechanism to reserve a record-breaking slice of an upcoming public carve-out for regular retail accounts.
This isn’t merely an expansion of the investor base. It is a calculated restructuring of modern corporate finance that rewrites how retail investor stock access is handled during generational market listings.
The Macro Capital Matrix
The broader capital markets are undergoing a fundamental structural transition. For the past four years, restrictive monetary policy and fluctuating interest rates compressed traditional public market listings, forcing late-stage technology firms to rely on private secondary liquidity rounds.
Yet, the sheer capital requirements of deep-tech infrastructure do not obey standard macroeconomic cycles. Building a multi-planetary transport system and a global orbital internet network requires a constant pipeline of tens of billions of dollars.
+-----------------------------------------------------------------+
|                  SPACEX LIQUIDITY EVOLUTION                     |
+-----------------------------------------------------------------+
|                                                                 |
|  [Phase 1: Institutional Domination]                             |
|  Sovereign Wealth -> Elite VC -> Accredited Family Offices     |
|                                                                 |
|  [Phase 2: Closed Loop Liquidity]                               |
|  Internal Employee Tender Offers -> Restricted Secondary Blocks  |
|                                                                 |
|  [Phase 3: The Retail Paradigm Shift]                           |
|  Direct Retail Brokerage Allocations -> Structured Public Trust |
|                                                                 |
+-----------------------------------------------------------------+
As the commercial space market valuation climbs to unprecedented heights, the traditional avenues of institutional private placements are hitting structural allocation limits. By turning toward a broad-based public retail base, the enterprise is unlocking an insulated reservoir of capital that remains highly resilient to institutional macro-hedging trends.
SECTION 1 — The Core Development
The structural core of this initiative involves an unprecedented distribution network designed to route equity directly to non-accredited accounts. According to draft filings reviewed by financial analysts, the company plans to utilize a syndicated consortium of consumer-facing fintech brokerages to orchestrate the SpaceX retail IPO allocation.
Historically, initial public offerings allocate less than 10% of their primary shares to retail syndicates, reserving the lion’s share for institutional asset managers who promise long-term price stability. Musk’s proposed framework aims to flip this ratio, earmarking up to 35% of the initial share float directly for retail accounts.
The mechanics of this arrangement rely on a multi-tiered allocation engine. Rather than relying solely on traditional Wall Street investment banks like Goldman Sachs or Morgan Stanley to handle distribution, the company intends to plug directly into application programming interfaces of retail platforms.
A recent report by Bloomberg Technology Intelligence indicates that this digital architecture will allow retail users to pre-commit capital with zero asset-minimum constraints. This effectively bypasses the historic net-worth hurdles that have governed late-stage private equity access since the passage of the Securities Act of 1933.
The scale of this capital mobilization matches the company’s operational footprint. On March 12, 2026, internal communications indicated that the preliminary allocation framework could place up to $15 billion in equity directly into consumer portfolios during the opening week of trading.
Data compiled by Reuters Financial Markets shows that a retail distribution of this magnitude would shatter the previous record set during the 2014 Alibaba listing. It signals a major shift in how mega-cap issuers view the balance between institutional stability and retail capital depth.
Traditional IPO Allocation:
[Institutional: 90%] [Retail: 10%]

Proposed SpaceX Structural Allocation:
[Institutional: 65%] [Retail: 35%]
Still, executing a retail distribution at this scale requires immense technical coordination. The company’s internal treasury team has spent the last five months auditing secondary market platforms to understand how massive retail inflows impact day-one trading volatility.
The goal is to establish a synthetic lock-up period for retail participants, offering loyalty incentives like priority access to future capital raises for accounts that hold their shares longer than 180 days.
SECTION 2 — Analytical Layer
To understand the financial engineering behind this move, one must separate the parent company’s heavy manufacturing operations from its recurring revenue engines. The true target for this retail mobilization is almost certainly the long-anticipated Starlink public offering.
While the core Starship development facility in Boca Chica, Texas, operates as a capital-intensive research laboratory, the orbital satellite constellation has matured into a predictable, highly cash-generative utility.
How will the SpaceX retail IPO allocation work?
The SpaceX retail IPO allocation will distribute up to 35% of its public share float directly to non-accredited investors via partner digital brokerages. By utilizing algorithmic allocation engines, the system allows retail accounts to pre-commit capital without traditional net-worth minimums, creating an inclusive public equity distribution.
The financial logic of separating these two business units is clear. The orbital internet division requires massive upfront capital expenditures to launch its next-generation satellite arrays, yet it delivers high-margin subscription software metrics once operational.
By taking this division public via an inclusive retail structure, Musk can secure a lower cost of capital while avoiding the aggressive governance demands typically imposed by late-stage institutional private equity groups.
| Financial Metric | Core Aerospace Operations | Satellite Communications Arm |
| Primary Revenue Model | Government & Commercial Launch Contracts | Global Consumer & Enterprise Subscriptions |
| Capital Intensity | Extreme (Starship Infrastructure Development) | Moderate (Routine Constellation Maintenance) |
| Target Investor Profile | Sovereign Wealth & Long-Term Institutional | Broad Public Retail & Growth Equity Funds |
| Cash Flow Velocity | Cyclical (Milestone-Based Payments) | Linear (Monthly Recurring Subscriptions) |
This structural design acts as a shield against corporate intervention. Institutional asset managers often demand board seats, operational transparency, and strict adherence to quarterly guidance metrics.
A fragmented retail base, conversely, rarely votes as a unified bloc, leaving operational control completely in the hands of corporate insiders. For an executive who famously views public market reporting requirements as an unnecessary distraction, a highly distributed retail shareholder base is an ideal corporate governance structure.
What follows, however, is a complex regulatory balancing act. The Securities and Exchange Commission has historically looked askance at retail-heavy distributions for companies with complex capital architectures.
The regulatory body’s primary concern centers on information asymmetry. Wall Street institutions possess the analytical resources to model orbital degradation rates and launch cadence liabilities; regular retail investors often do not. The company must therefore construct an incredibly detailed prospectus that translates deep-tech engineering risk into understandable retail disclosures.
SECTION 3 — Implications & Second-Order Effects
The downstream consequences of this allocation strategy will ripple far beyond the aerospace industry. First, it will profoundly alter the broader commercial space market valuation landscape.
When a dominant sector leader opens an accessible capital pipe of this size, it inevitably drains liquidity away from smaller, pure-play public space ventures. Investors holding speculative positions in secondary launch services or orbital imaging startups may rapidly liquidate those holdings to reposition into a diversified aerospace powerhouse.
       [SpaceX Liquidity Accumulation]
                     |
         +-----------+-----------+
         |                       |
         v                       v
[Capital Flight from]   [Valuation Premium]
[Smaller Space Firms]   [for High-Margin IP]
Second, this move will redefine infrastructure financing mechanics across the entire technology sector. If SpaceX successfully raises tens of billions from everyday portfolios while maintaining absolute operational autonomy, other mega-cap private entities will quickly adopt the same playbook.
A detailed study on The Financial Times Markets Desk notes that this democratization of primary issuance could fundamentally disrupt the traditional investment banking fee structure. It minimizes the role of institutional market makers and positions consumer fintech apps as the new gatekeepers of primary capital distribution.
This shift will also accelerate the evolution of secondary market infrastructure. To prepare for the retail onslaught, major financial clearinghouses are upgrading their systems to handle unprecedented volumes of fractional-share settlement.
On May 18, 2026, industry working groups reported that clearing networks are modifying their risk protocols to prevent the kind of settlement backlogs that plagued retail brokerages during the high-volume trading spikes of the early 2020s. The injection of millions of retail accounts into a complex capital structure demands a more resilient settlement layer.
Traditional Settlement Pipeline:
Issuer -> Investment Bank -> Institutional Vaults -> Slow Retail Drip

Modernized API Distribution:
Issuer -> Digital Syndicate Engine -> Automated Fractional Clearing -> Instant Retail Portfolios
Still, the broader systemic impact rests on the long-term performance of the equity itself. If the constellation’s subscriber growth flattens or geopolitical tensions disrupt manufacturing supply lines, the financial damage will be borne directly by consumer balances rather than institutional balance sheets.
This creates a brand-new socio-economic dynamic. The success of a space exploration program becomes directly tied to the net worth of millions of ordinary households.
SECTION 4 — Competing Perspectives or Counterargument
The enthusiasm surrounding this retail expansion is far from universal. Institutional short-sellers and corporate governance purists express deep concern over what they describe as a structural transfer of risk from sophisticated funds to vulnerable retail accounts.
The core argument rests on the volatility inherent in deep-tech execution. Space operations are plagued by binary outcomes; a single launch failure or a severe solar storm can instantly erase billions of dollars in orbital hardware.
+-----------------------------------------------------------------+
|                    THE RISK TRANSFER PATHWAY                    |
+-----------------------------------------------------------------+
|                                                                 |
|  [Sophisticated Venture Funds]                                   |
|  De-risk early stages -> Pocket secondary liquidity profits     |
|                                                                 |
|  [The Retail Public Bridge]                                     |
|  Absorbs high-valuation float -> Bears systemic launch risks    |
|                                                                 |
|  [Systemic Vulnerability]                                       |
|  Hardware failure -> Direct consumer portfolio impairment       |
|                                                                 |
+-----------------------------------------------------------------+
Furthermore, critics argue that the company’s valuation models are increasingly detached from traditional fundamental analysis. Analysis published by the Harvard Business Review Research Collection suggests that retail-driven capital raises frequently suffer from an “innovation premium” that distorts price discovery.
When retail buyers purchase shares based on cultural affinity or charismatic leadership rather than price-to-earnings ratios, the stock can become detached from its underlying cash flows. This opens the door to severe market corrections if the company misses its operational deadlines.
Market Valuation Drivers:
Institutional Model: [Cash Flow Multipliers + CapEx Auditing = Fundamental Value]
Retail Dynamic:      [Brand Affinity + Cultural Momentum = Speculative Premium]
There is also the thorny issue of dual-class stock structures. Musk’s planning documents indicate that the retail shares distributed through the public allocation will carry minimal voting rights—potentially a 10-to-1 or even 100-to-1 voting disadvantage compared to the Class B shares held by corporate insiders.
This structure ensures that public capital funds the enterprise without granting the public any say over its strategic direction. If the executive decides to divert capital from the profitable commercial satellite division to fund speculative planetary exploration programs, retail shareholders will have no legal mechanism to intervene or protect their capital.
CLOSING
The impending restructure of SpaceX’s capital allocation represents a pivotal crossroads for modern financial markets. By assembling an infrastructure capable of routing billions of dollars in primary equity directly to retail accounts, the enterprise is bypassing the traditional institutional gatekeepers that have dictated private equity rules for nearly a century. This strategy provides the organization with a highly diversified, uncoordinated, and fiercely loyal capital base, securing the funding necessary to power its multi-planetary ambitions without surrendering corporate control.
Yet, this democratization of financial access brings a parallel democratization of systemic risk. As the line between speculative deep-tech engineering and consumer wealth blurs, the financial stability of millions of everyday portfolios becomes inextricably bound to the operational success of an orbital infrastructure.
The ultimate success of this financial experiment will determine whether the democratization of private equity is a true evolution of capitalism, or simply a brilliant redistribution of late-stage risk.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


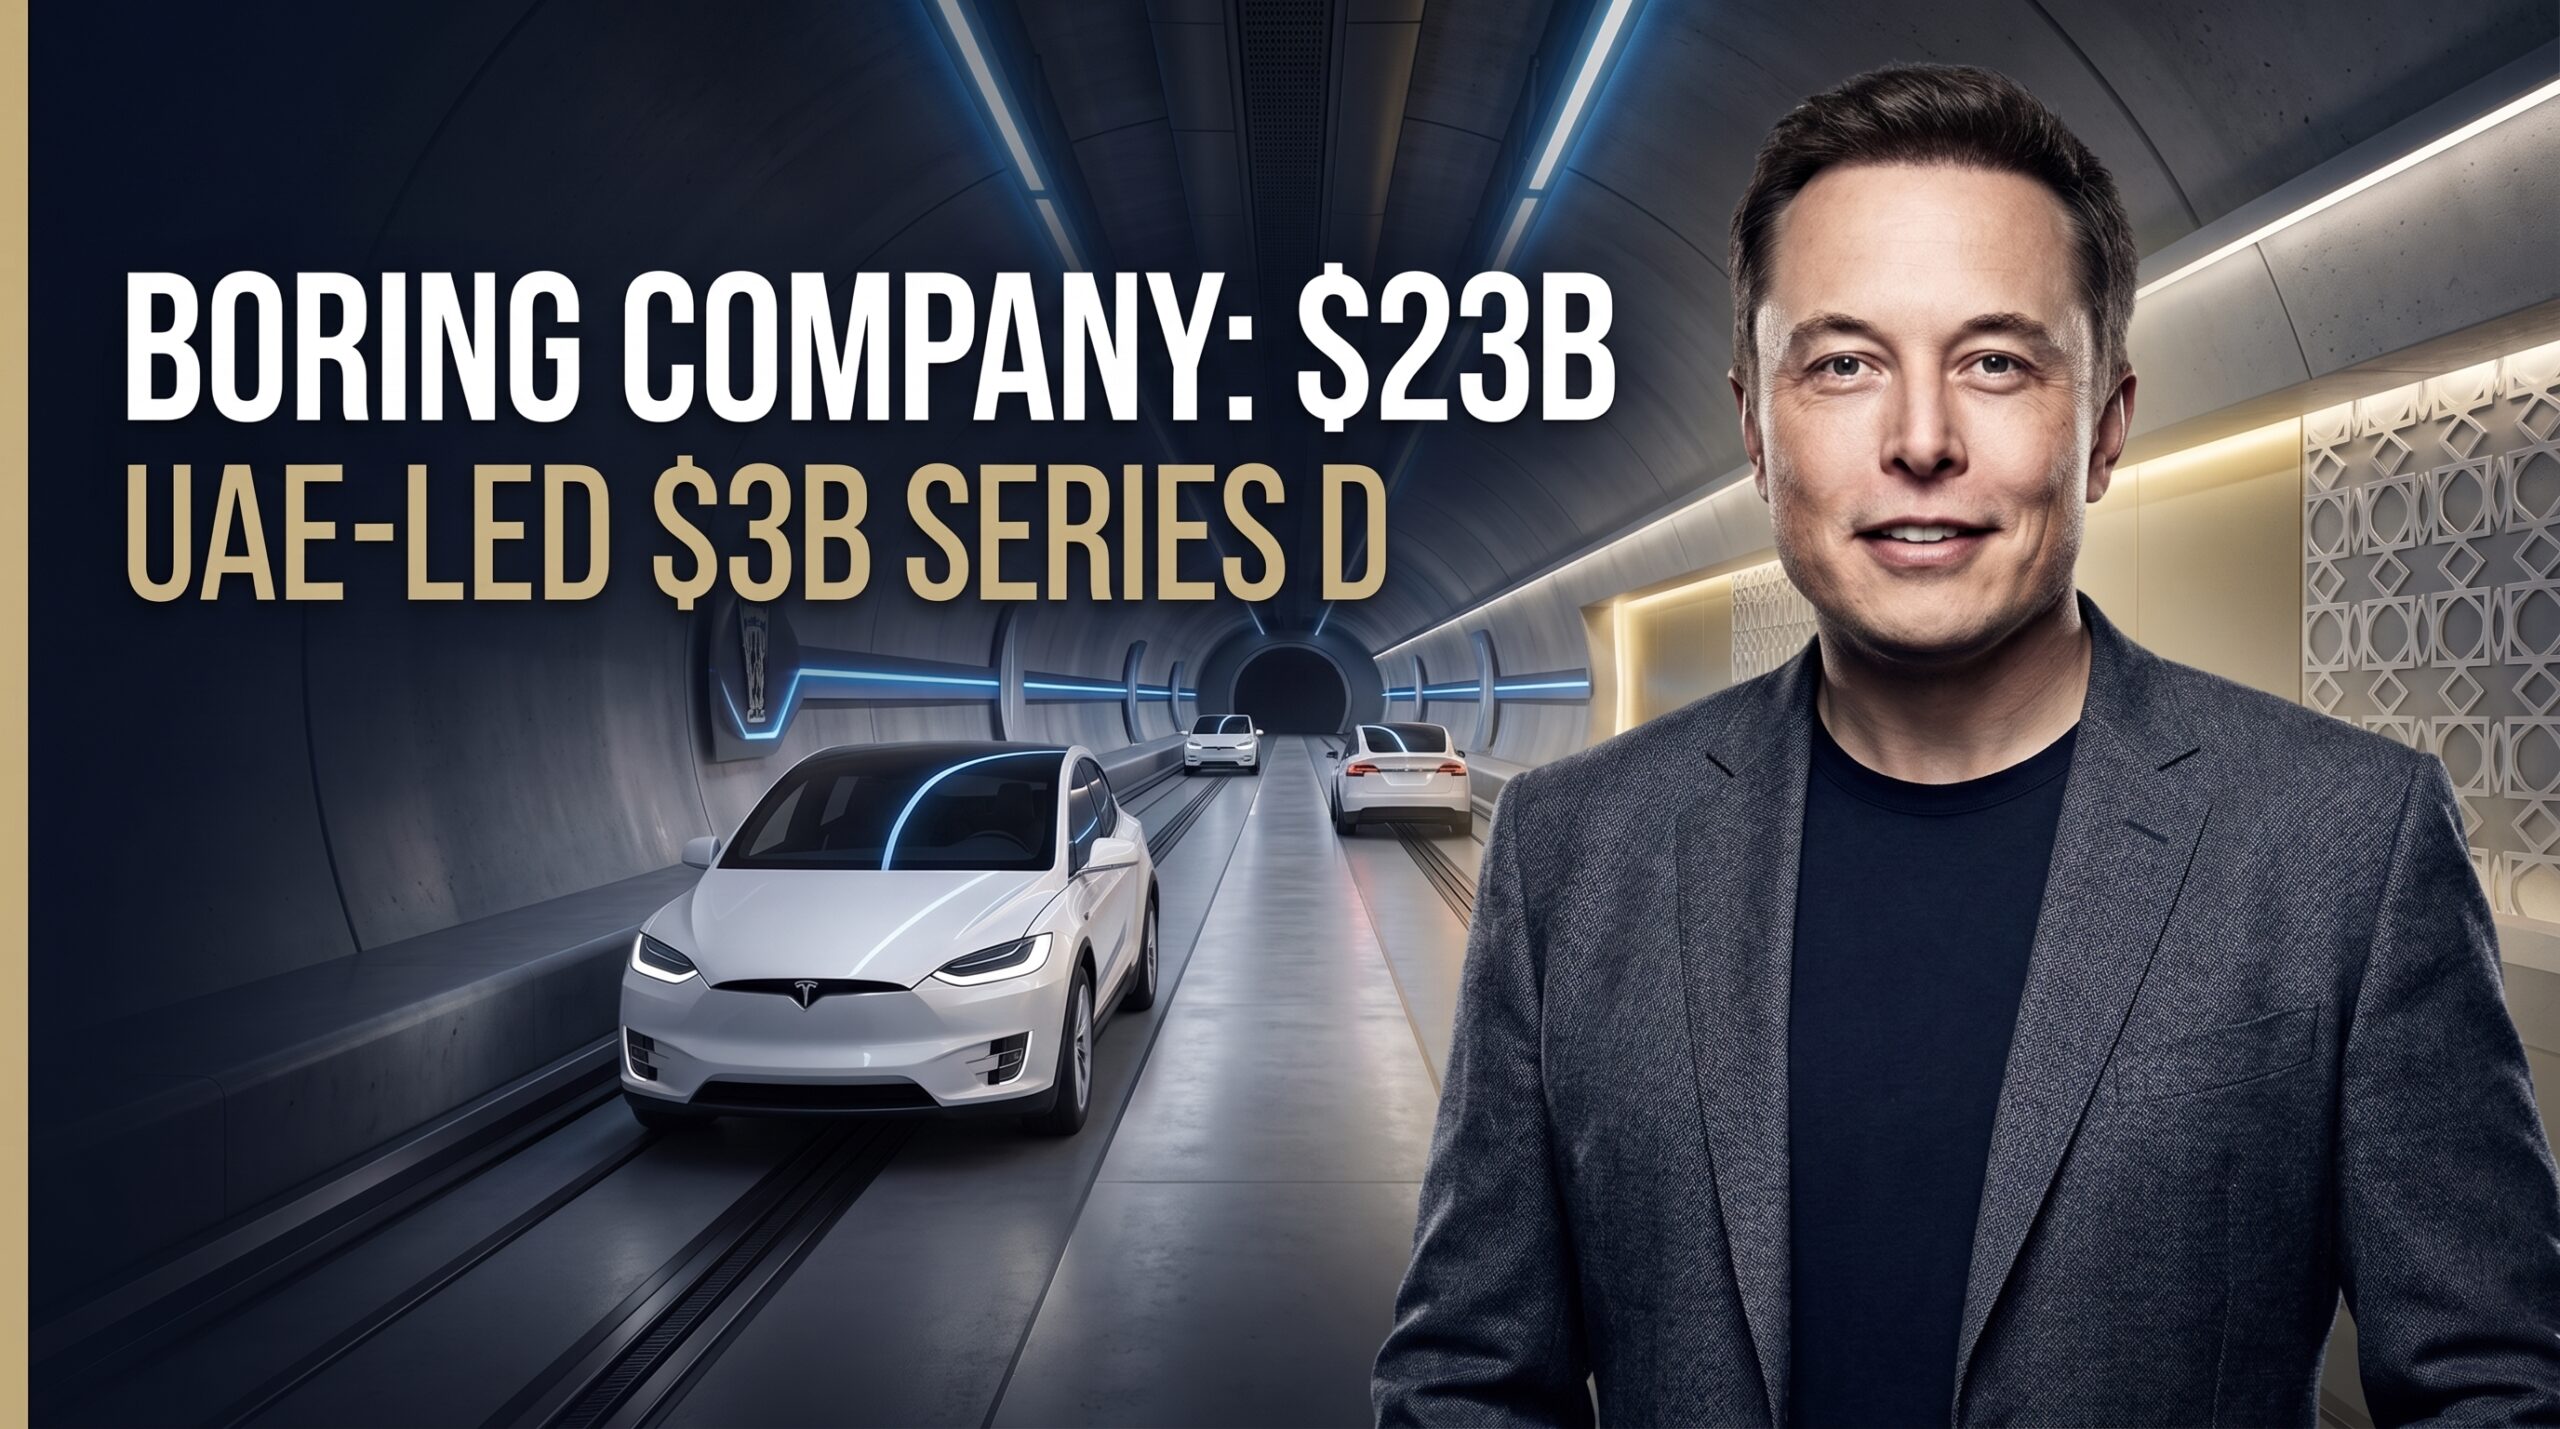
Elon Musk’s ambitious underground transit venture is officially scaling up its global footprint. The Boring Company has closed a massive $3 billion Series D funding round, catapulting its valuation to $23 billion. This represents a staggering four-fold increase from its $5.7 billion valuation in 2022.
Led by the United Arab Emirates (UAE) alongside a syndicate of heavyweight tech investors, this capital injection signals a decisive shift from a localized Las Vegas demonstration project to an international, multi-city infrastructure enterprise.
The Middle Eastern Pivot: A $3 Billion War Chest
The Series D round wasn’t just a capital raise; it was a strategic alignment. The UAE spearheaded the investment, joined by a roster of tier-one venture capital and private equity firms, including Sequoia Capital, Andreessen Horowitz (a16z), and Singapore’s state-owned Temasek. Additional participation came from Valor Equity Partners, Vy Capital, and Baron Capital.
The UAE’s role as the lead investor is deeply intertwined with its status as The Boring Company’s premier international customer. The funding is earmarked to deploy over 150 kilometers of underground infrastructure across the Emirates. This massive undertaking builds upon the foundation of the Dubai Loop, a project that was solidified at the World Governments Summit.
| Project Phase | Details | Estimated Cost |
| Dubai Pilot | 6.4 km route with 4 stations linking DIFC and Dubai Mall | ~$154 Million |
| Full UAE Network | >150 km of interconnected underground transit | TBD |
Manufacturing of precast tunnel segments for the Dubai pilot has already commenced, with active tunnel boring expected to begin in late 2026.
Scaling the Loop: Vegas, Nashville, and Beyond
While the Middle East represents the frontier of expansion, The Boring Company is simultaneously aggressively scaling its domestic operations in the United States.
- The Vegas Loop Expansion: Las Vegas remains the company’s operational showcase. Having already transported over four million passengers, the network recently added Tesla Cybertrucks to its autonomous fleet. Clark County regulators have greenlit a massive expansion, entitling the network to 123 stations, complete with a dedicated connector to the Harry Reid International Airport.
- Music City Loop (Nashville): Moving beyond the softer soils of Nevada, the company has broken ground in Nashville, Tennessee. Following regulatory approval in early 2026, crews are actively operating two Prufrock machines concurrently. This marks the company’s first foray into complex, hard-rock tunneling.
Prufrock and the Autonomous R&D Push
A significant portion of the new capital is allocated for aggressive hiring across engineering, operations, and production to scale the Prufrock tunnel-boring platforms.
The Boring Company’s core value proposition isn’t just digging holes—it’s automating the excavation process to drastically reduce costs and timelines. Recent milestones indicate that ring-building has become fully autonomous. Heavy concrete segments are now placed with millimeter precision via remote monitoring from the company’s Global Operations Control Center in Texas, effectively demonstrating “Zero-People-in-Tunnel” continuous mining.
For Musk, the mission remains philosophical as much as it is mechanical. In a statement accompanying the funding announcement, he noted: “Defeating traffic is the ultimate boss battle. Even the most powerful humans in the world cannot defeat traffic.”
With a $23 billion valuation and sovereign wealth backing, The Boring Company now has the financial firepower to test whether silicon valley automation can finally conquer legacy urban congestion.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Nintendo’s software strategy for Switch 2 aims to dominate Q1 2027. Releasing ‘Metroid Ravenous’ as a premium system-seller sidesteps the hardware loss-leader strategy. High-margin Special Editions and digital storefront ecosystems maximize software profitability to cushion the capital expenditure of the hardware launch.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The abrupt closure of multiple Denny’s locations in Minnesota and Wisconsin signals a systemic crisis in casual dining. M15 Inc.’s collapse highlights the combination of escalating commercial real estate debt, persistent food inflation, and softening consumer foot traffic. Overleveraged franchisees are collapsing under interest rates established during the zero-interest-rate policy era, facing unsustainable debt servicing requirements.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Stock Market Crash 2026? How the Trump $5,000 Dividend Impacts Global Inflation

Tax-to-GDP Ratio Explained: Global Benchmarks, Fiscal Sovereignty & 2026 Insights

Trade Deficit & Terms of Trade Explained: Global Impact, Real-World Examples, and 2026 Insights

Supply vs Demand Shocks Explained: Market Equilibrium, Inflation Risks & Policy Responses in 2026

Microeconomics vs. Macroeconomics Explained: Key Differences, Interdependence & Global Impact

Devaluation vs Depreciation: Clear Differences, Causes, and Economic Impact

Purchasing Power Parity (PPP) Explained: Global Rankings, Living Standards & Why Nominal Exchange Rates Mislead in 2026

Remittances 2026: Global Trends, Household Resilience & Economic Lifeline for Developing Nations

Stagflation Explained: Causes, Global Impact & 2026 Economic Outlook

Understanding Foreign Exchange Reserves: Key Purposes and Global Impact

The Business of Gaming and Tech: How Global Economies Are Driven by Digital Consumerism

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Anthony Scaramucci’s Crypto Prediction: Why MicroStrategy’s Move Is Bitcoin’s “iPhone Moment”

Best Dividend Stocks 2026: European & Asian Blue Chips

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Gold’s Wild 2026: From a Record $5,600 Peak to a 24% Crash and Back Toward $4,500

Oil Surges as Strait of Hormuz Traffic Collapses Again

The Rocket That Won’t Quit: Inside SpaceX’s Falcon 9 Launch Machine

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Retail Earnings Week: What Home Depot, Target & Walmart Reveal

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Tween Back-to-School Trends 2026: What’s Driving the $85B Season
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025