
Economics
Stagflation Explained: Causes, Global Impact & 2026 Economic Outlook

The Economic Nightmare of Stagnant Growth and Persistent Inflation
Stagflation is one of the most dreaded macroeconomic phenomena in economic history. It describes an economic condition characterized by three simultaneous afflictions: stagnant economic growth (or a recession), high unemployment, and high inflation.
For decades, mainstream economic theory dictated that this combination should be virtually impossible. According to traditional Keynesian economics—specifically the Phillips Curve—inflation and unemployment had an inverse relationship: when inflation was high, unemployment was low because a booming economy created jobs; when unemployment was high, inflation subsided due to weak consumer demand. Stagflation shattered this dogma, proving that an economy can suffer from soaring prices and stagnant output at the very same time.
For financial analysts and readers of economist.media, understanding stagflation is crucial because standard monetary and fiscal playbooks completely fail when it strikes.
The Historical Anatomy of Stagflation
The term “stagflation” was famously coined in the United Kingdom in 1965 by politician Iain Macleod during a parliamentary speech, but the phenomenon became a global crisis in the 1970s.
Prior to 1973, Western economies enjoyed robust post-war growth. However, the 1973 OPEC oil embargo—triggered by geopolitical conflicts in the Middle East—caused the price of crude oil to quadruple almost overnight. Because oil was the primary energy source powering global manufacturing, transport, and agriculture, this supply shock drove production costs sky-high.
Factories had to pay vastly more for energy and raw materials, forcing them to raise prices (fueling inflation) while simultaneously laying off workers and cutting production (triggering stagnation and unemployment). It was a masterclass in cost-push inflation.
Why Stagflation Puzzles Policymakers
To understand why stagflation is a nightmare for central banks, we must look at how monetary policy traditionally works:
- To fight inflation: A central bank raises interest rates to cool down consumer spending and corporate borrowing. But in a stagflationary environment, raising rates further strangles an already stagnant economy, driving unemployment even higher.
- To fight stagnation and unemployment: A central bank lowers interest rates to make borrowing cheap and stimulate business expansion. But in a stagflationary environment, flooding the market with cheap money pours gasoline on the fire, causing inflation to skyrocket out of control.
Central bankers are trapped between Scylla and Charybdis. Whichever policy lever they pull to fix one problem violently exacerbates the other.
The Modern Triggers of Stagflation
While oil shocks triggered the historic episodes of the 1970s, modern economies face new systemic vulnerabilities that can ignite stagflation:
- Supply Chain Disruptions: Events like global pandemics, geopolitical trade wars, and maritime shipping blockages create severe bottlenecks in raw material delivery. When supplies vanish, prices spike while production stalls.
- Aggressive Commodity Price Volatility: As seen during recent global crises, sudden spikes in agricultural commodities, natural gas, and fertilizer prices due to regional wars can push import-dependent developing nations straight into cost-push inflation while domestic growth grinds to a halt.
- Wage-Price Spirals: When inflation outpaces wage growth, workers demand higher pay. If companies grant these raises without a corresponding increase in productivity, they hike retail prices further, entrenching stagflationary psychology across the labor market.
Policy Responses: How to Survive Stagflation
Because monetary policy alone cannot solve stagflation, governments must deploy a coordinated mix of supply-side economics and fiscal discipline:
- Supply-Side Reforms: Governments must focus on deregulation, investing in domestic agricultural productivity, diversifying energy sources (such as transitioning to renewables or domestic hydrocarbons), and reducing trade barriers to lower the cost of production.
- Targeted Fiscal Support: Instead of broad-based money printing or universal stimulus checks—which only worsen inflation—governments must provide targeted cash transfers to the most vulnerable segments of society while cutting wasteful public expenditures.
- Structural Labor Market Improvements: Enhancing workforce training and matching labor skills to modern industries can reduce structural unemployment without triggering wage-driven inflation spikes.
For readers of Thefinance.pk, recognizing the early signs of stagflation is vital for asset allocation. In a stagflationary environment, traditional cash savings and fixed-income bonds get decimated by inflation. Investors typically pivot toward hard assets (like gold and real estate) and companies with strong pricing power that can pass rising costs onto consumers without losing market share.
Key Takeaways:
- Stagflation is the toxic combination of stagnant economic growth, high unemployment, and high inflation.
- It defies traditional economic models like the Phillips Curve, which assumed inflation and unemployment moved in opposite directions.
- Historical stagflation was triggered by massive supply shocks, such as the 1970s oil embargoes.
- Standard monetary policy fails during stagflation because raising rates hurts growth, while lowering rates worsens inflation.
Authoritative Sources & Further Reading:
- Federal Reserve Economic Data (FRED): Historical Inflation and Unemployment Analysis
- World Bank: Global Economic Prospects and Stagflation Risks Report
- International Monetary Fund (IMF): Dealing with Supply Shocks and Inflation
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Industory
Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge
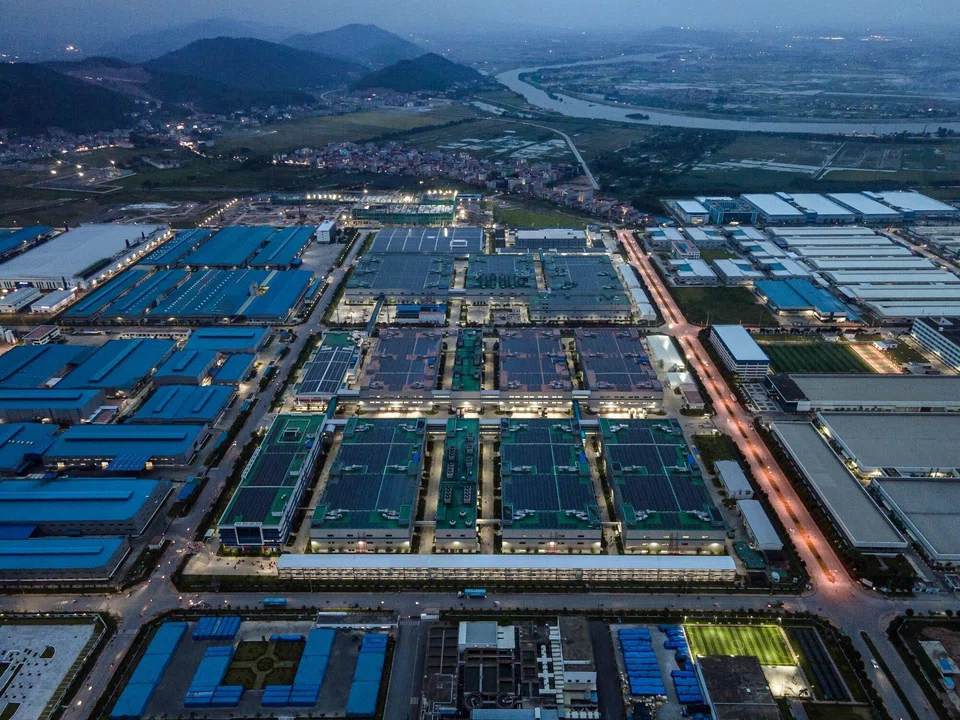
Vietnam’s economy is undergoing a structural transformation. While Tier-1 metropolitan hubs like Hanoi and Ho Chi Minh City maintain steady growth, a cluster of high-tech northern industrial provinces is driving the national economy toward a 10% annual GDP target.
According to official economic data tracked by the General Statistics Office of Vietnam, national real GDP expanded by 9.95% YoY in Q3, pushing cumulative nine-month growth to 9.01%. This momentum is fueled by a global electronics capital expenditure cycle, rising tech trade surpluses, and record-setting foreign direct investment (FDI).
1. The Northern Growth Phenomenon: Regional Divergence
Out of Vietnam’s 34 provinces and municipality-level cities, 12 recorded double-digit Gross Regional Domestic Product (GRDP) growth over the first nine months of the year—seven of which are located in Northern Vietnam.
While Hanoi (+8.85% GRDP) and Ho Chi Minh City (+9.06% GRDP) were weighed down by service-heavy transitions and real estate recalibrations, northern manufacturing hubs surged ahead:
- Quảng Ninh: 12.88% GRDP growth, driven by renewable energy manufacturing, industrial park expansion, and deep-water port logistics.
- Hải Phòng: >12.00% GRDP growth, supported by $3.1 billion in incoming FDI and industrial output expansion of 15.5% YoY.
- Bắc Ninh & Thái Nguyên: Benefited from high-capacity consumer electronics, semiconductor packaging, and mobile device manufacturing cycles.
Data compiled by the World Bank and the Asian Development Bank underscores that northern provinces are benefiting from their structural alignment with global technology capex.
| Region / Economic Hub | Q1–Q3 GRDP Growth Rate | Primary Industrial Drivers | Major Global Investors |
| Quảng Ninh | 12.88% | Port Logistics, High-Tech Manufacturing, Green Energy | Jinko Solar, Foxconn |
| Hải Phòng | >12.00% | Automotive, Electronics, Seaport & Logistics | LG Group, VinFast, Pegatron |
| Bắc Ninh | >11.50% | Consumer Electronics, Semiconductor Assembly | Samsung Electronics, Amkor Technology |
| Thái Nguyên | >10.80% | Mobile Hardware & Electronic Components | Samsung, Hansol Electronics |
| Hanoi (Tier-1 City) | 8.85% | Finance, Services, Software, Retail | Canon, Honda, Domestic Services |
| Ho Chi Minh City (Tier-1) | 9.06% | Financial Services, Commerce, Light Industry | Intel, Nidec, Logistics |
2. Structural Catalysts: Why Northern Vietnam Leads Tech Manufacturing
A. Seamless Cross-Border Logistics with Southern China
Northern industrial corridors (Hanoi–Hải Phòng–Quảng Ninh) share direct highway links to the border gates of Lạng Sơn and Móng Cái. This direct connection to China’s industrial powerhouse in Shenzhen and the Pearl River Delta enables same-day transport of critical raw components, silicon wafers, and sub-assemblies, a logistical advantage that southern or central provinces cannot replicate.
B. Multi-Modal Transport & Free Trade Zones
Hải Phòng stands out as the only northern locality offering direct access across all five primary transport modes: sea, road, rail, inland waterways, and air. The development of the Hải Phòng Free Trade Zone and the expansion of the Lạch Huyện Deep-Water Seaport allow mother vessels to bypass feeder ports and sail directly to North American and European markets, drastically lowering freight costs and transit times.
C. The Tech FDI Wave: Electronics & Semiconductors
According to global FDI metrics published by Investment Monitor, approved foreign direct investment into Vietnam surged 76.4% YoY to surpass $50.3 billion, with disbursed FDI reaching $21 billion.
The surge in trade performance is highlighted by specific high-tech export categories:
- Computers, Electronics & Components: Surged 59.6% YoY to $123.7 billion.
- Phones, Smart Devices & Components: Rose 18.8% YoY to $51.8 billion.
Together, these two categories generated approximately 40% of total national exports and nearly two-thirds of the total year-on-year increase in merchandise trade.
3. Key Operational Challenges & Strategic Outlook
Despite high growth rates, northern industrial hubs face structural bottlenecks that require ongoing management:
- Power Grid Resilience & Clean Energy Transitions: High-density semiconductor packaging and electronics assembly require uninterrupted, clean power. Ongoing investments in high-voltage transmission lines connecting central energy projects to northern industrial parks are critical to prevent seasonal grid strain.
- Skilled Engineering Talent Shortages: The rapid shift from manual assembly to advanced testing, packaging, and high-precision component production requires rapid upskilling of local engineers and technicians.
- Supply Chain Deepening: To maximize local value addition, Vietnam’s industrial policy focuses on nurturing local Tier-2 and Tier-3 suppliers to integrate into global supply chains dominated by foreign OEMs.
Market consensus data aggregated by Trading Economics and institutional research confirms that as global technology manufacturers continue diversifying under China+1 strategies, Northern Vietnam’s industrial cluster remains a primary beneficiary of foreign direct investment in Southeast Asia.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Opinion
Federal Reserve Defies White House Pressure: Inside Trump’s Demand for Sub-1% Interest Rates After Historic 2026 Rate Hike
The Eccles Building in Washington, D.C., home to the Federal Reserve Board of Governors.
Executive Summary
- The Decision: The Federal Open Market Committee (FOMC) voted 12–0 to raise the benchmark federal funds rate by 25 basis points to a target range of 3.75%–4.00%—marking the central bank’s first rate increase in over three years.
- The Presidential Rebuttal: President Donald Trump posted a sharp criticism on Truth Social, declaring that U.S. borrowing costs should be “1%, or less,” asserting that America’s credit standing warrants the lowest interest rates in the world.
- The Fed’s Stance: Federal Reserve Chair Kevin Warsh defended the policy tightening as a “sober, serious, responsible decision,” pointing to stubborn inflation driven by elevated geopolitical energy shocks and structural supply-side pressures.
- Market Projection: The updated FOMC “dot plot” reveals that 16 out of 18 policymakers anticipate at least one additional rate increase before the end of 2026.
1. The Rate Hike: Why the FOMC Acted
In a move that surprised some dovish market participants, the Federal Open Market Committee unanimously voted to raise the target range for the federal funds rate by 25 basis points to 3.75%–4.00%. According to official reporting from Livemint Monetary Coverage, this decision represents the first upward adjustment in borrowing costs since mid-2023.
President Donald Trump has repeatedly called for aggressive monetary easing to stimulate domestic capital investment.
Speaking at a post-meeting press conference, Fed Chair Kevin Warsh emphasized that persistent inflationary pressures leave central bankers with little room to ease monetary policy. Recent Bureau of Labor Statistics readings showed underlying consumer price inflation hovering consistently above the Fed’s 2% annual target.
“The plain fact is that inflation is too high and has been for too long. Summer inflation readings do not tell me that underlying trends have improved sufficiently to pause our stabilization efforts.”
— Kevin Warsh, Chair of the Federal Reserve Board
Economic headwinds contributing to sticky inflation include:
- Geopolitical Energy Shocks: High global crude oil and liquefied natural gas (LNG) prices linked to Middle Eastern conflict zones.
- Tariff Impacts: Import duties continuing to feed into intermediate manufacturing costs.
- Capital Spending Inflows: Heavy corporate investment in artificial intelligence infrastructure maintaining high credit demand across domestic capital markets.
2. Trump’s Escalating Criticism & The “1% or Less” Target
Within hours of the Fed’s announcement, President Trump issued a strongly worded response on social media, criticizing the FOMC’s policy direction and renewing his demand for radical rate reductions as reported by Economic Times.
Key Quotations from President Trump
- On Rates: “Interest Rates in the United States should be 1%, or less, because we are the Best Credit in the World — BY FAR.”
- On Speed: “LOWER THE INTEREST RATES FOR THE UNITED STATES OF AMERICA, AND FAST!”
- On Trade Deficits: “The word ‘Deficit’ is nothing more than a fancy word for LOSS. We are ‘carrying’ almost every country in the World, and that cannot go on any longer.”
Trump linked monetary policy directly to international trade balances, arguing that higher U.S. interest rates place domestic manufacturers at a competitive disadvantage against foreign trading partners with lower cost-of-capital environments.
3. White House Growth Mandate vs. Federal Reserve Inflation Control
The debate over the ideal path for interest rates reflects fundamentally different perspectives on macroeconomic priorities:
| Dimension | White House Economic Stance | Federal Reserve Policy Framework |
| Primary Goal | Maximize GDP expansion & capital investment | Maintain price stability (2% inflation target) & employment |
| Target Rate Range | 1.00% or lower (Aggressive Easing) | 3.75% – 4.00% (Restrictive / Neutral) |
| Inflation Assessment | Supply-side deregulation & tariffs offset price risks | Sticky Core CPI requires tight borrowing conditions |
| View on Trade Deficits | High rates strengthen dollar, worsening trade deficit | Trade balances are driven by savings-investment balances, not policy rates |
| Rate Outlook (2026) | Immediate multi-percentage-point cuts | Dot plot signals 1 additional 25 bps hike |
Institutional policy research published by the Center for American Progress underscores that central bank independence is crucial for maintaining long-term bond market stability and preventing inflation expectations from becoming unanchored.
4. Market Reaction & Consumer Economic Impact
Financial markets responded with elevated volatility following the policy decision and subsequent presidential statements, as detailed in market summaries by TradingView Financial Markets.
Consumer Borrowing Costs
- Mortgage Rates: The 30-year fixed mortgage rate remains anchored above 6.5%–7.0%, dampening residential housing turnover.
- Credit Cards & Consumer Loans: Average commercial credit card APRs remain near multi-decade highs above 21%, increasing debt service obligations for revolving balance holders.
- Savings Yields: High-yield savings accounts (HYSAs) and short-term U.S. Treasury bills continue offering cash holders yields between 3.5% and 4.0%.
Institutional Analysis on Rate Easing
In a comprehensive macroeconomic review, researchers at the Washington Center for Equitable Growth note that cutting the federal funds rate down to 1% in an economy operating near full employment would risk re-igniting double-digit wage-price spirals last seen in the late 1970s. Economists stress that rate cuts of that magnitude are historically reserved for deep recessions or systemic financial crises.
5. Looking Ahead: What to Watch at the Next FOMC Meeting
As the central bank approaches its upcoming policy gathering, three indicators will determine whether Chair Warsh and the FOMC proceed with another rate increase:
- Monthly Consumer Price Index (CPI) & PCE Deflator: Any persistent month-over-month increases above 0.3% in core indexes will lock in another 25 bps hike.
- Labor Market Tightness: Unemployment claims and non-farm payroll growth will reveal whether elevated borrowing costs are successfully cooling labor demand.
- Treasury Yield Dynamics: The spread between short-term 2-year Treasury notes and 10-year Treasury bonds will signal bond market expectations regarding future rate policy and economic growth.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Interest Rate Policy
How Rising Interest Rates Impact Gig Economy Apps: DoorDash, Uber, and Urban Services
The Fed hiked to 3.75%-4% with gas above $4. See how rates, fuel and consumer spending transmit into DoorDash unit economics and gig platform margins.The standard model says rising rates hurt gig platforms because they are long-duration growth assets and because discretionary spending contracts. Both halves of that model are currently being contradicted by the data.
Executive Summary / Key Takeaways
- The Federal Reserve raised rates to 3.75%–4.00% on 16 September 2026, with 16 of 18 FOMC participants projecting at least one more hike this year.
- The transmission into gig platforms runs through three channels, and only one is the discount rate: consumer discretionary spending, courier input costs, and the cost of capital for long-duration investment.
- DoorDash guided take rate to decline in Q4 2026 on seasonal Dasher cost increases, an insurance step-up and higher winter delivery complexity — margin compression that is structural, not cyclical.
- The company absorbed a gross cost of over $50 million for a Dasher gas relief programme in Q2 2026, a direct macro-to-margin transfer with national pump prices above $4 a gallon.
- The counterintuitive finding: DashPass subscriptions grew more in twelve months than the prior twenty-four combined, suggesting convenience platforms may function as household cost-management tools rather than pure discretionary spend.
The Fed raised its target range by a quarter point to 3.75%–4.00% on 16 September 2026, describing economic activity as expanding at a solid pace with domestic spending resilient, productivity growth strong and capital investment robust, while noting that inflation remains elevated. Sixteen of eighteen participants expect at least one further increase before year-end.
Yet on the day of the hike, the Dow fell more than 600 points while the Nasdaq finished close to flat, with the damage concentrated in cyclicals, transport and energy-exposed names — J.B. Hunt Transport fell 12.64% on an earnings warning citing rising operating costs — according to market coverage. The rate-sensitive damage landed on physical logistics, not on technology platforms.
For gig economy analysis, that is the tell. The binding constraint in 2026 is not the discount rate. It is the cost of moving things.
2. Core Analysis: Three Transmission Channels
2.1 Channel one — courier input costs
This is the dominant channel and the most direct.
DoorDash anticipated the gross cost of its Dasher gas relief programme at over $50 million for Q2 2026, expecting to fund it at least partly by adjusting investment elsewhere, per its Q1 disclosure. That is a macro variable landing straight on the income statement: the national average for regular gasoline was $4.329 a gallon on 15 September 2026, against $3.14 a year earlier.
The seasonal effect compounds it. Management guided take rate to remain flattish in Q3 before declining in Q4 due to seasonal increases in Dasher costs, an insurance step-up and higher delivery complexity during winter months, per the earnings call summary.
Translated for investors: courier supply is price-elastic, weather-sensitive and fuel-cost-exposed, and the platform absorbs the gap rather than fully passing it to consumers. Rising rates do not cause this. Rising energy prices do — and the same energy shock is what drove the Fed to hike, which is why the two appear correlated.
2.2 Channel two — consumer discretionary spending
Here the data contradicts the thesis.
In Q2 2026, DoorDash grew total orders 27% year-on-year to 970 million, Marketplace GOV 36% to $33.1 billion and revenue 36% to $4.45 billion — 17%, 23% and 24% respectively excluding the Deliveroo acquisition, per company results. US paid DashPass members increased more in the twelve months through Q2 2026 than in the previous twenty-four months combined.
Subscription penetration accelerating during a period of elevated food and fuel inflation is not the behaviour of a discretionary category under pressure. Management’s stated logic is that membership reduces transactional friction through affordability, driving retention and engagement. The plausible reading is that for a meaningful cohort, a delivery subscription functions as a cost-management instrument — a fixed fee that caps variable delivery expense — rather than as a luxury.
2.3 Channel three — cost of capital for long-duration bets
| Metric | Q2 2026 | Signal |
|---|---|---|
| Adjusted EBITDA | $914m (+40%) | Core profitability strong |
| GAAP net income | $200m (-30%) | Legal and regulatory expense drag |
| Operating cash flow | $944m (from $504m) | Self-funding capacity improving |
| 2026 stock comp | $1.2–1.3bn | Dilution cost of talent retention |
| 2026 D&A | $1.1–1.2bn | Including ~$450m acquired intangibles |
With operating cash flow at $944 million in a single quarter, DoorDash is largely self-funding its autonomy, AI and infrastructure investment. Higher rates raise the opportunity cost of that spending but do not gate it. The platforms that higher rates genuinely constrain are the sub-scale, cash-burning ones — and the rate environment therefore accelerates consolidation toward the profitable incumbents rather than damaging them.
3. Structural Drivers and Competitor Gaps
The correlation most analyses get backwards. Fed funds and gig platform margins are correlated in 2026, but not causally in the direction usually assumed. Both are downstream of the same energy shock: elevated crude drove gasoline up 27.4% year-on-year in the August CPI, which drove headline inflation, which drove the Fed to hike, and independently drove courier fuel costs up. Modelling gig margins as a function of the policy rate will produce a fitted relationship with no predictive validity once energy normalises.
Autonomy is a rate-environment bet. DoorDash Dot is expected to reach high single-digit penetration in test markets by year-end, scaling from Phoenix. If seasonal courier cost inflation is the recurring drag on Q4 take rate, autonomous capacity attacks that line directly. Higher-for-longer rates raise the hurdle rate on that investment while simultaneously increasing its payoff — which is why the company is accelerating rather than deferring it.
The regulatory tail risk is larger than the rate risk. DoorDash’s filing names an unresolved California Employment Development Department audit over payroll-tax liabilities tied to Dasher classification, with an amount accrued and resolution uncertain, per the 10-Q. GAAP net income fell 30% partly on higher legal and regulatory expenses. A classification ruling would reprice unit economics sector-wide in a way no plausible rate path would.
Consolidation is the visible second-order effect. DoorDash completed its Deliveroo acquisition in October 2025 for $3.72 billion. In a higher-rate environment, platforms with positive operating cash flow acquire those without it. The gig sector’s competitive structure in 2027 will be shaped more by that dynamic than by demand.
4. Key Implications for Stakeholders
Tech equity investors. Strip the acquisition before modelling — 24% organic revenue growth against 36% headline is the number the multiple should reflect. Then treat Q4 take rate against guidance as the cleanest available test of whether courier cost inflation is cyclical or permanent.
Consumer analysts. Subscription growth during an inflation squeeze is the most interesting datapoint in the sector. If delivery membership is behaving as a household hedge rather than a luxury, the standard discretionary-spending framework misclassifies the entire category.
Gig workers. Fuel relief programmes are discretionary platform spending, funded by reallocating investment elsewhere. They are not contractual, and they are most likely to be trimmed precisely when platform margins compress — which is Q4.
Policy analysts. The combination of an energy shock, a tightening cycle and an unresolved worker-classification case creates unusual conditions for gig regulation. Rising courier costs strengthen the platforms’ argument for flexibility and the workers’ argument for guaranteed earnings simultaneously.
5. Frequently Asked Questions
Q1: Do higher interest rates hurt gig economy apps?
Less directly than assumed. The larger 2026 pressure is energy costs feeding into courier pay — DoorDash spent over $50 million gross on Dasher gas relief in one quarter — while its core profitability and subscription growth both accelerated despite tightening.
Q2: Why is DoorDash’s take rate expected to fall in Q4?
Management cited seasonal increases in Dasher costs, an insurance step-up and higher delivery complexity during winter months. Courier supply is weather- and price-sensitive, and the platform absorbs the cost gap rather than fully passing it to consumers.
Q3: Is consumer spending on delivery falling with rates?
Not on current data. DoorDash grew orders 27% year-on-year to 970 million in Q2 2026, and US paid DashPass members grew more in twelve months than in the prior twenty-four combined.
Q4: What is the biggest risk to gig platform economics right now?
The unresolved California worker-classification audit, which carries payroll-tax implications that would affect the entire sector’s cost structure — a larger exposure than any plausible interest-rate path.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025