
International Trade
Tax-to-GDP Ratio Explained: Global Benchmarks, Fiscal Sovereignty & 2026 Insights

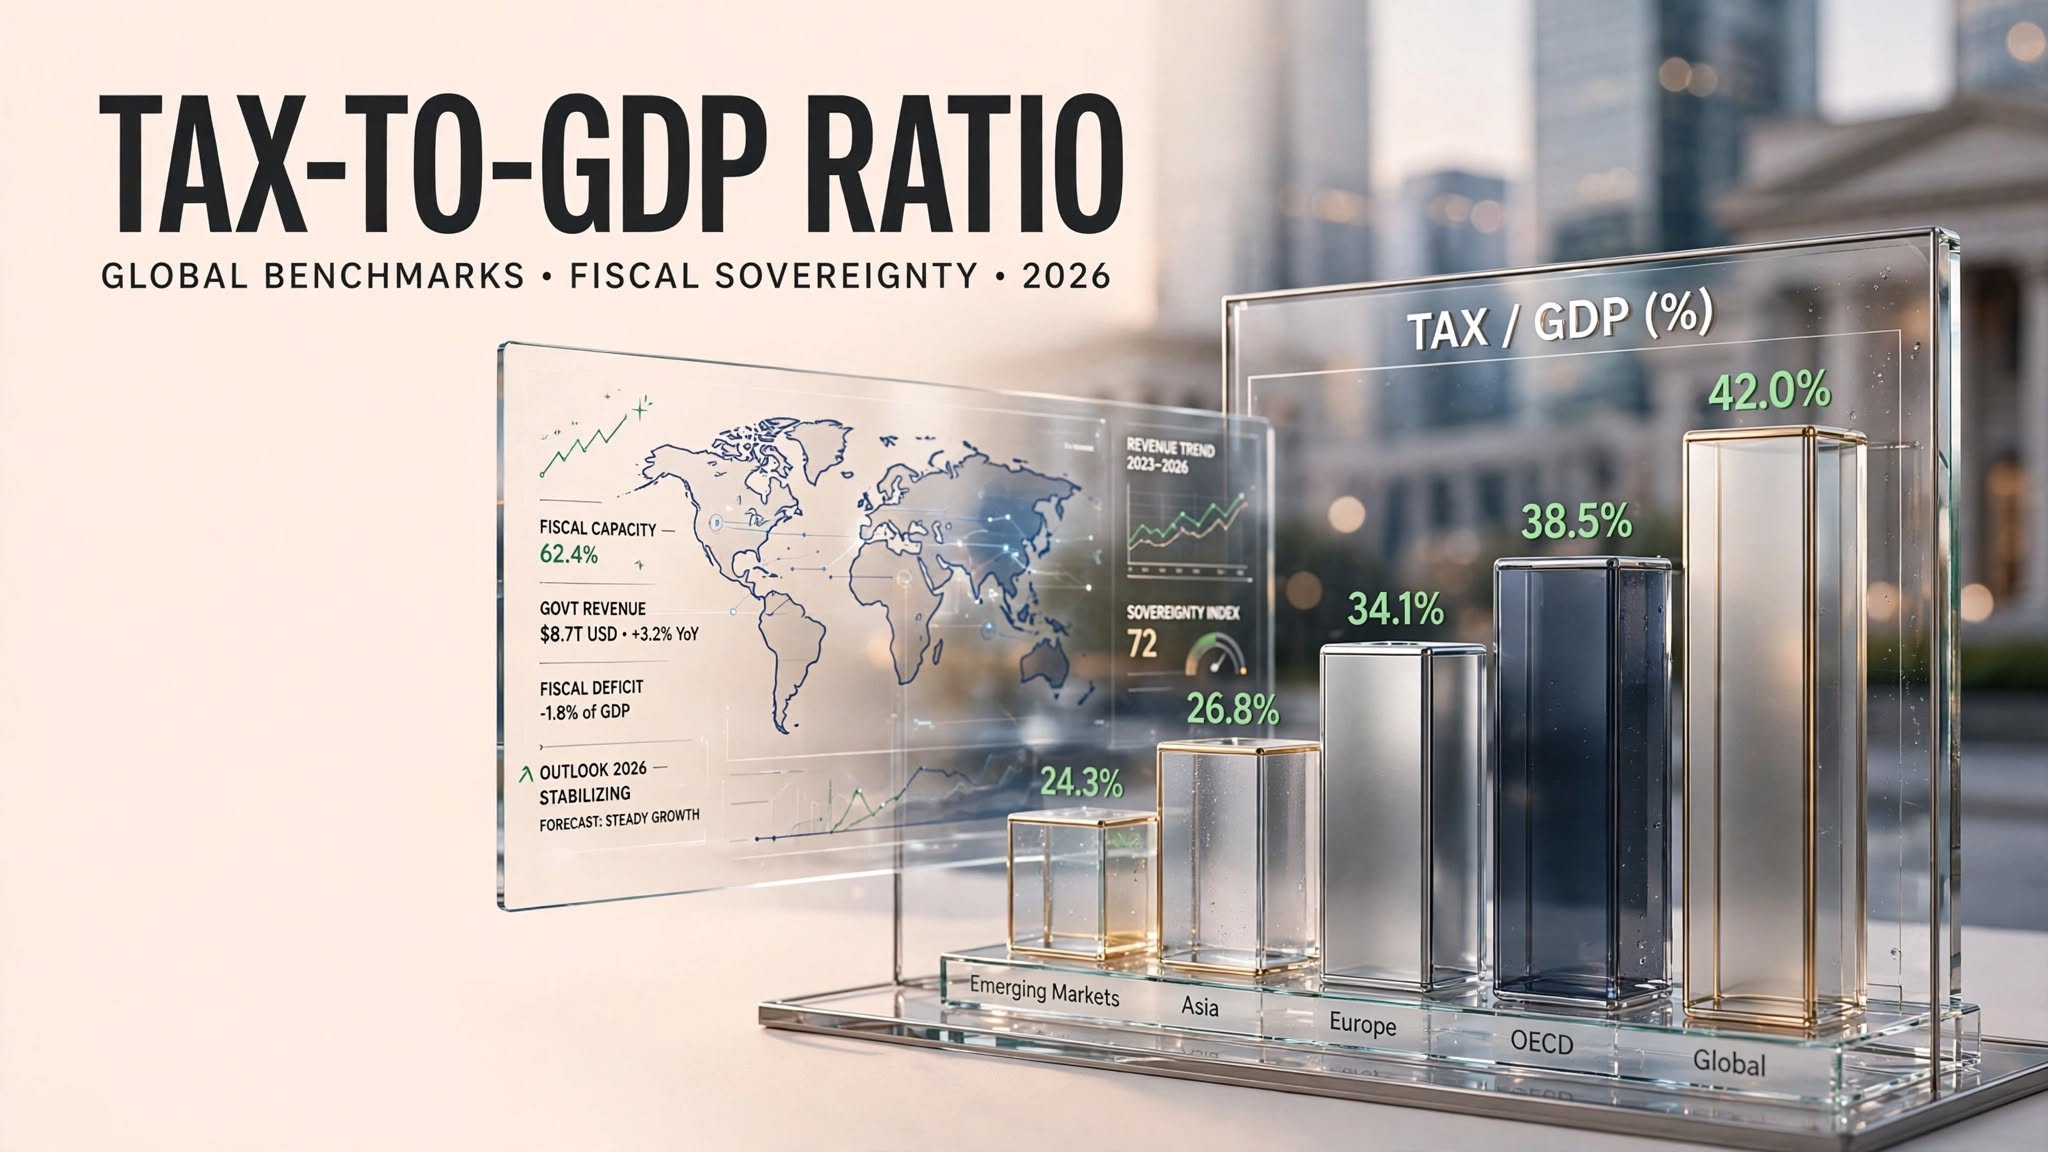
Measuring Government Revenue Efficiency and Fiscal Sovereignty
The Tax-to-GDP Ratio is a critical macroeconomic metric that compares total government tax revenue collection against the country’s Gross Domestic Product (GDP). Expressed as a percentage, it serves as the ultimate benchmark of a government’s fiscal capacity, revenue administration efficiency, and economic formalization.
For readers of economist.media and Thefinance.pk, tracking the tax-to-GDP ratio provides immediate insight into whether a government can fund its public infrastructure and debt obligations sustainably, or whether it is trapped in a perpetual cycle of fiscal deficits and external borrowing.
Why the Tax-to-GDP Ratio Matters
A healthy tax-to-GDP ratio is the cornerstone of economic sovereignty. It dictates how a government finances its public goods and services:
- Funding Public Infrastructure and Social Safety Nets: Developed nations (particularly Scandinavian and Western European economies) often boast tax-to-GDP ratios ranging from 30% to 45%. This high revenue collection allows them to build world-class public transport systems, fund universal healthcare, maintain robust public education networks, and provide social safety nets for vulnerable populations.
- Escaping the Debt Trap: When a developing nation struggles with a low tax-to-GDP ratio (often hovering between 9% and 12%), the government collects insufficient revenue to cover its day-to-day expenditures and interest payments. To bridge the gap, it must borrow heavily from domestic commercial banks or international lenders, driving up public debt and crowding out private sector investment.
The Informal Economy Trap
Why do some developing economies suffer from chronically low tax-to-GDP ratios despite high statutory tax rates? The answer lies in the informal economy (cash-based retail, undocumented labor, and unregistered small businesses).
When a massive percentage of economic activity operates off the books in cash, the tax net fails to capture it. Governments often respond by raising tax rates on the small, formal corporate sector and salaried workers already trapped in the tax net. This creates a vicious cycle: high tax rates on compliant businesses encourage more firms to slip into the informal economy, further shrinking the tax base and depressing the tax-to-GDP ratio.
Structural Tax Reform
To improve the tax-to-GDP ratio sustainably, governments must avoid harsh, regressive indirect taxes (like high flat sales taxes that disproportionately crush poor households) and instead focus on structural fiscal reforms:
- Expanding the Digital Tax Net: Integrating point-of-sale (POS) tracking systems, digitizing financial transactions, and leveraging data analytics to track high-net-worth individuals who evade income tax.
- Streamlining Exemptions: Eliminating massive corporate tax loopholes and exemptions that drain billions in potential state revenue.
- Broadening Direct Taxation: Shifting the burden toward progressive direct taxation, ensuring that wealth, high property values, and capital gains are taxed equitably.
For financial analysts, a rising tax-to-GDP ratio is a powerful signal of structural reform success, indicating that a government is moving toward fiscal self-reliance and macroeconomic stability.
Key Takeaways:
- The Tax-to-GDP ratio measures total government tax collection relative to the total size of the economy.
- Developed nations maintain high ratios (30-45%), enabling robust public infrastructure and social welfare programs.
- Low ratios in developing economies force reliance on deficit financing, heavy domestic borrowing, and external debt.
- Expanding the formal economy and capturing undocumented cash transactions are essential to raising the tax-to-GDP ratio sustainably.
Authoritative Sources & Further Reading:
- Organisation for Economic Co-operation and Development (OECD): Global Revenue Statistics and Tax-to-GDP Ratios
- World Bank: Government Revenue and Fiscal Policy Analytics
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The Federal Open Market Committee left its target range unchanged at 3.75%-4.00% on Wednesday 28 October, according to Admiral Markets’ FOMC summary. The vote was 10-2. The two dissenters, Governor Lisa Cook and Cleveland Fed President Beth Hammack, wanted to raise rates by 25 basis points. A committee that is split towards tightening rather than easing is a notable shift in tone.
The statement pointed to strong economic growth and elevated inflation. Chair Kevin Warsh said the committee held to gather more information, and he floated cutting the number of rate decisions from eight to six a year, per Trading Economics.
Why the Dissents Matter More Than the Hold
A hold was expected. The significance is the direction of dissent. Two voters wanting a hike signals that part of the committee sees inflation risks, aggravated by energy prices from the Middle East conflict, as large enough to justify tightening now. FXStreet and MUFG Research both framed the outcome as a hold with a hawkish edge, with the committee not explicitly committing to further hikes but not ruling them out.
MUFG’s read is that a December hike remains live, with more of another move priced by March. On Thursday, Reuters reported the CME FedWatch tool showing roughly a 90% chance of a December hike. That pricing, rather than the unchanged rate, is what moved currencies and precious metals around the decision.
The Inflation Problem Is an Energy Problem
The Fed’s challenge is that the inflation pressure is not purely domestic demand. Brent oil has climbed to around $115, a six-month high, as attacks on tankers and Saudi infrastructure keep supply worries alive, and Iran is weighing a Qatari draft deal that could ease or inflame the market depending on the answer. Central banks cannot lower oil prices with interest rates, but they can stop an energy shock from becoming embedded in wages and expectations, which is the argument the hawkish dissenters appear to be making.
Market Reaction
Crude oil barely moved on the decision, according to FXStreet, as traders waited on Iran’s response to the Qatari proposal. Gold slid toward $4,000 an ounce on Thursday after US Q3 growth printed at 3.4% and core PCE at 2.5%, per Kitco, with the 10-year yield near 5%.
What It Means Beyond the US
- Emerging markets: a Fed leaning hawkish tightens global financial conditions and raises the bar for easing elsewhere. Pakistan’s central bank raised its policy rate to 12% two days before the Fed meeting for domestic inflation reasons, but a firmer dollar adds pressure to the rupee.
- Gulf central banks: several Gulf central banks held rates after the decision, since their currencies are pegged to the dollar.
- Asia-Pacific: officials such as RBNZ’s governor have said another hike is plausible if inflation does not ease.
What to Watch Before December
- Inflation data: the next PCE and CPI prints will decide whether the dissenters gain allies.
- Oil: Iran’s reply on the Qatari draft, due by the end of the week, is the biggest swing factor. A deal would remove part of the hawks’ case; a breakdown would strengthen it.
- Chair Warsh’s messaging: his comments on the balance between AI-driven productivity and inflation risk.
- Labour market data ahead of the December meeting.
The Fed held, but the committee is no longer debating how fast to cut. It is debating whether to hike. Unless oil retreats, the December meeting is genuinely open.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The Global Interest rates have great Importance in 2026 because global economic growth is becoming more uneven, capital is increasingly sensitive to financing costs, and investors must distinguish a convincing story from an investable price. This guide focuses on research methods and risks rather than predictions of guaranteed returns. The IMF October 2026 outlook projects 3.1% global growth and 4.7% inflation for 2026, while the IMF financial-stability assessment warns that market resilience coexists with important vulnerabilities.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind how global interest rates affect investments is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
Why policy rates affect ordinary households
Central banks influence short-term financing conditions through monetary policy, but retail deposit and lending rates do not adjust one-for-one. Banks account for liquidity, funding costs, credit risk and competition. A rising benchmark may improve yields on new deposits while increasing the repayment burden on floating-rate loans. Compare effective annual rates, not advertising slogans. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Bonds and the price-yield relationship
Existing fixed-rate bonds usually lose market value when comparable yields rise; their coupons are unchanged, but new bonds become more attractive. The longer the duration, the larger the approximate price sensitivity. A two-percentage-point yield jump has different implications for a one-year bill than for a long-duration bond fund. Credit quality also matters: a high quoted yield may compensate for meaningful default risk. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Stocks: discounted profits, uneven sector effects
Higher discount rates can reduce the present value of expected future profits, particularly for expensive long-duration growth companies. Yet banks may benefit from some rate changes, while heavily indebted businesses face refinancing pressure. No single rule predicts stock prices because earnings expectations, inflation and risk appetite move simultaneously. Compare valuations against sustainable rather than peak profits. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
The exchange-rate channel for Pakistan
Differences between global and Pakistani interest rates can influence capital flows and currency expectations, but the rupee also depends on trade, remittances, reserves and policy credibility. A stronger dollar can increase local-currency import and foreign-debt costs even when domestic prices seem stable. Investors should calculate returns in the currency in which future expenses will occur. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
A practical decision checklist
Separate emergency cash, short-term commitments and long-term investments. Match fixed-income maturity to spending needs; compare fixed versus floating loan terms; avoid funding speculative investments with expensive debt. Revisit assumptions when policy statements change, but resist making portfolio decisions from one central-bank headline. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global borrowing conditions can tighten even if Pakistan is making domestic progress. Higher foreign yields change the price and availability of capital and can complicate debt management and currency stability. This feature explains the mechanisms, risks and practical decisions that matter through 2027, with particular attention to Pakistan’s different exposure to energy prices, external financing, global trade and AI investment.
At a glance
- World output is forecast to rise, but opportunities and costs are uneven across countries.
- Global inflation forecasts do not predict household prices in Pakistan.
- The AI capital expenditure cycle lifts trade in electronics but may not translate into productivity gains everywhere.
- Pakistan’s IMF staff-level agreement is a milestone, not final Board approval.
- Stronger exports, competitive energy, fiscal credibility and skills are essential to durable growth.
The verified starting point: what the numbers actually say
The IMF October 2026 World Economic Outlook projects global growth of 3.1% in calendar 2026 and 3.4% in calendar 2027, alongside global headline inflation of 4.7% and 4.1%, respectively. Its statistical cutoff is 1 October 2026. The WTO October 2026 trade outlook projects merchandise trade volume growth of 3.9% in 2026 and 4.1% in 2027, versus commercial-services trade volume growth of 3.3% and 6.4%. These are forecasts from different statistical systems, not interchangeable growth measures.
For Pakistan, the IMF Pakistan October 7 staff-level agreement estimated FY2026 growth of 3.6%, September headline inflation of approximately 10.3%, and gross reserves near $21.5 billion at end-September. The fourth EFF review and third RSF review had reached staff-level agreement only, pending IMF Executive Board approval as of the release. Pakistan’s fiscal years run July–June; IMF global growth figures refer to calendar years.
| Indicator | 2026 | 2027 | Important distinction |
|---|---|---|---|
| IMF world GDP growth | 3.1% | 3.4% | Calendar-year projection |
| IMF world headline inflation | 4.7% | 4.1% | Global estimate, not Pakistan CPI |
| WTO goods trade volume growth | 3.9% | 4.1% | Real volume, not nominal trade value |
| WTO commercial services volume growth | 3.3% | 6.4% | Conditional rebound, not guaranteed |
The World Bank June 2026 Global Economic Prospects provides an earlier comparison framework, but its publication date and methodology differ from the October IMF and WTO releases. A thoughtful analysis should compare like with like and should never treat projections as realized outcomes. For a Pakistan-focused story, the crucial question is how global conditions enter domestic economic life.
Why this story matters now
The WTO October 2026 executive summary says AI-enabling goods accounted for 47% of year-on-year growth in the value of world merchandise trade during the first half of 2026. That does not mean 47% of all merchandise trade was AI-related. It identifies a contribution to growth, and in nominal value terms. The same source notes that AI-enabling goods trade rose 67% year-on-year in that period. These figures show how a narrow technology cycle can make global trade appear stronger even as other sectors struggle.
Meanwhile the Reuters October 2026 IMF annual meetings reports persistent concern about global financial risks, geopolitical disruptions and the uneven sharing of AI gains. The Reuters October 2026 Asian growth describes a region where technology investment supports some exporters while energy costs and higher yields challenge others. Pakistan is therefore exposed simultaneously to a potential technology opportunity and to more conventional fuel, financing and trade vulnerabilities.
What higher global yields actually transmit
For what higher global yields actually transmit, A global rate increase affects Pakistan through risk appetite, dollar funding and the benchmark returns sought by international investors. The transmission is not one-to-one: country risk, reserve adequacy and domestic policy credibility can amplify or dampen it.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For what higher global yields actually transmit, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
How dollar strength reaches emerging markets
For how dollar strength reaches emerging markets, Domestic rates affect deposits, government securities and credit; international rates affect the opportunity cost of lending abroad. When both remain elevated, long-term private investment becomes harder to justify, particularly in sectors with weak margins.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For how dollar strength reaches emerging markets, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Debt servicing versus headline public debt
For debt servicing versus headline public debt, Currency forecasts should not be sold as certainty. A narrow exchange-rate target can obscure the variables that actually matter: export receipts, remittances, import payments, financing schedules and confidence.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For debt servicing versus headline public debt, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
How the State Bank balances competing priorities
For how the state bank balances competing priorities, A global rate increase affects Pakistan through risk appetite, dollar funding and the benchmark returns sought by international investors. The transmission is not one-to-one: country risk, reserve adequacy and domestic policy credibility can amplify or dampen it.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For how the state bank balances competing priorities, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Signals to monitor before assuming rate relief
For signals to monitor before assuming rate relief, Domestic rates affect deposits, government securities and credit; international rates affect the opportunity cost of lending abroad. When both remain elevated, long-term private investment becomes harder to justify, particularly in sectors with weak margins.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For signals to monitor before assuming rate relief, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Policy options: three alternative paths, not numerical forecasts
| Scenario | Assumptions | Implications for Pakistan | Early warning or confirmation |
|---|---|---|---|
| More favorable | Energy costs stabilize; export markets remain open; AI use generates measurable efficiency | Space for investment, steadier purchasing power and stronger services exports | Export orders, real income and private investment improve together |
| Central case | Global growth follows the broad institutional outlook; commodity and funding pressures fluctuate | Gradual recovery with uneven gains across sectors | Stable external balances without a broad productivity surge |
| Adverse | Energy disruptions persist; financing costs rise; AI investment is repriced | Imports become more costly, credit tighter and fiscal choices harder | Reserves, inflation expectations and financing costs weaken at once |
These are qualitative editorial scenarios, not probabilities assigned by an econometric model. Their value lies in clarifying which evidence would require an updated judgment. The IMF October 2026 World Economic Outlook explicitly emphasizes downside risks involving conflict, trade tension, debt and reassessment of AI expectations.
A practical action agenda
For policymakers, the first responsibility is to protect hard-won macroeconomic stability while removing barriers to productivity. Regulatory predictability, tax administration, targeted social protection and transparent energy decisions are more useful than shifting incentives that are impossible for businesses to plan around. The IMF Pakistan 2026 country report identifies revenue mobilization, reform of state enterprises, energy-sector viability and improvements in human capital as linked policy priorities.
For exporters, resilience means identifying where demand is growing, investing in reliable delivery and obtaining credible certifications. Export strategies should track volumes, domestic value added and customer retention; gross receipts alone do not disclose profitability. For small businesses, the practical priority is to map exposure to fuel, electricity, imports and foreign-exchange requirements and to stress-test cash flows before making expansion commitments.
For households, risk management begins with an affordable budget, attention to debt servicing and a realistic distinction between nominal wage gains and purchasing power. For workers, portable skills and credible training can expand options across changing industries. None of this makes external shocks harmless; it simply offers concrete ways to be less exposed.
How this analysis differs from generic global coverage
Major international reporting is indispensable for establishing what happened. The Reuters October 2026 WTO briefing emphasizes the boost from AI to merchandise trade and the pressure of geopolitical disruption. Institutional releases provide detailed projections. This article goes a step further by asking how those macroeconomic signals might translate into local import costs, export competitiveness, employment, household budgets and reform choices. It is an interpretation of attributed evidence, not a claim of exclusive interviews or original field reporting.
The difference is particularly relevant for Pakistan because a global technology boom may coincide with higher costs for countries that import fuel but do not manufacture the equipment in highest demand. No serious strategy should assume that a worldwide headline rate automatically delivers the same benefits locally.
Frequently asked questions
What is the IMF’s global growth forecast for 2027?
The IMF’s October 2026 World Economic Outlook projects 3.4% global GDP growth in 2027, following 3.1% in 2026. These are calendar-year forecasts and may be revised as new data becomes available. See the IMF October 2026 World Economic Outlook.
Is global inflation expected to fall in 2027?
Yes, the October IMF forecast projects global headline inflation easing from 4.7% in 2026 to 4.1% in 2027. That describes the world aggregate and does not imply that prices in Pakistan will fall in absolute terms.
Is Pakistan’s latest IMF financing already approved?
The 7 October 2026 IMF release announced staff-level agreement for the fourth EFF and third RSF reviews, subject to Executive Board approval. The release should not be described as a completed Board decision. See the IMF Pakistan October 7 staff-level agreement.
Will AI investment create jobs in Pakistan?
It could create demand for implementation, software services and specialist support, while also changing tasks in existing occupations. The result depends on skills, investment, electricity reliability and competitive access to customers. No credible source guarantees a particular employment gain.
Does the WTO predict rapid growth in all kinds of trade?
No. Its October outlook differentiates merchandise volume growth from commercial-services volume growth and notes uneven performance by sector and region. Read the WTO October 2026 executive summary.
What should Pakistani companies monitor through 2027?
Export order books, input costs, electricity reliability, financing terms, exchange-rate conditions and customer demand are more operationally useful than a single global growth figure. Businesses should compare these against their own cash flows and margins.
Conclusion: the decisive issue is transmission, not the headline
Global borrowing conditions can tighten even if Pakistan is making domestic progress. Higher foreign yields change the price and availability of capital and can complicate debt management and currency stability. The balance of risks is mixed: advanced technology can expand world production and trade, but it does not neutralize an energy shock or a financing squeeze. For Pakistan, policy credibility, internationally competitive exports and productivity-enhancing investment will determine how much of a fragile global expansion becomes better living standards at home.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Gold at the $4,000 Line: Possible December Fed Hike

Oil at $100+: Hormuz, a Qatari Peace Draft and the Iran Deadline

The Fed’s 10-2 Hold: Why Two Dissenters Wanted a Rate Hike

SBP Raises Policy Rate to 12%: What It Means for Your Loans, Savings and Business

IMF’s $1.2bn Staff-Level Deal: What Pakistan Promised on Surplus

Decoding the DBS–BCA Merger Rumour: Market Volatility, Strategic Realities

New Xbox Games October 26–30, 2026: Releases and Game Pass

Tokyo Disneyland Peter Pan’s Flight Closure: January–February 2027 Guide

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025