
Global Economy
The Knowledge Economy Revolution: Ten Ways Education Is Rewriting the Economic Destiny of Developing Nations

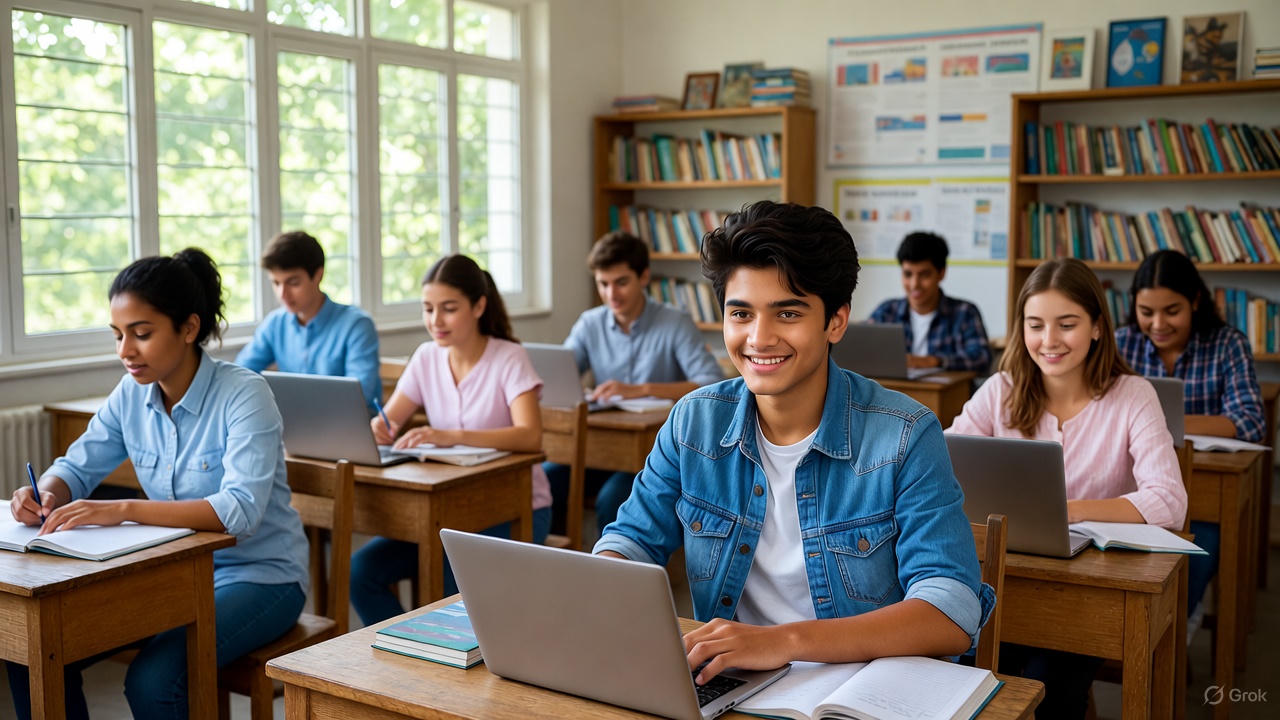
In a weathered classroom in Kigali, 23-year-old Grace Uwimana debugs Python code on a refurbished laptop—one of thousands distributed through Rwanda’s digital literacy initiative. Five years ago, she was contemplating a career in subsistence farming. Today, she leads a 15-person software team building agricultural technology solutions, earning eight times her country’s median income. Her transformation isn’t exceptional—it’s emblematic.
Grace’s journey mirrors a profound economic metamorphosis unfolding across the Global South. While developed economies grapple with automation anxiety and stagnant productivity, developing nations from Dhaka to Bogotá are systematically converting educational investments into knowledge economy infrastructure. According to the World Bank’s latest data, education generates a 9% increase in hourly earnings for every additional year of schooling globally—a return that reaches 15% in emerging markets. As knowledge economies now contribute at least 7% of global GDP and grow at approximately 10% annually, the question isn’t whether education drives economic transformation, but how developing nations can accelerate this conversion at scale.
This isn’t cheerleading for an inevitable future. The path from classroom to competitiveness is fraught with financing gaps, infrastructure deficits, and persistent inequalities. Yet the evidence from Rwanda’s 9.7% GDP growth in early 2024, Vietnam’s digital transformation, and India’s $283 billion IT sector tells a compelling story: education has become the primary mechanism through which developing nations build comparative advantage in the 21st century.
1. Closing the Digital Skills Gap Drives Tech Sector Employment
The most immediate impact of education investment appears in technology employment statistics. India’s IT-BPM sector, which employed just 2.8 million people in 2010, now sustains 5.4 million workers directly and contributes 7.5% to national GDP—approximately $194 billion in export revenue in fiscal year 2024. This didn’t happen by accident. India’s emphasis on STEM education, with IT graduates reaching 68.44% employability rates compared to 54% for traditional engineering fields, created a talent pipeline that global companies couldn’t ignore.
The correlation extends beyond India. Rwanda’s investment in digital literacy—targeting 60% of adults by 2024—has positioned the country to attract technology investments that seemed unthinkable a decade ago. The World Bank’s recent $200 million Priority Skills for Growth and Youth Empowerment project aims to provide 200,000 vulnerable youth with market-demanded digital skills. Early results show promise: participants in similar programs have seen income increases of 700-800% within five years of completing digital training.
Vietnam’s National Digital Transformation Programme projects 400 million job opportunities globally will be driven by digital innovations by 2035. By emphasizing digital skills from primary education through tertiary institutions, Vietnam positioned itself as a manufacturing and technology hub beyond China’s shadow. The payoff? GDP growth projected at 6% annually through 2026, with technology and services driving the expansion.
The skeptic might argue that technology jobs represent a tiny fraction of developing nation workforces. True—but they create multiplier effects. Every tech job generates approximately 4.3 additional jobs in supporting sectors, from logistics to hospitality. More critically, digital skills enable productivity improvements across traditional sectors. Kenyan farmers using mobile payment systems and agricultural apps demonstrate how basic digital literacy transforms even subsistence economies.
2. Innovation Ecosystems Flourish Where STEM Education Thrives
Patent applications and startup density provide harder metrics of innovation capacity. Countries that invested heavily in STEM education over the past two decades now harvest measurable innovation outputs. China’s transition from manufacturing hub to innovation powerhouse correlates directly with tertiary STEM enrollment that expanded from 1.4 million in 2000 to over 10 million today.
The pattern repeats at smaller scales. Rwanda’s emphasis on STEM—with “Tech Enabled STEM Teaching” programs incorporating virtual reality, gamification, and robotics—created conditions for startup ecosystems to emerge where none existed. The country now hosts innovation hubs like kLab, which has supported over 1,000 digital entrepreneurs, many focused on solving local challenges through technology.
India’s innovation metrics tell a similar story. The country ranks 39th in the Global Innovation Index 2024, climbing six positions in a single year. This improvement coincides with expanded higher education capacity and improved quality metrics. With over 76 crore citizens (760 million) connected to the internet—supported by some of the world’s lowest data costs at $0.12 per gigabyte—India created conditions where educated entrepreneurs could rapidly scale innovations.
The returns materialize in concrete outcomes. Bangalore, Hyderabad, and Pune now compete with Silicon Valley for certain categories of technology talent. This wasn’t inevitable—it resulted from decades of investment in Indian Institutes of Technology, engineering colleges, and technical training institutions that produced over 1.5 million engineering graduates annually by 2024.
Critics correctly note that many developing nation startups struggle with scaling and that brain drain remains persistent. Yet the trend line suggests improvement. Foreign direct investment in developing nation innovation increased 8.6% annually from 2002-2022, outpacing the 4.4% growth in total global FDI. Investors increasingly recognize that well-educated populations in emerging markets offer innovation opportunities previously unavailable.
3. Foreign Direct Investment Follows Human Capital Concentrations
Multinational corporations deploy capital where they find skilled workforces. This isn’t ideology—it’s arithmetic. A 2024 Kearney survey of 536 senior executives at global corporations found that talent and skill of labor pools ranked as the strongest factor attracting FDI to India and Mexico. The message: education infrastructure increasingly determines capital allocation decisions.
The numbers substantiate this logic. Emerging markets drew $430 billion in foreign direct investment in 2022. Countries with robust education systems captured disproportionate shares. Singapore’s emphasis on STEM education—with electronics engineering graduates directly supporting a $2 billion sector—explains why it received $140 billion in FDI in 2022 despite its small population.
Cambodia’s emergence as a top FDI destination for 2024 correlates with its education reforms and 6.1% projected GDP growth. The Philippines, ranking second in FDI momentum, benefited from its educated, English-speaking workforce and saw public and private investment reinforced by opening renewable energy sectors to foreign capital.
The mechanism is straightforward: companies prefer to invest where local managers, engineers, and technicians can operate sophisticated facilities. Ethiopia and Rwanda attracted significant manufacturing FDI partly because they invested heavily in technical and vocational education training (TVET). Rwanda’s Digital Skills for Employability program, targeting 10,000 young people with software development, cybersecurity, and data analysis training, directly responds to investor requirements.
The counterargument deserves consideration: FDI to emerging markets has faced headwinds, declining 9% to $841 billion in 2023, with major Asian markets experiencing a 12% drop. India saw a 47% decline in FDI inflows in 2023. However, this reflects macroeconomic conditions—rising interest rates, geopolitical tensions—rather than education capacity. The long-term trajectory remains clear: the most educated emerging markets capture FDI during expansions and weather contractions better than peers with weaker human capital foundations.
4. Export Diversification Follows Education-Driven Comparative Advantage
Developing economies historically exported commodities and low-skill manufactures. Education enables more sophisticated exports. India’s transformation from textile-focused to IT services exports—reaching $224 billion in FY25—demonstrates how tertiary education creates new export categories entirely.
The World Bank documents this pattern globally: education expenditure correlates with export complexity and diversification. Countries that invested 4-5% of GDP in education over sustained periods now export knowledge-intensive services, advanced manufactures, and technology solutions rather than primarily raw materials or simple manufactures.
Vietnam’s export profile shifted dramatically as education improved. Once dependent on agricultural exports, Vietnam now produces sophisticated electronics, with companies like Samsung establishing major manufacturing operations contingent on availability of trained engineers and technicians. The transformation required sustained investment in technical education—Vietnam trained over 2,000 teachers in digital skills, though challenges remain in rural areas.
Bangladesh provides another example. Its education reforms, particularly expansion of tertiary enrollment from 6% to 20% over two decades, enabled its pharmaceutical sector to compete globally. Bangladeshi manufacturers now export medications to 157 countries, a feat impossible without chemists, quality control specialists, and regulatory experts produced by university programs.
Trade skeptics note that global value chains remain dominated by advanced economies and China. True, but the gap narrows. Developing nations with strong education systems increasingly capture higher-value segments of global value chains. Mexico’s automotive engineers design components locally rather than simply assembling parts designed elsewhere. Indian software architects create original solutions rather than merely executing specifications from foreign clients.
5. Demographic Dividends Materialize Only With Education Investment
Developing nations possess young populations—a potential economic advantage if those populations acquire skills. Without education, youthful demographics become liabilities rather than assets. The contrast between countries that invested in education versus those that didn’t illuminates this reality starkly.
South Asia, home to the world’s largest youth population, faces divergent outcomes. India’s 18 million annual emigrants reflect both opportunity and challenge—many leave for better opportunities, but the educated workforce remaining drives domestic growth. India’s emphasis on skills development through initiatives like the Skill India Digital Hub aims to provide continuous learning in AI, machine learning, and automation.
Kenya, with 35.6% of youth aged 16-30 categorized as neither in employment, education, nor training (NEET) in 2022, demonstrates the cost of insufficient education investment. Rwanda, facing similar demographic pressures but investing aggressively in education, shows an alternative path. Its Vision 2050 explicitly targets becoming a “Globally Competitive Knowledge-based Economy,” with education as the primary mechanism.
The gender dimension matters enormously. Rwanda’s NEET rate shows stark disparities: 41% for young women versus 29.9% for young men. Educational initiatives targeting young women—like Rwanda’s Digital Skills for Employability program with its strong focus on female participation—directly address this gap. Research consistently shows that educating women generates higher returns than educating men in developing economies, with multiplier effects on health, family planning, and next-generation education.
Employment statistics reveal education’s impact. In India, salaried jobs—the most stable employment category—account for only one in five workers, or 130 million people. However, in urban areas where education levels are higher, half of all jobs are salaried, concentrated in manufacturing, education, health, trade, and technology. The correlation between education and stable employment couldn’t be clearer.
6. Spillover Effects Transform Healthcare and Agricultural Productivity
Education’s returns extend beyond the sectors we typically associate with knowledge economies. Healthcare and agriculture—traditionally low-productivity sectors in developing nations—experience transformative improvements when educational levels rise.
The mechanism operates through multiple channels. Educated healthcare workers improve diagnostic accuracy and treatment outcomes. Research from the World Bank indicates that education correlates with significant reductions in infant mortality, maternal death rates, and disease prevalence. Countries that achieved universal primary education saw healthcare outcomes improve even before healthcare infrastructure investments took effect.
Agriculture demonstrates even more dramatic transformations. In Ethiopia, where 98% of agricultural workers haven’t completed primary school, productivity remains stagnant. Contrast this with India, where educated farmers increasingly use precision agriculture, weather forecasting apps, and modern farming techniques. The productivity gap between educated and uneducated farmers in the same regions often exceeds 200%.
Kenya’s agricultural transformation, supported by $500 million in pharmaceutical FDI from companies like Moderna, illustrates how education enables sectoral convergence. Vaccine production requires sophisticated cold chain logistics, quality control, and regulatory compliance—capabilities that emerge only with educated workforces.
Vietnam’s success in agricultural technology exports similarly reflects its education investments. Vietnamese agricultural engineers develop irrigation systems, develop crop varieties, and create supply chain solutions exported throughout Southeast Asia—capabilities unimaginable without sustained education investment.
The cross-sectoral learning matters profoundly. Engineers trained for IT sectors apply problem-solving skills to agricultural challenges. Healthcare workers with data analysis training improve epidemiological surveillance. These spillovers represent education’s compounding returns—benefits that narrow cost-benefit analyses miss entirely.
7. Gender Equality Through Education Unlocks Economic Participation
Perhaps no single intervention generates higher returns than educating women in developing economies. The World Bank estimates returns to female education in developing countries often exceed 15% annually—higher than returns to male education—yet girls and women face persistent barriers to educational access.
The economic logic is compelling. Educated women participate in formal labor markets at significantly higher rates. They earn substantially more than uneducated women—the wage premium for tertiary education exceeds 60% in most developing nations. They have fewer children, space births further apart, and invest more in their children’s education, creating intergenerational benefits.
Countries that achieved gender parity in education reaped measurable economic rewards. Vietnam’s emphasis on gender equality in education correlates with its manufacturing competitiveness—factory managers cite the educated female workforce as a key advantage. Bangladesh’s garment sector, which employs predominantly women and generates $40 billion in annual exports, became globally competitive partly because educational improvements enabled women to enter the workforce.
Rwanda’s aggressive pursuit of gender equality in education—with explicit targets in programs like Priority Skills for Growth and Youth Empowerment—reflects understanding that excluding women from education means foregoing roughly half of potential human capital. The country’s 9.7% GDP growth in 2024 coincides with near-gender-parity in secondary and tertiary enrollment.
The return on investment statistics tell the story quantitatively. The World Bank calculates that the public net financial returns from tertiary education average $127,000 for men versus $60,600 for women in OECD countries—but this gap reflects persistent discrimination and opportunity constraints rather than inherent differences in education’s productivity. In developing countries where discrimination gradually diminishes, returns to female education increasingly match or exceed returns to male education.
India’s persistently low female labor force participation—four in ten working-age women versus eight in ten men—represents massive foregone economic output. If India achieved female labor force participation rates comparable to China or Vietnam, GDP would increase by an estimated 25-30%. Education represents the most powerful lever for achieving this.
8. Climate Adaptation and Green Technology Require Educated Workforces
The climate crisis demands technological solutions that developing nations must both adopt and increasingly produce. This transition requires educated workforces capable of installing solar panels, maintaining wind turbines, designing climate-resilient infrastructure, and managing increasingly complex environmental systems.
Green FDI flows to emerging markets demonstrate the connection between education and climate action. Research from the IMF shows that closing the climate policy gap between the average developing economy and the average advanced economy would triple green FDI inflow-to-GDP ratios. However, these investments materialize only where educated workforces exist to implement green technologies.
Kenya’s $2.29 billion green hydrogen project in Mombasa, announced by Dubai-based AMEA Power, exemplifies this dynamic. The investment hinges on availability of engineers, technicians, and project managers capable of operating cutting-edge renewable energy infrastructure. Kenya’s investments in STEM education directly enabled this opportunity.
The Philippines’ opening of renewable energy sectors to foreign investment generated significant FDI partly because its educated workforce could staff renewable projects. Countries with weak education systems cannot credibly offer to host green manufacturing or renewable energy installations regardless of natural resource endowments or favorable geography.
India’s IndiaAI Mission, with $1.2 billion allocated for AI development, positions the country to develop climate solutions at scale. AI applications in agriculture, energy management, and climate modeling require educated workers across multiple disciplines. India’s IT sector provides the talent foundation for these initiatives.
The critique that developing nations shouldn’t bear climate transition costs has merit. However, green technology represents economic opportunity, not merely obligation. Countries with educated populations can manufacture solar panels, wind turbines, and electric vehicles for export while simultaneously reducing domestic emissions. The renewable energy sector is projected to create millions of jobs globally—disproportionately benefiting nations that invested in relevant education.
9. Governance Quality Improves With Education, Attracting Investment
Corruption indices and governance quality metrics consistently correlate with education levels. The mechanism operates through multiple channels: educated citizens demand better governance, educated bureaucrats implement policies more effectively, and educated business leaders operate more transparently.
Research published in the Journal of the Knowledge Economy demonstrates that education expenditure improves labor market outcomes only when institutional quality reaches sufficient thresholds. Conversely, improving education strengthens institutions. This creates a virtuous cycle: education improves governance, which attracts investment, which funds further education.
Rwanda’s dramatic transformation from post-genocide chaos to relative stability and rapid growth illustrates this dynamic. Sustained education investment, combined with governance reforms, created conditions for economic development. The country’s ability to attract $200 million from the World Bank for skills development reflects investor confidence in Rwanda’s institutional capacity—confidence grounded partly in its educated bureaucracy and leadership.
Singapore’s trajectory—from developing nation to advanced economy in a single generation—demonstrates how education and governance reinforce each other. Its strategic focus on STEM education created a skilled workforce, while good governance created stable conditions for leveraging that workforce. The result: $140 billion in FDI in 2022, a sum that exceeds many much larger economies.
India’s complex federal system creates governance challenges, but states with stronger education systems consistently outperform peers on corruption and institutional quality metrics. Karnataka and Maharashtra, home to major IT hubs, demonstrate higher governance quality than less-educated states—partly because educated populations demand accountability.
The counterargument—that autocratic regimes sometimes deliver rapid educational improvements—has historical precedent. However, long-term evidence suggests that sustained education gains require governance systems responsive to citizen demands. Education creates pressures for political participation and transparency that autocratic systems ultimately cannot accommodate.
10. Global Value Chain Integration Follows Education-Driven Capabilities
The most sophisticated global value chains—semiconductors, aerospace, pharmaceuticals, advanced manufacturing—concentrate in countries with highly educated workforces. Developing nations that achieved sufficient education levels now participate in these chains, capturing higher-value activities.
Mexico’s automotive sector illustrates this progression. Initially focused on basic assembly, Mexican facilities increasingly handle design, engineering, and advanced manufacturing because of investments in technical education. Major automakers now locate R&D facilities in Mexico, confident that local engineers can handle sophisticated development work.
Vietnam’s integration into electronics supply chains follows similar logic. Companies like Samsung didn’t just seek cheap labor—they required educated workers capable of operating automated production lines and quality control systems. Vietnam’s education investments made this feasible, transforming it into a major electronics exporter.
The semiconductor sector provides perhaps the clearest example. India’s recent emergence as a potential semiconductor hub reflects both government incentives and availability of educated engineers. The Production-Linked Incentive scheme for IT Hardware generated Rs. 10,014 crore ($1.14 billion) in production as of December 2024, but these investments materialized only because educated workers existed to staff facilities.
Research from McKinsey Global Institute identifies 18 “future arenas” that could account for one-third of GDP growth by 2040, including AI services, semiconductors, robotics, and advanced manufacturing. These sectors demand educated workforces. Countries that invested in education over the past two decades position themselves to capture these opportunities; those that didn’t face exclusion from the most dynamic sectors of the global economy.
The critique that global value chains remain dominated by advanced economies and China has validity. However, the composition of participants evolves. Twenty years ago, developing nations beyond a few Asian tigers captured negligible shares of sophisticated value chains. Today, India, Vietnam, Mexico, and others participate meaningfully. Education enabled this transformation.
The 2030 Inflection Point
These ten dynamics converge toward a conclusion that should alarm complacent policymakers and energize reformers: education increasingly determines which nations prosper in coming decades. The World Bank’s projections that developing economy growth will hold steady at 4% through 2026 masks enormous variation—between countries that invested in education and those that didn’t.
The arithmetic is unforgiving. The World Bank estimates a $97 billion annual financing gap exists for achieving Sustainable Development Goal 4 (quality education) by 2030, with Sub-Saharan Africa accounting for $70 billion of this shortfall. Countries that close these gaps through domestic resource mobilization, innovative financing, and improved efficiency will build knowledge economy capabilities. Those that don’t will watch their educated citizens emigrate to countries that did.
The brain drain phenomenon—with India losing 18 million people annually, close to double any other nation—reflects both the success of education investments and the challenge of creating sufficient domestic opportunities for educated workers. Countries must not only educate populations but also create economic conditions that retain talent.
The equity dimension matters profoundly. If education access remains concentrated among elites, knowledge economy benefits will similarly concentrate. Rwanda’s emphasis on reaching 200,000 vulnerable youth through skills programs recognizes this reality. Vietnam’s efforts to extend digital education to rural areas, while facing infrastructure challenges, similarly acknowledge that broad-based education creates more robust economic transformation than elite-focused systems.
The quality versus quantity debate persists, but the evidence increasingly suggests both matter. Countries need more people with basic literacy and numeracy, more with secondary education, more with tertiary credentials, and more with advanced technical skills. The World Bank’s finding that 9% of returns accrue for each additional year of schooling indicates that marginal gains accumulate at all education levels.
The financing mechanisms will require innovation beyond traditional models. The World Bank’s first debt-for-education swap with Côte d’Ivoire demonstrates one approach—reducing costly debt to free resources for school investment. Public-private partnerships, particularly in technical education, offer another path. India’s industry-led Skills Councils, connecting education providers with employer demands, show how private sector engagement can improve relevance.
The measurement challenge persists. Global education spending increased steadily over the past decade, but spending per child stagnated or declined in many low-income countries with growing populations. Efficiency matters as much as total expenditure. Evidence from Brazil, Colombia, Indonesia, and Uganda shows ways to boost student achievement through budget-neutral policies like granting spending autonomy to subnational governments and reducing teacher absenteeism.
The Irreversible Momentum
Perhaps the most remarkable aspect of education’s role in knowledge economy development is its compounding nature. Unlike infrastructure that depreciates or commodities that exhaust, education creates lasting capabilities that strengthen over time. A well-educated 25-year-old contributes productively for four decades, mentors younger workers, and educates the next generation.
This compounding creates path dependencies. Rwanda’s education investments over the past 15 years position it to attract FDI, develop innovation capacity, and integrate into global value chains over the next 15 years. These developments will generate resources for further education investment, creating a virtuous cycle. Countries that delayed education investment face increasingly difficult catch-up challenges as leaders accumulate advantages.
The geopolitical implications merit attention. As knowledge economies grow to represent ever-larger shares of global GDP, economic power will shift toward nations that successfully built human capital. This represents a more fundamental transformation than shifts in manufacturing capacity or resource endowments. Education-driven competitive advantages persist longer and prove harder to replicate than advantages based on low wages or natural resource deposits.
The question facing policymakers in 2025 isn’t whether education drives knowledge economy development—the evidence overwhelmingly confirms this relationship. The question is whether countries can summon the political will and mobilize the resources to invest adequately and equitably in education over sustained periods. The returns justify the investment by every financial metric, but education requires patient capital and long time horizons often incompatible with political cycles.
For developing nations, the imperative is clear: invest in education or accept permanent second-tier economic status. For international financial institutions, the priority equally obvious: finance education with the same urgency previously reserved for infrastructure, understanding that education represents the most productive infrastructure investment available. For individuals in developing nations, the message is straightforward: education remains the most reliable path to economic advancement and personal opportunity.
The knowledge economy revolution doesn’t eliminate geography, history, or other structural factors shaping economic outcomes. But it provides a mechanism through which nations can transcend historical disadvantages and create new competitive advantages. Rwanda, Vietnam, Bangladesh, and others demonstrate this possibility. Their success stories share a common thread: sustained commitment to education as the foundation for economic transformation.
As we approach 2030, the divergence between educated and undereducated developing nations will likely accelerate. The fourth industrial revolution, artificial intelligence, and accelerating technological change reward education more than previous economic transitions. Countries that secured educational foundations will adapt and thrive. Those that didn’t will struggle to participate meaningfully in the global economy’s most dynamic sectors.
Grace Uwimana in Kigali, debugging code on her laptop, represents not just Rwanda’s transformation but a template available to any nation willing to invest systematically in its people. The technology changes, the specific skills evolve, but the fundamental equation remains constant: education transforms human potential into economic capability, and economic capability determines prosperity in the knowledge economy that increasingly defines our era.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The central development problem of 2026 is not simply a shortage of money. It is the gap between where finance is most urgently needed and where private and public capital is most willing to go. Many developing economies face expensive debt, exposure to climate shocks and large infrastructure needs at the same time that investors concentrate on a smaller group of countries and commercially familiar projects.
The UNCTAD World Investment Report 2026 says global FDI rose 6% to $1.6 trillion in 2025, but developing economies recorded only 2% growth, to $901 billion. More than 80% of global inflows went to the 20 largest recipients. This concentration matters because an aggregate recovery in investment can conceal a deterioration in access for smaller, poorer and climate-exposed countries.
Key takeaways
- Global investment has recovered unevenly; a handful of major recipients capture much of the growth.
- High sovereign yields increase the cost of financing long-lived infrastructure projects.
- Climate-finance goals are international commitments, not proof that money has already been delivered.
- Public guarantees and blended finance can mobilize investment but create fiscal risks if poorly designed.
- Pakistan and other climate-vulnerable economies need bankable projects, transparent procurement and financing terms that fit public balance sheets.
The paradox of rising global investment
A stronger headline FDI figure suggests that multinational companies have regained confidence. Yet location and purpose matter. The UNCTAD report shows that strategic sectors—including AI infrastructure, semiconductors, critical minerals and energy-transition technologies—accounted for 44% of announced greenfield project values in 2025, compared with 16% in 2020.
That does not mean the same share of projects are operating, or that employment and skill transfer have already materialized. Greenfield announcements refer to planned investment. The resulting development benefits depend on implementation, workforce integration, supplier networks and local regulatory conditions.
A large capital-intensive project can raise investment totals without producing substantial local employment. By contrast, a smaller power-distribution upgrade or irrigation investment might have broader productivity effects. Development policy must therefore be guided by outcomes, not project headline values.
How debt turns an investment gap into a development trap
A government may need to finance flood protection, transport networks, schools and electricity grids. When sovereign borrowing yields rise, debt servicing claims a greater share of future tax revenue. The government may then postpone maintenance or investment, reducing growth capacity and weakening the very revenue prospects that underpin debt sustainability.
This is a feedback loop, not a certainty for every borrowing country. The IMF’s October 2026 analysis of sovereign yields warns that high debt makes fiscal balances and market interest rates more sensitive to each other. Its April Fiscal Monitor reported global public debt just below 94% of GDP in 2025, projected to reach 100% by 2029 in that forecast vintage.
Global averages should not be used to label all developing economies insolvent. Debt sustainability depends on borrowing currency, maturity, interest costs, export earnings, domestic savings, tax capacity and creditor terms. A country with long-maturity concessional loans can have a very different risk profile from one refinancing short-term foreign-currency obligations at market rates.
For development projects, repayment risk can be even more nuanced. A new port may generate fees in foreign currency; an irrigation scheme may generate valuable social and productivity returns but relatively little direct cash flow. Both can be economically justified, yet they require different financing designs.
Climate finance: targets versus disbursements
At COP29 in 2024, countries agreed on a new climate-finance goal of at least $300 billion annually by 2035 for developing countries, with developed countries taking the lead, and a broader effort to scale total finance to $1.3 trillion per year by 2035. These commitments are described by the UN Climate Change secretariat.
The distinction between an announced goal and money actually disbursed cannot be overstated. A country facing flood risk in 2026 cannot pay for an embankment with a target set for 2035. It needs project preparation, agreed terms, implementation capacity and accessible funding now.
Finance also takes different forms: grants, concessional loans, guarantees, private investment and domestic budget allocations. A dollar of grant funding does not impose the same repayment burden as a dollar borrowed at commercial rates. Comparing climate-finance totals without identifying their form can mislead the public about the net benefit to recipients.
Adaptation is especially challenging because many protective projects generate benefits by avoiding future losses rather than collecting revenue. Protecting a town from flooding can be valuable to society while offering no direct income stream to repay a private investor. That is a strong case for carefully designed public or concessional funding, not evidence that the project is unproductive.
Four finance tools, four different obligations
| Instrument | Appropriate use | Advantage | Main caution |
|---|---|---|---|
| Grant | Socially essential, low-revenue adaptation | No debt repayment | Limited availability and donor conditions |
| Concessional loan | Infrastructure with public benefits | Lower-cost, longer-tenor finance | Still adds obligations |
| Public guarantee | Partially de-risking a viable private project | Can attract capital | Creates contingent government liability |
| Commercial investment | Projects with credible cash flows | Mobilizes private expertise and funds | Return requirements may be incompatible with affordability |
Original comparison. Appropriate financing depends on project economics and sovereign capacity.
A well-designed programme matches the financing instrument to a project’s cash flows and social returns. Governments should not ask commercial investors to deliver unremunerated public goods, nor should they use scarce grants to subsidize projects that would have proceeded profitably anyway.
The problem of bankability
A project can be economically sensible but financially unready. Investors want to know who owns the land, which authority sets tariffs, what happens if construction is delayed, whether contracts are enforceable and how foreign exchange can be accessed. Without answers, the cost of financing rises or the investment does not proceed.
Project preparation therefore deserves more attention than it receives. Reliable feasibility studies, credible demand forecasts, environmental safeguards, procurement transparency and clear risk allocation are themselves forms of economic infrastructure. They make public money more effective and reduce the need to compensate financiers for avoidable uncertainty.
The UNCTAD investment analysis emphasizes whether international investment builds productive capacity, jobs, skills and technology transfer. Those are better metrics of development success than the number of investment memoranda signed.
The climate–debt dilemma is also a timing dilemma
A flood barrier must be built before the storm. Drought-resistant irrigation must be maintained before harvest conditions deteriorate. Yet governments with financing constraints may postpone such investment because its payoff is uncertain in timing while the upfront cost is immediate and politically visible.
This creates a bias toward emergency relief after a disaster rather than resilience beforehand. International institutions can help by offering longer-maturity finance, technical support, credible insurance mechanisms and rapid access to grants when shocks occur. But financing arrangements should be published and independently scrutinized, especially when guarantees and contingent obligations are involved.
The UN DESA policy brief on the Middle East conflict and development finance underlines how geopolitical and energy shocks can reduce the room available for development investment. A country paying more for imported fuel has fewer funds left for climate protection, even before the next flood or drought arrives.
Pakistan: making resilience investable without mortgaging the future
Pakistan is exposed to external energy and financing shocks while facing major needs in irrigation, drainage, flood protection and electricity-sector reform. The IMF’s October 7 Pakistan assessment says reforms supported by the Resilience and Sustainability Facility include climate-aware public investment planning and disaster-risk financing. It reports a staff-level agreement, subject to Executive Board approval—not an automatic release of funds.
Three practical steps would improve outcomes. First, rank projects by avoided economic loss and realistic operating costs, not political visibility. Second, publish the full fiscal exposure of guarantees and contracts. Third, build local capability to maintain infrastructure after its ribbon-cutting moment. Climate resilience fails when maintenance is unfunded or responsibilities are fragmented between agencies.
Pakistan should also treat export growth and climate investment as complementary goals. A more reliable electricity network and less flood-prone logistics system can make businesses more productive as well as more resilient. The benefit is not confined to future disasters; it shows up in fewer outages, better delivery and lower uncertainty today.
A five-question test for every financing pledge
- Is the funding approved and disbursable, or only politically announced?
- Is it a grant, loan, guarantee or expected private investment—and who ultimately pays?
- Which institution owns implementation, procurement and subsequent maintenance?
- How will results be measured in employment, resilience, productivity or emissions?
- Could repayment or foreign-currency obligations crowd out essential spending later?
The point is not to reject international funding. It is to distinguish investment that expands development capacity from financing that merely moves risk into the future. Transparency helps lenders as well as citizens by reducing costly ambiguity.
Risks and uncertainties
FDI data are revised and announced projects may not be completed. Climate-finance accounting differs across sources and instruments. Borrowing costs can rise or fall quickly, and physical climate losses are difficult to forecast precisely. No financing mechanism eliminates governance risk; concessional funds can still be misallocated. A credible assessment must use country-level debt profiles and project-level cash flows rather than infer individual conclusions from global aggregate figures.
Frequently asked questions
Is global FDI increasing in 2026?
UNCTAD reports a rise in global FDI during 2025 in its 2026 report. That is historical data, not a statement that every country experienced an increase in 2026.
Why do poorer countries struggle to attract investment?
Financing costs, infrastructure constraints, market size, regulatory uncertainty and project preparation can all affect investor decisions.
Is the $300 billion climate-finance goal already being paid annually?
No. The COP29 goal concerns annual finance by 2035; actual commitments and disbursements must be measured separately.
What is concessional finance?
Finance on more favourable terms than typical commercial borrowing, often involving lower interest rates or longer repayment periods.
Can climate projects increase debt risk?
Yes, if financed with unsuitable loans or guarantees; but well-designed investments can also reduce losses and strengthen productivity.
What should Pakistan prioritize?
High-value resilience projects, transparent financing terms, credible maintenance plans and export- and energy-related productivity gains.
Conclusion
The investment divide cannot be closed through pledges alone. Developing economies need capital that arrives on viable terms and builds useful assets, while financiers need transparent projects and credible repayment structures. The most important test of the global development system in 2026 is whether it can channel resources toward genuine resilience without making vulnerable countries more financially fragile.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The global Banking growth is becoming more uneven, capital is increasingly sensitive to financing costs, and investors must distinguish a convincing story from an investable price. This guide focuses on research methods and risks rather than predictions of guaranteed returns. The IMF October 2026 outlook projects 3.1% global growth and 4.7% inflation for 2026, while the IMF financial-stability assessment warns that market resilience coexists with important vulnerabilities.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind global banking trends 2026 is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
Digital banks are extending beyond borders
Technology can reduce the need to duplicate large physical branch networks, but banking remains subject to local licensing, deposit protection, consumer law and capital rules. Cross-border scale is a business model, not a regulatory exemption. Readers should distinguish a licensed bank from an e-money provider, broker or unregulated payments application. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Artificial intelligence in credit and fraud
Banks use machine learning for transaction screening, fraud detection, service operations and risk analysis. The operational promise is significant, but opaque credit models can create unfair outcomes, and false-positive fraud alerts can disrupt customers. Model governance requires testing, human accountability, explainability and correction routes. Customer consent does not remove every data-protection obligation. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Cybersecurity is now systemic finance risk
An attack against a large processing vendor can affect many institutions simultaneously. The IMF’s October 2026 stability assessment identifies sophisticated cyber threats alongside sovereign-yield and AI valuation shocks. Banks should test recovery procedures, third-party concentration, authentication controls and incident communications, not merely purchase security software. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Compliance: technology must support judgment
Anti-money-laundering monitoring, sanctions screening and know-your-customer processes are increasingly automated. False matches and poor data can cause excessive account restrictions, while under-detection carries serious legal exposure. Institutions need measurable controls, independent audits and escalation channels. The Financial Stability Board provides international coordination context but rules vary by jurisdiction. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
What Pakistani customers and banks should do
Customers should verify a provider’s licensing status, understand complaint mechanisms, enable strong authentication and never disclose one-time passcodes. Financial firms need resilient payment systems, staff training and clear consent practices. Track SBP circulars for locally applicable requirements rather than extrapolating foreign regulations to Pakistan. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global growth is not the same as broad prosperity. Pakistan’s outcomes will depend less on the global average than on the channels through which external demand, energy, financing, and technology influence local firms. This feature explains the mechanisms, risks and practical decisions that matter through 2027, with particular attention to Pakistan’s different exposure to energy prices, external financing, global trade and AI investment.
At a glance
- World output is forecast to rise, but opportunities and costs are uneven across countries.
- Global inflation forecasts do not predict household prices in Pakistan.
- The AI capital expenditure cycle lifts trade in electronics but may not translate into productivity gains everywhere.
- Pakistan’s IMF staff-level agreement is a milestone, not final Board approval.
- Stronger exports, competitive energy, fiscal credibility and skills are essential to durable growth.
The verified starting point: what the numbers actually say
The IMF October 2026 World Economic Outlook projects global growth of 3.1% in calendar 2026 and 3.4% in calendar 2027, alongside global headline inflation of 4.7% and 4.1%, respectively. Its statistical cutoff is 1 October 2026. The WTO October 2026 trade outlook projects merchandise trade volume growth of 3.9% in 2026 and 4.1% in 2027, versus commercial-services trade volume growth of 3.3% and 6.4%. These are forecasts from different statistical systems, not interchangeable growth measures.
For Pakistan, the IMF Pakistan October 7 staff-level agreement estimated FY2026 growth of 3.6%, September headline inflation of approximately 10.3%, and gross reserves near $21.5 billion at end-September. The fourth EFF review and third RSF review had reached staff-level agreement only, pending IMF Executive Board approval as of the release. Pakistan’s fiscal years run July–June; IMF global growth figures refer to calendar years.
| Indicator | 2026 | 2027 | Important distinction |
|---|---|---|---|
| IMF world GDP growth | 3.1% | 3.4% | Calendar-year projection |
| IMF world headline inflation | 4.7% | 4.1% | Global estimate, not Pakistan CPI |
| WTO goods trade volume growth | 3.9% | 4.1% | Real volume, not nominal trade value |
| WTO commercial services volume growth | 3.3% | 6.4% | Conditional rebound, not guaranteed |
The World Bank June 2026 Global Economic Prospects provides an earlier comparison framework, but its publication date and methodology differ from the October IMF and WTO releases. A thoughtful analysis should compare like with like and should never treat projections as realized outcomes. For a Pakistan-focused story, the crucial question is how global conditions enter domestic economic life.
Why this story matters now
The WTO October 2026 executive summary says AI-enabling goods accounted for 47% of year-on-year growth in the value of world merchandise trade during the first half of 2026. That does not mean 47% of all merchandise trade was AI-related. It identifies a contribution to growth, and in nominal value terms. The same source notes that AI-enabling goods trade rose 67% year-on-year in that period. These figures show how a narrow technology cycle can make global trade appear stronger even as other sectors struggle.
Meanwhile the Reuters October 2026 IMF annual meetings reports persistent concern about global financial risks, geopolitical disruptions and the uneven sharing of AI gains. The Reuters October 2026 Asian growth describes a region where technology investment supports some exporters while energy costs and higher yields challenge others. Pakistan is therefore exposed simultaneously to a potential technology opportunity and to more conventional fuel, financing and trade vulnerabilities.
Why the headline growth rate hides divergence
For why the headline growth rate hides divergence, Growth averages blur distribution. A country manufacturing sought-after electronics can gain from a technology upcycle while an energy importer faces a larger fuel invoice. That contrast explains why Pakistan needs an exposure-weighted reading of international forecasts rather than simply celebrating a higher headline GDP projection.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For why the headline growth rate hides divergence, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Pakistan’s four exposure channels
For pakistan’s four exposure channels, The most useful indicator is not one number but a sequence: orders received by exporters, import bills, financial inflows, electricity charges and jobs created. These measures reach families at different speeds, which is why apparently stable GDP figures can coexist with a sense of economic pressure.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For pakistan’s four exposure channels, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
What the latest IMF agreement does and does not mean
For what the latest imf agreement does and does not mean, Economic resilience is the capacity to manage adverse shocks without repeatedly disrupting investment and consumption. Predictable policy, transparent fiscal choices and adequate external liquidity matter alongside short-term growth acceleration.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For what the latest imf agreement does and does not mean, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
What businesses should prepare for
For what businesses should prepare for, Growth averages blur distribution. A country manufacturing sought-after electronics can gain from a technology upcycle while an energy importer faces a larger fuel invoice. That contrast explains why Pakistan needs an exposure-weighted reading of international forecasts rather than simply celebrating a higher headline GDP projection.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For what businesses should prepare for, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
The policy choices that determine resilience
For the policy choices that determine resilience, The most useful indicator is not one number but a sequence: orders received by exporters, import bills, financial inflows, electricity charges and jobs created. These measures reach families at different speeds, which is why apparently stable GDP figures can coexist with a sense of economic pressure.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For the policy choices that determine resilience, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Policy options: three alternative paths, not numerical forecasts
| Scenario | Assumptions | Implications for Pakistan | Early warning or confirmation |
|---|---|---|---|
| More favorable | Energy costs stabilize; export markets remain open; AI use generates measurable efficiency | Space for investment, steadier purchasing power and stronger services exports | Export orders, real income and private investment improve together |
| Central case | Global growth follows the broad institutional outlook; commodity and funding pressures fluctuate | Gradual recovery with uneven gains across sectors | Stable external balances without a broad productivity surge |
| Adverse | Energy disruptions persist; financing costs rise; AI investment is repriced | Imports become more costly, credit tighter and fiscal choices harder | Reserves, inflation expectations and financing costs weaken at once |
These are qualitative editorial scenarios, not probabilities assigned by an econometric model. Their value lies in clarifying which evidence would require an updated judgment. The IMF October 2026 World Economic Outlook explicitly emphasizes downside risks involving conflict, trade tension, debt and reassessment of AI expectations.
A practical action agenda
For policymakers, the first responsibility is to protect hard-won macroeconomic stability while removing barriers to productivity. Regulatory predictability, tax administration, targeted social protection and transparent energy decisions are more useful than shifting incentives that are impossible for businesses to plan around. The IMF Pakistan 2026 country report identifies revenue mobilization, reform of state enterprises, energy-sector viability and improvements in human capital as linked policy priorities.
For exporters, resilience means identifying where demand is growing, investing in reliable delivery and obtaining credible certifications. Export strategies should track volumes, domestic value added and customer retention; gross receipts alone do not disclose profitability. For small businesses, the practical priority is to map exposure to fuel, electricity, imports and foreign-exchange requirements and to stress-test cash flows before making expansion commitments.
For households, risk management begins with an affordable budget, attention to debt servicing and a realistic distinction between nominal wage gains and purchasing power. For workers, portable skills and credible training can expand options across changing industries. None of this makes external shocks harmless; it simply offers concrete ways to be less exposed.
How this analysis differs from generic global coverage
Major international reporting is indispensable for establishing what happened. The Reuters October 2026 WTO briefing emphasizes the boost from AI to merchandise trade and the pressure of geopolitical disruption. Institutional releases provide detailed projections. This article goes a step further by asking how those macroeconomic signals might translate into local import costs, export competitiveness, employment, household budgets and reform choices. It is an interpretation of attributed evidence, not a claim of exclusive interviews or original field reporting.
The difference is particularly relevant for Pakistan because a global technology boom may coincide with higher costs for countries that import fuel but do not manufacture the equipment in highest demand. No serious strategy should assume that a worldwide headline rate automatically delivers the same benefits locally.
Frequently asked questions
What is the IMF’s global growth forecast for 2027?
The IMF’s October 2026 World Economic Outlook projects 3.4% global GDP growth in 2027, following 3.1% in 2026. These are calendar-year forecasts and may be revised as new data becomes available. See the IMF October 2026 World Economic Outlook.
Is global inflation expected to fall in 2027?
Yes, the October IMF forecast projects global headline inflation easing from 4.7% in 2026 to 4.1% in 2027. That describes the world aggregate and does not imply that prices in Pakistan will fall in absolute terms.
Is Pakistan’s latest IMF financing already approved?
The 7 October 2026 IMF release announced staff-level agreement for the fourth EFF and third RSF reviews, subject to Executive Board approval. The release should not be described as a completed Board decision. See the IMF Pakistan October 7 staff-level agreement.
Will AI investment create jobs in Pakistan?
It could create demand for implementation, software services and specialist support, while also changing tasks in existing occupations. The result depends on skills, investment, electricity reliability and competitive access to customers. No credible source guarantees a particular employment gain.
Does the WTO predict rapid growth in all kinds of trade?
No. Its October outlook differentiates merchandise volume growth from commercial-services volume growth and notes uneven performance by sector and region. Read the WTO October 2026 executive summary.
What should Pakistani companies monitor through 2027?
Export order books, input costs, electricity reliability, financing terms, exchange-rate conditions and customer demand are more operationally useful than a single global growth figure. Businesses should compare these against their own cash flows and margins.
Conclusion: the decisive issue is transmission, not the headline
Global growth is not the same as broad prosperity. Pakistan’s outcomes will depend less on the global average than on the channels through which external demand, energy, financing, and technology influence local firms. The balance of risks is mixed: advanced technology can expand world production and trade, but it does not neutralize an energy shock or a financing squeeze. For Pakistan, policy credibility, internationally competitive exports and productivity-enhancing investment will determine how much of a fragile global expansion becomes better living standards at home.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The Global South: Debt, Climate Finance and Investment in 2026

Energy Security Is the New Economic Security

Can Global Tourism Survive Geopolitical Shocks?

Global Maritime Hegemony: How China Secured Over 81% of All New Shipbuilding Orders

The Coming Battle Over AI, Jobs and Wages

Why Developing Economies Face a Sharper Inflation Problem

The New Geography of Trade: Are Supply Chains Coming Home?

Is AI Saving Global Growth or Creating the Next Bubble?

Global Banking Trends 2026: Digital Banks, AI and Compliance

Gold vs US Dollar vs Bitcoin in 2026: Inflation Hedge Compared

How Global Interest Rates Affect Savings, Loans and Investments

How to Invest During High Inflation: A Global Guide

Best Global Stocks to Watch in 2026: Four Sectors to Research

Pakistan’s 2027 Growth Strategy: Exports, AI, Energy and Jobs

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

World’s Largest Economies: Ranking the Top Global Powers

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025