
Analysis
Gold and Silver Slump Deepens: Why the Precious Metals Crash is Rattling Global Equities After a Record Rally

The glittering ascent of gold and silver—metals that for millennia have served as humanity’s ultimate stores of value—has come crashing down with a ferocity not seen in generations. As of February 2, 2026, spot gold has plummeted approximately 5-10% from last week’s record high of $5,600 per ounce, now trading in the $4,500-$4,700 range. Silver’s collapse has been even more dramatic: down 10-16% to $78-$82 per ounce after Friday’s catastrophic 30%+ single-day drop from $120 highs—the steepest decline since the Hunt Brothers’ silver manipulation collapse in 1980.
This isn’t merely a correction in commodity markets. The precious metals sell-off has sent shockwaves through global equity markets, with the S&P 500 shedding 2-3% and the Nasdaq experiencing heightened volatility as investors recalibrate risk across asset classes. The question now consuming trading floors from New York to Hong Kong: Is this a temporary unwinding of overcrowded positions, or does it signal something more profound about the global economic landscape?
The Anatomy of a Precious Metals Crash
To understand the current gold and silver price crash, we must first acknowledge the extraordinary rally that preceded it. Gold’s climb to $5,600 represented a 40%+ gain from 2024 levels, driven by persistent inflation fears, geopolitical tensions, and central bank accumulation. Silver, with its dual identity as both precious metal and industrial commodity, surged even more dramatically on manufacturing demand and speculation around green energy transitions.
But every parabolic rise contains the seeds of its own reversal. The gold price slump reasons for 2026 are multifaceted, reflecting a perfect storm of technical, monetary, and psychological factors:
Dollar Resurgence and Hawkish Fed Signals
The U.S. dollar has strengthened considerably against major currencies, making dollar-denominated commodities more expensive for foreign buyers. More significantly, President Trump’s nomination of Kevin Warsh as Federal Reserve chair has injected hawkish expectations into monetary policy discourse. Warsh, known for his inflation-fighting credentials and skepticism of prolonged easy money, represents a potential shift toward tighter monetary conditions—anathema to precious metals that thrive in low-rate, high-liquidity environments.
Market participants are reassessing their assumptions about the Fed’s trajectory, with Treasury yields climbing and real interest rates—gold’s traditional nemesis—moving higher. When bonds offer attractive risk-adjusted returns, gold’s appeal as a zero-yield asset diminishes rapidly.
Margin Requirements and Forced Liquidation
The Chicago Mercantile Exchange’s decision to raise margin requirements on precious metals futures contracts has amplified the sell-off. This technical adjustment, designed to reduce systemic risk during periods of extreme volatility, had the perverse effect of forcing leveraged speculators to liquidate positions to meet capital calls. In markets where momentum traders had piled in during the rally’s final stages, these forced sales created a cascade effect.
Silver, with its smaller market size and higher volatility, proved particularly susceptible. The metal’s Friday collapse wasn’t driven by fundamental deterioration in industrial demand or supply disruptions—it was a liquidity crisis within the futures market itself, reminiscent of the 1983 gold market dislocation when prices fell 12% in a single session.
Profit-Taking After Historic Gains
Sometimes the simplest explanation holds the most truth: investors are locking in profits after extraordinary gains. Portfolio managers who rode gold from $2,000 to $5,600 have compelling reasons to trim positions, particularly as quarterly reporting deadlines approach. The precious metals decline after rally reflects rational risk management as much as any fundamental shift in the investment thesis.
According to commodity strategists, the “smart money” began rotating out of precious metals into equities and credit in late January, anticipating that the speculative fervor had reached unsustainable levels. Retail investors, often the last to enter and first to panic, have since followed suit.
Silver’s Unique Vulnerability: Industrial Demand Meets Speculative Excess
While gold’s primary function remains as a monetary metal and store of value, silver straddles two worlds—and this duality has intensified its volatility. Approximately 50% of silver demand comes from industrial applications, particularly in solar panels, electronics, and emerging battery technologies. The other half comprises investment demand and jewelry.
The silver price crash impact on stocks has been particularly pronounced in mining equities and related ETFs. Companies like First Majestic Silver and Pan American Silver have seen their shares decline 15-20% in sympathy with the underlying metal, while broader materials sector indices have underperformed.
Yet beneath the panic lies an interesting contradiction: industrial fundamentals for silver remain robust. Green energy initiatives across Europe and Asia continue to drive structural demand for solar installations, which consume significant quantities of silver for photovoltaic cells. The disconnect between futures market pricing and physical market tightness suggests this sell-off may be creating opportunities for long-term investors willing to weather near-term volatility.
Equity Market Contagion: How the Precious Metals Rout Spreads
The ripple effects of the gold and silver slump extend far beyond mining stocks. Here’s how the sell-off is rattling broader equity markets:
| Market Segment | Impact | Primary Mechanism |
|---|---|---|
| S&P 500 | -2.3% (week-to-date) | Risk-off sentiment, correlation breakdown |
| Nasdaq 100 | -3.1% (volatile) | Tech liquidation to cover commodity losses |
| Mining Equities | -15 to -25% | Direct exposure to metal prices |
| Emerging Markets | -4.2% | Commodity-exporter currencies weaken |
| Treasury Bonds | +0.8% (yields down) | Flight to quality amid uncertainty |
The correlation mechanics are subtle but powerful. Many hedge funds and institutional investors maintain diversified portfolios where precious metals serve as inflation hedges and equity diversifiers. When these positions require sudden unwinding—either due to margin calls or risk reduction mandates—managers often sell their most liquid assets first. That typically means large-cap technology and growth stocks, explaining the Nasdaq’s outsized reaction.
According to market microstructure analysis, cross-asset correlations that typically hover near zero or negative during stable periods can spike toward +0.7 or higher during stress events. We’re witnessing this phenomenon now: assets that should theoretically move in opposite directions are instead falling in tandem as indiscriminate selling dominates thoughtful allocation.
Historical Context: Echoes of 1980 and 1983
For younger market participants, the current precious metals sell-off analysis may seem unprecedented. But history offers instructive parallels:
The 1980 Silver Collapse: After the Hunt Brothers attempted to corner the silver market, prices spiked to $50/oz before crashing 50% in four days when regulators intervened and exchanges changed margin rules. The parallels to today’s CME margin hikes and speculative positioning are striking.
The 1983 Gold Crash: Following Paul Volcker’s aggressive interest rate hikes to combat inflation, gold fell from $850 to $300 over two years. A single-session 12% drop in February 1983 shocked markets and presaged a multi-year bear market for precious metals.
Both episodes shared common features with 2026: speculative excess, rapid monetary policy shifts, and technical market structures that amplified volatility. Yet in both cases, gold and silver eventually found floors and resumed long-term uptrends as fundamental drivers reasserted themselves.
Why Gold and Silver Prices Are Falling Now: The Full Picture
Synthesizing the factors driving the current downturn reveals a complex interplay:
- Monetary Policy Expectations: The shift toward perceived hawkishness under potential Fed Chair Warsh raises real interest rates, gold’s kryptonite.
- Dollar Strength: A resurgent greenback makes commodities less attractive to international buyers and reduces inflation hedging urgency for U.S. investors.
- Technical Factors: Margin requirement increases forced liquidation among leveraged speculators, creating a self-reinforcing sell spiral.
- Profit Realization: After 40%+ gains, portfolio managers are locking in returns, particularly ahead of quarterly reporting periods.
- Sentiment Shift: The psychological transition from “fear of missing out” during the rally to “fear of holding” during the decline has accelerated capital outflows.
- Equity Competition: Improving corporate earnings and equity valuations are drawing capital that might otherwise remain in defensive precious metals positions.
The Road Ahead: Correction or Paradigm Shift?
The critical question for investors: Does this represent a healthy correction within a secular bull market for precious metals, or a fundamental reversal of the forces that drove prices to record highs?
Several factors suggest this is more correction than paradigm shift:
Central Bank Demand Remains Robust: According to World Gold Council data, central banks purchased over 1,000 tonnes of gold in 2025, continuing a multi-year diversification away from dollar reserves. This institutional bid provides a floor beneath prices.
Structural Inflation Pressures Persist: Despite near-term rate expectations, long-term inflation drivers—deglobalization, energy transition costs, fiscal deficits—remain intact. These favor hard assets over the medium term.
Industrial Silver Fundamentals: The green energy transition isn’t reversing. Solar panel installations, electric vehicle adoption, and 5G infrastructure deployment all require significant silver inputs.
Geopolitical Uncertainty: From U.S.-China tensions to Middle East instability, the global risk landscape continues to support safe-haven demand.
However, genuine risks exist. If Kevin Warsh’s Fed pursues aggressive tightening and the dollar extends gains, precious metals could face sustained headwinds. A recession scenario might initially hurt industrial silver demand while benefiting gold’s safe-haven appeal—but severely constricted credit conditions could pressure both metals as investors scramble for cash.
Investment Implications and Strategic Considerations
For sophisticated investors, the current volatility presents both challenges and opportunities:
Short-term traders should remain cautious. The technical damage to both gold and silver charts suggests further downside risk if key support levels fail. The $4,400 level for gold and $75 for silver represent critical thresholds.
Long-term allocators might view significant weakness as an opportunity to establish or add to positions at more attractive valuations. Few credible scenarios eliminate the case for modest precious metals exposure (5-10% of portfolios) as diversification and inflation insurance.
Mining equity investors face a unique situation where stocks have sold off more aggressively than underlying metals, potentially creating value. However, companies with high leverage or production challenges could face severe stress if metal prices remain depressed.
Options strategies such as selling volatility through covered calls or establishing protective collars may be appropriate for those maintaining positions through this turbulent period.
Conclusion: Navigating Uncertainty with Historical Perspective
The gold and silver slump of early 2026, while dramatic and unsettling, fits a recognizable pattern of boom, excess, and correction that has characterized precious metals for centuries. The speed and severity of the decline—particularly in silver—reflects modern market structures where leverage, algorithmic trading, and interconnected risk systems can amplify movements in both directions.
Yet beneath the volatility, the fundamental case for precious metals allocation hasn’t disappeared. Inflation risks, geopolitical tensions, currency debasement concerns, and portfolio diversification needs all persist. The question isn’t whether gold and silver have a role in modern portfolios, but at what price that role becomes compelling.
For investors, the wisest course may be the most difficult: patience. Let the forced liquidation run its course, allow technical indicators to stabilize, and reassess positioning once panic gives way to rational price discovery. History suggests that markets overshoot in both directions—and that the deepest values often emerge when sentiment is darkest.
The precious metals crash of 2026 will eventually be seen as either a painful but temporary correction in an ongoing bull market, or as the beginning of a multi-year bear phase. That determination won’t come from headlines or single-day price movements, but from careful analysis of monetary policy, inflation trajectories, and global economic evolution over months and years ahead.
In the meantime, as trading desks absorb the shock and portfolio managers recalibrate, one truth remains constant: in times of uncertainty, the ancient appeal of tangible assets continues to echo through modern financial markets—even when those assets themselves are experiencing extraordinary turbulence.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
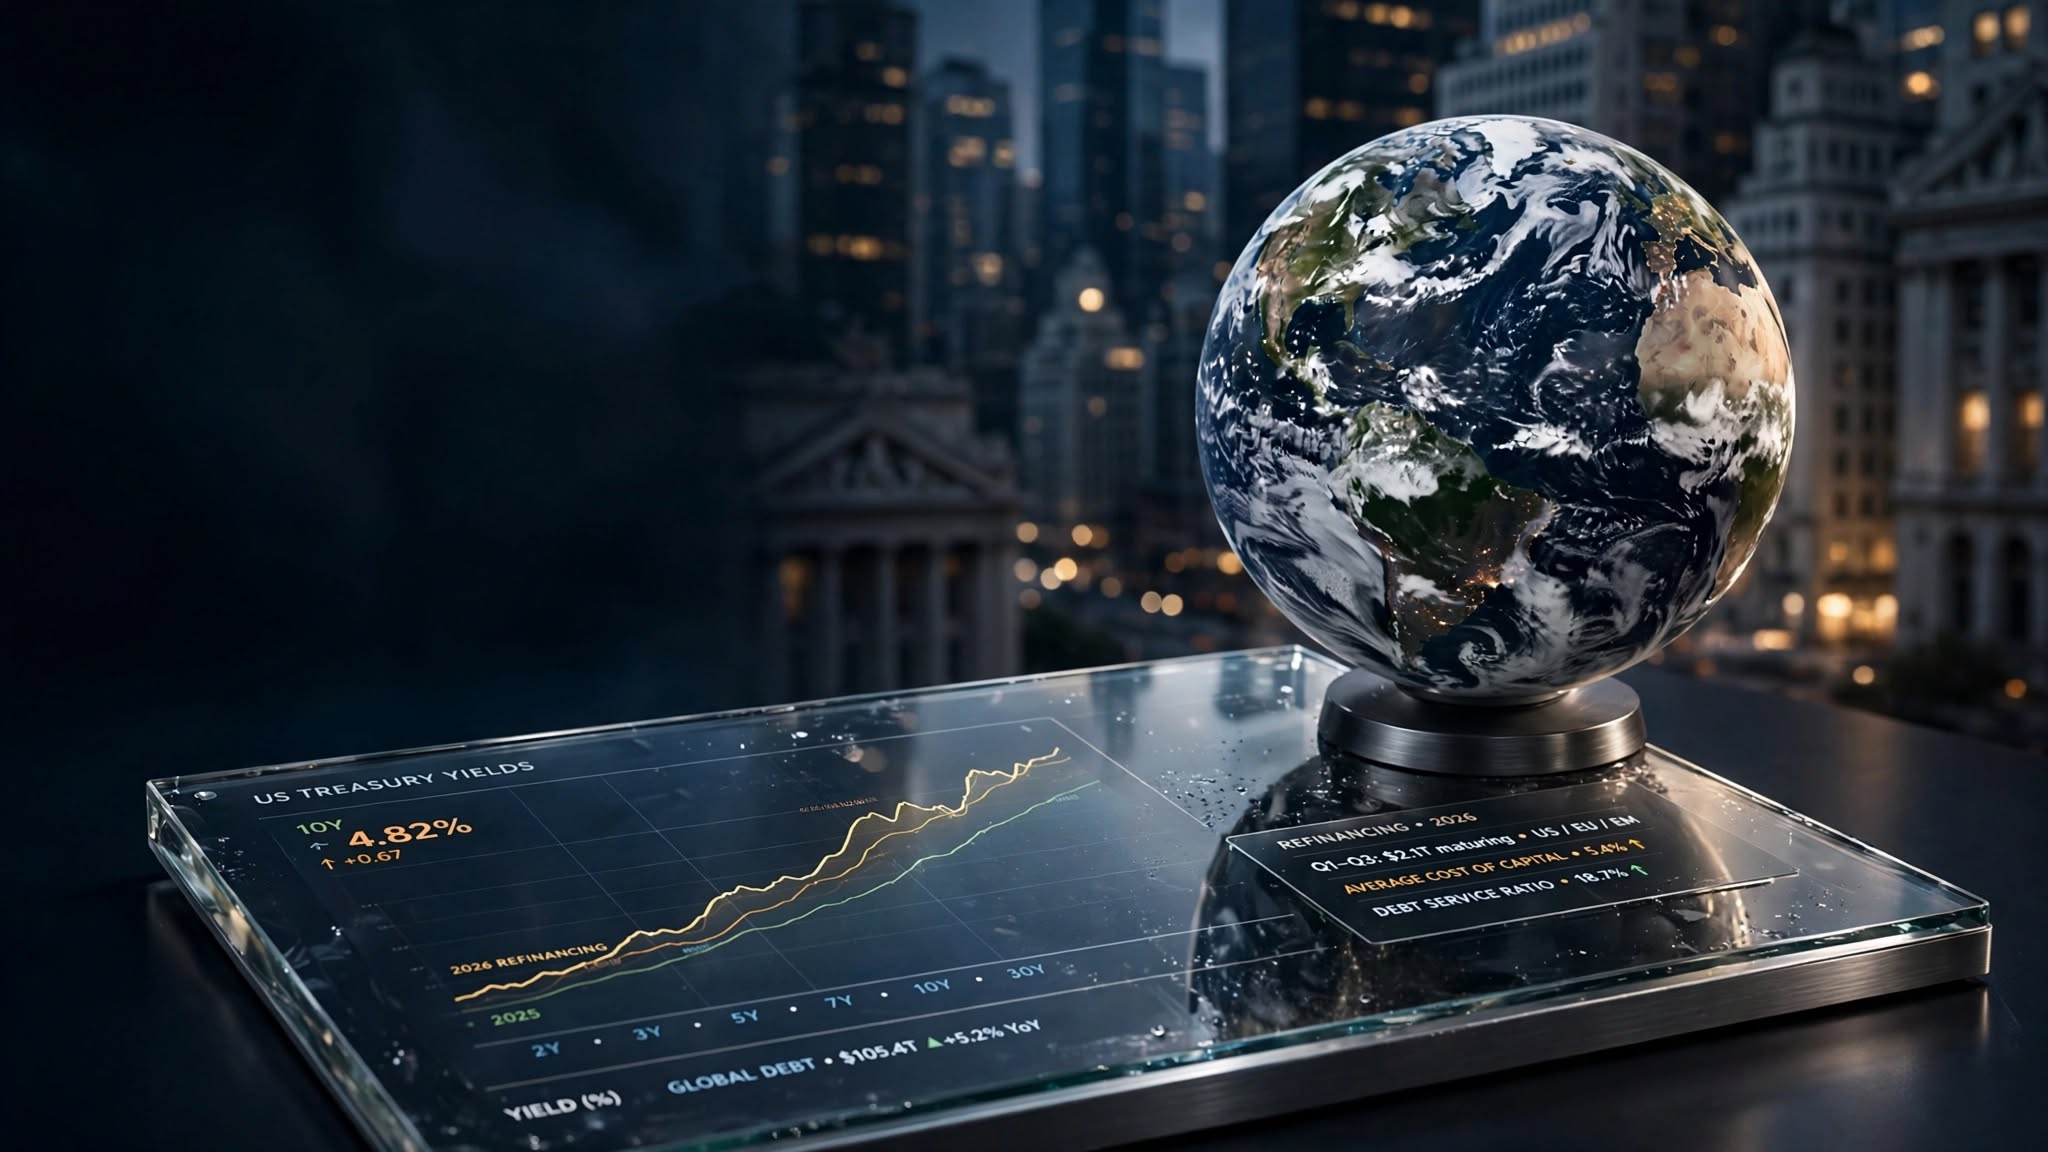
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors

Battle for the Farm Belt: How Tariff Pressures and Fuel Costs Are Reshaping Iowa’s 2026 Midterms

Southeast Asia’s Critical Minerals Power Play: Can ASEAN Avoid Choosing Between China and the US?

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN

Bank Jago’s Wealth Management Push:Indonesia’s 31.1 Million Investors boom

Beyond the Four-Year Degree: The $100K+ Trade Careers Young Americans Are Overlooking

SpaceX Starship Achieves First Full Orbit on Historic 10-Hour Test Flight 14

Google’s $15B Finland AI Investment: Data Centers, Nuclear Power & Jobs

Fast Invoice Factoring: Rates, APR Math & Contract Traps

SOC 2 Type II Guide: Cost, Timeline & Compliance Companies

Hong Kong Wages Surge 3.4% in June: Sector Data & Analysis

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025