
Analysis
US Appeals Court Overturns $16 Billion Argentina Ruling in Devastating Blow to Burford Capital

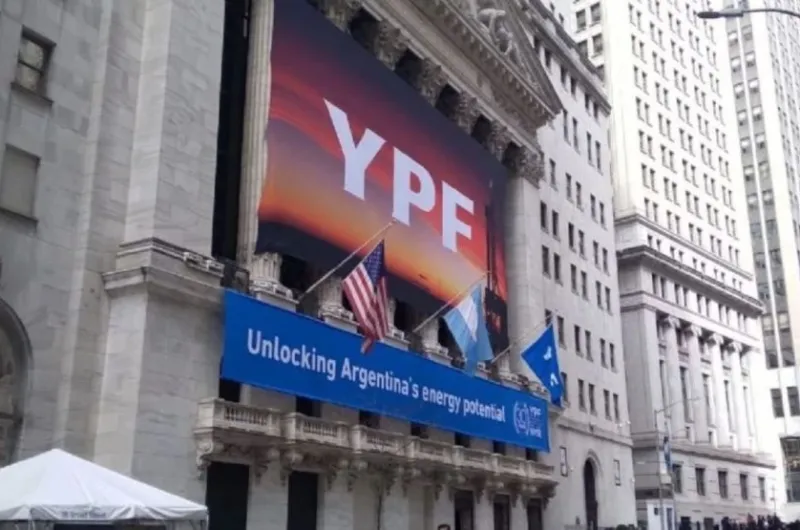
A US appeals court overturned a $16.1 billion judgment against Argentina in the YPF nationalization case — obliterating Burford Capital’s biggest bet. Here’s what it means for sovereign litigation and global investors.
The Biggest Bet in Litigation Finance Just Collapsed
On the morning of Friday, March 28, 2026, traders in London, New York, and Buenos Aires woke up to a number that seemed almost hallucinatory: –47%. That was the overnight implosion in shares of Burford Capital (NYSE: BUR), the world’s largest litigation finance firm — and it happened in a single session, on a single ruling, from a single court in lower Manhattan.
The 2nd U.S. Circuit Court of Appeals had just voided a $16.1 billion judgment against the Republic of Argentina — a judgment that had, with eight years of accruing 8% interest, ballooned to roughly $18 billion by the time it was argued on appeal last October. In a 2-1 decision that rewrites the rules of sovereign liability in U.S. courts, the appeals panel determined that Judge Loretta Preska’s landmark 2023 award rested on a fundamental misreading of Argentine law. The claims, Circuit Judge Denny Chin wrote for the majority, were simply “not cognizable.”
For Burford — which had purchased the litigation rights for a mere 15 million euros (roughly $17.3 million) and stood to collect a transformative windfall — the ruling was not merely a setback. It was an existential reckoning with the sovereign risk that has always lurked beneath the shimmering surface of third-party litigation finance.
The YPF Nationalization: A Decade of Legal Warfare
To understand Friday’s ruling, you need to go back to April 2012, when Argentine President Cristina Fernández de Kirchner announced one of the most audacious resource nationalizations in Latin American history. Citing YPF’s failure to invest sufficiently in domestic oil and gas production, her government expropriated a 51% controlling stake in YPF from Spain’s Repsol for $5 billion — a sum Repsol publicly derided as a fraction of fair value.
The move left two minority shareholders — Petersen Energía Inversora and Eton Park Capital Management, YPF’s second- and third-largest investors — stranded. Under YPF’s own corporate bylaws, any acquirer of a controlling stake was obligated to make a tender offer to all remaining shareholders at the same price. Argentina, exercising sovereign power of expropriation, simply didn’t. For Petersen and Eton Park, that omission cost them billions.
The lawsuit that followed wound its way through New York courts for the better part of a decade, clearing a Supreme Court hurdle on jurisdictional grounds before finally reaching its climax in September 2023, when Judge Preska handed down her $16.1 billion award — the largest judgment ever leveled against a sovereign nation in a U.S. commercial court. Petersen was owed $14.39 billion; Eton Park, $1.71 billion. Argentina’s total budget that year? About $36 billion. The judgment amounted to nearly half of it.
Burford Capital, which had acquired the litigation rights from Petersen for 15 million euros, was in line to collect the lion’s share. Its stock soared. Analysts revised valuations upward. The case was described, not without hyperbole, as the most valuable single legal asset in history.
Then came Friday.
The 2-1 Decision: What the Court Actually Said
In a 2-1 ruling authored by Circuit Judge Denny Chin, the Second Circuit held that Argentina’s breach-of-contract claims failed as a matter of Argentine law. The core logic is as elegant as it is consequential: when a sovereign state exercises its constitutional power of expropriation, the legal framework governing that act is public law — not the private corporate bylaws of a company it happens to be seizing.
YPF’s bylaws may well have required a tender offer when a private buyer acquired a controlling stake. But Argentina wasn’t acting as a private buyer. It was acting as a sovereign. And sovereigns, the majority held, are not bound by bylaw obligations designed to govern ordinary commercial transactions. The lower court, in the majority’s assessment, had conflated the two — and in doing so, manufactured a $16 billion liability from a legal theory the Argentine civil code simply does not support.
Dissenting Judge José Cabranes disagreed sharply. His dissent, which Burford’s statement pointedly described as giving rise to a ruling “sufficiently extraordinary” to warrant further review, argued that the bylaws created obligations that survived the nationalization. The 2-1 split is important: it signals genuine legal tension, which is precisely the kind of ambiguity that can attract Supreme Court attention.
Argentina’s lead attorney, Robert Giuffra of Sullivan & Cromwell, was characteristically blunt in victory. Burford, he said, had “paid just 15 million euros for the right to sue and collected… seeking to turn U.S. courts into a casino by using its own made-up interpretation of Argentine law.”
From Buenos Aires, President Javier Milei was rather less restrained. “WE WON THE YPF LAWSUIT,” he wrote on X, in full capitals. “It’s historic, unthinkable, the greatest legal achievement in national history.”
Burford Capital: Anatomy of a Collapse
Few moments in modern finance illustrate the volatility of litigation finance quite like Friday’s trading session. Burford’s stock had opened the year near $8 per share; by mid-morning on March 27, trading was halted multiple times as the price spiraled toward $4.14 — levels not seen since the company’s earlier controversies in 2019.
The magnitude of the collapse reflects a deeper truth about how Burford had positioned this asset in its books. The YPF judgment wasn’t merely a potential recovery; it had been carried as an “accrued gain” — a cornerstone of the company’s net asset valuation for years. When that cornerstone evaporated, so did the investment thesis for a significant slice of Burford’s shareholder base.
The company’s official statement, filed as an 8-K with the SEC on Friday, was notably measured given the carnage. Burford said it expects the plaintiffs to seek en banc rehearing before the full 13-judge Second Circuit within the 14-day window permitted by court rules — a process it candidly acknowledged is “disfavored and rarely granted.” Should that fail, a petition to the U.S. Supreme Court would follow within 90 days, though the Supreme Court accepts only a small fraction of cases presented to it each year, with a particular focus on cases presenting genuinely novel legal questions.
There is, however, a third path: investment treaty arbitration. Burford’s statement noted that arbitration “has always been available should the U.S. courts not entertain the case” and that Argentina has lost substantial investment arbitrations in the past — including at least one claim funded by Burford itself. But treaty arbitration is a long, expensive, and enforcement-uncertain road. The firm’s own documents suggest it could take five to seven years to reach a conclusion, with enforcement against sovereign assets notoriously difficult.
For investors, the calculus is brutally simple: a company that once counted an $18 billion notional gain as an asset now holds, in its place, a highly uncertain claim on a legal process that may take a decade to resolve — and may ultimately yield nothing.
What This Means for Argentina — and Milei’s Reform Agenda
For Argentina, the timing is exquisite, if not entirely serendipitous. President Milei has spent the better part of 15 months dismantling the statist economic architecture built by his Peronist predecessors — slashing subsidies, floating the peso, negotiating a fresh IMF program worth tens of billions of dollars, and attempting to re-open Argentina to foreign direct investment after decades of capital controls and default cycles.
An $18 billion judgment — equivalent, as Milei himself noted, to the entirety of Argentina’s recent IMF facilities — hanging over the sovereign balance sheet was precisely the kind of liability that spooked foreign investors and complicated debt market access. With it gone, at least provisionally, the macroeconomic picture improves meaningfully.
“It is an extremely positive ruling,” Roberto Geretto, an economist at Argentine financial consultancy Adcap, told Reuters, “because it not only implies a reduction in sovereign risk but also removes a significant overhang on state-controlled assets.” YPF shares, which had faced the extraordinary threat of forced transfer to plaintiffs under a June 2025 lower-court order, are now entirely free of that encumbrance. That order, too, was vacated by the Second Circuit once the underlying judgment was voided.
The ruling also removes a major distraction from Milei’s crown-jewel energy play: the Vaca Muerta shale formation in Patagonia, one of the world’s largest unconventional hydrocarbon basins, which his administration has been aggressively marketing to U.S. and European energy majors. Foreign oil executives who might have hesitated to invest in a company potentially stripped of its shares have one less reason for caution.
None of this, of course, resolves the structural challenges facing the Argentine economy — a history of serial default, political volatility, and an electorate not entirely sold on fiscal austerity. But in the short term, this ruling is unambiguously positive for Argentine sovereign debt, peso-denominated assets, and Milei’s narrative of technocratic renewal.
The Deeper Lesson: Sovereign Litigation Risk and the Limits of Litigation Finance
The YPF ruling is more than a single case outcome. It is a warning shot, fired from the most influential commercial appeals court in the United States, about the hazards of attempting to apply private contract law to sovereign acts.
Litigation finance funds have flourished over the past decade on the premise that undervalued legal claims — particularly those against deep-pocketed defendants, including sovereign states — represent a compelling asset class. The model is elegant in theory: buy distressed claims cheaply, absorb the legal costs, and capture a large share of any eventual award. Burford, the sector’s undisputed leader, built a multi-billion dollar business on precisely this logic.
But the YPF case exposes the model’s most dangerous assumption: that a U.S. court will act as a global enforcement mechanism for whatever legal theory the plaintiff can construct. The Second Circuit, in essence, refused that role. When Argentina nationalized YPF, it was acting under its own constitutional authority, on its own territory, under its own public law. The fact that those acts had financial consequences for U.S.-connected investors does not automatically transform them into violations of private contractual obligations enforceable in Manhattan.
This is not a novel insight — it is, in fact, a foundational principle of international law. What the YPF saga illustrates is how easily that principle can be temporarily overwhelmed by creative legal engineering and a sympathetic district court judge, only to reassert itself on appeal. For the litigation finance industry, the lesson is uncomfortable: sovereign risk is not just political risk. It is legal-structural risk — and U.S. courts, it turns out, are not infinitely malleable.
The broader fallout for third-party litigation funding may be felt most acutely in the growing pipeline of investment-treaty and commercial claims against Latin American, African, and Asian governments that have followed Argentina’s model of high-profile resource nationalization. Funders who priced those claims assuming U.S. court enforceability will now need to recalibrate.
What Comes Next
Burford and the plaintiffs have several options, none of them quick or cheap.
En banc rehearing is the first and most immediate step. The plaintiffs have 14 days to request that all 13 active judges of the Second Circuit reconsider the panel’s ruling. The odds are long — such requests are “disfavored and rarely granted,” as Burford’s own filings note — but Judge Cabranes’s forceful dissent gives grounds for a credible petition.
Supreme Court certiorari remains on the table within 90 days of the final Second Circuit disposition. Whether the Court takes the case depends heavily on whether it views the question — when does a sovereign’s expropriation trigger private contractual obligations under the target company’s bylaws? — as presenting a genuinely novel and nationally important legal issue. Given the U.S. government’s own interests in sovereign immunity jurisprudence, there is a non-trivial chance the Court calls for the Solicitor General’s views, as it did during the earlier jurisdictional phase of this very case in 2019.
Investment treaty arbitration may, in the long run, be the most viable path. Argentina has signed bilateral investment treaties with Spain (Petersen’s home country) and potentially with other relevant jurisdictions. Treaty arbitration bypasses U.S. court skepticism about sovereign acts and operates under international law standards that are arguably more favorable to aggrieved investors. Burford has won treaty arbitrations before. But the timeline — five to seven years, minimum — and the enforcement challenges against a sovereign with a documented history of refusing to honor adverse awards make this a patience-testing avenue.
For investors considering whether Friday’s crash represents an opportunity or a value trap, the honest answer is: it depends entirely on your assessment of those three paths, and your appetite for a long wait with uncertain outcomes.
The Bottom Line
A decade after Cristina Fernández de Kirchner nationalized YPF in a fit of resource nationalism, the legal edifice built to hold Argentina accountable has crumbled — not in Buenos Aires, but in a federal courthouse in lower Manhattan. The 2nd Circuit’s ruling is a reminder that U.S. courts have limits, that sovereign acts occupy a distinct legal category, and that litigation finance, however sophisticated, cannot fully price the risk that the legal theory underlying a $17 million investment turns out not to hold water.
For Milei’s Argentina, it is a gift: an $18 billion liability erased, a key state asset secured, and a narrative of pragmatic reform reinforced. For Burford Capital, it is a reckoning that will reshape how the firm — and the industry it dominates — thinks about sovereign exposure for years to come.
The story is not over. En banc petitions will be filed. Supreme Court arguments may yet be made. Treaty arbitrators may eventually weigh in. But for now, the court has spoken: the greatest legal bet in the history of litigation finance came up short.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Apply for a Bank Account Online: What You Need and How Long It Actually Takes

World’s Largest Economies: Ranking the Top Global Powers

Business Loan: A Complete 2026 Guide to Rates, Types, and Qualifying

Fast Invoice Factoring: How to Turn Unpaid Invoices Into Cash Within 24 Hours

Investment Banking Services: What They Cost and How to Choose the Right Firm in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025