
Analysis
Indonesia’s Fee Cap Threatens Ride-Hailing Profits, Clouds Outlook for Grab and GoTo

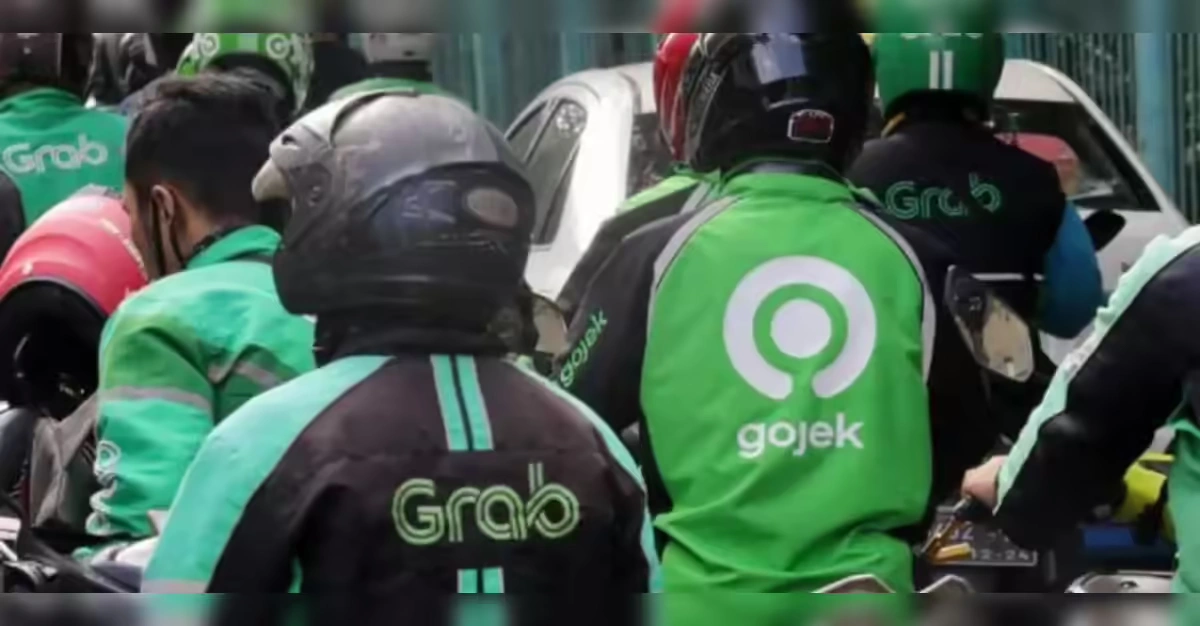
Analysts warn that the sweeping new policy could severely dampen investor sentiment—striking just as Southeast Asia’s ride-hailing giants finally clawed their way to profitability.
By the time the equatorial sun sets over the snarled, relentless traffic of Jakarta’s Jalan Sudirman, the city is a sea of green. Millions of motorcycle drivers, clad in the signature emerald jackets of Gojek and Grab, form the arterial lifeblood of Southeast Asia’s largest economy. For years, these gig workers have been the unseen engine powering a regional tech revolution, one that transformed scrappy startups into multibillion-dollar “super-apps.”
But a sudden regulatory earthquake has just fractured the foundational economics of that revolution.
On May 1, 2026, Indonesian President Prabowo Subianto delivered on a populist campaign promise that sent tremors through regional markets. Through the stroke of Presidential Regulation No. 27/2026, the Indonesian government mandated an aggressive 8% cap on the commissions ride-hailing platforms can extract from drivers—a brutal haircut from the historical industry standard of roughly 20%. Furthermore, the decree forces platforms to guarantee full accident and health insurance for their fleets, effectively dismantling the arms-length “independent contractor” loophole that has historically subsidized platform margins.
For the drivers, it is a historic victory—a massive wealth transfer that ensures they take home a minimum of 92% of the fare. But for dominant regional players Grab and GoTo (the merged entity of Gojek and Tokopedia), the timing could not possibly be worse.
Just as the grueling, decade-long era of cash-burning expansion finally yielded the elusive prize of profitability, the Indonesia ride-hailing fee cap threatens to plunge unit economics back into the red. As a result, the “Grab Indonesia regulation 2026” narrative has rapidly shifted from one of triumphant consolidation to one of existential regulatory risk.
The Populist Pivot: Deconstructing Regulation No. 27/2026
To understand the sheer magnitude of this policy, one must view it through the lens of Indonesia’s current sociopolitical climate. With over 275 million people and an immense informal sector, the gig economy is not a fringe employment alternative in Indonesia; for millions, it is the primary social safety net.
President Prabowo, who assumed office in late 2024 with a mandate centered on national self-reliance and the uplift of the working class, has increasingly focused his administration’s regulatory gaze on foreign-backed tech oligopolies. The May 1st decree is the sharpest manifestation of this agenda yet.
The regulation is uncompromising in its architecture:
- The 8% Ceiling: Platform take-rates are strictly capped at 8% of the total fare.
- The 92% Floor: Drivers are guaranteed 92% of the gross booking value (GBV) before nominal taxes.
- Mandatory Social Protection: Platforms must directly subsidize comprehensive health and accident coverage via BPJS Ketenagakerjaan (the national social security agency), stripping away the “voluntary” tier system previously used by the super-apps.
“This is not merely a market correction; it is a fundamental rewriting of the digital social contract,” notes a recent policy analysis by the Center for Strategic and International Studies (CSIS) in Jakarta. “The government has explicitly decided that the welfare of the Indonesian gig economy drivers supersedes the margin expansion targets of institutional investors in Singapore or New York.”
For a government aiming to boost domestic consumption, putting more Rupiah directly into the pockets of the working class is sound macroeconomic theory. But for the platforms orchestrating the marketplace, it is a financial crisis.
A Fragile Milestone: The End of the Cash-Burn Era
The sting of the Indonesia commission cap for Grab and GoTo is particularly acute because of what the companies just achieved.
For the better part of the last decade, the Southeast Asian ride-hailing market was defined by a ruthless, capital-intensive war of attrition. Backed by the bottomless coffers of SoftBank, Tencent, and Alibaba, companies subsidized rides to artificially build user habits. Operating losses routinely reached into the billions.
But the era of free money ended abruptly with the global tightening of interest rates. Forced to pivot from “growth at all costs” to sustainable unit economics, both companies embarked on brutal efficiency drives. They slashed corporate headcounts, shuttered underperforming experimental divisions, and, crucially, optimized their take-rates—steadily creeping commissions closer to the 20-25% mark.
The austerity worked. In early 2026, Grab reported its first-ever full-year net profit for the 2025 fiscal year, a staggering turnaround for a company that was bleeding over $3 billion annually just a few years prior. Hot on its heels, local champion GoTo announced its highly anticipated first profitable quarter in Q1 2026, a milestone that finally vindicated its complex merger and subsequent divestment of an unprofitable e-commerce arm to TikTok.
Investors were jubilant. The “super-app” model was finally generating cash. Then came May 1st.
“The introduction of this fee cap essentially kicks the stool out from under the newly established profitability of these firms’ mobility arms,” explains a senior tech equity analyst at Macquarie Group. “You cannot model a 60% reduction in top-line mobility revenue—which is what a drop from 20% to 8% represents—without acknowledging a severe deterioration in forward earnings.”
Crunching the Numbers: Margins Under Siege
The GoTo profit impact fee cap equation is relatively straightforward, and entirely grim. The mobility segment (two-wheel and four-wheel rides) is the high-frequency anchor of the super-app ecosystem. It drives daily active users (DAUs) into the higher-margin segments like food delivery, digital lending, and payments.
Let’s dissect the unit economics of an average ride in Jakarta before and after Regulation No. 27/2026:
Anatomy of an Average Ride-Hailing Fare (100,000 IDR)
| Metric | Pre-May 1 Era (20% Take Rate) | Post-May 1 Era (8% Take Rate) | Percentage Change |
| Gross Fare paid by Rider | Rp 100,000 | Rp 100,000 | 0% |
| Driver Earnings (Net) | Rp 80,000 | Rp 92,000 | +15.0% |
| Platform Revenue | Rp 20,000 | Rp 8,000 | -60.0% |
| Insurance Cost (Est) | Paid by driver/optional | Rp 2,000 (Paid by platform) | N/A |
| Platform Gross Margin | Rp 20,000 | Rp 6,000 | -70.0% |
Note: Figures are illustrative approximations based on historical industry averages.
The math is unforgiving. To absorb a 70% compression in gross margins per ride, platforms have only a few levers to pull, and none of them are palatable.
Unsurprisingly, capital markets reacted violently. Following the May 1st announcement, shares of GoTo on the Indonesia Stock Exchange (IDX) tumbled by nearly 6%, while Grab’s Nasdaq-listed shares faced intense pre-market selling pressure. The sell-off reflects a sudden, sobering realization: the regulatory moat in Southeast Asia is much shallower than Wall Street had modeled.
Both companies have issued carefully worded statements. Grab Indonesia emphasized its “commitment to collaborating with the government to ensure sustainable growth for all stakeholders,” while GoTo acknowledged the regulation and stated it is “actively reviewing the commercial impacts while remaining dedicated to the welfare of our mitra (partners).”
The Unintended Consequences: Who Really Pays?
If the platforms cannot absorb the loss, who will? Economic history suggests that artificial price controls in two-sided marketplaces rarely result in a clean transfer of wealth from corporation to worker without triggering secondary effects.
The immediate corporate response will likely be an attempt to pass the cost onto the consumer. But this introduces a perilous tightrope walk. Indonesia is a highly price-sensitive market. A 15% increase in the base fare to offset the commission cap could trigger severe demand destruction.
“If fares rise too much, middle-class Jakartans will simply revert to driving their own scooters, using public transit, or hailing traditional ojek (motorcycle taxis) off the street,” notes a consumer behavior report from NielsenIQ Indonesia. “The elasticity of ride-hailing demand in Southeast Asia is incredibly fragile.”
If demand drops, the 92% share drivers now receive will be 92% of a much smaller pie. Anecdotal evidence from earlier, less severe tariff adjustments in 2022 showed exactly this: higher per-ride earnings were quickly neutralized by longer idle times between bookings.
Furthermore, there is a distinct risk to the quality of service. With margins squeezed, platforms will inevitably gut their marketing budgets, consumer promotions, and customer service operations. The friction-free, highly subsidized magic of the super-app era will be replaced by a more utilitarian, bare-bones utility.
The Broader Threat: Regional Contagion
For Grab’s executive team in Singapore, the terror is not just confined to the Indonesian archipelago. The Southeast Asia ride-hailing regulation landscape operates on a domino effect.
Indonesia is the region’s bellwether. If President Prabowo successfully enforces an 8% cap without collapsing the transport grid, labor activists and progressive lawmakers in neighboring countries will take note.
Malaysia, under Prime Minister Anwar Ibrahim, has already been scrutinizing the gig economy heavily. In the Philippines, the Land Transportation Franchising and Regulatory Board (LTFRB) frequently clashes with platforms over fare matrices. If the “Indonesian Model” becomes the new regional standard, the valuation multiples of Southeast Asian tech firms will need to be structurally recalibrated by global asset managers.
Bloomberg Intelligence analysts warned earlier this week that “a contagion of margin-capping regulatory policies across the ASEAN-6 nations represents the single largest headwind to the profitability projections of Grab and its regional peers over the next 36 months.”
The Pivot: How the Super-Apps Must Evolve
Faced with a structurally impaired mobility business, the strategic imperative for Grab and GoTo is to accelerate their diversification away from pure transport. The ride-hailing Indonesia outlook now hinges entirely on cross-selling.
Mobility must be viewed not as a profit center, but as a loss-leading user acquisition tool for high-margin financial services.
- Fintech and Digital Banking: Both companies possess formidable fintech arsenals—GoTo with GoPay and its stake in Bank Jago, Grab with OVO and its regional digital banking licenses. By migrating drivers and riders deeper into their financial ecosystems (micro-loans, buy-now-pay-later, wealth management), they can monetize the user outside the purview of the Ministry of Transportation.
- Logistics and B2B: While consumer ride-hailing is highly scrutinized, business-to-business logistics and enterprise fleet management remain less regulated. Expect a massive pivot toward servicing e-commerce supply chains and corporate transport.
- Advertising Real Estate: Following the playbook of Uber and Instacart in the US, Grab and GoTo will likely transform their apps into high-margin digital advertising networks, monetizing user attention rather than user transit.
“They have to become digital landlords rather than taxi dispatchers,” says a venture partner at Sequoia Capital India & SEA (Peak XV Partners). “The toll-booth model of charging 20% on a motorcycle ride is dead in Indonesia. The next phase of profitability requires monetizing the data, the wallet, and the attention.”
Conclusion: A Tectonic Shift in Tech Capitalism
The narrative surrounding the Prabowo ride-hailing policy is inherently binary, depending on where one stands. For the millions of drivers braving the monsoon rains and labyrinthine streets of Indonesia’s megacities, Regulation No. 27/2026 is a long-overdue rebalancing of power. It is an assertion by the state that the human sweat powering the digital economy deserves a fairer share of the algorithmic spoils.
But for the global investors who poured billions into the promise of a frictionless, highly profitable Southeast Asian tech monopoly, it is a stark awakening. The May 1st decree shatters the illusion that Silicon Valley economics can be copy-pasted into emerging markets without encountering severe sociopolitical friction.
Grab and GoTo are not going bankrupt; they are too deeply entrenched in the daily lives of hundreds of millions, and their balance sheets have been sufficiently fortified over the past two years. However, their identity as hyper-growth margin machines is likely over. They are transitioning from unregulated tech disruptors into heavily regulated public utilities.
As they navigate this new reality, the ultimate test will not just be whether they can appease their shareholders in New York and Jakarta, but whether they can sustain the innovation that made them indispensable in the first place, all while surviving on a fraction of their historical lifeblood.
The era of easy money is long gone. Now, it seems, the era of easy margins has followed it out the door.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

SpaceX Starship Achieves First Full Orbit on Historic 10-Hour Test Flight 14

Google’s $15B Finland AI Investment: Data Centers, Nuclear Power & Jobs

Fast Invoice Factoring: Rates, APR Math & Contract Traps

SOC 2 Type II Guide: Cost, Timeline & Compliance Companies

Hong Kong Wages Surge 3.4% in June: Sector Data & Analysis

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Gavin Baker AI Outlook: Why the Compute Shortage Persists Through 2028
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025