
Analysis
Why Walmart’s Self-Checkout Retreat Exposes the Hidden Cost of Frictionless Retail

Alternative titles: — “Scan It Yourself, Pay for It Later: The True Price of Retail’s Self-Checkout Obsession” — “The Machine That Broke the Store: Inside Walmart’s Self-Checkout Reckoning”
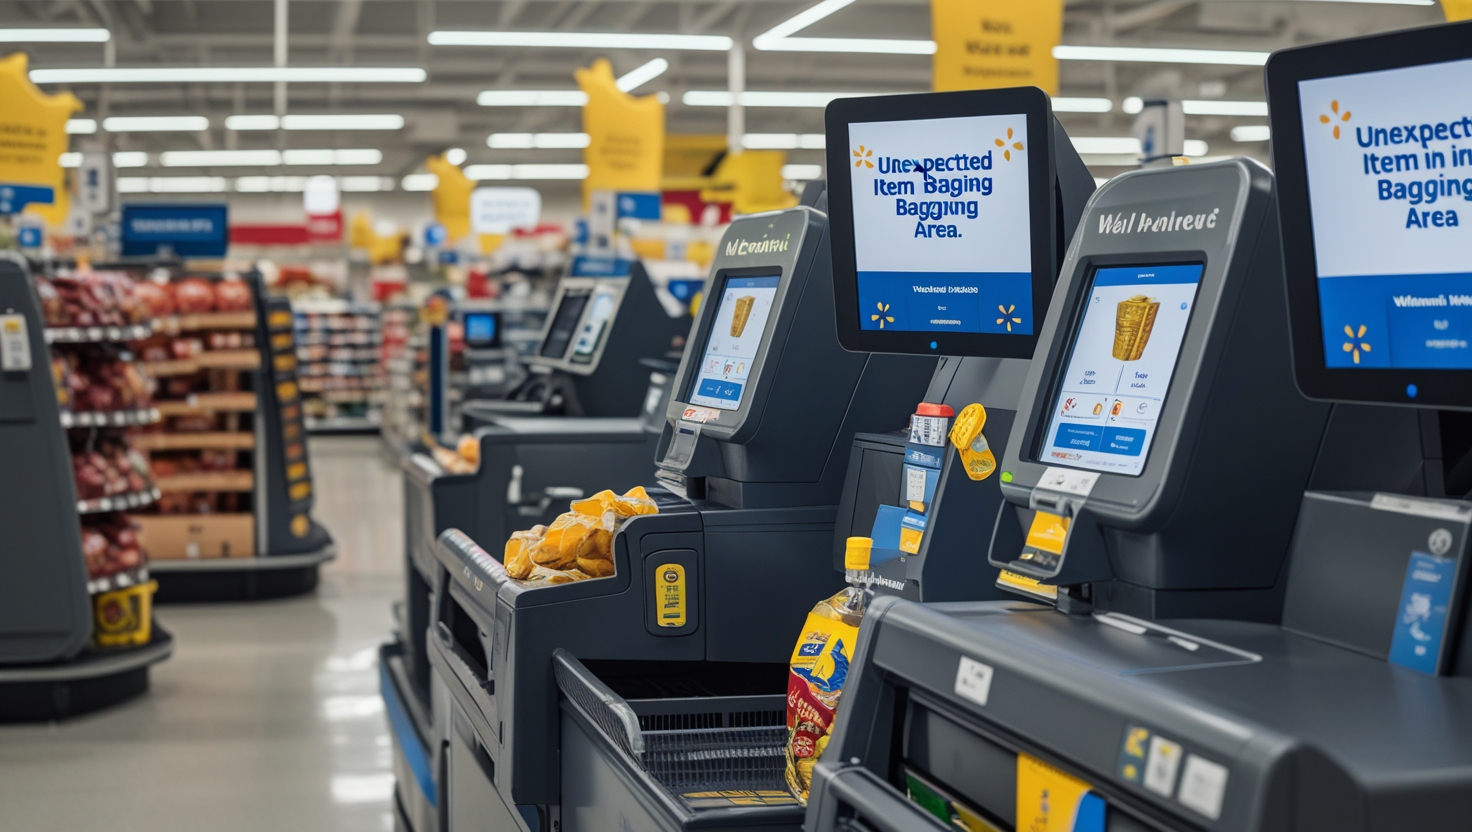
There is a moment, familiar to anyone who has stood in a Walmart self-checkout lane with a bag of produce and a mild sense of dread, when the machine announces — with all the patience of a parking ticket — “unexpected item in bagging area.” You haven’t moved. You haven’t breathed. The item is exactly where it should be. And yet the kiosk, confidently wrong, has frozen your transaction and summoned a frazzled attendant who will wave a card over a sensor and offer a smile that says: I know. I’m sorry. This happens constantly.
That moment — small, mundane, almost comic — turns out to be one of the most consequential design failures in modern retail history.
For nearly two decades, the self-checkout lane was the retail industry’s great productivity promise: fewer cashiers, faster throughput, lower labor costs, happier shareholders. Walmart, the world’s largest retailer by revenue, leaned into this promise harder than almost anyone. At peak deployment, Walmart operated self-checkout kiosks across thousands of its more than 4,700 U.S. stores, and its subsidiary Sam’s Club turned the concept into an evangelical mission. The logic was iron-clad — or so it seemed.
Now, quietly but unmistakably, the reckoning has arrived.
How Walmart’s Self-Checkout Strategy Unraveled — and What It Signals for Retail
The rollback began not with a press release but with a police log. In Shrewsbury, Missouri, the local police department responded to 509 calls from a single Walmart location in the first five months of 2024. Strip out self-checkout lanes, as Walmart subsequently did at that store, and the same period in 2025 produced 183 calls — a 64% decline. Arrests fell from 108 to 49. The local police chief attributed the drop directly to the removal of the automated kiosks, as documented in a May 2026 investigation by Rolling Out.
That is not a footnote. That is a business case.
Walmart has now fully removed self-checkout from at least six known locations — Shrewsbury, Missouri; Cleveland, Ohio; three stores in New Mexico; and one in Los Angeles, California — with an unknown number of additional stores reducing or restricting their use, according to retail industry tracker Kiosk Industry. The company has simultaneously imposed strict 15-item limits on self-checkout users and is enforcing lane monitoring to prevent the full-cart incursions that became a low-grade norm. “We currently have no additional conversions to announce,” a Walmart spokesperson told CX Dive with the careful precision of a company that almost certainly has more conversions to announce. “We believe the changes will improve the in-store shopping experience and give our associates the chance to provide more personalized and efficient service,” the company told Retail Dive.
That is corporate for: the experiment had side effects we didn’t fully price in.
The Shrink Problem: When Convenience Becomes a Liability
Let’s be precise about what is actually happening here, because the media narrative has oscillated between two equally misleading poles: Walmart is abandoning automation and this is just a few stores, calm down. Both miss the structural story.
The structural story is shrink.
In retail, “shrink” refers to inventory that disappears without generating revenue — theft, misplacement, vendor fraud, administrative error. For Walmart and its peers, the self-checkout kiosk transformed this line item from a manageable cost into a genuine crisis. Research cited by NetSuite and drawn from University of Leicester studies found shrink at self-checkout lanes running at 3.5% of sales — compared to just 0.2% at conventional cashier-staffed lanes. That is a 17-fold difference.
The scale of the theft problem became impossible to ignore. The National Retail Federation’s 2025 Impact of Theft & Violence report, based on surveys of retailers representing $1.3 trillion in annual U.S. sales, documented an 18% increase in average shoplifting incidents in 2024 compared to 2023. Threats or acts of violence during theft events rose 17% in the same period. And according to the Appriss Retail 2026 Total Retail Loss Benchmark Report, cited by security analysts at Safe and Sound, U.S. retailers lost an estimated $90 billion to inventory shrink alone in 2025.
These numbers demand context. The NRF figures have attracted legitimate methodological scrutiny — the organization discontinued its 32-year annual shrink survey in 2024 and replaced it with a survey of loss-prevention executives rather than hard inventory data, a change noted critically by analyst Judd Legum in Popular Information. Independent criminologists, including researchers at the Council on Criminal Justice, have noted that FBI property crime data suggests shoplifting rates in 2023 were actually lower than 2019 levels. Retailers and their lobby groups have strong incentives to amplify loss narratives. All of this is worth bearing in mind.
And yet — and this is the operative clause — none of it fully exonerates the self-checkout kiosk. Even if absolute theft levels are contested, the directional evidence that self-checkout generates disproportionately higher shrink than staffed lanes is substantial. The mechanism is obvious: unsupervised scanning creates frictionless opportunities for both deliberate fraud and unconscious non-scanning. A December 2025 LendingTree survey of 2,050 U.S. consumers found that 27% of self-checkout users admitted to intentionally leaving with at least one unscanned item, up from 15% in 2023, with another 36% saying they had accidentally done so — and of those, 61% simply kept the item rather than returning it.
The kiosk did not create dishonesty. But it systematically reduced the social and practical friction that discourages it.
What the Walmart Self-Checkout Changes of 2025–2026 Actually Mean
Walmart’s response to this reckoning has been strategically asymmetric — which is, in fact, the most interesting thing about it.
On one hand, the company is quietly retreating from pure self-checkout in high-theft, high-friction environments. On the other, it is simultaneously investing heavily in what might be called intelligent hybrid automation: AI-enhanced kiosks with computer-vision theft detection, mobile Scan & Go integration for Walmart+ members, digital shelf labels (being rolled out to 2,300 U.S. locations by 2026, per Money Digest), and a partnership with OpenAI to develop “Sparky,” a personalized shopping AI agent embedded in the Walmart app.
The Walmart self-checkout changes of 2025 and 2026, in other words, are not a retreat from technology. They are a recalibration of which technology, deployed where, in what combination with human labor.
Key Walmart self-checkout developments to track:
- AI surveillance integration: Walmart has deployed AI-powered cameras at self-checkout stations that detect missed scans in real time, generating overhead video replays for staff review. RFID tags and invisible barcodes are expanding to make fraud more technically demanding.
- 15-item limits and lane restrictions: High-shrink stores are now enforcing item caps, effectively redirecting large-basket shoppers to staffed lanes — where, not coincidentally, theft rates are dramatically lower.
- Walmart+ fast lanes: Paid membership holders gain access to expedited self-checkout pathways, creating a tiered experience that both rewards loyalty and generates data on high-trust shoppers.
- Staffing recalibration: New legislation in several states is also accelerating the calculus. States including California, Connecticut, Massachusetts, New York, Ohio, Rhode Island, and Washington are all pursuing laws that would mandate employee-to-kiosk ratios, item limits, or minimum staffed-lane requirements. The proposed 2026 framework in New York City would require at least one employee per three kiosks and cap self-checkout transactions at 15 items — daily fines of up to $100 per violation are the proposed enforcement mechanism.
The regulatory environment is no longer an afterthought. It is becoming a cost variable in the automation equation.
Sam’s Club’s Divergent Bet — and What It Tells Us
If Walmart’s core retail operation represents a strategic retreat from uncritical self-checkout expansion, then its subsidiary Sam’s Club is running an almost perfectly opposite experiment — and watching both simultaneously is the most instructive thing a retail strategist can do right now.
In April 2025, Sam’s Club President and CEO Chris Nicholas announced at Walmart’s Investment Community Meeting plans to phase out traditional checkout lanes entirely across all 600 U.S. locations. The replacement: an upgraded mobile Scan & Go system combined with “Just Go” — an AI-powered computer vision arch at store exits that identifies every item in a departing member’s cart within seconds, verifying payment without human intervention or receipt checks.
The Grapevine, Texas flagship, already operating on this model, is being positioned as the template for the club of the future. Sam’s Club reports a 23% faster exit time and an 11% jump in member satisfaction scores at locations using the exit technology, per Sam’s Club data published via Walmart Global Tech. The system — which the company emphasizes has been built and refined in-house rather than licensed from a third party — now processes millions of cart verification events with continuous AI learning.
“This is one of the fastest, most scalable transformations happening in retail today,” Nicholas declared. It is a remarkable statement, and not an entirely immodest one.
But here is the operative friction point: Sam’s Club’s model works, in significant part, because of who its members are and how they shop. Warehouse club members are higher-income, more tech-comfortable, and frequently motivated by the efficiency of a membership-model experience. They have already agreed to be tracked and verified as a condition of membership. Scan & Go adoption is high because the friction of using the app is lower than the friction of waiting in a warehouse checkout line.
The same logic does not translate cleanly to a Walmart Supercenter in a lower-income urban ZIP code, where smartphone penetration and app literacy are more variable, where basket sizes and product mixes are radically different, and where the social contract between store and shopper is less formalized. As analysts at Kiosk Industry have observed, mandating a phone-centric checkout model shifts accessibility barriers rather than eliminating them — from “can you reach the kiosk” to “do you own, understand, and trust the app.”
This is not a small distinction. Accessibility in retail is not merely a feel-good consideration; it is a market share consideration. Walmart serves roughly 255 million customers weekly across its global footprint. Designing its checkout architecture for the modal tech-comfortable shopper means designing it poorly for a substantial minority who aren’t.
The Competitive Landscape: Target, Costco, Dollar General, and the Checkout Wars
Walmart is not navigating this inflection point alone. The entire sector is conducting simultaneous experiments, arriving at fascinatingly varied conclusions.
Target moved earlier, limiting self-checkout to 10 items or fewer and granting store managers expanded discretion over lane ratios — a decentralization of checkout strategy that tacitly acknowledges no single formula fits every store format or customer demographic.
Dollar General took the most aggressive step. After rolling back self-checkout across thousands of locations and removing it entirely from roughly 300 stores most prone to shoplifting, the discounter reported year-on-year declines in merchandise shrink, with margin benefits expected to continue through 2025 and beyond. The data point is critical: removing self-checkout worked, financially, at Dollar General. The lesson may not transfer at scale to a Walmart, but it illustrates that the industry’s reflexive assumption — that more automation equals more efficiency equals more profit — was simply wrong at certain store formats and customer profiles.
Costco has taken the most contrarian position of all, essentially refusing to deploy meaningful self-checkout and continuing to invest in staffed checkout as a core element of its customer experience model. Its membership satisfaction scores remain among the highest in retail. The choice reflects a brand philosophy in which human interaction is itself a product feature — one that justifies the membership fee and sustains the loyalty that drives Costco’s extraordinary repeat-visit rates.
Three large, successful retailers. Three different answers to the same question. This, more than any individual data point, captures the true complexity of the self-checkout debate.
Customer Psychology and the Invisible Labor Transfer
There is a dimension of the self-checkout conversation that rarely surfaces in earnings calls or loss-prevention reports, and that is the labor it invisibly transfers onto the customer.
When Walmart or any retailer installs a self-checkout kiosk, it is not merely automating a process — it is outsourcing a job. The customer becomes the cashier: scanning, bagging, managing payment, troubleshooting errors, and navigating produce codes for items that have no barcode. This is unpaid labor. Research in consumer psychology has consistently shown that customers who experience friction — unexpected machine errors, weight-sensor failures, age-verification holds, the familiar indignity of waiting for an attendant to clear a flagged transaction — develop measurable negative associations with the retailer. The satisfaction hit from a failed self-checkout attempt is not recoverable with a receipt coupon.
This matters enormously in the context of Walmart’s competitive positioning. The company has, over the past several years, made remarkable strides in attracting higher-income shoppers who have historically preferred Target or specialty grocers. Its investments in store design, private-label quality, and digital integration reflect an understanding that the brand ceiling is not fixed. A dysfunctional self-checkout experience — or worse, a system that implicitly treats every customer as a potential shoplifter through overhead cameras, weight-sensor lockouts, and receipt verification demands — works directly against that repositioning effort.
The dignity question is real. It was articulated bluntly by customer advocates and disability rights organizations when retailers began deploying surveillance-heavy self-checkout enhancements: being required to scan under a camera, have your items visually verified, and prove your exit to an AI archway feels, to many shoppers, less like convenience and more like a checkpoint. The analogy to airport security is not accidental — it is, in fact, exactly how observers have described Walmart’s newer checkout gate designs. Airports do not inspire warmth or loyalty. Grocery stores that feel like airports will not, either.
The Labor Question: Automation, Jobs, and the Political Economy of the Checkout Lane
Any serious analysis of Walmart’s evolving self-checkout strategy must eventually engage the labor dimension — not merely as an ethical sidebar, but as a structural business variable.
Walmart employs approximately 1.6 million people in the United States alone. Self-checkout, as originally deployed, carried an explicit promise to reduce headcount at the front end. That promise was partially delivered. But the hidden costs — in shrink, in customer dissatisfaction, in regulatory exposure, in associate morale — have materially complicated the calculus.
When Dollar General reduced self-checkout, shrink declined. When Walmart removed kiosks from Shrewsbury, police calls dropped by two-thirds. Neither outcome was achieved by technology. Both were achieved by reintroducing human presence. The employee, it turns out, is not merely a cost line to be optimized away. The employee is, in significant contexts, the product: the deterrent, the problem-solver, the face of the brand.
Sam’s Club frames this carefully. “Our 100,000 associates remain central to the company’s momentum,” the company said alongside its Scan & Go announcement. AI, it insists, frees workers from repetitive tasks to focus on “more meaningful and engaging responsibilities.” This is the optimistic version of retail labor’s future, and it may be genuinely sincere. It is also, inevitably, the framing a company uses when it is reducing labor at the front end and needs the remaining workforce not to panic.
The honest answer is that the labor implications of Walmart’s hybrid automation strategy remain unresolved. Fewer cashiers are needed to staff a fleet of AI-monitored kiosks than to run an equivalent number of traditional lanes. The jobs that replace them — app support, tech troubleshooting, loss-prevention response — require different skills and, often, different people.
The Future of Walmart Self-Checkout: What 2026 and Beyond Actually Looks Like
The future of Walmart self-checkout is neither the triumphant frictionless utopia that Silicon Valley adjacent retail-tech optimists promised, nor the simple return to cashier-staffed lanes that populist critics occasionally demand. It is something more interesting and more operationally complex than either.
The emerging model — visible in Walmart’s own pilot programs, Sam’s Club’s architectural bets, and the competitive movements across the sector — looks something like this:
Stratified checkout by basket type. Self-checkout survives, robustly, for small-basket express transactions. The 15-item limit is not a retreat from automation; it is a rationalization of which use cases automation actually serves well. A customer buying toothpaste and a protein bar does not need a cashier. A customer buying a week of groceries for a family of five, including three types of loose produce, two items with security tags, and a baby formula that requires age verification, arguably does.
AI-augmented kiosks with real-time verification. Computer vision systems that flag missed scans, alert attendants to suspicious behavior, and log transactions for loss-prevention review are becoming standard rather than premium. This technology doesn’t eliminate the need for human oversight; it makes human oversight dramatically more scalable.
Mobile-first checkout for high-trust, high-loyalty customers. Scan & Go will expand — but its growth will be fastest in formats where the membership model creates a pre-verified, tech-comfortable customer base. For mainstream Walmart, it will remain an option, not a mandate.
Staffed lanes as a premium service feature. The most counterintuitive development is the reframing of the human cashier from cost liability to competitive differentiator. Retailers that invest in fast, friendly staffed checkout — and design the store experience to make it genuinely faster than the automated alternative — may discover they have a sustainable advantage in customer satisfaction scores that no kiosk upgrade can replicate.
The most important question Walmart and its peers must answer is not “how do we automate checkout?” It is “what does our customer actually want when they arrive at the front of the store, and how do we design for that outcome at the lowest total cost, including shrink, regulatory risk, and customer dissatisfaction?”
That is a more complex optimization problem than it appeared in 2010. Which is why the self-checkout lane — that small, humming monument to retail’s love affair with efficiency — is no longer a settled solution.
It is, once again, an open question.
Conclusion: The Limits of the Frictionless Ideal
Automation in retail is not a mistake. It is, in many contexts, genuinely better — faster, cheaper, more consistent than the human alternative. But the self-checkout experiment at scale has produced something more instructive than either its advocates or critics anticipated: a detailed empirical record of where the frictionless ideal encounters the resistant reality of human behavior.
People steal more when no one is watching. People feel more surveilled when machines treat them as suspects. People choose convenience differently depending on basket size, technology comfort, and what they silently expect from the relationship between a store and its customer. These are not engineering problems. They are behavioral and social ones, and no algorithm — however elegantly trained on exit-arch cart images — fully resolves them.
Walmart’s ongoing Walmart self-checkout changes in 2025 and 2026 are not a failure. They are a maturation: a company large enough to run controlled experiments at civilizational scale, learning, store by store, that the optimal checkout model is not universal. It is contextual. The Shrewsbury data point — 509 police calls reduced to 183 simply by returning a human being to the front of the store — may be the most quietly important retail insight of the decade.
What comes next will be a hybrid architecture: AI-enhanced kiosks where they work, human cashiers where they don’t, mobile checkout where the customer wants it, and staffed express lanes for everything in between. Retailers that treat this as a nuanced design challenge — rather than a cost-reduction mandate dressed up in the language of customer experience — will pull ahead.
The rest will keep getting that “unexpected item in bagging area” error. And this time, they’ll have no one to wave a card and say: I know. I’m sorry. This happens constantly.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Asian Stock Markets 2026: Japan, China, Pakistan & More

Mortgage Rates Today 2026: Full Rate Guide & Forecast

Beyond Paper Wealth: Unpacking Donald Trump’s Multibillion-Dollar Liquidity and Legal Crisis

Bitcoin & XRP 2026: Inside Crypto’s Institutional Era

Global Economy 2026: IMF Growth, AI Stocks & Market Risk

China’s Local Debt Race Against Time: Why Economists Demand Central Action Before the Deflation Window Closes

Money News: How to Protect Your Portfolio From Global Inflation

World Bank Projections: Emerging vs. Big Economies of Asia

IMF Reports 2026: What the Latest Data Means for the Global Economy

Singapore Stocks Outlook: A Safe Haven in the Asian Market?

China Stocks vs. Japan Stocks: Where Should You Invest in Late 2026?

VIX Index Explained: How to Trade Wall Street’s Fear Gauge Today

Commercial vs Residential Real Estate: Which Wins in 2026?

Presidential Stock Market Performance: How Trump’s Second Term Compares to History

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

BRICS+ Cross-Border Payments 2026: Interoperability Explained

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

Leveraging Viral AI & Climate Hashtags for Brand Growth on X
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025