
Global Finance
Fast Invoice Factoring: Rates, APR Math & Contract Traps

Fast invoice factoring converts unpaid B2B invoices into cash within one to two business days at a discount fee that typically runs 1% to 5% of invoice value per 30 days, with advance rates of 80% to 100% depending on the provider. On an annualized basis, that fee can equate to roughly 12% to 60% or more, which is why CFOs should compare factoring on effective APR rather than the headline rate.
Provider pricing in this guide is drawn from Forbes Advisor’s factoring rankings and NerdWallet’s factoring company guide. Legal framing references the Uniform Commercial Code as published by Cornell Law School. Ranges move with credit conditions; confirm live quotes before you sign.
Executive Summary & Core Benchmarks
Factoring is an asset sale, not a loan. You sell receivables to a factor, receive an advance, and get the reserve back after your customer pays, minus fees. Your customers’ credit quality matters more than yours.
| Metric | 2026 Benchmark | Source signal |
|---|---|---|
| Factoring fee | 1%-5% per 30 days (some tiers 2.5%-5%) | Forbes Advisor lists 2.5%-5% for one online leader |
| Advance rate | 80%-100% of invoice face value | NerdWallet lists advances up to 90% and 100% (minus fees) |
| Lowest published starting fee | ~0.8% | NerdWallet on a direct-lender factor |
| Funding speed | Next-day standard; same-day for an added fee | Forbes Advisor |
| Origination fees | $150-$500 or up to 1% of the advance | NerdWallet |
| Spot factoring | Often 3%-6% per invoice | Higher price for no commitment |
| Effective APR on a 2% / 30-day fee | Roughly 24%-27% | Calculated below |
| Target payback logic | Use only when gross margin exceeds annualized cost | See ROI section |
Key takeaway: The fee is the visible price. The reserve holdback, ancillary charges and days-to-pay determine the real price.
1: Strategic Overview & Commercial Drivers
B2B growth companies hit a structural cash gap. You pay salaries, contractors and cloud bills this month. Your customers pay on net-30, net-60 or net-90 terms. Growth widens the gap because each new contract requires working capital before revenue arrives.
Factoring closes that gap without new debt on the balance sheet. It suits companies with creditworthy commercial customers, invoices that are undisputed, and a need for speed.
Where factoring fits in the capital stack
Factoring is not a replacement for every financing product. Position it by use case.
- Bank line of credit: cheaper when you qualify, slower to arrange, and tied to your own credit and financials.
- Term loan: suits capital expenditure, not receivables timing.
- Invoice factoring: best when speed matters and your customers’ credit is stronger than yours.
- Spot factoring: best for one-off cash crunches, at a premium.
Some providers do not run a traditional credit check on the applicant. Forbes Advisor’s review notes one lender evaluating bank account and accounting software data instead, and requiring invoices to be under 90 days old.
Unit economics: when it pays
Factoring pays when the gross profit on work you can now afford to accept exceeds the factoring cost.
Factoring Net Benefit = (Incremental Gross Profit Enabled) − (Factoring Fees + Ancillary Fees)
An illustrative example: a $100,000 invoice factored at 3% total fee costs $3,000. If access to that cash lets you fulfill a second $100,000 order at 35% gross margin, you earn $35,000. The net benefit is $32,000. If the cash only prevents a late vendor payment with no growth effect, the math is much weaker.
2: Comprehensive Evaluation Matrix
Compare providers on five quantitative vectors: fee, advance rate, speed, fees beyond the discount rate, and fit. The data below is published by the outlets cited. Pricing bases differ, so read the footnotes.
Table 1: Provider comparison
| Provider (as reviewed) | Published factor fee | Advance rate | Funding speed | Additional costs and fit |
|---|---|---|---|---|
| FundThrough | 2.5%-5% (Forbes Advisor); 2.75%-8.25% on 30-day terms (NerdWallet) | Up to 100% minus fees | Next day; same-day costs extra | No credit check; invoices must be under 90 days; funding up to $10 million |
| altLINE (division of a bank) | From ~0.8% (NerdWallet) | Up to 90% | Fast; direct-lender decisions | Origination fee $150-$500 or up to 1% of advance |
| RTS Financial | Quote-based | Trucking-focused | Within 24 hours via web portal | Specialist for trucking and freight |
Why do Forbes Advisor and NerdWallet list different FundThrough ranges? They appear to reflect different pricing bases and time periods. Treat any published range as a starting point for negotiation, not a quote.
Table 2: Factoring structure comparison
| Structure | Who bears customer non-payment | Cost profile | Best for |
|---|---|---|---|
| Recourse factoring | You | Lower fees | Companies with reliable customers |
| Non-recourse factoring | Factor, within defined credit-loss limits | Higher fees; often with exclusions | Concentrated or higher-risk receivables |
| Spot factoring | Depends on contract | 3%-6% per invoice per one provider guide | One-off needs |
| Contract factoring | Depends on contract | Lower rate, volume commitments | Predictable monthly volume |
| Non-notification | Depends on contract | Customer does not see the factor | Brand-sensitive relationships |
Prime-plus pricing also exists. One provider guide describes structures tied to the prime rate plus a spread, which may suit large invoice volumes (Crestmont Capital).
3: Step-by-Step Implementation & Procurement Blueprint
Run factoring like a procurement project, not a panic button.
Implementation framework
- Audit your receivables. Age every invoice. Flag disputes, retainage, milestone billing and related-party customers. Factors reject disputed invoices.
- Rank customers by credit quality. Your best-paying enterprise customers are your most financeable.
- Calculate your cash-conversion gap. Use: Days Sales Outstanding − Days Payable Outstanding. A large positive gap is the structural need.
- Decide the structure. Recourse for low-risk books. Non-recourse when concentration risk is high. Spot for one-off events.
- Request written quotes from three factors. Ask each for the full fee schedule: discount rate, tier steps after day 30, origination, ACH or wire fees, same-day funding fees, minimums and termination fees.
- Model the effective APR for each quote at your actual average days-to-pay.
- Review the lien scope. Confirm whether the factor files a blanket lien on all assets or only on the receivables it buys.
- Negotiate the contract. Focus on term length, minimum volume, auto-renewal notice and early termination.
- Notify customers appropriately. Under UCC Section 9-406, an account debtor may pay the assignor until it receives authenticated notification of the assignment. After notification it must pay the assignee (Cornell LII: UCC 9-406).
- Pilot with one customer. Test funding speed, reporting and collections tone before you factor the whole book.
Risk checks before signing
- Customer concentration: if one customer exceeds a large share of your invoices, expect concentration caps.
- Cross-default: does factoring default trigger a default under your bank facility?
- Existing liens: a prior lender’s blanket lien may conflict with the factor’s security interest.
- Reporting burden: confirm what schedules and verification the factor requires.
Model your effective APR before you sign. Use our factoring calculator to compare three offers on the same invoice batch. Open the calculator
4: Cost Analysis, Contract Traps & ROI Mathematics
Core fee math
A factoring transaction has three moving parts: the advance, the reserve and the fee.
Advance = Invoice Face Value × Advance Rate
Reserve = Invoice Face Value − Advance
Rebate to You = Reserve − Factoring Fees
Net Proceeds = Advance + Rebate
Worked example. A $100,000 invoice, 85% advance rate, and a fee of 2% for the first 30 days plus 0.5% per additional 10-day period. The customer pays on day 50.
- Advance: $85,000
- Reserve: $15,000
- Fee: 2% + (2 × 0.5%) = 3% = $3,000
- Rebate: $15,000 − $3,000 = $12,000
- Net proceeds: $97,000
The tiered fee structure mirrors examples published by Crestmont Capital. Your contract’s tiers will differ.
Effective APR formula
Factors quote per-period fees. Lenders quote annual rates. Convert to compare.
Effective APR ≈ (Total Fee ÷ Cash Advanced) × (365 ÷ Days Outstanding)
For the example above: $3,000 ÷ $85,000 = 3.53%. Multiply by 365 ÷ 50 = 7.3. The effective APR is about 25.8%.
Notice that a simple 2% fee on a 30-day invoice with a 100% advance is about 24% annualized, and a lower advance rate raises the effective rate because the fee is charged on the full face value while you receive less cash. Always use cash advanced in the denominator.
Cost stack beyond the discount rate
| Cost line | What to ask | Typical signal |
|---|---|---|
| Discount fee | Flat or tiered? Step-up after day 30? | 1%-5% per 30 days is common |
| Origination fee | One-time or per schedule? | $150-$500, or up to 1% of the advance, on one direct lender (NerdWallet) |
| Same-day funding | Per-transaction fee? | Extra charge noted by Forbes Advisor |
| Early payment or rebate mechanics | How is the reserve released? | Varies |
| Monthly minimums | Fee if volume falls short? | Frequently negotiable |
| Termination fees | Penalty for leaving early? | Check notice periods |
| Lockbox and ACH fees | Who pays banking costs? | Small but recurring |
Contract traps
- Minimum volume clauses. You pay a fee even if you factor less than the agreed minimum.
- Auto-renewal with long notice. Negotiate notice windows down to 30 days where possible.
- Broad lien language. A lien covering all assets can block other financing.
- Notification control. Confirm the factor’s collection communications will not damage customer relationships.
- Chargeback and dilution rules. Understand how credits, discounts and disputes are treated.
- Anti-assignment clauses. Many customer contracts prohibit assignment. UCC 9-406(d) generally makes such terms ineffective against the assignment of accounts, but it has exceptions; read the text as codified in your state, for example New York’s version on FindLaw.
Ask counsel to review each of these. This guide is not legal advice.
ROI framework
Annualized Cost of Factoring = Effective APR × Average Cash Advanced Outstanding
Decision Rule: Factor when Incremental Gross Margin on Enabled Revenue exceeds Annualized Cost of Factoring plus internal administration cost.
If your gross margin is 20% and your effective factoring APR is 26%, factoring does not pay unless it prevents costlier outcomes such as missed payroll or lost contracts. If gross margin is 60%, the same APR is easily justified for growth spending.
5: Regulatory Compliance & Industry Standards
Factoring in the United States is governed mainly by state law under the Uniform Commercial Code, plus contract law and, for some structures, lending or usury statutes. Compliance points to know:
UCC Article 9
Article 9 covers sales of accounts and security interests in them. Factors typically file a UCC-1 financing statement to perfect their interest. Section 9-406 governs how an account debtor discharges its obligation and how notification of assignment works. The full text is available at Cornell LII.
Customer notification and payment redirection
After proper notification, your customer must pay the factor. If the customer pays you by mistake after notification, you hold those funds for the factor. Build a process to remit misdirected payments immediately. Failure to do so is a fast route to default.
Anti-assignment provisions
Many enterprise customer agreements contain no-assignment language. Statutory overrides exist for accounts, but customers may still resist. Check the specific state code and the customer agreement.
Lien coordination
If you already have a bank facility, seek an intercreditor or carve-out so the factor’s lien on receivables does not breach your bank covenants. Get written consent early.
Financial reporting
Whether factoring is treated as a sale or a secured borrowing on your balance sheet depends on contract terms and accounting standards. Confirm treatment with your auditor before you sign, because it affects covenant calculations.
Sanctions and KYC
Factors run know-your-customer checks on you and your customers. Expect requests for corporate documents, beneficial ownership and customer invoices.
Need a factoring contract review? Connect with commercial finance counsel who negotiate lien scope, minimums and termination terms. Find counsel
6: Enterprise Frequently Asked Questions (FAQ)
How fast can invoice factoring fund?
Many online factors fund within one business day after setup. Same-day funding is available from some providers for an added fee (Forbes Advisor). Initial onboarding, including account linking and verification, can take a few days.
What does fast invoice factoring cost?
Published ranges cluster at 1% to 5% of invoice value per 30 days, with some lenders starting near 0.8% and others quoting up to 8.25% on 30-day terms. The effective APR depends on the advance rate, tier step-ups and how long your customer takes to pay. A 2% fee over a 30-day invoice is roughly a 24%-27% annualized cost.
Is invoice factoring a loan?
Structurally, factoring is the sale of receivables, not a loan. That is why approval focuses on your customers’ creditworthiness. Accounting and legal treatment can vary by contract, so confirm with your auditor and counsel.
Recourse or non-recourse: which should a growth company choose?
Recourse factoring is typically cheaper because you keep the credit risk. Non-recourse shifts some of that risk to the factor, usually at a higher fee and with exclusions, such as disputes. Choose based on customer concentration and how reliably your customers pay.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The Democratic sweep of Congress in the November 3, 2026 midterms pulled the 10-year U.S. Treasury yield lower, as investors priced in a possible check on new federal borrowing. The benchmark fell from about 4.95% to 4.89% on election-week trading, and dipped to roughly 4.83% by November 5, its lowest level since September, according to market data reported by Morningstar/Dow Jones and Trading Economics. The move is real, but history suggests it is a weak guide to where yields go next.
Key Takeaways
- The 10-year yield fell roughly 50 basis points from its early-October highs, which had reached multi-decade levels, according to WisdomTree’s rates analysis.
- Bond investors read divided or gridlocked government as a possible brake on borrowing, but that thesis is contested.
- The Federal Reserve, not the election, is the bigger near-term driver. Markets have discussed a possible December rate hike.
- WisdomTree’s central expectation is a 10-year trading range of 4.50% to 5.25% into the coming months.
- Post-midterm history is mixed: Bloomberg-compiled data show yields were lower on average one and 12 months after comparable results, but individual cases vary widely.
Why the Election Moved Bonds at All
Bond markets care about supply. Every dollar of federal deficit must be financed by Treasury auctions, and the more the government borrows, the more investors must be paid to hold the debt. A unified Democratic government could theoretically expand spending, which would normally push yields up. The election result, however, was read as the opposite: a divided or narrowly controlled Washington that makes large new spending bills harder to pass.
That interpretation drove the initial rally. Morningstar reported that the two-year yield fell to a two-month low of 4.546% on the day after the results, while the 30-year yield declined from 5.323% to 5.282%. The sharpest moves came in the front end of the curve, where investors had been pricing a more aggressive Fed.
Bond strategists are not fully convinced. WisdomTree argues that divided government may not reduce deficits at all, because bipartisan spending agreements and existing fiscal commitments can keep Treasury borrowing needs high regardless of who controls Congress. In other words, the political headline may matter less than the arithmetic of entitlement spending, interest costs, and tax policy already on the books.
The Fed Matters More Than Congress
For the next several months, Federal Reserve policy is likely to outweigh the midterms in setting the tone for Treasuries. Through September, Fed officials had signaled that further rate increases might be needed to bring inflation back toward target, and markets priced at least one more hike for 2026. WisdomTree’s analysis suggests the election should have only limited direct effect on that policy path, with a December move still possible after October’s jobs report.
This matters for bond investors because a rate hike shifts the short end of the curve first, but it also influences long-term yields through inflation expectations and term premiums. If the Fed tightens while the market doubts the government’s fiscal discipline, the long end can rise even as short-term yields stabilize.
A practical framework for readers tracking this:
- Watch the Fed’s December decision and the statements that accompany it. A hawkish surprise will likely lift yields across the curve.
- Track monthly jobs and inflation data. Strong employment and sticky price pressures have been the main reasons yields rose this autumn.
- Monitor Treasury auction results. Weak demand at longer maturities is an early sign that investors are demanding more compensation for duration risk.
- Follow oil prices and geopolitical headlines. Energy-driven inflation expectations have repeatedly pushed yields around in 2026.
What the Historical Record Actually Shows
Midterm years are often assumed to produce predictable bond outcomes, but the record is noisy. Analysis from Capital Group and others cited in recent market commentary found that, from the mid-1950s through 2022, the 12 months ending in November of midterm years produced roughly a coin-flip pattern: an average change of about one basis point, a median close to zero, and yields rising in roughly half of cases.
Two comparisons illustrate how unreliable the political signal can be. In 1983, a Republican president faced a Democratic House and a Republican Senate, and the 10-year yield rose by about 129 basis points. In 2019, under a broadly similar political structure, the yield fell by about 97 basis points. Same configuration, opposite outcomes. The difference was inflation, Fed policy, and growth conditions, not the partisan label.
Bloomberg-compiled data offer a more favorable reading for the current situation. Benchmark 10-year yields have tended to be lower on average one and 12 months after midterms that produce a comparable result. That pattern is suggestive rather than predictive. A sample of a few dozen election cycles cannot isolate the effect of partisan control from the macro environment at the time.
Where Yields Could Go Into 2027
The most useful way to think about the 10-year yield is as a range shaped by three forces: Fed policy, inflation expectations, and the supply of Treasury debt. Each is currently pulling in a different direction.
Upward pressure comes from persistent inflation, a Fed still open to tightening, and a large federal deficit that requires heavy issuance. The 10-year yield’s early-October run to multi-decade highs showed how quickly sentiment can shift when those factors align.
Downward pressure comes from a possible slowdown in economic growth, a flight to safety during equity sell-offs, and a political environment that may limit new spending. Equity weakness in early November temporarily supported Treasuries as investors sought safe assets.
Given these crosscurrents, WisdomTree’s expected range of 4.50% to 5.25% is a reasonable planning band rather than a forecast of a specific level. Readers should treat any single-point projection with caution. The distribution of outcomes is wide, and the main risk is a surprise from the Fed or a sharp repricing of inflation.
What This Means for Borrowers, Savers, and Investors
For homebuyers and businesses, the 10-year yield is the reference point that anchors mortgage rates and many corporate borrowing costs. A move toward the lower end of the expected range would ease pressure on mortgage pricing, while a return above 5% would likely keep housing affordability constrained.
For savers, higher yields on short-term Treasuries remain attractive, but the trade-off is reinvestment risk if the Fed eases later. Investors holding long-duration bonds face the opposite exposure: they gain if yields fall and lose if inflation or fiscal worries push them higher.
Practical steps for individuals with exposure to rates:
- Match bond duration to your time horizon rather than trying to time the election-driven moves.
- Consider how much of your portfolio is sensitive to a 50 to 100 basis point move in yields.
- Revisit fixed-rate debt decisions if your borrowing plans are tied to mortgage or refinancing timelines.
Frequently Asked Questions
Did the midterm elections cause Treasury yields to fall?
The results contributed to a decline. The 10-year yield dropped after the Democratic sweep, as investors interpreted divided or constrained government as a possible limit on new borrowing. Other factors, including oil prices, Fed commentary, and an equity sell-off, also influenced the move.
Where is the 10-year Treasury yield now?
In the days after the election, the 10-year traded in the high 4% range, with reports placing it near 4.83% to 4.9% in early November. Yields move daily, so check a live source such as the Treasury Department’s daily yield curve before making decisions.
Will the Fed raise rates in December 2026?
A December hike remains possible, according to WisdomTree’s analysis, particularly if October’s jobs data and inflation readings keep pressure on the Fed. Markets are not certain, and the outcome will depend on incoming data.
Do midterm elections reliably move bond markets?
No. Historical comparisons show wide variation. Bloomberg-compiled data suggest yields have tended to be lower in the year after comparable midterms, but cases such as 1983 and 2019 demonstrate that inflation and Fed policy usually matter more than the political configuration.
What is a reasonable 10-year yield range for 2027?
WisdomTree’s current central range is 4.50% to 5.25%. This is a planning band, not a precise forecast, and the outcome depends heavily on inflation and Fed decisions.
Does a divided Congress reduce the federal deficit?
Not necessarily. Analysts note that bipartisan spending deals and existing fiscal commitments can keep borrowing high even under divided government, so the deficit trajectory depends on policy choices beyond party control.
How should I position a bond portfolio after the midterms?
Focus on duration that matches your time horizon, diversify across maturities, and avoid making large directional bets based on the election alone. Consider consulting a licensed financial adviser for decisions tied to your specific situation.
Conclusion: Watch the Fed and the Deficit, Not Just the Vote
The 2026 midterms moved Treasury yields, but the lasting story is likely to be the interaction between Fed policy and federal borrowing. The election gave bond investors a reason to hope for fiscal restraint, yet the arithmetic of deficits and inflation has not changed. Readers should expect volatility, track the December Fed decision and incoming inflation data, and treat any single forecast with skepticism.
For ongoing coverage, follow Treasury auction results, Fed communications, and monthly economic releases. Those signals will tell you more about where yields are headed than the election headline alone.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global merchandise trade continues to expand in 2026 even as the United States and other major economies impose sweeping tariffs and non-tariff barriers. The WTO’s Goods Trade Barometer reached 102.0 in September 2026, remaining comfortably above the 100 baseline that signals trend growth. AI-related goods have become the dominant driver, accounting for a sharply rising share of incremental trade volumes and offsetting the drag from higher duties. WTO data via Peacock Tariff Consulting
This resilience is not uniform. Traditional consumer and intermediate goods face clearer headwinds, while semiconductors, servers, networking equipment, and other AI infrastructure components are expanding rapidly. At the same time, Section 301 measures and broader tariff actions have accelerated supply-chain diversion toward Vietnam, India, Mexico, and selected other locations. Economic Times citing DHL-Stern and WTO/OECD
For businesses, investors, and policymakers the central question is whether AI-driven capital expenditure can keep outweighing protectionist pressures through 2027, or whether a slowdown in hyperscaler spending would quickly expose the underlying fragmentation of the trading system.
Table of Contents
- Why Is Global Trade Growing Despite High Tariffs?
- What Does the WTO Goods Trade Barometer Actually Show?
- How Are AI Goods Driving Trade Volumes?
- What Role Do Section 301 and Other Tariffs Play?
- Which Countries Are Winning and Losing from Diversion?
- What Are the Risks to the 2026–27 Outlook?
- Key Takeaways
- Frequently Asked Questions
Why Is Global Trade Growing Despite High Tariffs?
Merchandise trade volumes rose in the first half of 2026. WTO figures indicated roughly 1.9 percent quarter-on-quarter growth in the first quarter and stronger year-on-year comparisons. The composition of that growth matters more than the headline: restrictive measures (tariff increases, import bans, quantitative restrictions, and subsidies) have surged, yet overall volumes have not contracted. Peacock Tariff Consulting
Two forces dominate. First, explosive demand for AI-enabling goods. Second, firms’ ability to absorb, reroute, or re-invoice around higher duties rather than halt trade. DHL and NYU Stern raised their 2026 goods-trade growth forecast to 4.6 percent, explicitly citing adaptation and the AI boom. Almost three-quarters of cross-border commerce still occurs under relatively low WTO-bound tariff rates, providing a floor. Economic Times
What Does the WTO Goods Trade Barometer Actually Show?
The September 2026 reading of 102.0 was up from 101.7 in June and sits above the index’s long-term baseline of 100. Component indicators linked to export orders, international air freight, and container shipping remained supportive. The barometer is a leading indicator; hard volume data through mid-2026 have largely confirmed the signal. Peacock Tariff Consulting
Importantly, the index captures activity even while the policy environment is the most restrictive in a generation. Trade-easing measures have lost relative momentum, so the expansion is occurring against a deteriorating rules backdrop.

How Are AI Goods Driving Trade Volumes?
AI-related products accounted for approximately 42 percent of merchandise trade growth in 2025. That share jumped toward 76 percent of incremental growth in the first quarter of 2026, according to WTO and OECD data referenced in recent analyses. Semiconductors, high-bandwidth memory, servers, and networking gear have become the single largest growth engine. Economic Times
This concentration creates both upside and vulnerability. As long as hyperscalers and sovereign AI projects continue heavy capital expenditure, trade volumes receive a powerful tailwind. Any pause or downward revision in those spending plans would subtract the primary growth driver almost immediately.
What Role Do Section 301 and Other Tariffs Play?
In 2026 the United States layered additional Section 301 tariffs covering a very large share of imports from major partners, with many rates in the 10–12.5 percent range and higher duties on selected products. These measures were partly framed around forced-labour and supply-chain security concerns. Earlier IEEPA-based actions faced legal challenges, prompting reliance on other authorities. Peacock Tariff Consulting
The practical effect has been higher landed costs and accelerated diversion rather than a collapse in total trade. Companies have shifted assembly, testing, and final billing locations while still moving physical goods.
Which Countries Are Winning and Losing from Diversion?
Vietnam, India, and Mexico have been the clearest near-term beneficiaries in electronics and certain intermediate goods. Smaller exporters in South and Southeast Asia have faced collateral damage from higher baseline tariffs that do not distinguish finely among sources. China’s direct share has been under pressure, yet Chinese-owned or Chinese-linked capacity in third countries has often captured the redirected orders. [Economic Times and related trade analyses]
Trade Growth Drivers 2026 – Comparative Impact
| Driver | Volume Impact | Policy Sensitivity | Durability | Notes |
|---|---|---|---|---|
| AI / semiconductor goods | Strong positive | Medium | High if capex holds | Dominant engine |
| Traditional consumer goods | Modest / negative | High | Low | Tariff-sensitive |
| Energy & commodities | Mixed | High | Geopolitical | Hormuz / sanctions risk |
| Digital services | Positive | Lower | High | Outside goods barometer |
What Are the Risks to the 2026–27 Outlook?
The largest downside risk is a slowdown in AI infrastructure spending. Secondary risks include further tariff escalation, successful legal challenges that create uncertainty, energy or shipping disruptions, and a broader global growth disappointment. Upside would come from faster-than-expected supply-chain adaptation or additional fiscal support for strategic industries in multiple countries.
Key Takeaways
- WTO Goods Trade Barometer remains above 100 despite record tariffs and restrictions.
- AI-related goods are the primary reason volumes are still rising.
- Section 301 and parallel measures are redirecting rather than stopping flows.
- Vietnam, India, and Mexico are the clearest diversion winners so far.
- A slowdown in hyperscaler and AI capital expenditure is the biggest threat to the outlook.
Frequently Asked Questions
Is global trade actually growing in 2026?
Yes. WTO volume data, the Goods Trade Barometer, and independent forecasts such as DHL-Stern all show positive growth led by AI goods.
Why hasn’t the tariff surge collapsed trade?
Firms are rerouting supply chains and AI demand is currently strong enough to more than offset higher costs in the fastest-growing categories.
Which countries benefit most from trade diversion?
Vietnam, India, and Mexico have captured the largest redirected flows in electronics and related intermediate goods.
What is the single biggest risk to the current trade outlook?
A sharp slowdown or deferral in AI-related capital spending by hyperscalers and governments.
How do the 2026 Section 301 tariffs differ from earlier rounds?
They are broader in coverage, sit on top of existing duties, and have been paired with other restrictive tools, producing wider diversion effects.
Conclusion
Global trade in 2026 is being pulled in opposite directions: the most restrictive policy environment in decades on one side and an historic AI infrastructure boom on the other. So far the boom is winning, keeping the WTO barometer above trend and supporting positive volume growth. For economy, finance, and foreign-policy audiences, the critical variables to watch through 2027 are hyperscaler capex guidance, the durability and legal status of Section 301 measures, and whether diversion gains in Asia and Mexico prove structural. The next four to six quarters will reveal whether AI demand can continue to mask a more fragmented trading system or whether protectionism finally exerts a clearer drag.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
How economic globalization shapes the US economy, from record trade and the 35% fall in factory jobs since 1979 to wage stagnation and the 2025-26 tariffs.
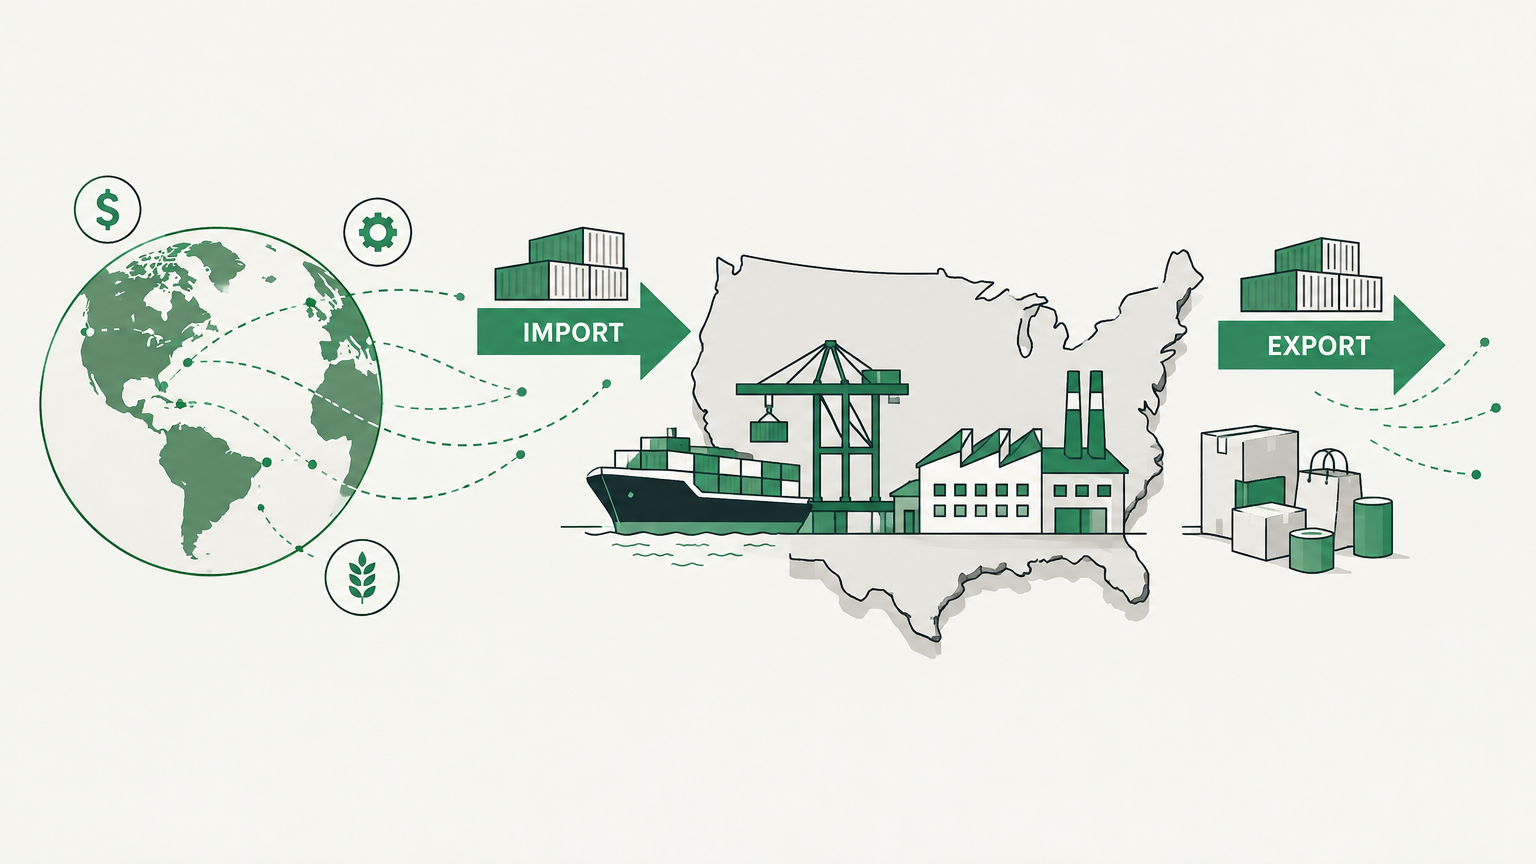
Economic globalization is the integration of national economies through trade, investment and capital flows, and for the United States it works out to a mixed ledger rather than a single verdict. In 2025 the US exported $3,432.3 billion of goods and services and imported $4,333.8 billion, running a record $1.2 trillion goods deficit beside a record $339.5 billion services surplus (BEA/Census, Census Bureau). Factory employment has fallen 35 percent since its June 1979 peak (BLS). And the tariffs built to reverse that now average just over 12 percent, adding about $1,230 a year to the average household (PIIE).
Three findings do most of the work in this debate:
- The gains are thin and spread out; the losses are deep and concentrated. Cheaper imports help every shopper a little, while factory closures hit particular towns hard, which is why the politics of trade run louder than the economics.
- The trade deficit is a poor scoreboard. It edged down in 2025 even as the goods deficit hit a record, and tariffs appear to have rerouted trade toward Mexico, Vietnam and Taiwan rather than removing it (Census Bureau).
- The evidence on factory jobs is more nuanced than the headlines. The government’s own long-run data ties the 35 percent fall in manufacturing employment mainly to a shift toward services and to recessions, not to imports alone (BLS).
The rest of this guide works through what each side of the ledger actually contains, and what the CHIPS Act, USMCA and the 2025-26 tariffs do about it.
What economic globalization means for the United States
Economic globalization is the growing integration of national economies through trade in goods and services, cross-border investment, capital flows, and the movement of people and ideas. In the United States it shows up as cheaper imports, larger export markets, and more competition at home.
That is the neutral definition. The argument starts with what you count. A shopper buying a $200 television and a machinist in Ohio whose plant has closed are both describing the same phenomenon from opposite ends, which is why the pros and cons of globalization in America never quite settle. The honest answer is that the impact of economic globalization on the US economy is not one number but a ledger, and in 2025 and 2026 both sides of it moved at once.
This guide works through the ledger in order: what the United States sells and buys, where the manufacturing jobs went, what happened to wages, and how the tariffs of 2025 and 2026 have changed the arithmetic.
Key takeaways
- The United States trades at record scale. In 2025 it exported $3,432.3 billion of goods and services and imported $4,333.8 billion, both all-time highs (BEA/Census).
- The goods deficit is large, and so is the services surplus. The 2025 goods deficit reached a record $1.2 trillion, while the services surplus hit a record $339.5 billion (Census Bureau).
- Manufacturing has shed jobs for four decades. Factory employment peaked at 19.6 million in June 1979 and had fallen to 12.8 million by June 2019, a drop of 6.7 million or 35 percent (BLS).
- Tariffs have raised the cost of importing. The average US tariff now runs just over 12 percent, up from about 2.5 percent before January 2025, adding roughly $1,230 a year to the average household’s costs (PIIE).
- The wage picture is mixed and contested. Real wages for the lowest-paid US workers fell 0.3 percent in 2025 even as median wages rose (EPI).
The mechanics underneath all this are worth ten minutes. This short explainer from the Federal Reserve Bank of St. Louis walks through why countries specialize, how world prices set the terms of trade, and why the same shift that lowers prices for buyers hurts some domestic sellers:

The gains: cheaper goods, bigger export markets, deeper innovation
Globalization’s benefits to American households are easy to underestimate, because they arrive as slightly lower prices rather than as a headline. Here is what the ledger shows on the plus side.

Cheaper goods and services for consumers
When a country imports $4,333.8 billion of goods and services in a single year, the size of the number matters less than what it buys (BEA/Census). Imports widen the range of goods on the shelf and hold prices down in the sectors where American producers compete with foreign suppliers. The Federal Reserve Bank of St. Louis explains the mechanism in the video above: when a good can be bought abroad more cheaply, the consumer surplus from the lower world price is the basic gain from trade.
That gain is also why the reverse is expensive. As the Peterson Institute for International Economics puts it, tariffs make tariffed goods more expensive for consumers and push production toward goods “that could be obtained more cheaply abroad” (PIIE). The consumer benefit of globalization and the consumer cost of protectionism are the same fact seen from two directions.
Export markets for services, technology and agriculture
The United States is not only a buyer. In 2025 it exported $3,432.3 billion of goods and services, with services exports alone reaching $1,234.9 billion (BEA/Census). The 2025 services surplus of $339.5 billion was the highest on record, and the US notched record exports to 47 countries, led by Mexico, the United Kingdom and the Netherlands (Census Bureau).
Trade agreements widen those channels. Under the United States-Mexico-Canada Agreement (USMCA), which replaced NAFTA and took effect on 1 July 2020, US goods and services trade with the bloc totaled an estimated $1.8 trillion in 2022, and US exports to it accounted for 33 percent of all US exports that year (USTR). For a country whose strengths run to software, finance, aerospace and agriculture, open markets are where its comparative advantage gets paid.
Innovation through global talent and capital
The third gain is harder to see but it drives the other two: capital and know-how that cross borders. US direct investment in its USMCA partners alone reached $569.0 billion in 2022, up 9.5 percent on the year (USTR).
The clearest recent example is industrial policy built on exactly that flow. The CHIPS and Science Act of 2022 gave the Department of Commerce $50 billion to rebuild domestic semiconductor research and manufacturing, split into $39 billion of incentives for US facilities and $11 billion for research and development (NIST). The bets are visible: an amended package for GlobalFoundries of up to $955 million, a final R&D award of up to $1 billion for Anderon, a new IBM subsidiary, and up to $100 million for Quantinuum (NIST). Semiconductor supply chains are the most globalised in the world, and the strategy is to pull more of that chain onto US soil rather than step out of it.
The costs: lost factory jobs, stagnant wages, and a deficit that will not close
The other side of the ledger is where the political energy is, because its costs are concentrated in particular towns and industries rather than spread thinly across every price tag.
The manufacturing jobs that never came back

American manufacturing employment peaked in June 1979 at 19.6 million. By June 2019 it was 12.8 million, down 6.7 million or 35 percent, and its share of all nonfarm jobs had fallen from 22 percent to 9 percent (BLS). The deepest damage was in durable goods: computers and electrical products lost 43 percent of their jobs over the same forty years, and durable goods as a group shed 4.3 million (BLS).
Here is the part that gets lost in the shouting. The BLS account of that decline does not blame trade. It ties the fall to a broad shift toward service industries and to recessions from which factory payrolls never fully recovered: “manufacturing has shed employment over the past 40 years as the U.S. economy has shifted to service-providing industries” (BLS). Automation, offshoring and import competition are all plausible contributors, and economists differ on the weights, but the government’s own retrospective puts the emphasis on structural change rather than a single villain.
The sector has stabilised rather than recovered. US manufacturing employed 12,681 thousand people in October 2026, with average hourly earnings of $37.24 and a sector unemployment rate of 2.7 percent (BLS). Those are not the numbers of a collapsing industry, but they are also a long way from 19.6 million. The familiar shorthand is the Rust Belt; the data behind it, in this BLS series, is national and by industry.
Wage stagnation at the bottom

Wage outcomes split sharply by where a worker sits in the distribution. In 2025 the 10th-percentile hourly wage, the line below which a tenth of workers fall, dropped 0.3 percent to $14.56, while the median rose 0.8 percent to $25.67 and the 90th percentile added 0.4 percent to $64.52 (EPI).
The longer trend is starker. Since 1979, wages at the 90th percentile grew an average of 1.1 percent a year against 0.5 percent at the 10th, and wages for the top 1 percent rose 182 percent from 1979 to 2023, roughly seven times the growth at the 10th percentile (EPI). Had low-end wages kept pace with productivity since 1979, the Economic Policy Institute estimates the 10th-percentile wage would be $21.04, or 45 percent higher than it is (EPI).
Where EPI and other economists part company is the cause. EPI attributes the 2025 reversal to policy choices, pointing to tariffs, deportations and federal layoffs, and argues “this reversal was not inevitable, it was caused by policy decisions that weakened the labor market” (EPI). That is a contested claim, and it is worth reading as one side’s reading of the evidence rather than a settled finding.
The trade deficit, explained

Source: BEA/Census, U.S. International Trade in Goods and Services, Annual 2025.
The US trade deficit is the gap between what the country buys from abroad and what it sells, and it is the single most misread number in this debate. In 2025 the total goods and services deficit was $901.5 billion, actually down $2.1 billion from 2024 (BEA/Census). But that modest headline hides a bigger gap underneath: the goods deficit alone hit a record $1.2 trillion, while the services surplus hit a record $339.5 billion (Census Bureau).
Two details make the deficit easier to read straight. First, it is not a scoreboard. A goods deficit is the accounting mirror of other flows, including investment coming into the US, and it can rise simply because American firms bought ahead of threatened tariffs. Second, the deficit has been reshaping rather than shrinking. The 2025 deficit with China fell $93.4 billion to $202.1 billion, but record deficits opened up with Mexico ($196.9 billion), Vietnam ($178.2 billion), Taiwan ($146.8 billion) and Ireland ($114.2 billion) (BEA/Census, Census Bureau). Tariffs moved the trade, in other words, more than they removed it. Our colleagues at The Economy have tracked the same rerouting in the new geography of trade.
Benefits vs drawbacks of globalization for the US economy
The table below is the ledger in one view. Every figure links to the evidence behind it.
| Dimension | What globalization gave the US | What it cost the US |
|---|---|---|
| Prices | Cheaper and wider choice of imported goods; consumer surplus from lower world prices (St. Louis Fed) | Tariffs are passed through to consumers, making tariffed goods more expensive (PIIE) |
| Jobs | Open markets for services, tech and agriculture; record exports to 47 countries in 2025 (Census Bureau) | Manufacturing employment down 6.7 million from its 1979 peak (BLS) |
| Wages | Median real wage up 0.8 percent in 2025 (EPI) | Lowest-paid workers’ real wages fell 0.3 percent in 2025, to $14.56 (EPI) |
| Trade balance | Record services surplus of $339.5 billion in 2025 (Census Bureau) | Record goods deficit of $1.2 trillion in 2025 (Census Bureau) |
| Investment and innovation | Foreign direct investment and industrial policy rebuild capacity; CHIPS Act put $50 billion into semiconductors (NIST) | Dependence on foreign supply chains for critical inputs, from chips to drugs (NIST) |
The honest summary is that the two columns are not symmetric. The gains are spread across hundreds of millions of consumers and are worth a little each; the losses are concentrated in particular industries and communities and are worth a great deal to those who carry them. That asymmetry, more than the totals, is what drives trade policy.
What Americans actually say about trade and globalization
The macro numbers rarely capture how the argument feels on the shop floor. On r/Economics, a thread on the US trade deficit running to 266 comments brought out the full range, from plant managers to defenders of protectionism.
A self-described US plant manager made the case against tariffs from the production side, not the consumer side:
“I actually do manufacture parts in the US. I am plant manager. But it is impossible to get raw materials, castings, steel, and many chemicals from inside the US… The tariff is just a 10% tax on US citizens. It does not effect other countries at all. It is not magically creating domestic sources of raw materials.”
- u/EnterpriseGate, r/Economics, “US trade deficit surges despite Donald Trump’s tariffs”
Not everyone in the thread agreed, and the dissent is worth taking seriously. One commenter argued the deficit itself was the wrong test of whether tariffs were working:
“It’s almost as if President Trump has tricked China into foolishly doing even more of our work for us in exchange for nothing more than printed pieces of paper, while making China even more dependent on US consumption.”
- u/dually, r/Economics, same thread
A third commenter accepted the goal of a more protectionist posture but doubted the execution, arguing that a mercantilist turn “needs sound industrial policy” and that this administration does not have one (u/CremedelaSmegma, r/Economics). The split inside one thread, between people who want manufacturing back and people who doubt tariffs will bring it, is the whole debate in miniature.
Modern US trade policy and the shift toward protectionism
If the 1990s were the high-water mark of American openness, the 2020s are the renegotiation. The shift is not a rejection of global trade so much as an attempt to re-price it.
Tariffs: from 2.5 percent to just over 12 percent

The tariff regime built through 2025 and 2026 has raised the average US tariff “to just over 12 percent,” up from about 2.5 percent before 20 January 2025, though down from a temporary peak of 28 percent (PIIE). The cost lands close to home: PIIE puts the added cost at roughly $1,230 per American household per year (PIIE), and separate PIIE research concludes that “US consumers and firms are paying nearly the full cost of US tariffs” because a country has limited ability to push the burden onto foreign exporters (PIIE).
The legal ground under the tariffs has shifted as fast as the rates:
- The broad “reciprocal” tariffs were first imposed under the International Emergency Economic Powers Act (IEEPA) in April 2025.
- On 20 February 2026, the Supreme Court struck the IEEPA tariffs down.
- The administration replaced them with an interim blanket tariff of 10 percent under Section 122 of the Trade Act of 1974, which expires after 150 days unless Congress extends it.
- The likely durable basis is Section 301, with USTR launching 76 new investigations covering 99 percent of US imports (PIIE).
Where that levy actually falls is the point most political arguments skip:

The tax is collected at the border, but the payer is the importer, and almost all of it is passed forward into what shoppers pay. The Economy has followed the same chain in Trump tariffs 2026 and in what the Supreme Court ruling means for trade.
USMCA and the deals that still stand
Not every channel is closing. The USMCA, which replaced NAFTA and entered into force on 1 July 2020, remains the backbone of North American trade, adding chapters on digital trade, anticorruption and good regulatory practices, and improving rules of origin for autos and trucks (USTR). Trade with the bloc totaled about $1.8 trillion in 2022, a third of all US exports (USTR).
| USMCA, by the numbers | |
|---|---|
| Entered into force | 1 July 2020, replacing NAFTA (USTR) |
| Total US goods and services trade with the bloc, 2022 | About $1.8 trillion (USTR) |
| US exports to the bloc, 2022 | $789.7 billion (USTR) |
| Share of all US exports, 2022 | 33.0 percent (USTR) |
| US services trade surplus with the bloc, 2022 | About $26.0 billion (USTR) |
Alongside tariffs, the US is also spending directly to rebuild capacity at home. The CHIPS Act’s $50 billion for semiconductors is the clearest case: less a retreat from globalization than a bet on keeping the most strategic link of the global supply chain inside the country (NIST). For how far that reshaping has gone, see the new tariff war and reshoring.
The verdict: integration continues, but on new terms
Economic globalization did not end in 2026; it changed its terms. The United States still exports more than $3.4 trillion a year and imports more than $4.3 trillion, and the world still buys American services in record volume. What has changed is who bears the friction. The old bargain spread small gains across consumers and concentrated large losses in factory towns. The new one adds a tariff bill of about $1,230 a year to the average household while promising to bring back the jobs that trade, on the evidence, is only one of several forces taking them.
That is the unsatisfying truth at the centre of this debate. The goods deficit is a poor scoreboard, tariffs appear to have moved trade more than they have removed it, and the government’s own long-run data pins the factory-job decline more on a shift to services and on recessions than on imports alone. None of that makes the losses less real for the people who lived through them. It just means the honest case for or against globalization rests on weighing the two columns in the table above, not on any single number.
More on the global economy from The Economy
Trade and globalization are running themes across The Economy’s coverage. For the wider picture, the 2026 global economic outlook maps the forces reshaping markets, and World Trade in 2026 covers the cost of fragmentation. Start from The Economy for daily coverage of trade, tariffs and the global economy.
Frequently asked questions about globalization and the US economy
Does economic globalization help or hurt the average American worker?
It does both, and which one dominates depends on where the worker sits. Globalization has kept prices on imported goods low and opened export markets for services, tech and agriculture, but it has also coincided with a 35 percent fall in manufacturing employment since 1979. The BLS data behind that fall points mainly to a shift toward services and to recessions, so trade is one factor among several rather than a single cause. For a closer look at how wages have moved, see The Economy‘s coverage of the global economy.
How does globalization affect inflation in the United States?
Cheaper imports pull prices down, which is deflationary, so globalization has generally held US inflation below where it would otherwise be in import-heavy categories. Tariffs work in the opposite direction: the average US tariff rose from about 2.5 percent to just over 12 percent through 2025 and 2026, and PIIE estimates the added cost at roughly $1,230 per household per year. Our explainer on US tariffs and inflation covers how that pass-through works.
What is the difference between globalization and international trade?
International trade is the buying and selling of goods and services across borders. Globalization is broader: it includes trade but also cross-border investment, capital flows, and the movement of people and ideas. A country can trade heavily without being deeply globalized, and a company can invest abroad without exporting a single product. The Federal Reserve Bank of St. Louis explains the trade half of the picture clearly.
What is the US trade deficit and does it matter?
The trade deficit is the gap between the value of what the US buys from abroad and what it sells, and it is often misread as a scoreboard. In 2025 the total goods and services deficit was $901.5 billion, slightly down on 2024, while the goods deficit alone hit a record $1.2 trillion and the services surplus hit a record $339.5 billion. Our piece on trade imbalances explains why the narrower goods figure moves around so much.
How much do the 2026 tariffs cost the average American household?
About $1,230 a year, according to PIIE, with most of the cost passed through to consumers rather than absorbed by foreign exporters. The tariffs themselves now average just over 12 percent, and their legal basis shifted after the Supreme Court struck down the IEEPA tariffs in February 2026. The Economy’s analysis of the ruling walks through what replaced them.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Open Banking Trends 2026: What Consumers Should Know

Nvidia After the Selloff: What to Watch Before Earnings

Black Friday 2026 Early Deals: A Data-Driven Shopping Guide

Fed Policy Path 2027: Rate Expectations After the Hold

Asia’s Economic Resilience in 2026: The Strategic Blueprint for Sustaining the Global Growth Engine

Credit Scoring Changes 2026: What Mortgage Buyers Need to Know

10-Year Treasury Yield Outlook for 2027 After the Democratic Sweep

Is the AI Infrastructure Boom Sustainable? A Reality Check

Disability Insurance Demand in 2026: Who’s Buying and Why

What the 2026 Midterms Mean for Treasury Yields and Bond Markets

Payroll Outlook After the Midterms: 2027 Tax Changes, Compliance Risks and AI Trends

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025