
Insurance
Disability Insurance Demand in 2026: Who’s Buying and Why

Demand for disability income insurance is rising in 2026, but the strength of the trend depends on which data you read. U.S. sales of disability insurance reached about $491.8 million in 2025, and the Council for Disability Income Awareness (CDIA) has highlighted continued interest in income protection. Public Social Security claims data, however, show a different picture: an Urban Institute analysis found about 7% fewer disability benefit claims filed in the first half of 2025 than in the same period a year earlier. Buyers should treat “surging demand” as a directional story rather than a settled statistic.
Key Takeaways
- U.S. disability insurance sales rose to roughly $491.8 million in 2025, according to Serrari Group’s review of industry data.
- Gen Re reported U.S. disability insurance sales growth of about 2.7%, with medical occupations still dominating new business.
- Mental health conditions are a growing share of claims in several markets, including Australia, where mental illness accounts for roughly one-third of total and permanent disability claims.
- Most individual disability policies are bought by professionals with higher incomes, not by the general workforce.
- Coverage gaps remain large: one market report estimates about 65% of private-sector workers have no long-term disability coverage.
Why Demand Is Growing
Three forces are pushing more people toward income protection. The first is cost-of-living pressure. When household budgets are tight, a single missed paycheck from illness or injury becomes more dangerous, and workers with dependents or mortgages are more likely to consider coverage they previously skipped.
The second is the changing nature of illness-related claims. The CDIA’s 2026 fact sheet lists pregnancy, musculoskeletal disorders, injuries, and mental health conditions among the most common reasons for disability claims. Mental health is increasingly prominent. In Australia, industry reporting in May 2026 attributed a rise in income support demand to mental health claims, with mental illness accounting for about 20% of income protection claims.
The third is employer uncertainty. Workers who depend on group coverage through a job may find that benefits are limited, short-term, or tied to employment that changes frequently. Individual policies, which travel with the worker, are attractive to freelancers, contractors, and anyone who expects job changes.
Who Is Actually Buying
The buyer profile has changed less than the headlines suggest. Medical professionals, executives, and high-income workers remain the core market for individual disability income insurance because premiums scale with income and insurers underwrite carefully.
Growth in some segments is worth watching. Industry reporting has pointed to rising applications from professional services and technology workers, a group that historically bought less coverage than construction or manufacturing employees. Those figures come from secondary summaries rather than a single public dataset, so verify them against the originating insurer surveys before citing them as firm evidence.
Practical buyer segments:
- Self-employed and freelance workers, who have no employer-sponsored short-term or long-term disability.
- Professionals with specialized incomes, such as physicians, dentists, and lawyers, who face high replacement-cost risk.
- Business owners using buy-sell or key-person arrangements.
- Employees whose group benefits are capped, reduced, or unclear about portability.
Understand the Policy Before You Buy
Disability insurance is more complicated than most life or auto coverage. Four features matter most.
Benefit amount. Most insurers replace a percentage of income, commonly 50% to 70%, subject to a monthly maximum. Check whether the policy pays on pre-tax or after-tax income.
Elimination period. This is the waiting time before benefits begin, often 30, 60, 90, or 180 days. A longer waiting period lowers premiums but requires more savings to bridge the gap.
Own-occupation versus any-occupation definitions. An own-occupation policy pays if you cannot perform your specific job. An any-occupation policy may pay only if you cannot perform any job suited to your education and experience. Own-occupation coverage costs more and is usually more valuable for specialized workers.
Benefit period. Coverage may run to a set age, such as 65, or for a fixed number of years. Mental health and musculoskeletal conditions often have specific limitations, so read those clauses closely.
Applicants should expect detailed underwriting, including medical records and occupation review. Approval is not guaranteed, and pre-existing conditions can be excluded or priced higher.
How Public Disability Benefits Compare
Many buyers assume Social Security Disability Insurance (SSDI) will cover them. It often does not, and the process is slow. The CDIA fact sheet notes that most initial SSDI applications are denied and that approvals frequently come only after reconsideration or appeal. Processing can take several months, which is why private income protection matters for many workers.
The Urban Institute’s finding that claims fell in 2025 suggests that application volume has not simply risen with economic stress. Policy changes and application friction may be part of the explanation, which makes public data harder to read as a demand signal.
What the Numbers Do and Do Not Tell You
Readers should be cautious with headline growth figures. Sales data from a single survey, claims data from a government agency, and international data from different regulators measure different things. A rise in new individual policies, for example, may not reflect a rise in workers who are actually disabled.
Three limitations stand out:
- Some demand estimates come from insurance industry marketing materials or secondary blogs with limited methodology disclosure.
- International figures, including Australian and UK data, do not translate directly to the U.S. market.
- Industry growth may partly reflect higher premiums rather than more policyholders.
Where possible, rely on the original sources: the Social Security Administration’s monthly statistical snapshot, insurer trade association surveys, and regulatory filings.
Frequently Asked Questions
Is demand for disability insurance really rising in 2026?
Some indicators point up, including U.S. sales growth in 2025 and reported interest in mental health coverage. Public SSDI claims data, however, showed a decline in early 2025. The honest answer is that demand appears to be rising among certain buyer groups, while overall evidence is mixed.
Who should consider buying disability insurance?
Self-employed workers, professionals with high incomes, business owners, and employees with limited or unclear group coverage have the strongest case for individual policies. Anyone who depends on earned income should review their options.
What is the difference between short-term and long-term disability coverage?
Short-term coverage typically pays for months, while long-term coverage can pay for years or until a set age. Long-term policies usually have longer waiting periods and higher premiums.
Does Social Security cover disability for most workers?
Not reliably. SSDI has strict medical criteria, and many initial applications are denied. Approval can take months, which leaves a gap that private coverage can fill.
What is an own-occupation policy?
It pays benefits if you cannot perform the core duties of your specific occupation, even if you could work in a different field. It is generally more expensive and more valuable for specialized professionals.
Are mental health conditions covered?
It depends on the policy. Some contracts have limits or longer review periods for mental health and substance-related claims. Read the definitions carefully before buying.
Should I buy coverage through my employer or individually?
Compare both. Employer coverage is often cheaper but may be limited or tied to your job. Individual coverage is portable, but underwriting is stricter and premiums depend on your health and occupation.
Conclusion: Buy for the Gap, Not the Headline
Disability insurance demand is growing among specific groups, and mental health claims are becoming a more visible part of the risk picture. The strongest argument for coverage is not market growth but the gap between what workers earn, what public programs pay, and what employers provide. Before buying, check the definitions, the waiting period, and the benefit cap, and compare quotes from several insurers. For specific advice, consult a licensed insurance professional.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


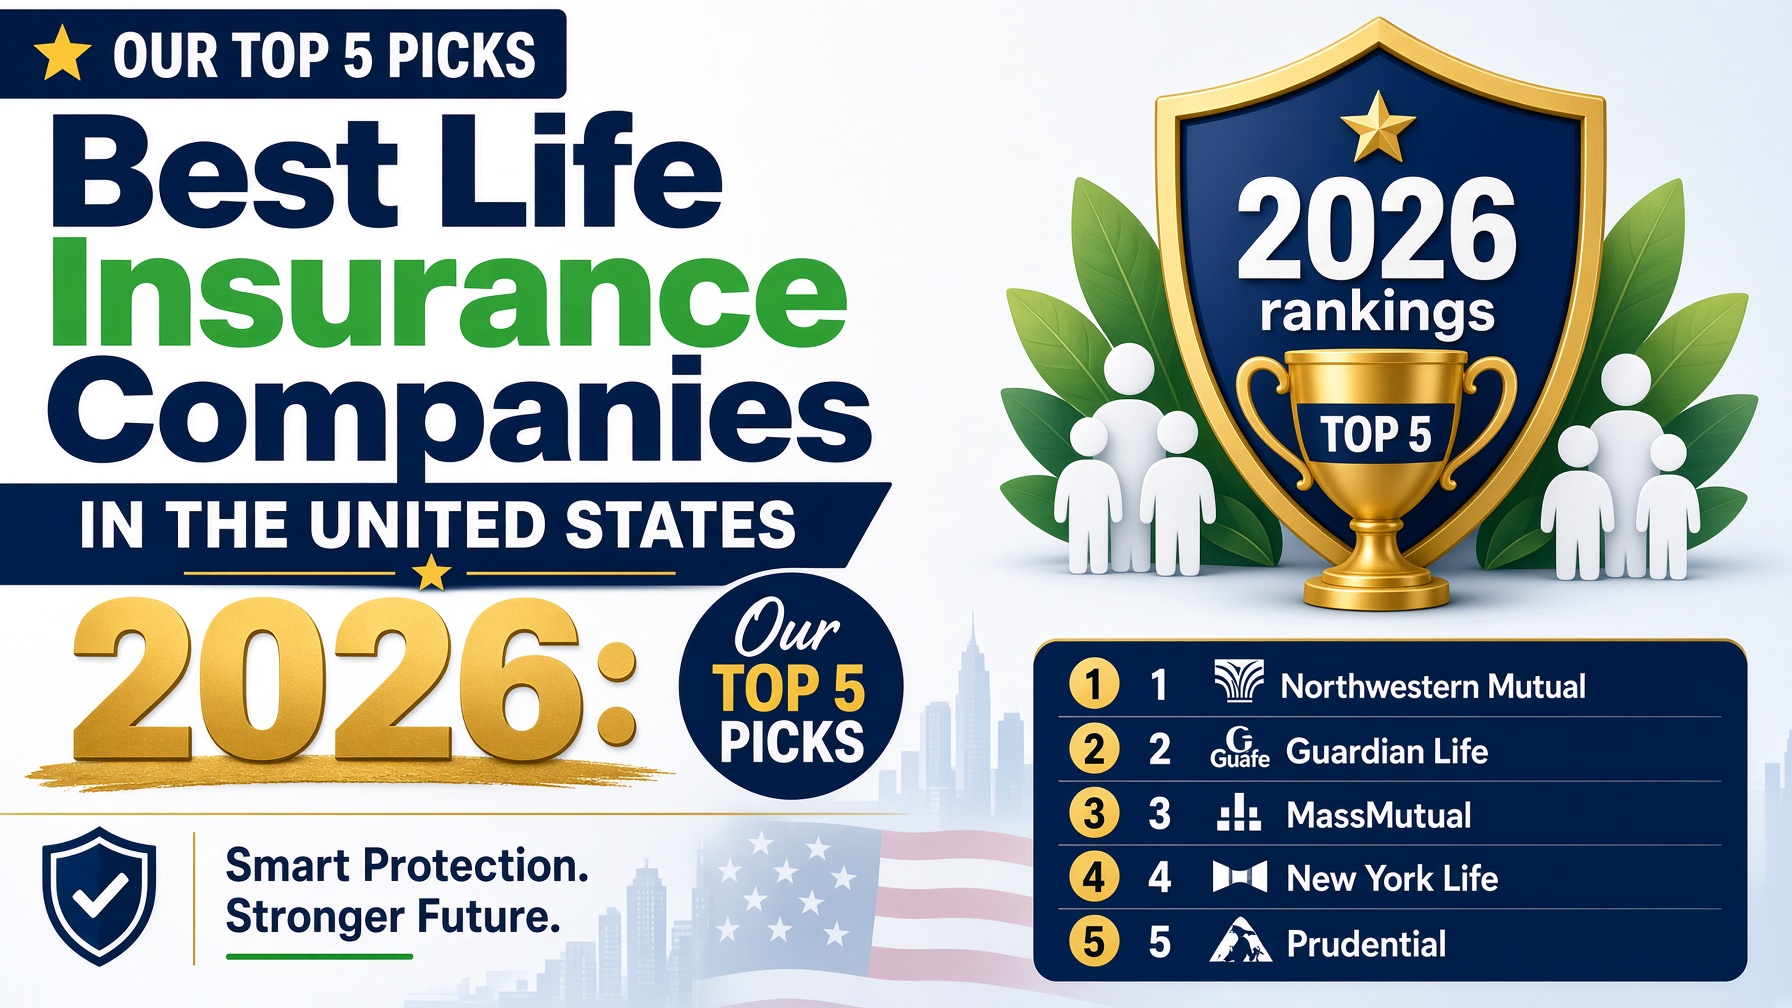
Our 2026 shortlist of the best life insurance companies in the United States: Northwestern Mutual, New York Life, MassMutual, State Farm and Prudential, and how to choose between them.
The best life insurance company in the United States depends far less on the name on the policy than on the type of cover you need and the person who sells it to you. For 2026, we would shortlist five:
- Northwestern Mutual and New York Life for permanent, dividend-paying whole life from two of the strongest balance sheets in the industry. Both hold the top financial-strength rating from all four major agencies (Northwestern Mutual, New York Life).
- MassMutual for whole life with a dividend history and an online term option through its Haven Life arm (MassMutual).
- State Farm if you would rather add life coverage to the home and auto policies you already have (State Farm).
- Prudential for fast, no-medical-exam term life, quoted online (Prudential).
Here is the catch, and it is the whole point of this piece: the J.D. Power 2026 U.S. Individual Life Insurance Study puts Nationwide (701), State Farm (692) and Mutual of Omaha (680) on top for customer satisfaction, against an industry average of 649. Two of the three strongest brands on that list do not appear in most “biggest insurer” rankings, and the two safest balance sheets on ours (Northwestern Mutual and New York Life) do not top the satisfaction list. For most buyers, the policy you choose and the agent you get matter more than the company badge.
How we ranked the best life insurance companies in the United States
We compared the five on four things:
- Financial strength – the ratings from agencies like AM Best, Fitch, Moody’s and S&P that decide whether a claim decades from now actually gets paid.
- Product range and how easy it is to buy – from a same-day approved whole life application to a five-minute online term quote.
- Scale and longevity – revenue, assets and how long the company has been paying claims and dividends.
- What customers say – taken from the J.D. Power 2026 U.S. Individual Life Insurance Study, which surveyed 6,145 life-insurance customers between July 2025 and July 2026.
Where a company does not publish something, we say so rather than guess. Every figure below links to the source it came from. This is independent editorial, not financial advice, and no insurer paid for its place.
| Company | Best for | Ownership | Financial strength | How you buy |
|---|---|---|---|---|
| Northwestern Mutual | Dividend-paying whole life | Mutual (policyholder-owned) | Top rating from all four agencies – A++, Aa1, AA+ | Through an advisor |
| New York Life | Whole life from the largest US mutual | Mutual (policyholder-owned) | A++ (AM Best), AAA (Fitch), Aaa (Moody’s), AA+ (S&P) | Through an agent |
| MassMutual | Whole life plus an online term option | Mutual (policyholder-owned) | Not stated in the sources we reviewed | Through a financial professional, or Haven Life online for term |
| State Farm | Bundling life with home and auto | Mutual (policyholder-owned) | Not stated in the sources we reviewed | Through a 19,000-agent network (Wikipedia) |
| Prudential | Fast, no-medical-exam term life | Public (NYSE: PRU) | Not stated in the sources we reviewed | Online quote, or through an advisor |
1. Northwestern Mutual – best for dividend-paying whole life
Best for: buyers who want a permanent policy that builds guaranteed cash value and has shared profits with policyholders since 1872 (Northwestern Mutual).Northwestern Mutual’s life insurance page, captured live from northwesternmutual.com
Northwestern Mutual is a mutual, which means it is owned by its policyholders rather than shareholders, and it has paid dividends every year since 1872. It expects to pay $10.4 billion in dividends in 2027 (Northwestern Mutual). The company sells whole, universal, variable universal and term life; term is written for a set period such as 10 or 20 years and can be converted to permanent cover later (Northwestern Mutual).
Its balance sheet is the reason it tops this list. It holds the highest financial-strength ratings awarded to any US life insurer by all four major agencies – cited as A++, Aa1 and AA+ – and reported $41.2 billion in revenue and $497 million in net income for 2025, ranking No. 110 on the Fortune 500 and in the top 30 US companies by assets held (Northwestern Mutual, Wikipedia). Named riders include Waiver of Premium, an Additional Purchase Benefit that lets you buy more cover at set ages or life events regardless of health changes, and an Accelerated Care Benefit that lets you draw on the death benefit early for qualified long-term care (Northwestern Mutual).
Northwestern Mutual does not publish premiums; they are set case by case through health and lifestyle questions during the advisory process, though some applications can be approved as soon as the same day (Northwestern Mutual).
Our take: the strongest overall choice if you have already decided on permanent cover and want a mutual’s dividend record behind it. It is a poor fit if you want cheap term life and a five-minute online quote, since everything here runs through an agent. Worth knowing: in 2025 a Guardian investigation alleged the company pushed interns into aggressive sales of expensive whole life policies to their personal contacts (Wikipedia) – which is a reason to be clear about what you are buying, not a reason to avoid the balance sheet.
2. New York Life – best for whole life from the largest US mutual
Best for: buyers who want a straightforward, permanent whole life policy from the largest mutual life insurer in the country.New York Life’s life insurance page, captured live from newyorklife.com
New York Life is the second-largest life insurer and the largest mutual life insurer in the United States, founded in 1845 and owned by its policyholders with no outside shareholders (Wikipedia). Like Northwestern Mutual it holds the best possible rating from all four agencies in 2025 – A++ from AM Best, AAA from Fitch, Aaa from Moody’s and AA+ from S&P – and it has paid a dividend every year since 1854 (Wikipedia).
It writes term, whole, universal and variable universal life, plus an “accumulation-focused” category aimed at longer-term goals such as retirement, alongside the core whole life product. Its own comparison table is refreshingly blunt about the difference between the types: term premiums “gradually increase after a certain period”, whole life premiums are “always the same amount”, and only whole life lists potential dividend earnings (New York Life).
The financials are large and stable: $27.19 billion in revenue and $470 million in net income for 2024, total assets of $244.9 billion, and a No. 69 rank on the 2025 Fortune 500 (Wikipedia). Distribution is agent-led – the main call to action on its site is “Connect with an agent” – and prices are not published (New York Life).
Our take: the pick if you want whole life from a household-name mutual and are happy to work with an agent. If a fast online term quote is what you are after, this is the wrong door; go to Prudential or MassMutual’s Haven Life. The company’s own history is also worth naming: it insured enslaved people’s lives for their owners in 1846-1848 before the board ended the practice, and its president was forced out in 1905-06 after the Armstrong investigation into bribery (Wikipedia).
3. MassMutual – best for whole life with an online term option
Best for: buyers who want a dividend-paying whole life policy for the long haul, but would like a no-fuss online route for simple term cover.MassMutual’s life insurance page, captured live from massmutual.com
MassMutual is a mutual insurer founded in 1851 in Springfield, Massachusetts, with the same policyholder-owned structure as the others (Wikipedia). It offers four types: term (often 10, 20 or 30 years), whole life, universal life and variable universal life. Of the four, only whole life is explicitly linked to dividends, and the page says plainly that “dividends are not guaranteed” (MassMutual).
Two details matter for a buyer. First, its term policies carry guaranteed premiums, while its universal life policies have flexible premiums with only “some” guarantees (MassMutual). Second, MassMutual owns Haven Life, a 2015 subsidiary that sells term life only, aimed at the online, no-medical-exam market (Wikipedia) – a useful middle path if you want a mutual behind the policy without a sit-down with an agent.
On scale, MassMutual recorded $10.7 billion in revenue in 2022 and ranked 100th on that year’s Fortune 500, with over 8,000 financial professionals (Wikipedia, MassMutual). Its financial-strength ratings did not appear in the sources we reviewed, and its Wikipedia entry is internally inconsistent on assets under management ($466 billion in the infobox against $312 billion in the body) (Wikipedia) – so treat the headline size numbers with a little caution.
Our take: a strong whole life option with a genuine online escape hatch for term. The dividend record is shorter than New York Life’s or Northwestern Mutual’s, and the company’s history includes Tremont Capital, a Madoff feeder fund that lost $3.3 billion (Wikipedia).
4. State Farm – best for bundling life coverage with home and auto
Best for: existing State Farm customers who want life cover in the same place as their home and car insurance and who value a local agent.State Farm’s life insurance page, captured live from statefarm.com
State Farm is the largest property and casualty insurer and the largest auto insurer in the United States, so life insurance is a smaller line inside a very large business (Wikipedia). It sells term, whole and universal life through more than 19,000 agents (Wikipedia), and its permanent policies carry tax-deferred cash value with level premiums (State Farm).
The bundling case is the whole point. If you already hold State Farm home and auto policies, adding life cover keeps one agent, one billing relationship and one claim process. Customers who bought a new life policy since 1 January 2022 can also earn rewards through the Life Enhanced app, though policyholders in Florida, New York and South Dakota are not eligible for the full programme (State Farm).
The company’s size is not in doubt: $104.2 billion in revenue in 2023 and a No. 39 rank on the 2024 Fortune 500 (Wikipedia). But that same year it posted a net loss of $6.3 billion, driven by its property-casualty book (Wikipedia). It does not publish life premiums or term lengths on the hub page; quotes start by selecting your state.
It also does well where customers notice: second place, at 692, in the J.D. Power 2026 study (J.D. Power).
Our take: the pick if convenience and an existing relationship matter more than a specialist’s product depth. It is not the cheapest way to buy pure term life, and a property-casualty-heavy balance sheet is a different kind of risk from a life-only mutual.
5. Prudential – best for fast, no-medical-exam term life
Best for: healthy buyers who want a term policy sorted out online, today, with a big name behind it.

Prudential is the odd one out here as a public company, traded on the NYSE as PRU (Wikipedia). It sells the widest spread of permanent products on this list – universal, indexed universal, indexed variable universal and variable universal life, all carrying no-lapse guarantees – but its most distinctive offer is on the term side: no-medical-exam term life up to $1 million, starting at $10 a month, positioned as going “from quote to covered in minutes” (Prudential).
Two caveats. Issuance can still depend on the health answers in the application, and the on-page quote funnels you to Prudential’s partner, SelectQuote (Prudential). One genuinely useful feature is the BenefitAccess rider, which lets you draw on the policy if you are diagnosed with a chronic illness (Prudential).
As a public company Prudential is large but has a messier record than the mutuals: $60.8 billion in revenue and $3.58 billion in net income for 2025, with $1.512 trillion in assets under management – yet its history also includes an $8 billion investor-fraud finding at Prudential Securities in the 1990s and a 1997 class action over unnecessary life insurance sales that called for roughly $2 billion in repayments (Wikipedia). More recently, its Japanese life subsidiary suspended new sales through November 2026 after an employee-misconduct investigation (Wikipedia).
Our take: the best route on this list if you want term life quickly and without a medical exam. If you want permanent cover and a mutual’s dividend record, you are in the wrong section.
The catch: “best” depends on the kind of life insurance you need

All five companies above are strong. But the gap between them matters far less than the gap between the three kinds of policy they sell. Buying the wrong type of life insurance from a great company costs more than buying the right type from a good one. The policy type is the decision; the brand is the detail.
- Term life covers a set period (often 10, 20 or 30 years) and builds no cash value. It is, by a wide margin, the cheapest way to protect a mortgage and young children for the years they depend on you. Every company on this list sells it.
- Whole life is permanent, with level premiums, guaranteed cash value and, at a mutual, dividends. It costs several times more than term for the same death benefit, and it only makes sense for a need that never goes away – an estate bill, a lifelong dependent, or a business succession plan.
- Universal life sits in between: flexible premiums and cash value tied to interest rates, with guarantees that vary by policy.
The insurers make the trade-off unusually clear themselves. New York Life’s own comparison table notes that term premiums “gradually increase after a certain period” while whole life premiums are “always the same amount”, and that only whole life lists potential dividend earnings. MassMutual makes the same point from the other direction, stating twice on its life insurance page that dividends are not guaranteed.
What customers actually say about life insurance companies

Ratings and balance sheets tell you whether a claim will be paid. They do not tell you whether the experience will be pleasant, and the J.D. Power 2026 U.S. Individual Life Insurance Study is the best window into that. It surveyed 6,145 customers between July 2025 and July 2026 across eight dimensions, with trust ranked first.
Two findings are worth carrying into any purchase. First, distribution matters more than branding: centrally distributed and direct-to-consumer plans scored 684, twelve points lower than a year earlier, while distributor-sold policies scored 645, six points higher (J.D. Power). Second, a single bad experience wrecks trust: one negative interaction drops overall trust satisfaction by 96 points (J.D. Power).
Review sites, which capture the unhappy tail that studies average out, can look much darker. New York Life, for example, holds a TrustScore of 1.3 out of 5 from 71 reviews on Trustpilot, and 1.1 out of 5 from 207 reviews on ConsumerAffairs – even as it holds the top financial-strength rating from all four agencies (Trustpilot, ConsumerAffairs). The lesson is not that the company is bad; it is that the strongest balance sheet and the happiest customers are rarely the same company, and you should weigh the two separately.
“Customer service is horrible. It seems to be impossible to connect with my mother’s agent. I have sent documents via email which were received, but apparently, they now have none on file. They will easily take your money but good luck if you need anything from this company.”
- Trustpilot review of New York Life, 21 September 2026 (permalink)
How to buy life insurance without getting oversold

The forums are blunt about where this goes wrong. The most-repeated line in US personal-finance communities is “buy term and invest the difference”, and the objection is rarely to the companies – it is to the advice:
“Why whole life? Whole life policies are one of the worst insurance products on the market. Buy term and invest the difference.”
- r/LifeInsurance, thread on a Northwestern Mutual whole life offer
A former agent put the sales dynamic more plainly:
“As a former NYL ins agent, we were trained to tell you life insurance is an investment.”
- r/LifeInsurance, thread “Please help me understand my NYL whole life insurance.”
So here is the order of operations we would follow:
- Decide the type before you talk to anyone. Term, whole or universal. If you have a mortgage and children at home, term almost always wins on cost.
- Work out how much cover you actually need – a common rule of thumb is 10 to 15 times your income, and you can check it against Prudential’s needs calculator.
- Get at least three quotes, and get at least one from an independent broker rather than a captive agent who can only sell one company’s products.
- Ask the agent how they are paid. A commission on a permanent policy is several times the commission on term, which tells you why the recommendation often points one way.
- Check the insurer, not just the price. Look at financial-strength ratings and at a consumer-review profile for complaint patterns, the same way you would before choosing a bank.
- Insurance is not an investment. If a policy is being sold to you as a way to save or retire, get a second opinion before you sign – the tax treatment of the death benefit is real, and so is the 2027 federal tax picture if you are thinking about what your family inherits.
- Buy only for the years someone depends on your income. Cover for a period of life, not forever, is often the honest answer.
More on money and policy from The Economy
The same discipline that applies to a life policy applies across your finances. If you want the background on the safety nets and market questions that shape these decisions, why SSI payments arrive when they do and our calm-investor checklist for a 2026 market wobble are good next reads. For the macro picture behind many of these products, start from The Economy’s front page.
Frequently asked questions about life insurance companies
What is the best life insurance company in the United States?
There is no single best company for everyone, because the type of policy matters more than the name on it. For dividend-paying whole life, Northwestern Mutual and New York Life top this list on financial strength, each holding the highest ratings from all four major agencies. For fast, no-medical-exam term life, Prudential is the easiest place to start, and for bundling life cover with home and auto, State Farm is the natural fit.
Is term or whole life insurance better?
Term life is far cheaper for the same death benefit and is usually the right choice while a mortgage and dependent children are why you need cover. Whole life is permanent, builds guaranteed cash value and, at a mutual insurer, may pay dividends, which suits needs that never go away, such as estate costs or a lifelong dependent. New York Life’s own comparison notes that term premiums rise after a set period while whole life premiums stay level.
Which life insurance company has the best customer satisfaction?
In the J.D. Power 2026 U.S. Individual Life Insurance Study, Nationwide scored highest at 701, followed by State Farm at 692 and Mutual of Omaha at 680, against an industry average of 649. The strongest balance sheets and the happiest customers are often different companies, so weigh financial strength and service quality separately.
Do I need a medical exam to get life insurance?
Not always. Prudential sells no-medical-exam term life up to $1 million starting at $10 a month, and MassMutual’s Haven Life arm is built around online, simplified-issue term cover. Issuance can still depend on the health answers in your application, and larger or permanent policies more often require full underwriting.
How much life insurance do I need?
A common rule of thumb is 10 to 15 times your annual income, adjusted for your mortgage, other debts, childcare and the number of years your family would need the money. The exact figure matters less than buying the right type of cover for the years someone depends on your income. For the wider picture, see The Economy.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
A single slip-and-fall lawsuit against an uninsured small business can wipe out years of profit in one settlement — yet a large share of small business owners still operate without even basic general liability coverage, often simply because no one ever explained clearly what’s actually required versus optional.
Business insurance isn’t a single product — it’s a category spanning general liability, workers’ compensation, professional liability, commercial property, and more, each protecting against different risks. Figuring out which coverage your specific business actually needs, and what it should reasonably cost, is one of the most commonly delayed and misunderstood decisions small business owners face.
This guide breaks down the core types of business insurance, current 2026 cost benchmarks, and how to build the right coverage package without overpaying.
How Business Insurance Actually Works: The Core Coverage Types
Most small businesses don’t need every type of commercial insurance — the right combination depends heavily on industry, whether you have employees, and whether you interact with the public or handle client data.
Key takeaway: General liability insurance isn’t legally required in most states, but it’s often necessary to secure a client contract, obtain a business license, or sign a commercial lease — meaning many business owners end up needing it as a practical requirement of doing business, even without a legal mandate.
The Core Business Insurance Types
- General liability insurance — covers third-party bodily injury, property damage, and personal injury claims arising from your business operations.
- Workers’ compensation insurance — required in most states once you hire employees, covering medical costs and lost wages for work-related injuries.
- Professional liability insurance (errors & omissions) — protects service-based businesses against claims of negligence, mistakes, or failure to deliver promised services.
- Commercial property insurance — covers physical business assets (equipment, inventory, the building itself) against fire, theft, and other covered perils.
- Business Owner’s Policy (BOP) — bundles general liability and commercial property coverage into a single, typically discounted policy.
- Cyber liability insurance — increasingly essential for businesses handling customer payment data or sensitive personal information.
Step-by-Step: Building Your Business Insurance Package
- Assess your specific risk profile — client-facing businesses, those with employees, and those handling sensitive data each face different primary risks.
- Determine legal and contractual requirements — workers’ comp is state-mandated once you have employees, and many commercial leases and client contracts require proof of general liability coverage.
- Get quotes for a Business Owner’s Policy first, since bundling liability and property coverage is typically more cost-effective than purchasing separately.
- Add specialized coverage as needed — professional liability for advice-based businesses, cyber liability for data-handling businesses, commercial auto for businesses with vehicles.
- Review coverage limits against your actual risk exposure, not just the cheapest available policy, since underinsurance can be as costly as no insurance in a serious claim.
- Reassess annually as your business grows, since coverage needs — and available discounts — change as revenue, staff count, and operations evolve.
Financial and Strategic Implications: 2026 Business Insurance Cost Benchmarks
Costs vary substantially by industry, business size, and claims history, but understanding typical ranges helps set realistic budget expectations.
| Coverage Type | Typical Monthly Cost (2026) | Notes |
|---|---|---|
| General liability insurance | $40–$100/month for most small businesses | Median new-customer rate around $55/month per Progressive Commercial data |
| Workers’ compensation | $45–$70/month median, varies heavily by industry risk | Office-based businesses pay far less than construction or manual-labor industries |
| Business Owner’s Policy (BOP) | $57–$150/month | Bundled liability + property, typically cheaper than separate policies |
| Professional liability (E&O) | Varies by profession and revenue | Higher for advice-heavy professions (consulting, financial services, healthcare-adjacent) |
Expert insight: Most small businesses pay roughly $500 to $2,000 a year for general liability or a BOP, with total costs climbing meaningfully once workers’ compensation, commercial auto, or professional liability are added — meaning a realistic total insurance budget should account for the full coverage stack your business actually needs, not just a single policy.
Why Cost Varies So Much by Industry
A home-based bookkeeper and a residential construction crew face fundamentally different risk profiles, and insurers price accordingly. A small consulting firm with a clean claims history might pay $750 to $1,200 per year for general liability coverage, while a construction company with similar revenue could pay $3,000 to $5,000 or more for the same coverage type, reflecting the materially higher claims frequency and severity in higher-risk industries.
Bundling and Discount Strategies
Bundling multiple policies with a single insurer commonly produces automatic discounts of 10% to 15%, and choosing a higher deductible — when cash flow allows — can meaningfully lower monthly premiums for businesses confident in their ability to absorb a modest out-of-pocket cost in the event of a claim.
How to Choose the Right Business Insurance
- Start with a Business Owner’s Policy if you qualify — most small businesses without significant specialized risk exposure fit within a standard BOP more cost-effectively than piecing together separate policies.
- Don’t skip workers’ compensation once you hire employees — it’s legally required in nearly every state and the penalties for non-compliance can be severe.
- Get quotes from at least three insurers, since — as with other insurance categories — identical coverage can price very differently between carriers for the same business profile.
- Work with an independent broker for complex risk profiles, since brokers can shop multiple insurers and identify industry-specific coverage gaps a single-carrier quote might miss.
- Review your policy annually as your business changes — added employees, new locations, or expanded services can all create coverage gaps if the policy isn’t updated.
- Don’t assume a personal umbrella policy covers business activity — business risks generally require dedicated commercial coverage, and mixing personal and business insurance can leave real gaps.
Key takeaway: The businesses that get burned by inadequate insurance are rarely the ones that skipped coverage entirely — they’re far more often the ones that bought a policy years ago and never revisited it as the business grew, leaving real gaps between what’s covered and what the business now actually does.
Future Outlook: Business Insurance Trends Through 2027
- “Social inflation” continues to pressure premiums upward. Rising litigation costs and larger jury awards continue to put upward pressure on general liability premiums nationally, a trend insurers refer to as social inflation, meaning even businesses with clean claims histories may see gradual rate increases independent of their own risk profile.
- Cyber liability coverage is shifting from optional to expected. As data breach costs and regulatory penalties continue rising, more commercial leases, client contracts, and vendor agreements are beginning to require proof of cyber liability coverage alongside traditional general liability.
- Digital-first insurers continue to compress quote-to-bind timelines. More small business insurance providers now offer instant online quotes and same-day coverage, reducing a process that historically took days or weeks through a traditional broker.
- State-level regulatory divergence on liability rules continues. States with joint-and-several-liability frameworks and higher litigation rates continue to see meaningfully higher general liability premiums than lower-litigation states, reinforcing the value of location-aware comparison shopping.
Frequently Asked Questions
Is business insurance legally required?
It depends on the type. Workers’ compensation is legally required in nearly every state once you have employees, while general liability insurance is not legally mandated in most states but is frequently required by landlords, lenders, and client contracts.
What’s the difference between general liability and professional liability insurance? General liability covers third-party bodily injury and property damage claims, while professional liability (errors & omissions) covers claims of negligence, mistakes, or failure to deliver services as promised — the coverage most relevant to service and advice-based businesses.
How much does small business insurance typically cost?
Most small businesses pay roughly $500 to $2,000 a year for general liability or a bundled Business Owner’s Policy, with total costs increasing once workers’ compensation, professional liability, or commercial auto coverage is added.
What is a Business Owner’s Policy (BOP)?
It’s a bundled policy combining general liability and commercial property coverage into a single, typically discounted package, well-suited to most small businesses without highly specialized risk exposure.
Do I need cyber liability insurance for a small business?
Increasingly yes, particularly if your business handles customer payment information or sensitive personal data, as data breach costs and related legal exposure have grown substantially in recent years.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
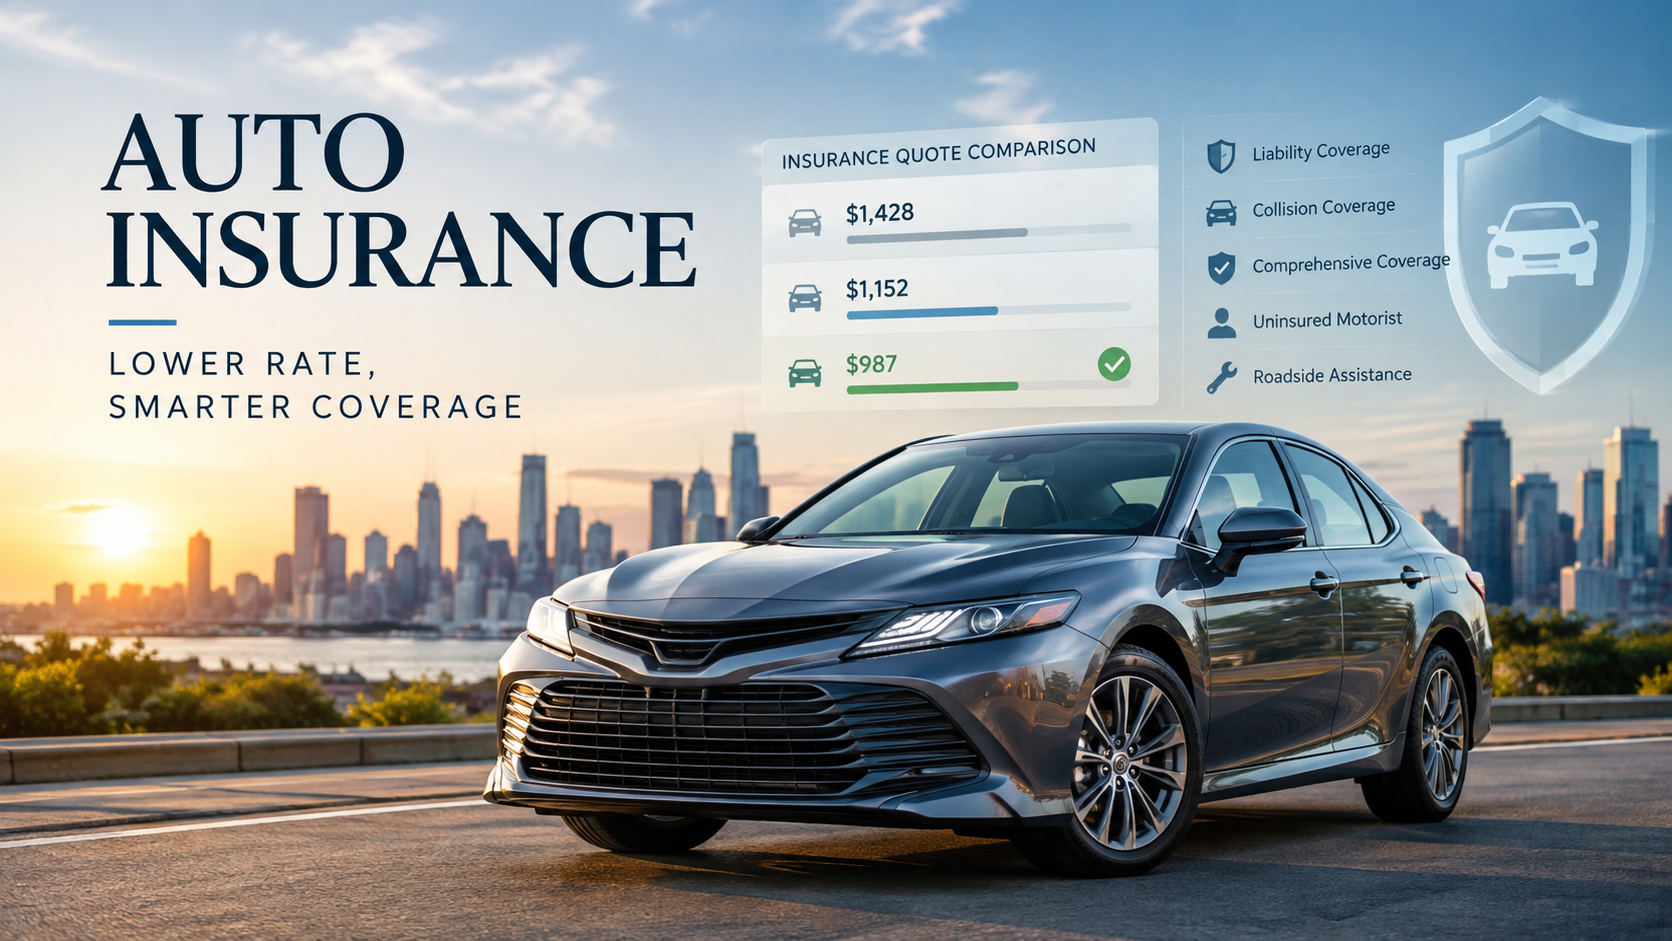
The gap between the cheapest and most expensive auto insurer for the exact same driver and the exact same coverage can exceed $500 a year — meaning the single highest-leverage financial decision most drivers never make is simply comparing quotes before renewal.
Auto insurance pricing isn’t a fixed number set by the market; it’s a highly individualized calculation that varies dramatically between insurers for identical coverage. Two drivers with the same age, location, and driving record can receive wildly different quotes from the same set of companies, which is precisely why shopping multiple quotes — rather than auto-renewing with a single carrier — remains one of the most reliable ways to reduce a major recurring household expense.
This guide covers how auto insurance quotes are actually calculated, current 2026 rate benchmarks, and how to compare quotes effectively without accidentally under-insuring yourself.
How Auto Insurance Quotes Are Actually Calculated
Insurers use dozens of variables to price a policy, and because each company weighs these factors differently, the “best” insurer for one driver is frequently not the best for another.
Key takeaway: The national average cost of full coverage car insurance is $2,315 per year, or about $193 per month, while minimum coverage averages $621 per year, according to NerdWallet’s 2026 rate analysis — but your own quote will likely differ substantially based on factors specific to you.
The Core Factors That Drive Your Quote
- Location — state and even ZIP code meaningfully affect rates, with full coverage ranging from roughly $128 per month in the cheapest states to over $330 per month in the most expensive.
- Driving record — accidents, violations, and DUIs are among the largest individual rate drivers.
- Credit-based insurance score — used in most states (though prohibited in a handful) as a statistically validated predictor of claims likelihood.
- Age and driving experience — younger, less experienced drivers consistently pay significantly more.
- Vehicle make, model, and year — repair costs, safety ratings, and theft rates all factor into pricing.
- Coverage limits and deductibles — higher liability limits and lower deductibles increase premiums.
Step-by-Step: How to Shop Auto Insurance Quotes Effectively
- Gather your current policy details — coverage limits, deductibles, and driver information — so you’re comparing equivalent coverage across quotes.
- Get quotes from at least three to five insurers, including both large national carriers and regional companies, since regional insurers frequently beat national rates in specific states.
- Request identical coverage limits on every quote — comparing a $500 deductible quote against a $1,000 deductible quote will produce a misleading price comparison.
- Ask about all available discounts explicitly, since not every discount is applied automatically.
- Compare the final out-the-door price, including fees, not just the advertised premium.
- Review coverage details, not just price — the cheapest quote sometimes reflects lower liability limits or missing coverage types.
Financial and Strategic Implications: 2026 Rate Benchmarks
Understanding current market rates helps you evaluate whether a quote you’ve received is actually competitive.
| Coverage Level / Company | 2026 Rate Benchmark | Source |
|---|---|---|
| National average, full coverage | $193/month ($2,315/year) | NerdWallet April 2026 analysis |
| National average, minimum coverage | $52/month ($621/year) | NerdWallet April 2026 analysis |
| Cheapest large insurer, full coverage | Travelers, ~$139/month | NerdWallet March 2026 analysis |
| Cheapest large insurer, liability-only | GEICO, ~$41/month | NerdWallet March 2026 analysis |
| Most expensive state (full coverage) | Nevada, ~$335/month | ValuePenguin 2026 State of Auto Insurance |
| Cheapest state (full coverage) | Vermont, ~$128/month | ValuePenguin 2026 State of Auto Insurance |
Expert insight: 2026 is shaping up to be the calmest year for auto insurance pricing since 2022, with national rates projected to rise less than 1% on average — following double-digit annual increases in 2023 and 2024. That relative stability makes this a favorable year to shop aggressively, since insurers competing for market share in a flatter-rate environment are often more willing to offer competitive new-customer pricing.
Why Identical Coverage Can Still Produce Very Different Quotes
Because each insurer’s underwriting model weighs risk factors differently — one company might penalize a recent speeding ticket heavily while barely adjusting for credit score, while another does the reverse — your price can vary meaningfully between insurers even for the same driver and coverage, which is exactly why comparison shopping consistently produces savings that simply renewing with the same insurer does not.
How to Choose the Right Auto Insurance Quote
- Don’t default to price alone — verify the liability limits, comprehensive/collision deductibles, and any exclusions match across every quote you’re comparing.
- Ask about bundling discounts — combining auto with homeowners or renters insurance frequently produces a meaningful discount with the same carrier.
- Check for usage-based/telematics programs — safe drivers can often secure additional discounts through an insurer’s driving-monitoring app.
- Re-shop annually, not just at renewal notice, since insurer pricing models shift and a company that was competitive last year may not be this year.
- Confirm the insurer’s claims-handling reputation, not just price, using state insurance department complaint ratios or third-party satisfaction surveys.
- Review minimum coverage carefully — the cheapest liability-only policy may leave you underinsured relative to your actual assets in a serious at-fault accident.
Key takeaway: The single biggest mistake drivers make isn’t picking the wrong insurer — it’s not requoting at all. Insurance pricing models change frequently enough that a policy competitive two years ago can quietly become overpriced relative to the current market, with no notification from your current insurer.
Future Outlook: Auto Insurance Rate Trends Through 2027
- Rate growth is expected to remain unusually flat. ValuePenguin projects national auto insurance rates to rise by less than 1% on average in 2026, the smallest increase since 2022, though state-level trends diverge significantly — some states are projected to see rates fall by several percentage points while others, led by New Jersey, are projected to rise more sharply.
- State-level divergence is widening. More than half of states are expected to see rates decline in 2026, even as a handful of states see continued increases, making location-specific comparison shopping more valuable than ever.
- Usage-based insurance adoption continues to grow. As more insurers expand telematics-based discount programs, safe drivers increasingly have access to meaningfully lower rates than standard pricing models would otherwise offer.
- Credit-based insurance scoring remains a contested policy issue. Several states continue to debate restricting or eliminating the use of credit history in auto insurance pricing, a change that could meaningfully shift relative pricing among insurers if enacted more broadly.
Frequently Asked Questions
How many auto insurance quotes should I get before choosing a policy? Most experts recommend comparing quotes from at least three to five insurers, including a mix of large national carriers and regional companies, since regional insurers can significantly undercut national pricing in specific states.
Will getting multiple auto insurance quotes hurt my credit score?
Generally no. Auto insurance quotes typically use a “soft pull” that doesn’t affect your credit score, unlike a hard inquiry from a loan or credit card application.
Why did my auto insurance quote go up even though I haven’t had any accidents?
Rate changes can reflect broader factors unrelated to your personal driving record, including inflation in vehicle repair costs, regional claims trends, and insurer-wide rate filings approved by state regulators.
Is the cheapest auto insurance quote always the best choice?
Not necessarily. A lower price can reflect reduced liability limits, higher deductibles, or missing coverage types, so it’s important to confirm you’re comparing genuinely equivalent coverage before choosing based on price alone.
How often should I shop for new auto insurance quotes?
Annually is a reasonable standard practice, since insurer pricing models and competitive positioning change over time, and a policy that was competitively priced in a prior year may no longer be.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Open Banking Trends 2026: What Consumers Should Know

Nvidia After the Selloff: What to Watch Before Earnings

Black Friday 2026 Early Deals: A Data-Driven Shopping Guide

Fed Policy Path 2027: Rate Expectations After the Hold

Asia’s Economic Resilience in 2026: The Strategic Blueprint for Sustaining the Global Growth Engine

Credit Scoring Changes 2026: What Mortgage Buyers Need to Know

10-Year Treasury Yield Outlook for 2027 After the Democratic Sweep

Is the AI Infrastructure Boom Sustainable? A Reality Check

Disability Insurance Demand in 2026: Who’s Buying and Why

What the 2026 Midterms Mean for Treasury Yields and Bond Markets

Payroll Outlook After the Midterms: 2027 Tax Changes, Compliance Risks and AI Trends

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025