
UK Economy
UK Political and Economic Turmoil: Rachel Reeves’ Fall, Britain’s Fiscal Crisis

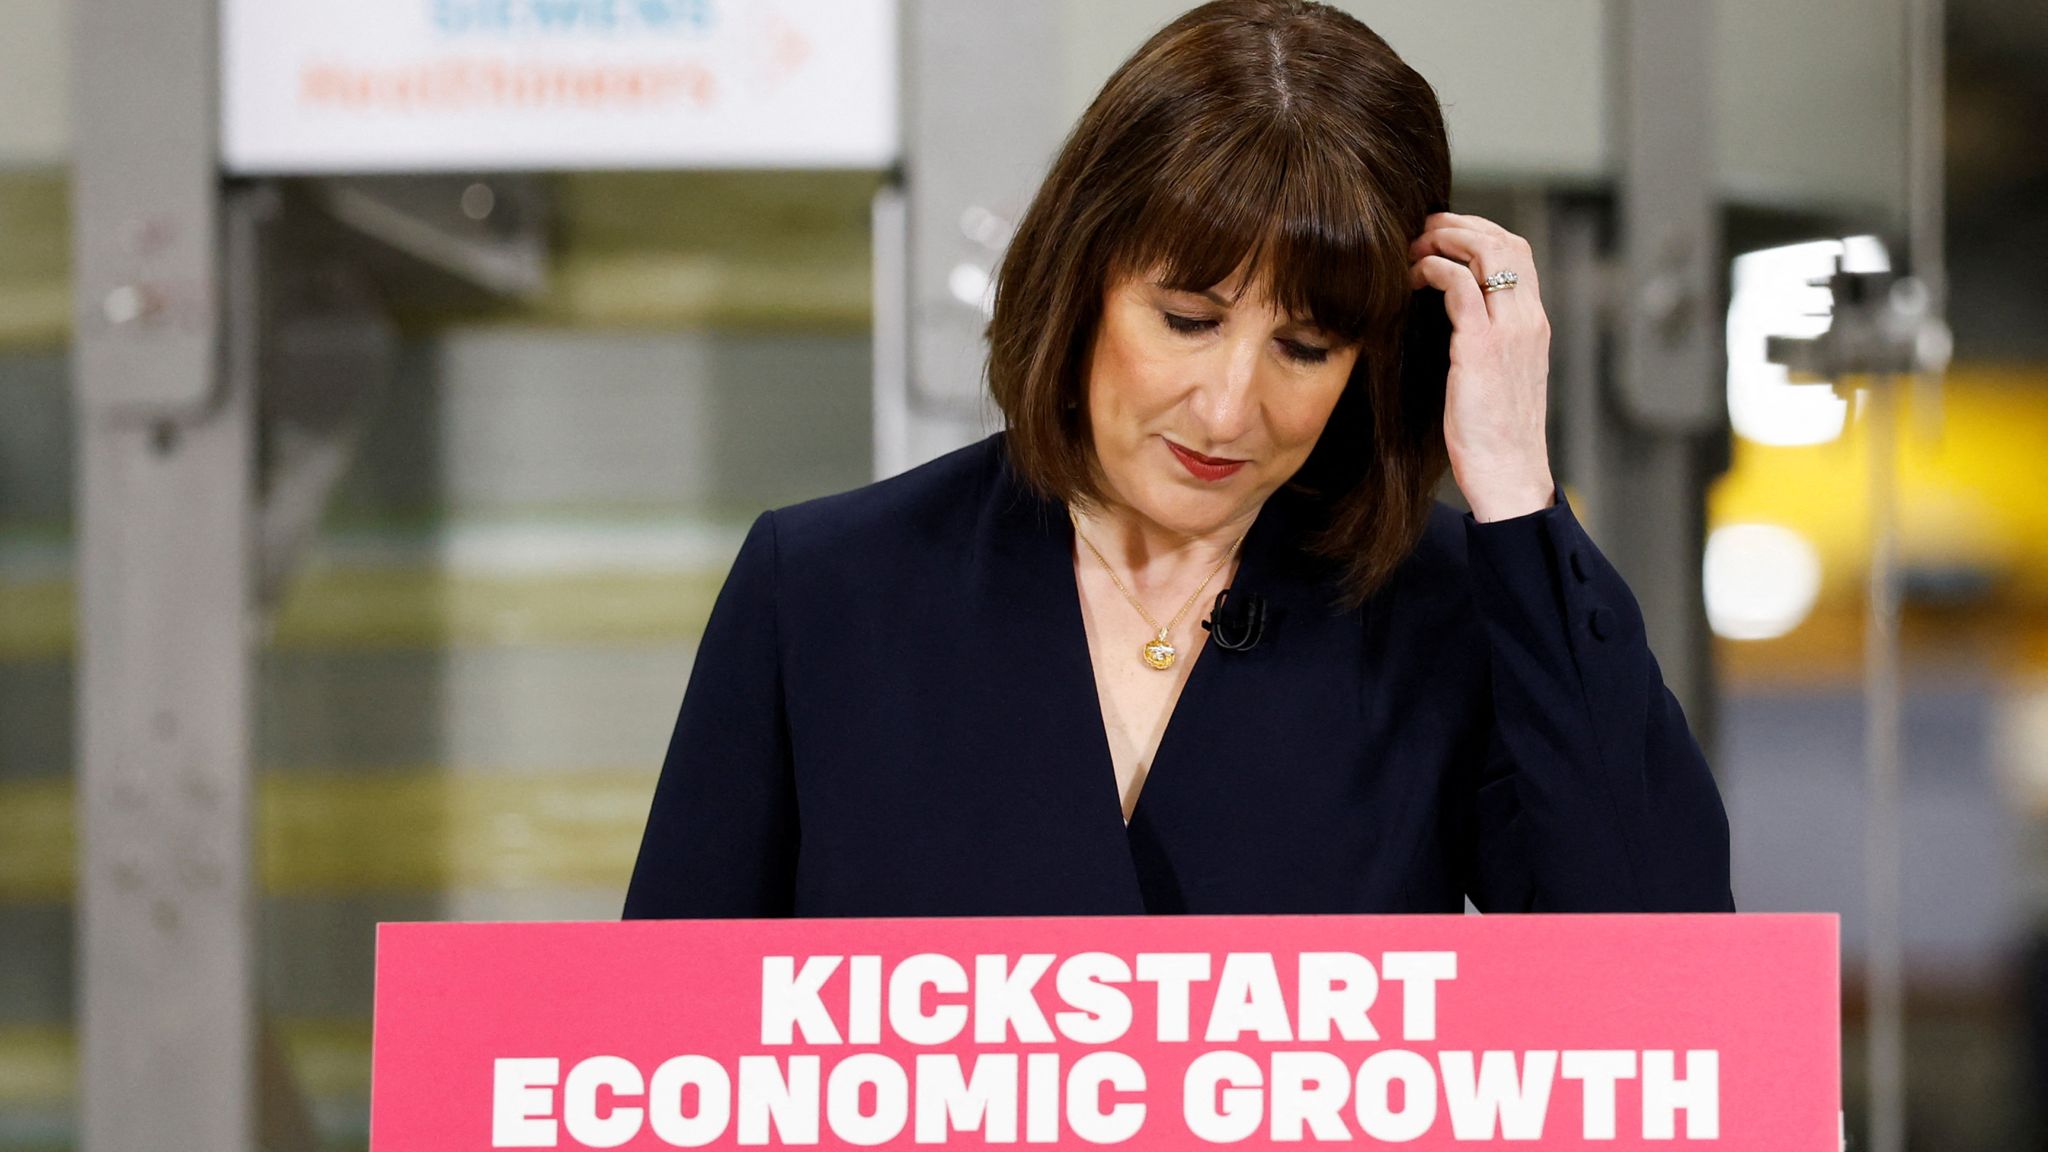
The British pound and UK markets are under pressure as reports suggest incoming Prime Minister Andy Burnham plans to demote Chancellor Rachel Reeves, while the Fed’s hawkish pivot tightens global financial conditions. Here is what Britain’s compounding crises mean for investors.
A Kingdom in Political and Economic Uncertainty
Britain entered June 25, 2026, facing a confluence of pressures that have become characteristic of the country’s post-Brexit decade: political instability at the top, persistent inflation, and a global monetary environment that is tightening at precisely the wrong moment for the UK’s already-strained public finances.
The BBC and the Financial Times reported that Andy Burnham — the sole contender to replace Keir Starmer as Prime Minister — would demote Rachel Reeves from Chancellor of the Exchequer to a more junior role should he become prime minister. The prospect of yet another change at the UK’s Treasury — the country’s fourth Chancellor in eight years — sent ripples through sterling and gilt markets.
The response was immediate and predictably fractious. Former Goldman Sachs Asset Management Chairman Jim O’Neill, a member of the House of Lords and informal advisor to Burnham, pushed back publicly on CNBC, suggesting the reports may not be “entirely accurate” and that there “shouldn’t be so much focus on who the person is.” The ambiguity itself was damaging — markets dislike uncertainty about who controls fiscal policy in the world’s sixth-largest economy.
The Bank of England’s Difficult Balancing Act
Against this political backdrop, the Bank of England faces one of its most difficult policy environments in decades. The Bank of England kept its base rate steady at 3.75% at its most recent Monetary Policy Committee meeting, acknowledging that it was “hard to predict” what will happen to prices as a result of the Iran war. Annual inflation in the UK was unchanged at 2.8% in May versus the previous month.
UK inflation at 2.8% is above the 2% target but below the 4.2% running in the United States, giving the MPC somewhat more flexibility than its American counterpart. However, the energy shock from the Hormuz crisis has driven transport inflation sharply higher, and the global backdrop — with the US Fed now signaling potential rate hikes — limits how far the Bank of England can diverge from American monetary policy without putting downward pressure on sterling.
A weaker pound raises import prices and adds to domestic inflation — the classic import inflation trap that has bedeviled UK monetary policy for much of the post-2016 period.
Fiscal Credibility: Reeves’ Legacy and Burnham’s Challenge
Rachel Reeves, love her or loathe her, represented continuity for markets. Her replacement — or even the uncertainty over her replacement — introduces a fiscal risk premium at a time when the UK’s debt burden is already elevated, public services are under strain, and the government’s fiscal rules are being tested by slow growth and high borrowing costs.
Whoever runs the Treasury in 2026 faces the same brutal arithmetic: limited room to spend, political pressure to invest in public services, and borrowing costs elevated by global monetary tightening. The question for markets is whether the incoming leadership has the credibility and the will to maintain fiscal discipline under that pressure.
Jim O’Neill’s intervention — telling markets not to fixate on the individual — suggests that those close to Burnham are aware of the optics and are attempting damage control. But in finance, perception often creates its own reality. UK gilt yields and sterling will be closely watched in the days ahead.
What Investors Should Watch
Sterling: Any confirmed report that Reeves is being demoted is likely to trigger a sterling selloff as markets reprice fiscal risk. Watch the GBP/USD rate closely.
UK Gilts: 10-year gilt yields remain the key indicator of market confidence in UK fiscal policy. A rise above 4.5% would signal genuine concern about fiscal credibility.
UK Equities: The FTSE 100’s heavy commodity exposure means it is actually partially shielded from domestic political risk — energy stocks have benefited from higher oil prices during the Iran crisis. The FTSE 250, more domestically focused, is more vulnerable to UK-specific political risk.
Bank of England Path: If the Fed hikes in 2026, the Bank of England will face pressure to follow, even if domestic conditions would otherwise argue for a hold. The global rate environment has become the binding constraint on UK monetary policy.
FAQ
Q: Who is Andy Burnham? Andy Burnham is the Mayor of Greater Manchester and, as of June 2026, the sole contender to replace Keir Starmer as Labour leader and UK Prime Minister. Known for his populist, Northern England-focused political brand, he has not yet fully articulated his economic programme.
Q: What has Rachel Reeves done as Chancellor? Reeves has focused on fiscal stability and attempted to restore market confidence in UK public finances following a period of turbulence. Her approach has been broadly orthodox — maintaining fiscal rules while trying to create space for public investment.
Q: What is the Bank of England’s current interest rate? As of June 2026, the Bank of England’s base rate stands at 3.75%, following a period of cautious easing. The next move is uncertain, with the MPC balancing persistent above-target inflation against the economic drag from the Iran war’s energy shock.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Is the FTSE 100 at a record high in 2026? Yes, repeatedly. The UK’s blue-chip index broke through the 10,000-point threshold for the first time in its history on January 2, 2026, touching an intraday peak of 10,046.25 points, and has gone on to set a string of further records through the year — reaching roughly 10,846.70 by late February and approaching 10,908 by late July, according to tracking from Trading Economics and Hargreaves Lansdown.
That run extends a strong 2025, when the index posted an annual gain of more than 20% — a performance that had already reset expectations for what UK equities could deliver after years of being treated as a laggard relative to U.S. markets.
What’s Driving the Rally
Featured Snippet Target: The FTSE 100’s 2026 rally has been driven by a combination of earnings resilience across globally diversified blue-chip companies, attractive valuations relative to international peers, expectations of further Bank of England interest rate cuts as UK inflation eases, and a weaker sterling that boosts overseas earnings for the index’s many exporter-heavy constituents.
UK inflation has been the single biggest tailwind. By mid-February, inflation had slowed to 3% — its lowest level since March 2025 — driven by falling petrol, airfare, food, and education costs, which strengthened market expectations for continued Bank of England rate cuts, according to Trading Economics. That combination of falling inflation and rate-cut expectations has repeatedly been cited as the catalyst behind individual record-high sessions throughout the year — including a session in which the index breached 8,300 points as traders returned from a long weekend pricing in additional Bank of England easing ahead of a policy meeting, per Reuters coverage carried by Yahoo Finance.
Sector leadership has rotated through the year rather than concentrating in one theme the way U.S. markets have around AI. Early-year gains were led by companies with global earnings exposure — Shell, HSBC Holdings, and AstraZeneca all posted record highs during a rally that saw the index climb 8.5% in the first two months of 2026 alone, a bounce that followed a sharp April 2025 selloff tied to that year’s “Liberation Day” tariff turmoil, according to analysis from interactive investor. Defence stocks were a standout theme later in the rally, with BAE Systems gaining roughly 4% on stronger revenue, orders, and profit, alongside gains for Babcock and Rolls-Royce, while mining names including Glencore, Antofagasta, and Fresnillo advanced as metals and precious-metals prices climbed.
The Global Comparison Matters
For context on what a 20%+ annual gain actually represents globally: the FTSE 100’s roughly 8.5% year-to-date gain by late February was only bettered among major global indices by a near-14% jump in Japan’s Nikkei 225, which was itself boosted by fiscal stimulus expectations following a change in Japanese political leadership. That places UK equities firmly in the upper tier of global index performance for 2026 — a notable reversal from the index’s reputation in prior years as an unloved, undervalued market overshadowed by U.S. technology stocks.
Individual stock winners have varied by theme. Takeover targets Beazley and Schroders posted the largest single gains among FTSE 100 constituents earlier in the year, while the mining quartet of Antofagasta, Endeavour Mining, Glencore, and Fresnillo posted gains between 27% and 33% on the back of rising metals prices. More than 40 constituent stocks registered double-digit gains through the first two months of the year alone, spanning sectors from consumer staples (Diageo) to telecoms (BT Group) to retail (Tesco).
Not Every Sector Is Winning
The rally has not lifted every FTSE 100 name. Data and information-services companies including RELX, Experian, and Sage Group have lagged the broader index — RELX shares fell by more than a fifth through the early part of the year — as investors reassessed the competitive threat AI-driven tools pose to traditional data and legal-services businesses. That divergence mirrors, on a smaller scale, the AI-driven winner-loser split playing out across U.S. markets, where AI infrastructure spenders have vastly outperformed companies whose core business AI threatens to disintermediate.
Risks to the Rally
Analysts tracking the FTSE 100’s record run through 2026 have consistently flagged the same set of risks even as the index kept climbing: heightened geopolitical tensions (particularly any escalation of the Middle East conflict affecting oil prices, which spiked to $110 a barrel at one point during the year), an unexpected resurgence in UK inflation that could stall Bank of England rate cuts, a sharper-than-expected slowdown in global growth, or an earnings-delivery breakdown among the index’s largest constituents that could unsettle broader sentiment. None of these risks had materialized meaningfully enough to derail the rally as of late summer 2026, but each remains a live catalyst that could reverse the index’s momentum.
The Bottom Line
The FTSE 100’s 2026 performance represents one of the most significant re-ratings of UK equities in years, driven by a genuine combination of falling inflation, rate-cut expectations, resilient blue-chip earnings, and a weaker pound that flatters the index’s globally-earning exporters. But the rally is not uniform — data and information-services stocks facing AI disruption have been left behind, and the same geopolitical and inflation risks that have periodically rattled global markets all year remain squarely in play for UK equities too.
Next step: Investors tracking UK equities should watch Bank of England policy meetings and UK inflation prints as the clearest near-term signal for whether the FTSE 100’s rate-cut-driven rally has further room to run.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
A new Reuters poll shows 90% of economists expect the BoE to hold rates at 3.75% for the rest of 2026 — up from 83% last month. Here’s why the consensus hardened.
The Bank of England looks set to sit tight for the rest of 2026, and the consensus behind that view is getting stronger, not weaker. Per Investing.com’s coverage of the Reuters poll, the Bank will leave rates unchanged at 3.75% for the rest of the year according to a strong majority of economists, who have held that view since the war began in late February. Nearly 90% — 56 of 64 respondents — now expect no change through year-end, up from 83% last month, with six expecting a hike and two a cut; no one in the poll, conducted August 13–18, expects a September move.
Key Takeaways
- A Reuters poll of 64 economists (Aug 13–18) shows 56 now expect the BoE to hold Bank Rate at 3.75% through year-end — 90%, up from 83% last month.
- No economist in the poll expects a rate change at the September MPC meeting.
- The consensus has held since the US-Israeli war on Iran began in late February, with little evidence yet of energy-price spillover into the broader economy.
- Markets remain slightly more hawkish than economists, still pricing some chance of a rise by year-end.
- The BoE’s own guidance flags rising Q3/Q4 inflation risk tied specifically to Middle East energy prices.
The consensus is driven less by domestic demand and more by an external variable the Bank has flagged repeatedly. Per the same Reuters poll coverage, the UK economy has stayed mostly resilient since the war began, with little evidence of energy-price spillover into the broader economy — giving the Bank room to stay on the sidelines.
That resilience is fragile by the Bank’s own admission. According to an August 2026 review from Hanbury Wealth, the MPC voted six-to-three at its July 30 meeting to hold at 3.75%, with policymakers signaling rates could rise if Middle East-linked inflationary pressure intensifies; Governor Andrew Bailey said inflation had fallen faster than expected, but the conflict continues to mean high and volatile energy prices that will push inflation back up later in the year. The Bank’s own trajectory reflects this: per the House of Commons Library’s inflation briefing, based on mid-June energy pricing, the Bank projected CPI at “a little under 3%” in Q3 2026 and “a little over 3¼%” in Q4 — a downgrade from its April forecast.
There’s a genuine two-sided risk the poll’s headline framing tends to flatten. On the downside for inflation, the same House of Commons briefing notes that if Middle East energy disruption proves short-lived and oil and gas prices decline, inflation could instead fall from a September 2026 peak toward the Bank’s 2% target by Q2 2027. On the upside risk, HSBC UK economist Elizabeth Martins told Reuters (via Investing.com) that “a big rebound in energy prices would certainly change things.”
Markets aren’t as settled as the economist consensus: per the same poll coverage, financial markets are still pricing in one quarter-point rate rise by year-end — a genuine gap between what economists expect and what traders are hedging against, reported by outlets as two separate data points rather than connected explicitly.
Underlying data support a “resilient but fragile” framing. A KPMG-cited economic overview from Opus Business Advisory Group shows GDP grew 0.7% in the three months to May, slightly down from 0.8% in April, while core inflation fell more than expected in the twelve months to June, reaching its lowest rate since March 2025 — evidence the disinflation trend independent of energy hasn’t reversed. Separately, the House of Commons Library data shows food price inflation eased to 1.7% in June, its lowest since August 2024, reinforcing that the risk is concentrated in energy rather than broad-based prices.
Why It Matters
For borrowers, a prolonged hold at 3.75% keeps mortgage costs elevated relative to sharper-cut scenarios floated earlier in the year. For savers, it sustains relatively attractive cash returns. For the government, Opus’s review notes Prime Minister Andy Burnham has pledged a £2 bus-fare cap and removal of VAT from household electricity bills from October while maintaining existing fiscal rules and avoiding tax rises — a combination that gets harder to fund if borrowing costs stay elevated through year-end.
Data and Evidence
- Bank Rate: held at 3.75% since the July 30 MPC vote (6-3)
- Reuters poll: 56 of 64 economists (90%) expect no change through year-end, up from 83% last month
- BoE inflation forecast: ~3% Q3 2026, ~3.25%+ Q4 2026
- GDP growth: 0.7% in the three months to May 2026
- Food inflation: 1.7% in June 2026, lowest since August 2024
Global Impact
A UK central bank holding firm against energy-driven inflation risk is a data point other energy-importing economies — including Pakistan and much of South and Southeast Asia — are watching as a template for treating Middle East-linked price shocks as transitory.
What Happens Next
The next live decision point is the September MPC meeting, where the poll shows unanimous expectation of no change. The Q3/Q4 inflation prints will show whether the Bank’s own ~3.25% forecast materializes — and whether the hold consensus survives contact with that data.
Frequently Asked Questions
What is the UK’s current interest rate?
3.75%, unchanged since July 30, 2026.
Why isn’t the BoE cutting further?
Concern that Middle East-driven energy prices could push inflation back up in H2 2026.
Will UK mortgage rates change soon?
Based on the current poll, no near-term move is expected.
What would change the outlook?
A significant rebound — or further de-escalation — in Middle East energy prices.
Do markets agree with economists?
Not entirely — traders still price some chance of a year-end rate rise.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Four major UK forecasters — the OBR, the Bank of England-adjacent IFS, NIESR, and RSM UK — are converging on a similar diagnosis for 2026: an economy that’s avoiding outright recession but also not meaningfully growing, squeezed between resilient inflation and cautious business investment.
The Growth Numbers Are Converging Downward
RSM UK’s latest forecast puts 2026 GDP growth at just 1.0%, down from 1.4% in 2025, describing the pattern explicitly as “stagflation-lite” for a second consecutive year, with a modest recovery only expected in 2027 as inflation fades and rate cuts continue, according to RSM’s economic outlook. NIESR’s central forecast is slightly more optimistic at 1.4% GDP growth for 2026, describing the economy as beginning the year “closer to normal than at any other point this decade” despite heightened geopolitical stress, per NIESR’s winter 2026 outlook.
The Institute for Fiscal Studies frames the constraint more directly: consumption and business investment will likely stay muted as elevated uncertainty, still-restrictive monetary policy, and continued household saving all weigh on activity, with businesses “dissuaded from investing by squeezed margins and high financing costs,” according to IFS’s economic outlook.
Inflation Is Heading Back Up, Not Down
The most consequential shared theme across forecasters: inflation, which briefly dipped below 3% in early 2026, is expected to climb back toward 3.5% by year-end. RSM attributes this to a 13% rise in the energy price cap in July, higher motor fuel costs, and pass-through effects into food and goods prices, forecasting inflation to average 3.1% for 2026 overall, per RSM’s analysis. Notably, the report flags that the IMF has revised its UK inflation and growth forecasts more sharply than for any other developed economy, given Britain’s outsized reliance on gas for electricity pricing.
Bank of England Rate Path
Despite the inflation uptick, both NIESR and IFS still expect further Bank of England rate cuts through 2026. NIESR forecasts two further 25-basis-point cuts bringing Bank Rate to 3.25% by year-end — its estimate of the long-run neutral rate — following a cut to 3.75% in December 2025. IFS’s own forecast assumes Bank Rate reaches 3.5% in the first half of 2026. The divergence between continued rate cuts and rising inflation is the core tension defining UK monetary policy through the rest of the year.
Fiscal Headroom Is Nearly Gone
The Office for Budget Responsibility’s March 2026 outlook flags the tax-to-GDP ratio rising to a post-war high of 38% by 2030-31, with the November 2025 Budget having raised taxes by roughly £26 billion annually against OBR-assessed fiscal headroom of just £22 billion, according to NIESR’s reading of the same data. NIESR’s own forecast is notably more pessimistic than the OBR’s, projecting the current budget stays close to balance by 2029-30 with effectively no headroom at all — meaning public debt continues climbing toward 100% of GDP by decade’s end, sharply limiting the government’s room to respond to any future shock. RSM adds a domestic political risk on top: a Labour leadership contest raising the prospect of higher borrowing and renewed gilt yield pressure, with a short recession “not ruled out” if that risk materializes alongside global headwinds.
For UK-based investors, Deloitte notes the practical fallout includes a reduced cash ISA allowance for under-65s (down from £20,000 to £12,000) and a 2027 increase in tax on landlord property income — both tightening the traditional wealth-preservation toolkit just as broader growth conditions stay subdued, according to Deloitte’s TaxScape 2026 briefing.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

SpaceX Starship Achieves First Full Orbit on Historic 10-Hour Test Flight 14

Google’s $15B Finland AI Investment: Data Centers, Nuclear Power & Jobs

Fast Invoice Factoring: Rates, APR Math & Contract Traps

SOC 2 Type II Guide: Cost, Timeline & Compliance Companies

Hong Kong Wages Surge 3.4% in June: Sector Data & Analysis

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Gavin Baker AI Outlook: Why the Compute Shortage Persists Through 2028
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025