
China Economy
China’s Economy Is Now Dangerously Dependent on One Thing: Exports

China’s economy has held up better than many expected through 2026’s geopolitical turbulence, with growth for the second quarter tracking toward roughly 4.5% year-on-year, according to a median forecast of analysts surveyed by AFP — a step down from 5% in the prior quarter but still within the government’s 4.5–5% annual target. The headline resilience, however, is masking a structural shift that has received far less attention than it deserves: China’s growth engine has become almost entirely dependent on one lever, exports, at exactly the moment that lever faces the most geopolitical uncertainty in years.
The Domestic Engine Has Effectively Stalled
The data on China’s internal economy is stark. Retail sales fell for the first time in three years in May, despite the government pumping billions of yuan into special bonds supporting consumer trade-in subsidy programmes since 2024. Fixed-asset investment has also slumped. Rabobank’s Teeuwe Mevissen summarised the underlying problem bluntly: with no signal that the real estate crisis is ending, a recovery in consumption is hard to envision — a crisis now in its fifth consecutive year, with once-reliable home prices stagnating and dissuading buyers from treating property as a store of wealth.
The World Bank’s own July 2026 update confirms the property drag is structural rather than cyclical, projecting growth to slow to 4.4% in 2026 and 4.3% in 2027 as the property sector continues adjusting to genuinely lower housing demand. The Bank’s specific policy recommendation — strengthening the social safety net by raising benefit levels and extending coverage to informal workers — is a tacit admission that Chinese households are saving defensively rather than spending, precisely because they lack the social insurance that would let them draw down savings with confidence.
Exports Are Doing All the Work
What’s compensating for this domestic weakness is a genuinely resilient export sector. Goldman Sachs Research projects China’s current account surplus will rise to 4.2% of GDP in 2026, up from 3.6% in 2025 — a materially more bullish call than the Bloomberg consensus of 2.5%. The team’s reasoning rests on three pillars: rapid export expansion to emerging-market economies, limited ability among trade partners to erect meaningful new barriers given China’s dominance in critical supply chains, and falling export prices making Chinese goods increasingly price-competitive globally, even as dollar-denominated export price inflation is expected to turn positive in 2026, rising to 0.7% from -2.7% the prior year.
China’s service-sector trade tells the same story from a different angle: services trade expanded 6% year-on-year in the first five months of 2026, with knowledge-intensive service exports jumping 12.2%, reaching a combined 3.1 trillion yuan in total trade value — evidence that China’s export resilience isn’t confined to manufactured goods but extends into higher-value digital and intellectual-property-linked services as well.
The Labour Market Is the Weak Link Nobody’s Pricing
Perhaps the most underreported risk sits in China’s job market. Goldman Sachs’ own wage tracker shows year-over-year growth in urban nominal wages slowing to just 3.8% in the third quarter of 2025 — the weakest hiring environment in a decade outside of the Covid lockdown period, based on a composite of PMI employment sub-indexes. High-tech manufacturing, the sector generating China’s export strength, is simply not labour-intensive enough to absorb the workers displaced from the shrinking property and construction sector. That mismatch is a structural, not cyclical, constraint on any consumption-led rebalancing.
Why the Export Dependency Is a Genuine Vulnerability
The risk in over-relying on exports is not abstract. UBS’s own 2026-27 outlook flags uncertainties related to US trade and technology policy as a direct risk to the baseline forecast, noting that a burst of the global AI investment bubble could hit China’s tech-export momentum just as hard as a fresh round of tariff escalation. China’s own “new economy” sectors — estimated to already contribute roughly a quarter of GDP growth from 2020-24 — are precisely the export-exposed, high-tech segments most vulnerable to a shift in US policy or a correction in global AI capital expenditure.
The Bottom Line
China’s 2026 growth numbers look stable on the surface, but the composition has shifted meaningfully toward a single external lever — exports — at a moment when trade friction, an AI capex cycle that some analysts already worry is overextended, and a structurally weak domestic labour market all point toward the same conclusion: China’s rebalancing toward consumption, a stated priority since at least the 15th Five-Year Plan, remains more aspiration than reality. Investors and trading partners — including Pakistan, whose textile exports compete directly with Chinese manufacturing in some segments — should watch export data more closely than GDP headlines for the real signal on China’s trajectory.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Executive Summary
- Trade Truce Extension: Washington and Beijing extended the Busan economic truce by two months to January 10, 2027, establishing a bilateral Board of Trade mechanism with a $30 billion cap on tariff reductions for non-sensitive goods.
- Taiwan Policy Stance: President Xi Jinping pressed the U.S. administration to shift from “not supporting” to explicitly “opposing” Taiwan independence, while a U.S. $14 billion arms package to Taipei remains on hold.
- AI & Governance Divergence: Trump advocated for minimal federal AI regulation relying on existing legal channels, whereas Xi emphasized international norm-setting and human-controlled AI governance.
- Conflict Prevention: Both leaders highlighted shared WWII historical ties, but underlying systemic friction over technology controls and critical supply chains remains unhedged.
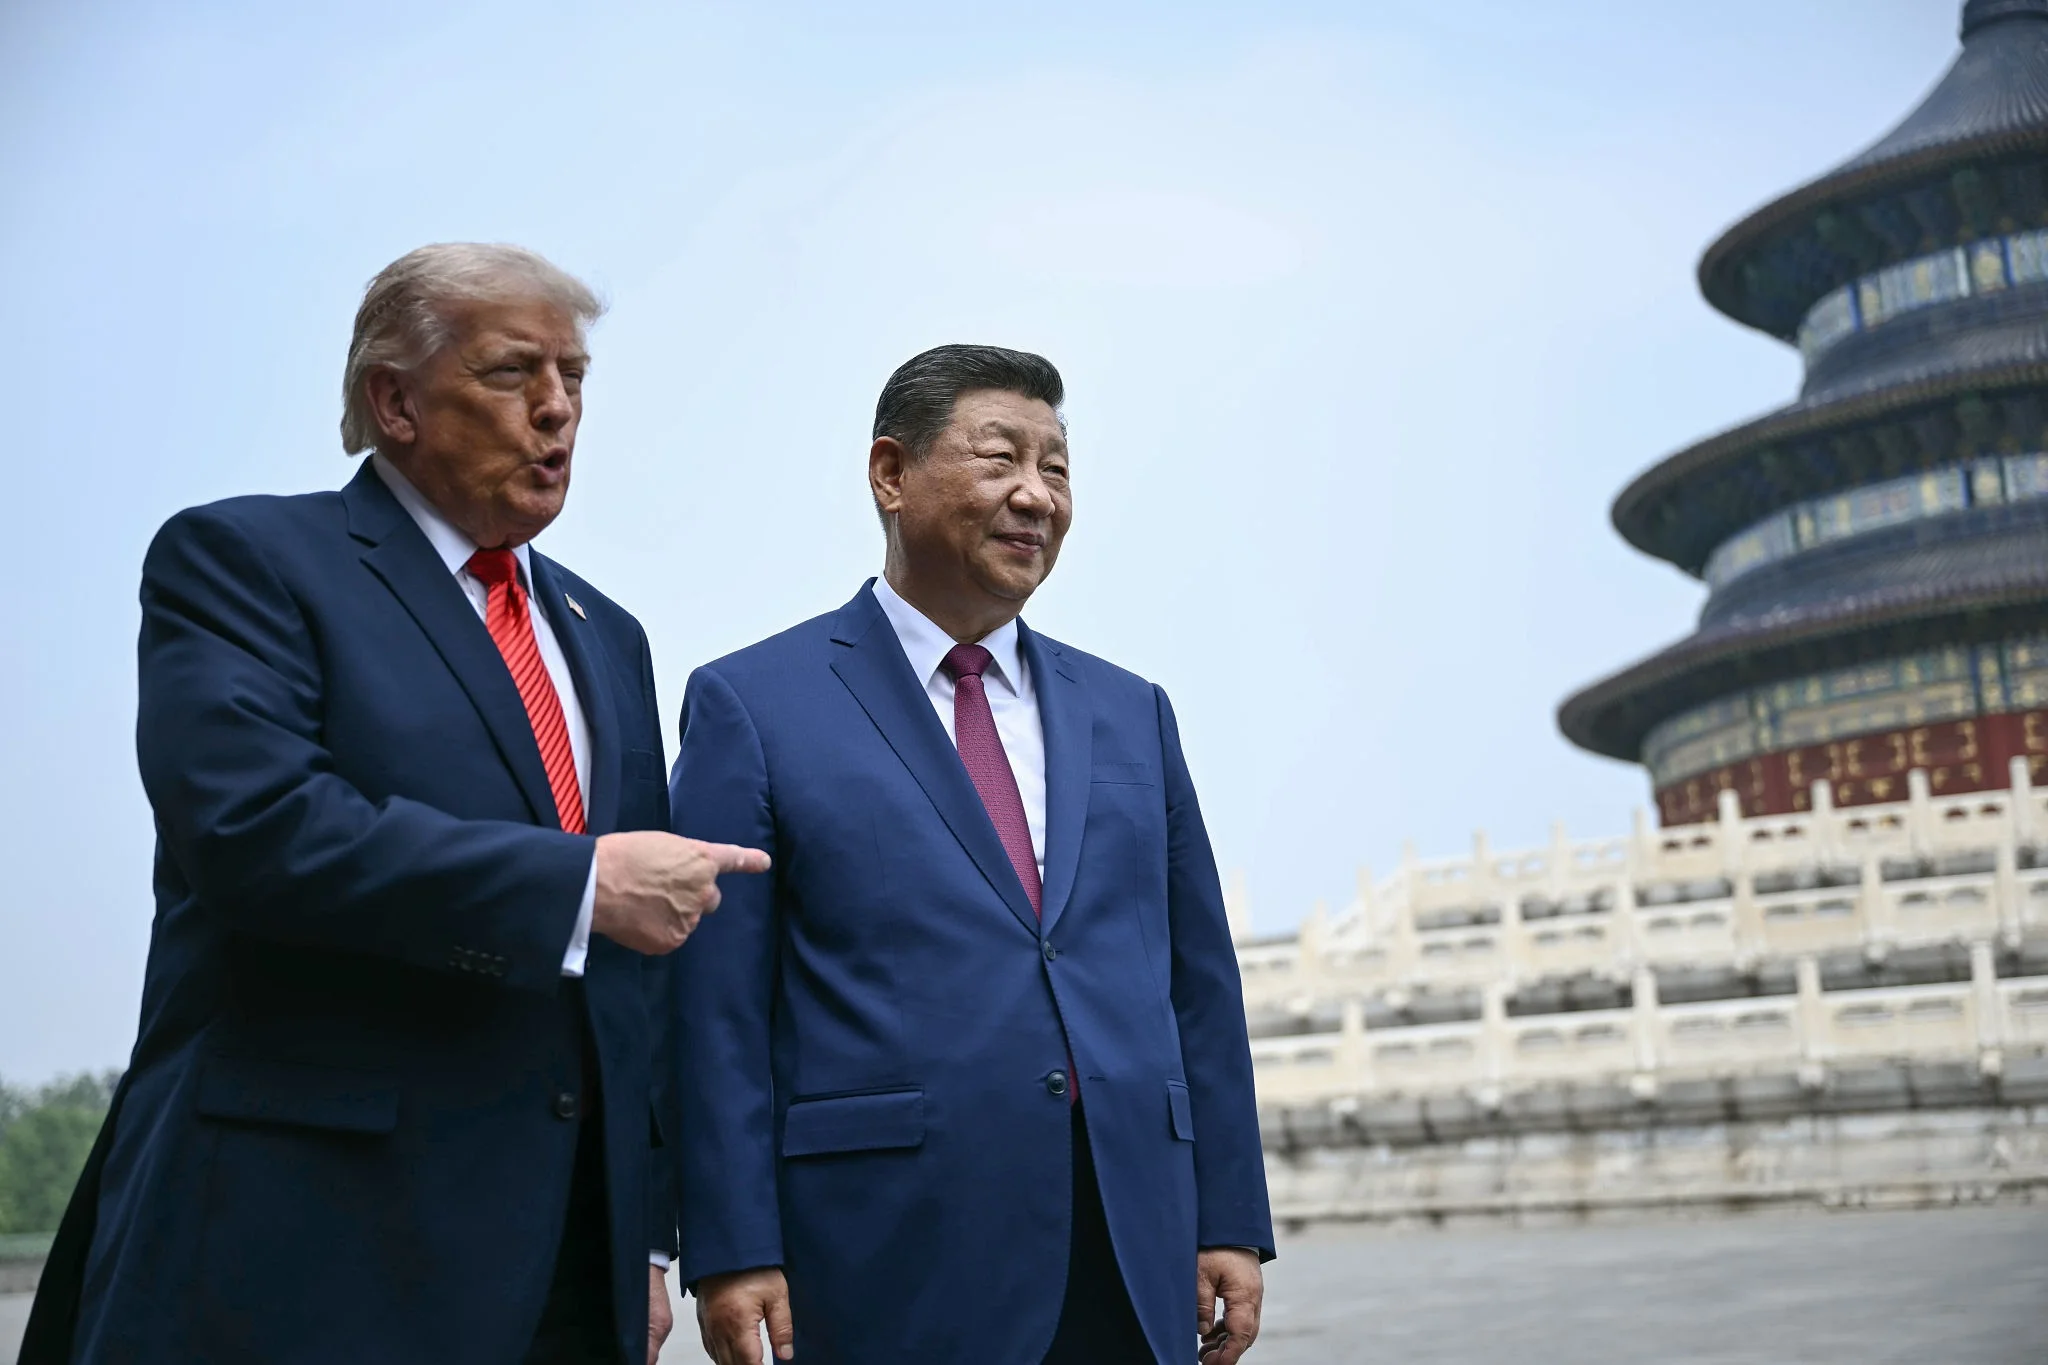
Presidents Xi Jinping and Donald Trump met in Washington, D.C., marking President Xi’s first official state visit to the United States in over a decade. The 43-hour diplomatic engagement combined high-profile ceremonial gestures with intense negotiations over economic policy, regional security, and emerging technologies.
1. Trade Deliverables & Managed Economic Detente
The core economic outcome of the summit was a mutual decision to extend the trade truce originating from the Busan agreements by an additional two months, pushing the negotiation window to January 10, 2027. According to analysis published by The Business Times, this temporal buffer buys critical space for both economies to formalize structured frameworks before political shifts take hold following the U.S. midterm elections.
Key Economic Components:
- Board of Trade Framework: Establishing a structured mechanism to oversee managed bilateral commerce.
- Tariff Cap Reductions: A planned mutual tariff reduction capped at US$30 billion per side, targeting non-sensitive consumer and industrial goods.
- Agricultural Commitments: China continues to meet its baseline commitments for purchasing 25 million metric tons of U.S. soybeans.
However, friction points persist below the surface. U.S. trade officials noted that Beijing remains behind on its broader pledge to purchase $17 billion in other U.S. agricultural exports. Furthermore, delivery quotas for critical rare-earth elements—essential for high-tech manufacturing—have fallen short of target allocations. As detailed by the Chicago Council on Global Affairs, reliance on personalistic leader-to-leader negotiations creates short-term pauses but leaves structural trade imbalances and supply chain dependencies unaddressed.
2. The Taiwan Question & Strategic Security
Diplomatic maneuvering over Taiwan represented the most sensitive geopolitical dynamic of the summit. President Xi reiterated Beijing’s core stance, urging Washington to handle the Taiwan issue with “extreme prudence” and asking the U.S. to actively oppose Taiwan independence rather than maintaining its traditional diplomatic posture of simply “not supporting” it.
Strategic assessments from the Institute for the Study of War indicate that Beijing views the current economic detente as a key window to influence U.S. security commitments in the Indo-Pacific. A planned U.S. $14 billion arms transfer package to Taiwan remains paused, delivering a tactical diplomatic win for Beijing ahead of upcoming multilateral regional gatherings.
3. Divergent Visions on AI Governance & High-Tech Competition
The summit exposed contrasting philosophies regarding the regulation of Artificial Intelligence and advanced computing capabilities. While both leaders acknowledged AI’s transformative influence on global power balances, their proposed paths forward reflect fundamental governance differences.
| Dimension | United States Stance | China Stance |
| Regulatory Model | Market-driven with minimal federal intervention; oversight through existing DOJ frameworks. | State-directed guardrails emphasizing central oversight and alignment with national strategy. |
| Global Governance | Defense of competitive edge and strict export controls on advanced hardware. | Multilateral norm-setting under international organizations (“AI for Good”). |
| Core Objective | Commercial freedom, innovation velocity, and technological superiority. | Human control, risk mitigation, and preventing technological decoupling. |
Reporting from The Federal highlighted that while Xi urged joint international responsibility to ensure AI remains under human control, the U.S. side favored preserving flexibility for domestic technological developers without introducing international regulatory mechanisms.
4. “Thucydides Trap” Avoidance & Strategic Guardrails
Throughout the summit, President Xi repeatedly warned against falling into the “Thucydides Trap”—the historical tendency toward conflict when a rising power challenges an established power. Calling for “constructive strategic stability,” Xi emphasized that global competition should resemble a “race of catching up with one another, not a wrestle in which one wins and the other loses.”
Institutional Takeaways:
- Regular Military Communications: Reaffirming bilateral crisis-prevention channels to prevent miscalculations in air and maritime corridors.
- Historical Commemoration: Leveraging shared World War II history during visits to national monuments to emphasize foundational ties.
- Corporate Engagement: Hosting state dinners with executive leadership to reinforce commercial interdependencies as a stabilizing buffer.
Strategic Outlook
While the 43-hour Washington summit succeeded in projecting stability and securing short-term economic extensions, fundamental strategic competition remains unresolved. The coming months will test whether temporary trade truces and managed tariff caps can withstand broader geopolitical rivalries in technology supply chains, semiconductor export policies, and Pacific security dynamics.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
China Economy
China’s Local Debt Race Against Time: Why Economists Demand Central Action Before the Deflation Window Closes
Key Policy Takeaways
- The Fiscal Dilemma: China’s local government hidden debt (off-balance-sheet LGFV liabilities) is estimated by the International Monetary Fund (IMF) to exceed 60 trillion yuan (~US$8.4 trillion).
- The Vanishing Window: Ultra-low benchmark interest rates and weak price indices offer Beijing an ideal window to swap high-cost, short-duration local liabilities for long-duration central sovereign bonds.
- The Risk of Delay: Waiting until inflation rebounds or global monetary policy tightens will significantly increase debt-servicing burdens and squeeze commercial bank margins.
- Structural Reform Needed: Refinancing alone is insufficient; Beijing must overhaul central-local tax distribution to prevent new hidden debts from accumulating.
1. The Perishable Window: Why Low Inflation Is a Double-Edged Sword
Prominent Chinese economic advisors are urging Beijing to capitalize on the country’s prevailing low-interest and soft-price environment to execute a comprehensive debt restructuring. According to research from the World Bank, China’s subdued consumer and producer price trends have created a rare, temporary period where sovereign issuance can be expanded with minimal immediate risk of runaway inflation or surging debt-servicing yields.
When price levels and market borrowing rates are low, the cost of issuing special central government bonds (Treasuries) is at historical troughs. By leveraging this environment, Beijing can absorb or refinance high-yield municipal obligations at fractions of their original servicing cost.
However, macroeconomists warn that this window is shrinking:
[Low Inflation & Low Yields] ──► [Lower Sovereign Issuance Costs] ──► [Ideal Debt Swap Window]
          │                                                                  │
          ▼ (If Delayed)                                                     ▼ (If Executed Now)
[Erosion of Local Revenues] ──► [Rising Default & Credit Risks]   ──► [Restored Fiscal Flexibility]
If Beijing delays central balance-sheet expansion, prolonged deflation risks further eroding local government tax revenues and land sales proceeds. Analysis from S&P Global Market Intelligence indicates that land sales revenues—historically accounting for up to 30% of municipal fiscal funds—have dropped significantly from their peak levels, leaving local authorities without the primary engine used to service off-balance-sheet vehicles.
2. The LGFV Mechanics: How Hidden Debt Stalls Regional Growth
The root of China’s fiscal challenge lies in Local Government Financing Vehicles (LGFVs)—special entities created by provinces and cities to finance public infrastructure without officially breaching central deficit caps.
The Anatomy of China’s Municipal Balance Sheet
- Official Municipal Debt: Directly tracked bonds subject to strict quota limits set by the National People’s Congress.
- Implicit / Hidden LGFV Debt: High-cost, off-balance-sheet bank loans, corporate bonds, and shadow banking products carrying implicit guarantees but yielding insufficient commercial returns.
As highlighted in a macroeconomic study by the Peterson Institute for International Economics (PIIE), when local debt-servicing costs outpace local economic growth, municipal governments are forced into fiscal austerity. This results in delayed civil service pay, cuts to public transit subsidies, and reduced local procurement—directly depressing domestic demand and compounding broader deflationary pressures.
3. The “Involution” Loop: Price Wars and Subsidized Capacity
A critical dynamic overlooked in conventional coverage is how local debt fuels industrial “involution” (内卷)—cutthroat, race-to-the-bottom price competition.
Faced with declining traditional tax revenues and mounting debt obligations, regional authorities frequently use local subsidies, cheap land allocation, and state-directed credit to prop up favored local manufacturing sectors (such as solar components, EV parts, and industrial chemicals).
┌────────────────────────────────────────────────────────────────────────┐
│                        THE INVOLUTION CYCLE                            │
├────────────────────────────────────────────────────────────────────────┤
│ 1. Local Debt Pressure  ──► Municipalities seek fast industrial GDP    │
│ 2. Target Subsidies     ──► Directed capital into local manufacturing  │
│ 3. Industrial Overcap   ──► Manufacturers overproduce to maintain scale  │
│ 4. Price Wars (CPI/PPI) ──► Deflationary pressure squeezes margins     │
│ 5. Lower Tax Revenues   ──► Debt burden expands relative to revenue    │
└────────────────────────────────────────────────────────────────────────┘
According to sector reporting from Rhodium Group, this localized credit allocation keeps unproductive firms afloat, floods domestic markets with overcapacity, and drives price deflation across industrial outputs. To break this loop, economists argue that Beijing must restrict local industrial subsidies while substituting them with direct central transfers to households.
4. Policy Roadmap: How Beijing Can Safely De-Risk Local Liabilities
To outperform past partial debt swaps, top financial experts recommend a coordinated four-point execution plan:
| Strategic Pillar | Action Item | Target Economic Outcome |
| 1. Central Balance Sheet Expansion | Issue Ultra-Long Special Sovereign Bonds to swap LGFV debt into central debt. | Reduces aggregate interest payments by hundreds of billions of yuan annually. |
| 2. Commercial Bank Shielding | Structure interest rate cuts alongside targeted PBoC liquidity injections. | Protects bank Net Interest Margins (NIMs) from lower bond yields. |
| 3. Tax Revenue Sharing Reform | Rebalance the 1994 tax-sharing system to allocate a higher tax share to local authorities. | Permanently aligns municipal spending obligations with recurring revenue. |
| 4. Consumption-Focused Stimulus | Shift state expenditures from physical infrastructure to social security, healthcare, and income support. | Unlocks household savings and drives organic demand-led reflation. |
Reports from the Organisation for Economic Co-operation and Development (OECD) emphasize that structural fiscal reform—specifically updating the distribution of revenues between Beijing and provincial capitals—is necessary to prevent local governments from simply building new hidden debt after the current swap is completed.
5. Global Implications for Investors and Markets
For international markets, China’s decision to act decisively on local debt carries substantial weight:
- Commodity & Global Demand: Restructuring local debt allows municipalities to resume core public works and social spending, stabilizing demand for global industrial metals and capital equipment, as monitored by the Asian Development Bank.
- Currency and Yield Dynamics: As noted by analysis in the Financial Times and market coverage in Bloomberg News, a central government debt swap reduces tail-risk in China’s financial sector, offering long-term stability for the Renminbi (RMB) even as benchmark rates remain low.
- Banking Sector Relief: Replacing non-performing or low-yielding LGFV loans with sovereign-backed paper lowers credit risk weights for state banks, preserving regulatory capital buffers across the broader financial system.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global Economy
Beyond Rhetoric: How the EU Is Deploying ‘All Tools’ to Rebalance Its €1 Billion-a-Day Trade Deficit with China
Key Takeaways
- The Tipping Point: European Commission President Ursula von der Leyen has declared that Europe’s trade deficit with China has reached an “unsustainable” €1 billion per day, pushing bilateral trade relations to a historical tipping point.
- Enforcement Over Engagement: Signaling a fundamental shift in doctrine, von der Leyen issued a direct ultimatum: “Words are good. But deeds are better.”
- The Defensive Arsenal: Brussels is escalating beyond traditional anti-dumping tariffs, actively deploying the Foreign Subsidies Regulation (FSR), the International Procurement Instrument (IPI), and establishing a centralized European Critical Raw Materials Corporation under the RESourceEU framework.
- Supply Chain Exposure: European and Asian enterprises face heightened compliance scrutiny, potential market access restrictions, and supply chain realignment risks across green-tech, automotive, and critical mineral sectors.
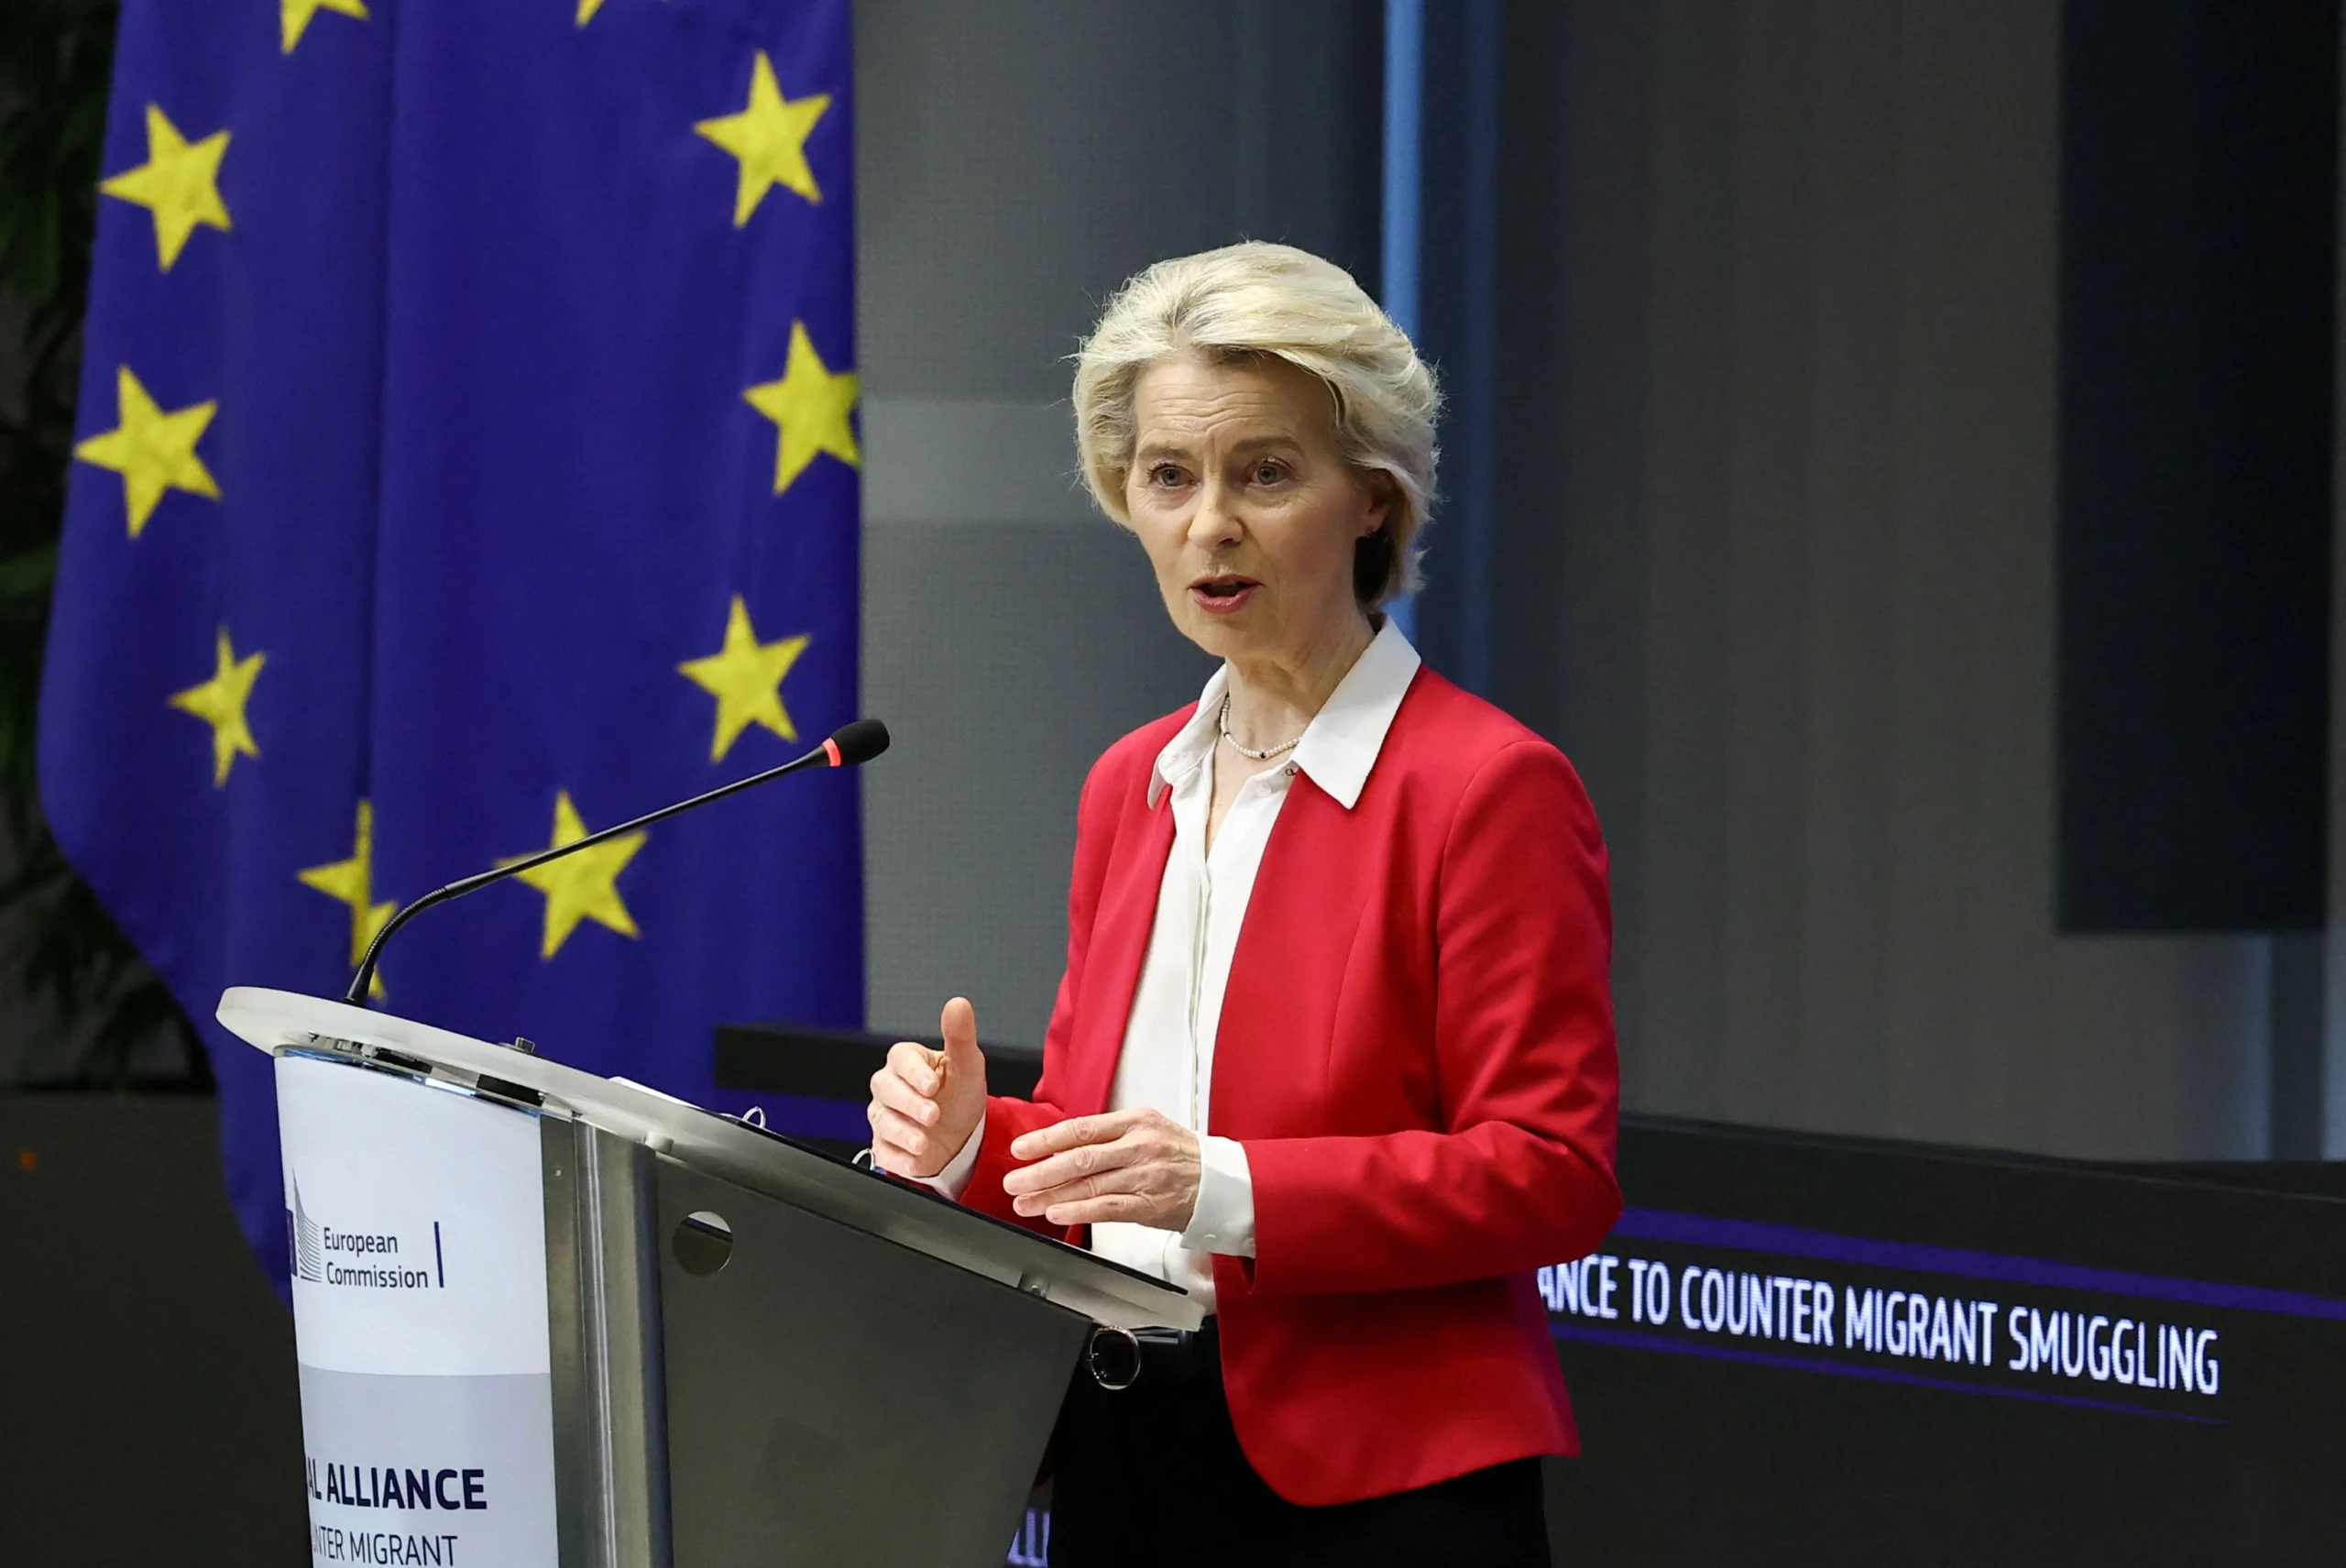
Commission President von der Leyen outlining EU trade policy in Brussels. Source: Yves Herman / REUTERS
The €1 Billion-a-Day Dilemma: Inside Brussels’ Trade Ultimatum
In her 2026 State of the Union address, European Commission President Ursula von der Leyen delivered her sternest warning to date regarding economic relations with Beijing. Citing structural industrial overcapacity in China and subsidized export dumping into the Single Market, von der Leyen emphasized that Europe’s trade deficit with China—now running at approximately €1 billion every single day—has crossed a critical threshold.
While reaffirming that diplomatic dialogue remains open, von der Leyen signaled that Brussels’ patience with protracted negotiations has expired:
“Words are good. But deeds are better. If market imbalances persist and level-playing-field conditions are not restored, the European Union will use all tools at its disposal to rebalance trade.” — Ursula von der Leyen, President of the European Commission
According to official data released alongside the address by the European Union External Action Service, the EU’s merchandise trade deficit with China has expanded sharply over the past decade. The expansion is driven by state-directed investments in clean technology, advanced industrial machinery, and automotive manufacturing, combined with persistent market barriers facing European exporters in mainland China.
Deconstruction of the EU’s Trade-Defence Arsenal
To move beyond political warnings, the European Commission is mobilizing a multi-layered regulatory architecture designed to shield European industries from non-market practices.
| Trade Defence Instrument | Legal Basis & Focus | Operational Impact on Chinese Exports |
|---|---|---|
| Foreign Subsidies Regulation (FSR) | EU Regulation 2022/2560 | Allows Brussels to inspect and block foreign state-subsidized companies from bidding on EU public tenders or acquiring European firms. |
| International Procurement Instrument (IPI) | EU Regulation 2022/1031 | Restricts access to EU public procurement markets for companies from countries that discriminate against EU businesses. |
| Anti-Subsidy & Anti-Dumping Duties | EU Regulation 2016/1037 | Enables retroactive tariffs on subsidized goods (e.g., Electric Vehicles, solar modules, wind turbines). |
| Critical Raw Materials Corporation (RESourceEU) | 2026 Industrial Strategy | Co-finances joint purchasing, strategic stockpiling, and processing of rare earth elements to reduce single-source dependency. |
As highlighted by macroeconomic analysis from Reuters Global Economic News, the Commission’s strategy represents a transition from reactive tariff enforcement to proactive market access restriction.
EU and China trade relations face growing regulatory and tariff barriers. Source: Bloomberg / Bloomberg via Getty Images
De-Risking in Action: Critical Minerals & the RESourceEU Imperative
A core pillar of von der Leyen’s strategic agenda is severing Europe’s vulnerable supply chain dependencies. China currently controls over 70% of global lithium refining, 85% of rare earth processing, and a dominant share of permanent magnet manufacturing.
To counter this vulnerability, von der Leyen confirmed the formal launch of the European Critical Raw Materials Corporation under the broader RESourceEU initiative. This entity will serve as a centralized buyer and investor, co-funding strategic mining, processing, and recycling projects within the EU, North America, and partner nations across Africa and Latin America.
Key objectives of the mineral security framework include:
- Extraction Mandates: At least 10% of the EU’s strategic raw materials extracted domestically by 2030.
- Processing Sovereignty: At least 40% of the EU’s annual consumption of strategic raw materials processed within the bloc.
- Diversification Caps: No more than 65% of any strategic raw material sourced from a single third country.
Economic reporting by the Financial Times Trade Analysis notes that these targets represent one of the most aggressive state-supported supply chain realignment efforts in modern European history.
Geopolitical Fallout & Beijing’s Countermeasures
Beijing’s Ministry of Commerce (MOFCOM) has expressed strong opposition to Brussels’ hardening stance, warning that increased trade barriers risk destabilizing global recovery and violating World Trade Organization (WTO) principles.
In response to European investigations under the FSR and anti-subsidy rules, China has initiated targeted anti-dumping probes into European exports, including brandy, dairy products, and agricultural machinery. Analysts anticipate that further unilateral measures by Brussels could prompt reciprocal restrictions on European automotive and chemical majors operating in mainland China.
+-----------------------------------------------------------------------+
|                 EU-CHINA TRADE TENSION CASCADE MATRIX                  |
+-----------------------------------------------------------------------+
| 1. EU Measures: FSR Inspections, Tariff Escalation, Raw Material Caps |
|    │                                                                  |
|    ▼                                                                  |
| 2. Chinese Countermeasures: Target Agribusiness, Spirits, Luxury Goods|
|    │                                                                  |
|    ▼                                                                  |
| 3. Corporate Impact: Supply Chain Realignment, Dual-Hub Production    |
+-----------------------------------------------------------------------+
Strategic Playbook for Global Business Leaders
For corporate executive teams and supply chain planners navigating this evolving landscape, the European Union Trade Policy Framework recommends three strategic adjustments:
- Audit State Subsidy Exposure: European subsidiaries of non-EU firms must conduct thorough audits of parent company subsidies, tax credits, and state grants to avoid disqualification under FSR procurement reviews.
- Diversify Critical Mineral Sourcing: Manufacturers reliant on graphite, neodymium, lithium, or cobalt should secure secondary supply contracts outside China ahead of 2027 compliance deadlines.
- Adopt “China + 1” Regionalization: Multinationals serving both European and Asian markets should decouple supply chains into distinct regional hubs to insulate operations from tariff hikes and export controls.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

IREN Stock in 2026: AI Cloud Growth, Bitcoin Transition and the Risks Investors Miss

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

Concert Ticket Prices in 2026: Dynamic Pricing, Fees and How to Buy Safely

High-Yield Savings Accounts in 2026: How to Compare APY Without Chasing a Headline

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025