
Analysis
Trump and his CEOs want China’s business – but has Asia moved on?

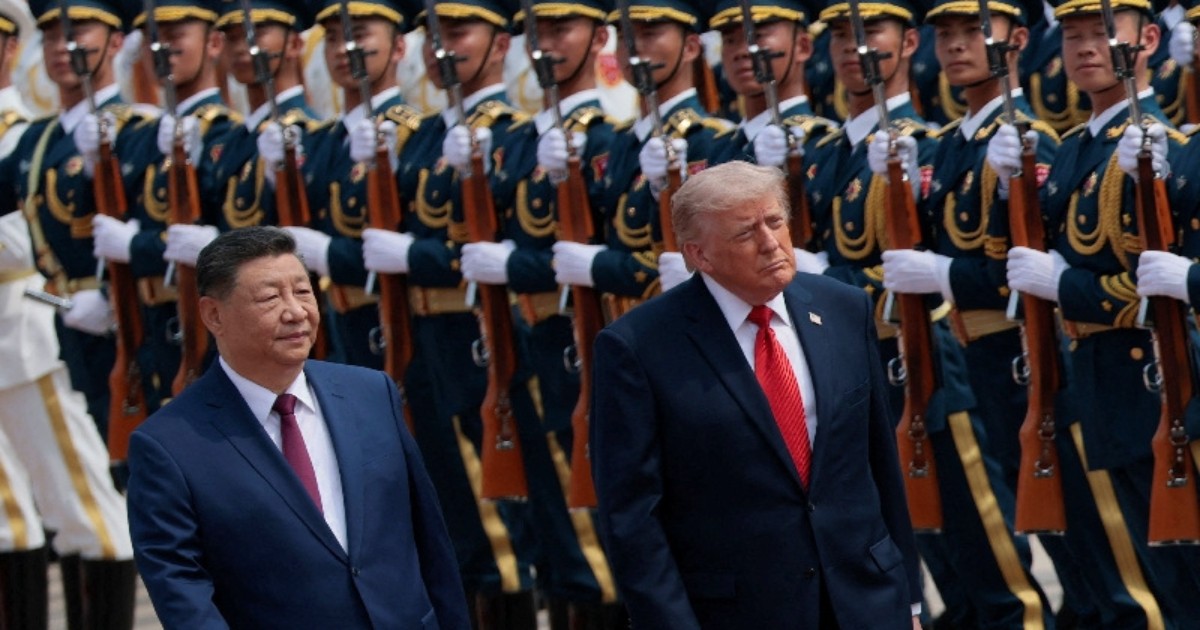
The US delegation went to Beijing looking for deals, but a ‘super cycle’ of capital expenditures across Asia is already fuelling enormous growth.
There is a particular species of optimism that attaches itself to grand diplomatic entrances. When a motorcade of black SUVs swept through Zhongnanhai’s red-lacquered gates last week carrying some of the most powerful executives in American capitalism — the heads of Apple, Nvidia, BlackRock, Tesla, and more than a dozen other corporate empires — it carried with it an unmistakable whiff of that optimism. Deals would be struck. Tariffs would soften. A new chapter of profitable engagement would begin.
Then Beijing spoke — not with a roar, but with the studied composure of a party that no longer needs to prove anything. President Xi Jinping received the delegation warmly. Communiqués were issued. Smiles were photographed. And then, underneath all the diplomatic theatre, the harder reality reasserted itself: Asia has been building its own future, and it has been doing so at a pace that makes American corporate courtship feel, at times, like arriving fashionably late to a party that peaked three years ago.
This is not decoupling. It is something subtler and, in many ways, more consequential — a reorientation of economic gravity so gradual that Washington’s political class has barely noticed, even as its most celebrated business leaders quietly scrambled to stay relevant.
The Delegation and What It Wanted
The composition of the US business delegation that accompanied President Donald Trump to Beijing for his first formal summit with Xi since returning to the White House was itself a kind of argument. Reuters reported a cohort of roughly 17 chief executives, a number that had Washington observers reaching for historical comparisons: it was reminiscent, in scale if not in spirit, of Nixon’s 1972 entourage of industrialists and strategists. Among them were Tim Cook of Apple, whose sprawling Chinese manufacturing ecosystem remains stubbornly difficult to replicate elsewhere; Jensen Huang of Nvidia, who came bearing a very specific anxiety about export controls and their effect on his company’s access to the world’s most voracious AI-chip market; Larry Fink of BlackRock, whose firm has been quietly expanding its asset management footprint in China; and Elon Musk, who occupies the curious position of being simultaneously the world’s most prominent American entrepreneur and one with his deepest manufacturing roots in Shanghai.
What did they want? The list was long and surprisingly familiar. A relaxation of semiconductor export restrictions — or at least a more predictable licensing regime — topped Huang’s agenda. Cook wanted reassurance on supply chain continuity and, more discreetly, progress on Apple’s stalled discussions about iPhone distribution in a market where Huawei’s domestic revival has been eating into its market share with uncomfortable speed. Fink wanted market access liberalisation in financial services. The aerospace contingent — Boeing’s representatives attended in an advisory capacity — hoped for progress on the 50-odd 737 MAX aircraft China has ordered but not yet accepted. And hovering above every conversation was the question of rare earth export controls, which China had quietly weaponised in early 2026 as a counterpunch to American chip restrictions, with effects rippling through defence and clean-energy supply chains from Detroit to Stuttgart.
Key items on the US delegation’s agenda · Beijing, May 2026
| Agenda Item | Companies Involved |
|---|---|
| Semiconductor export control reform | Nvidia, Qualcomm, Intel |
| Rare earth / critical minerals access | Auto, Defence, Energy sectors |
| Boeing aircraft deliveries | ~50 MAX units outstanding |
| Financial services market access | BlackRock, Goldman, JPMorgan |
| Tariff schedule renegotiation | 25–145% on Chinese goods |
| Apple supply chain assurances | Tim Cook / Apple |
The outcomes, at least as disclosed, were modest. A framework for “ongoing technical dialogue” on chip licensing. A vague endorsement of expanded cultural and student exchanges. Beijing’s agreement to review the Boeing deliveries — a process that has been under review, in one form or another, since 2019. The rare earths issue was not resolved so much as deferred, assigned to a working group that will report back at an unspecified future date. For a delegation of this commercial firepower, the haul was thin.
Asia’s Super Cycle: The Numbers Behind the Quiet Revolution
To understand why Beijing felt no particular urgency to make sweeping concessions, one needs to understand the economic context in which these negotiations took place. Across Asia, a capital expenditure super cycle is underway that is, by several measures, the largest coordinated burst of industrial investment since the postwar reconstruction of Japan and Germany.
Morgan Stanley’s Asia economics team has been tracking what it calls “the three-wave supercycle”: a simultaneous surge of investment in artificial intelligence infrastructure, energy transition assets, and strategic industrial capacity. In China alone, fixed-asset investment in high-technology manufacturing grew by more than 15% year-on-year in the first quarter of 2026, led by data centres, advanced semiconductor fabrication, and electric vehicle battery plants. The numbers are staggering in their aggregation: Bloomberg Intelligence estimates that Chinese technology companies committed over $120 billion in planned capital expenditure for 2026, a figure that, if realised, would exceed the combined annual technology capex of all European Union economies.
“Asia is not waiting for the West to decide what the future looks like. It is building the future’s plumbing — and doing so at a speed that makes Western planning cycles look glacial.”
— Senior economist, Asian Development Bank
But the story extends far beyond China’s borders, and this is the part that Washington’s China-focused analysts have been slowest to absorb. In India, Prime Minister Modi’s Production-Linked Incentive schemes have catalysed over $35 billion in committed manufacturing investment since 2023, with Apple, Samsung, and a constellation of Taiwanese suppliers now running or building facilities in Tamil Nadu and Karnataka that will, within two years, produce a meaningful share of the world’s smartphones. Vietnam — once dismissed as a temporary overflow valve for Chinese manufacturing — is now home to sophisticated electronics assembly operations run by Samsung and Intel that rival, in process complexity, anything in Shenzhen. Malaysia has become a critical node in the global semiconductor back-end supply chain, with OSAT (outsourced semiconductor assembly and test) capacity expanding at double-digit rates in Penang and Kuala Lumpur.
The Asian Development Bank’s 2026 outlook projects the developing economies of Asia will collectively expand by 4.9% this year, more than three times the forecast pace of the advanced economies. That differential is not new — it has persisted, with interruptions, for four decades. What is new is the quality of that growth: it is increasingly driven not by labour-cost arbitrage but by genuine technological capability, domestic demand, and what the ADB calls “intra-regional economic density.”
The AI Infrastructure Race
Nowhere is the super cycle more visible than in AI infrastructure. China’s hyperscaler companies — Alibaba Cloud, Huawei Cloud, Tencent, and ByteDance — committed collectively to well over $50 billion in data centre construction in 2025–2026, a response not only to domestic AI demand but to a deliberate strategic choice to build computational sovereignty. The irony for Jensen Huang was not lost on anyone in the room: Nvidia’s export-controlled chips are precisely what Chinese hyperscalers most want and cannot freely buy, and yet the market they are denied access to is building itself anyway, through a combination of Huawei’s Ascend processors, homegrown foundry capacity, and sheer engineering determination.
Meanwhile, across Southeast Asia, a parallel data centre boom is being funded by a mix of sovereign wealth capital — Singapore’s GIC and Temasek have been aggressively co-investing with regional developers — and the US hyperscalers themselves. Microsoft, Google, and Amazon Web Services have each announced multi-billion dollar regional expansions in 2025 and 2026 in Malaysia, Indonesia, and Thailand. This creates a fascinating paradox: American technology companies are simultaneously lobbying Washington for China market access while building out an alternative Asian technology ecosystem that could, over time, reduce the strategic significance of any single country’s approval.
Asia capex super cycle — selected commitments, 2025–2026
| Indicator | Figure | Trend |
|---|---|---|
| China tech fixed-asset investment growth (Q1 2026) | +15.4% YoY | ↑ |
| China hyperscaler data centre capex (2026 est.) | $50–60bn | ↑ |
| India PLI manufacturing commitments (since 2023) | $35bn+ | ↑ |
| ASEAN semiconductor capex (Malaysia, Vietnam, Thailand) | $28bn (2026) | ↑ |
| Intra-Asian FDI flows (2025) | $620bn | ↑ +18% |
| Asia-Pacific renewables investment (2026 est.) | $820bn | ↑ |
Has Asia Moved On? The Evidence of Diversification
The question embedded in the title of this piece deserves a careful answer — because it is easy to overstate the case. Asia has not moved on from the United States. American capital, technology, and consumer demand remain structurally significant to nearly every economy in the region. The bilateral trade relationship between the US and China alone, despite tariffs reaching 145% on certain goods categories by mid-2026, was still tracking at over $550 billion annually — an astonishing testament to how difficult it is to disentangle two economies that spent thirty years deliberately weaving themselves together.
But “moved on” is perhaps the wrong frame. What has happened is more like what a good portfolio manager does when one asset becomes volatile: you don’t sell it entirely, you reweight. Asia has been quietly, systematically reweighting away from US-dependent growth models and toward structures that are resilient to American policy volatility.
Consider the evidence at the trade level. WTO trade statistics show that intra-Asian trade — commerce between and among the economies of East Asia, Southeast Asia, and South Asia — has grown to represent approximately 58% of Asia’s total trade flows, up from roughly 50% a decade ago. RCEP, the Regional Comprehensive Economic Partnership that came into full effect in 2022, has quietly become one of the world’s most consequential free trade frameworks, lowering barriers across a bloc representing nearly a third of global GDP. Its institutional architecture is distinctly Asian, and conspicuously absent of American participation.
At the investment level, the picture is equally striking. The concept of “friendshoring” — originally a US policy idea about redirecting supply chains toward allies — has been enthusiastically adopted by Asian capital markets, but with a different roster of “friends.” JPMorgan’s regional research team documented in its 2026 outlook that intra-Asian foreign direct investment hit a record $620 billion in 2025, with Chinese, Singaporean, South Korean, and Japanese capital flowing into Indonesia, Vietnam, India, and the Philippines at unprecedented volumes. The US is a participant in this story, but it is no longer the protagonist.
The Geopolitical Premium on Self-Sufficiency
Perhaps the most enduring consequence of the 2018–2026 era of US–China trade conflict has been to confer enormous political legitimacy on self-sufficiency as an economic virtue. In China, the “dual circulation” strategy — prioritising domestic consumption and homegrown innovation as the primary growth engine, with international trade as a supplementary circuit — has moved from theoretical framework to practical imperative. The result is a Chinese economy that is genuinely less dependent on American final demand than it was a decade ago, even if the adjustment has not been painless.
In Southeast Asia, the effect has been subtler but real. Governments from Jakarta to Hanoi have become acutely aware of their own leverage in a world where both the United States and China are competing for supply-chain relationships. Vietnam, which simultaneously manufactures for Apple and maintains a carefully managed relationship with Beijing, has elevated the art of strategic ambiguity to a high form. Its economy grew 6.8% in 2025, and its trade surplus — achieved simultaneously with China, the United States, and the European Union — is a masterclass in not choosing sides.
“Vietnam has mastered what I’d call the double hedge: exporting to the US while importing from China while maintaining formal neutrality. It is, in the jargon of finance, a pure alpha play on geopolitical volatility.”
— Regional strategist, Singapore-based family office
Implications: For US Firms, Investors, and the Supply Chain
What does all this mean for the 17 chief executives who flew back from Beijing with their goodwill communiqués and their working-group assignments? Several things, not all of them comfortable.
First, the window of maximum US leverage in Asia may have already passed. The Trump administration’s tariff strategy was predicated, implicitly, on the idea that American market access was a prize valuable enough to extract substantial concessions. That premise was always debatable; it is now actively eroding. Chinese companies have spent four years finding alternative markets for their exports — in Southeast Asia, in the Middle East, in Africa — and they have had considerable success. The marginal value of American market access, while still significant, is declining.
Second, for companies like Nvidia, the export control regime has a structural irony embedded within it. By restricting access to the most advanced American chips, Washington has accelerated — rather than arrested — China’s domestic semiconductor ambitions. Semiconductor Industry Association data suggests Chinese companies are on track to achieve meaningful domestic capability in certain legacy and mid-range chip segments within three to five years. The market Huang wants to sell into today may look fundamentally different in 2030.
Third, for investors, the Asian super cycle presents genuine opportunities that are independent of US–China diplomatic weather. The energy transition investment wave across the region — solar, battery storage, green hydrogen, grid modernisation — is being driven by domestic policy mandates and falling technology costs that no tariff schedule can easily arrest. Morgan Stanley’s Asian equity strategists have been advocating overweight positions in regional utilities, industrial conglomerates, and technology infrastructure names precisely because their growth drivers are endogenous to Asian development, not contingent on Washington’s mood.
For supply chain managers, meanwhile, the lesson of this decade is uncomfortable simplicity: there is no clean alternative to Asia. Attempts to nearshore or reshore manufacturing to the United States have produced some success stories — semiconductor fabrication in Arizona, some pharmaceutical production in North Carolina — but the broader ambition of reducing Asian dependency has largely collided with the reality of skill concentrations, infrastructure depth, and supplier ecosystems that took thirty years to build and cannot be replicated in five. World Bank analysis of global value chain resilience consistently shows that diversification works best when it operates within Asia, spreading risk across multiple countries in the region, rather than attempting to relocate production back to high-cost Western markets.
The Longer Arc: Interdependence Persists, But the Terms Are Changing
It would be a mistake — a seductive, analytically convenient mistake — to conclude from all of this that the US and Asia are drifting into permanent estrangement. The sinews of economic connection are too numerous, too profitable, and too deeply embedded in the interests of too many powerful parties on both sides for anything as dramatic as genuine decoupling to occur in any foreseeable timeframe.
What is changing is the terms of interdependence. For most of the post-Cold War era, Asia’s integration with the global economy was mediated primarily through American institutional frameworks — the dollar, American capital markets, American technology platforms, American security guarantees. Each of these anchors is still present, but each is facing more competition than at any point since 1945. The renminbi’s share of global trade finance has been growing steadily. Asian capital markets — particularly Singapore, Hong Kong (complications notwithstanding), and increasingly Mumbai — are developing genuine depth. Huawei, BYD, and a cohort of Chinese technology companies have demonstrated that it is possible to build world-class products without American intellectual property at their core.
The delegation of CEOs that arrived in Beijing was, in a sense, a proxy for a larger question that American business is only beginning to fully internalise: in a world where Asia is no longer simply a manufacturer for the West but an increasingly self-contained economic ecosystem with its own capital, its own technology, and its own aspirations, what role does American corporate presence play? As a partner? A vendor? Or something awkwardly in between?
Asia GDP growth forecasts, 2026
| Economy | Forecast |
|---|---|
| Developing Asia (ADB aggregate) | +4.9% |
| India | +6.7% |
| Vietnam | +6.5% |
| Indonesia | +5.2% |
| ASEAN-6 average | +5.1% |
| China | +4.6% |
Forward Outlook
The Beijing summit will likely be remembered not for any single deal struck but for what it revealed about the current state of play: a United States still commanding enormous financial and technological leverage, but deploying it in a theatre where the audience has learned to produce its own entertainment. Asia’s capital expenditure super cycle is not a rebuke of American engagement — it is, in part, a product of it, born from decades of technology transfer, investment, and integration. But it is now mature enough to sustain itself on its own terms.
For investors, the implication is to stop treating “Asia” as a mirror of American risk appetite and start treating it as a source of endogenous growth with its own distinct cycle. For policymakers, the implication is more uncomfortable: leverage that is not exercised at the moment of maximum advantage tends to depreciate. And for the 17 CEOs on that motorcade — men who built their empires partly on the assumption of an infinitely expanding global market — the implication may be the most clarifying of all: the future of growth is in Asia, but Asia, increasingly, is deciding on whose terms.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Bank of England Warns of AI Systemic Risk: How Autonomous Trading Threatens Financial Stability

Bank of Japan Hikes Benchmark Rate to 1.25%: Unwinding the Global Yen Carry Trade

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors

Battle for the Farm Belt: How Tariff Pressures and Fuel Costs Are Reshaping Iowa’s 2026 Midterms

Southeast Asia’s Critical Minerals Power Play: Can ASEAN Avoid Choosing Between China and the US?

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN

Bank Jago’s Wealth Management Push:Indonesia’s 31.1 Million Investors boom

Beyond the Four-Year Degree: The $100K+ Trade Careers Young Americans Are Overlooking

SpaceX Starship Achieves First Full Orbit on Historic 10-Hour Test Flight 14

Google’s $15B Finland AI Investment: Data Centers, Nuclear Power & Jobs

Fast Invoice Factoring: Rates, APR Math & Contract Traps

SOC 2 Type II Guide: Cost, Timeline & Compliance Companies

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025