
Banks
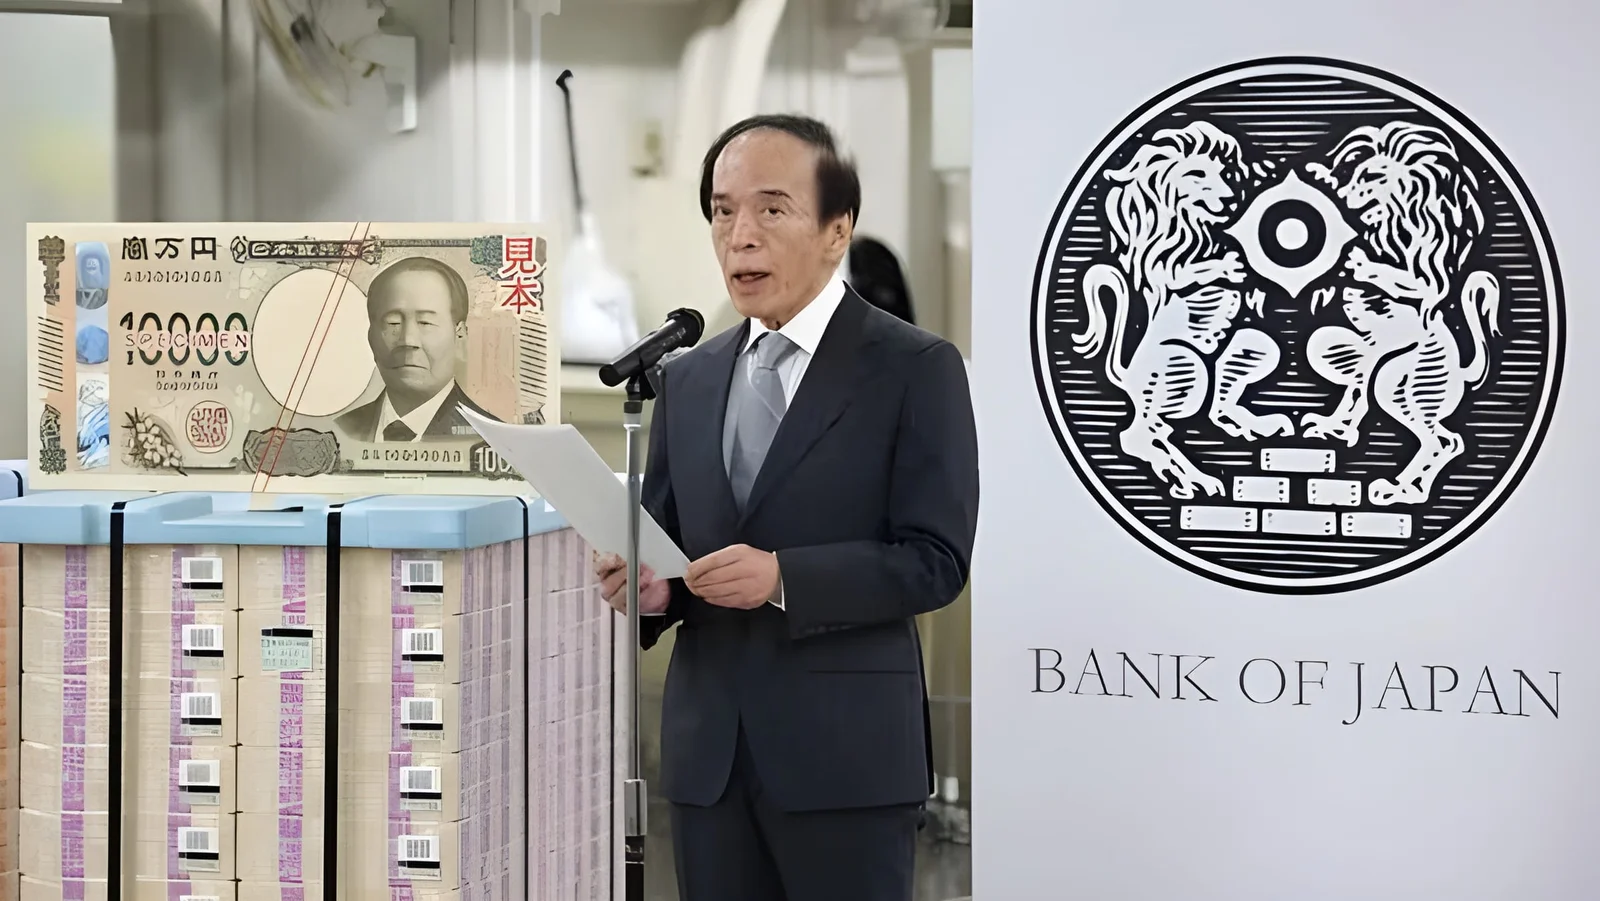
Bank of Japan Hikes Benchmark Rate to 1.25%: Unwinding the Global Yen Carry Trade

Key Takeaways
- Historic Policy Shift: The Bank of Japan (BOJ) raised its benchmark interest rate to 1.25%, moving decisively away from decades of near-zero and negative rate regimes.
- Yen Carry Trade Collapse: Institutional investors who borrowed cheap Yen to fund high-yielding global investments are forced to liquidate positions to cover escalating yen liabilities.
- Yen Appreciation: The Japanese Yen (JPY) strengthened sharply against the USD, forcing global macro funds to readjust cross-border leverage.
- Global Volatility: Emerging markets and high-growth US tech equities face short-term selloffs as cross-border foreign capital flows back into Japanese domestic assets.
The End of Cheap Money: Understanding the 1.25% Shift
For nearly three decades, Japan served as the world’s primary provider of low-cost capital. Under prolonged quantitative easing and negative interest rate policies (NIRP), global hedge funds, banks, and corporate treasuries routinely utilized the Yen Carry Trade—borrowing JPY at near-zero interest rates, converting it to USD or EUR, and investing in high-yielding assets like US Treasuries or mega-cap tech stocks.
As analyzed in economic insights from Deloitte, the BOJ’s decision to hike rates to 1.25% effectively dismantles this low-cost liquidity engine.$$\text{Carry Trade Profit} = \text{Foreign Asset Yield} – \text{Japanese Borrowing Rate} \pm \text{Currency Exchange Fluctuation}$$
With Japanese borrowing costs rising to 1.25% and the JPY rapidly appreciating, the net profit margin of these leveraged trades turns negative, triggering rapid automated unwinding.
                  Global Yen Carry Trade Unwinding Mechanics

  [Borrow Low-Cost JPY at 1.25%] ---> [Convert JPY to USD] ---> [Invest in US Tech / Bonds]
               |                                                         |
               v                                                         v
   [BOJ Rate Hike Spikes JPY] <--- [Sell Foreign Assets] <--- [Repay Appreciating JPY Debt]
Global Market Spillover: From Wall Street to Tokyo
The structural impact of the BOJ’s monetary tightening is felt far beyond Tokyo. As Japanese institutional investors—who hold trillions of dollars in foreign sovereign debt—find higher yields domestically, capital repatriates back to Japan.
Financial reporting from the Financial Times highlights that domestic Japanese institutional funds are reallocating back into 10-year Japanese Government Bonds (JGBs), reducing participation in US Treasury auctions.
Cross-Border Capital Realignment:
- US Equities Pressure: High-beta tech stocks that benefited from leveraged carry-trade inflows face liquidity contractions.
- Japanese Banking Sector Surge: Domestic Japanese financial institutions, including major retail banks, enjoy net interest margin expansions for the first time in a generation.
- Emerging Market Stress: Developing nations with high JPY-denominated debt debt services see immediate surges in sovereign repayment obligations.
Economic Metrics: Japan vs. Global Peer Comparison
Asia market tracking from Nikkei Asia illustrates how Japan’s monetary normalization compares with global peer central banks.
Central Bank Policy Matrix 2026
| Central Bank | Benchmark Rate | Policy Stance | 10-Year Sovereign Yield | Currency Trend vs USD |
| Bank of Japan (BOJ) | 1.25% | Hawkish / Tightening | 1.62% | Strong Appreciation |
| US Federal Reserve (Fed) | 3.75% – 4.00% | Hawkish / Restrictive | 5.24% | Range-Bound / Strong |
| European Central Bank (ECB) | 3.25% | Neutral / Holding | 2.85% | Moderate Depreciation |
| Bank of England (BoE) | 4.50% | Cautionary / Restrictive | 4.65% | Slight Depreciation |
Strategic Action Plan for Global Investors
To safeguard investment portfolios against the unwinding of cross-border carry trades, wealth managers recommend three immediate adjustments:
- Reduce Currency-Unhedged Foreign Exposure: Ensure global equity holdings maintain currency-hedging layers to prevent JPY appreciation from eroding capital returns.
- Capitalize on Japanese Financial Equities: Allocate capital toward major Japanese commercial banks and financial insurance firms benefiting directly from local rate expansion.
- Monitor Sovereign Yield Spreads: Track the spread between 10-year JGBs and US 10-year Treasuries; a narrowing spread signals accelerated capital flight back to Tokyo.
Frequently Asked Questions (FAQ)
What is the Yen carry trade and why does the BOJ rate hike destroy it?
The Yen carry trade involves borrowing money in Japan at very low interest rates and investing it in higher-yielding foreign assets (like US stocks or bonds). When the BOJ hikes interest rates to 1.25% and the Yen strengthens, borrowing becomes expensive and liquidations occur, unwinding the trade.
Why did the Bank of Japan raise rates to 1.25% after decades of near-zero rates?
The BOJ raised rates due to sustainable wage growth, persistent domestic inflation above its 2% target, and a desire to stabilize the Yen against severe currency devaluation, which was driving up domestic import costs.
How does the BOJ rate hike impact US stock market liquidity?
When the carry trade unwinds, global hedge funds are forced to sell US equities and other international assets to pay back their JPY-denominated loans. This sudden withdrawal of leverage creates downward price pressure on US stock exchanges.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


AI
Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power
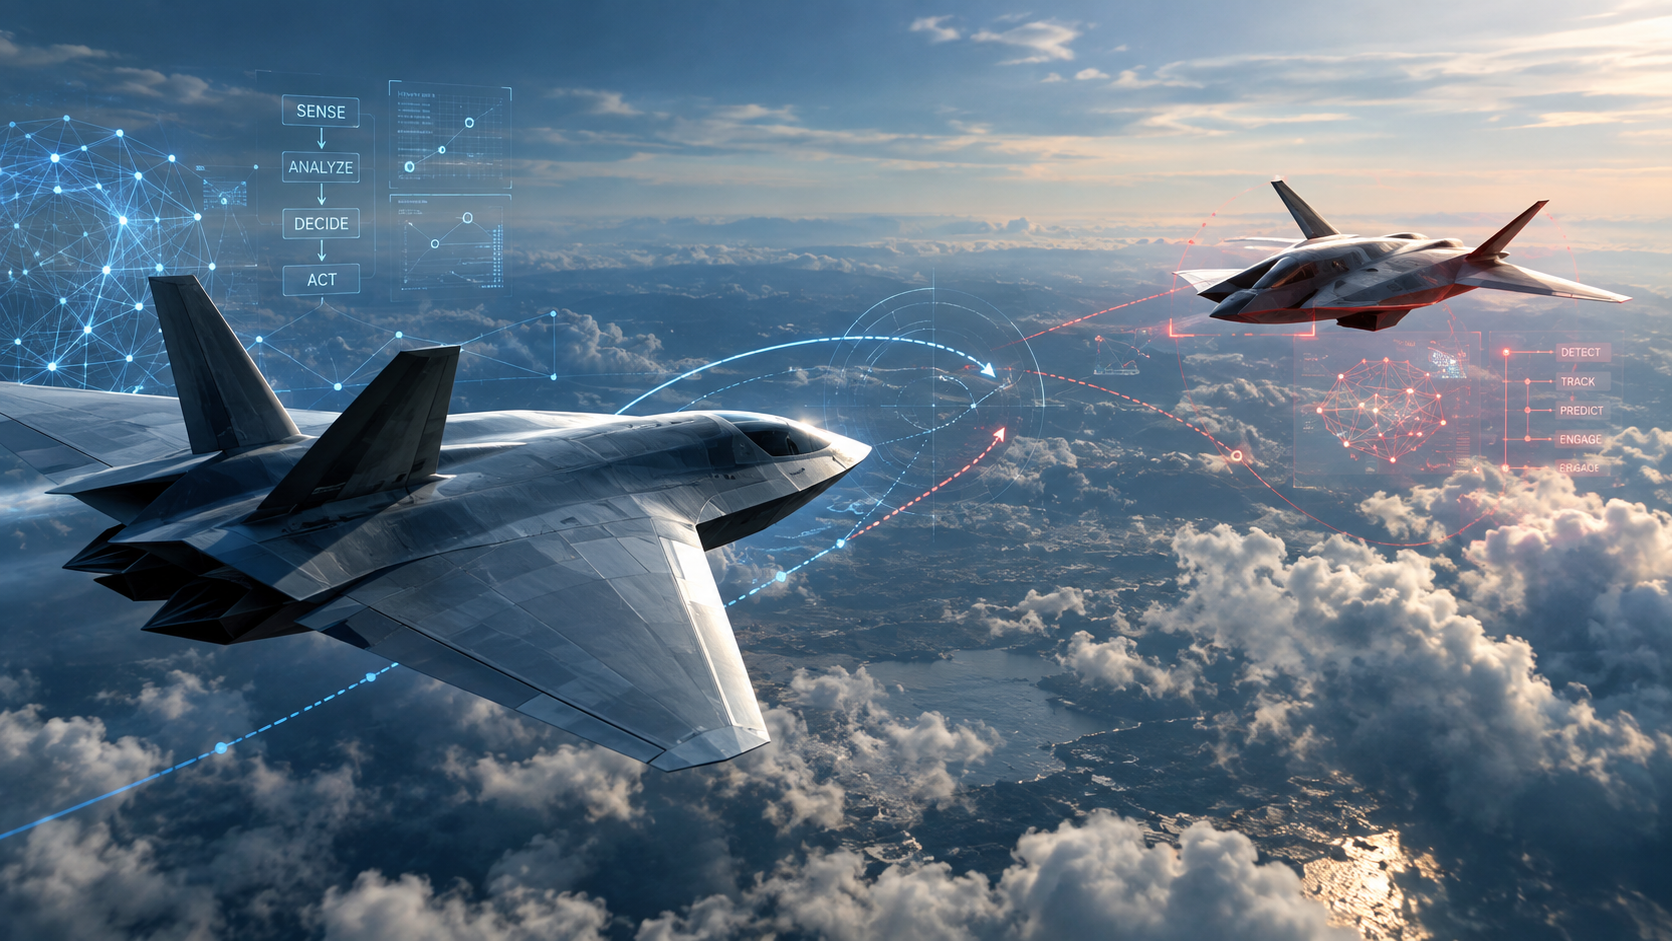
The military balance of power across the Indo-Pacific is undergoing a fundamental transformation. As both the United States and China transition artificial intelligence from simulator environments to front-line fighter jets, the primary threat of accidental military escalation in international airspace is shifting from human pilot miscalculation to machine learning error.
While much of the diplomatic discourse surrounding military AI focuses on nuclear command and strategic autonomy, the most immediate danger lies in tactical air intercepts over contested waters like the South China Sea and the Taiwan Strait. Without clear, bilateral rules of engagement (RoE) specifically tailored for autonomous aircraft, a routine encounter between uncrewed combat air vehicles (UCAVs) could trigger a rapid, unintended escalation ladder that human command structures cannot arrest in time.
The Dawn of Mach-Speed Autonomy
The race to field autonomous combat aircraft is no longer theoretical; it is an operational priority for both Washington and Beijing.
Under the U.S. Air Force’s Collaborative Combat Aircraft (CCA) initiative, the Pentagon plans to field at least 1,000 AI-enabled “loyal wingmen”—uncrewed aircraft designed to fly alongside crewed platforms like the F-35 and Next Generation Air Dominance (NGAD) fighters. Experiments conducted under the DARPA Air Combat Evolution (ACE) program have already demonstrated that AI agents can successfully outmaneuver human pilots in visual-range dogfights, adapting to tactical dynamic shifts at sub-second speeds. Details outlined by the U.S. Department of Defense emphasize the imperative of responsible autonomy, yet tactical real-time execution in contested zones remains a major wild card.
Concurrently, the People’s Liberation Army Air Force (PLAAF) is aggressively pursuing its own uncrewed platforms. Chinese defense contractors have showcased platforms such as the FH-97A and the WZ-8, designed to perform autonomous reconnaissance, electronic warfare, and forward-line air-to-air suppression. Research published by the RAND Corporation indicates that Beijing views military AI integration as a “force multiplier” capable of offsetting traditional U.S. power projection advantages in the First Island Chain.
The Escalation Trap: Why AI Changes Air-to-Air Tactics
In conventional intercept scenarios involving piloted aircraft—such as a Chinese J-16 intercepting a U.S. RC-135—human pilots operate under established visual signals, radio frequencies, and the multilateral Code for Unplanned Encounters at Sea (CUES). When a human pilot assesses intent, they rely on visual cues, physical distance, and tactical behavior to gauge aggression versus standard shadowing.
When two autonomous or semi-autonomous systems intercept one another, these human buffers disappear:
- Compression of the OODA Loop: Machine-learning algorithms operate on microsecond decision cycles. If an autonomous aircraft interprets a standard radar lock, electronic jamming pod, or evasive banking maneuver by an opposing drone as an incoming attack vector, its predictive neural networks may trigger defensive or pre-emptive maneuvers instantly.
- The “Black Box” Problem: Deep neural networks operate via complex pattern matching rather than deterministic logic trees. As noted in security studies by the Center for Strategic and International Studies (CSIS), predicting how an edge-deployed military AI model will respond to unpredictable real-world inputs (such as spoofed GPS or unexpected weather events) remains an unsolved challenge.
- Loss of Signaling Nuance: Human pilots can de-escalate a confrontation by rocking wings, pulling back on throttles, or establishing radio contact. Autonomous systems lack standard mechanisms to convey ambiguous or non-hostile intent to an opposing nation’s algorithmic system.
+-----------------------------------------------------------------------+
|                       THE ACCIDENTAL ESCALATION LOOP                 |
|                                                                       |
|   [U.S. Autonomous CCA]  <--- Sensor Query --->  [PLA Autonomous UCAV]|
|            |                                            |             |
|   Algorithm perceives                               Algorithm perceives|
|   evasive banking as hostile                         radar lock as     |
|   targeting signal                                  pre-emptive strike|
|            |                                            |             |
|            v                                            v             |
|   Automated Countermeasure                       Automated Deficit    |
|   Deployments (Chaff/Jamming)                    Tracking & Target    |
|            |                                     Acquisition          |
|            +-------------------+------------------------+             |
|                                |                                      |
|                                v                                      |
|             HUMAN COMMANDERS NOTIFIED POST-DISCHARGE                  |
|             (Escalation threshold crossed in <3 seconds)             |
+-----------------------------------------------------------------------+
The Existing Governance Vacuum
Multilateral efforts to regulate military AI have made modest progress, but they fall short of addressing tactical air intercepts.
The Responsible AI in the Military Domain (REAIM) summits and the U.S.-led Declaration on Responsible Military Use of Artificial Intelligence and Autonomy offer general principles regarding human oversight, command structure integrity, and rigorous testing. Similarly, diplomatic analysis published by the Brookings Institution highlights that high-level bilateral summits between Washington and Beijing have opened initial dialogues on AI risk reduction.
However, these broad political declarations lack operational mechanics. They do not define:
- What constitutes a hostile act by an autonomous platform in international airspace.
- What standardized electronic signals an uncrewed system must broadcast to declare peaceful transit.
- How machine-to-machine communications should function during an unintended proximity event.
Without concrete, technical protocols embedded directly into aircraft software suites, high-level political commitments will fail the moment silicon meets silicon over the Western Pacific.
A Four-Pillar Blueprint for U.S.-China AI Air Engagement
To mitigate the risk of an unintended confrontation, defense officials and technical experts from the United States and China must establish a dedicated Autonomous Air De-confliction Framework. Analysts writing in Foreign Affairs repeatedly note that arms control in the digital age requires technical solutions co-designed alongside strategic policy.
1. Hard-Coded Strategic Fail-Safes
Both nations should agree to hard-code deterministic “red lines” into autonomous flight control systems that cannot be overridden by machine-learning models. These include hard caps on maximum speed increases during close encounters, mandatory stand-off distances when intercepting uncrewed platforms, and automated weapon system lock-outs unless explicit human authority is transmitted.
2. Standardized Autonomous Identification Friend-or-Foe (A-IFF)
Similar to transponder systems used in commercial aviation, military uncrewed systems operating in international airspace should transmit a standardized, cryptographically signed “Autonomous Platform Intent” signal. This broadcast would inform nearby air units of the flight’s mission state, autonomous level (e.g., tethered to human lead vs. fully autonomous), and non-aggressive flight path vector.
3. Machine-to-Machine De-confliction Hotlines
Traditional voice-based communication links—such as the U.S.-China Defense Telephone Link—are too slow to manage algorithmic interactions. A modern de-confliction protocol requires an automated, low-latency data channel between U.S. Indo-Pacific Command and the PLA Eastern/Southern Theater Commands. This channel would automatically ping human operators the instant two opposing autonomous platforms enter a designated safety perimeter.
4. Joint Synthetic Simulation and Stress-Testing
Before deploying advanced autonomous fighters at scale, defense laboratories from both nations should participate in joint track-sharing and simulated scenario stress-tests. By running algorithmic models against each other in virtual environments, both sides can identify edge cases where neural networks misinterpret opponent maneuvers, allowing software engineers to patch systemic vulnerabilities before they manifest in real air combat.
The Imperative of Algorithmic Restraint
The integration of artificial intelligence into air warfare is an inevitable reality driven by strategic competition and technological momentum. However, autonomy without governance introduces an unacceptable level of operational risk.
If Washington and Beijing fail to establish clear rules of engagement for autonomous combat jets today, they risk allowing computer algorithms to dictate the timing and conditions of a major-power conflict tomorrow. Establishing guardrails for AI air power is not a sign of military weakness—it is a mandatory requirement for strategic stability in the 21st century.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Key Takeaways
- SAVE is over. A court order ended the plan in March 2026, and the Department of Education told 7.5 million enrolled borrowers to move into a legal repayment plan.
- The clock is running right now. Servicers began sending 90-day notices on July 1, and the first wave of deadlines landed in late September. Miss yours and you will be placed in a Standard or Tiered Standard plan, usually with higher payments.
- A new plan exists. The Repayment Assistance Plan (RAP) launched July 1, 2026, with payments set at 1% to 10% of adjusted gross income and a $10 monthly minimum.
- New loans cost more. Undergraduate Direct Loans first disbursed this school year carry a 6.52% fixed rate, up from 6.39% a year earlier.
- Consolidation is no longer a casual move. Under the settlement that ended SAVE, consolidating restarts the clock on income-driven forgiveness, though not on Public Service Loan Forgiveness.
If you have federal student loans, 2026 is the year the rulebook got rewritten while you were still holding the pen. Plans closed, new ones opened, and deadlines started arriving by email.
This guide cuts through the noise. You’ll see what changed, how the remaining plans compare, when consolidation helps and when it hurts, and which strategy tends to fit which kind of borrower. It reflects the situation as of October 6, 2026, so confirm details with your servicer and on StudentAid.gov before you act.
What Changed in 2026, in Plain English
Congress passed sweeping changes in the 2025 reconciliation law, and 2026 is when they landed. Three events matter most.
| Date | What happened | Why it matters |
|---|---|---|
| March 2026 | A federal court order ended the SAVE plan | Roughly 7.5 million borrowers lost their plan |
| March 27, 2026 | The Department of Education announced the SAVE exit process | Borrowers get at least 90 days to choose a new plan |
| July 1, 2026 | RAP and the Tiered Standard plan launched; new loan rules began | Every borrower with new loans faces a different menu |
Meanwhile, SAVE borrowers had been sitting in a forbearance limbo. That limbo is ending, one notice at a time.
The SAVE Deadline: What to Do If You Haven’t Moved
Your 90 days start on the date of your notice, not on a universal calendar day. Notices have been going out in waves, so deadlines are staggered. The earliest hit at the end of September, and the last may stretch into early 2027.
If you do nothing, you won’t be left without a plan. The Department says non-responders are automatically enrolled in either the Standard Repayment Plan or the new Tiered Standard Plan. The catch is that those plans are not income-based, so your payment can jump.
Your move list:
- Find your notice. Check your servicer’s messaging portal and your email, including spam.
- Confirm your own deadline. Don’t rely on a date you saw online.
- Run the numbers in the Loan Simulator on StudentAid.gov.
- Apply for your chosen plan before the clock runs out.
Your Repayment Menu After SAVE
| Plan | Who can use it | How payments work | Forgiveness |
|---|---|---|---|
| Repayment Assistance Plan (RAP) | Direct Loan borrowers (Parent PLUS loans excluded) | 1% to 10% of AGI, $10 minimum; unpaid interest is waived | After 30 years of payments |
| Income-Based Repayment (IBR) | Borrowers whose loans were all made before July 1, 2026 | Typically 10% or 15% of discretionary income, capped at the 10-year standard amount | 20 or 25 years, depending on when you first borrowed |
| Standard (10-year) | Existing borrowers | Fixed monthly payment | None, because the loan is repaid in full |
| Tiered Standard | Borrowers with loans disbursed on or after July 1, 2026 | Fixed payment that scales with balance | None |
| SAVE | Nobody | Ended | Ended |
A few details deserve attention.
- RAP is stricter on pauses. Economic-hardship deferment is eliminated for new loans, so unemployed borrowers still owe at least the $10 minimum, according to Saving for College.
- IBR remains the safety valve. It stays available for older loans, which makes it a serious option if RAP produces a bigger bill.
- Parent PLUS is a special case. The only income-driven route was consolidating before July 1, 2026, a window that has now closed.
Interest Rates: What New Borrowers Pay
Federal rates reset every July 1 and stay fixed for the life of the loan. For loans first disbursed between July 1, 2026 and June 30, 2027, the Department of Education’s rate announcement sets statutory ceilings of 8.25% for undergraduate loans, 9.50% for unsubsidized graduate loans and 10.50% for PLUS loans.
| Loan type (2026-27) | Fixed rate |
|---|---|
| Undergraduate Direct (subsidized and unsubsidized) | 6.52% |
| Graduate and professional unsubsidized | 8.07% |
| PLUS loans (for the borrowers still eligible) | 9.07% |
Two practical points. First, a 6.52% rate is far above the pandemic-era lows, so prepaying high-rate debt now carries real value. Second, borrowers who sign up for autopay may qualify for a temporary interest-rate reduction, which NerdWallet reports as 1%. Borrower advocates say the sign-up window runs through the end of 2026, so ask your servicer to confirm the terms.
Consolidation: Helpful Tool or Expensive Mistake?
A Direct Consolidation Loan combines federal loans into one, with a weighted-average rate. It can simplify billing and, in some cases, unlock eligibility for a plan. But in 2026 it carries a new sting.
The settlement trap. Under the settlement that ended SAVE, consolidating restarts your progress toward income-driven forgiveness. Public Service Loan Forgiveness is treated differently, according to Massachusetts’ student loan guidance, but a restart on the IDR clock can cost years.
The RAP-only rule. For loans disbursed or consolidated after July 1, 2026, RAP is the only income-driven option. If you currently qualify for IBR on older loans, a rushed consolidation could close that door.
Consolidate when:
- You have older FFEL loans that need to become Direct Loans to qualify for a program.
- Your many servicers and due dates are causing missed payments.
Think twice when:
- You are already making progress toward IDR forgiveness or PSLF.
- Your current plan has a lower payment than the one consolidation would unlock.
Forgiveness: What Is Still Available
- Public Service Loan Forgiveness (PSLF) remains available for borrowers who work full time for qualifying government or nonprofit employers and make the required qualifying payments. Only Direct Loans qualify.
- Income-driven forgiveness arrives after 20 to 25 years under IBR and 30 years under RAP.
- Taxes are back in the picture. The temporary federal tax exclusion for income-driven forgiveness expired at the end of 2025, so forgiven balances discharged in 2026 and later may count as taxable income at the federal level. Talk to a tax professional before you plan around a discharge date.
Strategy by Borrower Type
| If you are… | A sensible starting point | Watch out for |
|---|---|---|
| A public servant pursuing PSLF | Stay on a qualifying plan and document every year of employment | Consolidating without checking how it affects your count |
| Low income with a large balance | Compare RAP and IBR payments and long-term forgiveness | Higher taxes on forgiveness |
| Higher income with a modest balance | Standard plan, or paying extra toward the highest-rate loans | Giving up federal protections by refinancing privately |
| A Parent PLUS borrower | Review options carefully, since RAP is not available | The lack of an income-driven path |
| A SAVE borrower | Pick a plan before your individual deadline | Auto-placement into a payment that jumps |
New Loan Limits Worth Knowing
The same law changed how much new borrowers can take. Grad PLUS is closed to new borrowers, and annual and aggregate caps now apply to graduate, professional and Parent PLUS borrowing. If your plan depends on borrowing federal dollars for graduate school, check the current caps on StudentAid.gov and price out the gap before you commit.
Asked & Answered
What happens if I miss my SAVE deadline?
You’re moved automatically into the Standard Repayment Plan, or into the Tiered Standard Plan if you have loans disbursed on or after July 1, 2026. You can usually still apply for a different plan afterward, but you’ll be billed under the default until your application is processed.
Does consolidation reset student loan forgiveness?
For income-driven forgiveness, yes, under the SAVE settlement terms. Public Service Loan Forgiveness is handled differently. Check your qualifying-payment count before you consolidate.
Can I still get Public Service Loan Forgiveness in 2026?
Yes. PSLF remains available to eligible Direct Loan borrowers who work for qualifying employers and make the required payments.
Is RAP better than IBR?
It depends on your income, family size and loan type. RAP can produce a larger payment for some borrowers and a smaller one for others, and its forgiveness timeline is longer. Run both through the Loan Simulator.
Is student loan forgiveness taxable in 2026?
Possibly. The federal exclusion that covered income-driven forgiveness ended after 2025, so discharged balances may be taxable at the federal level. State rules vary, so get tax advice for your situation.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
US Treasury yields have climbed to multi-year highs, pushing corporate financing costs higher and creating a growing refinancing challenge for American companies. The immediate pressure is concentrated among weaker borrowers, but a prolonged high-rate environment could eventually affect investment, mergers, buybacks and economic growth across corporate America.
The US bond market has entered a more difficult phase for corporate borrowers.
A sharp rise in Treasury yields is increasingly feeding into the cost of corporate debt, forcing companies to reconsider when and how they borrow. The impact is most severe for highly leveraged and lower-rated businesses, but even investment-grade companies are facing a more expensive capital market than they enjoyed during the ultra-low-rate era of the early 2020s.
The issue is no longer simply whether the Federal Reserve raises or cuts short-term interest rates. The bigger question for corporate America is how long long-term borrowing costs remain elevated.
That distinction matters because companies refinancing debt today are replacing old financing obtained at substantially lower rates with new debt priced in a very different market.
The Treasury market is setting a tougher price for corporate debt
The starting point is the US government bond market.
The 10-year Treasury yield has climbed to levels not seen in more than two decades, increasing the baseline rate against which much of the corporate bond market is priced. Recent market reporting has put the 10-year yield above 5%, with investors demanding greater compensation for holding long-duration government debt.
The Federal Reserve has warned that higher interest rates can increase debt-servicing costs for businesses with substantial leverage and upcoming refinancing requirements. The central bank has also noted that the corporate sector entered 2026 with relatively strong investment-grade credit quality, meaning the current environment should not automatically be interpreted as an economy-wide credit crisis.
That distinction is crucial.
The problem is increasingly concentrated in companies that have some combination of high leverage, weak cash flow, floating-rate liabilities or large amounts of debt coming due.
Federal Reserve financial-stability analysis supports the view that corporate credit vulnerabilities remain uneven rather than universal.
Why refinancing is becoming the central risk
Many companies borrowed heavily when interest rates were exceptionally low.
As those bonds mature, companies must either repay the debt from existing cash, refinance it at prevailing rates, sell assets, raise equity or reduce spending.
The refinancing arithmetic can be painful.
Suppose a company borrowed $10 billion at an average interest rate of 3%. Its annual interest bill would be approximately $300 million.
If that debt has to be refinanced at 6%, the annual interest expense rises to approximately $600 million.
The company has not borrowed another dollar, yet its annual financing burden has doubled.
That is why refinancing can become a hidden earnings shock.
Reuters estimates that approximately $4.3 trillion of US non-financial corporate bonds will mature between 2027 and 2031. Annual maturities are expected to rise from roughly $572 billion in 2027 to approximately $1.03 trillion in 2030.
This creates what investors increasingly describe as a corporate refinancing wall.
The weakest companies are feeling the pressure first
The deterioration is not evenly distributed.
Companies with investment-grade balance sheets can generally access capital markets more easily and often have diversified sources of funding.
Highly leveraged companies have fewer options.
According to the Financial Times, borrowing costs for companies rated CCC or lower have risen to approximately 17%, while their risk premium has reached about 12 percentage points.
That level of financing can fundamentally change corporate decision-making.
A project that looked profitable when money cost 5% may no longer make economic sense when financing costs move substantially higher.
This can lead companies to postpone:
- acquisitions;
- share buybacks;
- expansion projects;
- capital expenditure;
- hiring;
- new factories;
- technology investments;
- refinancing transactions.
The consequences can therefore spread beyond bond investors into the real economy.
Corporate America is not facing one uniform debt crisis
One of the most important nuances missing from many discussions about higher borrowing costs is that corporate America is highly divided.
At one end are highly profitable technology companies and other large investment-grade borrowers with enormous cash flows and strong access to capital markets.
At the other are highly leveraged companies whose earnings leave relatively little room to absorb a major increase in interest expense.
The Federal Reserve’s 2026 Financial Stability Report found that investment-grade corporate credit quality remained robust, although some riskier firms, particularly those dependent on private credit, were experiencing greater debt-servicing challenges.
That suggests the current environment is better described as a credit-selection problem than a generalized corporate solvency crisis.
The longer yields remain elevated, however, the greater the probability that today’s refinancing pressure becomes tomorrow’s default problem.
The corporate bond market is already sending signals
Market pricing provides an important window into this transition.
FRED data show Moody’s seasoned Baa corporate bond yield at approximately 6.73% on October 1, 2026. The Baa spread over the 10-year Treasury was about 1.49 percentage points at the beginning of October.
This distinction is important.
Corporate borrowing costs consist broadly of two components:
Treasury yield + corporate credit spread = corporate borrowing yield
The Treasury component compensates investors for the time value of money and government interest-rate risk.
The credit spread compensates investors for taking corporate credit risk.
When both rise simultaneously, companies experience a much more powerful increase in financing costs.
So far, much of the pressure has come from the Treasury side, although credit spreads for weaker borrowers have also widened substantially.
Paramount’s enormous financing illustrates the new reality
The Paramount Skydance transaction provides a particularly useful case study.
Paramount disclosed plans for tens of billions of dollars of debt financing connected with its acquisition of Warner Bros. Discovery. Its SEC filings show that the transaction involved substantial debt commitments, including a large bridge financing facility that was expected to be replaced or reduced through permanent financing.
The transaction demonstrates a broader challenge facing corporate finance teams.
When financing costs are uncertain, companies increasingly have to think about:
How much should we borrow?
For how long?
At what fixed rate?
How much floating-rate exposure should we accept?
Should we refinance now or wait?
Can the acquisition generate enough additional cash flow to justify the higher financing expense?
Those questions become especially important for highly leveraged mergers and acquisitions.
Why companies are shortening maturities
One logical response to high long-term interest rates is to avoid locking in today’s expensive financing for decades.
Companies may therefore prefer shorter maturities.
The strategy has an obvious advantage: if rates fall later, the company can refinance at a lower cost.
But it also creates another risk.
Shorter maturities mean more refinancing requirements in the future.
If interest rates remain high, companies could find themselves repeatedly refinancing debt at elevated rates.
That creates a difficult trade-off between paying more today for long-term certainty and accepting refinancing risk in exchange for shorter-term flexibility.
AI is creating an important exception
One of the most interesting features of the current credit market is the enormous borrowing associated with artificial intelligence infrastructure.
Technology companies are spending unprecedented amounts on data centres, chips, networking infrastructure and electricity capacity.
The Financial Times has reported estimates that hyperscalers could borrow around $1 trillion through 2030 to support AI infrastructure expansion.
For these companies, the calculation is different.
If management believes that failing to invest in AI infrastructure would result in losing a strategic position, higher financing costs may be treated as the price of maintaining competitive advantage.
This creates a strange two-speed corporate credit market.
AI-related investment can remain aggressive while other companies cut capital spending.
That divergence could become one of the defining characteristics of the next phase of the US corporate bond market.
The refinancing wall could become an earnings problem
The most important transmission mechanism is straightforward:
Higher Treasury yields → higher corporate borrowing costs → higher interest expense → lower free cash flow → reduced investment or weaker credit quality.
For companies with strong margins, the increase may be manageable.
For companies operating with thin margins, it can be decisive.
Consider a company generating $1 billion in annual operating cash flow and paying $300 million in interest.
If refinancing raises annual interest expense to $500 million, the company’s interest burden consumes a much larger share of its cash flow.
Management then has fewer resources available for investment, acquisitions, dividends and buybacks.
If revenues simultaneously weaken, the problem becomes more serious.
Could this trigger a wave of corporate defaults?
Not necessarily.
The Federal Reserve’s earlier 2026 assessment showed that corporate bond issuance remained strong and investment-grade credit quality was generally solid.
That provides an important cushion.
Large corporations have also had years to prepare for higher rates by extending maturities and locking in fixed-rate financing.
But the risk is asymmetric.
A stable economy can allow heavily indebted companies to refinance successfully.
A combination of high interest rates, slowing economic growth and falling corporate profits would be much more dangerous.
That is when refinancing pressure can turn into covenant breaches, distressed exchanges, restructurings and defaults.
The Federal Reserve has explicitly warned that higher rates can amplify vulnerabilities associated with leverage and upcoming refinancing needs.
What investors should watch next
Investors should focus on five indicators rather than Treasury yields alone.
1. The 10-year Treasury yield
A sustained move above current levels would increase the baseline cost of corporate financing.
2. High-yield credit spreads
A sharp widening would indicate that investors are demanding substantially greater compensation for corporate credit risk.
3. Corporate refinancing volumes
If companies begin delaying bond issuance, it could signal that borrowers consider market pricing too expensive.
4. Interest coverage ratios
Companies with declining earnings and rising interest expense are particularly vulnerable.
5. Default and distressed-debt indicators
A sustained increase in defaults would suggest that the refinancing problem is becoming a solvency problem.
The bigger issue is the cost of capital
The most important consequence of the bond sell-off may not be a sudden wave of bankruptcies.
It may be a gradual repricing of corporate decision-making.
For more than a decade, exceptionally low interest rates encouraged companies to borrow cheaply, refinance frequently, acquire competitors and return capital to shareholders.
That model becomes less attractive when the cost of capital rises substantially.
The result could be a more disciplined corporate environment in which companies demand higher returns from acquisitions and capital projects.
That may ultimately be healthy.
But the transition could be painful for companies that built their business models around cheap debt.
A new test for corporate America
The US economy has already demonstrated considerable resilience in the face of higher rates.
The question now is whether that resilience extends to a corporate sector facing a large refinancing cycle.
The numbers suggest that the pressure will build gradually rather than arrive as a single shock.
The immediate danger is concentrated among highly leveraged and lower-rated companies. Investment-grade borrowers remain considerably better positioned.
But the refinancing calendar means the issue cannot simply be dismissed.
With roughly $4.3 trillion of non-financial corporate bonds coming due between 2027 and 2031, the cost of money over the next several years will matter enormously.
If Treasury yields eventually decline, many companies could refinance more comfortably.
If yields remain elevated while earnings weaken, the pressure could move steadily up the credit spectrum.
That makes the current bond-market sell-off more than a story about government debt.
It is becoming a test of how much corporate America can adapt to a world in which capital is no longer cheap.
Bottom line
The US corporate sector is not yet facing a systemic debt crisis. The stronger borrowers retain substantial market access, while investment-grade credit quality remains relatively resilient.
But the refinancing cycle is creating a growing divide between companies that can absorb higher interest costs and those that cannot.
The crucial variable is therefore not simply whether the Federal Reserve raises or lowers its policy rate.
It is whether long-term borrowing costs remain high long enough for the refinancing wall to become an earnings and solvency problem.
For investors, the next phase of the credit cycle will be about separating companies that can grow their cash flows faster than their financing costs from those whose balance sheets were built for the era of cheap money.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025