
Analysis
Tarique Rahman’s Plan to Revive Bangladesh’s Economy: Challenges and Opportunities in 2026

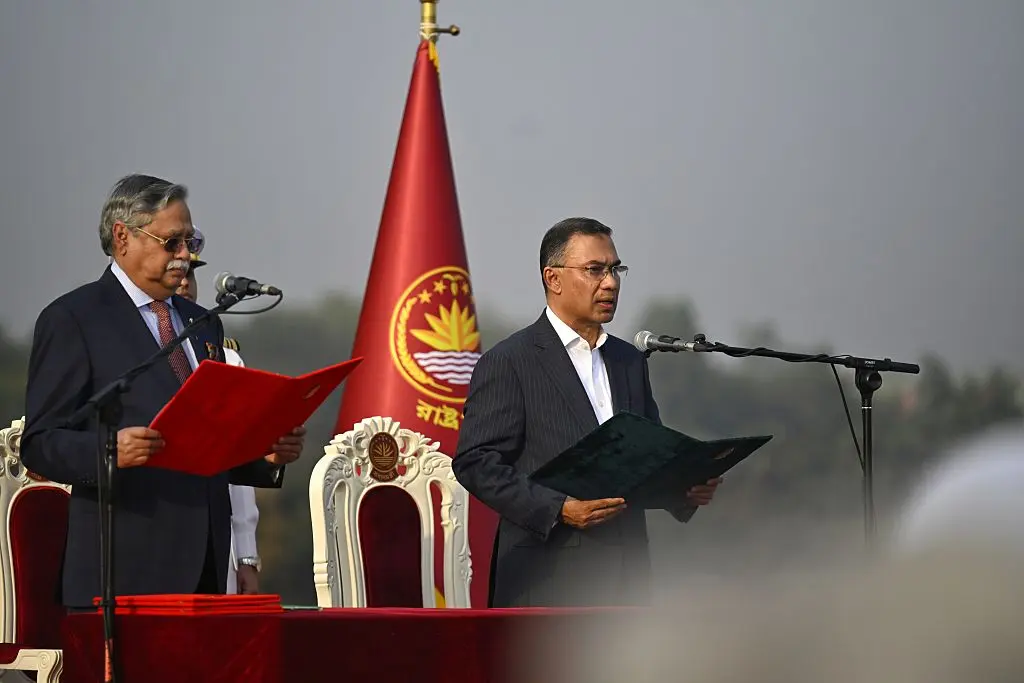
Explore how Bangladesh’s new PM Tarique Rahman aims to boost GDP growth, manage remittances, and navigate China-US relations amid post-election revival.
When Tarique Rahman finally set foot on Bangladeshi soil after nearly two decades in London exile, the crowds that greeted him weren’t merely celebrating a political homecoming. They were, in a very real sense, betting their livelihoods on him. The BNP’s sweeping two-thirds majority in February 2026 — an election made possible only by the extraordinary student-led uprising that drove Sheikh Hasina from power in 2024 — handed Rahman a mandate that is simultaneously historic and terrifying in its weight. Bangladesh’s GDP stands at roughly $460 billion, growth has decelerated to a sluggish 4%, and a geopolitical tightrope stretches in every direction. The question isn’t whether Rahman wants to revive Bangladesh’s economy. The question is whether the tools he has are equal to the task.
The Economic Inheritance: More Fragile Than It Looks
Bangladesh’s macro story has long been one of development economics’ favorite fairy tales — a low-income country that outpaced neighbors through garment exports, microfinance, and disciplined remittance flows. That story has grown considerably more complicated.
The IMF projects GDP growth to rebound to 4.7% in FY2026, a modest recovery from the post-Hasina political turbulence that rattled investor confidence in late 2024 and through 2025. But 4.7% is not the 6–7% Bangladesh needs to absorb its vast young workforce, reduce poverty meaningfully, or finance the public investment that decades of cronyism left underfunded. The structural gaps are significant: private investment hovers well below the 35% of GDP economists identify as necessary for sustained high growth. Public institutions — tax administration, the judiciary, anti-corruption bodies — carry the scars of 15 years of systematic politicization.
Agriculture still employs roughly 44% of the workforce, a share that underscores both the rural depth of economic vulnerability and the limits of an export-led model that has concentrated prosperity in Dhaka and Chittagong. When a cyclone hits the Sundarbans or global cotton prices spike, nearly half the country feels it in their bones.
Then there’s the remittance lifeline. Bangladeshis abroad sent home $30 billion in 2025 — a remarkable surge driven partly by the depreciation of the taka making dollar transfers more attractive, and partly by the expanded diaspora built up across the Gulf, Malaysia, and Europe. Remittances now rival garment export earnings as the backbone of foreign exchange reserves. That’s a double-edged asset: invaluable as a buffer, but structurally fragile because it depends on labor-market conditions in Riyadh and Dubai, not Dhaka.
The Garment Sector: A Crown Jewel Under Pressure
Bangladesh’s readymade garment industry — a $40+ billion export engine that dresses much of the Western world — faces its most complex moment in a generation. The challenges are formidable: automation threatens lower-skill sewing jobs, Western buyers are demanding ESG compliance that many Bangladeshi factories can’t yet afford, and competitors from Vietnam and Ethiopia are chipping away at market share.
US tariff policy adds another layer of uncertainty. Bangladesh’s garment exports to America — its single largest market — flow under preferences that have never been fully secure and are now subject to the broader unpredictability of Washington’s trade posture. Rahman’s government has signaled it will pursue a formal trade framework with the US, a pragmatic move that would reduce vulnerability but requires diplomatic capital Bangladesh is only beginning to rebuild.
The harder domestic challenge is labor. The 2024 revolution was partly ignited by garment workers and students united by economic grievance. Any BNP government that ignores wage stagnation in the sector risks repeating the political miscalculations that ultimately doomed Hasina. Rahman has spoken of a “social compact” with workers — the test will be whether that translates into enforceable minimum wages and functional unions, or remains campaign rhetoric.
Navigating the Great Power Triangle: China, the US, and India
China: Partner, Creditor, or Competitor?
Bangladesh’s trade relationship with China is the defining economic relationship most Western analysts underestimate. Bilateral trade runs at approximately $18 billion, overwhelmingly weighted toward Chinese exports — machinery, raw materials, electronics — that Bangladesh’s industry desperately needs but can’t yet produce domestically. Chinese firms have also financed key infrastructure, from the Padma Bridge rail link to power plants, creating debt obligations that constrain fiscal flexibility.
Rahman’s stated approach is “multipolar pragmatism” — maintaining strong economic ties with Beijing while signaling openness to Washington and Tokyo. It’s a reasonable strategy, and it reflects a broader trend across Southeast and South Asia. But it requires a diplomatic dexterity that Bangladesh’s foreign ministry has not traditionally needed to exercise. The risk is that both great powers interpret hedging as hostility rather than prudence.
The India Question: Thaw or Freeze?
Relations with India are the most emotionally charged variable in Rahman’s foreign policy inbox. New Delhi was perceived as Hasina’s patron — a relationship Bangladeshi nationalists resented and the BNP stoked for electoral advantage. Border tensions have flared since the revolution, with incidents along the fencing that runs most of the 4,000-kilometer frontier. The Teesta water-sharing agreement, long in diplomatic limbo, remains unsigned.
And yet the economics of India-Bangladesh interdependence are powerful enough to compel engagement regardless of political temperature. Indian goods flood Bangladeshi markets via both formal and informal channels. Bangladesh’s northeast-facing connectivity — ports, power grids, transit routes — cannot be optimized without Indian cooperation. A sustained chill with Delhi would cost Rahman more than it costs Modi. The smart money is on a gradual, face-saving thaw: enough symbolism to satisfy nationalist sentiment at home, enough pragmatism to keep the border economy functioning.
ASEAN: The Aspiration That Requires Homework
Bangladesh’s ASEAN aspirations have been discussed for years with more enthusiasm than strategy. Joining ASEAN — even as a dialogue partner — would require institutional reforms, trade liberalization, and a regional diplomatic posture that Dhaka has not historically prioritized. Rahman’s team has floated ASEAN engagement as part of a broader Indo-Pacific pivot. It’s an appealing vision. Translating it into policy requires, first, getting the basics right at home.
The Political Economy of Reform: Who’s Really in the Room?
Any honest assessment of Bangladesh’s economic outlook has to grapple with the coalition Rahman is governing within. The BNP’s two-thirds majority is a powerful instrument — but it came partly on the back of Jamaat-e-Islami’s organizational muscle in constituencies where the BNP had been weakened during the Hasina years. Jamaat’s social conservatism and ambiguous attitude toward Bangladesh’s secular liberal elite creates real tension with the reform agenda that investors and multilaterals are expecting.
Youth are the other critical constituency. The students who brought down Hasina want jobs — real ones, not patronage positions — transparency, and an end to the culture of political violence that has made Bangladeshi politics so costly to its own institutions. Rahman’s government has promised a crackdown on corruption and civil service reform. These are not merely good governance talking points; they are the precondition for private investment to grow toward that 35% of GDP target. Foreign capital follows institutional credibility, and Bangladesh’s institutional credibility is currently being rebuilt from a low base.
The Awami League, despite its electoral collapse, commands deep roots in parts of the bureaucracy, the military officer class, and civil society. A wise BNP government manages this not through purges — which historically backfire — but through transparent accountability processes that don’t look like victors’ justice.
LDC Graduation: The November 2026 Cliff
Looming over everything is Bangladesh’s scheduled graduation from Least Developed Country status in November 2026. This is, in development terms, a success story — Bangladesh has met the income, human assets, and economic vulnerability thresholds for graduation. But success brings a cost: the erosion of preferential trade terms that have underpinned garment export competitiveness for decades.
Duty-free access to the EU under the Everything But Arms initiative will phase out. WTO-TRIPS flexibilities on pharmaceuticals will tighten. The IMF and World Bank have urged Bangladesh to negotiate transition arrangements and diversify its export base before the preferences expire. Rahman’s government has approximately two years of post-graduation transition runway — time that must be used to move up the value chain, attract technology-intensive investment, and build the trade infrastructure that makes Bangladeshi exports competitive on merit rather than preference.
This is where the $460 billion economy’s future is genuinely being written. Not in political speeches, but in whether Chittagong port gets the upgrades it needs, whether the power grid can reliably supply the industrial zones, and whether the education system starts producing graduates with skills the 21st-century economy demands rather than the 20th.
Opportunities and Pitfalls: A Forward Look
Where the optimists have a point:
- The remittance surge provides a genuine foreign exchange cushion that buys reform time.
- Bangladesh’s demographic dividend — a young, urbanizing population — is a real asset if youth employment programs gain traction.
- The global supply chain diversification away from China creates an opening for Bangladesh in electronics and light manufacturing if the enabling environment improves.
- The BNP’s large majority, paradoxically, gives Rahman room to absorb short-term political pain from reform — a luxury narrow coalition governments rarely have.
Where the pessimists may be right:
- Jamaat-e-Islami’s influence in the coalition could slow liberal economic reforms and deter Western investors with ESG mandates.
- India-Bangladesh tensions, if they deepen, could disrupt the connectivity projects that unlock northeastern Bangladesh’s economic potential.
- LDC graduation without adequate preparation could trigger a garment sector shock that reverberates across the 4 million workers — mostly women — who depend on it.
- Institutional rebuilding takes longer than election cycles. The IMF’s 4.7% projection is predicated on policy continuity and reform progress that is far from guaranteed.
The Bottom Line
Tarique Rahman inherits a Bangladesh that is more resilient than its critics acknowledge and more fragile than its boosters admit. The $460 billion economy has real foundations — a hardworking diaspora, an adaptable garment sector, a tradition of pragmatic policymaking that survived even the Hasina years’ worst excesses. But those foundations need serious maintenance: institutional reform, investment in human capital, and a foreign policy sophisticated enough to manage great power competition without becoming a casualty of it.
The students who made this government possible are watching with the same energy they brought to the streets in 2024. They are not an audience to be managed with press releases. They are Bangladesh’s most important economic asset — and its most demanding constituency. Getting the economy right, for Rahman, is not just a technocratic challenge. It’s the condition of his political survival, and the measure by which history will judge whether the 2024 revolution delivered on its promise.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

Concert Ticket Prices in 2026: Dynamic Pricing, Fees and How to Buy Safely

High-Yield Savings Accounts in 2026: How to Compare APY Without Chasing a Headline

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Russia Diesel Deal 2026: Oil Prices and Inflation Risks

Fed Rates 2026: Treasury Yields, Bonds and SGOV Explained

S&P 500 Market Breadth 2026: Weak Rally or Rotation?

The AI Capex Boom: Data Centers Reshaping Growth

Palantir Stock in 2026: Extraordinary AI Growth

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025