
Wealth Management
Gulf Sovereign Wealth Funds Hit Record $53.9B in H1 2026 Despite Iran War

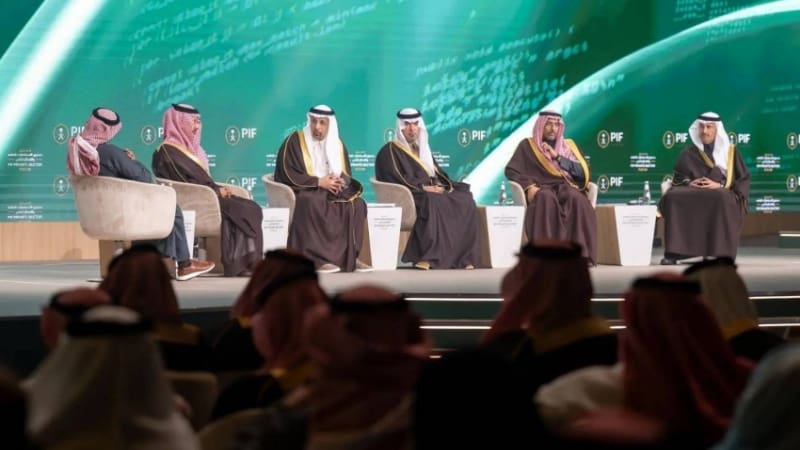
There’s a version of this story that writes itself: a shooting war breaks out between Israel, the US and Iran, oil markets seize up, the Strait of Hormuz effectively shuts for weeks, and the region’s biggest financial institutions pull back to lick their wounds. That is not what happened. Instead, Gulf sovereign wealth funds just booked their most active first half on record, and the numbers are hard to square with the headlines they were competing against.
According to data compiled by Global SWF, the region’s state-owned investors committed $53.9 billion across 108 deals between January and June 2026 — an all-time high for any six-month stretch. That’s not a modest uptick. It’s a record set in the middle of the very conflict that was supposed to freeze capital markets across the Gulf.
Where the money actually went
Roughly half of that capital crossed the Atlantic, landing in the United States. Semafor’s reporting points to a specific pattern: big-ticket funding rounds for AI companies including Anthropic and xAI (before its merger with SpaceX) absorbed a meaningful share of that flow. China came in second at 17% of allocations, with the UK rounding out the top three destinations, per Arab News.
Abu Dhabi’s Mubadala led the pack among individual institutions, deploying $15.2 billion at group level in six months — enough to make it the world’s single most active sovereign investor over that period, according to Khaleej Times. Add in Abu Dhabi Investment Authority and the newer L’Imad Holding, and the emirate alone accounted for roughly half of all Gulf-linked sovereign deals in the period.
Why the war didn’t stop the money
The obvious question is why a regional war made these funds move faster rather than slower. Part of the answer is structural: Gulf sovereign capital has spent the past decade positioning itself as a bridge between oil revenue and long-duration global assets — tech, infrastructure, credit — precisely because oil revenue itself is volatile. When crude prices spike, as they did when the Strait of Hormuz crisis unfolded, these funds simply have more petrodollars to recycle, and they’re recycling them into exactly the sectors that boomed regardless of the war: artificial intelligence infrastructure, private credit and strategic real assets.
There’s also a security dimension that Arab News flags directly: the conflict sharpened Gulf governments’ focus on resilience — supply chains, defense-adjacent technology, counterdrone systems — and sovereign capital increasingly follows that same strategic logic, not just commercial return.
Globally, the picture is even bigger. Total state-owned investor activity worldwide hit $143.6 billion across 366 transactions in the first half, with Canada’s so-called Maple 8 pension funds and Singapore’s twin funds, GIC and Temasek, also posting unusually strong numbers. Gulf funds were involved in 21 of the 42 global “mega-deals” over $1 billion — meaning nearly half of the largest transactions on the planet this year had Gulf fingerprints on them.
The bigger picture for the region
None of this means the war was costless. Global SWF’s own commentary, cited by The National, acknowledges that the conflict and the resulting oil-price volatility “affected the industry dearly” over the period — just not enough to derail the deal pipeline. The relative weight of Middle Eastern funds within the global total actually fell, from 48% in the second half of 2025 to 38% in the first half of 2026, simply because everyone else — Canada, Singapore, public pension funds broadly — was also deploying capital at a record pace.
For anyone tracking capital flows out of the Gulf, the takeaway isn’t that geopolitical risk stopped mattering. It’s that these funds have built enough scale and enough diversification that a war in their own backyard no longer functions as an automatic brake. If this pace holds through year-end, 2026 could turn into the most prolific year on record for sovereign and pension capital combined — a statement that would have sounded implausible in March, when tankers were turning back from Hormuz and oil was pushing past $100 a barrel.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Markets & Finance
The Falkland Islands Dispute: Sovereign Wealth, Offshore Drilling, and Market Impacts
A sovereignty dispute that has simmered largely unresolved since the 1982 Falklands War has erupted into its sharpest confrontation in decades this September, driven not by military posturing but by offshore oil drilling economics. Argentine President Javier Milei announced sweeping new sanctions on September 3, 2026, targeting companies, directors, shareholders, and suppliers involved in the Sea Lion oil project near the Falkland Islands (Islas Malvinas) — escalating dramatically after U.S. President Trump publicly stated Washington’s decades-long neutral stance on the islands’ sovereignty was “under review.” With first oil from Sea Lion targeted for 2028 and Navitas Petroleum and Rockhopper Exploration having already taken final investment decisions in December 2025, this dispute has moved from historical grievance to live geopolitical risk assessment territory for any investor with exposure to South Atlantic energy or shipping.
Key Takeaways
- Argentina announced new sanctions on September 3, 2026 against foreign firms, directors, and suppliers connected to offshore oil and gas extraction near the Falklands without Argentine authorization — with penalties potentially extending to companies’ ability to operate or sign contracts within Argentina itself.
- The escalation was directly triggered by President Trump’s September 2026 comment that the U.S. position on Falklands sovereignty was “under review” — a break from decades of formal U.S. neutrality on the issue.
- Sea Lion, operated by U.K.-based Rockhopper Exploration and Israel’s Navitas Petroleum, took final investment decisions in December 2025, with first oil currently planned for 2028, located roughly 136 miles north of the Falklands on the Argentine continental shelf.
- A lawsuit filed September 1, 2026 by Argentine environmental groups and Falklands War veterans seeks a federal court injunction to halt the Sea Lion development entirely, citing both environmental and sovereignty concerns.
- Milei has simultaneously pledged increased military spending for a new naval base in Tierra del Fuego and telecommunications upgrades in the South Atlantic — even while pursuing an otherwise aggressive austerity program — signaling the dispute’s rising domestic political salience in Argentina.
From Historical Grievance to Live Resource Conflict
The Falkland Islands sovereignty dispute has a well-documented, largely static legal history: Argentina bases its claim on inheritance from Spain, geographic proximity, and its 19th-century position on the islands, while the United Kingdom relies on continuous administration since 1833 and the principle that the roughly 3,000 Falkland Islanders should determine their own political future. The 1982 war ended with restored British administration but never resolved the underlying sovereignty question — and UN General Assembly Resolutions from 1965 and 1976 explicitly declined to determine territorial title, endorse either state’s claim, or establish any binding resolution mechanism.
What has fundamentally changed in 2026 is the economic stakes. As one legal analysis put it: petroleum activity around the islands has brought “a long-running sovereignty dispute into direct conflict with the planned extraction of a finite offshore resource” — converting an abstract historical argument into an immediate, quantifiable commercial conflict.
| Sea Lion Project Milestone | Date/Status |
|---|---|
| Final investment decision (Navitas Petroleum, Rockhopper) | December 2025 |
| Planned first oil | 2028 |
| Location | ~136 miles north of Falklands, on Argentine continental shelf |
| Argentine legal challenge filed | September 1, 2026 |
| Argentine sanctions announced | September 3, 2026 |
| UK government response | September 4, 2026 (reaffirmed sovereignty position) |
The Trump Factor: A Genuine Break From Decades of U.S. Neutrality
The single most consequential development in this dispute’s 2026 escalation is not Argentine domestic politics — it’s President Trump’s public statement that the U.S. position on Falklands sovereignty was “under review.” For a dispute where Washington has maintained formal neutrality for over four decades (even during the 1982 war, when the U.S. ultimately provided intelligence and material support to Britain while officially neutral), any signal of reconsidering that posture carries outsized diplomatic weight. Milei explicitly credited Trump’s comments as the catalyst for his own escalation, using the moment to reassert Argentina’s claim publicly and frame the dispute in explicitly nationalist terms: “The Falkland Islands are Argentinian, historically and legally.”
Argentina’s Sanctions Mechanism: How Far Does It Reach?
Milei’s September 3 measures are notable for their extraterritorial ambition. Rather than simply barring Argentine entities from involvement, the proposed sanctions target:
- Companies directly involved in offshore extraction without Argentine approval
- Directors and executives of those companies personally
- Suppliers providing goods or services to the projects
- Shareholders with financial stakes in involved companies
- Potential exclusion from operating or signing contracts within Argentina for any tied entity
Argentina’s government has already begun actively enforcing this scrutiny — Bloomberg reported on September 7 that Milei’s press office circulated statements from major oilfield service firms Halliburton, SLB, and Baker Hughes explicitly confirming they have no involvement in Falklands-area oil activities, an unusual public disclosure pattern suggesting real commercial pressure is already being applied to the broader oilfield services industry, not just the direct project operators.
Legal Challenge: Domestic Litigation Adds a Second Front
Beyond executive-branch sanctions, the dispute now has a parallel domestic legal track. On September 1, 2026, Falklands War veterans and environmental lawyers filed suit in Argentine federal court, seeking an injunction to halt the Sea Lion development on both environmental (marine ecosystem protection) and sovereignty grounds. This dual-track approach — executive sanctions plus judicial injunction — gives Argentina multiple simultaneous pressure points against the project, even though Argentine courts have no jurisdiction to actually halt British-licensed extraction occurring under Falkland Islands Government authority.
The Local Investment Angle: Elsztain’s Complicated Position
An underappreciated wrinkle in the dispute involves Argentine businessman Eduardo Elsztain, CEO of real estate firm IRSA, who has previously sought to acquire a majority interest in the Falkland Islands Company (though British authorities declined to allow an Argentine investor to take control). Elsztain has publicly defended continued economic engagement with the islands, invoking his grandfather’s view that deeper Argentine economic involvement throughout the 20th century might have prevented the 1982 war entirely — a notably dissenting voice within Argentina’s business community against Milei’s confrontational approach, illustrating that Argentine opinion on strategy (if not on the underlying sovereignty claim) is not monolithic.
What This Means for Sovereign Wealth Funds and Geopolitical Risk Assessment
For sovereign wealth funds and institutional investors managing exposure to South Atlantic energy assets, shipping routes, or UK/Argentine sovereign risk, several structural factors are worth tracking as part of ongoing geopolitical risk assessment frameworks:
| Risk Factor | Assessment |
|---|---|
| Direct expropriation risk to Sea Lion | Low — project operates under UK/Falklands jurisdiction, outside direct Argentine legal reach |
| Reputational/compliance risk to project suppliers | Rising — Argentina’s sanctions threaten to extend to any entity with commercial ties, creating real due-diligence burden |
| Broader UK-Argentina bilateral relationship risk | Elevated — diplomatic relations likely to cool further regardless of project outcome |
| U.S. policy shift risk | Genuinely uncertain — Trump’s comments represent the first real crack in 40+ years of formal neutrality |
| Regional diplomatic alignment risk | Moderate — Latin American nations have historically backed Argentina’s sovereignty claim at forums like the Rio Group, and could do so again |
Broadly, 2026 sovereign wealth fund research (from IFSWF’s Annual Review and related industry analysis) confirms that funds are increasingly applying multidisciplinary risk assessment frameworks that explicitly weight geopolitics, alongside ESG, climate, and technology, when evaluating portfolio company and direct investment risk — the Falklands dispute is a clean, contained case study of exactly this kind of geopolitically-entangled resource risk that such frameworks are now designed to catch.
A Practical Framework for Investors and Corporate Risk Teams
- Distinguish legal jurisdiction from commercial pressure risk. Argentina cannot legally halt Sea Lion, but its sanctions regime can meaningfully complicate supplier relationships, financing, and insurance for any company with Argentine commercial exposure elsewhere.
- Monitor U.S. policy statements closely as the primary escalation variable. Trump’s “under review” comment is the single development most likely to shape whether this dispute remains a contained bilateral irritant or escalates toward a genuine diplomatic crisis.
- Watch for supplier/oilfield-services company disclosure patterns. The Halliburton/SLB/Baker Hughes public disclaimers suggest a template other companies with any Argentina exposure may need to follow proactively.
- Track the domestic Argentine legal case as a secondary signal. While unlikely to succeed in halting the UK-licensed project, its outcome will be a useful gauge of how much domestic legal and political pressure Milei can sustain around the issue.
- Factor regional diplomatic alignment into broader Latin America risk models. Historical precedent (Rio Group, UNASUR) shows Latin American nations readily back Argentina’s sovereignty claim at multilateral forums, which could complicate unrelated UK commercial interests across the region if the dispute escalates further.
FAQ
Why has the Falklands dispute escalated so sharply in September 2026?
The immediate trigger was President Trump’s public comment that the U.S. position on Falklands sovereignty was “under review” — breaking decades of formal U.S. neutrality — which Argentine President Milei used as justification to announce sweeping new sanctions against companies involved in offshore oil extraction near the islands.
Can Argentina legally stop the Sea Lion oil project?
No — Sea Lion operates under UK and Falkland Islands Government jurisdiction, outside direct Argentine legal authority. Argentina’s sanctions instead target the commercial relationships of involved companies, their directors, shareholders, and suppliers, creating compliance and reputational pressure rather than direct legal authority to halt the project.
When is Sea Lion expected to begin producing oil?
First oil from the Sea Lion project, operated by Rockhopper Exploration and Navitas Petroleum, is currently planned for 2028, following a final investment decision taken in December 2025.
What is the biggest risk this dispute poses to companies with unrelated Argentina exposure? Argentina’s proposed sanctions could extend to barring any company connected to Falklands oil extraction — including their suppliers and shareholders — from operating or signing contracts within Argentina, creating due-diligence and compliance risk well beyond the direct project participants.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Wealth Management
UK Wealth Tax Fears Trigger Record £13.9bn Investor Exodus Ahead of October Budget
There is no bank queue, no dramatic headline photo — just a steady, monthly bleed of capital out of UK equity funds that has now become the worst sustained withdrawal pattern investment platforms have recorded in years. According to fund-flow data from Calastone, UK investors pulled £1.6 billion out of stock market funds in July alone, making it the weakest month for UK equity fund flows since late 2025. Zoom out further and the picture sharpens: withdrawals over the trailing twelve months have reached a record £13.9 billion.
This is not a market-timing story. It is a policy-anticipation story, and it is unfolding in the run-up to one of the most closely watched fiscal events of Prime Minister Andy Burnham’s government: Chancellor John Healey’s first Budget, scheduled for October 28, 2026.
What Investors Are Actually Afraid Of
A Boring Money survey cited in UK business coverage found that capital gains tax is the single biggest concern among investors, cited by 76% of respondents, followed by fears of a possible wealth tax at 64%, land and stamp duty reform at 51%, and inheritance tax changes at 50%. Strikingly, only 7% of investors surveyed believe the Burnham government’s policies will improve their personal financial position, while half expect an outright negative effect.
This sentiment is not occurring in a vacuum. It follows a period in which prior changes to inheritance-tax treatment of pensions already unsettled long-term savers, and it comes as speculation mounts — fueled in part by public commentary from figures including US President Donald Trump, who has separately described the UK’s fiscal position in blunt terms — about the scale of revenue-raising measures Healey may need to close the country’s fiscal gap.
The Broader Economic Backdrop
The capital-flight story is unfolding against a genuinely mixed UK economic picture. On one hand, the Services PMI has returned to expansion territory at 52.1, with the Composite PMI reaching 52.2, and construction’s downturn has eased. On the other, UK job postings fell 11% during the first half of 2026 and remain roughly 32% below pre-pandemic levels, according to Indeed data — with private-sector employment now in its 22nd consecutive month of decline, according to PMI figures.
Housing tells a similarly split story. Britain’s largest residential developers issued eight profit warnings in the first half of 2026 — matching the number recorded at the start of the 2008 financial crisis — with Vistry among the worst affected as its first-half home sales fell 11% to roughly 6,100 units. That makes the government’s pledge to deliver 1.5 million new homes before the 2029 general election an increasingly difficult target, with knock-on effects for the SME contractors and material suppliers that depend on housebuilding activity.
One notable bright spot: small-business growth expectations tell a bleaker story than the headline PMI figures suggest. Novuna Business Finance research found business growth confidence in England has dropped to just 24% — the lowest reading in the survey’s 12-year history, with construction, retail, and hospitality recording the sharpest declines. Only the North West bucked the trend, with growth expectations rising modestly.
Where the Money Is Going
For SEO content strategists and wealth advisors serving cross-border clients, the practical question is not whether UK capital is leaving equity funds — the data already answers that — but where it is relocating. Historical patterns during periods of UK wealth-tax anxiety point toward two primary destinations that recur consistently in advisor conversations: Dubai’s zero personal income tax regime under DIFC structuring, and Singapore’s combination of political stability, low capital gains exposure, and its role as a base for family offices serving Asian and Gulf wealth simultaneously. Both jurisdictions have spent 2025 and 2026 actively courting exactly this demographic through streamlined golden-visa and family-office licensing regimes.
What to Watch Before October 28
Three signals will matter most between now and Budget day:
- Whether Calastone’s monthly outflow figures accelerate or stabilize in August and September — a stabilization would suggest markets have already priced in the worst-case Budget scenario; continued acceleration would suggest investors expect measures more severe than currently rumored.
- Any pre-Budget signaling from Chancellor Healey or Number 10 about the scope of capital gains, wealth, or inheritance tax changes — governments frequently use August recess speeches and September party conference season to test-float measures.
- Bank of England commentary on energy price volatility, given BOE Deputy Governor Pill’s warning that energy price volatility is likely to persist into 2027, a factor that will constrain the Chancellor’s room to maneuver on the spending side of the Budget.
The Bottom Line
Britain is experiencing a slow-motion, policy-anticipation capital exodus rather than a market crash — but the effect on long-term investment, housebuilding, and small-business confidence is proving just as corrosive. With Chancellor Healey’s October 28 Budget now the single most consequential date on the UK fiscal calendar, the £13.9 billion already gone may be only the opening chapter.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Analysis
Dubai’s Millionaire Magnet: How the UAE Turned Middle East Turmoil Into a Capital Safe-Haven Boom
Introduction
While much of the commentary on the 2026 Middle East conflict has focused on oil tankers and the Strait of Hormuz, a quieter and arguably more consequential story has been unfolding in Dubai and Abu Dhabi: capital is flowing in, not out. The UAE attracted roughly 9,800 net new millionaires in 2025 — the highest net millionaire inflow of any country globally, according to Henley & Partners — and 2026 data suggests the pattern is holding even as regional tensions have periodically spiked (Tap Fiscal). For a global content audience trying to understand why a country geographically adjacent to an active conflict zone is functioning as a safe haven rather than a risk zone, the answer lies in three decades of deliberate institutional design.
The Headline Numbers
Dubai’s economy grew 2.4% in the first quarter of 2026 alone, with GDP reaching AED 232 billion, according to figures reported via the official WAM news agency (Gateway Group UAE Weekly Business News). The UAE Central Bank’s own outlook projects national economic growth of 5.6% for 2026, outpacing the broader GCC average, with the hydrocarbon sector expected to grow 7.3% on higher oil production even as non-oil sectors — financial services, manufacturing, trade, tourism and transport — continue to carry the bulk of long-term momentum (Xinhua). Non-oil activity now accounts for roughly 75% of GDP, a diversification level that insulates the economy from oil-price shocks far more than headlines about the region typically convey (Tap Fiscal).
Why S&P and the Central Bank Both Say the UAE Can Absorb the Shock
A dedicated S&P Global Ratings assessment concluded the UAE’s banking sector has shown strong resilience and financial soundness through the recent period of regional volatility, and the agency expects solid loan growth to continue into 2027, supported by ample system liquidity amid expected monetary easing (Gulf News). S&P separately reaffirmed the UAE’s sovereign credit rating at AA/A-1+ with a stable outlook, citing strong fiscal buffers and one of the world’s largest sovereign wealth portfolios (Xinhua).
The scale of that buffer is difficult to overstate. S&P estimates the UAE’s consolidated net asset position will reach roughly 184% of GDP in 2026, with government liquid assets calculated at approximately 210% of GDP (Gulf News). That firepower sits across a small number of globally diversified institutions — the Abu Dhabi Investment Authority, Mubadala Investment Company, ADQ, the Investment Corporation of Dubai, and the Emirates Investment Authority — which generate income well beyond the oil sector and give the state fiscal flexibility that few conflict-adjacent economies possess (Gulf News).
The UAE Central Bank’s own Q1 2026 review points to the same conclusion from the market side: the Dubai Financial Market’s share price index rose 22.9% year-on-year in the fourth quarter of 2025, the Abu Dhabi Securities Market General Index gained 6.6%, and credit default swap spreads for both Abu Dhabi and Dubai narrowed further — a signal of sustained investor confidence rather than flight (Central Bank of the UAE Quarterly Economic Review).
The Short-Term Noise Was Real — But It Didn’t Stick
None of this means the conflict has been costless. In the early days of escalation, some expatriates left the UAE, private jet charter prices to exit Dubai briefly spiked to as much as $250,000, and hotel occupancy dipped alongside disrupted aviation routes (Tap Fiscal). But the institutional and long-term investor data tell a different story than the panic-driven headlines: the Dubai International Financial Centre has resumed normal operations and remains home to nearly 9,000 active firms spanning wealth management, banking and capital markets (Tap Fiscal). A UAE government minister framed the resilience explicitly, describing the economy as structurally sound and built over decades to adapt to crisis rather than be destabilized by it (Tap Fiscal).
What’s Driving the Millionaire Inflow Specifically
High-net-worth migration to the UAE is not a new phenomenon, but 2025’s record net inflow suggests the safe-haven thesis is strengthening rather than fading. The pattern is consistent with what analysts describe as a flight to stable, low-tax jurisdictions with strong rule of law during periods of global uncertainty (Tap Fiscal) — a category the UAE has spent two decades positioning itself to fit, through free zones, golden visa programs, and a deliberately diversified, sovereign-wealth-anchored economy that does not rise or fall with a single sector or a single regional headline.
Risks Worth Watching
- Banking system exposure to regional escalation: while S&P’s baseline case is resilience, further escalation involving direct disruption to Gulf shipping lanes or energy infrastructure would test the “limited and short-term” impact assumption analysts currently hold (Xinhua).
- Real estate cooling: separate reporting on new vehicle and property registrations suggests parts of the UAE’s consumer economy are cooling from exceptional prior-year growth rates, even if not contracting (Arabian Business).
- Global AI valuation correction spillover: as with other major financial centers, UAE sovereign funds carry meaningful exposure to global equity markets, including AI-related names that regulators elsewhere have flagged as a concentration risk.
Key Takeaways
- The UAE recorded the world’s highest net millionaire inflow in 2025 and Dubai’s economy grew 2.4% in Q1 2026 despite regional conflict.
- Sovereign wealth institutions (ADIA, Mubadala, ADQ, ICD) give the UAE a net asset position near 184% of GDP, its core buffer against geopolitical shocks.
- S&P has reaffirmed a stable AA/A-1+ sovereign rating, citing fiscal buffers and banking sector resilience.
- Early-conflict disruption (jet charter spikes, occupancy dips) proved short-lived; DIFC activity and equity indices have both strengthened.
- Non-oil GDP diversification, now at roughly 75%, is the structural reason the UAE decouples from pure oil-price and conflict-headline risk.
Sources: S&P/Gulf News UAE Resilience Analysis, Xinhua/UAE Central Bank, Tap Fiscal UAE Economic Outlook 2026, Central Bank of the UAE Quarterly Economic Review, March 2026, Gateway Group UAE Weekly Business News, Arabian Business
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The Global South: Debt, Climate Finance and Investment in 2026

Energy Security Is the New Economic Security

Can Global Tourism Survive Geopolitical Shocks?

Global Maritime Hegemony: How China Secured Over 81% of All New Shipbuilding Orders

The Coming Battle Over AI, Jobs and Wages

Why Developing Economies Face a Sharper Inflation Problem

The New Geography of Trade: Are Supply Chains Coming Home?

Is AI Saving Global Growth or Creating the Next Bubble?

Global Banking Trends 2026: Digital Banks, AI and Compliance

Gold vs US Dollar vs Bitcoin in 2026: Inflation Hedge Compared

How Global Interest Rates Affect Savings, Loans and Investments

How to Invest During High Inflation: A Global Guide

Best Global Stocks to Watch in 2026: Four Sectors to Research

Pakistan’s 2027 Growth Strategy: Exports, AI, Energy and Jobs

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

World’s Largest Economies: Ranking the Top Global Powers

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025