
Policy
US Section 301 Tariffs 2026: 60 Countries Face 12.5% Duties on Forced Labour Goods

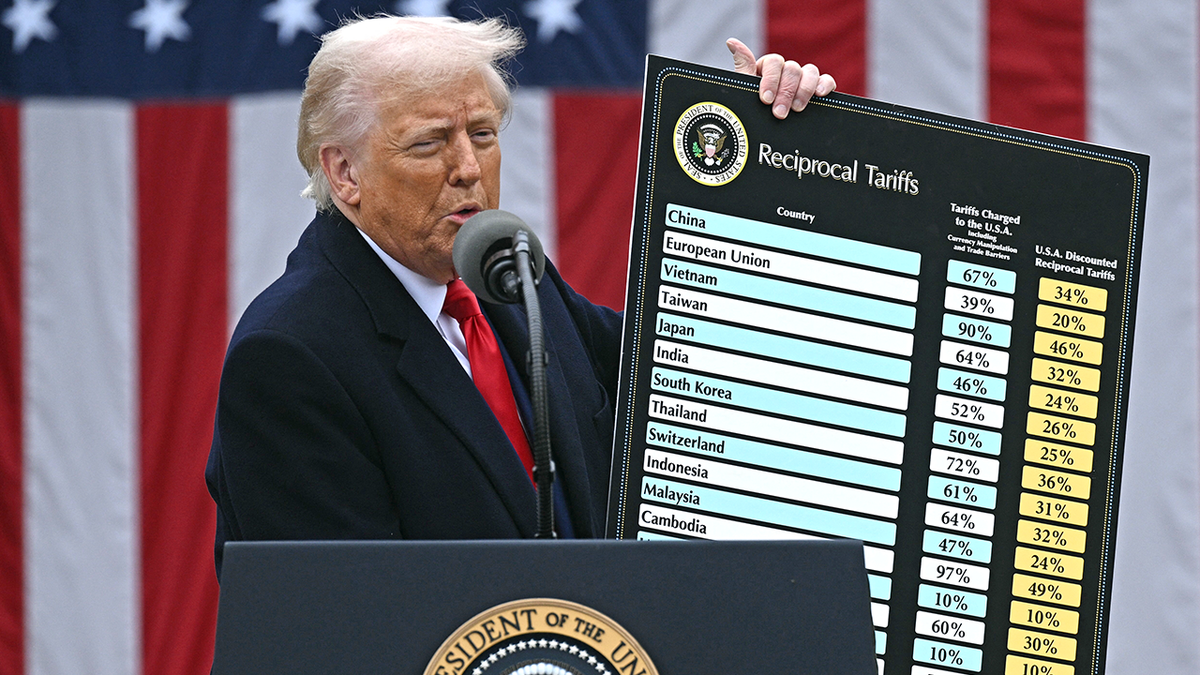
Having lost its most powerful tariff tool in the Supreme Court, the Trump administration has found a new one — and it comes with a moral argument attached.
On June 2, 2026, the Office of the United States Trade Representative concluded 60 simultaneous Section 301 investigations, finding that each of the targeted economies had failed to impose or effectively enforce a prohibition on the importation of goods produced with forced labour. The proposed remedy: additional tariffs of 10% to 12.5% on all imports from those economies, covering 99.4% of total US imports by origin. The scope is unprecedented. It sweeps in China, the European Union, Japan, India, Vietnam, Australia, South Korea, and 52 other trading partners in a single action.
The Legal Architecture Post-Supreme Court
The context matters. In February 2026, the US Supreme Court struck down most of President Trump’s “Liberation Day” emergency tariffs, ruling that they exceeded the executive’s authority under the International Emergency Economic Powers Act (IEEPA). That decision dismantled the headline tariff architecture the administration had built over 2025. Rather than abandon the strategy, the Trump administration pivoted to legal frameworks with stronger statutory grounding. Section 301 of the Trade Act of 1974 authorises the president to impose levies to counter foreign trade practices that are “unreasonable or discriminatory and burden or restrict U.S. commerce” — a standard that the USTR has now applied to forced labour enforcement failures.
The investigations were formally initiated on March 12, 2026, with public hearings drawing testimony from nearly 60 witnesses and 500 written comments over April and May. The USTR’s findings drew a direct causal link between inadequate forced labour enforcement and competitive harm to US companies and workers.
The Rate Architecture
The proposed tariff structure creates two tiers. Economies that have adopted full or partial forced labour import prohibitions — notably Canada, Mexico, and a handful of others — would face 10% additional duties. The remaining 45 economies, including China, India, Japan, Vietnam, Australia, and New Zealand, would face 12.5% additional duties. A separate textile mechanism would allow a capped volume of apparel and textile imports from certain economies at a reduced rate. Electronics and AI-related products are widely expected to carry significant exemptions, according to the Economist Intelligence Unit.
The public comment period closes July 6, 2026, with hearings beginning July 7. The duties are not yet in effect — but for companies sourcing from any of the 60 targeted economies, the window to map exposure and file comments is rapidly closing.
Trading Partners Push Back
Responses from affected governments were swift and uniformly dismissive of the USTR’s reasoning. Beijing‘s commerce ministry spokesperson stated flatly that “there is no so-called forced labor in China,” and that Washington and Beijing should “meet each other halfway.” China’s foreign ministry called the accusations politically motivated.
The European Union is in a particularly complex position. Brussels signed a broad bilateral trade agreement with Washington in 2025, which the European Parliament ratified. The proposed new tariffs — which the EU called “unjustified” — would come on top of the existing 15% tariff framework from that deal. The USTR’s own report acknowledged that the EU’s anti-forced-labour regulation only entered into force in December 2027 and lacks certain enforcement elements — giving the administration its statutory foothold. The chair of the European Parliament’s trade committee described the determination as “utterly absurd” given the 2024 EU forced labour import ban law.
France‘s government questioned whether the investigation reflected genuine concerns, with officials suggesting a tariff measure was “sought first, and only then is a suitable legal justification found.”
The Supply Chain Reality for Multinationals
For global supply chain managers, the practical implications are immediate regardless of the final duty levels. The Clark Hill law firm’s trade practice advised clients to map exposure against the 60 targeted economies by HTS code, model the 10% and 12.5% rate scenarios, and test exclusion eligibility before assuming coverage — noting that even partial exposure in electronics supply chains could run to billions in added costs at scale.
Nick Marro of the Economist Intelligence Unit told CNBC that he expects the Trump administration to “unleash further investigations and tariff announcements in preparation for renewed rounds of trade talks,” characterising the Section 301 action as part of a broader pattern of building leverage ahead of bilateral negotiations. The July 24 expiration of the separate 10% baseline tariff imposed under Section 122 adds another inflection point to the calendar.
For the global trading system, the implication is clear: the US high-tariff era is not over; it has simply found a new statutory vehicle.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Mortgage
How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors
The September 24 Trump-Xi summit produced a two-month trade-truce extension rather than a durable deal — and that ambiguity, not a headline breakthrough, is what’s now keeping the 10-year Treasury yield elevated and mortgage rates parked near 7% heading into the fourth quarter.
Mortgage Rates Today: The Q4 2026 Baseline
Freddie Mac’s benchmark survey put the 30-year fixed-rate mortgage at 6.95% for the week of September 17, 2026 — the fourth consecutive weekly increase and the highest reading since January 2025. The 15-year fixed climbed in tandem to 6.26%. A year earlier, the 30-year average sat more than half a point lower, near 6.26%.
| Loan Type | Rate (week of Sept. 17, 2026) | Rate (1 year prior) |
|---|---|---|
| 30-year fixed | 6.95% | 6.26% |
| 15-year fixed | 6.26% | 5.41% |
| 5/1 ARM | ~6.8%–7.0% | — |
| 30-year VA | ~6.2%–6.3% | — |
Source: Freddie Mac Primary Mortgage Market Survey; Zillow daily rate tracker.
The proximate driver is the bond market, not the housing market. Mortgage pricing tracks the 10-year Treasury yield, and that yield has been climbing toward the high-4% range through September on a combination of heavy government issuance and a Federal Reserve that has signaled it is in no hurry to cut. Layer geopolitical risk on top — oil above $90 a barrel amid Middle East disruption, plus unresolved US-China friction — and lenders are pricing in a wider risk premium.
Why the Summit Matters to Your Rate Lock
Real estate investors tend to treat foreign policy as background noise. That’s a mistake in Q4 2026. The Trump-Xi relationship is now the single largest swing factor in how bond markets price forward risk, because it touches three things that feed directly into Treasury yields: tariff policy, rare-earth and technology export controls, and the credibility of the disinflation narrative the Fed needs to justify future rate cuts.
What Actually Happened at the September 24 Summit
Xi Jinping’s September 24 visit to the White House was the second Trump-Xi meeting of 2026, following a May 14–15 state visit to Beijing where the two sides agreed to pursue what they termed a “constructive, strategically stable relationship.” The Washington leg was shorter on ceremony and shorter on breakthroughs. According to Reuters’ pool reporting, Treasury Secretary Scott Bessent confirmed the two sides extended their trade truce — originally due to lapse in November — by roughly two months, buying time rather than locking in a structural agreement.
That is the detail markets are trading on. An extension without resolution leaves tariff rates, Chinese purchasing commitments, rare-earth export licenses, and technology restrictions all still in play heading into the new year. For bond investors, unresolved trade risk is inflationary risk: tariffs raise input costs, and rare-earth bottlenecks squeeze manufacturers that feed into consumer prices. Both push against the case for near-term Fed easing, and Fed policy is the single biggest lever on where mortgage rates land.
Three Summit Threads With Direct Rate Impact
- The 60-day trade truce clock. With the new deadline now sometime in early 2026’s first quarter, expect renewed rate volatility as that date approaches — mortgage desks should treat any lock decision inside that window as elevated-risk.
- AI and export-control friction. Both sides used the September summit to air disagreements over AI development and chip/technology export controls, an area CSIS analysts have flagged as the least-resolved dimension of the relationship. Unresolved tech friction keeps a geopolitical risk premium baked into yields.
- No durable tariff resolution. Core tariff and purchasing questions were pushed into the next round of talks, meaning the inflation uncertainty that has kept the Fed cautious remains unresolved.
Featured Snippet: What Is the Average Mortgage Rate Today?
As of mid-to-late September 2026, the average 30-year fixed mortgage rate in the US is running just under 7%, per Freddie Mac’s weekly survey — the highest level since January 2025, driven by rising Treasury yields tied to heavy government borrowing and unresolved US-China trade risk following the September 24 Trump-Xi summit.
Asian Growth and the Global Rate Picture
The mortgage story doesn’t stop at the US border. The Asian Development Bank’s September 2026 outlook nudged developing Asia’s 2026 growth forecast up slightly to 5.0%, even as regional inflation stays elevated near 4.2%. Stronger Asian growth alongside sticky inflation is broadly consistent with the “higher for longer” global rate environment that’s keeping US mortgage rates elevated — it’s not just a domestic story.
Q4 2026 Predictive Outlook
- Base case: 30-year fixed rates hold in the 6.7%–7.1% band through year-end, with volatility clustering around the new US-China truce deadline and the next two Fed meetings.
- Upside risk (higher rates): A breakdown in the truce, renewed tariff escalation, or a hawkish surprise from the Fed pushes the 30-year toward 7.25%–7.5%.
- Downside risk (lower rates): A durable trade framework or a faster-than-expected inflation cooldown could pull rates back toward the low 6% range, though nothing in current Fed communication points to that in Q4.
FAQ
Will mortgage rates go down before the end of 2026?
Most forecasters, including those tracked by Freddie Mac and major bank research desks, see rates holding near current levels through Q4 2026 absent a clear resolution to US-China trade tensions or a faster Fed pivot.
How does the Xi-Trump summit affect US mortgage rates?
It affects rates indirectly, through Treasury yields. Unresolved trade and tech-export issues keep an inflation and geopolitical-risk premium in bond markets, which raises the yields that mortgage-backed securities are priced against.
What is a good mortgage rate right now?
Relative to the current national average near 6.9%–7.0%, well-qualified borrowers securing rates half a point or more below the weekly Freddie Mac average are getting a comparatively strong deal in today’s market.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Executive Summary
- Trade Truce Extension: Washington and Beijing extended the Busan economic truce by two months to January 10, 2027, establishing a bilateral Board of Trade mechanism with a $30 billion cap on tariff reductions for non-sensitive goods.
- Taiwan Policy Stance: President Xi Jinping pressed the U.S. administration to shift from “not supporting” to explicitly “opposing” Taiwan independence, while a U.S. $14 billion arms package to Taipei remains on hold.
- AI & Governance Divergence: Trump advocated for minimal federal AI regulation relying on existing legal channels, whereas Xi emphasized international norm-setting and human-controlled AI governance.
- Conflict Prevention: Both leaders highlighted shared WWII historical ties, but underlying systemic friction over technology controls and critical supply chains remains unhedged.
Presidents Xi Jinping and Donald Trump met in Washington, D.C., marking President Xi’s first official state visit to the United States in over a decade. The 43-hour diplomatic engagement combined high-profile ceremonial gestures with intense negotiations over economic policy, regional security, and emerging technologies.
1. Trade Deliverables & Managed Economic Detente
The core economic outcome of the summit was a mutual decision to extend the trade truce originating from the Busan agreements by an additional two months, pushing the negotiation window to January 10, 2027. According to analysis published by The Business Times, this temporal buffer buys critical space for both economies to formalize structured frameworks before political shifts take hold following the U.S. midterm elections.
Key Economic Components:
- Board of Trade Framework: Establishing a structured mechanism to oversee managed bilateral commerce.
- Tariff Cap Reductions: A planned mutual tariff reduction capped at US$30 billion per side, targeting non-sensitive consumer and industrial goods.
- Agricultural Commitments: China continues to meet its baseline commitments for purchasing 25 million metric tons of U.S. soybeans.
However, friction points persist below the surface. U.S. trade officials noted that Beijing remains behind on its broader pledge to purchase $17 billion in other U.S. agricultural exports. Furthermore, delivery quotas for critical rare-earth elements—essential for high-tech manufacturing—have fallen short of target allocations. As detailed by the Chicago Council on Global Affairs, reliance on personalistic leader-to-leader negotiations creates short-term pauses but leaves structural trade imbalances and supply chain dependencies unaddressed.
2. The Taiwan Question & Strategic Security
Diplomatic maneuvering over Taiwan represented the most sensitive geopolitical dynamic of the summit. President Xi reiterated Beijing’s core stance, urging Washington to handle the Taiwan issue with “extreme prudence” and asking the U.S. to actively oppose Taiwan independence rather than maintaining its traditional diplomatic posture of simply “not supporting” it.
Strategic assessments from the Institute for the Study of War indicate that Beijing views the current economic detente as a key window to influence U.S. security commitments in the Indo-Pacific. A planned U.S. $14 billion arms transfer package to Taiwan remains paused, delivering a tactical diplomatic win for Beijing ahead of upcoming multilateral regional gatherings.
3. Divergent Visions on AI Governance & High-Tech Competition
The summit exposed contrasting philosophies regarding the regulation of Artificial Intelligence and advanced computing capabilities. While both leaders acknowledged AI’s transformative influence on global power balances, their proposed paths forward reflect fundamental governance differences.
| Dimension | United States Stance | China Stance |
| Regulatory Model | Market-driven with minimal federal intervention; oversight through existing DOJ frameworks. | State-directed guardrails emphasizing central oversight and alignment with national strategy. |
| Global Governance | Defense of competitive edge and strict export controls on advanced hardware. | Multilateral norm-setting under international organizations (“AI for Good”). |
| Core Objective | Commercial freedom, innovation velocity, and technological superiority. | Human control, risk mitigation, and preventing technological decoupling. |
Reporting from The Federal highlighted that while Xi urged joint international responsibility to ensure AI remains under human control, the U.S. side favored preserving flexibility for domestic technological developers without introducing international regulatory mechanisms.
4. “Thucydides Trap” Avoidance & Strategic Guardrails
Throughout the summit, President Xi repeatedly warned against falling into the “Thucydides Trap”—the historical tendency toward conflict when a rising power challenges an established power. Calling for “constructive strategic stability,” Xi emphasized that global competition should resemble a “race of catching up with one another, not a wrestle in which one wins and the other loses.”
Institutional Takeaways:
- Regular Military Communications: Reaffirming bilateral crisis-prevention channels to prevent miscalculations in air and maritime corridors.
- Historical Commemoration: Leveraging shared World War II history during visits to national monuments to emphasize foundational ties.
- Corporate Engagement: Hosting state dinners with executive leadership to reinforce commercial interdependencies as a stabilizing buffer.
Strategic Outlook
While the 43-hour Washington summit succeeded in projecting stability and securing short-term economic extensions, fundamental strategic competition remains unresolved. The coming months will test whether temporary trade truces and managed tariff caps can withstand broader geopolitical rivalries in technology supply chains, semiconductor export policies, and Pacific security dynamics.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Who is the Federal Reserve chair in 2026? Kevin Warsh was confirmed as the 17th chair of the Federal Reserve in a narrow 54-45 Senate vote on May 13, 2026 — the most divisive confirmation in the Fed’s history — with his term officially beginning when Jerome Powell’s term expired two days later, according to J.P. Morgan Wealth Management’s analysis. Warsh, who at 35 had been the youngest person ever appointed to the Fed’s Board of Governors back in 2006, returned to the central bank after years in the private sector, including a stint as a partner at Duquesne Family Office.
His confirmation followed months of tension between President Trump and outgoing Chair Powell over the pace of rate cuts, and markets immediately began parsing Warsh’s public statements for clues about where he would steer policy.
What Warsh Actually Believes About Inflation
Featured Snippet Target: Fed Chair Kevin Warsh has signaled tighter inflation discipline through a “trimmed averages” approach to measuring price changes — removing the most extreme price movements from the inflation basket before calculating overall trends — while also arguing in a pre-confirmation Wall Street Journal op-ed that artificial intelligence could act as a significant disinflationary force on the broader economy.
That combination puzzled Fed-watchers who expected Warsh, nominated by a president who had repeatedly pushed for lower rates, to simply deliver the dovish policy Trump wanted. Instead, according to analysis from The Motley Fool, Warsh has been notably tight-lipped in his first months, by design — he has stated he wants the Fed to take more of a “back seat” in market communication, believing markets function more efficiently digesting economic data directly rather than reacting to Fed guidance.
The First Meeting: A Hawkish Surprise
Warsh’s debut as chair came at the June 16-17, 2026 FOMC meeting, and it delivered a genuine surprise to markets pricing in continued easing. The Fed held its federal funds rate steady at 3.50%-3.75% for a third consecutive meeting, but new quarterly projections showed nine Fed officials now anticipating a rate hike by the end of 2026 — a sharp reversal from the cutting cycle markets had expected — with the median forecast raised to 3.6% by year-end, according to reporting from The Daily Record. The updated policy statement also removed all forward guidance language about future rate moves, adopting a shortened format reminiscent of the Alan Greenspan era — an early, tangible sign of Warsh’s stated preference for a more narrowly focused, less communicative central bank.
That hawkish pivot came against a genuinely difficult inflation backdrop. Inflation had been running stubbornly above the Fed’s 2% target even before Warsh’s arrival, and the eruption of the Iran conflict in late February 2026 pushed oil prices sharply higher, adding a fresh layer of cost-push inflation pressure just as the new chair was settling in.
Why the FOMC Itself Is Divided
Warsh inherited a genuinely split committee. The 19-member FOMC had signaled openness to a prolonged pause after delivering three rate cuts in the prior fall, with many policymakers believing those cuts had sufficiently addressed slowing job growth, according to analysis from ChannelChek. April 2026’s meeting — held before Warsh’s confirmation — brought the most policy disagreement among committee members in decades, reflecting a genuine intellectual split between officials worried about persistent inflation and those worried about a weakening, “low-hire, low-fire” job market.
Convincing that divided committee to resume cutting rates, rather than hike as the June projections suggested, will likely be one of Warsh’s most consequential early challenges — particularly if inflation data continues running hot on the back of elevated energy costs.
The Bigger Structural Agenda
Beyond the immediate rate debate, Warsh has signaled an intent to reshape how the Fed operates more broadly. He has stated a goal of shrinking the central bank’s balance sheet and strengthening coordination between the Fed, the Treasury, and the White House on economic policy, according to reporting on his confirmation. That coordination goal is itself a departure from the traditional emphasis on Fed independence from fiscal policymakers — a shift some economists have flagged as worth watching closely, given how central bank independence has historically been treated as a bulwark against politically-driven inflation.
The Market Reaction
Markets initially reacted to Warsh’s nomination with genuine uncertainty rather than a clear directional bet. Following his January 2026 nomination, Fed funds futures were pricing a 65.3% probability of at least one rate cut by June — up from 61.8% the prior day — with markets pricing in a total of 52 basis points of cuts for all of 2026 at that point, according to fixed-income commentary from Asset Allocation & Management Company. That dovish pricing has since been substantially unwound by the actual June hawkish pivot — a reminder that a new Fed chair’s confirmed policy stance, once articulated in an actual meeting, matters far more to markets than pre-confirmation speculation about political allegiance.
The Bottom Line
Kevin Warsh’s first months as Fed chair have defied the simple “Trump appointee cuts rates” narrative that dominated coverage of his nomination. Instead, he has delivered a genuinely hawkish debut meeting, adopted a more hands-off communication style, and articulated an inflation-measurement philosophy that gives him intellectual cover to hold rates higher for longer if energy-driven inflation persists. Whether that stance holds through the rest of 2026 will depend heavily on how the Iran conflict’s economic fallout evolves and whether the divided FOMC can coalesce around a consistent direction.
Next step: Track the Fed’s quarterly Summary of Economic Projections alongside actual CPI and PCE inflation prints — the gap between the two, more than any single Warsh public statement, is the clearest signal of whether the Fed’s late-2026 rate path tilts toward the hike some officials now anticipate or back toward the cuts markets originally expected.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Apply for a Bank Account Online: What You Need and How Long It Actually Takes

World’s Largest Economies: Ranking the Top Global Powers

Business Loan: A Complete 2026 Guide to Rates, Types, and Qualifying

Fast Invoice Factoring: How to Turn Unpaid Invoices Into Cash Within 24 Hours

Investment Banking Services: What They Cost and How to Choose the Right Firm in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025