
Asia
South Asia’s Economic Renaissance: 5 Markets Leading Recovery

South Asia emerges as a global economic powerhouse in the mid-2020s, defying worldwide economic uncertainties with strong growth trajectories across multiple markets. The region’s post-pandemic recovery momentum has accelerated substantially, driven by strategic policy reforms and targeted investment initiatives that are reshaping economic patterns.
Five standout markets lead this transformation: India, Bhutan, Maldives, Pakistan, and Sri Lanka. Each demonstrates unique recovery strategies spanning manufacturing excellence, sustainable energy development, tourism revitalization, fiscal discipline, and export diversification. Growing investor confidence reflects the region’s successful navigation from traditional agriculture-based economies toward diversified, technology-integrated growth models.
This renaissance extends beyond simple recovery metrics. Strategic positioning between China and global markets creates competitive advantages, while infrastructure-led development strategies and foreign direct investment policy reforms establish foundations for sustained growth through 2026 and beyond.
Key Takeaways
Essential insights from South Asia’s economic renaissance:
• India maintains fastest growth among major global economies through manufacturing initiatives and MSME support contributing 30% of GDP • Pakistan achieves substantial inflation reduction from double digits to 4-6% through fiscal tightening and comprehensive trade reforms • Tourism-driven recovery powers Maldives and Sri Lanka with 9.4% and 2.2 million visitor increases respectively • Hydropower expansion positions Bhutan for 40% electricity revenue growth from 2026 onward • Export diversification creates new opportunities, with Sri Lanka’s coconut sector surpassing $1 billion in exports
Understanding South Asia’s Economic Transformation
Regional growth dynamics reflect a major shift from agriculture-dependent economies toward diversified growth models integrating digital technologies and strategic manufacturing. Infrastructure-led development strategies, export-oriented manufacturing initiatives, tourism sector revitalization, and foreign direct investment policy reforms serve as primary recovery drivers across multiple countries.
Investment climate improvements include regulatory framework modernization, enhanced ease of doing business rankings, and strategic partnerships with major economies. Production-Linked Incentive (PLI) schemes have attracted over $20 billion in investments across 12 sectors, demonstrating the region’s capacity to implement large-scale economic transformation initiatives.
The integration of digital technologies accelerates economic development, while strategic positioning between China and global markets creates competitive advantages that enhance export competitiveness and attract international partnerships.
Market Leader #1: India – The Manufacturing Powerhouse
India’s economic policy revolution centers on comprehensive tax reform, with direct income tax exemptions and GST rationalization boosting domestic consumption. Accommodative monetary policies enhance investment confidence, while MSME empowerment initiatives support 240 million employees across small and medium enterprises contributing nearly 30% of GDP and 45% of exports.
Manufacturing sector dominance emerges through Make in India success, with manufacturing contributing 16-17% of GDP. PLI scheme results show $20 billion attracted across 12 strategic sectors, while large increases in foreign direct investment demonstrate growing international confidence in India’s manufacturing capabilities.
Digital economy integration applies technological advancement in the services sector, supporting export competitiveness through innovation hubs that attract global partnerships. Infrastructure development includes increased government capital expenditure driving growth, massive electric vehicle sector investments, and green energy transition initiatives creating new market opportunities.
Strategic investment opportunities for 2024 include production-linked incentive sectors offering immediate entry points, government capital expenditure creating contractor and supplier opportunities, and export-oriented technology services expansion. MSMEs contribute nearly 30% of GDP while employing over 240 million people, representing substantial market opportunities for investors and business leaders.
Market Leader #2: Bhutan – Hydropower Innovation Hub
Bhutan’s hydropower sector expansion includes major project completions with Punatsangchhu-II and Kholongchhu hydropower plants coming online. Electricity exports are projected to contribute up to 40% of revenues from 2026, positioning Bhutan as South Asia’s clean energy supplier and enhancing regional energy security.
Tourism recovery demonstrates sustainable development principles, with a 25% increase in arrivals during the first half of 2025. Infrastructure development supports high-value, low-impact tourism, while government-led promotional campaigns drive international interest and visitor growth.
Government development strategy through the 13th Five-Year Plan includes major infrastructure, education, and digital connectivity spending. Taxation reforms strengthen government revenues, while strategic investments in telecommunications infrastructure support digital connectivity initiatives.
Investment opportunities in Bhutan include hydropower project partnerships and equipment supply, eco-friendly accommodation and infrastructure development for sustainable tourism, and connectivity and technology service provision for digital infrastructure expansion. Hydropower exports are expected to contribute 40% of electricity revenues from 2026 onward.
Market Leader #3: Maldives – Tourism and Infrastructure Synergy
The Maldives demonstrates tourism sector leadership with a 9.4% increase in tourist arrivals in early 2025, driving projected 5% real GDP growth in 2025. Post-pandemic recovery momentum proves resilient, establishing tourism as the primary economic driver with sustainable growth prospects.
Infrastructure development revolution includes airport expansion with new terminal completions increasing capacity, sustainable townships representing a new integrated development category combining hospitality, residential, healthcare, and education, and renewable energy integration supporting tourism sustainability initiatives.
Economic diversification strategy moves beyond traditional resort-only tourism models through integrated developments, healthcare and education sectors supporting long-term economic stability, and strategic partnerships with India for infrastructure and defense modernization.
Business opportunities include sustainable tourism through eco-friendly resort development and operations, infrastructure development for airports, transportation, and utilities, healthcare services including medical tourism and local healthcare provision, and renewable energy project implementation focusing on solar and wind power.
Market Leader #4: Pakistan – Fiscal Discipline Success Story
Pakistan’s fiscal and monetary policy transformation achieves substantial inflation reduction from double digits to 4-6% by 2025-2026 through strategic fiscal tightening creating budget stability. Major public debt reduction through strategic planning and prudent central bank policies anchor economic confidence.
Trade policy revolution represents the most substantial changes in over three decades, featuring comprehensive reform with strategic shift from import-dependent to export-driven growth. Tariff simplification reduces barriers enhancing competitiveness, with expected results including 13% export increase and 6.6% investment growth projections.
Foreign investment revival shows increased inflows in power and financial services sectors, regional integration efforts to join RCEP and other trade blocs, and investment spreading beyond traditional industries through sector diversification initiatives.
| Indicator | Previous Level | 2025-2026 Target | Improvement |
|---|---|---|---|
| Inflation Rate | Double-digit | 4-6% | 50%+ reduction |
| Export Growth | Declining | +13% | Strong increase |
| Investment Growth | Stagnant | +6.6% | Strong recovery |
Strategic investment sectors include power generation with energy infrastructure development opportunities, financial services through banking and fintech expansion potential, export manufacturing in textile, agriculture, and technology sectors, and infrastructure development needs in transportation and logistics.
Market Leader #5: Sri Lanka – Resilient Recovery Model
Sri Lanka’s debt restructuring success includes IMF collaboration through Extended Fund Facility (EFF) program supporting transformation, strategic tax increases and cost-reflective pricing implementation, and complex debt management restructuring processes showing positive results.
Tourism sector resurgence demonstrates over 2.2 million tourists in 2025 marking strong comeback, $1.1 billion earned in the first quarter of 2025, and international recognition of recovery progress enhancing market confidence.
Export industry diversification achieves coconut sector success surpassing $1 billion in exports with 40% year-on-year growth. Export projections target $1.2 billion by year-end for coconut products alone, while traditional sectors demonstrate notable resilience through industry expansion initiatives.
Investment opportunities include tourism infrastructure through hotel development and transportation services, agricultural exports focusing on value-added processing and international distribution, manufacturing through export-oriented production facilities, and infrastructure rehabilitation including reconstruction and modernization projects.
Strategic Opportunities for Investors and Business Leaders
Cross-regional investment themes include infrastructure development spanning transportation, energy, and digital connectivity across all markets. Tourism and hospitality opportunities range from sustainable tourism models in the Maldives to Sri Lanka’s recovery initiatives. Manufacturing and export prospects include production-linked opportunities in India and Pakistan, while clean energy includes hydropower in Bhutan and renewable tourism infrastructure in the Maldives.
Sector-specific opportunities in manufacturing and production include India’s PLI schemes offering immediate entry points, Pakistan’s export-oriented manufacturing revival, and Sri Lanka’s agricultural processing expansion. Tourism and services opportunities span Maldives’ sustainable township developments, Bhutan’s high-value eco-tourism initiatives, and Sri Lanka’s tourism infrastructure rehabilitation.
Energy and infrastructure opportunities include Bhutan’s hydropower project partnerships, regional connectivity improvements across all markets, and digital infrastructure development opportunities throughout the region.
Risk mitigation strategies emphasize diversification through spreading investments across multiple countries and sectors, local partnerships using regional expertise and government relationships, and policy monitoring to stay informed about regulatory changes and incentive programs.
Implementation timeline recommendations include short-term entry into tourism and services sectors within 6-12 months, medium-term manufacturing and infrastructure investments over 1-3 years, and long-term major infrastructure and energy projects spanning 3-5 years.
The Future of South Asian Markets
South Asia’s economic renaissance demonstrates five distinct recovery models showcasing diverse pathways to growth through policy reforms, infrastructure investment, and export diversification. This combined approach creates a resilient economic foundation supporting sustained regional development.
Key success factors include strategic government intervention through targeted policies supporting specific sectors, foreign investment integration balancing international partnerships with domestic development, sustainable development focus enhancing long-term viability through environmental and social responsibility, and export orientation reducing dependency on domestic markets through international expansion.
Future growth projections indicate sustained momentum expected through 2026 and beyond, increasing regional integration creating synergistic opportunities, and growing global recognition attracting additional international investment. Combined economic initiatives across these five markets demonstrate potential for sustained regional growth exceeding global averages.
Investors should consider diversified South Asian portfolio allocation, business leaders should examine manufacturing and services expansion opportunities, and policymakers should study successful reform models for broader regional application. South Asia’s transformation represents more than recovery—it signals major change creating lasting opportunities for strategic market engagement.
FAQ
Q: What makes South Asia’s economic recovery unique compared to other regions? A: South Asia’s recovery combines diverse strategies including manufacturing excellence in India, sustainable energy in Bhutan, tourism revitalization in Maldives, fiscal discipline in Pakistan, and export diversification in Sri Lanka, creating an approach that reduces regional economic risk.
Q: Which sectors offer the best investment opportunities across South Asian markets? A: Infrastructure development, sustainable tourism, export-oriented manufacturing, and clean energy represent the strongest cross-regional opportunities, with specific advantages in India’s PLI schemes, Bhutan’s hydropower projects, and the Maldives’ integrated tourism developments.
Q: How sustainable are these growth trends through 2026 and beyond? A: Growth sustainability is supported by policy reforms, strategic international partnerships, export diversification, and infrastructure development that create lasting economic foundations rather than short-term recovery measures.
Q: What risks should investors consider when entering South Asian markets? A: Primary risks include regulatory changes, currency fluctuation, and political stability variations. Mitigation strategies include diversification across multiple countries and sectors, local partnerships, and continuous policy monitoring.
Q: How do these five markets complement each other for regional investors? A: The markets offer complementary opportunities: India provides scale and manufacturing, Bhutan offers clean energy, Maldives delivers tourism excellence, Pakistan enables export manufacturing, and Sri Lanka provides agricultural and tourism diversification, creating comprehensive regional investment portfolios.
Cited Sources
- https://www.deloitte.com/us/en/insights/topics/economy/asia-pacific/india-economic-outlook.html
- https://www.ibef.org/industry/manufacturing-sector-india
- https://www.investindia.gov.in/india-opportunity
- https://bhutantimes.bt/bhutans-economic-growth-trajectory-at-6-percent-in-2026-3
- https://mof.gov.bt/wp-content/uploads/2025/10/Press-Release-on-Bhutans-Economy-Sustains-Strong-Growth-Momentum-1.pdf
- https://www.worldbank.org/en/country/maldives/publication/maldives-development-update-october-2025
- https://www.hospitalitynet.org/news/4129685.html
- https://www.worldbank.org/en/news/press-release/2025/10/27/-pakistan-sustained-reforms-needed-for-inclusive-growth-economic-stability-and-flood-recovery
- https://vae.ahk.de/de/content/download/624971/9770528?version=1
- https://www.omfif.org/2025/12/floods-in-sri-lanka-will-test-its-fragile-economic-recovery
- https://www.facebook.com/AviationVoice/posts/sri-lanka-welcomes-over-22-million-tourists-in-2025-marking-strong-tourism-comeb/1317441793762835
- https://www.facebook.com/chathuranga.abeysinghe/posts/one-of-the-key-highlights-of-sri-lankas-export-performance-in-2025-has-been-the-/10163881361703537
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Economic Costs of Wars
Ceasefire Negotiations in 2026: Predicting the Rebound of European and Asian Economies
Key Takeaways
- The European Commission has already cut its 2026 eurozone growth forecast to 0.9% (from 1.2%) and raised inflation projections to 3.0%, directly citing the Middle East war’s energy shock — with a full rebound contingent on how quickly, and how durably, any ceasefire holds.
- The ECB has laid out an explicit scenario split: its June 2026 baseline assumes gradual de-escalation and sees growth reaching 1.3% in 2027, while an adverse scenario with oil peaking near $180/barrel would roughly halve projected 2026 growth and push inflation 1.1 percentage points higher in 2027.
- Historical ceasefire episodes from earlier in 2026 show Asian markets — Japan’s Nikkei, South Korea’s Kospi — rallying 5%+ in single sessions on de-escalation headlines, only to reverse sharply when agreements broke down within days to weeks.
- As of mid-September 2026, no ceasefire is currently in place — the conflict has escalated rather than eased this month — meaning both the EU’s baseline and adverse scenarios remain live possibilities rather than settled outcomes.
- The World Bank’s April 2026 regional outlook shows the MENAAP region absorbing the sharpest growth downgrade of any global region, while South Asia remains comparatively resilient — illustrating how unevenly any eventual rebound would likely be distributed.
Every economic forecasting body tracking the global economy in 2026 — the European Commission, the ECB, the World Bank — has built its projections around the same fundamental uncertainty: nobody knows exactly when, or how durably, the US-Iran war will end. This piece works through what the major institutions’ own published scenarios say about how European and Asian economies would actually rebound once a ceasefire holds, and how sharply those forecasts diverge from what’s likely if the conflict instead drags on.
Europe’s Baseline vs. Adverse Scenario
The European Commission’s most recent forecast, published in May 2026, cut its eurozone 2026 growth projection to 0.9%, down from an earlier 1.2% estimate, while raising expected inflation to 3.0% — well above the ECB’s 2% target. EU economy chief Valdis Dombrovskis attributed the downgrade directly to the Middle East conflict, which he said “triggered a major energy shock, further testing Europe as it navigates an already volatile geopolitical and trade environment.”
Critically, the Commission built its forecast around two explicit scenarios. The baseline assumes energy prices gradually normalize as the conflict eases — even accounting for a “fragile ceasefire” that was in place at the time of the forecast’s cutoff date (though the Strait of Hormuz remained effectively closed even under that truce). The adverse scenario assumes oil prices continue climbing toward $180 per barrel by year-end; under that path, the Commission estimated inflation would run 0.3 percentage points higher in 2026 and a full 1.1 percentage points higher in 2027, while growth would come in at roughly half the baseline forecast.
The ECB has published its own parallel scenario work. Its June 2026 projections put baseline euro-area growth at 0.9% in 2026, improving to 1.3% in 2027 and 1.4% in 2028 — a “downward revision, especially for 2026,” reflecting what the ECB explicitly called “the global effects of the war on commodity markets, real incomes and confidence.” By September, more recent ECB commentary noted the euro area economy was proving “more resilient than expected” to the shock, supported by domestic demand, a robust labour market, and AI-related investment — suggesting some of the earlier worst-case assumptions may not be fully materializing, even without a durable ceasefire yet in place.
Asia’s Pattern: Sharp Rallies, Sharper Reversals
Asian equity markets have shown a far more volatile, headline-driven relationship with ceasefire news than Europe’s more gradual, forecast-revision-based response. When the US and Iran announced a framework agreement to end hostilities in June 2026, Japan’s Nikkei 225 surged 5.5% in a single morning session, South Korea’s Kospi jumped as much as 5.7%, and Taiwan’s Taiex climbed 2.7%. A separate ceasefire announcement in April 2026 produced a similar pattern: the Nasdaq 100 rose nearly 3% while Japan and Korea posted comparable Asia-Pacific gains.
In both cases, the rallies proved short-lived. The April ceasefire unraveled within roughly two weeks amid mutual accusations of violations, and by early September 2026, fighting had resumed in earnest, with oil prices climbing back above $107 per barrel and diesel approaching a record $6 per gallon in the US. This pattern — sharp, headline-driven Asian equity rallies followed by reversal once agreements prove unstable — has now repeated at least three times in 2026, a track record worth weighing heavily against any future ceasefire headline.
Scenario Comparison Table
| Scenario | Eurozone 2026 Growth | Eurozone Inflation | Asian Equity Pattern |
|---|---|---|---|
| EU baseline (gradual de-escalation) | 0.9% | 3.0% | Gradual stabilization |
| EU adverse (oil to $180/bbl, prolonged conflict) | ~0.4-0.5% (roughly half baseline) | +1.1pp above baseline by 2027 | Continued volatility, no durable rally |
| Historical pattern: ceasefire announcement | N/A (US/Euro-specific) | N/A | Nikkei/Kospi +5%+ single session |
| Historical pattern: ceasefire collapse | N/A | N/A | Reversal within 1-3 weeks |
The Uneven Regional Picture
Not every region would rebound equally even in the optimistic baseline scenario. The World Bank’s April 2026 regional economic update found that, excluding Iran itself, the broader MENAAP region’s growth is expected to slow from 4.0% in 2025 to just 1.8% in 2026 — the sharpest downgrade of any region the Bank tracks. By contrast, the Bank’s July 2026 Global Economic Prospects report identifies South Asia as remaining the fastest-growing region globally despite the conflict, with the Bank explicitly noting that regional impacts differ based on each economy’s energy exposure, strategic reserves, and available policy buffers — meaning net energy importers without deep reserves face a structurally slower rebound path than better-insulated economies even after any ceasefire takes hold.
Why This Matters: Treat Ceasefire Headlines as Scenario Triggers, Not Resolutions
For investors and businesses trying to plan around the global economy’s trajectory, the most useful framework isn’t predicting exactly when a ceasefire arrives — it’s understanding which of the major institutions’ published scenarios that ceasefire would activate. A durable, Hormuz-reopening ceasefire would plausibly validate the EU Commission and ECB’s baseline growth and inflation paths, alongside a genuine (rather than headline-driven) Asian equity rebound. A fragile, easily-reversed truce — the pattern seen three times already in 2026 — would instead simply reset the clock on the adverse scenario, with markets likely repeating the same rally-then-reversal cycle that has defined 2026 so far. Given that no ceasefire is currently in place as of mid-September, and given the specific track record of the last three attempts, the adverse-scenario framework remains the more probable near-term base case.
Frequently Asked Questions
How would a Middle East ceasefire affect European economic growth?
Under the European Commission’s baseline scenario, a durable de-escalation would support eurozone growth around 0.9% in 2026, improving further in 2027. A prolonged conflict instead risks roughly halving that growth figure, per the Commission’s own adverse scenario.
Do Asian stock markets typically rally on ceasefire news?
Yes, historically sharply — Japan’s Nikkei and South Korea’s Kospi have both surged 5%+ in single sessions following prior 2026 ceasefire announcements, but those rallies have reversed within one to three weeks each time the agreements subsequently broke down.
Which regions would benefit most from a durable ceasefire?
The World Bank identifies the MENAAP region (Middle East, North Africa, Afghanistan, Pakistan) as having absorbed the sharpest 2026 growth downgrade, meaning it stands to see the largest relative rebound from a durable ceasefire, while South Asia has remained comparatively resilient throughout the conflict.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
With the S&P 500 yielding a historically thin 1.2% and trading at a P/E above 31 following its 2025 rally, income-focused investors have been forced to look further afield. Europe and Asia’s blue-chip dividend payers are filling that gap — offering yields two to five times the U.S. benchmark, backed in many cases by decades of uninterrupted payout growth. Here is where the highest-quality income is actually sitting in 2026, and where headline yield is masking real risk.
Why U.S. Yields No Longer Cut It
The math is straightforward. As Sure Dividend notes, the S&P 500 closed out 2025 with a year-to-date total return of nearly 19%, pushing its price-to-earnings ratio above 31 and compressing yields across the board. Even reliable U.S. dividend growers now offer modest current income: NextEra Energy yields just 2.7% (though it is growing its payout at a 6% compound annual rate through 2028), Coca-Cola yields about 2.7%, and Mastercard — despite raising its dividend more than 9,500% since its first payment — yields a mere 0.7%, according to The Motley Fool. For investors who need current income rather than pure growth, that combination of high valuations and low yields has made the U.S. market a difficult place to build an income portfolio in 2026.
Europe: Insurance and Compounders Lead on Yield
European blue chips have emerged as the highest-conviction income allocation for 2026, according to screening data from Dividend Talk, which evaluates stocks on dividend safety, valuation, and long-term growth rather than headline yield alone.
Top European dividend stocks (verified June 17, 2026):
| Stock | Yield | Sector |
|---|---|---|
| Munich Re | 5.17% | Reinsurance |
| ASR Nederland | 5.15% | Insurance |
| Wolters Kluwer | 4.21% | Information services |
| Novo Nordisk | 4.10% | Pharmaceuticals |
| Fuchs Petrolub | — | Specialty lubricants |
| London Stock Exchange Group | — | Financial market infrastructure |
| Halma | — | Safety/health technology |
| RELX | — | Information/analytics |
| SAP | — | Enterprise software |
The critical distinction Dividend Talk draws is between yield and dividend safety. Munich Re, ASR Nederland, Wolters Kluwer, and Novo Nordisk all carry both an above-3.8% yield and a “Safe” or “Very Safe” internal safety rating, alongside multi-decade dividend records — meaning the yield is backed by durable free cash flow rather than a depressed share price masquerading as a bargain. That distinction matters most in the insurance names: Munich Re and ASR Nederland benefit structurally from higher reinsurance pricing following a run of costly global catastrophe years, giving their payouts unusually strong underlying support heading into 2026.
Asia: Banking and Semiconductor Leadership, With a Payout Caveat
Asian dividend stocks offer a different risk-reward profile, combining higher headline yields with more variable payout coverage. According to Analytics Insight’s 2026 Asia screen, DBS Group Holdings stands out with an estimated dividend yield of 5.4% to 6.1% — among the highest of any large-cap regional bank globally — supported by its wealth-management franchise, deep Southeast Asian deposit base, and digital banking scale.
Top Asian dividend stocks for 2026:
| Stock | Yield | Note |
|---|---|---|
| DBS Group Holdings | 5.4%–6.1% | Deep deposit base, wealth management scale |
| TSMC | Lower, growth-oriented | Semiconductor leadership, diversified cash flow |
| ITC | Moderate | Diversified conglomerate, business visibility |
| Anhui Heli | 3.3%–4.47% | Track payout coverage closely |
| Shibusawa Logistics | 3.3%–4.47% | Track payout coverage closely |
| Rheon | 3.3%–4.47% | Track payout coverage closely |
| Japan market payer (top-quartile yield) | ~4.0% | JPY 31/share; payout ratio 40.1% |
The caution flag in Asia sits with the smaller-cap names. Analytics Insight specifically flags that while stocks like Anhui Heli, Shibusawa Logistics, and Rheon offer attractive 3.3%–4.47% yields, investors need to verify free cash flow coverage before committing capital. One unnamed top-quartile Japanese dividend payer illustrates the risk clearly: its payout ratio of 40.1% suggests the dividend is covered by earnings but not comfortably by free cash flow, and its dividend history has been volatile over the past decade — a pattern that can quietly erode a portfolio’s income reliability even when the trailing yield looks attractive on a screener.
Building a 2026 Income Allocation: The Framework
The right approach for 2026 income investors is to treat yield as a starting filter, not a selection criterion. Analytics Insight’s own guidance is explicit: “investors should also consider key metrics such as payout ratio, free cash flow coverage, market position, and dividend consistency before investing” — a standard that immediately separates DBS, TSMC, and ITC (dependable large-cap options with strong business visibility) from the higher-yielding but less-established smaller names.
A practical due-diligence checklist before buying any high-yield stock in 2026:
- Payout ratio relative to earnings AND free cash flow — a dividend covered by earnings but not FCF is a warning sign, not a green light
- Dividend growth streak length — a multi-decade record (Novo Nordisk, RELX, SAP) filters out cyclical one-off high yields
- Sector tailwinds — European insurers are riding a hard reinsurance pricing cycle; Asian banks like DBS benefit from elevated regional rates and wealth inflows
- Currency exposure — unhedged EUR, SGD, and JPY dividend income introduces FX volatility that can offset or amplify the yield advantage over USD alternatives
Final Verdict
For income-focused investors priced out of a 1.2%-yielding, 31x-earnings S&P 500, Europe’s insurance and compounder names — led by Munich Re, ASR Nederland, Wolters Kluwer, and Novo Nordisk — currently offer the best combination of yield and safety available in developed markets. In Asia, DBS Group is the standout large-cap income name, while TSMC and ITC offer lower yields with stronger long-term visibility. The smaller Asian dividend payers can supplement a portfolio’s income but demand active monitoring of payout ratios rather than a buy-and-forget approach. The overarching 2026 lesson: geographic diversification into non-U.S. blue chips isn’t just a currency or growth play anymore — for income investors, it has become close to a necessity.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
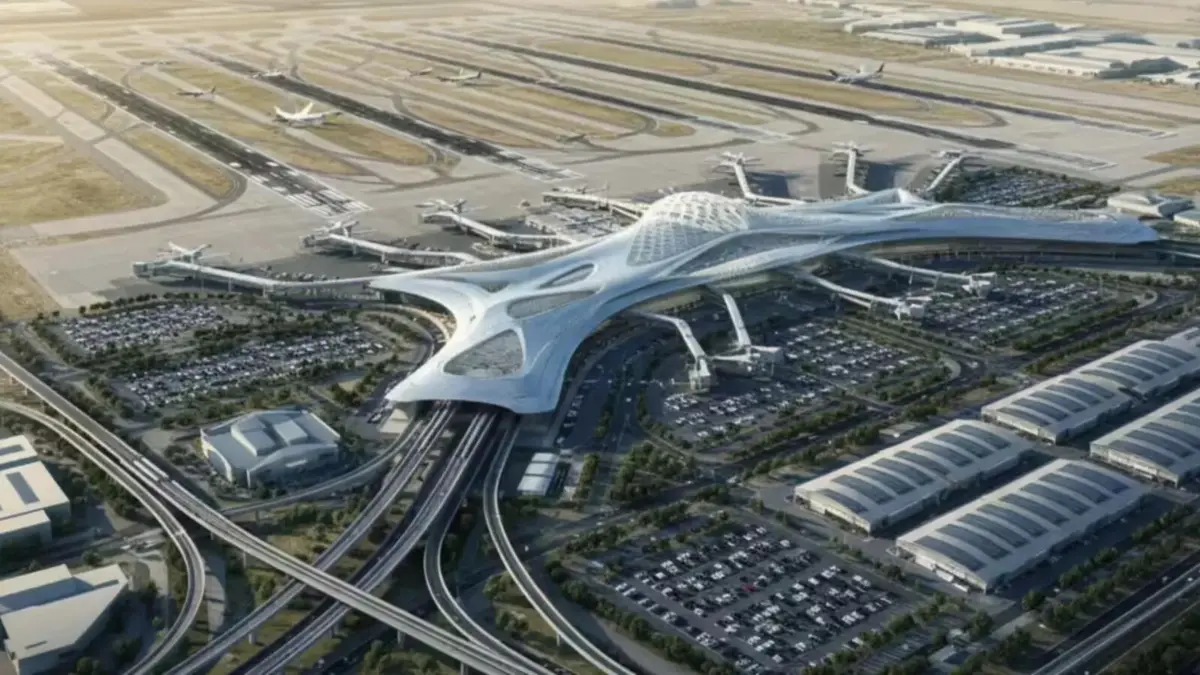
Dubai is in the middle of building what is intended to become the world’s largest airport by capacity — a Dh128 billion ($34.8 billion) expansion of Al Maktoum International Airport at Dubai World Central (DWC), according to Gulf News. When complete, the facility will feature five parallel runways, roughly 400 gates, and the capacity to handle up to 260 million passengers a year — nearly three times the current capacity of Dubai International Airport (DXB), already the world’s second-busiest airport for international traffic, per analysis from K Estates.
Where the project actually stands in 2026
Construction crews have already excavated more than 45 million cubic metres of earth and completed the airport’s second runway, according to MyBayut’s DWC guide. The first phase — a central passenger terminal and four concourses designed to handle 150 million passengers annually — is targeted for completion around 2032, per Khaleej Times. Dubai is set to allocate AED 55 billion worth of expansion contracts by the end of 2026 alone, underscoring the pace at which the project is being financed and built.
The scale of ambition extends beyond aviation infrastructure. DWC is being planned as a self-contained “airport city,” incorporating business, cultural, and residential districts across Dubai South, roughly 35 kilometres from Dubai Marina, according to the same Khaleej Times reporting. All operations currently based at DXB — including Emirates’ long-haul network — are expected to eventually transfer to the new hub.
Part of a much bigger regional aviation build-out
Al Maktoum’s expansion is the largest single project within a broader regional wave of investment: airports across the Middle East, Africa, and South Asia are expected to spend a combined $183 billion on capacity, connectivity, and passenger-experience upgrades, with the UAE and Saudi Arabia leading the push, according to Gulf News. Within the UAE alone, expansion plans extend beyond Dubai to Sharjah and Ras Al Khaimah, with a shared emphasis on AI-enabled operations, IoT systems, and energy-efficient terminal design.
What it means for the region’s real estate and travel markets
The airport build-out is already reshaping property markets nearby. Transactions in Dubai South exceeded AED 15 billion ($4.1 billion) in just the first five months of 2025 — nearly matching the entire AED 16.1 billion recorded across all of 2024 — with analysts forecasting further price appreciation as the airport nears completion, according to K Estates. For travellers and airlines, the eventual payoff is a dramatic increase in regional connectivity capacity at a time when global air travel demand — and airfares — have both been climbing steadily through 2026.
Key takeaways
- Al Maktoum International Airport’s expansion carries a price tag of roughly $34.8 billion (Dh128 billion) and is intended to make it the world’s largest airport by 2050.
- Full build-out capacity: five runways, ~400 gates, up to 260 million passengers annually and 12 million tonnes of cargo.
- Phase one, targeted for around 2032, alone will handle 150 million passengers a year.
- The project has already reshaped Dubai South real estate, with transactions surpassing AED 15 billion in the first five months of 2025.
- It is the anchor project within a broader $183 billion regional airport investment wave across the Middle East, Africa, and South Asia.
FAQ
When will Al Maktoum International Airport be the world’s largest? Full completion is projected around 2050, though the first major phase is targeted for roughly 2032.
How many passengers will Al Maktoum Airport handle? Up to 260 million passengers annually at full capacity, with the first completed phase alone handling 150 million.
Will Emirates move its operations to the new airport? Yes — all Dubai International Airport operations, including Emirates’ long-haul network, are expected to eventually transfer to Al Maktoum International.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Beyond Rhetoric: How the EU Is Deploying ‘All Tools’ to Rebalance Its €1 Billion-a-Day Trade Deficit with China

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

INTC Stock Forecast 2026: Can Intel’s Government-Backed Turnaround Hold?

Bitcoin Price Action in Q4 2026: Safe-Haven Asset or High-Risk Tech Play?

The Target Pokémon x Owala Drop: Everything to Know Before It Sells Out

The U.S. Just Confirmed It Has Weapons in Space — Here’s What It Means for Defense Stocks

IRS 2027 Tax Bracket Projections: How to Get Ahead of Bracket Creep

Dow Jones vs. Middle East Tensions: How Wall Street Is Pricing In a 2026 Conflict Nobody Saw Coming

Bank of England’s September 17 Decision: Will UK Interest Rates Finally Move?

Inflation Is Outpacing Wage Growth Again: What It Means for Your Paycheck

10-Year Treasury Yield Tops 5%: What It Means for Mortgages, Stocks, and the Fed

Ceasefire Negotiations in 2026: Predicting the Rebound of European and Asian Economies

Emerging Markets Update: The Impact of World Bank Policies on PSX Stability

Costco Oil Shortage 2026: Will Prices Double for All Synthetic Motor Oils?

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Gold’s Wild 2026: From a Record $5,600 Peak to a 24% Crash and Back Toward $4,500

Oil Surges as Strait of Hormuz Traffic Collapses Again

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Global Chip Selloff Deepens: What’s Driving the Aug. 19 Semiconductor Rout

Shein Clothes Quality & Safety in 2026: What Lab Tests Show
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pingback: Pakistan's Strategic Economic Position in South Asia - The Economy